
 Vitamin K2 Market | 2026-2036
Vitamin K2 Market Size, Share, and Industry Trends Forecast 2026-2036
Vitamin K2 Market Outlook
China is fragmenting as new fermentation capacity comes online, challenging the historical dominance of Japanese and European suppliers. Gnosis by Lesaffre anchors its position through backward integration into proprietary fermentation strains. Kappa Bioscience differentiates via synthetic MK-7 purity standards that appeal to pharmaceutical-grade buyers. DSM Firmenich AG leverages its broader nutritional ingredients portfolio to secure multi-year supply contracts with global supplement brands.
Vitamin K2 comprises a group of menaquinones designated MK-4 through MK-13, with MK-7 and MK-4 dominating commercial applications due to their superior bioavailability and longer serum half-life compared to dietary vitamin K1. The compound functions as a cofactor for gamma-glutamyl carboxylase, activating osteocalcin and matrix Gla protein to direct calcium toward bone matrix and away from arterial walls. Natural and fermented product types command premium positioning as clean-label demand from health-conscious consumers intensifies, while synthetic variants retain cost advantages in mass-market pharmaceutical applications where purity specifications are less stringent. Pharmaceutical and nutraceutical applications together represent the core margin pool, though cosmetic formulations featuring topical K2 for skin elasticity are emerging as a faster-growing niche with higher per-unit pricing.
Japan's Ministry of Health, Labour and Welfare maintains specific FOSHU (Foods for Specified Health Uses) standards that validate bone-density claims for MK-7, directly shaping product development priorities for exporters targeting Japanese consumers. The European Food Safety Authority and FDA both regulate structure-function claims with differing evidentiary thresholds, forcing manufacturers to maintain dual dossier strategies for transatlantic market access. Stakeholders must monitor evolving pharmacovigilance requirements for high-dose K2 interactions with anticoagulant therapies, as regulatory scrutiny of supplement-drug contraindications tightens across major health authorities.
Market Dynamics
Fermentation-based production methods are compressing synthetic K2 margins as manufacturers race to secure clean-label positioning ahead of tightening EFSA and FDA substantiation requirements for bone-health claims.
Growth Catalysts
- FOSHU Standards:Japan's Ministry of Health, Labour and Welfare validates specific bone-density claims for MK-7, creating a regulatory template that exporters replicate for premium positioning in other Asian markets.
- Anticoagulant Interaction Awareness:Cardiology clinics now routinely screen for vitamin K status, expanding clinical testing protocols that drive prescriber familiarity with K2 supplementation protocols.
- Natto-Derived Strain Proliferation:Bacillus subtilis fermentation platforms are scaling across Chinese bioreactor facilities, flooding mid-tier supply with culture-authenticated MK-7 at price points synthetic producers struggle to match.
Market Restraints
- Soy Isoflavone Input Volatility:Natto fermentation depends on non-GMO soybean substrate availability, with Ukrainian supply disruptions and Brazilian crop cycles creating six-month price swings that strain contract manufacturing economics.
- Single-Country Concentration Risk:Over 60 percent of documented clinical trials for K2 bone-health outcomes originate from Japanese research institutions, creating evidentiary geography bias that Western regulators question during novel food dossier reviews.
- MK-4 Therapeutic Substitution:Japanese physicians retain prescription authority for high-dose synthetic MK-4 (menatetrenone) for osteoporosis, limiting nutraceutical MK-7 penetration in the world's most validated K2 market despite superior pharmacokinetics.
Strategic Opportunities
- Indian Preventive Cardiology:The country's escalating coronary artery calcification burden among diabetic populations creates demand for matrix Gla protein activation therapies that K2 suppliers can address through cardiologist education partnerships.
- Cosmeceutical Topical Formulation:Dermocosmetic brands are experimenting with microencapsulated MK-7 for collagen cross-linking claims, opening per-gram pricing multiples that dwarf bulk nutraceutical ingredient economics.
- EU Green Deal Biorefinery Incentives:Fermentation capacity expansions in Portugal and the Netherlands qualify for circular economy subsidies when waste-stream feedstocks replace virgin agricultural inputs, compressing capital recovery timelines for European producers.
Industry Challenges
- Fermentation Scale-Up Expertise Gap:Industrial microbiologists capable of optimizing menaquinone titer in 10,000-liter bioreactors command compensation premiums that strain mid-tier manufacturer operating budgets.
- Dual Dossier Compliance Burden:Structure-function claim substantiation for US FDA notification requires distinct toxicology and clinical evidence packages from EFSA health claim applications, doubling regulatory affairs headcount for transatlantic suppliers.
- Batch-to-Batch MK-7 Purity Variance:Natural fermentation outputs exhibit cis-trans isomer ratio fluctuations that pharmaceutical-grade buyers reject, forcing producers to maintain redundant synthetic capacity for contract pharmaceutical supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitamin K2 Market |
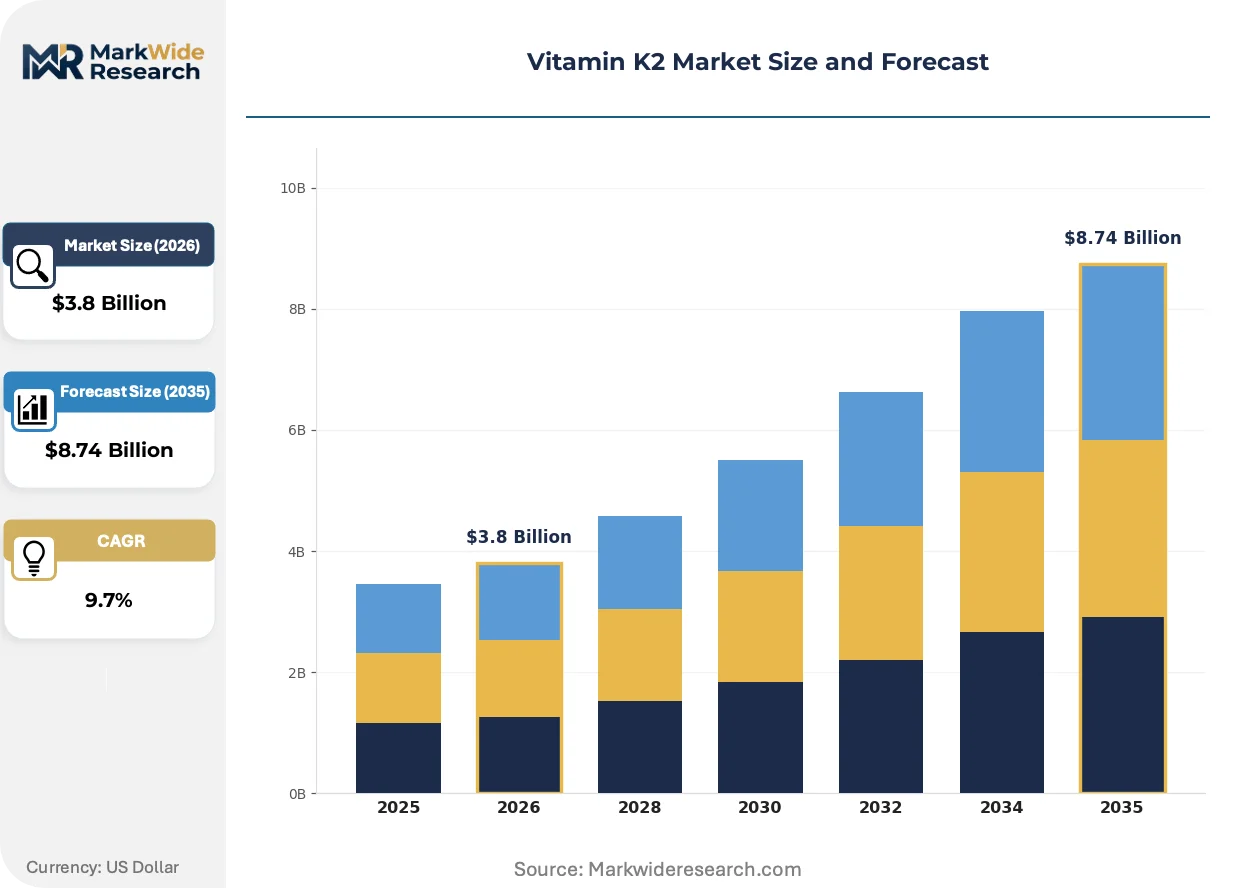
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Fermented, Oil-based Application: Food Supplement, Pharmaceutical, Nutraceutical, Cosmetic Distribution Channel: Online Retail, Health Stores, Pharmacies, Supermarkets End User: Adults, Athletes, Elderly, Health-conscious Consumers |
| Companies Covered | Balchem Corporation, Viridis BioPharma, Gnosis by Lesaffre, J-Oil Mills, Seebio Biotech, Kappa Bioscience, Lesaffre, Nestlé, DSM Firmenich AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitamin K2 Market Strategic Shifts
Continuous fermentation monitoring via Raman spectroscopy is compressing quality assurance cycles, while regulatory divergence between Tokyo and Brussels forces formulation scientists to maintain parallel development tracks for identical active ingredients.
Single-use bioreactor systems with integrated metabolite sensors are rendering obsolete stainless-steel tank infrastructure that requires CIP/SIP validation cycles. Contract manufacturers in Denmark and Singapore are adopting these disposable platforms for K2 production, cutting batch turnaround from fourteen days to four. This shift is rendering obsolete the capital-intensive facility designs that previously anchored supplier moats.
EFSA's 2024 updated guidance on bone-health claim substantiation now mandates fracture-risk reduction endpoints rather than bone-mineral-density proxy measures, forcing K2 marketers to sponsor multi-year clinical trials. The revised evidentiary threshold favors deep-pocketed ingredient suppliers capable of funding 500-plus subject studies. Pharmaceutical-grade MK-7 producers targeting medical food positioning are accelerating dossier preparation ahead of anticipated 2026 enforcement windows.
Direct-to-practitioner distribution models are displacing traditional supplement wholesale channels as functional medicine clinicians seek batch-tested, certificate-of-analysis-verified K2 for patient protocols. Specialized telehealth platforms now curate professional-grade ingredient lines, capturing margin that mass-market retailers previously extracted. This channel migration is most visible in Australia and Canada where TGA and Health Canada natural product number requirements already filter out unverified suppliers.
Vitamin K2 Market Segmentation
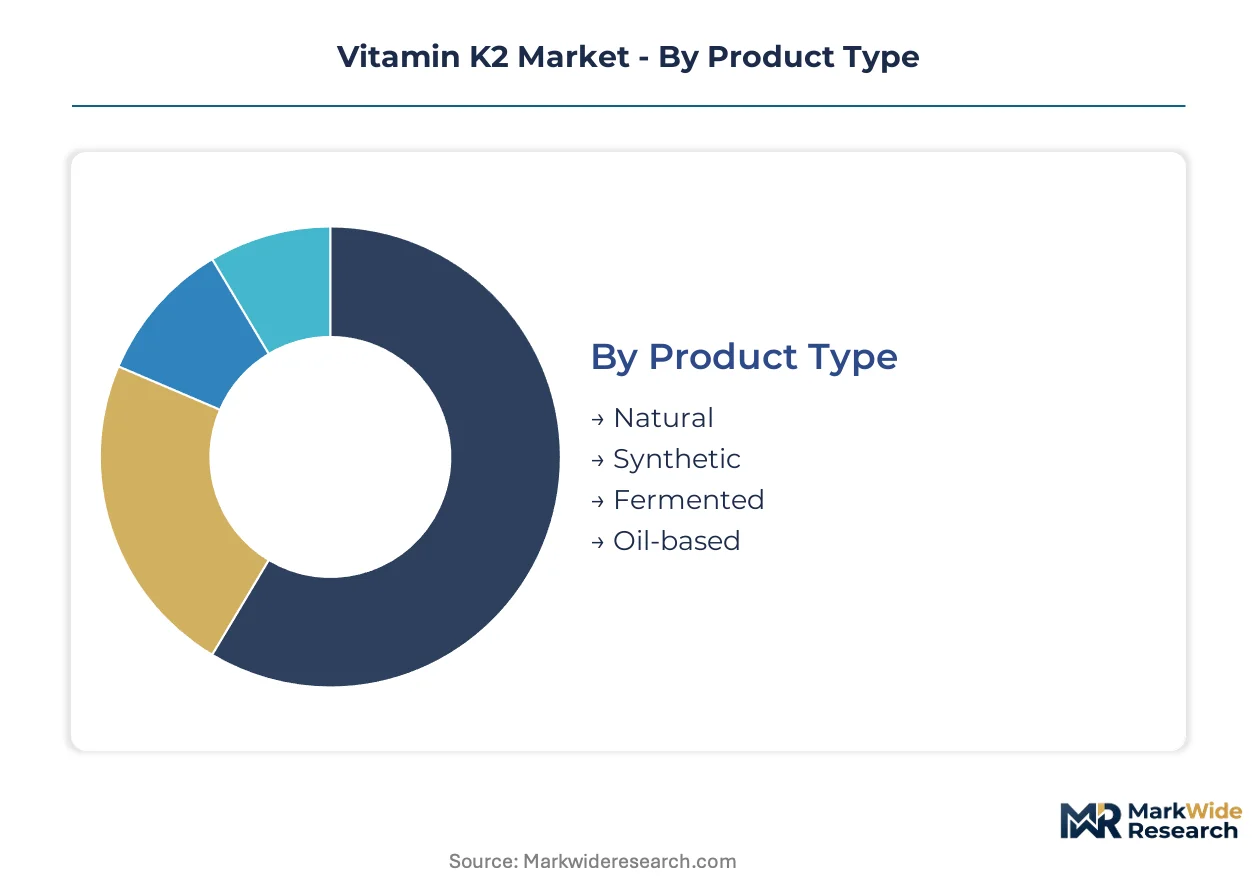
Segmentation in the Vitamin K2 market reflects divergent technical requirements across pharmaceutical-grade buyers seeking cis-trans isomer purity and nutraceutical brands prioritizing fermentation-derived clean labels. Each dimension carries distinct margin structures and regulatory substantiation burdens that shape supplier positioning.
Product Type:
After-sales service intensity varies sharply across production methods, with fermented variants demanding strain-authentication documentation and synthetic grades requiring batch-specific certificates of analysis for pharmaceutical compliance.
- Natural:Derived from animal-sourced MK-4 tissues with shorter serum half-life than MK-7 homologs. Demand concentrates in Japanese prescription markets where physicians retain authority for high-dose osteoporosis protocols, though nutraceutical penetration remains limited by dosing frequency requirements.
- Synthetic:Petrochemical-derived MK-7 and MK-4 produced via organic synthesis with controlled stereochemistry. European pharmaceutical compounders source synthetic MK-7 for medical food positioning ahead of anticipated EFSA enforcement windows tightening bone-health claim substantiation.
- Fermented:Bacillus subtilis-fermented MK-7 from natto cultures commands clean-label premiums.
- Oil-based:Lipid-dissolved formulations enhance fat-soluble bioavailability for softgel manufacturers.
Synthetic grades hold the largest share; momentum sits with fermented variants as EFSA and FDA substantiation requirements tighten.
Application:
Cost tier stratification separates pharmaceutical applications requiring multi-year clinical dossiers from cosmetic formulations capturing per-gram pricing multiples through microencapsulation technology.
- Food Supplement:Mass-market tablets and capsules targeting general wellness consumers with structure-function bone health claims. Australian and Canadian telehealth platforms curate professional-grade lines capturing margin previously extracted by mass-market retailers.
- Pharmaceutical:Prescription and medical-food positioning requiring fracture-risk reduction endpoints rather than bone-mineral-density proxies under updated EFSA guidance.
- Nutraceutical:Condition-specific formulations targeting cardiovascular calcification and bone density.
- Cosmetic:Topical MK-7 for collagen cross-linking claims in dermocosmetic applications.
Food supplements dominate volume; cosmetic applications are climbing the fastest on per-unit pricing expansion.
Distribution Channel:
Customer type fragmentation separates practitioner-directed protocols from self-directed consumer purchasing, with channel migration most visible in regulated markets requiring natural product number verification.
- Online Retail:Direct-to-consumer platforms and specialized telehealth channels. Australian TGA and Health Canada requirements filter unverified suppliers, concentrating share with batch-tested, certificate-of-analysis-verified offerings.
- Health Stores:Specialty retailers serving health-conscious consumers seeking fermented and natural variants.
- Pharmacies:Professional-grade distribution for pharmaceutical and medical-food positioning.
- Supermarkets:Mass-market accessibility for basic supplement formulations.
Pharmacies retain the highest margin concentration; online retail is gaining share fastest through practitioner-directed platform expansion.
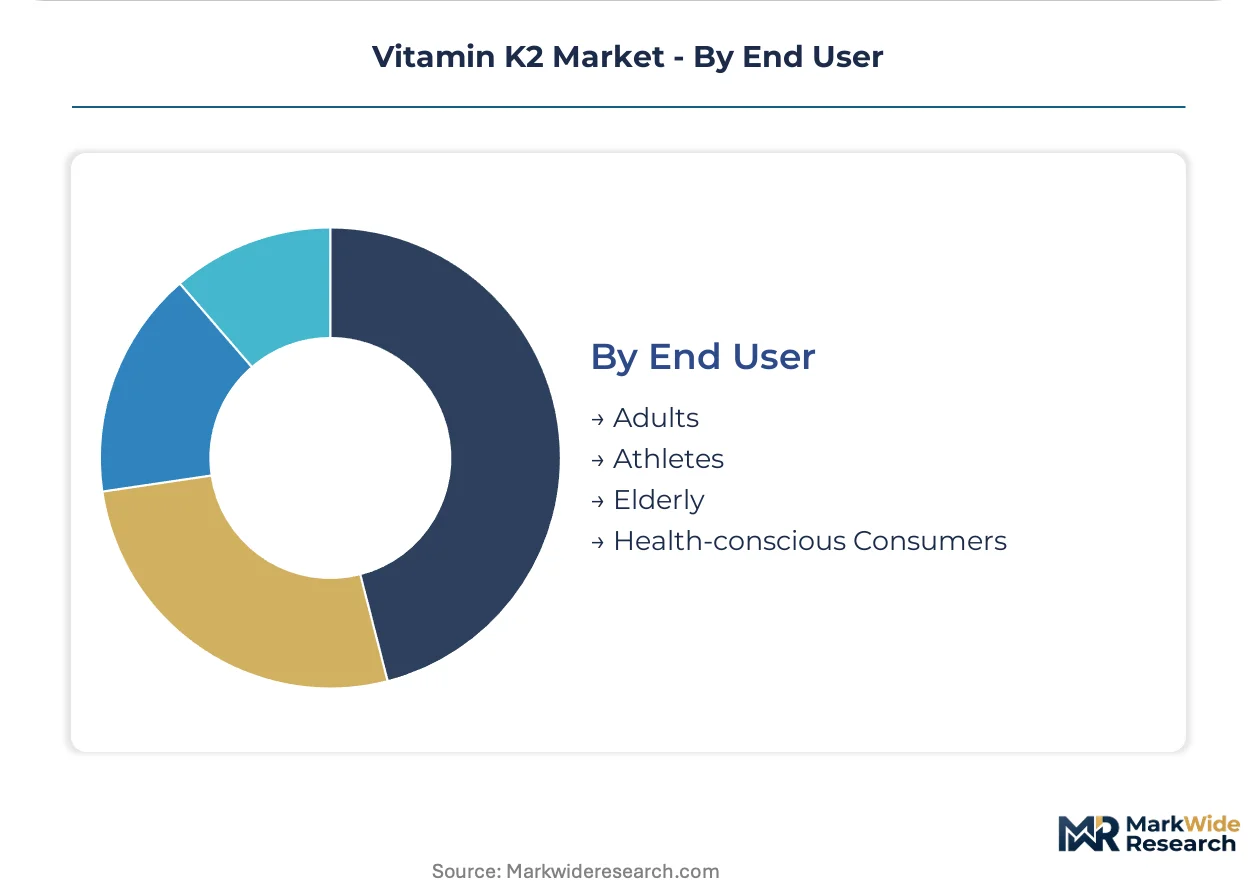
End User:
Volume concentration tracks demographic risk profiles, with elderly populations driving pharmaceutical-grade demand and athletes emerging as an experimental segment for cardiovascular performance claims.
- Adults:General preventive supplementation targeting bone maintenance and cardiovascular health.
- Athletes:Emerging demand for arterial compliance and recovery protocols.
- Elderly:Osteoporosis and coronary artery calcification prevention in aging populations. Indian diabetic demographics create specific demand for matrix Gla protein activation therapies addressable through cardiologist education partnerships.
- Health-conscious Consumers:Clean-label preference driving fermented MK-7 selection.
Elderly users represent the deepest volume pool; health-conscious consumers show the steepest expansion trajectory on clean-label fermentation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's Ministry of Health, Labour and Welfare anchors regulatory validation for bone-density claims through FOSHU standards, creating a template that shapes product development across Asian export markets. Clinical research concentration in Japanese institutions generates evidentiary geography bias that Western regulators scrutinize during novel food dossier reviews. Fermentation capacity expansion in China and bioreactor adoption in Europe are redrawing supply maps.
Japan
Natto-derived MK-7 retains strong cultural and clinical validation among elderly consumers seeking osteoporosis prevention. The Ministry of Health, Labour and Welfare maintains specific FOSHU standards that validate bone-density claims, directly shaping exporter priorities. Kanto region fermentation facilities scale Bacillus subtilis platforms to serve domestic nutraceutical demand and premium export channels.
China
New fermentation capacity coming online fragments supply concentration as bioreactor facilities scale Bacillus subtilis platforms. The National Medical Products Administration oversees novel food ingredient registrations for imported K2 variants. Zhejiang and Jiangsu province manufacturers flood mid-tier supply with culture-authenticated MK-7 at price points challenging historical Japanese and European dominance.
United States
Cardiology clinics now routinely screen for vitamin K status, expanding clinical testing protocols that drive prescriber familiarity with K2 supplementation. The FDA regulates structure-function claims with evidentiary thresholds distinct from European counterparts, forcing dual dossier strategies. California and New Jersey formulation hubs develop practitioner-directed distribution models for functional medicine channels.
India
Escalating coronary artery calcification burden among diabetic populations creates demand for matrix Gla protein activation therapies. The Food Safety and Standards Authority of India governs nutraceutical ingredient imports and health claim substantiation. Maharashtra and Gujarat contract manufacturers explore cardiologist education partnerships to build prescriber familiarity with K2 protocols.
Germany
Medical food positioning for pharmaceutical-grade MK-7 accelerates ahead of anticipated EFSA enforcement windows tightening bone-health claim substantiation. The European Food Safety Authority mandates fracture-risk reduction endpoints rather than bone-mineral-density proxies. Bavaria and North Rhine-Westphalia fermentation specialists qualify for EU Green Deal biorefinery incentives when waste-stream feedstocks replace virgin agricultural inputs.
Vitamin K2 Market Competitive Environment
Fermentation specialists and synthetic producers split the market between clean-label premiums and cost-controlled pharmaceutical supply. Tiered supplier concentration reflects divergent technical requirements: pharmaceutical-grade buyers demand cis-trans isomer purity while nutraceutical brands prioritize fermentation-derived credentials. Strategic archetypes include backward-integrated fermentation platforms, synthetic purity standard-setters, and broad nutritional ingredient portfolios securing multi-year supply contracts. Dominant competitive moves center on bioreactor capacity expansion and regulatory dossier preparation for transatlantic market access.
Within the fermentation-anchored tier, Gnosis by Lesaffre and Kappa Bioscience exemplify divergent positioning strategies. Gnosis by Lesaffre, a Lesaffre S.A. entity, represents backward integration into proprietary fermentation strains. Kappa Bioscience occupies a position emphasizing synthetic MK-7 purity standards that appeal to pharmaceutical-grade buyers. DSM Firmenich AG anchors the diversified nutritional ingredients archetype, leveraging broader portfolios to secure supply relationships with global supplement brands. Seebio Biotech and Viridis BioPharma sit within the emerging Asian fermentation capacity cluster.
| Leading Market Players |
|---|
| Balchem Corporation |
| Viridis BioPharma |
| Gnosis by Lesaffre |
| J-Oil Mills |
| Seebio Biotech |
| Kappa Bioscience |
| Lesaffre |
| Nestlé |
| DSM Firmenich AG |
| Others |
Value Chain & Pricing Dynamics
Bioreactor overcapacity in Zhejiang and Jiangsu provinces is compressing synthetic MK-7 margins as Chinese fermentation facilities flood mid-tier supply, forcing Japanese and European incumbents toward premium strain-authenticated positioning or pharmaceutical-grade purity arbitrage.
Pricing Analysis
Chinese-Japanese price spreads now exceed threefold for equivalent MK-7 titer, with contract-based long-term offtake dominating pharmaceutical procurement and spot purchasing governing nutraceutical spot markets. Price differentiation rests on cis-trans isomer certification grade and FOSHU-equivalent documentation depth. Cost compression in fermented variants is intensifying because Bacillus subtilis platform scale-up has outpaced quality-consolidation timelines. Mass-market supplement brands exhibit highest price sensitivity; medical food compounders and cosmetic formulators show least.
Supply Chain Analysis
Tariff exposure between China and Western pharmaceutical markets dominates supply chain risk calculus as fermentation capacity regionalizes. Geographic supply concentrates in China, Japan, and Germany, with raw material dependencies on non-GMO soybean substrate, pharmaceutical-grade carrier oils, and sterilized fermentation media. Single-source vulnerability around Ukrainian soy isoflavone inputs creates six-month price cycle exposure. Distribution runs through direct-to-practitioner telehealth platforms and specialized nutraceutical distributors rather than mass-market retail wholesale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Vitamin K2 market sits in early-cycle expansion as cardiologist screening protocols for matrix Gla protein activation drive prescriber familiarity and clinical testing penetration in preventive cardiology.
For Market Incumbents: Entrench proprietary fermentation strain control and backward integration into Bacillus subtilis culture banks to defend against Chinese bioreactor cost undercutting. Prioritize EFSA fracture-risk reduction dossier completion ahead of enforcement window tightening. Lock multi-year supply contracts with global supplement brands before quality-verification requirements filter unverified suppliers from regulated channels. For New Entrants and Emerging Players: Establish a beachhead in Indian preventive cardiology through cardiologist education partnerships targeting diabetic coronary artery calcification protocols. White-space concentrates in dermocosmetic microencapsulated MK-7 formulations where per-gram pricing multiples dwarf bulk nutraceutical economics. Pursue cosmeceutical brand co-development agreements as the most penetrable entry vector. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across single-use bioreactor platforms as disposable systems displace stainless-steel infrastructure. Long-term viability favors acquisition targets with validated pharmaceutical-grade purity capabilities and dual-dossier regulatory affairs infrastructure spanning FDA notification and EFSA health claim pathways. Watch EFSA bone-health claim enforcement timing as the critical demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Strain Development | Backward integration into Bacillus subtilis culture banks secures clean-label differentiation against synthetic competitors. |
| EFSA Dossier Preparation | Fracture-risk reduction endpoint studies ahead of enforcement windows lock pharmaceutical-grade positioning. |
| Single-Use Bioreactor Adoption | Disposable platform conversion cuts batch turnaround from fourteen days to four, collapsing capital recovery timelines. |
| Practitioner-Direct Distribution | Telehealth platform partnerships capture margin previously extracted by mass-market retail wholesale channels. |
| Cosmeceutical Formulation Partnership | Microencapsulated MK-7 collagen cross-linking claims open pricing multiples unattainable in bulk nutraceutical supply. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with fermentation platform engineers, regulatory affairs directors at nutraceutical compounders, cardiology clinic procurement leads, and cosmetic formulation scientists; and secondary validation through EFSA guidance documents, FDA structure-function claim notifications, FOSHU registration databases, and customs trade flow records. Bottom-up capacity modeling triangulated against top-down demand segmentation across pharmaceutical, nutraceutical, and cosmetic application tiers.
Forecast inputs considered production method splits, purity grade stratification, and regional regulatory cluster adoption curves across the projection horizon. Segmentation dimensions modeled include product type, application vertical, distribution channel architecture, and end-user demographic risk profile. CAGRs were derived from capacity expansion timelines, clinical trial publication velocity, and prescriber protocol adoption rates in preventive cardiology and osteoporosis management.
Stress conditions across soybean substrate price volatility, EFSA enforcement timing, and anticoagulant interaction pharmacovigilance were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding fermentation scale-up success rates and regulatory dossier approval trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Camu Camu Extract Market
Nutritional Supplements
Effervescent Product Market
Nutritional Supplements
Australia Whey Protein Market
Nutritional Supplements
Medium Chain Triglyceride (MCT) Diet Market
Nutritional Supplements
Bee Pollen Supplements Market
Nutritional Supplements
Micronutrient Powders (Mnps) Market
Nutritional Supplements
Forskolin Market
Nutritional Supplements
Mineral Supplements Market
Nutritional Supplements
Spirulina Purple Blend Market
Nutritional Supplements
Pulse Protein Market
Nutritional Supplements
Middle-East and Africa Dietary Supplement Market
Nutritional Supplements
Global Ashwagandha Extract Market
Nutritional Supplements
Fiber Supplements Market
Nutritional Supplements
Nutritional Lipids Market
Nutritional Supplements
Plant Based Protein Supplements Market
Nutritional Supplements
Middle East Protein Market