
 Whey Protein Powder Market | 2026-2036
Whey Protein Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Whey Protein Powder Market Outlook
E-commerce and direct-to-consumer subscription models is rewriting how whey protein reaches end users, bypassing traditional retail markups and building recurring revenue streams. Glanbia plc leverages its vertically integrated dairy supply chain to control ingredient quality from farm to finished powder. Fonterra Co-operative Group Ltd. anchors its competitive position through New Zealand-sourced milk solids and bulk ingredient supply contracts with global brands. Arla Foods differentiates through cooperative ownership structures that stabilize farmer pricing and secure long-term whey streams.
Whey protein powder consists of globular proteins isolated from liquid whey, a cheese manufacturing byproduct, typically containing beta-lactoglobulin, alpha-lactalbumin, and immunoglobulins with protein concentrations ranging from 25% to 90% depending on processing grade. Manufacturers employ ion exchange or microfiltration to concentrate proteins, with ultrafiltration yielding whey protein concentrate and cross-flow microfiltration producing isolate grades exceeding 90% protein content. Concentrate and isolate categories dominate current production volumes, while hydrolysate commands premium positioning in clinical nutrition and infant formula applications where pre-digested proteins reduce allergenic response. Athletes and bodybuilders remain the core consumer base, though fitness enthusiasts represent the fastest-expanding target segment as mainstream consumers adopt protein supplementation for weight management and general wellness.
FDA oversees protein content labeling and health claim substantiation in the United States, while EFSA governs nutrition and health claims across European markets, with both agencies intensifying scrutiny of amino acid profile disclosures and bioavailability assertions. FSSAI in India and China's SAMR are implementing stricter dairy import standards and protein fortification guidelines that reshape supplier qualification requirements. Stakeholders must monitor evolving clean label demands and alternative protein competition to calibrate portfolio allocation between commodity whey and value-added nutritional formulations.
Market Dynamics
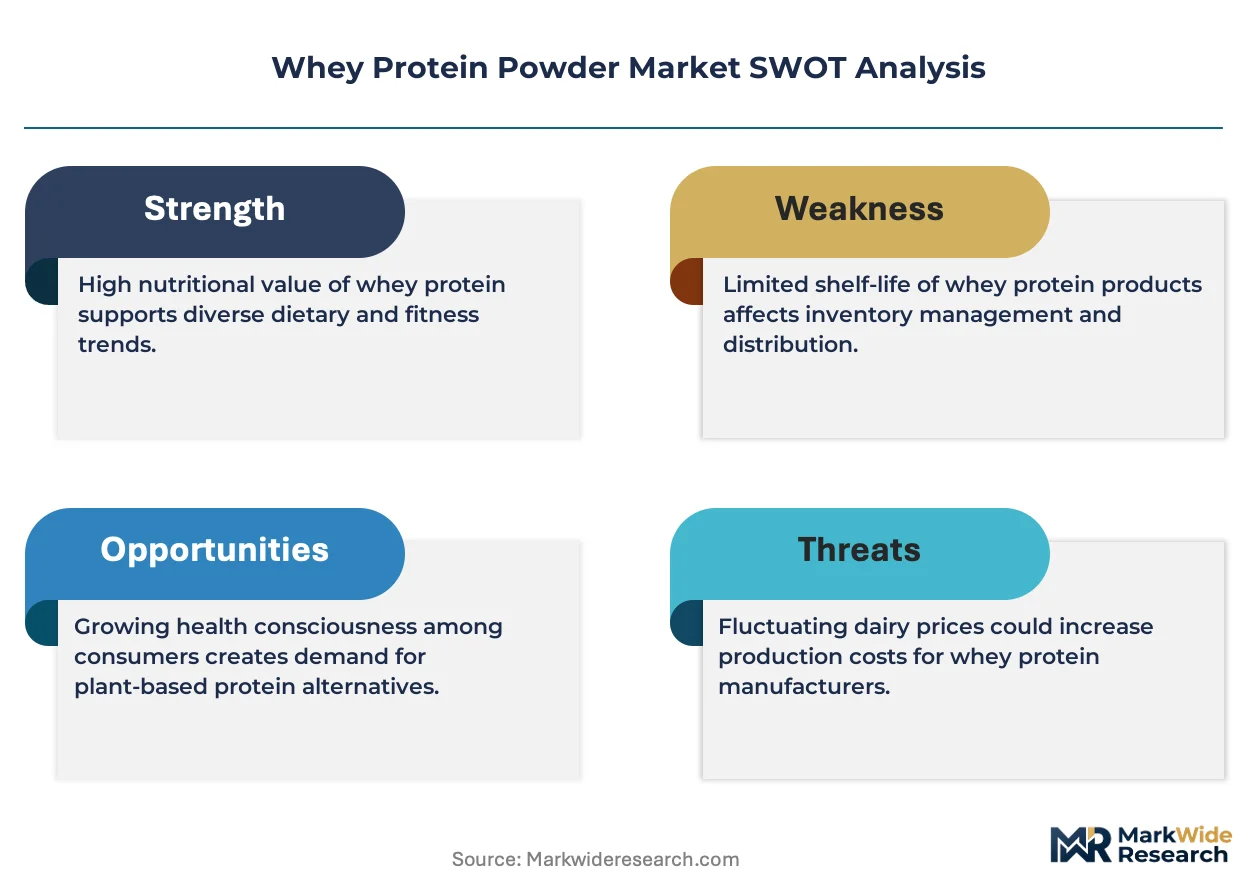
The whey protein powder market is being restructured by the tightening of protein content substantiation requirements under FDA and EFSA frameworks, which is forcing manufacturers to invest in amino acid profiling and bioavailability testing infrastructure.
Growth Catalysts
- FSSAI fortification mandates:India's mandatory protein fortification guidelines in school nutrition and public health programs are creating institutional procurement channels for whey concentrate suppliers.
- Cross-flow microfiltration adoption:This membrane separation technology is enabling 90%+ protein isolate production with preserved bioactive fractions, opening clinical nutrition applications.
- Germany's sports nutrition retail density:The country's developed gym infrastructure and pharmacy distribution networks sustain premium whey product consumption at scale.
Market Restraints
- Cheese whey supply concentration:Over 70% of global liquid whey originates from cheese production concentrated in the United States, New Zealand, and EU dairy belts, creating feedstock vulnerability.
- EFSA health claim friction:The agency's strict substantiation requirements for muscle maintenance and satiety claims limit marketing language and compress differentiation space.
- Pea and fava protein substitution:Plant-based isolates are capturing flexitarian consumers in Northern Europe and North American coastal markets, eroding addressable demand.
Strategic Opportunities
- China's SAMR import standard evolution:Stricter dairy protein registration requirements are raising barriers that favor established suppliers with testing infrastructure and regulatory affairs capabilities.
- Ready-to-drink beverage integration:Functional beverage manufacturers are incorporating whey isolates into shelf-stable protein waters, creating new formulation partnerships.
- Subscription direct-to-consumer channels:Recurring revenue models bypass retail markups and build proprietary customer data assets for flavor and format optimization.
Industry Challenges
- Chromatography and mass spectrometry talent scarcity:Amino acid assay validation and protein identity testing require specialized analytical chemists in short supply across contract laboratories.
- Dual certification timeline compression:Simultaneous pursuit of Informed Sport and NSF Certified for Sport programs extends product launch cycles by 4-6 months.
- Legacy ERP integration with batch genealogy systems:Dairy processors face friction connecting farm-to-finished-powder traceability platforms with existing manufacturing execution software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Whey Protein Powder Market |
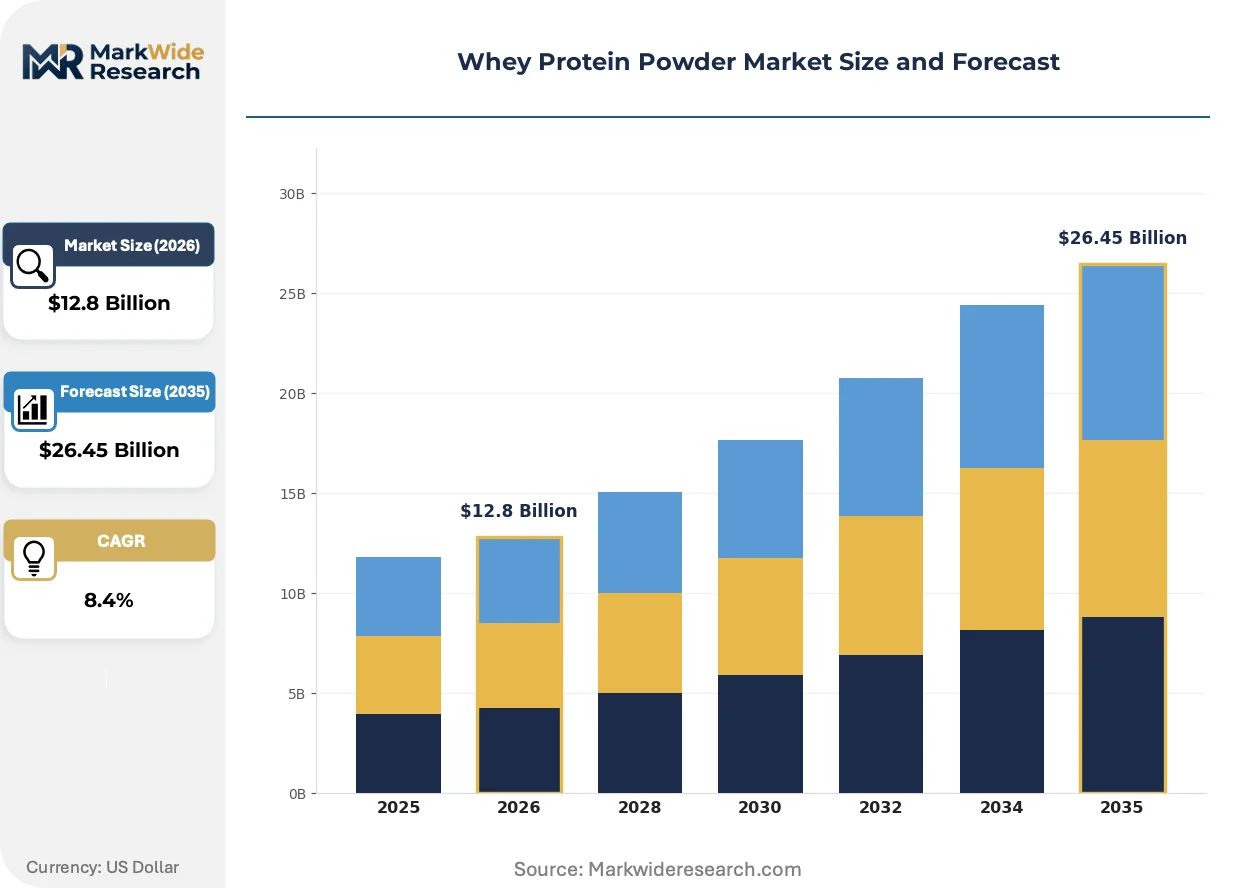
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrate, Isolate, Hydrolysate, Native Target Consumer: Athletes, Fitness Enthusiasts, Vegans, Bodybuilders Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Gyms Packaging Type: Bags, Tubs, Sachets, Canisters |
| Companies Covered | Hilmar Cheese Company, Inc., Saputo Inc., Glanbia plc, Fonterra Co-operative Group Ltd., Arla Foods, Carbery Group, Lactalis Ingredients, Milk Specialties, Agropur, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Whey Protein Powder Market Strategic Shifts
Membrane processing advances and regulatory data requirements are converging to reshape how whey proteins are manufactured, certified, and brought to market across sports nutrition and clinical applications.
Cross-flow microfiltration combined with ceramic membrane cascades is rendering obsolete traditional ion exchange methods that denature bioactive whey fractions. Clinical nutrition formulators and premium sports brands are adopting ceramic-filtered isolates at accelerated procurement cycles. The technology is compressing cost differentials between concentrate and isolate grades while preserving immunoglobulin content for immune-positioned products.
EFSA's 2023 updated guidance on protein quality assessment and PDCAAS calculation methodology is forcing reformulation of products carrying muscle maintenance claims. Manufacturers must now submit amino acid digestibility data from human clinical trials rather than rat assays. Sports nutrition brands targeting EU distribution are reformulating with whey hydrolysates to secure favorable protein quality scores.
Direct-to-consumer subscription models are displacing brick-and-mortar sports nutrition retail as the primary customer acquisition channel. Specialty e-commerce platforms and brand-owned storefronts are capturing repeat purchase behavior through personalized flavor rotation and auto-shipment flexibility. This channel shift is most visible in the United States and United Kingdom, where gym-goers increasingly discover products through fitness influencer content rather than in-store sampling.
Whey Protein Powder Market Segmentation
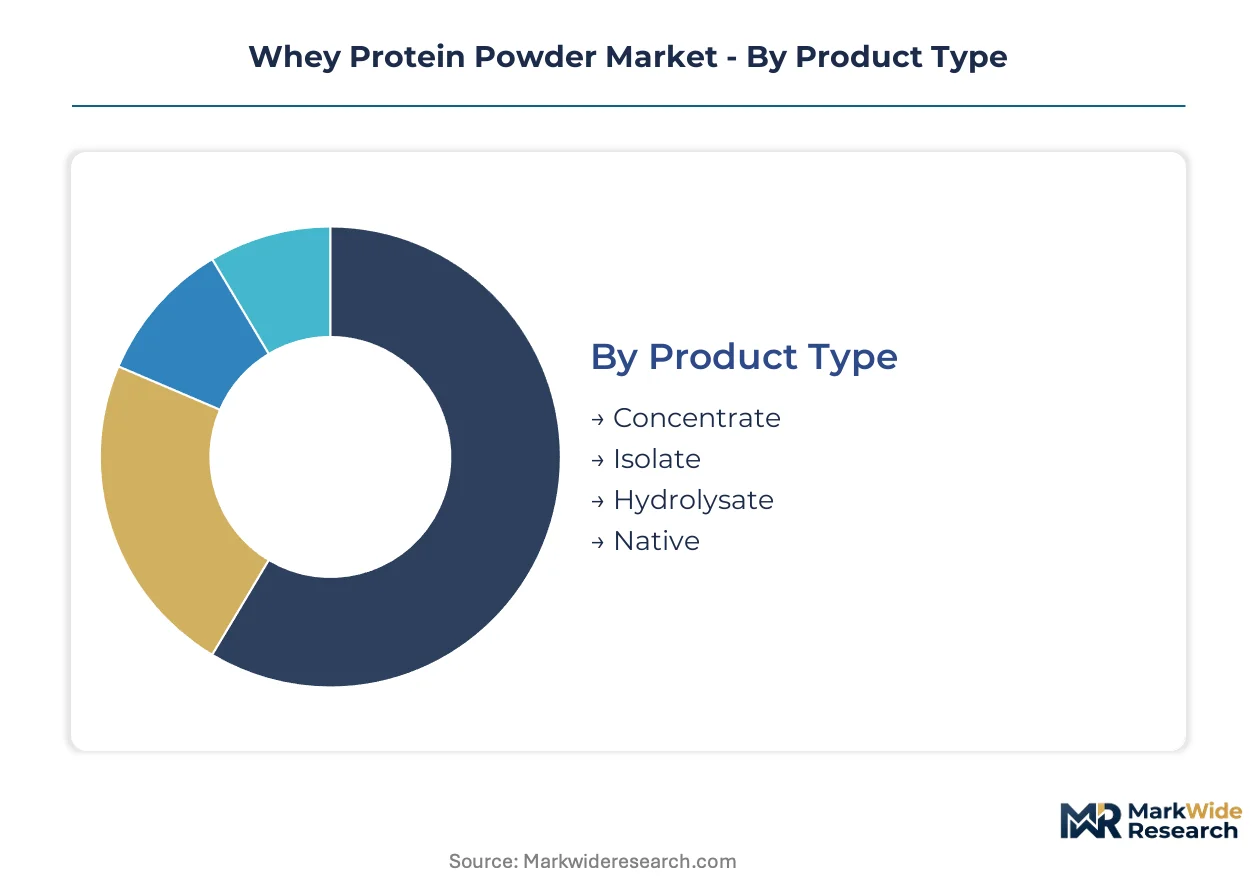
Whey protein segmentation reveals how processing technology, consumer identity, and channel economics create distinct commercial battlegrounds. Manufacturers must align product specifications with precise usage occasions and purchase behaviors to capture margin.
Product Type:
The maturity spectrum runs from commodity-grade concentrates to precision-engineered hydrolysates, with processing intensity determining application access and pricing power.
- Concentrate:Whey protein concentrate retains 25-80% protein content with residual lactose and lipids, making it the workhorse ingredient for mass-market sports nutrition powders and bakery fortification. Demand concentrates in private-label protein powders sold through German pharmacy chains and US mass retail, where cost-per-serving drives procurement decisions.
- Isolate:Cross-flow microfiltration yields 90%+ protein isolates with minimal lactose, opening formulation partnerships with functional beverage manufacturers in China and clinical nutrition suppliers serving diabetic and renal patient populations. Isolate commands premium positioning in ready-to-drink protein waters where clarity and shelf stability are non-negotiable.
- Hydrolysate:Enzymatically pre-digested proteins with reduced allergenic response, primarily specified for infant formula and post-surgical clinical nutrition where rapid amino acid absorption is clinically indicated.
- Native:Undenatured whey extracted directly from milk rather than cheese byproduct, preserving bioactive immunoglobulins for immune-positioned premium supplements targeting affluent wellness consumers in Japan and South Korea.
Concentrate handles the majority of throughput; hydrolysate is the fastest mover on share as clinical nutrition formulators seek faster gastric emptying profiles.
Target Consumer:
Customer archetypes stratify by performance ambition, dietary restriction, and training frequency, with each segment demanding differentiated messaging and product formats.
- Athletes:Competitive and recreational athletes pursuing performance optimization through timed protein intake around training windows, with demand clustering in US collegiate sports programs and Australian professional team nutrition contracts where Informed Sport certification is mandatory.
- Fitness Enthusiasts:Mainstream gym members incorporating protein supplementation for body composition management, representing the steepest expansion trajectory as boutique fitness studio penetration deepens in Chinese tier-one cities and UK suburban markets.
- Vegans:Plant-forward consumers seeking whey alternatives, though this segment paradoxically drives whey innovation through hybrid formulations that blend dairy and pea proteins to improve amino acid completeness.
- Bodybuilders:High-volume protein consumers prioritizing cost-per-gram and flavor variety, sustaining bulk bag formats and direct-to-consumer subscription models with monthly flavor rotations.
Fitness enthusiasts now outnumber bodybuilders in absolute headcount; athletes retain the highest per-capita spend and certification requirements.
Distribution Channel:
Channel economics are restructuring as digital-native discovery displaces physical retail sampling, with recurring revenue models capturing lifetime value previously lost to transactional purchase patterns.
- Online Retail:Amazon, brand-owned storefronts, and specialty fitness e-commerce platforms capture auto-ship subscriptions and influencer-driven discovery, with US and UK consumers showing highest propensity for monthly replenishment programs.
- Supermarkets:Mass retail placement in Walmart, Tesco, and Carrefour reaches occasional users seeking convenience, though shelf space compression limits flavor and format variety compared to digital channels.
- Specialty Stores:GNC, Vitamin Shoppe, and European pharmacy chains serve informed buyers seeking staff consultation and immediate availability, particularly in Germany where pharmacist recommendations carry significant weight.
- Gyms:Point-of-workout vending and pro-shop sales capture impulse replenishment, with Equinox and Life Time Fitness in the US and PureGym in the UK operating proprietary retail ecosystems.
Online retail commands the fastest share gain; specialty stores maintain the highest conversion rates for premium isolate and hydrolysate grades.
Packaging Type:
Format selection reflects usage occasion granularity, from daily home consumption to travel portability and sampling economics.
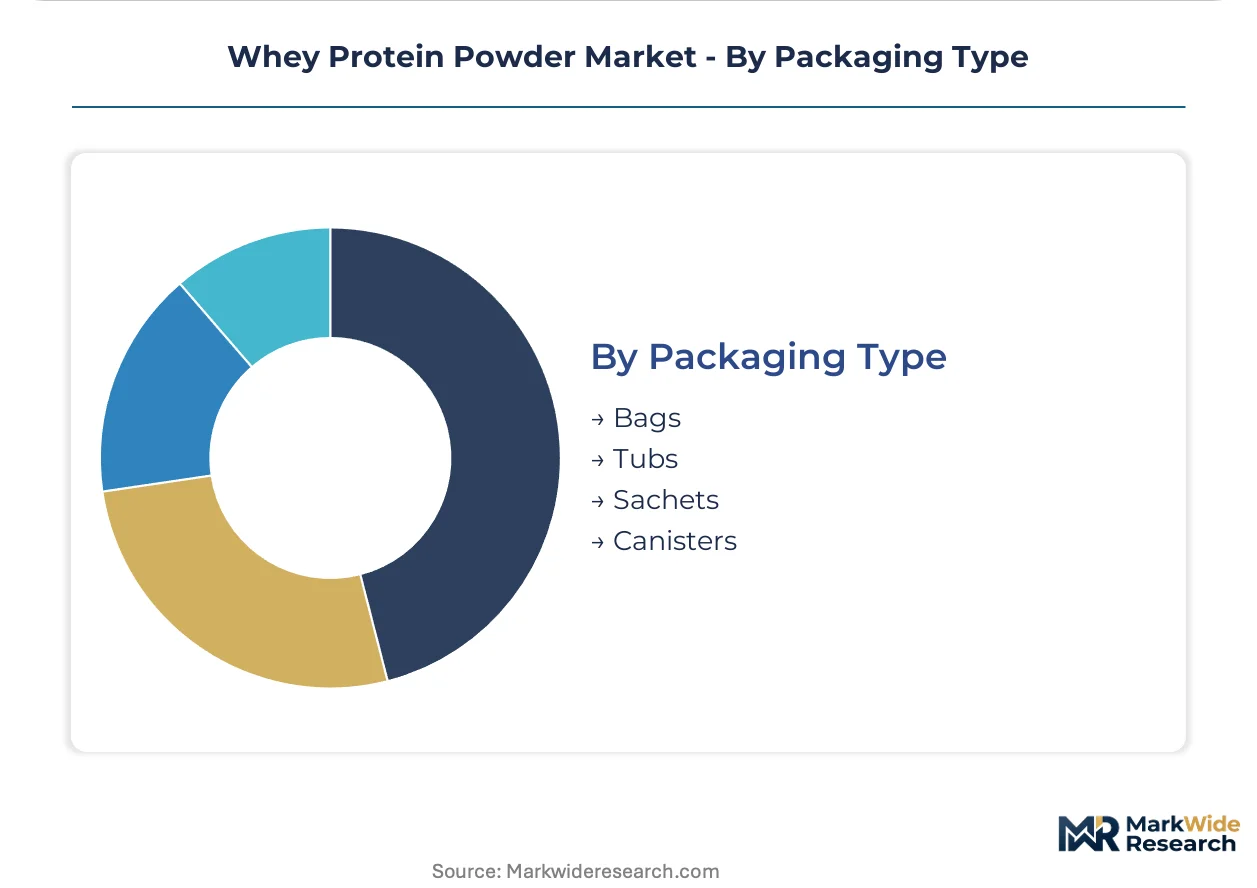
- Bags:Flexible multi-kilogram bags dominate bodybuilder and family household purchasing in the US and Australia, minimizing per-gram packaging cost while requiring consumer investment in storage infrastructure.
- Tubs:Rigid plastic containers with scoop retention dominate retail shelves and online subscription programs across all major markets, balancing protection, portability, and brand billboard presence.
- Sachets:Single-serve packets drive trial acquisition through influencer seeding, hotel fitness center placement, and airline premium cabin amenities, with highest penetration in Japanese convenience retail.
- Canisters:Metal and composite canisters occupy premium positioning in gift sets and pharmacy channels across Continental Europe, conveying durability and quality associations that justify price premiums.
Tubs handle the majority of throughput; sachets are expanding most quickly as sampling economics improve through digital-native brand launches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's liquid bulk terminals anchor European whey protein import flows, while Union Pacific's refrigerated rail corridors connect Midwest cheese production to West Coast export facilities. These infrastructure assets underpin regional supply security.
United States
Collegiate sports nutrition contracts and military procurement programs drive institutional whey concentrate demand. FDA protein labeling substantiation requirements tighten amino acid disclosure standards. Wisconsin's Fox Valley cheese belt supplies liquid whey feedstock to processing clusters in Green Bay and La Crosse.
Germany
Pharmacy chain distribution networks and boutique fitness studio penetration sustain premium isolate consumption. EFSA health claim substantiation protocols constrain muscle maintenance marketing language. North Rhine-Westphalia's Ruhr Valley hosts sports nutrition formulation labs serving Benelux markets.
China
Tier-one city gym expansion and cross-border e-commerce subscription models accelerate whey isolate adoption. SAMR dairy protein import registration requirements raise supplier qualification barriers. Yangtze River Delta free trade zones concentrate ready-to-drink beverage co-manufacturing capacity.
India
FSSAI mandatory protein fortification in school nutrition programs creates institutional procurement channels. Central food safety authority import testing protocols reshape dairy ingredient qualification timelines. Maharashtra's Pune-Ahmednagar corridor emerges as contract manufacturing hub for domestic sports nutrition brands.
Australia
Professional team nutrition contracts and influencer-driven direct-to-consumer channels expand isolate demand. TGA therapeutic goods classification affects clinical nutrition positioning claims. Victoria's Gippsland dairy region supplies native whey streams to premium supplement exporters.
Whey Protein Powder Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying bulk isolates and concentrates to finished goods manufacturers. The vendor base stratifies between dairy cooperative giants with captive milk supply and independent processors purchasing liquid whey on spot markets. Three archetypes dominate: vertically integrated dairy cooperatives controlling farm-to-powder traceability, independent whey fractionators serving private-label brands, and sports nutrition houses outsourcing protein sourcing. Competitive moves concentrate on membrane technology licensing partnerships and dual-certification pursuit for elite athletic channels.
Among cooperative-structured suppliers, Fonterra Co-operative Group Ltd. and Arla Foods exemplify the farm-gate control archetype, securing long-term whey streams through member ownership models. Glanbia plc occupies a position representing the integrated processor tier, bridging dairy ingredient supply and finished sports nutrition formulation. These three anchors illustrate how governance structure and supply chain positioning differentiate competitive standing in a market where feedstock security determines margin stability.
| Leading Market Players |
|---|
| Hilmar Cheese Company, Inc. |
| Saputo Inc. |
| Glanbia plc |
| Fonterra Co-operative Group Ltd. |
| Arla Foods |
| Carbery Group |
| Lactalis Ingredients |
| Milk Specialties |
| Agropur, Inc. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in European whey processing facilities compresses supplier margins while simultaneously expanding pricing flexibility for bulk concentrate buyers negotiating multi-year offtake agreements. This utilization dynamic forces processors to prioritize high-margin isolate grades and clinical nutrition contracts over commodity sports nutrition volumes.
Pricing Analysis
Volume-discount tiering structures separate institutional procurement contracts from direct-to-consumer subscription pricing, with the former anchored to Fonterra and Glanbia bulk supply agreements and the latter floating on flavor innovation premiums. Price differentiation hinges on certification grade—Informed Sport and NSF Certified for Sport tiers command substantial premiums—and geographic delivery cost differentials between New Zealand-sourced and EU-origin material. Pricing pressure stems from pea protein substitution in Northern European flexitarian segments, eroding whey addressable demand. Private-label protein powders sold through German pharmacy chains exhibit highest price sensitivity, while clinical nutrition formulators in China show least sensitivity due to regulatory qualification barriers.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for whey isolate exporters serving SAMR-registered product lines. Feedstock concentration draws from the United States, New Zealand, and Germany, with over 70% of global liquid whey originating from cheese production in these three markets. Raw material dependencies rest on membrane filtration equipment, ceramic membrane cascades, and specialized chromatography reagents for amino acid profiling. Single-source vulnerability concentrates in cross-flow microfiltration technology licensing held by limited equipment vendors. Distribution runs through Union Pacific refrigerated rail corridors to West Coast export facilities, with Port of Rotterdam liquid bulk terminals anchoring European import flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated direct-to-consumer subscription platforms that aggregate demand and disintermediate traditional sports nutrition retail, fragmenting supplier pricing power across fragmented brand portfolios.
For Market Incumbents: Entrench feedstock security through cooperative ownership structures that stabilize farmer pricing, mirroring Arla Foods and Fonterra models. Deepen backward integration into membrane processing technology to preserve immunoglobulin content for immune-positioned premium tiers. Defensive investment in dual Informed Sport and NSF certification infrastructure protects against emerging plant-protein entrants targeting elite athletic channels. For New Entrants and Emerging Players: Pursue white-space opportunities in ready-to-drink protein waters where formulation partnerships with Chinese functional beverage manufacturers remain underdeveloped. India's FSSAI-mandated school nutrition programs offer the most penetrable institutional procurement channel for whey concentrate suppliers lacking established brand equity. A direct-to-consumer subscription go-to-market angle bypasses retail markups and builds proprietary customer data assets. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among sports nutrition houses operating proprietary e-commerce storefronts with auto-ship flexibility. Long-term viability across the analysis window favors processors with captive milk supply and membrane technology licensing rather than spot-market whey purchasers. Acquisition target archetype: independent whey fractionators serving private-label brands with underutilized ceramic microfiltration capacity. Watch cross-border e-commerce subscription growth rates in Chinese tier-one cities as inflection indicator for isolate demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Technology Licensing | Ceramic microfiltration partnerships preserve bioactive fractions for clinical nutrition applications. |
| Dual Certification Investment | Simultaneous Informed Sport and NSF pursuit opens elite athletic procurement channels. |
| Direct-to-Consumer Launch | Brand-owned storefronts bypass retail markups and capture recurring revenue streams. |
| Backward Integration into Farm Supply | Cooperative ownership structures stabilize whey feedstock pricing and traceability. |
| Regulatory Affairs Capability Buildout | SAMR and FSSAI registration expertise raises barriers against unqualified competitors. |
Study Parameters
Operator-level perspectives from whey processing plant managers, sports nutrition brand procurement directors, clinical nutrition formulators, and membrane technology equipment vendors anchored the qualitative base. Primary interviews combined with secondary validation from FDA protein labeling guidance documents, EFSA health claim substantiation protocols, FSSAI fortification mandates, and Fonterra and Glanbia SEC filings. Bottom-up volume modeling triangulated against top-down market sizing across concentrate, isolate, hydrolysate, and native product grades.
Scenario-bracketing framed optimistic and conservative demand trajectories across the projection horizon, with segmentation dimensions spanning processing technology, target consumer archetype, distribution channel economics, and regional regulatory cluster. CAGRs derived from protein fortification policy implementation timelines, gym penetration curves in Chinese tier-one cities, and plant-protein substitution elasticity estimates in Northern European markets. Forecast inputs incorporated membrane processing capacity expansion announcements and cross-border e-commerce subscription growth patterns.
Sensitivities concentrate around SAMR import registration timeline extensions, EFSA protein quality assessment methodology revisions, and ceramic membrane equipment supply bottlenecks. Forecasts reflect assumptions about regulatory enforcement intensity and consumer willingness-to-pay for certified sports nutrition grades. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Milk Powder for Pregnant Women Market
Nutritional Supplements
North America Digestive Health Supplements Market
Nutritional Supplements
Vegan Supplements Market
Nutritional Supplements
Tea Tree Oil Market
Nutritional Supplements
Middle East Protein Market
Nutritional Supplements
Global Hemp Protein Market
Nutritional Supplements
Forskolin Market
Nutritional Supplements
Fish Collagen Peptides Market
Nutritional Supplements
Wellness Supplements Market
Nutritional Supplements
Global Natural Health Supplements Market
Nutritional Supplements
Andro Supplements Market
Nutritional Supplements
Nutritional Food and Drink Market
Nutritional Supplements
Activated Charcoal Supplement Market
Nutritional Supplements
High-Concentrated Protein Market
Nutritional Supplements
US Nutraceuticals Market
Nutritional Supplements
Europe Nutrition and Supplements Market