
 Global Garcinia Market | 2026-2036
Global Garcinia Market Size, Share, and Industry Trends Forecast 2026-2036
Global Garcinia Market Foresight
Asset-light contract manufacturing and third-party leasing of extraction facilities is reshaping competitive entry in garcinia cambogia supply chains. NOW Foods leverages backward integration into raw material sourcing in Southeast Asia. Himalaya Herbal Healthcare anchors its position through Ayurvedic heritage and pharmaceutical-grade manufacturing standards. NutraScience Labs differentiates via private-label partnerships with wellness centers across North America.
Garcinia cambogia denotes a tropical fruit species whose rind contains hydroxycitric acid (HCA), typically standardized to 50-60% concentration in commercial extracts through solvent extraction and spray-drying processes; the compound functions primarily as a citrate lyase inhibitor for lipid metabolism modulation in dietary supplements. Extract powder formulations lead volume due to bulk manufacturing economies and blending flexibility for capsule and tablet finished goods. Online retail channels represent the fastest-growing sales pathway, driven by direct-to-consumer subscription models and influencer marketing conversion. Weight management applications occupy the largest margin pool, though mood enhancement positioning shows emerging traction among stress-adjacent wellness consumers.
FDA dietary supplement GMP enforcement and FTC substantiation requirements govern product claims and manufacturing quality in the United States, while India's FSSAI mandates botanical identity testing and heavy metal limits for domestic and export-bound garcinia extracts. The EU's EFSA novel food evaluation pathway and REACH compliance for extraction solvents create additional market access conditions for European-bound suppliers. Stakeholders must monitor evolving HCA standardization thresholds and adapt label claim strategies as regulatory scrutiny on weight-loss supplement efficacy intensifies across multiple jurisdictions.
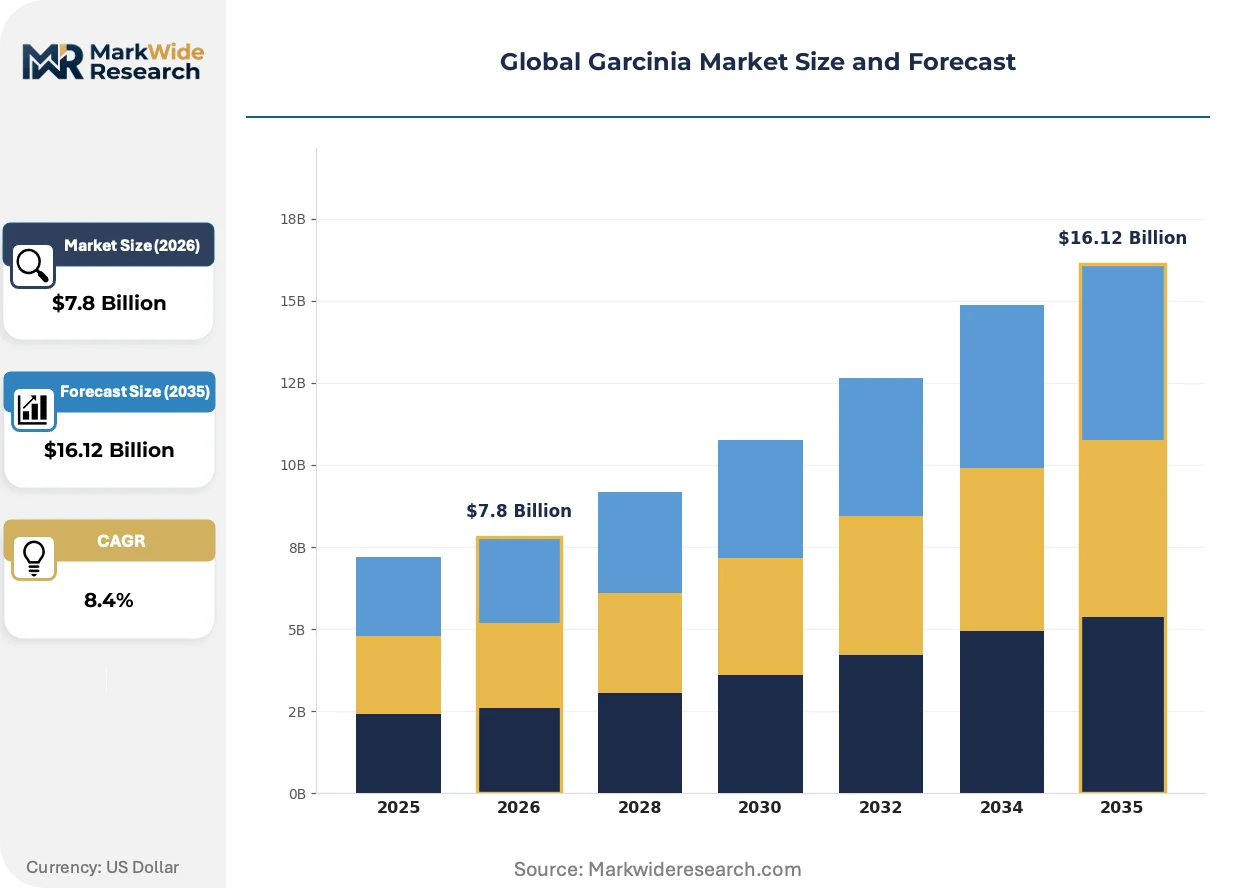
Market Dynamics
India's PLI scheme for botanical extraction is redistributing garcinia cambogia supply capacity toward pharmaceutical-grade facilities, forcing legacy solvent-based processors to upgrade or exit.
Growth Catalysts
- FSSAI quality mandates:India's enforcement of botanical identity testing and heavy metal limits for garcinia extracts is filtering substandard suppliers and elevating average product quality for export markets.
- Direct-to-consumer subscription models:Online retail channels are capturing repeat purchase volume through influencer-driven conversion funnels targeting weight management consumers in the United States and Germany.
- HCA standardization at 60% concentration:Premium extract specifications are commanding margin premiums in finished goods formulations for capsule and tablet manufacturers seeking differentiation.
Market Restraints
- Raw material concentration in Southeast Asia:Garcinia cambogia fruit sourcing clusters in Indonesia, Malaysia, and southern Thailand, exposing processors to monsoon-driven crop volatility and port congestion.
- FTC substantiation requirements:The United States' enforcement of clinical evidence standards for weight-loss claims is restricting label positioning and increasing legal review costs for supplement marketers.
- Green coffee bean extract substitution:Chlorogenic acid-based alternatives are capturing shelf space in mass-market weight management segments with lower price points and comparable consumer awareness.
Strategic Opportunities
- Mood enhancement positioning:Stress-adjacent wellness consumers in Germany and the United States represent an underpenetrated application segment for HCA's serotonergic modulation properties.
- EU novel food pathway completion:EFSA approval for garcinia extract as a novel food ingredient would unlock food and beverage integration beyond current supplement-only positioning.
- Asset-light contract manufacturing:Third-party leasing of extraction facilities in India and Vietnam is lowering capital barriers for private-label entrants seeking pharmaceutical-grade production without facility ownership.
Industry Challenges
- Phytochemical analytical capability gaps:Commercial laboratories capable of HCA quantification and adulterant detection are concentrated in Mumbai, Hyderabad, and Bangalore, creating testing bottlenecks for smaller processors.
- Spray-drying equipment lead times:Pharmaceutical-grade drying systems from European and Japanese suppliers face 14-18 month delivery schedules, delaying capacity expansion timelines for qualified extract producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Garcinia Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extract Powder, Capsule, Liquid Extract, Tablet, Gummies Application: Weight Management, Appetite Suppressant, Digestive Aid, Mood Enhancement, Athletic Performance Sales Channel: Online Retail, Pharmacies, Health Food Stores, Direct Selling, Specialty Retailers Customer Type: Dietary Supplement Users, Fitness Enthusiasts, Wellness Centers, Nutritionists, Herbal Therapists |
| Companies Covered | NOW Foods, Himalaya Herbal Healthcare, NutraScience Labs, BioGanix, Nature Wise, Natrol, Hi-Tech Pharmaceuticals, Nutririse, NutraValley Biotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Garcinia Market Shifts & Advancements
Supercritical CO2 extraction technology is displacing conventional solvent-based processing in premium garcinia extract manufacturing, altering capital requirements and competitive entry thresholds.
Supercritical CO2 extraction systems operate at elevated pressure and temperature to isolate HCA without residual solvent contamination. Pharmaceutical-grade supplement manufacturers in Germany and Switzerland are adopting this technology to meet REACH compliance for extraction solvents and command certification premiums. Batch-scale supercritical processing is rendering obsolete methanol and ethanol-based extraction lines in facilities serving European-bound supply chains.
REACH compliance for extraction solvents is tightening residue limits for methanol, ethanol, and hexane in botanical imports to the European Union. The regulation is forcing Southeast Asian processors to retrofit solvent recovery systems or pivot to supercritical CO2 alternatives. German and Dutch importers are consolidating supplier relationships around REACH-certified facilities, compressing the qualified vendor base.
Subscription-based replenishment models are displacing one-time retail purchases for garcinia cambogia supplements in the United States direct-to-consumer channel. Wellness influencers on TikTok and Instagram are compressing consumer education cycles and driving trial-to-subscription conversion through algorithmic targeting. This channel shift is most visible in weight management applications targeting women aged 25-40 in metropolitan markets.
Global Garcinia Market Segmentation
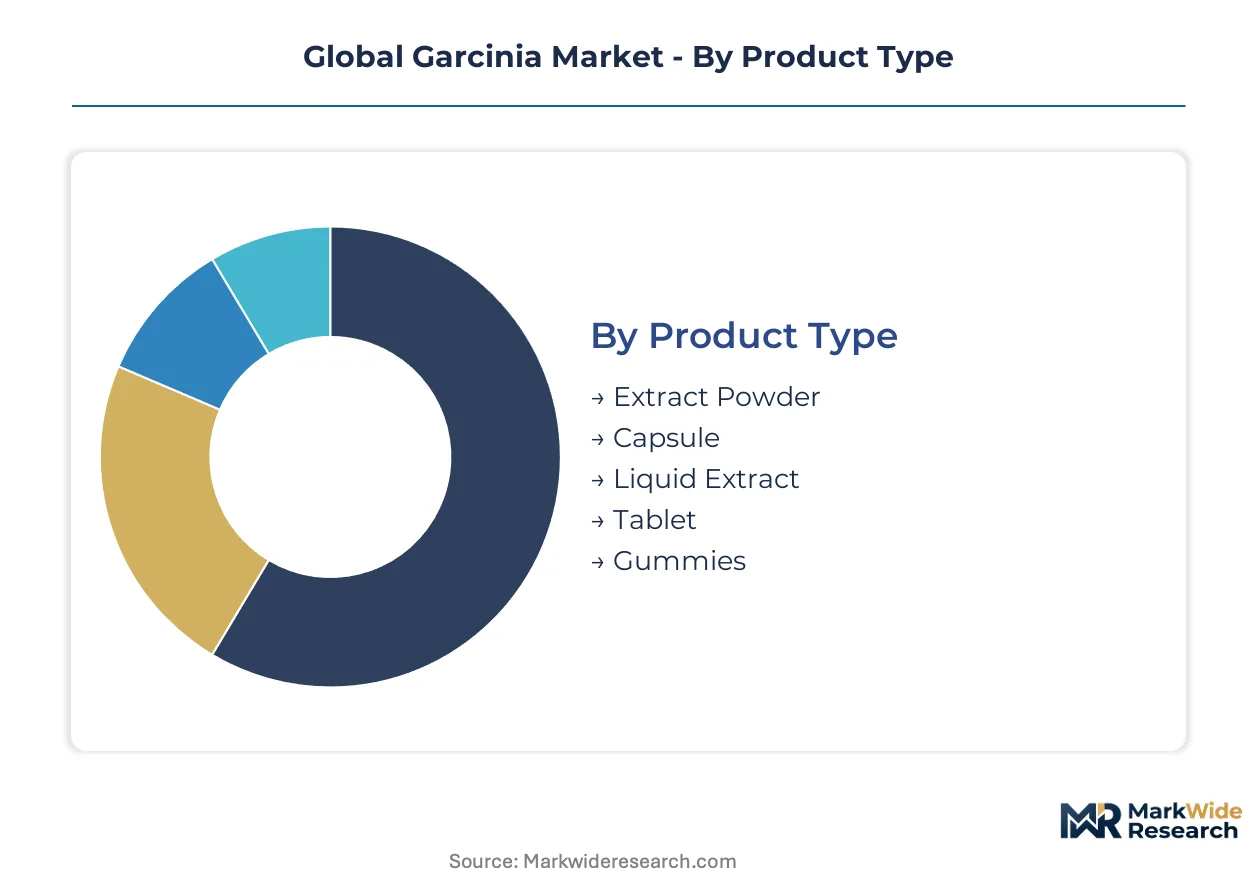
Segmentation in the garcinia market reveals how hydroxycitric acid delivery formats, end-use positioning, and procurement pathways split margin pools and regulatory exposure across distinct buyer ecosystems. Each dimension carries divergent capital requirements and compliance burdens.
Product Type:
Cost tier determines manufacturing complexity and working capital intensity across finished goods formats.
- Extract Powder:Bulk HCA concentrate standardized to 50-60% concentration through spray-drying enables downstream blending flexibility for capsule and tablet manufacturers. Demand concentrates in contract manufacturing facilities across India and Vietnam serving North American private-label brands, driven by economies of scale in high-volume production runs.
- Capsule:Two-piece gelatin or vegetable cellulose shells containing 500-1000mg garcinia extract dominate pharmacy and online retail shelves in the United States and Germany. Consumer preference for pre-measured dosing and portability sustains this format's margin premium over bulk powders.
- Liquid Extract:Glycerin or alcohol-based suspensions offering rapid absorption appeal to functional beverage integrators and tincture specialists.
- Tablet:Compressed formulations with binders and coatings suit mass-market distribution through pharmacy chains requiring extended shelf stability.
- Gummies:Pectin or gelatin-based chewable formats targeting taste-sensitive consumers in direct-to-consumer subscription channels.
Extract powder commands the established base. The steepest expansion runs through gummies.
Application:
End-use positioning shapes clinical substantiation requirements and permissible label claims across jurisdictions.
- Weight Management:Citrate lyase inhibition claims for lipid metabolism modulation drive the largest volume segment, though FTC enforcement in the United States and EFSA scrutiny in Europe intensify evidentiary demands for marketers. This application anchors finished goods pricing power.
- Appetite Suppressant:Satiety signaling through serotonergic pathways attracts formulation interest from meal replacement and intermittent fasting adjacent products. Regulatory classification varies—some jurisdictions treat this as a structure-function claim, others as implied disease prevention.
- Digestive Aid:Traditional Ayurvedic positioning for gut health supports niche premium pricing in wellness center channels.
- Mood Enhancement:Stress-adjacent wellness consumers in Germany and the United States represent an underpenetrated segment for HCA's serotonergic properties.
- Athletic Performance:Endurance and recovery positioning targets fitness enthusiasts through specialty retail and sports nutrition channels.
Weight management commands the established base. The steepest expansion runs through mood enhancement.
Sales Channel:
Customer acquisition economics and repeat purchase mechanics diverge sharply across distribution pathways.
- Online Retail:Direct-to-consumer subscription models with algorithmic targeting via TikTok and Instagram compress education cycles and drive trial-to-repeat conversion among women aged 25-40 in metropolitan United States markets. Influencer marketing costs now rival traditional slotting fees.
- Pharmacies:Brick-and-mortar pharmacy chains in Germany and Switzerland require pharmaceutical-grade GMP certification and local language labeling, filtering supplier bases to established extractors.
- Health Food Stores:Independent and chain natural products retailers emphasize organic and non-GMO positioning, commanding certification premiums.
- Direct Selling:Multi-level marketing networks leverage personal relationship selling for high-margin personalized coaching bundles.
- Specialty Retailers:Sports nutrition and Ayurvedic specialty shops serve enthusiast segments with technical specification demands.
Pharmacies command the established base. The steepest expansion runs through online retail.
Customer Type:
Procurement sophistication and volume scale separate institutional buyers from individual consumers.
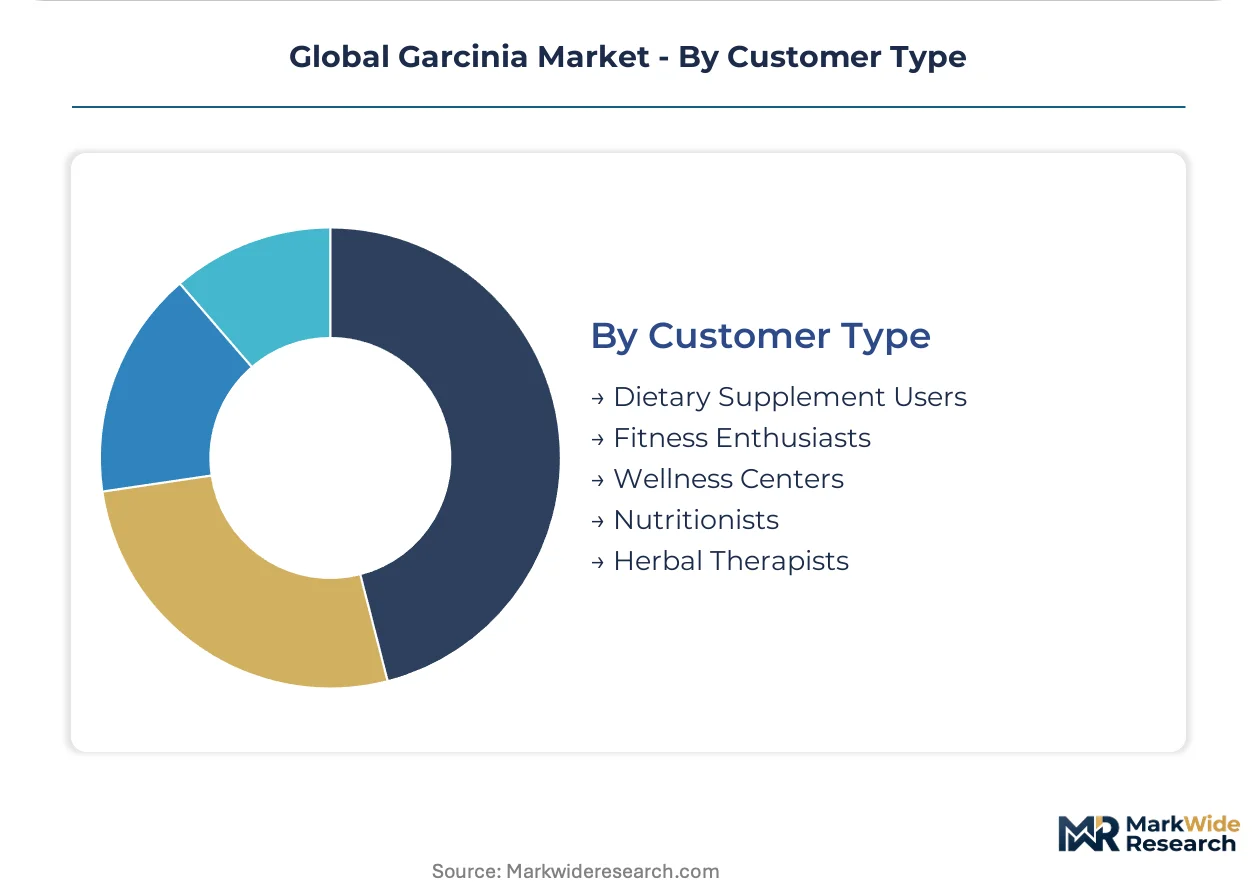
- Dietary Supplement Users:Self-directed consumers purchasing for personal weight management goals drive mass-market volume through retail and online channels, with purchase decisions influenced by influencer content and review aggregation platforms.
- Fitness Enthusiasts:Gym-attached consumers seeking body composition optimization purchase through sports nutrition specialty channels with higher frequency and brand loyalty than general wellness buyers.
- Wellness Centers:Integrated health facilities in the United States and Germany source private-label formulations through contract manufacturers like NutraScience Labs, requiring batch documentation and third-party testing.
- Nutritionists:Licensed practitioners recommending specific HCA dosages create prescription-like demand for pharmaceutical-grade extracts.
- Herbal Therapists:Traditional medicine practitioners in India and Southeast Asia prioritize whole-fruit or traditional preparation formats over standardized extracts.
Dietary supplement users command the established base. The steepest expansion runs through wellness centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Weight management consumers in the United States, China, and Germany concentrate garcinia cambogia procurement, with wellness centers and direct-to-consumer channels reshaping demand geography. Regulatory enforcement in India and quality mandates in Switzerland filter supplier bases toward pharmaceutical-grade extractors.
United States
Fitness enthusiasts and stress-adjacent wellness consumers drive garcinia extract consumption through online subscription channels. FDA dietary supplement GMP enforcement and FTC substantiation requirements govern label claims and manufacturing quality. Los Angeles and New York metropolitan areas anchor influencer-driven direct-to-consumer marketing operations targeting women aged 25-40.
Germany
Pharmacy chains and wellness centers source pharmaceutical-grade garcinia extracts for weight management and mood enhancement applications. EFSA novel food evaluation pathways and REACH compliance for extraction solvents create market access conditions for European-bound suppliers. Frankfurt and Munich concentrate import distribution and third-party testing laboratory capacity.
India
Ayurvedic heritage positioning and contract manufacturing scale attract global private-label brands to domestic extraction facilities. FSSAI botanical identity testing mandates and the PLI scheme for botanical extraction redistribute supply capacity toward pharmaceutical-grade processors. Hyderabad, Mumbai, and Bangalore cluster analytical laboratories capable of HCA quantification and adulterant detection.
China
Functional beverage integrators and dietary supplement manufacturers absorb bulk extract powder for downstream formulation. SAMR oversight of health food registration and GB standards for botanical extracts shape compliance requirements. Guangdong and Zhejiang provinces host spray-drying and capsule manufacturing facilities serving domestic and export markets.
Switzerland
Premium supplement brands and supercritical CO2 extraction technology adopters command certification premiums in European supply chains. Swissmedic pharmaceutical-grade manufacturing standards and REACH solvent residue limits filter supplier relationships. Basel and Zurich anchor quality verification and import consolidation for German and French distribution.
Global Garcinia Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions, with online retail platforms and pharmacy chains exerting downstream pricing pressure on extract manufacturers. The vendor base separates into three strategic archetypes: backward-integrated raw material sourcers, pharmaceutical-grade contract manufacturers, and private-label formulation specialists. Capacity expansion through third-party facility leasing and technology licensing for supercritical CO2 extraction represent dominant competitive moves.
Among United States-based supplement marketers, NOW Foods exemplifies backward integration into Southeast Asian raw material sourcing, while NutraScience Labs occupies a position within private-label partnership archetypes serving wellness centers. Himalaya Herbal Healthcare anchors Ayurvedic heritage positioning through pharmaceutical-grade manufacturing standards. These three companies represent distinct competitive vectors: captive supply control, contract manufacturing scale, and traditional medicine brand equity.
| Leading Market Players |
|---|
| NOW Foods |
| Himalaya Herbal Healthcare |
| NutraScience Labs |
| BioGanix |
| Nature Wise |
| Natrol |
| Hi-Tech Pharmaceuticals |
| Nutririse |
| NutraValley Biotech |
| Others |
Supply & Pricing Matrix
Hyderabad's pharmaceutical-grade extraction capacity expansion is compressing margins for legacy solvent-based processors while elevating pricing power for REACH-certified facilities serving European buyers. Cost-plus contracts with raw material indexation to Indonesian rupiah-denominated fruit prices dominate procurement between Southeast Asian collectors and Indian processors.
Pricing Analysis
Cost-plus contracts with rupiah-indexed raw material adjustments govern transactions between Indonesian collectors and Indian extraction facilities. Pricing stratifies across pharmaceutical-grade, food-grade, and feed-grade tiers based on HCA standardization thresholds and FSSAI certification status. Cost compression in standard-grade powder runs through green coffee bean extract substitution in mass-market weight management segments. Direct-to-consumer subscription buyers exhibit lowest price sensitivity; contract manufacturing clients for pharmacy chains show highest.
Supply Chain Analysis
Third-party contract manufacturers in India and Vietnam hold concentrated spray-drying and supercritical CO2 extraction capacity for pharmaceutical-grade output. Raw material sourcing draws from Indonesian, Malaysian, and southern Thai fruit collection networks; methanol and ethanol feed chemical inputs; and European-imported drying equipment. Single-source vulnerability concentrates in Mumbai-Hyderabad-Bangalore analytical laboratory clusters for HCA quantification. Distribution runs through direct-to-consumer platforms, pharmacy chains, and wellness center private-label channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as India's PLI scheme for botanical extraction redistributes capacity toward pharmaceutical-grade facilities and filters substandard competitors.
For Market Incumbents: Entrench supply security through backward integration into Southeast Asian raw material sourcing or captive plantation development in Indonesia. Secure REACH certification for European market access before competitor capacity expansion in Vietnam matures. Prioritize supercritical CO2 technology licensing to defend margin position against solvent-based cost competitors. For New Entrants and Emerging Players: Pursue mood enhancement application white space in German and United States wellness center channels where serotonergic positioning remains underdeveloped. Target asset-light contract manufacturing entry through third-party facility leasing in Hyderabad or Ho Chi Minh City. Deploy influencer-driven direct-to-consumer subscription models for rapid trial conversion among stress-adjacent consumers. For Investors and Strategic Acquirers: Long-term, this sits as a certification-premium play because regulatory tightening across FDA, FSSAI, and REACH jurisdictions is elevating barriers for uncertified competitors. Acquisition targets should display pharmaceutical-grade GMP compliance, established European importer relationships, and supercritical CO2 production capability. Monitor EFSA novel food pathway decisions as inflection signal for food and beverage integration expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Technology Licensing | REACH-compliant extraction eliminates solvent residue risks for European-bound supply chains. |
| Backward Integration into Raw Material Sourcing | Captive Indonesian plantation supply secures cost stability against monsoon-driven crop volatility. |
| EFSA Novel Food Pathway Completion | Regulatory approval unlocks food and beverage integration beyond supplement-only positioning. |
| Private-Label Partnership Expansion | Wellness center channel relationships in Germany and United States command recurring volume commitments. |
| Asset-Light Contract Manufacturing Scale-Up | Third-party facility leasing in India lowers capital barriers for pharmaceutical-grade market entry. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FSSAI enforcement records, FDA warning letters, EFSA novel food applications, and customs trade data. Extraction facility operators, procurement managers at United States supplement brands, regulatory affairs specialists, and wellness center formulation buyers provided operational perspective. Bottom-up volume estimates from individual facility capacity and top-down demand calibration from channel shipment data were cross-validated.
Forecast inputs incorporate HCA standardization tier adoption curves, regulatory pathway completion timelines, and channel shift velocity from retail to direct-to-consumer subscription models across the projection horizon. Segmentation modeling spans product format, application positioning, sales channel, and customer procurement sophistication. CAGRs derive from regression against historical volume-price relationships and scenario-weighted regulatory outcome probabilities.
Sensitivities concentrate around EFSA novel food approval timing, FTC enforcement intensity on weight-loss claims, and Indonesian crop yield volatility. Forecasts reflect documented assumptions on certification adoption rates and channel migration speed. Quarterly review of FSSAI inspection outcomes, REACH solvent residue limit amendments, and Southeast Asian port congestion indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Mexico Fruits & Vegetables Market
Fruits and Vegetables
Brined Vegetable Market
Fruits and Vegetables
Turkish Figs Market
Fruits and Vegetables
Asia-Pacific Fruit and Vegetable Ingredient Market
Fruits and Vegetables
Dried Red Jujube Market
Fruits and Vegetables
Raisins Market
Fruits and Vegetables
Farro Market
Fruits and Vegetables
Freeze Dried Fruits and Vegetables Market
Fruits and Vegetables
Europe Stone Fruits Market
Fruits and Vegetables
Japan Frozen Fruit Puree Market
Fruits and Vegetables
Mung Beans Market
Fruits and Vegetables
Dried Figs Market
Fruits and Vegetables
Aronia Berries Market
Fruits and Vegetables
Olive Market
Fruits and Vegetables
North America Olive Market
Fruits and Vegetables
Persimmons Market