
 Europe Welding Equipment Market | 2026-2036
Europe Welding Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Welding Equipment Market Foresight
Aluminum is broadening its substitution of steel in European automotive chassis and battery enclosure assemblies, forcing welding equipment makers to retool arc stability and thermal management systems. Lincoln Electric Holdings Inc. leverages its R&D intensity in advanced wire-feed technologies for thin-gauge aluminum. ESAB Corp. anchors its position through captive supply of consumables paired with power-source platforms. Fronius International GmbH differentiates via precision TIG systems engineered for EV battery tray welding.
Europe welding equipment comprises power sources, torches, wire feeders, and consumables engineered to join metals through controlled electrical arcs or plasma streams, typically operating at 20-500 amperes depending on material thickness and process type. The equipment serves primary industrial purposes of permanent metallurgical bonding in fabrication, repair, and serial manufacturing environments. Arc welders and MIG machines retain the largest installed base across European metalworking shops, while robotic welding systems capture the fastest expansion as automotive plants automate body-in-white assembly. Manual technology segments face margin compression from Chinese imports, whereas hybrid systems that blend operator oversight with programmable path control command premium positioning in aerospace subcontractor networks.
CE marking under the EU Machinery Directive and REACH compliance for electrode coatings constrain product design and market access for non-European suppliers. Germany's KBA enforces weld-quality traceability standards that shape procurement specifications for automotive Tier-1 suppliers. ECHA's evolving substance restrictions on hexavalent chromium in anti-spatter compounds are accelerating reformulation of consumable chemistries. Stakeholders must monitor how the EU AI Act's risk-classification rules will apply to autonomous seam-tracking systems before committing capital to next-generation robotic welding cells.
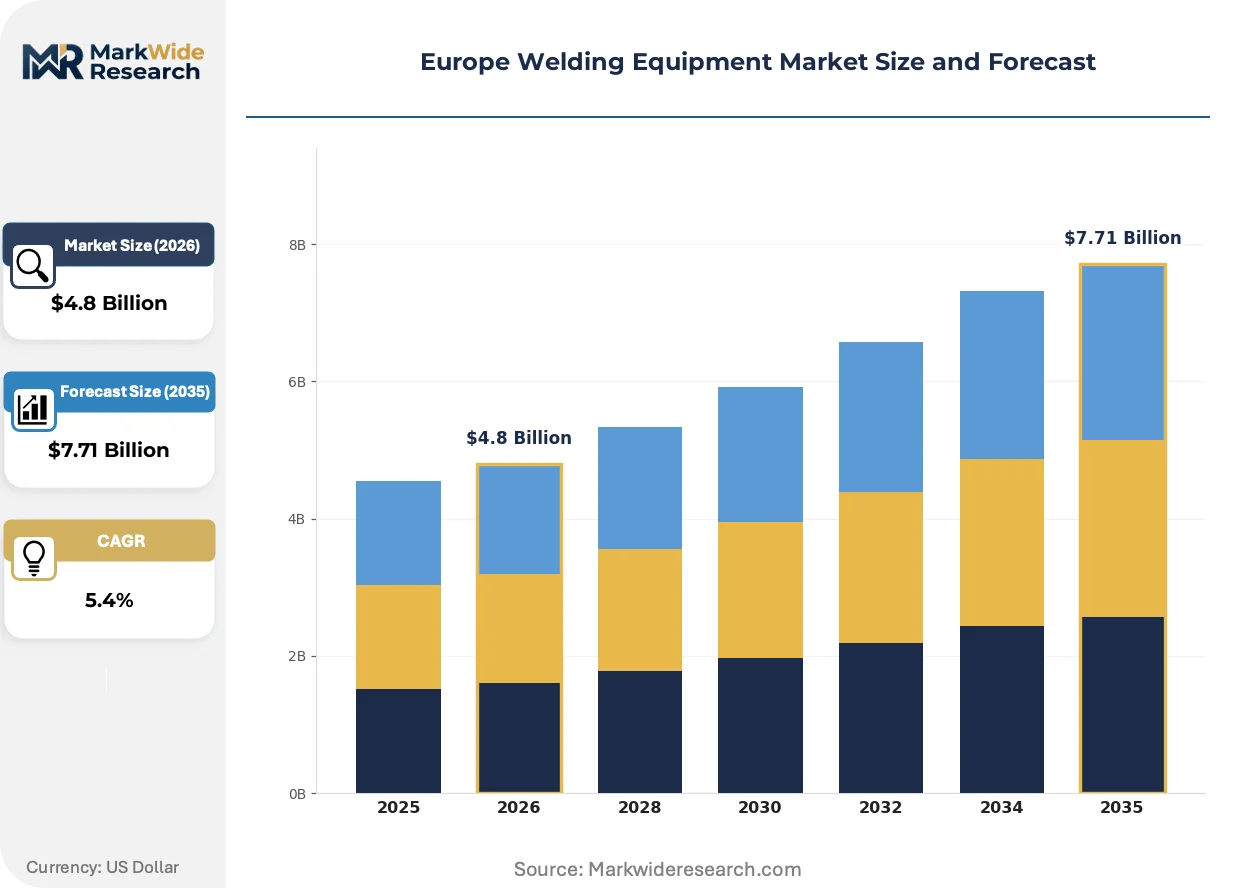
Market Dynamics
EU Green Deal production mandates are forcing automotive OEMs to retool entire welding lines for aluminum-intensive EV architectures, creating a structural demand pull for arc stability systems and thermal management platforms that legacy steel-optimized equipment cannot satisfy.
Growth Catalysts
- EU Green Deal manufacturing standards:Automotive OEMs across Germany and France are expanding robotic welding capacity to meet binding carbon-intensity thresholds for battery electric vehicle production.
- Aluminum substitution in chassis assemblies:Lightweighting mandates are accelerating demand for specialized MIG and TIG systems capable of managing thin-gauge aluminum thermal profiles without burn-through.
- France and Italy:These markets concentrate demand for maintenance-intensive fabrication services as regional infrastructure renewal programs expand metalworking shop throughput.
Market Restraints
- Chinese import pressure:Manual welding equipment segments face sustained margin compression from low-cost Asian manufacturers flooding European distributor channels.
- REACH compliance costs:ECHA substance restrictions on hexavalent chromium in anti-spatter compounds force consumable reformulation that raises raw material input costs.
- CE marking barriers:Non-European suppliers confront extended certification timelines under the EU Machinery Directive, limiting competitive entry velocity.
Strategic Opportunities
- Eastern European manufacturing expansion:Poland and Czech Republic automotive supplier parks remain underpenetrated for robotic welding cell deployment relative to German benchmark density.
- EU AI Act seam-tracking systems:Risk-classification rules for autonomous welding quality control create first-mover advantage for compliant platform vendors before 2025 enforcement windows.
- Hybrid system convergence:Blending operator oversight with programmable path control opens premium positioning in aerospace subcontractor networks where full automation remains uneconomical.
Industry Challenges
- Skilled welder scarcity:European metalworking shops report acute shortages of certified TIG operators capable of battery tray precision welding for EV OEMs.
- Legacy system integration friction:Tier-1 automotive suppliers struggle to retrofit KBA-mandated weld-quality traceability standards onto decades-old resistance welding infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Welding Equipment Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Arc Welders, MIG Machines, TIG Equipment, Plasma Cutters Technology: Manual, Automated, Robotic, Hybrid End User: Construction, Automotive, Shipbuilding, Aerospace Application: Fabrication, Repairs, Manufacturing, Maintenance |
| Companies Covered | Kemppi Oy, Denyo Co. Ltd, Lincoln Electric Holdings Inc., Plansee SE, Obara Corporation, ESAB Corp., Panasonic Industry Europe GmbH, voestalpine Böhler Welding, Fronius International GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Welding Equipment Market Shifts & Advancements
Welding equipment architecture is fragmenting into configurable subsystems as end-users demand flexible capital deployment. Three distinct vectors are compressing traditional integrated-platform business models.
Power-source hardware is modularizing into swappable inverter modules and detachable wire-feed units. Automotive Tier-1 suppliers in Stuttgart and Wolfsburg are adopting platform-agnostic configurations that permit rapid process switching from steel to aluminum without full line replacement. This modularity is compressing capital recovery timelines and eroding vendor lock-in for integrated system providers.
REACH substance restrictions are accelerating reformulation of electrode coatings and anti-spatter chemistries. ECHA's evolving hexavalent chromium bans force consumable manufacturers to validate alternative surface-active compounds without sacrificing arc stability. German KBA traceability standards now extend to coating batch records, compelling suppliers to rebuild quality documentation systems.
Service unbundling is disrupting traditional equipment-plus-consumables bundling. French and Italian fabrication shops are separating maintenance contracts from initial hardware procurement, favoring third-party service networks over captive OEM support. This pattern is most visible in maintenance-intensive segments where downtime costs exceed premium support pricing.
Europe Welding Equipment Market Segmentation
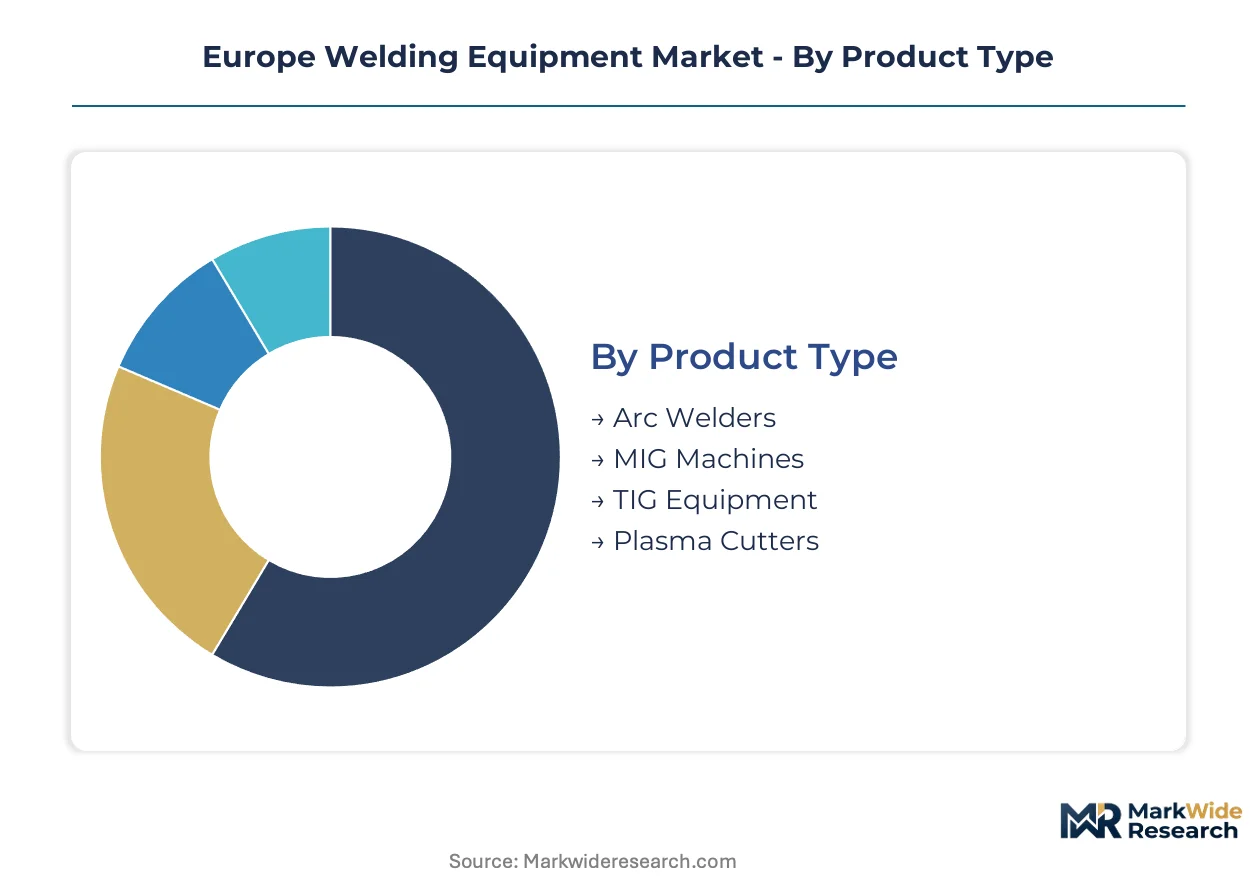
Welding equipment segmentation in Europe reflects divergent integration depths across industrial environments. Equipment ranges from standalone manual units for job-shop flexibility to fully embedded robotic cells in automotive body-in-white lines.
Product Type:
Arc welders and MIG machines operate as standalone capital assets in most European metalworking facilities, while TIG systems and plasma cutters embed more frequently into specialized fabrication cells.
- Arc Welders:These inverter-based power sources deliver controlled electrical arcs across 20-500 amperes for metallurgical bonding of steel and aluminum. German automotive Tier-1 suppliers in Stuttgart and Wolfsburg deploy arc welders as backbone equipment for chassis fabrication, though thermal management limitations constrain their effectiveness on thin-gauge aluminum EV battery enclosures.
- MIG Machines:Metal inert gas systems utilize continuous wire feed and shielding gas to achieve high-deposition-rate joining. French and Italian fabrication shops concentrate maintenance-intensive demand for MIG equipment as regional infrastructure renewal programs expand metalworking throughput, with wire-feed reliability determining vendor selection.
- TIG Equipment:Tungsten inert gas systems provide precision arc control for critical joints in aerospace subcontractor networks across the UK and Italy.
- Plasma Cutters:These thermal cutting systems generate concentrated plasma streams for precision metal severing in shipbuilding yards along the North Sea and Mediterranean coasts.
Arc welders lead volumes today; TIG equipment is gaining share fastest.
Technology:
Technology segmentation stratifies by labor substitution depth, with manual systems requiring full operator control and robotic platforms eliminating direct human intervention in seam execution.
- Manual:Operator-dependent systems dominate job-shop environments where batch sizes and joint configurations vary unpredictably. Polish and Czech metalworking facilities retain substantial manual welding bases, though margin compression from Chinese imports erodes equipment vendor profitability in this tier.
- Robotic:Six-axis articulated arms with integrated seam-tracking execute programmed weld paths without continuous operator oversight. German and French automotive OEMs expand robotic welding capacity to meet EU Green Deal carbon-intensity thresholds for battery electric vehicle production, with aluminum-intensive EV architectures demanding upgraded arc stability systems.
- Automated:Fixed-automation systems blend mechanized part handling with limited path programmability for medium-volume production.
- Hybrid:Operator-supervised programmable systems blend human oversight with automated path control, commanding premium positioning in aerospace subcontractor networks where full automation remains uneconomical.
Manual technology retains the largest installed base; robotic systems climb the fastest.
End User:
End-user segmentation tracks capital intensity and certification requirements, with automotive and aerospace demanding traceable quality systems while construction tolerates broader equipment specifications.
- Automotive:OEMs and Tier-1 suppliers drive specification intensity through KBA-mandated weld-quality traceability standards. German manufacturers in Wolfsburg and Munich retool entire welding lines for aluminum-intensive EV architectures, creating structural demand pull that legacy steel-optimized equipment cannot satisfy.
- Aerospace:Subcontractor networks in the UK, France, and Italy require precision TIG systems with full process documentation for airworthiness certification. EU AI Act risk-classification rules for autonomous seam-tracking systems are reshaping procurement timelines before enforcement windows.
- Construction:Infrastructure renewal programs across France and Italy expand metalworking shop throughput for structural steel fabrication.
- Shipbuilding:Yards along the Mediterranean and North Sea coasts concentrate demand for heavy-deposition arc welding in hull assembly.
Automotive leads volumes today; aerospace is expanding most quickly.
Application:
Application segmentation distinguishes between original fabrication and post-installation service activities, with divergent equipment mobility and duty-cycle requirements.
- Manufacturing:Serial production environments in German automotive plants demand robotic cells with integrated quality monitoring and KBA-compliant traceability documentation. These installations prioritize uptime reliability over capital cost minimization.
- Maintenance:Field-service and in-situ repair operations favor portable manual equipment with rapid setup characteristics. French and Italian fabrication shops separate maintenance contracts from initial hardware procurement, favoring third-party service networks over captive OEM support.
- Fabrication:Job-shop metal forming and assembly combines cutting, forming, and joining operations in variable-batch environments.
- Repairs:Corrective welding interventions on installed infrastructure and equipment require portable systems with site-access flexibility.
Manufacturing leads volumes today; maintenance is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive clusters in Stuttgart and Wolfsburg anchor European welding equipment demand through EV retooling cycles. France and Italy concentrate maintenance-intensive fabrication activity. Eastern European supplier parks in Poland and Czech Republic present underpenetrated robotic deployment opportunities relative to western benchmarks.
Germany
Automotive OEMs in Wolfsburg and Munich retool entire welding lines for aluminum-intensive EV battery enclosures. KBA weld-quality traceability standards shape procurement specifications for Tier-1 chassis suppliers. Stuttgart's supplier parks deploy robotic cells at density levels unmatched elsewhere in Europe.
France
Infrastructure renewal programs expand metalworking shop throughput for structural steel fabrication. EU Green Deal carbon-intensity thresholds accelerate robotic welding adoption at Renault and Stellantis facilities. Lyon and Marseille fabrication clusters separate maintenance contracts from hardware procurement, favoring third-party service networks.
Italy
Maintenance-intensive demand concentrates in Emilia-Romagna and Lombardy job shops serving regional construction activity. ECHA hexavalent chromium restrictions force consumable reformulation across electrode coating supply chains. Turin aerospace subcontractors require precision TIG systems with full airworthiness documentation.
Poland
Automotive supplier parks near Wrocław and Poznań remain underpenetrated for robotic welding cell deployment. CE marking compliance timelines constrain non-European vendor entry velocity. Polish metalworking facilities retain substantial manual welding bases despite margin compression from Chinese imports.
United Kingdom
Aerospace subcontractor networks in the Midlands and Southwest England demand hybrid systems blending operator oversight with programmable path control. EU AI Act risk-classification rules reshape procurement timelines for autonomous seam-tracking systems. Birmingham fabrication clusters report acute shortages of certified TIG operators.
Europe Welding Equipment Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbent suppliers retool for aluminum-intensive EV architectures. The vendor base stratifies across three tiers: integrated power-source specialists, consumables-captive platforms, and modular subsystem providers. Strategic archetypes include technology licensors seeking royalty streams, regional fabricators defending local service relationships, and automotive-focused system integrators. M&A activity and geographic expansion represent the two dominant competitive vectors reshaping market boundaries.
Among Finland-based equipment specialists, Kemppi Oy exemplifies the modular power-source archetype with swappable inverter configurations. Lincoln Electric Holdings Inc. and ESAB Corp. anchor the consumables-integrated tier, pairing captive wire-feed supply with platform-agnostic hardware deployments. Fronius International GmbH occupies a position within the precision-systems segment, reflecting Austrian engineering concentration in TIG applications for quality-critical environments.
| Leading Market Players |
|---|
| Kemppi Oy |
| Denyo Co. Ltd |
| Lincoln Electric Holdings Inc. |
| Plansee SE |
| Obara Corporation |
| ESAB Corp. |
| Panasonic Industry Europe GmbH |
| voestalpine Böhler Welding |
| Fronius International GmbH |
| Others |
Supply & Pricing Matrix
German automotive Tier-1 suppliers concentrate procurement specifications for robotic welding cells, enforcing contract-based long-term offtake agreements that tether pricing to KBA-mandated traceability certification tiers. This buyer concentration compresses margin flexibility for equipment vendors while amplifying price premiums for compliant platforms.
Pricing Analysis
Input-cost pass-through from copper winding and IGBT inverter modules drives quarterly price adjustments across power-source manufacturers. Pricing stratifies across premium, standard, and economy tiers based on CE marking tier and after-sales service bundling. Cost compression in manual equipment segments is intensifying because Chinese imports flood distributor channels. Job-shop fabricators in France and Italy exhibit highest price sensitivity, whereas German automotive OEMs prioritize uptime reliability over capital cost minimization.
Supply Chain Analysis
Workforce availability constraints in Czech Republic and Poland manufacturing zones limit expansion velocity for robotic welding cell assembly. Supply concentrates in Germany, Austria, and China for inverter modules, wire-feed mechanisms, and tungsten electrodes. The chain draws from copper concentrates, rare-earth magnet materials, and specialized semiconductor components. Single-source vulnerability around IGBT modules from Chinese suppliers poses structural risk. Distribution runs through captive OEM service networks and third-party industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as aluminum-intensive EV architectures force retooling toward premium arc stability systems that legacy steel-optimized equipment cannot satisfy.
For Market Incumbents: Deploy consumables-captive bundling to defend against modular subsystem providers unbundling service contracts. Lincoln Electric and ESAB should deepen backward integration into specialty wire alloys for thin-gauge aluminum. Fronius must accelerate EU AI Act compliance for autonomous seam-tracking systems before enforcement windows close. Channel control through Stuttgart and Wolfsburg supplier park proximity remains essential. For New Entrants and Emerging Players: Digital-channel routes through French and Italian fabrication shop networks bypass entrenched automotive OEM procurement barriers. Eastern European supplier parks in Poland and Czech Republic present the most penetrable geography given underdeployment relative to German benchmark density. Target maintenance-intensive segments with platform-agnostic configurations that permit rapid steel-to-aluminum process switching without full line replacement. For Investors and Strategic Acquirers: Automotive-focused system integrators are the most active acquirer in this space, seeking precision TIG capabilities for EV battery tray welding. The five-to-ten year viability window favors targets with captive consumables supply and KBA-traceability certification infrastructure. Monitor EU AI Act risk-classification enforcement as the critical inflection signal for autonomous welding quality control platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Consumables Reformulation Investment | ECHA hexavalent chromium bans force electrode coating chemistry rebuilds without sacrificing arc stability. |
| Modular Power-Source Platform Launch | Swappable inverter configurations compress capital recovery timelines for Stuttgart Tier-1 suppliers. |
| EU AI Act Compliance Pathway | Risk-classification rules for autonomous seam-tracking create first-mover advantage before enforcement. |
| Third-Party Service Network Expansion | French and Italian shops separate maintenance contracts, favoring independent support over captive OEM. |
| Eastern European Manufacturing Footprint | Poland and Czech Republic supplier parks remain underpenetrated for robotic cell deployment density. |
Research Methodology
Direct dialogue with welding equipment procurement managers at German automotive Tier-1 suppliers, maintenance directors at French fabrication shops, and aftermarket service heads at Italian metalworking facilities grounded qualitative findings. Secondary validation drew from KBA regulatory filings, ECHA substance restriction updates, EU Machinery Directive documentation, and customs trade data for welding equipment imports. Bottom-up equipment deployment tallies triangulated against top-down automotive production forecasts.
Segmentation-level projections across power sources, torches, wire feeders, and consumables by manual, robotic, automated, and hybrid technology tiers shaped the analytical framework over the projection horizon. CAGRs derived from aluminum substitution rates in EV architectures and infrastructure renewal program spend. Modeled inputs included KBA traceability compliance timelines and ECHA coating reformulation adoption curves.
The model assumes a particular technology adoption path; alternative pathways for hybrid operator-supervised systems would alter the outlook. Forecasts reflect assumptions about EU Green Deal manufacturing standard enforcement and skilled welder scarcity resolution. Material deviation in aluminum-intensive EV production volumes or REACH substance restriction timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Hydraulic Shearing Machine Market
Construction Equipment
China Elevator Ropes Market
Construction Equipment
Smart Crane Market
Construction Equipment
Rotary Trommel Market
Construction Equipment
Cutter Suction Dredger (CSD) Market
Construction Equipment
Mini Excavators Market
Construction Equipment
Middle East and Africa Construction Equipment Market
Construction Equipment
Industrial Steam Washer Market
Construction Equipment
Horizontal Machining Center Market
Construction Equipment
Automotive Surface Heat Treatment Furnaces Market
Construction Equipment
Europe Crane Market
Construction Equipment
Rotomolding Market
Construction Equipment
Mobile Light Tower Market
Construction Equipment
Global Airport Snow Removal Vehicles and Equipment Market
Construction Equipment
Asia-Pacific Heavy Construction Equipment Market
Construction Equipment
Log Splitters Rental Market