
 Ferroelectric FET Market | 2026-2036
Ferroelectric FET Market Size, Share, and Industry Trends Forecast 2026-2036
Ferroelectric FET Market Foresight
Multi-source wafer supply for ferroelectric layers is pivoting toward captive hafnium oxide deposition as foundries internalize critical film growth. Toshiba leverages decades of ferroelectric memory expertise to anchor early FeFET device architectures. TSMC sustains process leadership by integrating ferroelectric modules into its most advanced logic nodes. Applied Materials competes through deposition and anneal equipment dominance for hafnium zirconium oxide stacks.
A ferroelectric FET is a transistor incorporating a ferroelectric material—typically hafnium zirconium oxide with orthorhombic phase crystallinity—in its gate stack, enabling non-volatile polarization states that retain data without power and permit logic-in-memory computation. The device operates at sub-1-volt switching thresholds compatible with existing CMOS fabrication flows, targeting energy-efficient edge AI and persistent memory applications. Digital FET variants occupy the largest development pipeline as foundries prioritize binary non-volatile logic for cache and embedded memory replacement. Power FET segments attract renewed R&D investment where ferroelectric negative capacitance can break the Boltzmann tyranny limit in power converters. RF FET applications remain nascent but specialize in reconfigurable front-ends where polarization switching enables tunable impedance matching.
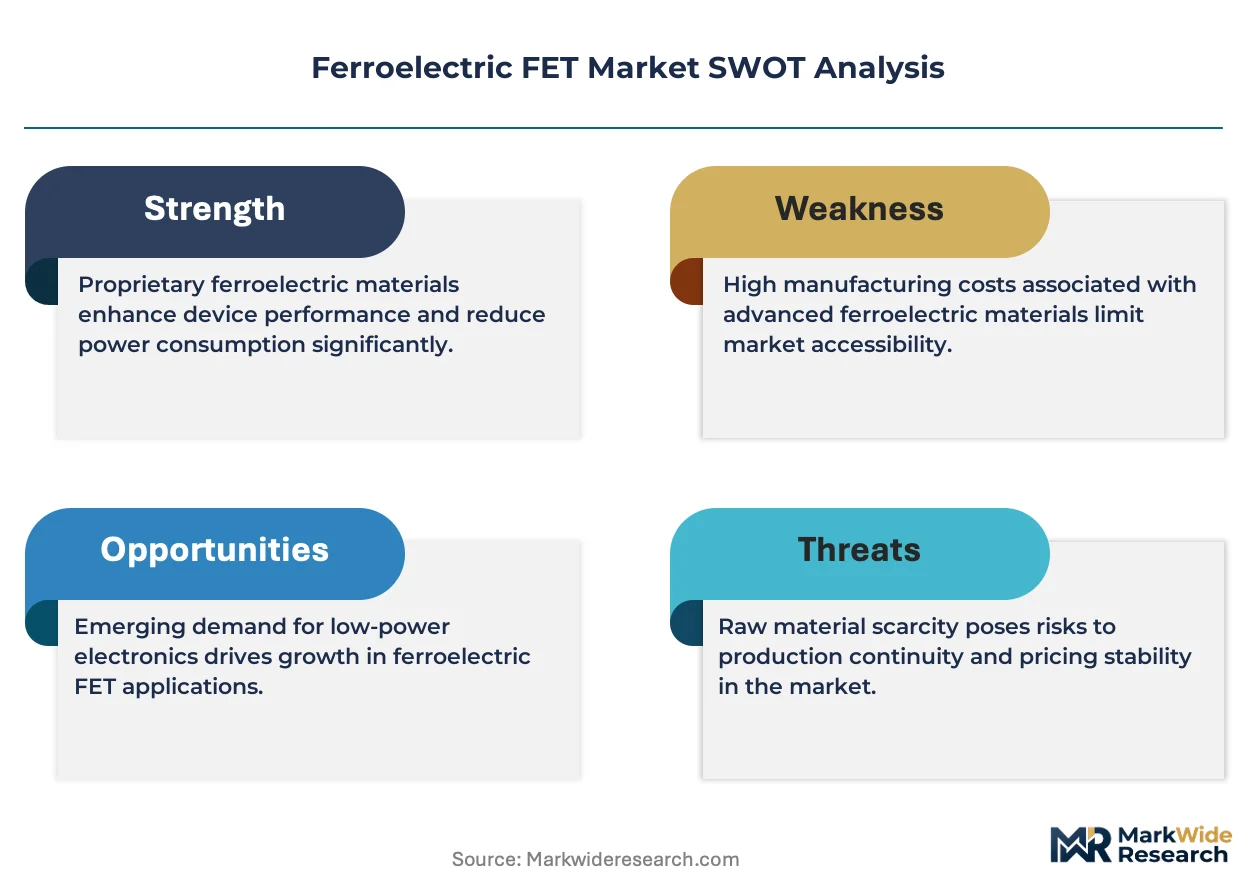
FDA oversight of diagnostic AI edge devices indirectly shapes FeFET demand by mandating local, non-volatile inference storage without cloud dependency. EPA hazardous material rules for hafnium precursor handling constrain deposition chemistry choices and supplier qualification timelines. ISO 26262 functional safety requirements in automotive push Infineon and Fujitsu toward ferroelectric-based fail-safe logic with instant state retention. Stakeholders must monitor which foundry node first achieves qualified FeFET bitcell yield, as this gate will determine licensing structures and equipment pull-through for the subsequent decade.
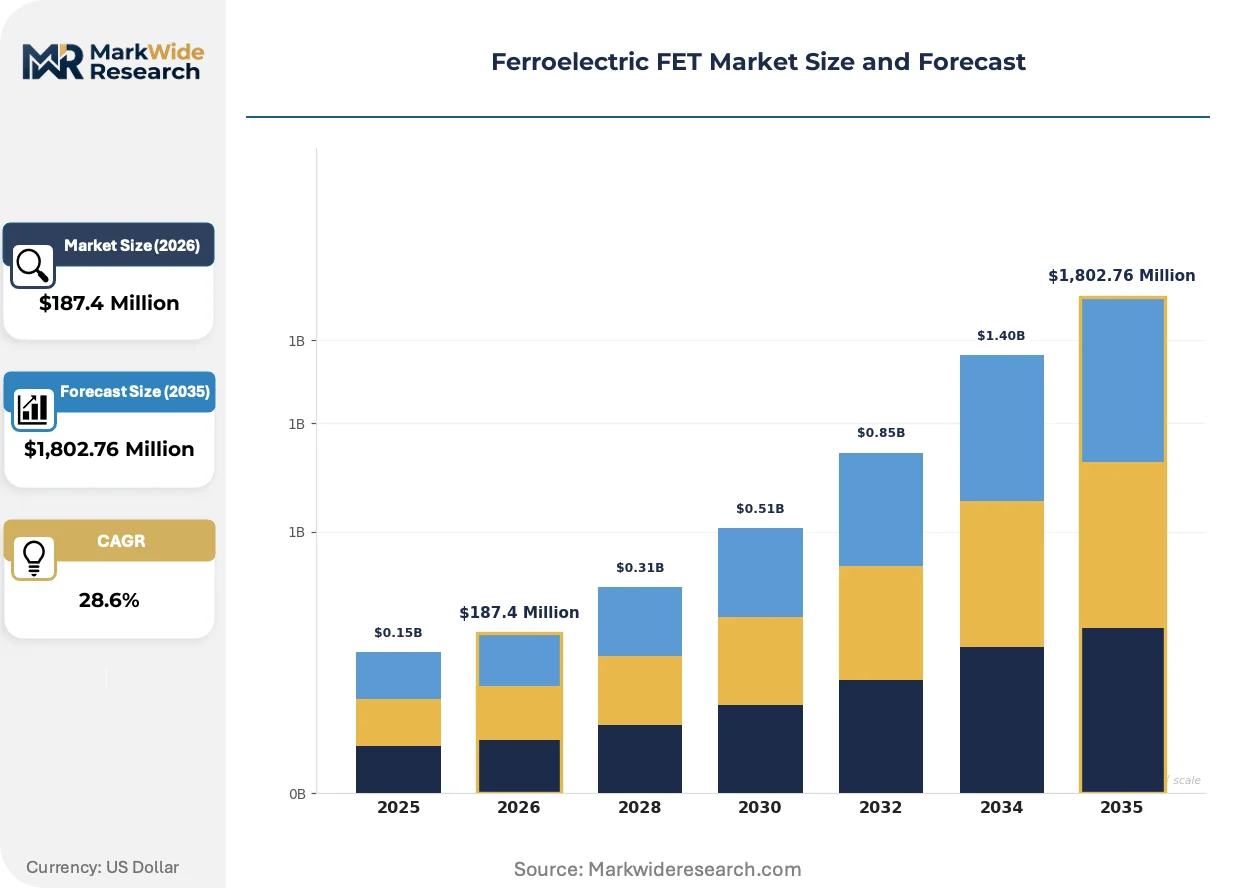
Market Dynamics
The ferroelectric FET market pivots on foundry node qualification timelines, where hafnium zirconium oxide bitcell yield gates commercial licensing and equipment pull-through for the coming decade.
Growth Catalysts
- ISO 26262 mandates:Automotive functional safety requirements push Infineon and Fujitsu toward ferroelectric-based fail-safe logic with instant state retention for power-loss scenarios.
- Edge AI inference localization:FDA diagnostic device rules mandating non-volatile local storage without cloud dependency accelerate FeFET procurement for medical edge compute.
- Hafnium oxide ferroelectricity maturation:IMEC breakthroughs in orthorhombic phase crystallinity achieve CMOS compatibility, enabling sub-1-volt switching thresholds in advanced logic nodes.
Market Restraints
- Precursor supply concentration:EPA hazardous material rules for hafnium precursor handling constrain qualified chemical suppliers to a handful of specialty gas vendors in Germany and Japan.
- Deposition equipment oligopoly:Atomic layer deposition tools for hafnium zirconium oxide stacks concentrate among two dominant equipment manufacturers, creating procurement bottlenecks.
- Flash memory cost floor:Mature NAND flash pricing at sub-4-cent-per-gigabyte levels displaces FeFET in cost-sensitive consumer storage applications.
Strategic Opportunities
- Power FET negative capacitance:Ferroelectric gate stacks breaking the Boltzmann tyranny limit open design space for 48V-to-12V datacenter power converters.
- RF front-end reconfigurability:Polarization-switching impedance matching enables tunable antennas for 5G mmWave and satellite communication terminals.
- EU Chips Act funding:European semiconductor sovereignty initiatives direct capital toward non-volatile logic pilot lines in Dresden and Leuven.
Industry Challenges
- Process integration talent scarcity:Foundries compete for specialists spanning ferroelectric thin-film physics, ALD reactor tuning, and advanced node transistor design.
- Reliability qualification timelines:Ten-year data retention and 10^12 cycle endurance testing for embedded memory bitcells extend productization schedules.
- Cross-licensing complexity:Patent thickets covering hafnium oxide ferroelectricity, ferroelectric FET architectures, and ALD process recipes fragment IP ownership across academic labs and industrial consortia.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ferroelectric FET Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,802.76 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital FET, Analog FET, RF FET, Power FET End User: Consumer Electronics, Automotive, Telecommunications, Industrial Application: Data Storage, Signal Amplification, Sensing, Power Conversion Technology: Silicon-Based, Gallium Nitride, Organic Materials, Hybrid Technology |
| Companies Covered | Toshiba, Applied Materials, Texas Instruments, TSMC, GlobalFoundries, Fujitsu, Ferroelectric Memory Company, Intel, Infineon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ferroelectric FET Market Shifts & Advancements
Hafnium zirconium oxide integration is compressing the boundary between logic and memory functions, enabling new compute paradigms while regulatory frameworks scramble to accommodate persistent-state edge devices.
Ferroelectric negative capacitance is converging with power converter design, where gate-stack polarization dynamics enable sub-threshold swing operation below 60 mV/decade. Datacenter power architects at hyperscale operators are evaluating 48V direct conversion topologies using FeFET-based switches. This technology is converging with gallium nitride power stages to displace traditional silicon MOSFETs in high-density rack power supplies.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of hafnium precursor chemistries used in ferroelectric film deposition. Equipment suppliers must requalify alternative metal-organic compounds for atomic layer deposition reactors. European foundry pilot lines in Belgium and Germany face the steepest compliance timelines as they scale hafnium zirconium oxide capacity.
Memory procurement at cloud operators is fragmenting between volatile DRAM refresh and persistent FeFET cache tiers, with buyers negotiating separate supply contracts for each technology class. Foundry direct sourcing of ferroelectric wafers is displacing merchant memory vendor relationships in advanced node engagements. This bifurcation is most visible in Taiwan's semiconductor ecosystem, where TSMC and partners internalize critical film growth while maintaining legacy DRAM supply for transitional architectures.
Ferroelectric FET Market Segmentation
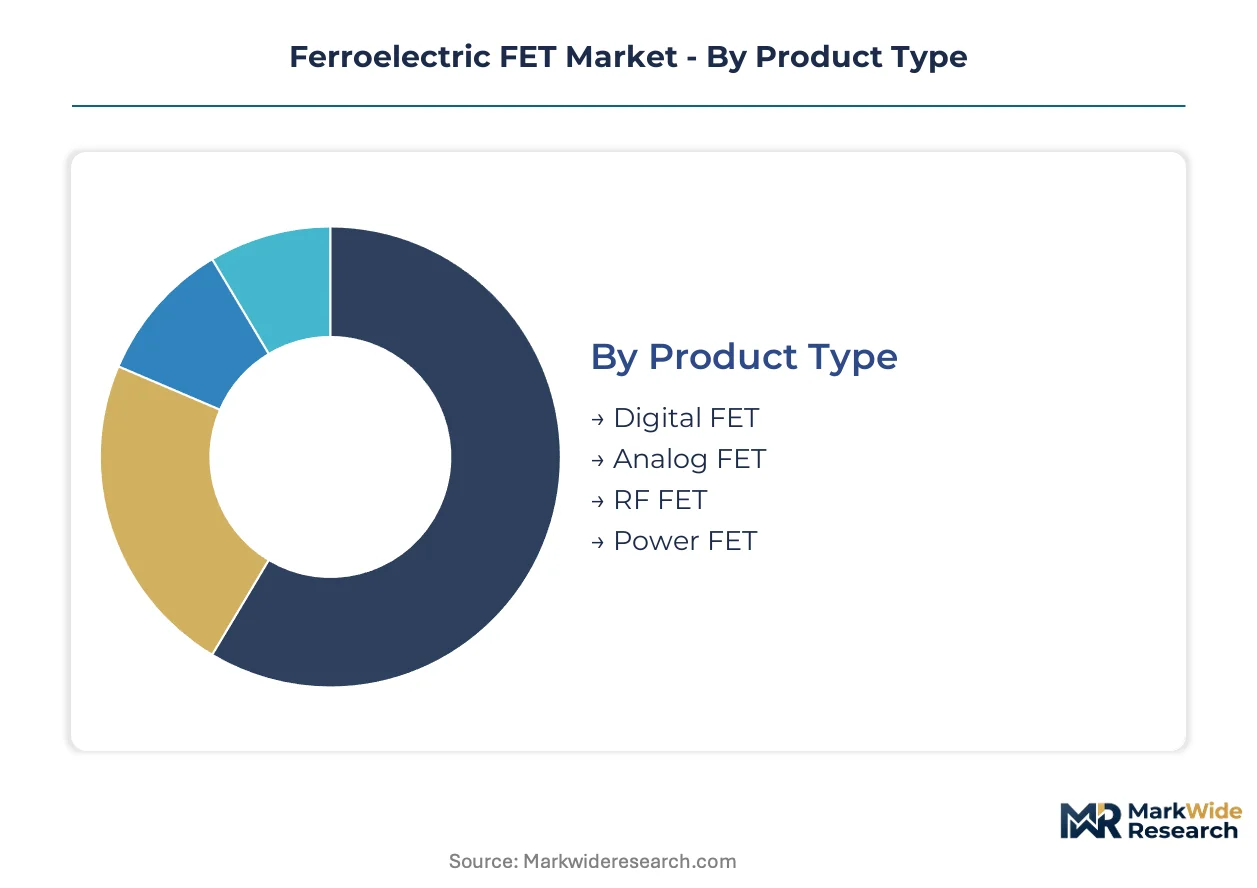
FeFET segmentation reveals divergent capital requirements across device architectures, with memory-intensive variants demanding specialized deposition equipment while power applications require co-development with wide-bandgap semiconductor platforms. Foundry qualification timelines vary dramatically by segment, creating asymmetric investment windows for equipment suppliers and materials vendors.
Product Type:
Digital FET architectures command the steepest upfront capital outlays due to sub-10nm node integration complexity and multi-patterning lithography requirements.
- Digital FET:Binary non-volatile logic devices incorporating hafnium zirconium oxide gate stacks with orthorhombic phase crystallinity. Demand concentrates in Taiwan's foundry ecosystem where TSMC pilots embedded memory replacement for advanced node cache. The segment drives the bulk of ALD equipment procurement for ferroelectric film deposition.
- Power FET:Negative capacitance switches exploiting ferroelectric polarization dynamics to break the Boltzmann tyranny limit. Datacenter power architects at hyperscale operators evaluate 48V direct conversion topologies in Dresden and Leuven pilot lines. Capital intensity stems from co-packaging with gallium nitride power stages.
- Analog FET:Precision amplification devices leveraging polarization-dependent transconductance for sensor interfaces.
- RF FET:Reconfigurable front-end transistors enabling tunable impedance matching through polarization switching.
Digital FET absorbs the bulk of installed capacity; Power FET is expanding most quickly.
End User:
Automotive qualification protocols impose the longest validation cycles, stretching procurement timelines while inflating non-recurring engineering costs per design win.
- Automotive:Functional safety systems requiring instant state retention under power-loss scenarios per ISO 26262 mandates. Infineon and Fujitsu anchor development in Germany and Japan, targeting fail-safe logic for electric vehicle powertrain controllers. Regulatory compliance extends productization schedules by 18-24 months versus consumer applications.
- Consumer Electronics:Cost-sensitive storage and compute devices where FeFET competes against mature NAND flash. Procurement concentrates in South Korea and Taiwan for smartphone embedded memory and wearable persistent cache tiers. Price pressure from sub-4-cent-per-gigabyte flash limits addressable market scope.
- Telecommunications:5G infrastructure and satellite communication terminals demanding reconfigurable RF front-ends.
- Industrial:Edge AI inference nodes requiring non-volatile local storage without cloud dependency.
Automotive commands the highest qualification burden; Consumer Electronics offers the steepest volume ramp once cost thresholds cross.
Application:
Data storage applications concentrate equipment utilization in memory fab environments, while power conversion spreads capital across discrete packaging and module assembly.
- Data Storage:Embedded non-volatile memory bitcells replacing SRAM and flash in advanced logic nodes. TSMC and partners internalize critical hafnium zirconium oxide film growth for this segment, displacing merchant memory vendor relationships. Ten-year data retention and 10^12 cycle endurance testing govern reliability qualification.
- Power Conversion:48V-to-12V datacenter rack supplies leveraging ferroelectric negative capacitance for sub-threshold swing operation. Development clusters in Belgium and Germany align with EU Chips Act funding for sovereign semiconductor capacity. Integration with existing silicon carbide and gallium nitride ecosystems determines commercial viability.
- Signal Amplification:Low-noise analog front-ends for medical and industrial sensor interfaces.
- Sensing:Piezoelectric-coupled transducers exploiting ferroelectric polarization for mechanical strain detection.
Data Storage captures dominant equipment hours; Power Conversion is climbing the fastest as hyperscale operators validate topologies.
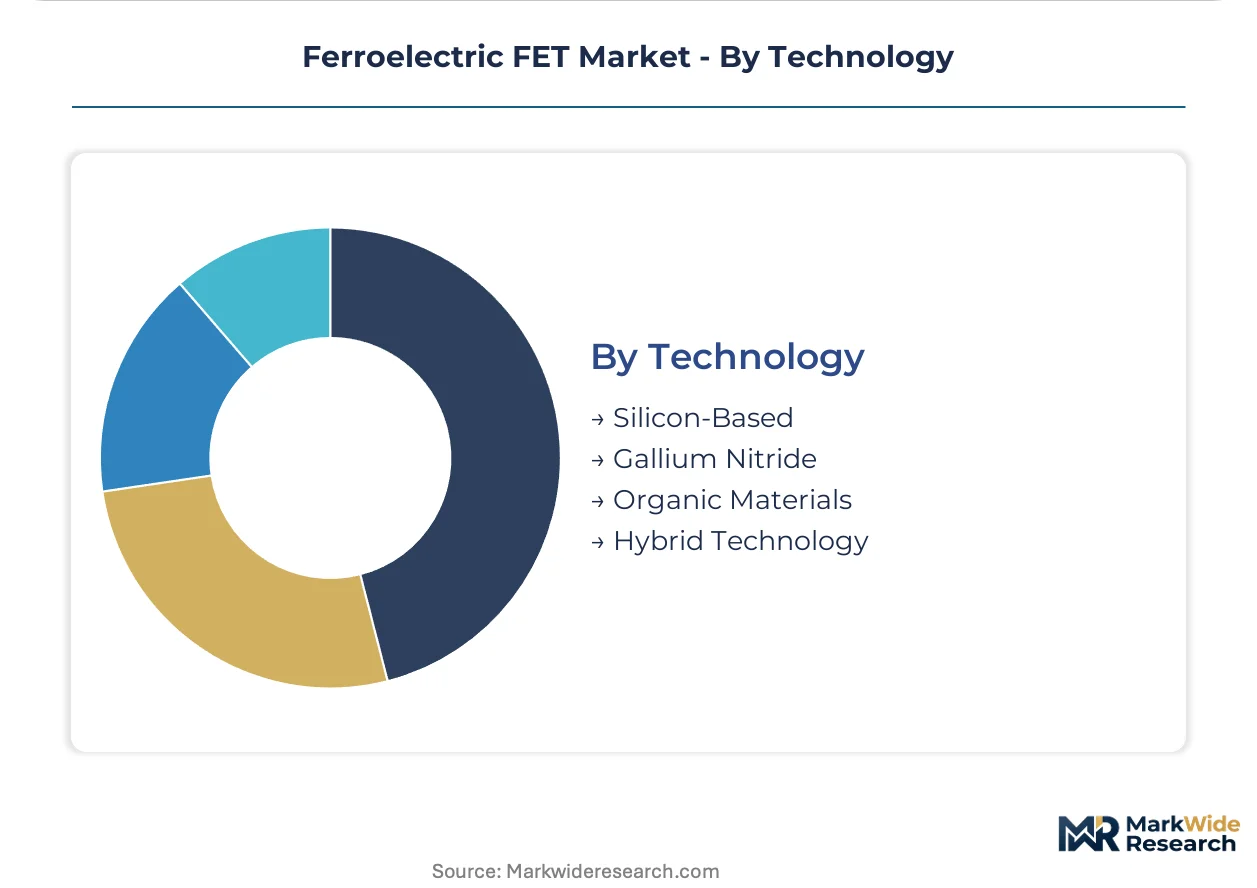
Technology:
Silicon-based platforms leverage existing foundry infrastructure, while hybrid approaches demand greenfield integration lines with unproven depreciation schedules.
- Silicon-Based:CMOS-compatible FeFET architectures using conventional silicon substrates and standard logic process flows. IMEC breakthroughs in orthorhombic phase crystallinity mature toward commercial deployment in Leuven and Dresden pilot lines. The technology pathway minimizes capital risk by extending existing 300mm wafer investments.
- Gallium Nitride:Wide-bandgap heterointegration for power FET applications combining ferroelectric gate stacks with GaN HEMT channels. Development concentrates in US and Japanese power semiconductor houses targeting 650V and above switching applications. Thermal expansion mismatch between heterolayers complicates packaging economics.
- Organic Materials:Solution-processed ferroelectric polymers for flexible and large-area electronics.
- Hybrid Technology:Multi-material stacks combining oxide ferroelectrics with 2D channel materials or ferromagnetic layers.
Silicon-Based holds the installed base; Gallium Nitride is gaining share fastest in power segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hafnium oxide precursor supply chains anchor geographic concentration in Germany and Japan, while foundry demand clusters in Taiwan and pilot line development spreads across Belgium and the United States.
United States
Hyperscale datacenter operators drive procurement of FeFET-based power converters for 48V rack architectures. EPA hazardous material rules constrain hafnium precursor handling protocols, extending supplier qualification timelines. Austin and Silicon Valley clusters host power semiconductor development targeting negative capacitance integration with existing silicon carbide ecosystems.
Germany
Automotive functional safety mandates per ISO 26262 accelerate Infineon development of fail-safe logic with instant state retention. ECHA REACH restrictions on per- and polyfluoroalkyl substances force reformulation of metal-organic precursor chemistries. Dresden pilot lines leverage EU Chips Act funding to scale hafnium zirconium oxide capacity for sovereign semiconductor production.
Japan
Fujitsu anchors decades of ferroelectric memory expertise toward early FeFET device architectures for industrial applications. METI industrial policy directs capital toward non-volatile logic pilot programs. Tokyo and Osaka metropolitan areas concentrate ALD equipment supplier relationships and specialty gas vendor networks.
Taiwan
TSMC sustains process leadership by integrating ferroelectric modules into advanced logic nodes for embedded memory replacement. The national semiconductor strategy prioritizes captive hafnium oxide deposition to internalize critical film growth. Hsinchu Science Park clusters foundry ecosystem partners piloting FeFET bitcell yield qualification.
Belgium
IMEC breakthroughs in orthorhombic phase crystallinity mature toward commercial CMOS compatibility with sub-1-volt switching thresholds. ECHA compliance timelines for REACH-regulated precursors create urgency in Leuven pilot line scaling. The Flanders region concentrates atomic layer deposition equipment deployment for ferroelectric stack development.
Ferroelectric FET Market Competitive Landscape
Capacity expansion dominates the current landscape as foundries race to qualify hafnium zirconium oxide bitcell yield at advanced nodes. The vendor base stratifies across three tiers: integrated device manufacturers with captive fabrication, pure-play foundries licensing ferroelectric modules, and equipment suppliers controlling deposition tool oligopolies. Two strategic archetypes define positioning: process technology leaders internalizing critical film growth, and materials specialists supplying qualified precursor chemistries. Competitive moves concentrate on strategic partnerships for ALD reactor co-development and vertical integration into hafnium oxide deposition capacity.
Among Asia-Pacific-based foundries, TSMC exemplifies the process-technology-leader archetype through advanced node ferroelectric integration, while Toshiba represents integrated device manufacturers leveraging historical ferroelectric memory expertise. Applied Materials occupies a position within the equipment tier, anchoring deposition and anneal equipment supply for hafnium zirconium oxide stacks. These three entities collectively illustrate the competitive structure binding foundry demand to materials and equipment supply constraints.
| Leading Market Players |
|---|
| Toshiba |
| Applied Materials |
| Texas Instruments |
| TSMC |
| GlobalFoundries |
| Fujitsu |
| Ferroelectric Memory Company |
| Intel |
| Infineon Technologies |
| Others |
Supply & Pricing Matrix
Hyperscale datacenter procurement teams concentrate purchasing power for FeFET-based power converters, anchoring contract-based long-term offtake as the dominant pricing structure for high-volume engagements.
Pricing Analysis
Warranty and reliability qualification bundling separates automotive-grade FeFET supply from unbundled consumer electronics procurement, with ISO 26262-certified devices commanding substantial premiums over standard logic variants. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by endurance cycling, data retention guarantees, and foundry node maturity. Pricing pressure stems from mature NAND flash cost floors below four cents per gigabyte, compressing FeFET margins in cost-sensitive storage applications. Consumer electronics buyers exhibit highest price sensitivity, while automotive and medical edge compute segments absorb premium positioning for functional safety assurance.
Supply Chain Analysis
EPA and ECHA certification requirements for hafnium precursor handling gate qualified suppliers to specialty chemical vendors in Germany and Japan, constraining atomic layer deposition feedstock availability. Taiwan, Belgium, and Germany anchor ferroelectric film production, with hafnium zirconium oxide deposition drawing from captive foundry capacity and merchant precursor supply. Single-source vulnerability concentrates in ALD equipment manufacturing, where two dominant vendors control reactor deployment. Distribution runs through direct foundry engagement for advanced node wafers, displacing traditional memory vendor relationships in leading-edge procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Atomic layer deposition equipment bottlenecks prop pricing power for qualified reactor suppliers, as foundry capacity expansion outpaces certified tool installation timelines.
For Market Incumbents: Cement process leadership by locking exclusive ALD reactor co-development agreements with deposition equipment specialists before competitor qualification cycles complete. Prioritize captive hafnium oxide deposition capacity in Taiwan and Belgium to defend against emerging merchant film suppliers. Infineon and Fujitsu's automotive anchor positions face encroachment from TSMC's advanced node integration, demanding accelerated ISO 26262 certification investment. For New Entrants and Emerging Players: Ferroelectric negative capacitance power FET architectures offer the most penetrable white-space, as hyperscale datacenter operators seek alternatives to silicon MOSFETs in 48V rack supplies. Target EU Chips Act-funded pilot lines in Dresden and Leuven for initial qualification partnerships. A technology licensing model to second-tier foundries bypasses capital-intensive reactor ownership barriers. For Investors and Strategic Acquirers: The window for entry favors specialty gas and precursor chemistry specialists with ECHA REACH-compliant hafnium formulations. Long-term viability hinges on ten-year data retention qualification completion at leading foundries. Watch for the first announced FeFET bitcell yield qualification at sub-10nm nodes as the inflection signal triggering equipment pull-through acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ALD Reactor Co-Development Partnership | Applied Materials and TSMC collaboration locks in deposition tool specifications for advanced node FeFET integration. |
| Captive Hafnium Oxide Deposition Buildout | Foundry internalization of critical film growth in Hsinchu Science Park reduces precursor supply concentration risk. |
| EU Chips Act Pilot Line Funding | IMEC and Dresden consortia secure sovereign capacity for non-volatile logic qualification outside Taiwan's ecosystem. |
| REACH-Compliant Precursor Reformulation | German and Japanese specialty gas vendors requalify metal-organic compounds ahead of ECHA perfluoroalkyl substance restrictions. |
| Automotive Functional Safety Certification | Infineon's ISO 26262 qualification investment targets instant state retention for electric vehicle powertrain controllers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with foundry process integration engineers, ALD equipment specialists, automotive semiconductor procurement managers, and hafnium precursor supply chain directors. SEC 10-K disclosures, ECHA REACH substance registrations, and Taiwan's national semiconductor strategy documents provided secondary validation. Bottom-up bitcell yield projections and top-down equipment spending estimates were triangulated against foundry capex announcements.
Segmentation granularity modeled device architecture, end-use vertical, application function, and technology platform across the projection horizon. Digital FET, Power FET, and RF FET variants were tracked separately with foundry node qualification timelines as a cross-cutting dimension. CAGRs derived from equipment procurement forecasts and memory fab utilization rates incorporated hafnium zirconium oxide deposition capacity buildout assumptions.
Several conditions sit outside the modeled scope, including unannounced breakthroughs in alternative non-volatile memory technologies and geopolitical disruptions to hafnium ore supply from Australia and African sources. Forecasts reflect assumptions about orthorhombic phase crystallinity yield maturation and EPA precursor handling rule stability. A model refresh is warranted upon material change in TSMC or Intel FeFET bitcell qualification announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Gallium Nitride (Gan) Semiconductor Devices Market
Semiconductor Devices
Chip Equalizers Market
Semiconductor Devices
COF (Chip-On-Film) Market
Semiconductor Devices
Automotive Grade Emmc Market
Semiconductor Devices
Silicon Epitaxial Wafer Market
Semiconductor Devices
Pcie Switches Market
Semiconductor Devices
Asia-Pacific Semiconductor Device Market
Semiconductor Devices
Programmable Logic Device (PLD) Market
Semiconductor Devices
Large-Size PV Silicon Wafer Market
Semiconductor Devices
IGBT and Super Junction MOSFET Market
Semiconductor Devices
APAC Semiconductor Device in Consumer Industry Market
Semiconductor Devices
Japan MLCC Market
Semiconductor Devices
Semiconductor Memory IP Market
Semiconductor Devices
High Resistivity Silicon Wafers Market
Semiconductor Devices
North America Silicon Carbide Wafers Market
Semiconductor Devices
Global Trench Gate Power MOSFET Market