
 Germany Digital Pathology Market | 2026-2036
Germany Digital Pathology Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Digital Pathology Market Insights
Cloud-native storage architectures are shifting cost structures away from capital-intensive on-premise server farms. Carl Zeiss AG leverages its microscopy heritage to anchor premium scanner placements in German university hospitals. 3DHISTECH Ltd. competes through modular hardware configurations that accommodate mid-tier diagnostic laboratories. F. Hoffmann-La Roche AG (Ventana) extends its immunohistochemistry dominance into digital workflow integration.
Digital pathology encompasses the acquisition, management, and computational analysis of digitized histopathological specimens using whole-slide imaging systems that typically achieve 20x or 40x optical magnification with sub-micron resolution, enabling remote diagnosis and quantitative biomarker assessment. Its primary purpose is to replace physical glass-slide logistics with scalable data infrastructure for clinical and research workflows. Whole Slide Imaging currently occupies the largest product segment as German pathology institutes prioritize scanner fleet standardization. Artificial Intelligence within the Technology dimension represents the fastest-expanding margin pool, though cloud-based solutions sustain broader deployment volume across hospital networks constrained by IT security protocols.
Germany's Federal Institute for Drugs and Medical Devices (BfArM) and the EU Medical Device Regulation (MDR) impose conformity assessment requirements on diagnostic software, while the Digital Healthcare Act (DVG) structures reimbursement eligibility for digitally enabled care pathways. These frameworks compel vendors to maintain parallel regulatory competencies across national and European channels. Stakeholders must monitor how BfArM's evolving digital health application assessment criteria interact with MDR notified body capacity constraints to determine viable commercialization timelines.
Market Dynamics
Cloud-native storage architectures are compressing capital requirements for German pathology institutes while the EU Medical Device Regulation accelerates software certification timelines for AI-assisted diagnostic tools.
Growth Catalysts
- Digital Healthcare Act (DVG):The DVG establishes reimbursement pathways for digitally enabled care pathways, compelling hospital networks to accelerate procurement of whole-slide imaging systems.
- Whole-slide imaging standardization:University hospital networks across Berlin, Munich, and Heidelberg are consolidating scanner fleets to enable molecular diagnostics workflow integration.
- Bavaria and Baden-Württemberg:Academic medical centers in these states are expanding procurement of whole-slide imaging systems to anchor regional pathology digitization hubs.
Market Restraints
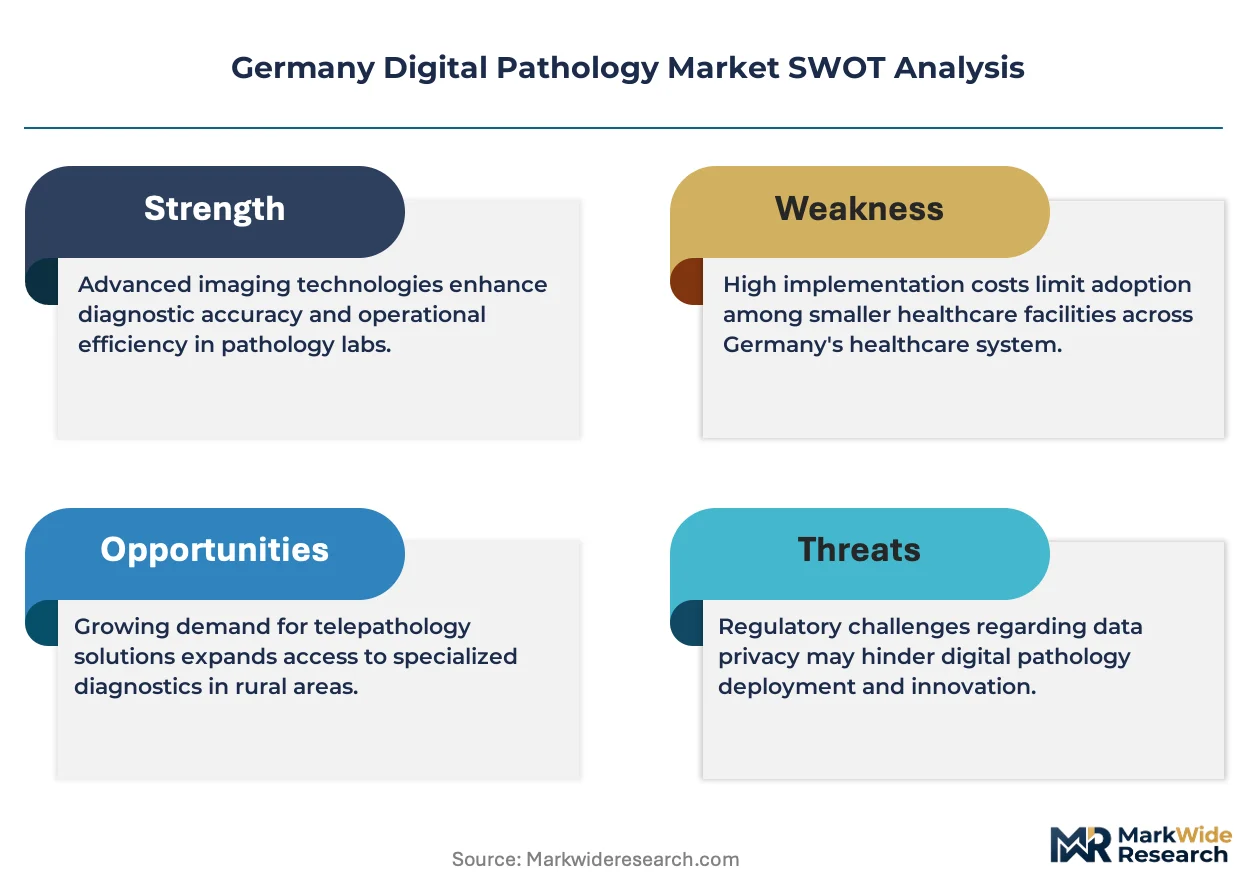
- IT security protocol constraints:Hospital networks face structural barriers deploying cloud-based solutions due to stringent data sovereignty requirements under German federal data protection frameworks.
- MDR notified body capacity:Bottlenecks in EU Medical Device Regulation conformity assessment capacity are extending commercialization timelines for diagnostic software vendors.
- Capital intensity of scanner hardware:Premium whole-slide imaging systems require substantial upfront investment, limiting deployment in mid-tier diagnostic laboratories.
Strategic Opportunities
- AI-assisted diagnostics convergence:Integration of artificial intelligence with whole-slide imaging is creating new margin pools in quantitative biomarker assessment applications.
- Baden-Württemberg research corridor:Heidelberg's molecular diagnostics concentration offers underpenetrated deployment opportunities for computational pathology platforms.
- Modular hardware configurations:Flexible scanner architectures accommodate mid-tier laboratories seeking phased digitization without full fleet replacement.
Industry Challenges
- BfArM assessment criteria evolution:Shifting digital health application evaluation standards at Germany's Federal Institute for Drugs and Medical Devices create compliance timeline uncertainty for vendors maintaining parallel national and European regulatory competencies.
- Legacy system integration complexity:Pathology institutes face operational friction connecting new digital workflows with existing laboratory information management systems and hospital IT infrastructure.
- Computational pathology talent scarcity:Shortage of professionals combining histopathology expertise with bioinformatics and machine learning competencies constrains implementation velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Digital Pathology Market |
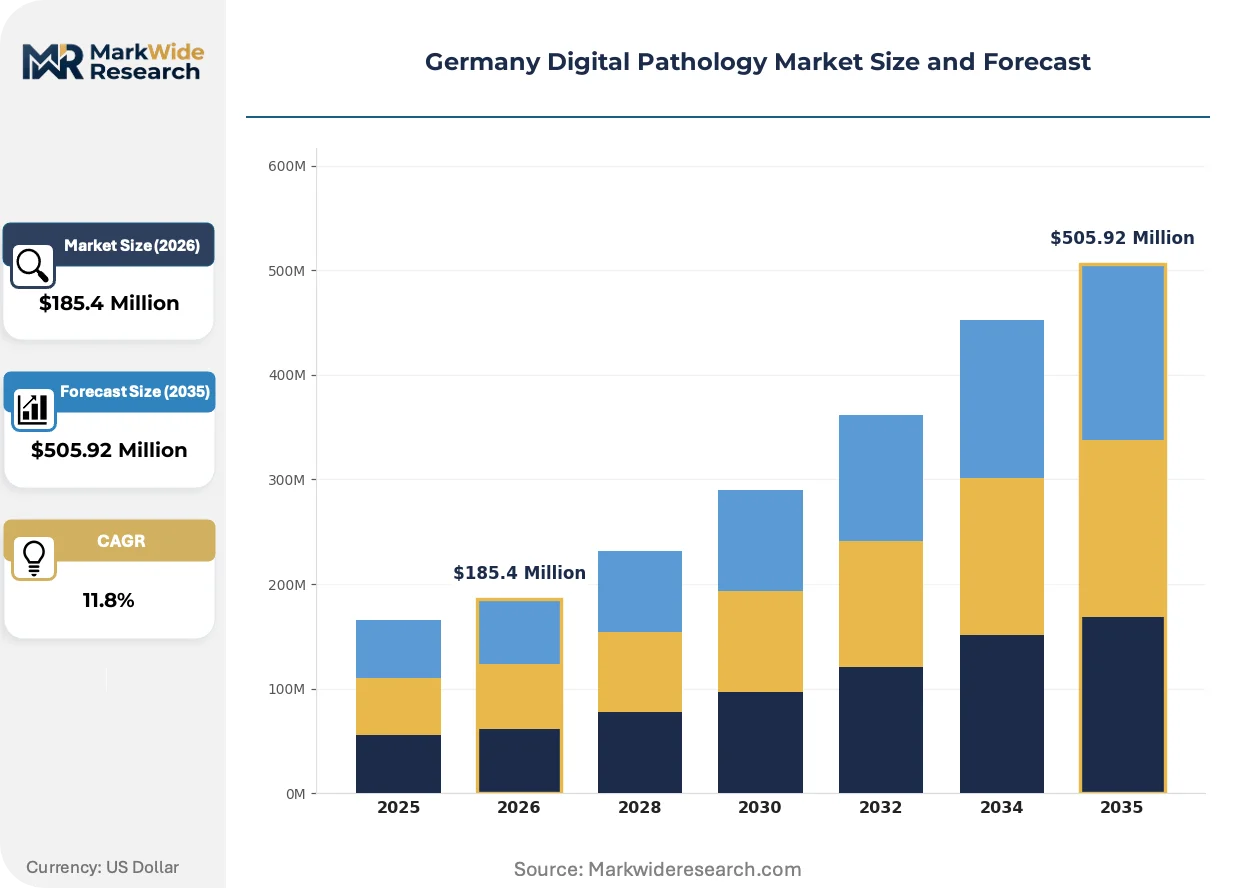
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $505.92 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Slide Imaging, Digital Scanners, Image Management Software, Analysis Software End User: Hospitals, Diagnostic Laboratories, Research Institutes, Educational Institutions Technology: Artificial Intelligence, Cloud-Based Solutions, Machine Learning, Image Recognition Application: Telepathology, Education, Clinical Diagnosis, Research |
| Companies Covered | Carl Zeiss AG, 3DHISTECH Ltd., F. Hoffmann-La Roche AG (Ventana), Visiopharm A/S, Hamamatsu Photonics K.K., Koninklijke Philips N.V., Sectra AB, VMscope GmbH, Leica Biosystems Nussloch GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Digital Pathology Market Trends and Innovations
Computational analysis capabilities are transforming how German pathology institutes process histopathological specimens, with three distinct forces reshaping technology deployment, regulatory compliance, and procurement behavior.
Artificial intelligence is rewriting diagnostic workflows by enabling quantitative biomarker assessment from digitized specimens at sub-micron resolution. University hospital networks are adopting AI-assisted analysis tools at accelerating pace to integrate with molecular diagnostics pipelines. This compression of analytical timelines is enabling remote diagnosis capabilities while reducing pathologist review bottlenecks in high-volume screening programs.
The EU Medical Device Regulation imposes conformity assessment requirements on diagnostic software that interact with Germany's national implementation frameworks. BfArM's evolving digital health application criteria are creating parallel compliance obligations for vendors seeking market access. AI-assisted diagnostic modules face the most stringent scrutiny, with manufacturers responding by front-loading clinical validation investments to secure notified body approvals.
Scanner fleet standardization is consolidating procurement decisions within centralized hospital network IT governance structures. Mid-tier diagnostic laboratories are losing direct purchasing autonomy as Bavarian and Baden-Württemberg academic medical centers anchor regional procurement consortia. This concentration is most visible in Berlin's university hospital network, where pathology digitization budgets now flow through centralized digital transformation offices rather than individual institute capital committees.
Germany Digital Pathology Market Segmentation
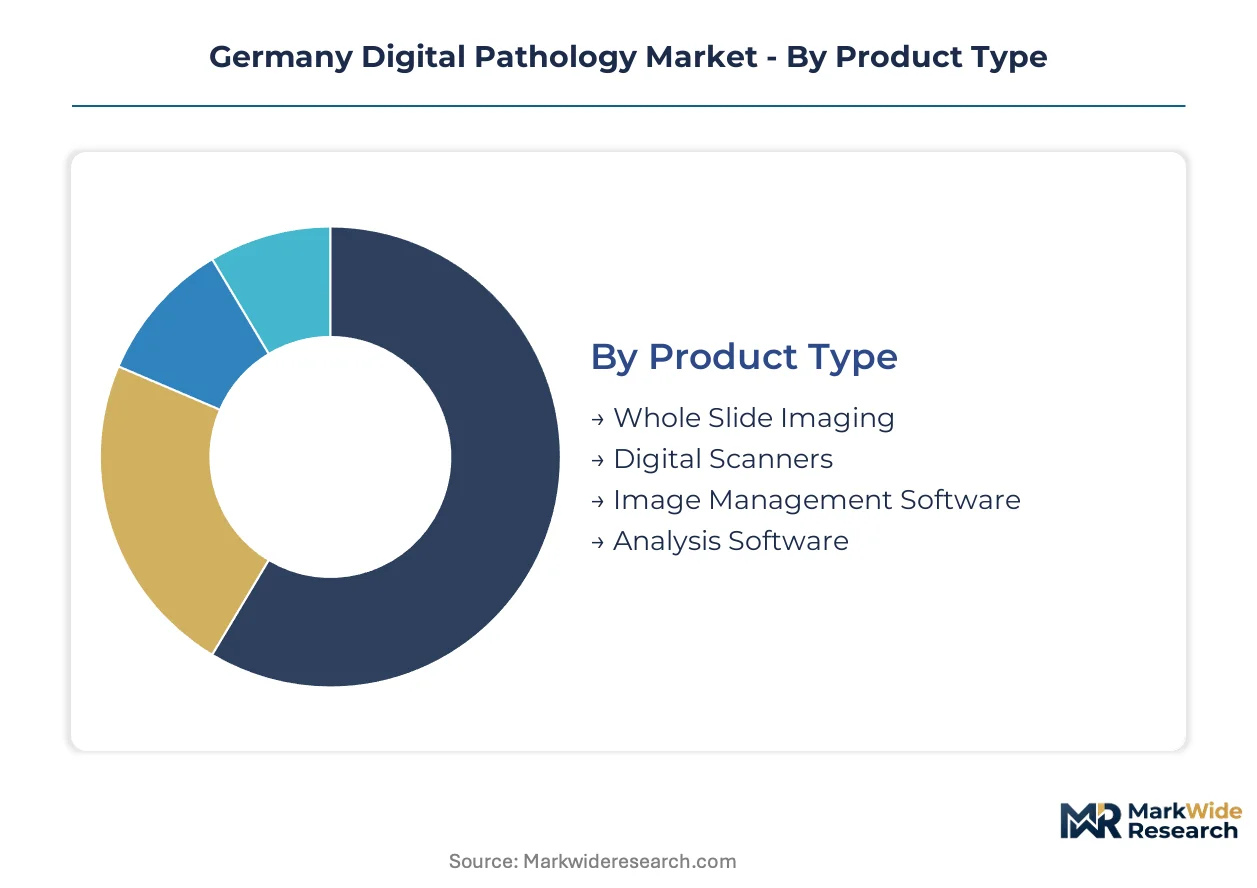
Segmentation in the Germany Digital Pathology Market reveals how procurement authority concentrates in academic medical centers while mid-tier laboratories seek phased deployment pathways. Understanding these divisions exposes where standardization pressures override cost sensitivity and where modular architectures unlock access.
Product Type:
Standalone hardware systems dominate capital budgets while embedded software modules integrate into existing laboratory information management infrastructure.
- Whole Slide Imaging:Scanner fleets achieving 20x or 40x optical magnification with sub-micron resolution form the backbone of digitization efforts. University hospital networks across Berlin, Munich, and Heidelberg prioritize fleet standardization to enable molecular diagnostics workflow integration, though upfront capital intensity limits deployment in mid-tier diagnostic laboratories.
- Digital Scanners:Hardware units convert physical glass slides into high-resolution digital formats at throughput rates determining laboratory operational capacity. Bavarian and Baden-Württemberg academic medical centers anchor regional procurement consortia that concentrate purchasing decisions within centralized IT governance structures.
- Image Management Software:Platforms orchestrating storage, retrieval, and workflow routing of digitized specimens.
- Analysis Software:Computational tools enabling quantitative biomarker assessment from digitized histopathological specimens.
Volume placements concentrate in Whole Slide Imaging; the faster expansion belongs to Analysis Software.
End User:
Customer types separate by regulatory compliance burden and integration complexity with existing hospital IT infrastructure.
- Hospitals:University hospital networks command procurement authority through centralized digital transformation offices rather than individual institute capital committees. The Digital Healthcare Act structures reimbursement eligibility for digitally enabled care pathways, compelling these networks to accelerate whole-slide imaging system procurement.
- Diagnostic Laboratories:Mid-tier facilities face structural barriers deploying cloud-based solutions due to stringent data sovereignty requirements under German federal data protection frameworks. Modular hardware configurations accommodate their need for phased digitization without full fleet replacement.
- Research Institutes:Heidelberg's molecular diagnostics concentration offers concentrated deployment opportunities for computational pathology platforms.
- Educational Institutions:Training programs in Bavaria and Baden-Württemberg generate demand for entry-level scanner configurations.
Procurement volume clusters in Hospitals; Research Institutes are climbing the fastest.
Technology:
Technology layers stack from infrastructure through algorithmic capability, with cloud architectures enabling scale and AI modules capturing margin.
- Artificial Intelligence:Diagnostic modules enabling quantitative biomarker assessment face the most stringent scrutiny under BfArM's evolving digital health application criteria. Manufacturers front-load clinical validation investments to secure notified body approvals under EU Medical Device Regulation conformity assessment requirements.
- Cloud-Based Solutions:Storage architectures compress capital requirements for pathology institutes while hospital networks face IT security protocol constraints limiting deployment velocity. Data sovereignty requirements under German federal frameworks create structural barriers to adoption despite operational advantages.
- Machine Learning:Algorithmic training pipelines requiring histopathology expertise combined with bioinformatics competencies.
- Image Recognition:Pattern detection capabilities automating preliminary screening and classification tasks.
Deployment breadth favors Cloud-Based Solutions; steepest expansion trajectory belongs to Artificial Intelligence.
Application:
Use cases separate by revenue model clarity, with clinical applications commanding premium pricing and research applications tolerating longer validation cycles.
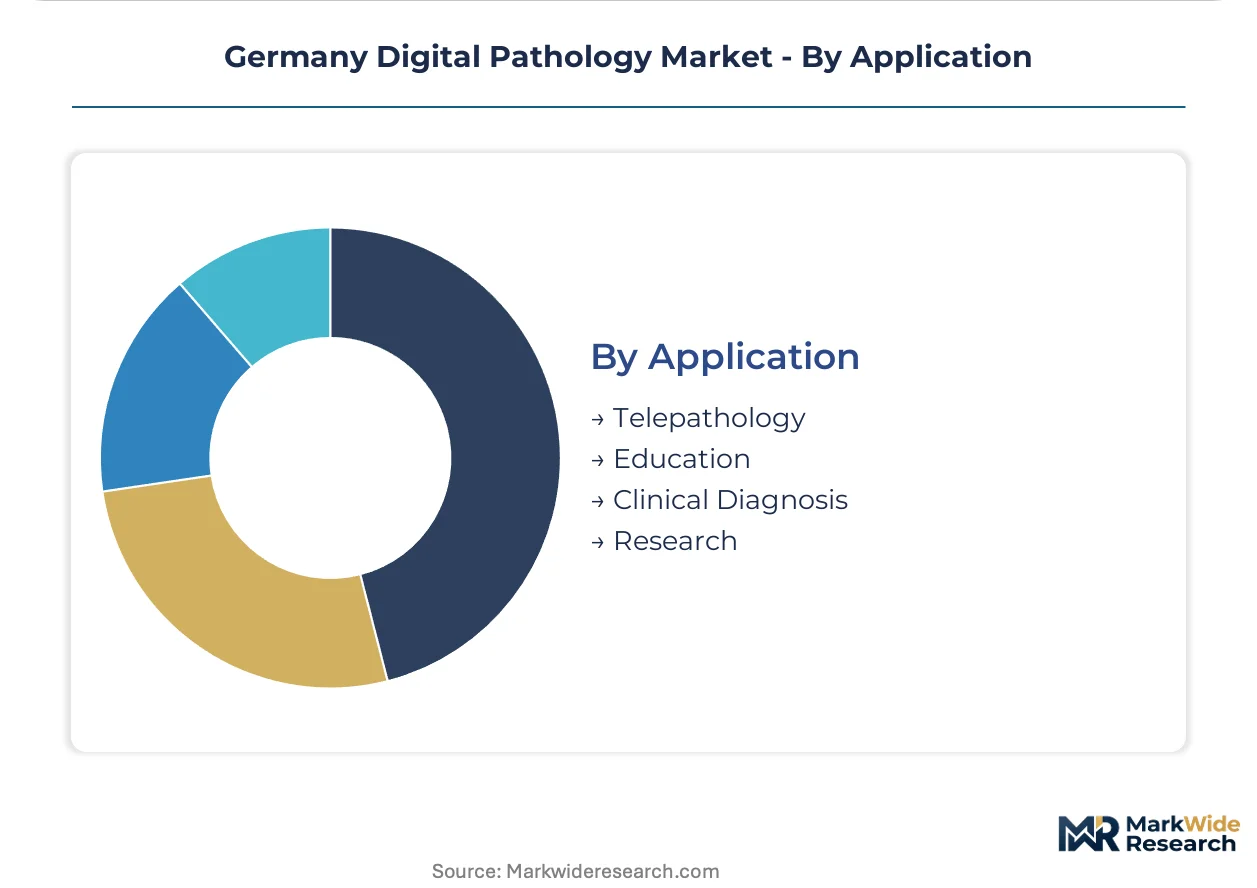
- Telepathology:Remote diagnostic capabilities reduce pathologist review bottlenecks in high-volume screening programs while enabling specialist consultation across distributed hospital networks. Cloud infrastructure requirements intersect with German data sovereignty constraints to complicate deployment architecture decisions.
- Clinical Diagnosis:Diagnostic workflows integrating with molecular diagnostics pipelines command highest software licensing values. AI-assisted analysis tools compress analytical timelines while facing stringent BfArM assessment criteria for reimbursement eligibility under Digital Healthcare Act provisions.
- Education:Training applications in university medical centers generate demand for standardized scanner configurations.
- Research:Experimental workflows tolerate longer validation cycles and less regulatory scrutiny than clinical deployments.
Revenue concentration sits with Clinical Diagnosis; Telepathology is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement authority concentrates in university hospital networks across Berlin, Munich, and Heidelberg, where pathology digitization budgets flow through centralized digital transformation offices rather than individual institute capital committees.
Bavaria
Academic medical centers in Munich and Erlangen anchor regional procurement consortia for whole-slide imaging systems. The Digital Healthcare Act structures reimbursement eligibility for digitally enabled care pathways, compelling these networks to accelerate scanner fleet standardization. Bavaria's university hospitals integrate pathology digitization with molecular diagnostics workflows at the Technical University of Munich campus.
Baden-Württemberg
Heidelberg's molecular diagnostics concentration offers underpenetrated deployment opportunities for computational pathology platforms. BfArM's evolving digital health application criteria create parallel compliance obligations for vendors seeking market access in this research corridor. The University Hospital Heidelberg anchors regional digitization efforts alongside Mannheim's diagnostic laboratory networks.
Berlin-Brandenburg
Charité – Universitätsmedizin Berlin commands procurement authority through centralized IT governance structures that consolidate pathology digitization budgets. EU Medical Device Regulation conformity assessment requirements extend commercialization timelines for diagnostic software vendors targeting this network. Berlin's university hospital network prioritizes AI-assisted analysis tools for quantitative biomarker assessment applications.
North Rhine-Westphalia
University hospitals in Cologne and Düsseldorf face structural barriers deploying cloud-based solutions due to stringent data sovereignty requirements under German federal data protection frameworks. The DVG establishes reimbursement pathways that nonetheless compel these networks toward whole-slide imaging procurement. Mid-tier diagnostic laboratories in the Ruhr region seek modular hardware configurations for phased digitization.
Hesse
Goethe University Hospital Frankfurt integrates digital pathology with existing laboratory information management systems amid legacy system integration complexity. BfArM assessment criteria evolution creates compliance timeline uncertainty for vendors maintaining parallel national and European regulatory competencies. Frankfurt's diagnostic laboratories concentrate demand for image management software platforms.
Germany Digital Pathology Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors navigate parallel regulatory competencies across national and European channels. The vendor base clusters around three distinct archetypes: microscopy heritage specialists leveraging optical engineering expertise, modular hardware configurators targeting mid-tier laboratories, and immunohistochemistry incumbents extending into digital workflow integration. M&A activity and technology licensing agreements represent the dominant competitive moves as manufacturers seek to compress clinical validation timelines.
Among Germany-based heritage specialists, Carl Zeiss AG occupies a position exemplifying premium scanner placement strategies in university hospital networks. 3DHISTECH Ltd. and VMscope GmbH represent the modular configuration archetype, with the latter anchoring regional vendor presence in domestic mid-tier diagnostic laboratories. F. Hoffmann-La Roche AG (Ventana) exemplifies the IHC-to-digital extension pattern, leveraging existing diagnostic workflow relationships.
| Leading Market Players |
|---|
| Carl Zeiss AG |
| 3DHISTECH Ltd. |
| F. Hoffmann-La Roche AG (Ventana) |
| Visiopharm A/S |
| Hamamatsu Photonics K.K. |
| Koninklijke Philips N.V. |
| Sectra AB |
| VMscope GmbH |
| Leica Biosystems Nussloch GmbH |
| Others |
Pricing and Supply Chain Analysis
Computational pathology talent scarcity in Baden-Württemberg and Bavaria widens spreads between premium AI-assisted diagnostic modules and economy-tier scanner hardware, as labor-cost differentials in algorithm development versus optical engineering propagate through vendor pricing architectures.
Pricing Analysis
Volume placements cluster in whole-slide imaging hardware while margin capture concentrates in artificial intelligence software modules. Three-tier pricing structure across premium, standard, and economy levels separates Carl Zeiss AG's university hospital scanner placements from 3DHISTECH Ltd.'s mid-tier laboratory configurations and entry-level educational systems. Pricing pressure stems from MDR notified body capacity constraints extending commercialization timelines for diagnostic software vendors. Mid-tier diagnostic laboratories exhibit highest price sensitivity due to capital intensity barriers, while university hospital networks prioritize standardization over cost optimization.
Supply Chain Analysis
Workforce availability in German precision optics manufacturing and Hungarian software development centers shapes component sourcing strategies for scanner hardware and AI algorithm training pipelines. Optical sensor arrays draw from Japanese and German component suppliers, while cloud storage infrastructure rests on domestic data center operators constrained by federal data sovereignty frameworks. Single-source vulnerability concentrates in high-magnification lens assemblies from Carl Zeiss AG's captive production. Distribution runs through regional procurement consortia anchored by Bavarian and Baden-Württemberg academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where MDR notified body capacity bottlenecks prop pricing power for vendors with secured conformity assessments.
For Market Incumbents: Anticipate consolidation pressure from modular hardware configurators targeting mid-tier laboratories by accelerating backward integration into AI algorithm development and securing BfArM pre-assessment consultations ahead of formal submission queues. Priority defensive moves center on locking hospital network procurement consortia through multi-year service bundling and preemptive clinical validation investments for reimbursement eligibility under DVG pathways. For New Entrants and Emerging Players: Cloud-native telepathology platforms represent the most penetrable wedge for new market access, targeting North Rhine-Westphalia diagnostic laboratories facing structural barriers to on-premise deployment. White-space concentration sits in modular subscription pricing for mid-tier facilities seeking phased digitization without full fleet replacement. Go-to-market execution should prioritize direct engagement with regional procurement consortia rather than individual institute capital committees. For Investors and Strategic Acquirers: Re-rating potential sits with AI-assisted diagnostics specialists given BfArM's evolving digital health application criteria creating scarcity value for notified body-approved algorithms. Long-term viability favors vendors combining computational pathology platforms with established hospital system relationships. Signal to watch is MDR notified body capacity expansion announcements as inflection indicator for commercialization timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Conformity Assessment Front-Loading | Clinical validation investments secure notified body approvals ahead of competitor queues under EU Medical Device Regulation. |
| Regional Procurement Consortium Lock-In | Multi-year service agreements with Bavarian academic medical centers preempt modular competitor access. |
| Cloud-Native Architecture Development | Subscription models bypass capital intensity barriers constraining mid-tier diagnostic laboratory adoption. |
| AI Algorithm Training Pipeline Investment | Proprietary datasets from Heidelberg molecular diagnostics workflows create differentiation in quantitative biomarker assessment. |
| DVG Reimbursement Pathway Navigation | Early BfArM engagement accelerates digitally enabled care pathway eligibility for hospital network procurement. |
Research Methodology
Regulatory filings from BfArM and EMA databases, hospital procurement records from Bavarian and Baden-Württemberg university networks, and EU Medical Device Regulation notified body capacity reports formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with pathology department heads, hospital IT procurement officers, biomedical engineers, and GPO contracts managers validated scanner fleet standardization trends and AI-assisted diagnostics adoption timelines. Bottom-up and top-down triangulation reconciled vendor shipment data with hospital network budget disclosures.
Bottom-up modeling aggregated scanner placements, software licensing values, and service contract values across product type, end user, technology, and application dimensions over the projection horizon. Top-down validation cross-referenced total addressable market estimates against German healthcare IT expenditure trends and DVG reimbursement pathway expansion trajectories. CAGRs derived from logistic adoption curve fitting for AI-assisted diagnostics and linear extrapolation for mature whole-slide imaging hardware replacement cycles. Forecast inputs incorporated BfArM assessment criteria evolution and MDR notified body capacity constraints.
Several conditions sit outside the modeled scope, including specific MDR implementation delays beyond notified body capacity bottlenecks, federal data sovereignty framework amendments affecting cloud deployment architecture, and unforeseen AI algorithm performance failures triggering regulatory reassessment. Forecasts reflect assumptions regarding DVG reimbursement pathway stability and academic medical center procurement authority concentration. Material deviation in MDR notified body capacity expansion, BfArM digital health application criteria, or federal data protection enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Digital Subtraction Angiography Market
Medical Imaging
Industrial Radiography Market
Medical Imaging
Portable Ultrasound Bladder Scanner Market
Medical Imaging
France Magnetic Resonance Imaging Market
Medical Imaging
Global Technetium-99M Market
Medical Imaging
X-Ray Flat Panel Detectors Market
Medical Imaging
Global Orthopedic Imaging Equipment Market
Medical Imaging
Global Nuclear Imaging Equipment Market
Medical Imaging
India Mammography Market
Medical Imaging
Preclinical Ultrasound Systems Market
Medical Imaging
Molecular Breast Imaging Market
Medical Imaging
Americas Interventional Radiology Market
Medical Imaging
Carotid Ultrasound Imaging Market
Medical Imaging
South Korea Nuclear Imaging Market
Medical Imaging
Germany Nuclear Imaging Market
Medical Imaging
US Digital Radiology Market