
 Global Computer Vision in Healthcare Market | 2026-2036
Global Computer Vision in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Global Computer Vision in Healthcare Market Foresight
North American AI chip production is decoupling from legacy semiconductor supply chains as foundries dedicate capacity to healthcare-optimized GPUs. NVIDIA Corporation leverages its CUDA ecosystem to anchor development pipelines for medical imaging startups. Siemens Healthineers sustains installed-base dominance through embedded computer vision modules on CT and MRI systems. GE HealthCare competes by integrating real-time surgical navigation with proprietary depth-sensing hardware.
Computer vision in healthcare encompasses algorithms and hardware systems that extract quantitative and qualitative information from medical images, video streams, and three-dimensional patient scans, typically operating at sub-millimeter spatial resolution and processing latency under 50 milliseconds for intraoperative applications. Its primary purpose is to augment clinician decision-making by automating detection, segmentation, and classification tasks across radiology, pathology, and endoscopy workflows. Medical imaging analysis commands the largest revenue share due to entrenched PACS infrastructure and radiologist workflow integration, while surgical assistance tools represent the fastest-expanding margin pool as hospitals seek to standardize outcomes across laparoscopic and robotic procedures. Deep learning dominates technology deployment, though pattern recognition retains relevance in resource-constrained settings where model compression and edge inference become critical.
FDA premarket authorization pathways for AI-enabled diagnostic devices establish the primary gating mechanism for commercial entry in the United States, while the EU AI Act and MDR impose conformity requirements that extend clinical validation obligations across European markets. China's NMPA has accelerated review timelines for domestically developed ophthalmology and lung-nodule detection algorithms, creating divergent regulatory gravity that shapes regional R&D allocation. Stakeholders must monitor evolving reimbursement codes for algorithm-specific professional fees, as payer decisions will determine whether computer vision deploys as a cost-saving automation tool or a premium-priced clinical service.
Market Dynamics
Algorithm-assisted diagnostic workflows are compressing radiologist review cycles from hours to minutes, forcing infrastructure reinvestment across hospital networks and imaging centers.
Growth Catalysts
- FDA 510(k) clearance acceleration:Streamlined premarket pathways for AI-enabled radiology software are shortening commercialization timelines for domestic developers.
- Edge inference chips:Healthcare-optimized GPUs are enabling real-time surgical navigation without cloud dependency, expanding deployment in ambulatory settings.
- Germany's DiGAs:Digital health application reimbursement codes are creating sustainable revenue models for algorithm-assisted pathology tools.
Market Restraints
- GPU supply concentration:Taiwan-based foundry capacity allocation for healthcare silicon remains subordinate to automotive and consumer electronics contracts.
- EU MDR clinical validation:Extended conformity assessment timelines for AI diagnostic devices are delaying European market entry by 18-24 months relative to US authorization.
- Interoperability fragmentation:Proprietary DICOM extensions from incumbent imaging equipment vendors are locking algorithm developers into single-platform deployments.
Strategic Opportunities
- India's tertiary hospital expansion:Government-funded medical college hospitals are procuring AI-enabled screening tools for diabetic retinopathy at volume scale.
- Federated learning architectures:Privacy-preserving model training across institutional boundaries is opening multi-site clinical validation without data centralization.
- China's NMPA fast-track:Accelerated review channels for domestically developed lung nodule detection algorithms are redirecting R&D investment toward ophthalmology and cardiology applications.
Industry Challenges
- Regulatory science workforce:FDA and notified bodies lack sufficient technical reviewers trained in machine learning validation methodologies, creating submission backlogs.
- Legacy PACS integration:Hospital IT departments face 12-18 month deployment cycles to embed computer vision modules into existing radiology workflow infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Computer Vision in Healthcare Market |
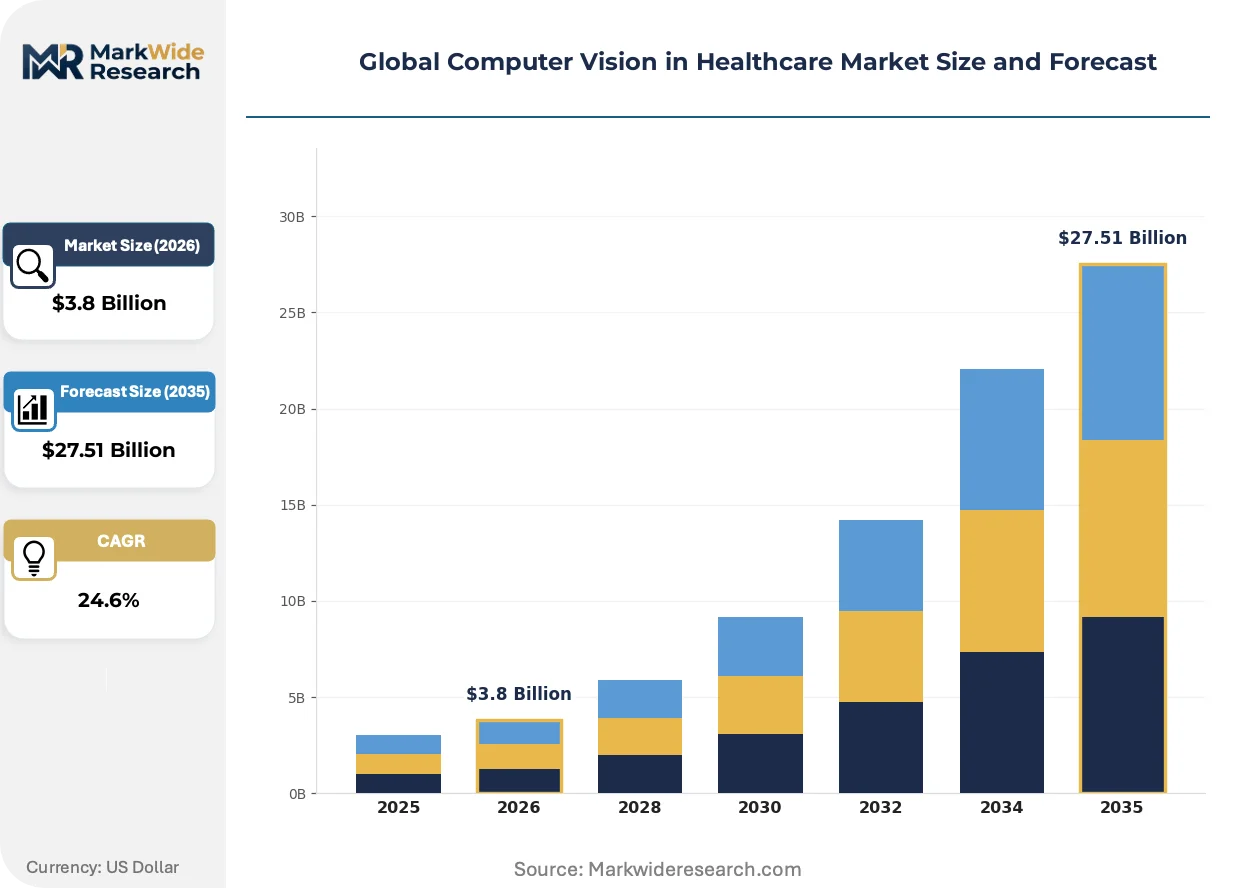
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $27.51 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medical Imaging Analysis, Patient Monitoring Systems, Surgical Assistance Tools, Diagnostic Support Software Application: Disease Detection, Treatment Planning, Drug Discovery, Medical Documentation, Remote Consultations Technology: Deep Learning, Machine Vision, Pattern Recognition, Image Processing, Neural Networks End User: Hospitals, Diagnostic Laboratories, Research Institutes, Telemedicine Providers |
| Companies Covered | Siemens Healthineers, GE HealthCare, Koninklijke Philips, NVIDIA Corporation, Microsoft Corporation, Intel Corporation, IBM Corporation, Google, Basler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Computer Vision in Healthcare Market Shifts & Advancements
Foundation models trained on multi-modal medical data are displacing task-specific algorithms, compressing development costs while raising new questions about clinical liability and validation scope.
Self-supervised learning architectures are absorbing unlabeled imaging data to pre-train diagnostic models before fine-tuning on smaller annotated datasets. Academic medical centers in the United States are deploying these approaches for rare disease detection where curated training samples remain scarce. The technology is absorbing annotation labor costs that previously constrained algorithm development for low-prevalence conditions.
The EU AI Act's risk classification system is mandating conformity assessments for high-risk diagnostic applications before market placement. Medical device manufacturers must now document post-market monitoring plans and algorithm change control protocols. European radiology software vendors are responding by segregating product portfolios between Class IIa and Class III device categories to manage regulatory burden.
Hospital procurement committees are consolidating vendor relationships around integrated imaging-platform providers rather than standalone algorithm developers. Radiology departments are negotiating enterprise licenses that bundle AI modules with PACS maintenance contracts. This pattern is most visible in United States health systems where capital budgets are contracting and IT integration costs dominate total cost of ownership calculations.
Global Computer Vision in Healthcare Market Segmentation
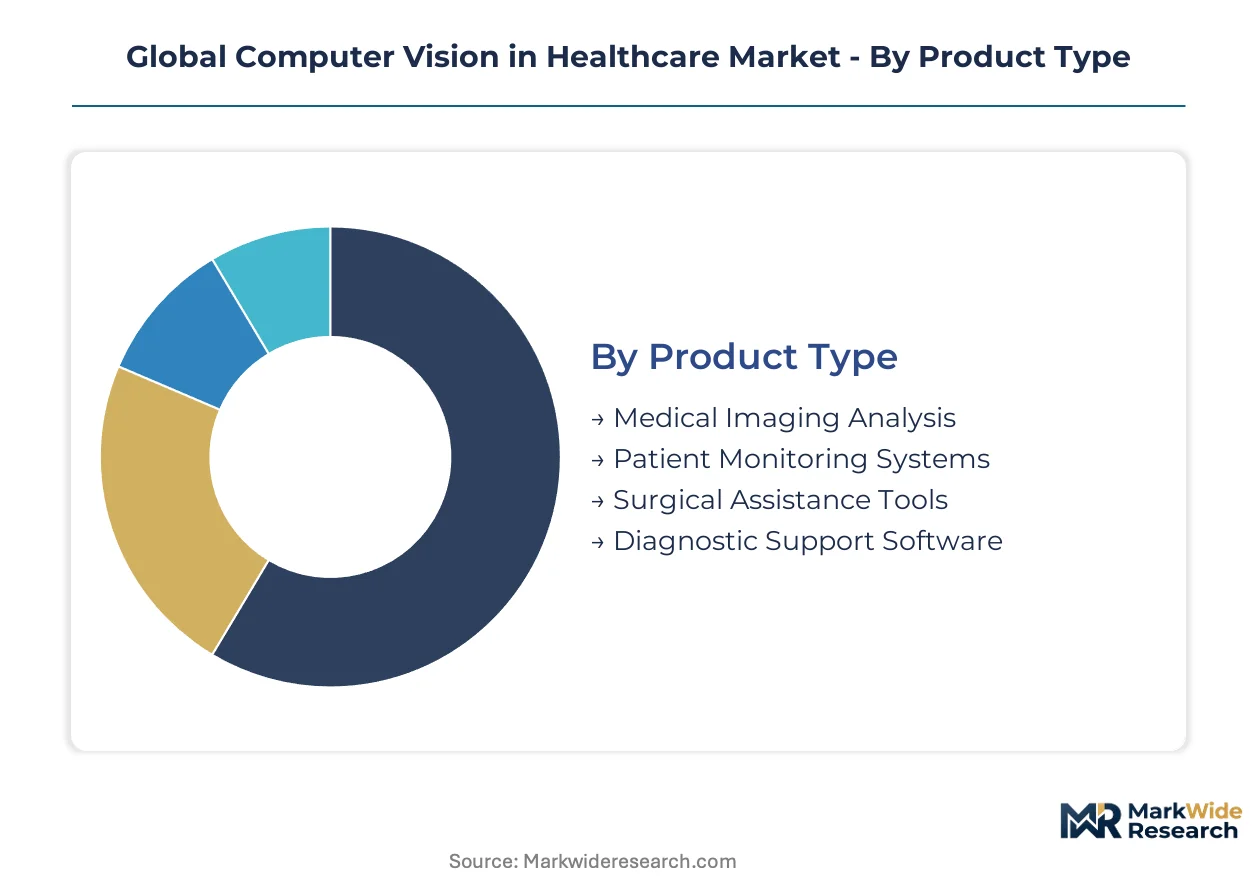
Computer vision deployment patterns vary sharply across product architectures, clinical applications, and institutional settings. Supply concentration in GPU fabrication and algorithm development talent creates asymmetric growth trajectories between segments.
Product Type:
GPU foundry capacity allocation favors segments demanding real-time inference at the edge, concentrating component supply among medical imaging and surgical assistance developers.
- Medical Imaging Analysis:Algorithms process CT, MRI, and X-ray data through PACS-integrated workflows. Demand concentrates in United States hospital networks seeking FDA-cleared radiology automation, constrained by legacy infrastructure retrofit costs.
- Surgical Assistance Tools:Real-time navigation systems overlay anatomical guidance during laparoscopic and robotic procedures. German university hospitals drive procurement volume through DiGA reimbursement pathways, accelerating ambulatory deployment.
- Patient Monitoring Systems:Continuous video analytics for ICU fall detection and deterioration alerts.
- Diagnostic Support Software:Cloud-based pathology screening tools for resource-limited settings.
Today's leader: Medical Imaging Analysis. Tomorrow's challenger: Surgical Assistance Tools.
Application:
Clinical validation costs stratify segments, with disease detection commanding premium pricing while medical documentation competes on workflow efficiency metrics.
- Disease Detection:Automated screening for lung nodules, diabetic retinopathy, and skin lesions. China's NMPA fast-track channels concentrate ophthalmology algorithm approvals, redirecting R&D investment from oncology toward cardiology applications.
- Drug Discovery:Phenotypic screening and molecular interaction visualization accelerate pharmaceutical pipelines. United States biotech clusters absorb venture funding for cell imaging analytics, constrained by FDA biomarker qualification timelines.
- Treatment Planning:Radiation therapy contouring and surgical trajectory simulation.
- Medical Documentation:Automated procedure coding and clinical note generation.
- Remote Consultations:Telemedicine-integrated diagnostic support for dermatology and radiology.
Disease Detection captures current revenue concentration. Drug Discovery offers the steepest expansion trajectory as pharmaceutical outsourcing accelerates.
Technology:
Computational requirements and data availability determine which architectures achieve production deployment versus research-stage promise.
- Deep Learning:Convolutional and transformer-based architectures dominate commercial diagnostic products. Taiwan-based foundry contracts for healthcare-optimized silicon concentrate supply among NVIDIA CUDA ecosystem partners, limiting second-source alternatives.
- Pattern Recognition:Classical computer vision retains deployment in India and Southeast Asia where annotated training data scarcity favors rule-based approaches over neural methods.
- Machine Vision:Industrial-grade hardware for laboratory automation and quality control.
- Image Processing:Enhancement and reconstruction algorithms for legacy equipment compatibility.
- Neural Networks:Recurrent and graph architectures for temporal physiological monitoring.
Deep Learning commands installed-base dominance. Pattern Recognition defends share in cost-sensitive emerging markets.
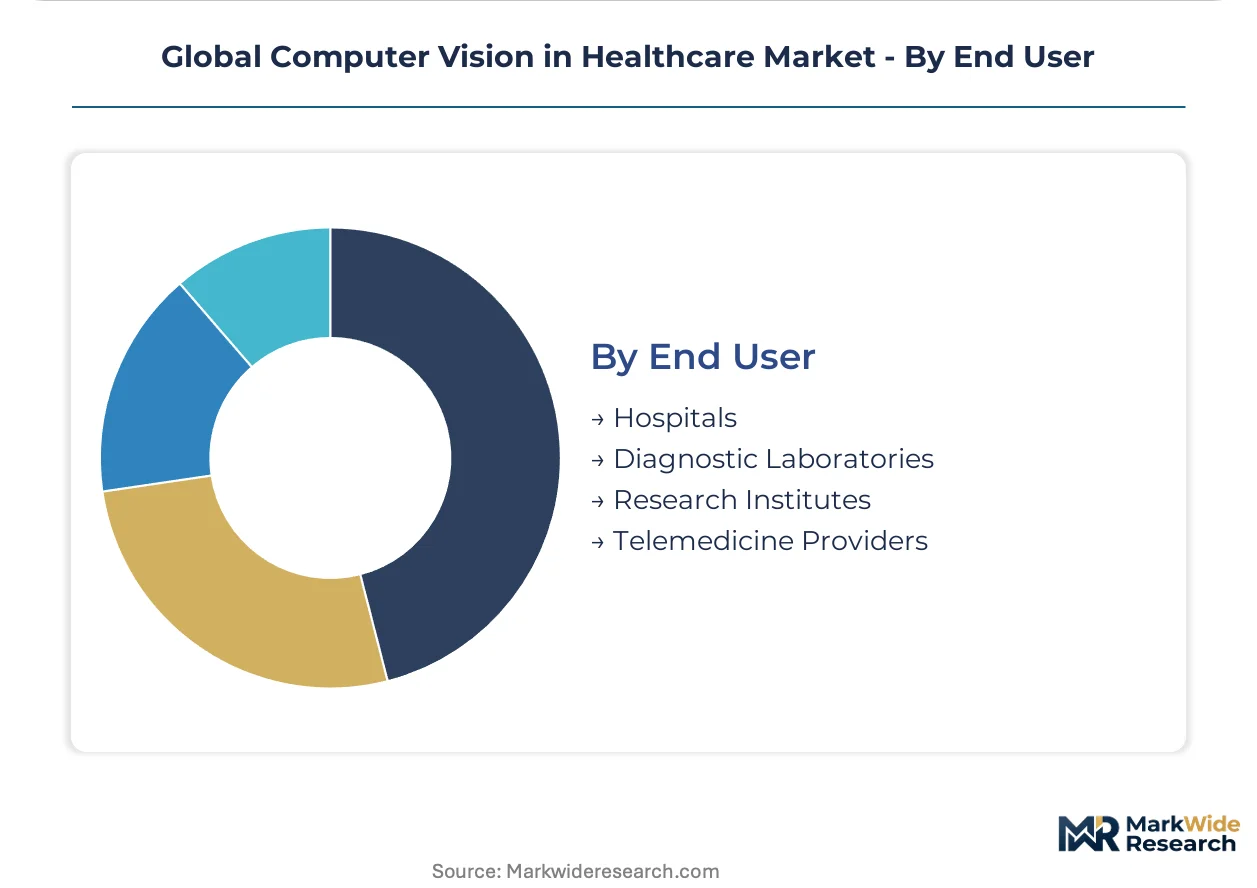
End User:
Procurement authority and integration complexity create distinct customer segments with diverging vendor selection criteria.
- Hospitals:Enterprise imaging platforms bundle AI modules with PACS maintenance contracts. United States health system consolidation concentrates purchasing power among ten national networks, forcing standalone algorithm developers toward acquisition or partnership.
- Diagnostic Laboratories:High-throughput pathology screening drives volume pricing for digital slide analysis. Germany's centralized laboratory networks negotiate multi-site licenses, establishing reference pricing across European markets.
- Research Institutes:Federated learning pilots and foundation model development.
- Telemedicine Providers:Cloud-native deployment for asynchronous specialist consultation.
Hospitals anchor current procurement volume. Diagnostic Laboratories are gaining share fastest as independent pathology networks expand automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing computer vision R&D investment toward jurisdictions with faster premarket authorization timelines. FDA clearance velocity in the United States contrasts with EU MDR conformity burdens, while China's NMPA fast-track channels concentrate ophthalmology algorithm development domestically.
United States
FDA 510(k) premarket submissions for AI-enabled radiology software exceeded comparable EU filings by substantial margins in recent review cycles. The agency's Digital Health Center of Excellence streamlined validation protocols for machine learning-based diagnostic devices. Academic medical centers in Boston and Stanford anchor multi-site clinical trials for foundation model deployment.
Germany
DiGA reimbursement codes for algorithm-assisted pathology sustain procurement volume across university hospital networks. The Federal Institute for Drugs and Medical Devices enforces MDR conformity assessments that extend timelines relative to US authorization. Berlin and Munich clusters concentrate surgical navigation startups targeting ambulatory surgery center expansion.
China
NMPA accelerated review channels for domestically developed lung nodule detection algorithms redirect R&D investment toward cardiology applications. National reimbursement expansion for AI-assisted screening drives hospital procurement in tertiary medical centers. Shenzhen and Hangzhou industrial parks concentrate edge inference chip fabrication for healthcare-optimized GPUs.
India
Government-funded medical college hospitals procure AI-enabled diabetic retinopathy screening tools at volume scale under national health mission programs. The Central Drugs Standard Control Organization regulates software as medical device imports through licensing requirements. Hyderabad and Bangalore clusters host federated learning pilots for multi-site clinical validation without data centralization.
Japan
PMDA consultation pathways for SaMD pre-submissions guide domestic developers through clinical evidence requirements for deep learning diagnostic products. METI funding programs subsidize edge computing infrastructure deployment in rural prefectures. Tokyo and Osaka metropolitan areas concentrate hospital system procurement for PACS-integrated AI modules.
Global Computer Vision in Healthcare Market Competitive Landscape
United States technology conglomerates anchor one tier through CUDA ecosystem control and cloud infrastructure dominance; European and Chinese specialists hold equipment-integrated positions through embedded module deployment on CT and MRI systems. Market structure consolidates around imaging platform bundling as hospital procurement committees favor enterprise licenses over standalone algorithm procurement. Three archetypes dominate: semiconductor foundry partners, incumbent imaging equipment vendors, and cloud-native software developers. Competitive moves concentrate on strategic partnerships between algorithm developers and PACS vendors, plus capacity reservation agreements for healthcare-optimized GPU fabrication.
Within the semiconductor tier, NVIDIA Corporation occupies a position as the CUDA ecosystem anchor for medical imaging startup pipelines. Siemens Healthineers and GE HealthCare exemplify the incumbent imaging equipment archetype through embedded computer vision module deployment. These three entities represent divergent strategic positions: ecosystem platform, installed-base defender, and integrated hardware-software bundler.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE HealthCare |
| Koninklijke Philips |
| NVIDIA Corporation |
| Microsoft Corporation |
| Intel Corporation |
| IBM Corporation |
| Basler AG |
| Others |
Supply & Pricing Matrix
EU AI Act conformity requirements for high-risk diagnostic applications gate qualified supply to algorithm developers with documented post-market monitoring capabilities, reserving premium-tier pricing access for vendors with MDR Class III certification and established European notified body relationships.
Pricing Analysis
Distributor margins for PACS-integrated AI modules compress standalone algorithm pricing by 15-25 percent, favoring enterprise license bundling over per-seat SaaS tiers. Pricing stratifies across FDA-cleared premium tiers, CE-marked standard offerings, and emerging economy-tier products for India's government procurement. Cost compression in the standard tier intensifies as NVIDIA CUDA ecosystem partners consolidate around reference architectures. Academic medical centers in the United States exhibit lowest price sensitivity due to grant-funded pilot budgets, while India's tertiary hospitals operate under rigid national health mission cost ceilings.
Supply Chain Analysis
Specialized machine learning engineering talent shortages in Taiwan and South Korea constrain healthcare GPU foundry expansion, forcing capacity allocation toward automotive and consumer electronics contracts. Taiwan Semiconductor Manufacturing draws from CoWoS advanced packaging substrates and HBM3 memory stacks manufactured in South Korea. Single-source vulnerability concentrates in TSMC's N4 process node for NVIDIA H100 healthcare-optimized silicon. Distribution runs through medical device distributors with FDA establishment registration and EU authorized representative status, linking foundry output to hospital procurement committees through imaging equipment OEM channel networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where FDA 510(k) clearance velocity in the United States creates 18-24 month revenue head starts against EU MDR conformity timelines, compressing European developer margins while accelerating American first-mover capitalization.
For Market Incumbents: Deploy embedded module strategies to lock algorithm developers into proprietary DICOM extension ecosystems. Siemens Healthineers and GE HealthCare anchor installed-base defense through CT and MRI hardware-software bundling that raises switching costs for hospital procurement committees. Capacity reservation agreements with Taiwan-based foundries for healthcare-optimized GPU allocation hedge against automotive sector contract competition.
For New Entrants and Emerging Players: Capture India's diabetic retinopathy screening procurement under national health mission programs where government-funded medical college hospitals absorb volume pricing for rule-based algorithms. Germany's DiGA reimbursement pathway for pathology tools offers second white-space target with faster revenue conversion than FDA premarket authorization. Go-to-market leverage rests on federated learning pilots that satisfy European data localization requirements without infrastructure-heavy centralization.
For Investors and Strategic Acquirers: Roll-up economics work for cloud-native diagnostic software developers because hospital procurement consolidation around integrated imaging-platform providers strands standalone algorithm vendors without PACS vendor partnerships. Five-to-ten year viability hinges on reimbursement code expansion for algorithm-specific professional fees. Signal to monitor: CMS Medicare coverage determinations for AI-assisted radiology that would trigger enterprise license repricing across United States health systems.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Digital Health Center of Excellence streamlined protocols compress premarket timelines for domestic radiology software developers. |
| CE Marking Pathway Investment | MDR conformity assessment preparation extends European market entry but secures sustainable DiGA reimbursement eligibility in Germany. |
| Hospital System Partnership | Enterprise license bundling with PACS maintenance contracts locks out standalone algorithm competitors in consolidating United States networks. |
| Software Companion Development | Real-time surgical navigation modules for laparoscopic procedures capture fastest-expanding margin pool in ambulatory settings. |
| Reimbursement Strategy Execution | Algorithm-specific CPT code advocacy determines whether computer vision deploys as cost-saving automation or premium clinical service. |
Research Methodology
Direct dialogue with hospital purchasing committee chairs, biomedical engineers at academic medical centers, GPO contracts managers, and FDA regulatory affairs specialists grounded qualitative findings in procurement workflow realities. Secondary validation drew from FDA 510(k) premarket notification databases, CMS Medicare reimbursement determinations, EU MDR notified body conformity assessment records, and hospital procurement database aggregators. Bottom-up algorithm deployment counts across PACS installations triangulated against top-down imaging equipment OEM revenue disclosures.
Bottom-up modeling segmented addressable demand by product architecture, clinical application, technology deployment, and institutional end-user across the analysis window. Top-down cross-checks anchored on semiconductor foundry capacity allocation disclosures for healthcare-optimized GPUs and imaging equipment OEM reported segment revenues. CAGRs derived from installation base expansion rates, reimbursement code adoption curves, and regulatory authorization velocity differentials between FDA and EU MDR pathways.
Regulatory authorization delays, foundry capacity reallocation to automotive contracts, and payer reimbursement denials for algorithm-specific professional fees are the dominant revision risks to demand forecasts. Material deviation in FDA clearance velocity, Taiwan-based GPU allocation priorities, or CMS coverage determinations warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Intraoperative Imaging Market
Medical Imaging
Europe Mobile Tomography Market
Medical Imaging
United Kingdom Digital X-Ray Devices Market
Medical Imaging
Fluorescein Angiography Market
Medical Imaging
Portable Cardiology Ultrasound Systems Market
Medical Imaging
Neurophotonics Market
Medical Imaging
South Korea Nuclear Imaging Market
Medical Imaging
Argentina Digital X-Ray Market
Medical Imaging
Quantitative Pathology Imaging Market
Medical Imaging
China VNA and PACS Market
Medical Imaging
Canada Nuclear Imaging Market
Medical Imaging
Europe Nuclear Imaging Devices Market
Medical Imaging
Asia Pacific Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Preclinical Ultrasound Systems Market
Medical Imaging
Global Veterinary Radiography System Market
Medical Imaging
India Mammography Market