
 Push Button Dropper Market | 2026-2036
Push Button Dropper Market Size, Share, and Industry Trends Forecast 2026-2036
Push Button Dropper Market Analytics
Modular dropper-cap assemblies paired with variable-volume inserts is restructuring how pharmaceutical and cosmetic buyers configure their primary packaging. Bormioli Pharma leverages its European glass manufacturing footprint to supply compliant dropper systems for regulated drug applications. Gerresheimer anchors the high-barrier segment through specialized borosilicate glass and polymer combinations. Virospack competes by controlling decoration and customization capabilities that differentiate cosmetic brand presentations.
A push button dropper is a dispensing closure combining a compressible bulb or piston mechanism with a calibrated orifice, typically manufactured from thermoplastic elastomers, polypropylene, or borosilicate glass components, designed to deliver repeatable micro-doses of liquid formulations. Glass droppers sustain premium positioning in pharmaceutical and essential oil segments where chemical inertness and UV protection command higher unit margins. Plastic variants dominate volume in mass-market cosmetics and household applications where cost efficiency and shatter resistance outweigh barrier requirements. The 5 mL and 10 mL capacity bands capture the majority of pharmaceutical and nutraceutical demand, while 1 mL formats concentrate in ophthalmic and diagnostic reagent packaging.
Europe's MDR and REACH frameworks enforce biocompatibility and extractables testing for dropper materials contacting drug formulations, elevating compliance costs for suppliers serving regulated markets. The FDA's container closure guidance and USP Class VI standards govern material qualification for ophthalmic and parenteral applications in the United States, creating divergent certification pathways. Stakeholders must monitor how evolving ESG disclosure rules under CSRD and emerging state-level packaging extended producer responsibility laws reshape material selection and sourcing transparency requirements.
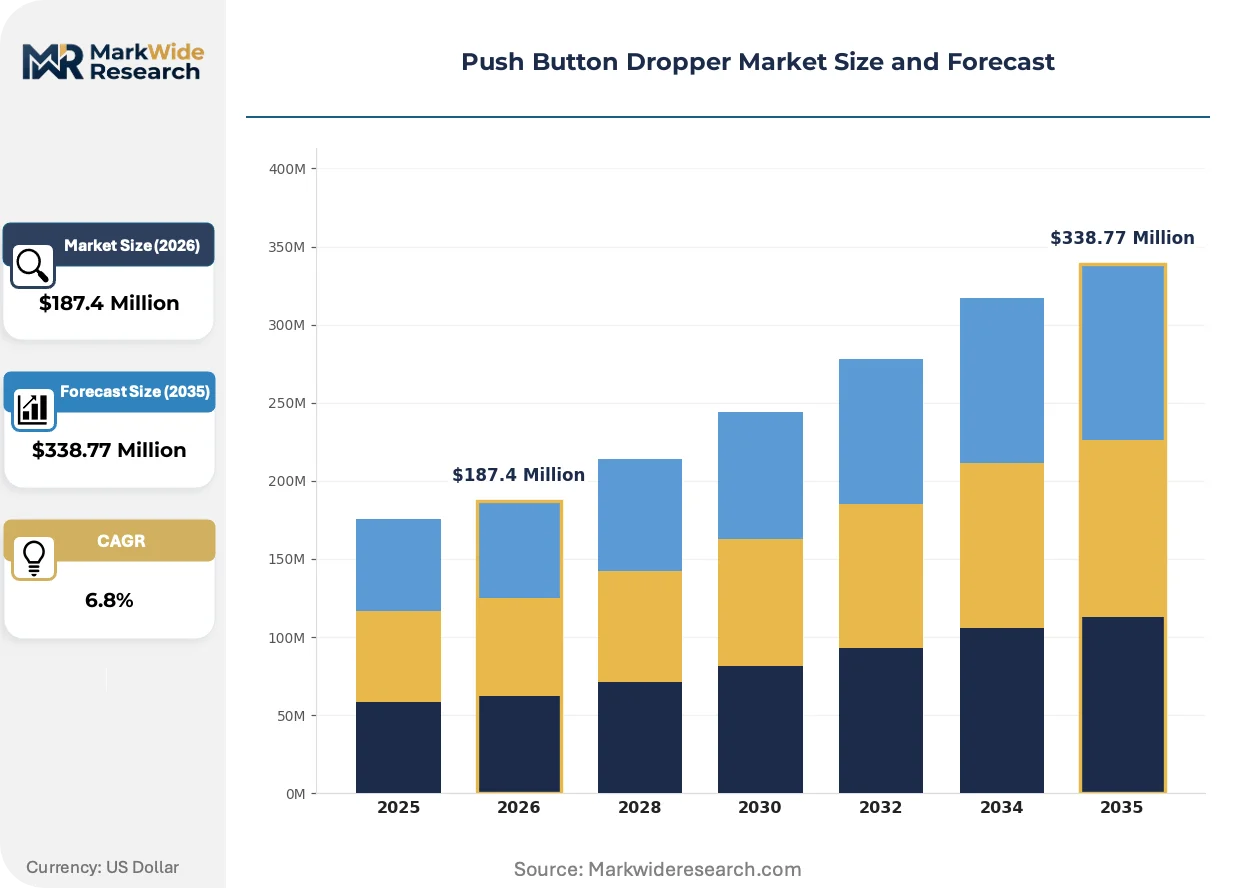
Market Dynamics
Pharmaceutical manufacturers are consolidating procurement around certified single-source dropper systems to satisfy Europe's MDR and REACH compliance timelines, compressing supplier qualification windows from 18 months to under 12 months for primary packaging components.
Growth Catalysts
- Ophthalmic dosing precision:Chronic eye disease prevalence in aging populations drives demand for calibrated micro-dose delivery. Germany's Federal Institute for Drugs and Medical Devices (BfArM) fast-tracks device-drug combination approvals when dropper systems demonstrate dose reproducibility.
- REACH material compliance:Restricted substance lists force reformulation of thermoplastic elastomers and polypropylene compounds. Suppliers completing ECHA registration dossiers gain preferred vendor status with multinational pharmaceutical packagers.
- Modular assembly platforms:Variable-volume insert technology allows cosmetic brands to reconfigure single SKUs across 1 mL to 10 mL capacities without mold retooling, reducing inventory carrying costs for seasonal product launches.
Market Restraints
- Borosilicate glass supply concentration:European furnace capacity for pharmaceutical-grade tubing concentrates in Germany and Italy, exposing buyers to energy cost volatility and single-source risk during maintenance shutdowns.
- Extractables testing burden:USP Class VI and USP 1664 protocols require 12-18 month validation cycles for new elastomer formulations, freezing material innovation timelines and elevating R&D amortization costs.
- Prefilled syringe substitution:Parenteral biologics increasingly bypass dropper formats entirely, migrating to ready-to-use injection systems that eliminate patient dosing variability.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO's phased implementation of medical device rules creates first-mover advantage for dropper suppliers establishing local testing laboratories and BIS certification pathways.
- Diagnostic reagent packaging:Point-of-care molecular testing expansion requires 0.5-2 mL precision droppers with integrated desiccant chambers, a format underserved by incumbent cosmetic-focused suppliers.
- CSRD supply chain disclosure:Mandatory ESG reporting under EU Corporate Sustainability Reporting Directive rewards transparent material sourcing, enabling premium positioning for suppliers with certified recycled content and carbon-accounted logistics.
Industry Challenges
- Multidisciplinary talent scarcity:Compound expertise spanning polymer science, pharmaceutical regulation, and high-speed automation engineering concentrates in Switzerland and southern Germany, constraining facility expansion in lower-cost manufacturing regions.
- Legacy equipment integration:Pharmaceutical packagers running 1990s-era glass forming lines face retrofit complexity when connecting to modern vision-inspection and serialization systems required for EU Falsified Medicines Directive compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Push Button Dropper Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Glass, Stainless Steel, Aluminium Capacity: 1 mL, 3 mL, 5 mL, 10 mL End User: Pharmaceuticals, Cosmetics, Nutrition, Household Distribution Channel: Retail, Online, Wholesale, Direct Sales |
| Companies Covered | Bormioli Pharma, APG Pharma, Comar, Berlin Packaging, Gerresheimer, Virospack, Pacific Packaging, The Plasticod Company, DWK Life Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Push Button Dropper Market Evolving Landscape
Automation and closed-loop quality systems are compressing defect rates and batch release timelines, while regulatory data integrity requirements reshape how dropper manufacturers document and transmit compliance evidence to pharmaceutical customers.
Precision piston pump technology is automating dose accuracy verification in real-time during high-speed assembly. Ophthalmic drug packagers in Switzerland and the Netherlands are retrofitting production lines with in-line gravimetric checking at 400 units per minute. This is automating the elimination of manual sampling protocols that previously required 2-4 hour laboratory holds per production batch.
Europe's Medical Device Regulation (MDR) Annex I general safety and performance requirements now govern dropper systems classified as Class I medical devices. Manufacturers must maintain technical documentation and post-market surveillance systems equivalent to implantable device suppliers. Small-format essential oil droppers with claimed antimicrobial properties face reclassification scrutiny from notified bodies in Germany and France.
Direct sourcing from specialized component suppliers is displacing traditional distribution intermediaries in pharmaceutical procurement. Large European cosmetics houses now negotiate borosilicate glass ampoules and elastomer bulbs as separate line items rather than purchasing finished dropper assemblies. This pattern concentrates in France and Italy where brand houses maintain internal packaging engineering teams capable of qualifying multi-source component combinations.
Push Button Dropper Market Segmentation
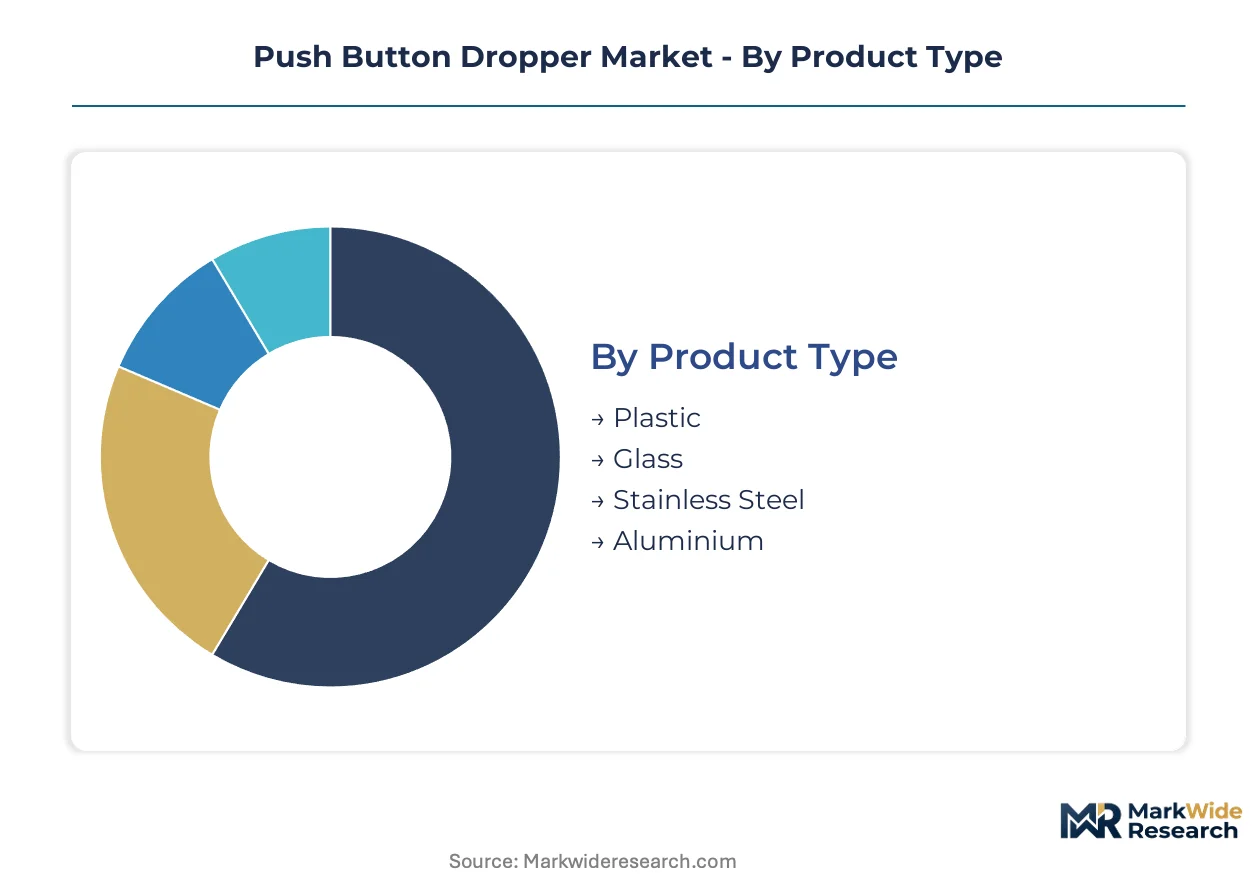
Push button dropper procurement patterns diverge sharply between regulated pharmaceutical applications demanding certified material traceability and mass-market segments prioritizing cost efficiency and decoration flexibility. Understanding these segment boundaries clarifies why suppliers maintain parallel production lines with incompatible qualification timelines and pricing structures.
Product Type:
Glass commands premium positioning in applications where chemical inertness justifies higher unit costs, while plastic variants dominate volume through shatter resistance and mold flexibility.
- Glass:Borosilicate and soda-lime formulations serve ophthalmic drugs and essential oils where UV protection and extractables compliance are mandatory. European pharmaceutical manufacturers in Germany and Switzerland specify glass for MDR Class I device classifications requiring post-market surveillance documentation.
- Plastic:Polypropylene and thermoplastic elastomer assemblies target mass-market cosmetics and household cleaners with lower barrier requirements. REACH-registered compound suppliers gain preferred status with multinational packagers reformulating restricted substance lists.
- Stainless Steel:Medical-grade 316L variants serve diagnostic reagent packaging requiring autoclave compatibility and corrosion resistance in point-of-care settings.
- Aluminium:Lightweight metal housings protect precision piston mechanisms in portable diagnostic devices and luxury cosmetic presentations.
Mature deployment sits with Glass. Newer deployment is concentrated in Plastic.
Capacity:
Dose reproducibility requirements concentrate procurement in mid-range formats, with extreme capacities serving specialized diagnostic and ophthalmic niches.
- 5 mL:The workhorse format balances sufficient formulation volume with portability for chronic disease medications and premium skincare serums. Pharmaceutical packagers in Italy and France standardize on this capacity for modular assembly platforms.
- 10 mL:Extended-use formulations and combination therapies drive demand in nutraceutical applications where daily dosing spans 30-day cycles.
- 1 mL:Ophthalmic micro-dosing and molecular diagnostic reagents require precision-calibrated orifices with integrated desiccant chambers.
- 3 mL:Travel-size cosmetics and sample formulations exploit this intermediate capacity for seasonal promotional launches without mold retooling costs.
Volume concentration favors 5 mL. Steepest expansion trajectory belongs to 1 mL.
End User:
Regulatory burden intensity separates pharmaceutical procurement—where MDR technical documentation consumes 12-18 month qualification windows—from cosmetic sourcing prioritizing speed-to-market.
- Pharmaceuticals:Ophthalmic and nasal drug-device combinations require USP Class VI elastomer validation and ECHA extractables dossiers. BfArM fast-tracks approvals for systems demonstrating dose reproducibility.
- Cosmetics:Brand differentiation through decoration capabilities and variable-volume inserts dominates sourcing criteria. French and Italian houses negotiate glass ampoules and elastomer bulbs as separate line items.
- Nutrition:Liquid vitamin and probiotic formulations favor plastic assemblies with child-resistant closures meeting ISO 8317 standards.
- Household:Cleaning concentrates and fragrance refills prioritize cost efficiency over barrier performance, sourcing from high-volume Asian molders.
Compliance complexity peaks with Pharmaceuticals. Volume scale concentrates in Cosmetics.
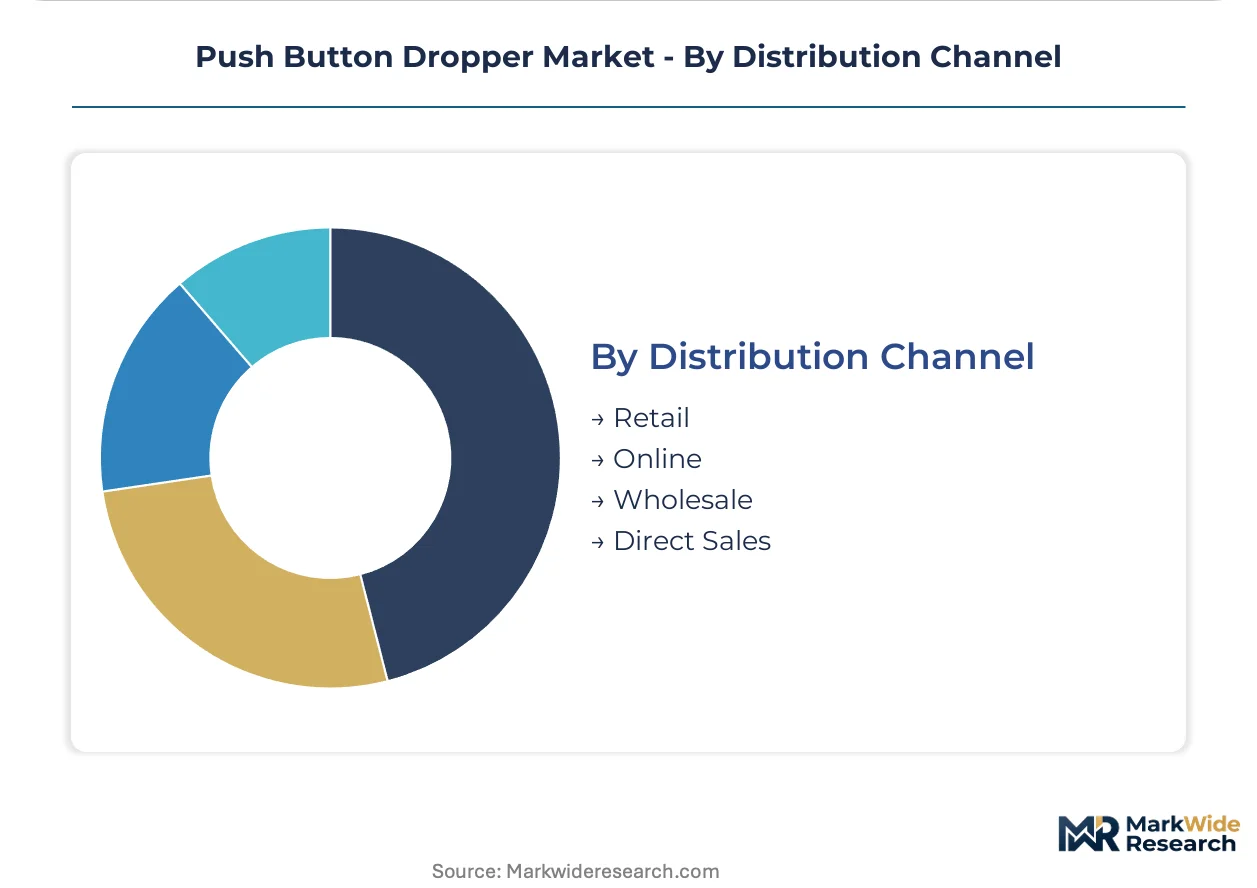
Distribution Channel:
Direct sourcing patterns are displacing traditional intermediaries as pharmaceutical packagers consolidate around certified single-source dropper systems.
- Direct Sales:Pharmaceutical manufacturers negotiate multi-year supply agreements with Bormioli Pharma and Gerresheimer for MDR-compliant assemblies with locked formulations.
- Wholesale:Regional distributors serve mid-tier cosmetic brands lacking internal packaging engineering teams for component qualification.
- Online:E-procurement platforms capture spot demand from emerging nutraceutical brands and contract manufacturers seeking rapid sampling.
- Retail:Point-of-sale packaging for DIY essential oil blending and craft applications drives small-format demand through specialty channels.
Relationship intensity concentrates in Direct Sales. Channel experimentation is expanding fastest in Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in European glass furnace corridors while consumption disperses across pharmaceutical clusters in Germany, Switzerland, and emerging Indian manufacturing hubs. This geographic split shapes logistics costs and regulatory compliance pathways for dropper suppliers.
Germany
Chronic ophthalmic disease prevalence and aging demographics sustain demand for precision micro-dose droppers. BfArM fast-tracks device-drug combination approvals when systems demonstrate dose reproducibility. The Mainz-Wiesbaden pharmaceutical corridor hosts primary packaging engineering teams qualifying multi-source glass and elastomer combinations.
Switzerland
Specialized biologics packaging and high-barrier pharmaceutical applications command premium positioning for borosilicate glass assemblies. Swissmedic maintains stringent post-market surveillance requirements equivalent to implantable device classifications. Basel and Zurich clusters concentrate polymer science and automation engineering talent for MDR-compliant production.
India
CDSCO's phased medical device rules implementation creates procurement consolidation around certified single-source suppliers. Domestic pharmaceutical manufacturing expansion drives demand for child-resistant plastic assemblies in liquid vitamin segments. Maharashtra and Gujarat pharmaceutical zones attract dropper suppliers establishing local BIS certification and testing laboratories.
United States
FDA container closure guidance and USP Class VI standards govern material qualification for ophthalmic applications, creating divergent certification pathways from European frameworks. New Jersey and Massachusetts pharmaceutical corridors drive demand for serialized packaging systems under DSCSA compliance timelines. Diagnostic reagent packaging expansion in California requires precision 0.5-2 mL formats with integrated desiccant chambers.
France
Luxury cosmetic brand houses negotiate glass ampoules and elastomer bulbs as separate procurement line items rather than finished assemblies. ANSM scrutinizes small-format essential oil droppers with claimed antimicrobial properties for MDR reclassification. Paris and Lyon packaging engineering teams maintain internal qualification capabilities for multi-source component combinations.
Push Button Dropper Market Competitive Landscape
The competitive structure tilts toward integrated glass manufacturers with pharmaceutical certification depth. Three tiers separate MDR-compliant system suppliers serving regulated drug applications from decoration-focused cosmetic specialists and high-volume Asian molders. Dominant competitive moves include backward integration into borosilicate furnace capacity and strategic partnerships with serialization technology providers for EU Falsified Medicines Directive compliance.
Among European glass specialists, Bormioli Pharma and Gerresheimer occupy positions anchoring the high-barrier pharmaceutical segment through certified material traceability and REACH-registered compound supply. Virospack represents the cosmetic-specialist archetype, with differentiation concentrated in decoration capabilities and variable-volume insert platforms serving brand house customization requirements. These three exemplify how divergent end-use regulatory burdens sustain parallel production lines with incompatible qualification timelines.
| Leading Market Players |
|---|
| Bormioli Pharma |
| APG Pharma |
| Comar |
| Berlin Packaging |
| Gerresheimer |
| Virospack |
| Pacific Packaging |
| The Plasticod Company |
| DWK Life Sciences |
| Others |
Value Network & Pricing Analysis
Borosilicate glass furnace energy costs in Germany and Italy cascade through three-tier pricing stratification across MDR-certified pharmaceutical, REACH-registered cosmetic, and unregulated household tiers. Pharmaceutical buyers absorb premium positioning for extractables-tested assemblies while cosmetic houses negotiate component-level sourcing to bypass finished-goods markups.
Pricing Analysis
Margin tightening in pharmaceutical-grade glass traces to concentrated European furnace capacity and ECHA-registered elastomer compound premiums. Three-tier pricing structure across premium, standard, and economy levels separates MDR Class I device assemblies with post-market surveillance documentation from cosmetic decoration-focused systems and commodity plastic variants. Price differentiation hinges on certification grade and volume scale, with diagnostic reagent packagers showing highest sensitivity to per-unit costs and Swiss biologics manufacturers least responsive to price premiums for barrier performance.
Supply Chain Analysis
Dual-sourcing mandates from Germany's BfArM and Swissmedic force pharmaceutical packagers to qualify secondary borosilicate glass suppliers in Italy alongside primary German furnace operators. Raw material flows draw from soda-lime and borosilicate tubing feedstock, thermoplastic elastomer compounds, and precision-molded polypropylene components. Single-source vulnerability concentrates in pharmaceutical-grade glass furnace maintenance cycles, while distribution runs through direct multi-year supply agreements with Bormioli Pharma and Gerresheimer for regulated drug applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
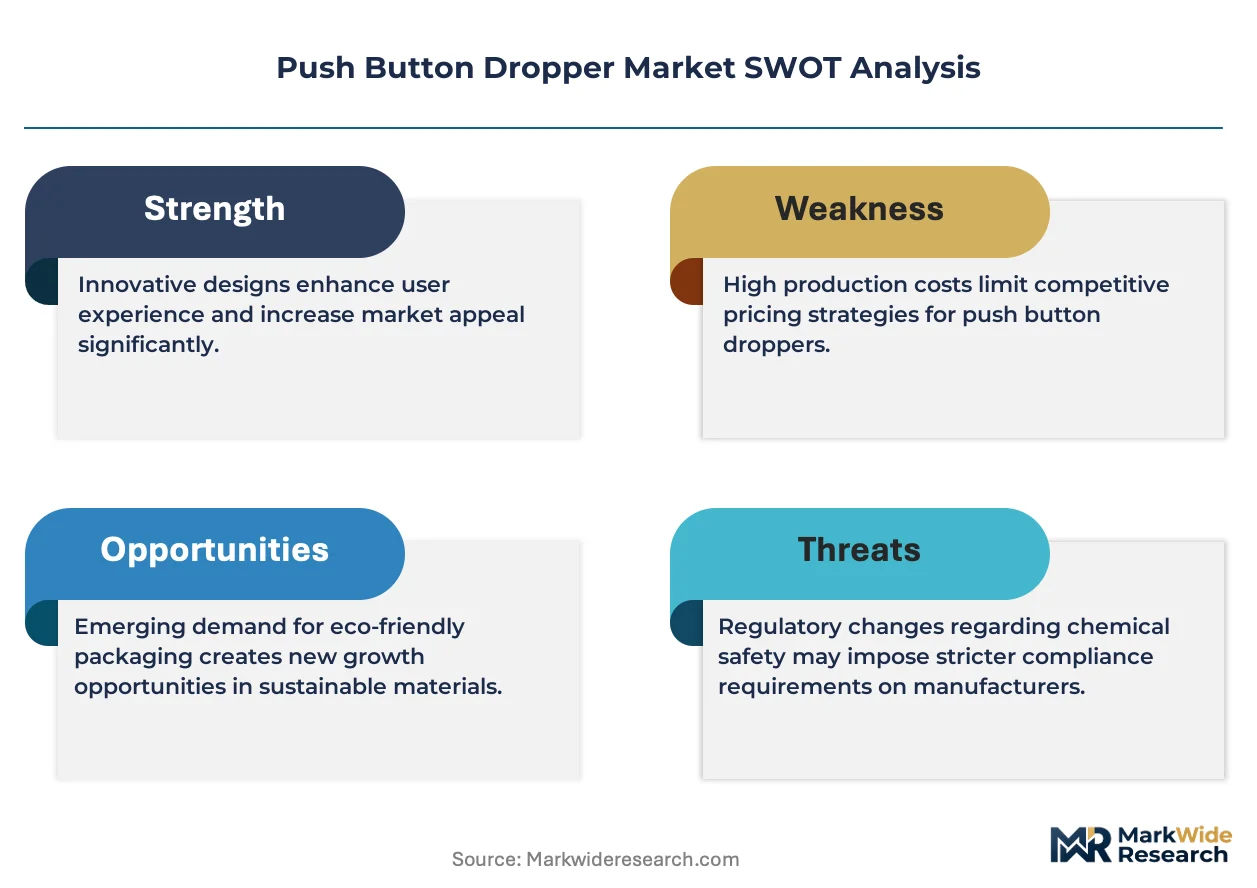
Backward integration into captive borosilicate furnace capacity and downstream serialization technology partnerships defines the competitive race, as MDR compliance timelines compress supplier qualification windows below 12 months.
For Market Incumbents: Extend REACH-registered compound libraries to lock formulation exclusivity with multinational pharmaceutical packagers facing reformulation deadlines. Add redundant furnace capacity in southern Germany to mitigate single-source exposure during maintenance shutdowns, while prefilled syringe substitution in parenteral biologics threatens long-term dropper demand in high-margin segments. For New Entrants and Emerging Players: Launch via e-procurement platforms serving emerging Indian nutraceutical brands seeking rapid BIS certification pathways without legacy supplier onboarding delays. Target diagnostic reagent packaging in Maharashtra and Gujarat pharmaceutical zones, where 0.5-2 mL precision formats with integrated desiccant chambers remain underserved by incumbent cosmetic-focused suppliers. For Investors and Strategic Acquirers: CDSCO's phased medical device rules implementation is the leading indicator that Indian pharmaceutical manufacturing expansion will consolidate procurement around certified single-source suppliers with local testing infrastructure. Acquisition candidates include mid-cap specialists with BIS certification pathways and established relationships with Maharashtra pharmaceutical clusters. Watch for BfArM fast-track approval announcements as signal of dose-reproducibility technology inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Furnace Capacity | Captive supply of pharmaceutical-grade tubing mitigates energy cost volatility and single-source risk during German maintenance cycles. |
| REACH-Registered Elastomer Compound Investment | ECHA dossier completion secures preferred vendor status with multinational packagers reformulating restricted substance lists. |
| Serialization Technology Partnership | EU Falsified Medicines Directive compliance integration enables supply of MDR Class I device assemblies with traceability documentation. |
| Diagnostic Reagent Format Development | 0.5-2 mL precision droppers with desiccant chambers address point-of-care molecular testing expansion in California and Swiss clusters. |
| Indian BIS Certification Laboratory Establishment | Local testing infrastructure captures CDSCO medical device rule implementation first-mover advantage in Maharashtra pharmaceutical zones. |
Research Methodology
Document review covered ECHA registration dossiers, BfArM device-drug combination approval records, and CDSCO medical device rule implementation schedules, complemented by interviews with pharmaceutical packaging engineering directors, REACH compliance officers at thermoplastic elastomer compounders, and procurement managers at French cosmetic brand houses. Secondary validation drew from FDA container closure guidance documents, USP Class VI certification databases, and EU MDR technical documentation templates. Bottom-up capacity assessments at German and Italian glass furnace operators were triangulated against top-down pharmaceutical packaging demand forecasts.
Unit volume and value projections across the modeling period were generated through segmented demand modeling by material type, capacity band, end-use regulatory intensity, and distribution channel structure. CAGRs were derived from regression analysis against ophthalmic disease prevalence demographics, diagnostic reagent packaging expansion rates, and REACH compliance cost pass-through elasticity. Industry-specific forecast inputs included BfArM fast-track approval velocity and CDSCO phased rule implementation timelines.
The model assumes a particular technology adoption path for precision piston pump automation in ophthalmic packaging lines; alternative pathways for manual dosing retention in emerging markets would alter the outlook. Deviation in European furnace energy cost volatility or MDR reclassification of small-format essential oil droppers would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Antenna Switch Module Market
Switches
Hazardous Location Limit Switches Market
Switches
Oil Level Switches Market
Switches
Argentina Automotive Reed Sensors Switches Market
Switches
Europe Low Voltage Switchgear Market
Switches
Membrane Switch Market
Switches
Digital Crosspoint Switches Market
Switches
In-Wall Smart Switch Market
Switches
North America Switchgear Market
Switches
North America MV Switchgear Market
Switches
Off-Road Machine Ruggedized Switch and Indicator Systems Market
Switches
5G Solid State Switches Market
Switches
Fixed Switch Cabinet Market
Switches
Micro Switch Market
Switches
Differential Pressure Switches Market
Switches
Mexico Rocker Switch Market