
 Brazil Switchgear Market | 2026-2036
Brazil Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Switchgear Market Insights
The capital-intensity divergence between integrated manufacturers and assembly-focused competitors is redrawing competitive boundaries in Brazil's switchgear sector. ABB Ltd leverages its local manufacturing footprint to sustain cost advantages in medium-voltage assemblies. Schneider Electric SE anchors its position through extensive service networks spanning utility and industrial accounts. Siemens AG differentiates via digital switchgear platforms that integrate grid automation software with hardware portfolios.
Switchgear encompasses electrical apparatus designed to control, protect, and isolate power circuits through mechanisms such as circuit breakers, disconnectors, and fuses rated from low voltage through extra-high voltage classes. These systems employ vacuum interrupters, SF6 gas insulation, or air-insulated designs to interrupt fault currents and ensure operational safety across generation, transmission, and distribution infrastructure. Medium voltage switchgear dominates current revenue flows due to extensive utility procurement for substation modernization, while gas insulated technology captures premium margins in space-constrained urban installations. Vacuum technology segments expand fastest as environmental regulations constrain SF6 deployment and utilities prioritize maintenance-reduction outcomes.
ANEEL mandates shape equipment certification requirements and grid reliability standards that manufacturers must satisfy for market access. ABNT technical standards and INMETRO conformity assessment protocols further define product compliance pathways for domestic and imported switchgear. BNDES financing conditionalities increasingly favor local content thresholds, influencing procurement decisions among state-owned utilities. Stakeholders must monitor regulatory evolution around green finance taxonomy alignment and carbon disclosure requirements that will reshape supplier qualification criteria.
Market Dynamics
ANEEL's grid reliability mandates are compressing equipment replacement cycles across Brazil's transmission and distribution infrastructure, forcing utilities to accelerate procurement of smart-switchgear systems that integrate digital monitoring with legacy substation architectures.
Growth Catalysts
- ANEEL Reliability Mandates:Brazil's national electric energy regulator imposes strict outage duration penalties that compel utilities to prioritize fault-resistant switchgear upgrades. Distribution concessionaires in São Paulo state face the tightest compliance windows.
- Southeast Grid Modernization:Transmission expansion programs across Minas Gerais and Rio de Janeiro are generating concentrated demand for medium-voltage assemblies. State-owned utilities channel BNDES financing into localized procurement.
- Vacuum Interrupter Adoption:Environmental constraints on SF6 gas insulation are redirecting utility specifications toward vacuum-based interruption technology. Maintenance cost reduction drives preference shifts in urban substation deployments.
Market Restraints
- Copper and Steel Input Volatility:Raw material price swings for conductive metals and enclosure steel compress assembly margins. Brazilian manufacturers lack long-term hedging mechanisms against commodity exchange fluctuations.
- Import Dependency for Vacuum Interrupters:Domestic production gaps in ceramic vacuum bottle manufacturing concentrate supply risk with Asian specialized suppliers. Lead times extend procurement cycles for critical medium-voltage components.
- SF6 Phase-Down Regulatory Friction:INMETRO conformity assessment protocols lag international environmental standards for gas-insulated switchgear. Certification delays strand capital in transitional product inventories.
Strategic Opportunities
- Northeast Renewable Integration:Wind and solar generation clusters in Ceará and Rio Grande do Norte require new substation infrastructure. Switchgear vendors can anchor early relationships with renewable developers before grid codes finalize.
- Digital Twin Convergence:Integration of switchgear hardware with predictive analytics platforms creates service revenue streams. Utilities in São Paulo's metropolitan zone pilot condition-based maintenance contracts.
- BNDES Green Finance Alignment:The development bank's local content conditionalities increasingly favor suppliers with certified carbon disclosure. Early compliance creates qualification advantages for state utility tenders.
Industry Challenges
- Protection Relay Integration Complexity:Legacy electromechanical relay systems in Brazil's aging substation base resist seamless digital retrofit. Utilities face operational downtime risks during hybrid architecture transitions.
- Specialized Field Technician Scarcity:Vacuum interrupter maintenance and gas handling certification programs operate below required throughput. Training infrastructure gaps extend service response times for critical fault restoration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Switchgear Market |
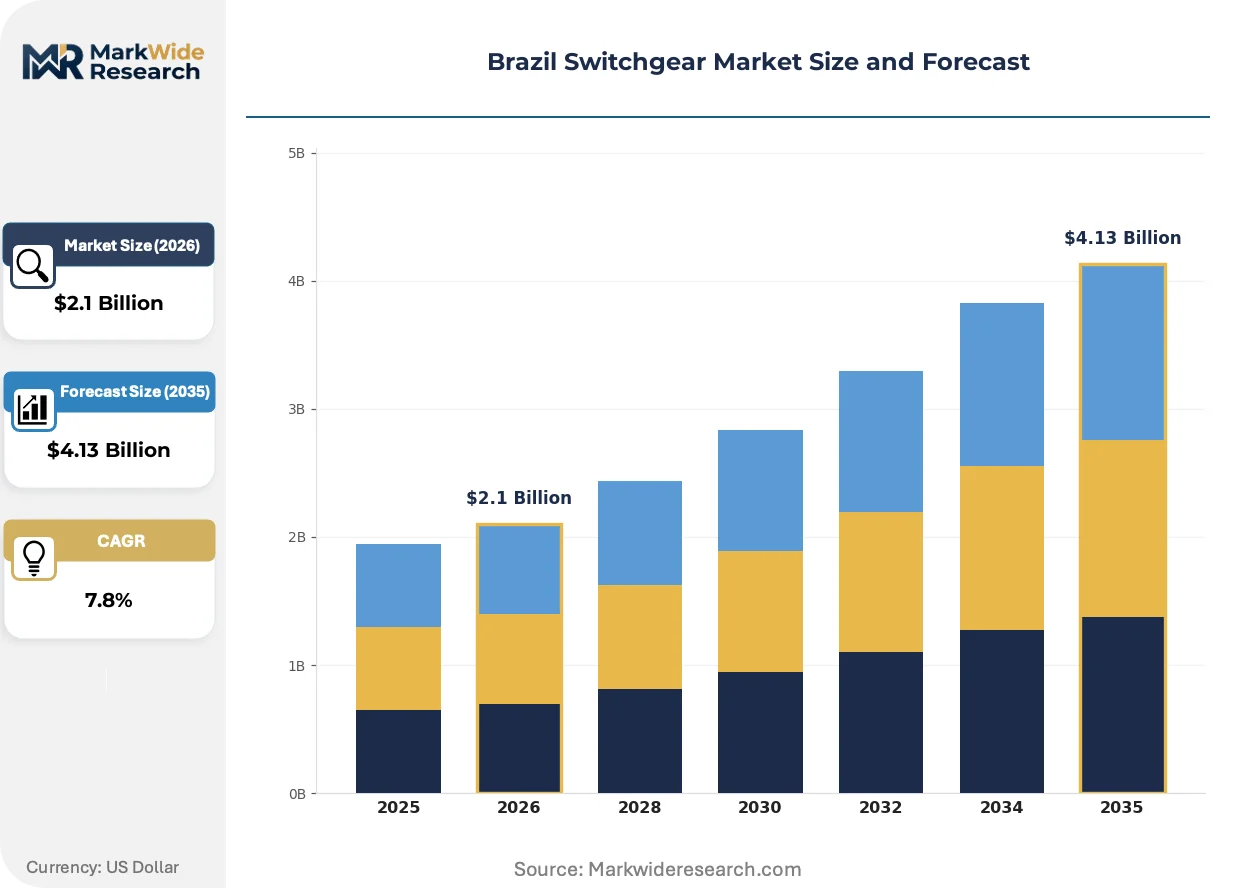
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medium Voltage, Low Voltage, High Voltage, Hybrid Technology: Vacuum, Air Insulated, Gas Insulated, Miniature End User: Utilities, Industrial, Commercial, Residential Installation Type: Indoor, Outdoor, Modular, Compact |
| Companies Covered | ABB Ltd, Schneider Electric SE, General Electric Company, Siemens AG, Mitsubishi Electric Corporation, Toshiba International Corporation, Eaton Corporation, Hitachi Energy Ltd, Fuji Electric Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Switchgear Market Trends and Innovations
Digitalization is restructuring competitive advantage in Brazilian switchgear markets, with hardware-software integration now determining vendor selection criteria alongside traditional reliability metrics and installed base relationships.
Vacuum interruption technology is displacing SF6 gas-insulated designs across medium-voltage distribution applications. Eletrobras distribution subsidiaries and private concessionaires in São Paulo specify vacuum-based switchgear for new substation builds. The technology is displacing premium-priced gas-insulated alternatives in space-constrained urban installations where maintenance access is limited.
ANEEL's smart grid regulatory framework is mandating remote monitoring capabilities in all new switchgear procurements above specified voltage thresholds. Distribution utilities must demonstrate real-time fault location and isolation functionality to qualify for tariff adjustment mechanisms. Medium-voltage ring-main units across the Southeast region incorporate embedded sensors and communication modules to satisfy compliance requirements.
Service unbundling is separating switchgear hardware procurement from long-term maintenance contracts. Industrial buyers in Minas Gerais mining corridors negotiate equipment purchase and aftermarket support through distinct vendor relationships. Third-party specialized service providers capture maintenance revenue previously retained by original equipment manufacturers.
Brazil Switchgear Market Segmentation
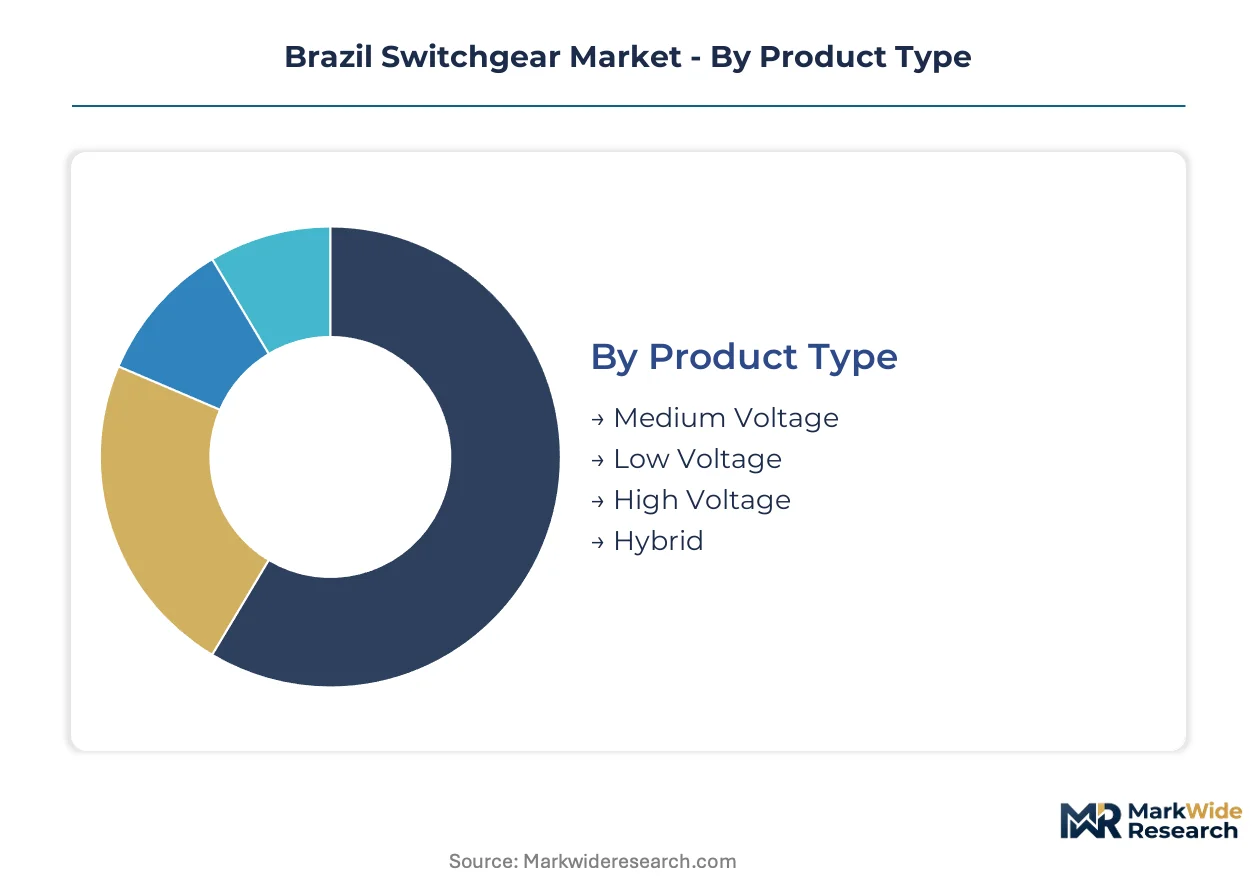
ANEEL's reliability mandates and BNDES financing conditionalities create divergent procurement pathways across switchgear categories. Equipment specification requirements vary sharply by voltage class and installation environment, forcing vendors to maintain segmented certification portfolios.
Product Type:
ANEEL's grid reliability mandates impose differentiated outage penalties across voltage tiers, concentrating procurement urgency in specific segments.
- Medium Voltage:Rated between 1kV and 52kV, these assemblies employ vacuum interrupters or SF6 insulation for substation feeder protection. São Paulo state utilities channel the majority of BNDES-financed procurement into this tier for distribution network upgrades. ANEEL's strictest outage duration penalties apply to medium-voltage failures, accelerating replacement cycles.
- Low Voltage:Systems rated below 1kV serve building distribution boards and industrial motor control centers. Commercial construction in Rio de Janeiro and Belo Horizonte drives steady demand for panelboard assemblies. Certification under ABNT NBR IEC 61439 standards governs market access.
- High Voltage:Extra-high voltage switchgear above 52kV serves transmission interconnection points. Eletrobras transmission subsidiaries dominate procurement for regional backbone expansion.
- Hybrid:Mixed-technology designs combine air and gas insulation for specialized retrofit applications. Limited deployment in space-constrained urban substations.
Established volume favors medium voltage; emerging adoption favors hybrid configurations for substation modernization.
Technology:
Cost tier differentiation separates premium gas-insulated designs from maintenance-optimized vacuum alternatives.
- Vacuum:Ceramic interrupter bottles extinguish arcs without greenhouse gas emissions. Environmental regulations constraining SF6 deployment redirect utility specifications toward this technology. São Paulo metropolitan utilities specify vacuum for all new urban substation builds to reduce maintenance access requirements.
- Air Insulated:Open-frame designs with atmospheric insulation serve outdoor transmission substations. Lower capital cost suits rural distribution networks in Minas Gerais and Rio de Janeiro states. ABNT NBR 62271-100 standards govern dielectric testing protocols.
- Gas Insulated:SF6-filled enclosures enable compact footprint in dense urban installations. Premium pricing persists in legacy specifications despite environmental headwinds.
- Miniature:Reduced-scale assemblies for secondary distribution and renewable integration projects. Wind farm developers in Ceará specify miniature ring-main units for collector substations.
Environmental compliance is accelerating vacuum displacement of gas-insulated share; air insulated retains cost advantage in rural expansion.
End User:
Customer type determines specification complexity and service bundling expectations.
- Utilities:State-owned distribution concessionaires and Eletrobras subsidiaries drive equipment standardization through centralized procurement. ANEEL-mandated smart grid functionality requires embedded monitoring in all new switchgear acquisitions.
- Industrial:Mining operations in Minas Gerais and petrochemical complexes in Rio de Janeiro demand arc-resistant enclosures and specialized relay coordination. Unbundled maintenance contracts separate hardware procurement from long-term service agreements.
- Commercial:Shopping centers and office complexes in São Paulo's metropolitan zone specify compact indoor switchgear with integrated protection. Third-party electrical contractors influence vendor selection.
- Residential:Low-voltage panelboards and consumer units serve building construction. Volume concentrates in mid-rise developments across Southeast state capitals.
Utility procurement dominates absolute volume; industrial accounts generate premium margin capture through specialized engineering.
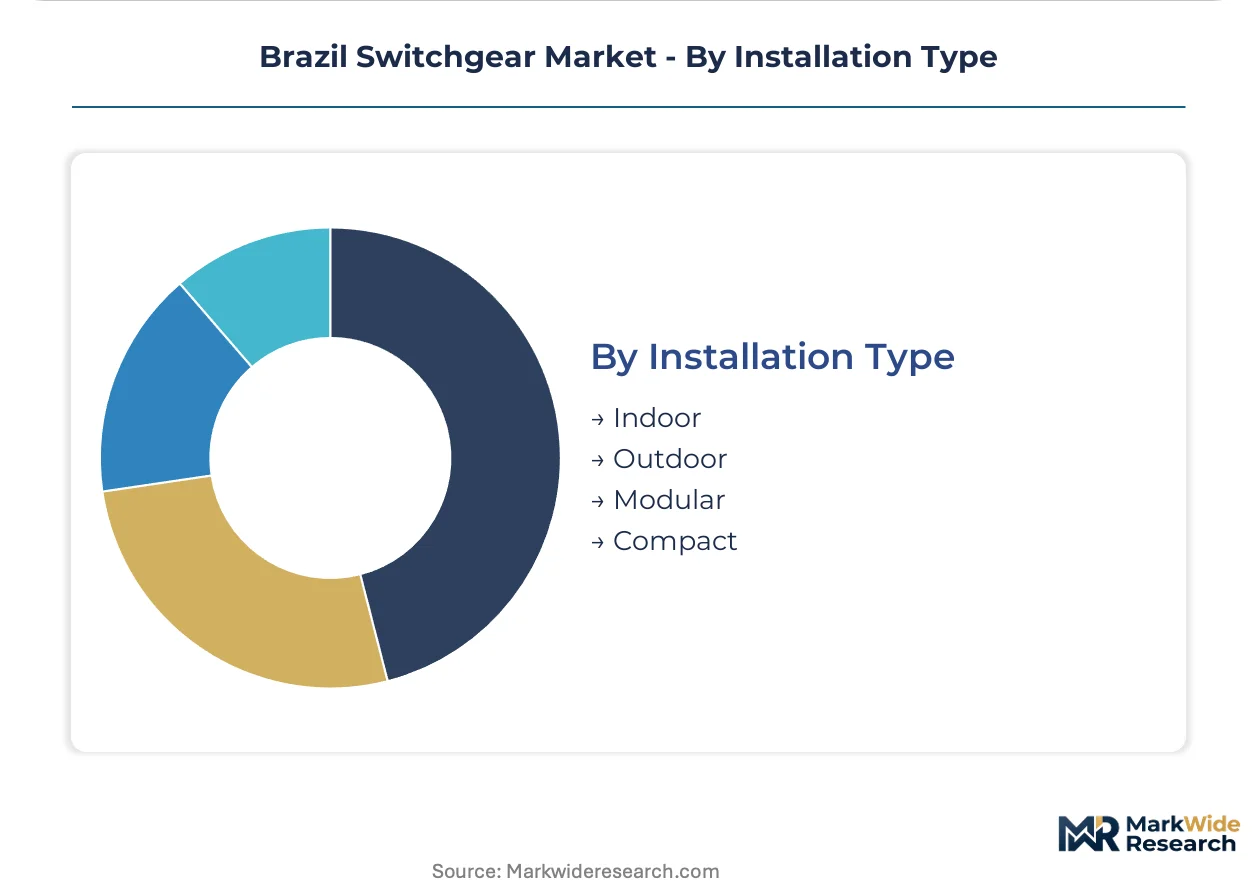
Installation Type:
Geography and climate exposure dictate enclosure specifications and thermal management requirements.
- Indoor:Metal-enclosed assemblies for climate-controlled substation buildings. São Paulo's dense urban network favors indoor deployment to limit environmental exposure and vandalism risk.
- Outdoor:Weather-resistant housings with tropicalized finishes for transmission substations. High humidity and salt exposure in coastal Rio de Janeiro drive corrosion-resistant specification requirements.
- Modular:Factory-integrated substation packages combining switchgear, transformers, and protection in transportable enclosures. Renewable developers in Rio Grande do Norte specify modular solutions to accelerate wind farm energization schedules.
- Compact:Reduced-footprint designs for retrofit into existing substation civil works. Space constraints in legacy São Paulo distribution facilities favor compact gas-insulated or vacuum alternatives.
Outdoor installations retain volume leadership in transmission expansion; modular designs are climbing fastest in renewable integration applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's switchgear consumption patterns diverge sharply between the industrialized Southeast and the renewable-rich Northeast, with state-level regulatory enforcement and utility ownership structures driving distinct procurement behaviors across sub-national markets.
São Paulo
Metropolitan distribution networks and heavy industrial loads anchor the largest procurement volumes. ANEEL's strictest outage penalties apply to utilities operating here, compressing replacement cycles for medium-voltage assemblies. São Paulo state's BNDES-financed grid modernization channels concentrated demand through state-owned distribution concessionaires.
Minas Gerais
Mining corridors and metallurgical complexes generate specialized demand for arc-resistant switchgear configurations. Eletrobras transmission subsidiaries dominate high-voltage procurement for regional backbone expansion. The state's rural distribution networks favor cost-optimized air-insulated designs over premium gas-insulated alternatives.
Rio de Janeiro
Petrochemical complexes and coastal transmission infrastructure drive corrosion-resistant specification requirements. Salt exposure and high humidity in coastal substations enforce tropicalized enclosure standards. State utility procurement increasingly unbundles hardware acquisition from long-term maintenance contracts.
Rio Grande do Norte
Wind farm clusters in this Northeast state require rapid-deployment modular substation packages. Renewable developers specify miniature ring-main units for collector substations to accelerate energization schedules. Early supplier relationships formed here before grid code finalization carry strategic weight.
Ceará
Solar and wind integration projects are creating new substation infrastructure demand in this emerging renewable hub. ANEEL's smart grid mandates apply with equal force here, requiring embedded monitoring in all new switchgear acquisitions. Local content thresholds in BNDES financing favor suppliers with established regional presence.
Brazil Switchgear Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding premium positioning through captive manufacturing and service networks while specialists compete on application-specific engineering. The market structure reflects capital-intensity divergence between full-stack manufacturers and assembly-focused competitors. Three archetypes dominate: European industrial conglomerates with local manufacturing footprints, Japanese electrical equipment specialists with technology licensing arrangements, and regional integrators serving niche utility accounts. Competitive moves center on backward integration into vacuum interrupter sourcing and geographic anchoring through BNDES-compliant local content investments.
Within the integrated multinational tier, ABB Ltd and Schneider Electric SE exemplify divergent strategic positioning—one leveraging manufacturing scale advantages, the other anchoring through service network density. Siemens AG occupies a distinct position through digital-physical convergence in switchgear platforms. Among Japanese specialists, Mitsubishi Electric Corporation and Toshiba International Corporation represent technology-led entry models, while Hitachi Energy Ltd and Fuji Electric Co., Ltd. illustrate portfolio breadth strategies. Eaton Corporation and General Electric Company demonstrate North American-origin competitive approaches adapted to Brazilian regulatory conditionalities.
| Leading Market Players |
|---|
| ABB Ltd |
| Schneider Electric SE |
| General Electric Company |
| Siemens AG |
| Mitsubishi Electric Corporation |
| Toshiba International Corporation |
| Eaton Corporation |
| Hitachi Energy Ltd |
| Fuji Electric Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Scale economies in vacuum interrupter manufacturing anchor price floors across Brazil's switchgear tiers, with Asian production concentration compressing margins for assembly-focused competitors while integrated multinationals defend spreads through captive component sourcing and localized fabrication.
Pricing Analysis
Aftermarket service contracts and extended maintenance agreements generate lifetime value multiples exceeding original equipment sales for established vendors. Three-tier pricing structure across premium digital-integrated, standard vacuum-based, and economy air-insulated levels separates vendors by certification grade and smart-grid functionality. Pricing pressure stems from BNDES local-content conditionalities favoring domestic assembly over imported finished goods. State-owned utilities in São Paulo exhibit lowest price sensitivity due to regulatory compliance mandates, while commercial contractors in Rio de Janeiro prioritize capital cost minimization.
Supply Chain Analysis
Ceramic vacuum bottle manufacturing concentrates supply risk with Japanese and Chinese specialized producers, extending procurement cycles for critical medium-voltage components. Brazilian assembly operations draw from copper and steel inputs subject to commodity exchange volatility, with limited domestic hedging infrastructure. Single-source vulnerability in vacuum interrupter sourcing creates exposure to lead-time extensions and quality consistency risks. Distribution runs through Eletrobras centralized procurement channels and state concessionaire tender processes, with industrial accounts increasingly unbundling hardware from service procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified vacuum interrupter technicians and smart-grid integration specialists represent acute capability gaps constraining market expansion, with training infrastructure throughput trailing utility deployment schedules across Brazil's Southeast region.
For Market Incumbents: Shield installed-base relationships through captive vacuum interrupter supply agreements and accelerated field technician certification programs. Deepen backward integration into ceramic bottle sourcing to reduce exposure to Asian supplier concentration. Prioritize ANEEL smart-grid compliance pre-certification to accelerate tender qualification timelines against emerging competitors. For New Entrants and Emerging Players: Third-party maintenance service gaps in Minas Gerais mining corridors and Ceará renewable clusters offer white-space entry points with lower capital barriers than hardware manufacturing. Target modular substation packages for wind farm developers in Rio Grande do Norte before grid code finalization locks incumbent relationships. Anchor go-to-market through BNDES local-content partnership structures with established Brazilian electrical contractors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among service-network-anchored specialists with ANEEL certification portfolios and existing Eletrobras framework agreements. Long-term viability favors acquisition targets with vacuum technology capabilities and Northeast regional presence. Monitor ANEEL penalty regime tightening as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum Interrupter Backward Integration | Captive ceramic bottle sourcing reduces Asian supplier dependency and compresses lead times for São Paulo utilities. |
| Smart-Grid Certification Pre-Investment | Early ANEEL compliance creates tender advantages as remote monitoring mandates expand across voltage classes. |
| Northeast Regional Manufacturing Footprint | Localized assembly satisfies BNDES conditionalities for Ceará and Rio Grande do Norte renewable integration projects. |
| Field Technician Training Scale-Up | Expanded certification throughput addresses scarcity constraining service response times for critical fault restoration. |
| Digital Twin Platform Development | Predictive analytics integration captures condition-based maintenance contracts from São Paulo metropolitan utilities. |
Research Methodology
Initial hypotheses were tested against primary input from utility planning officers, EPC contractors, switchgear procurement managers, and aftermarket service heads, then refined through secondary validation against ANEEL regulatory filings, BNDES financing disclosure databases, ABNT certification registries, and Eletrobras tender documentation. Bottom-up equipment shipment tracking and top-down grid investment flow analysis were triangulated to reconcile volume estimates.
Variance decomposition across voltage class, technology type, end-user segment, and installation environment shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated ANEEL reliability penalty evolution, BNDES local-content threshold adjustments, and vacuum interrupter import substitution progress.
Forecasts assume regulatory continuity in ANEEL grid reliability mandates and BNDES financing conditionalities; material policy shifts would require re-modeling. Commodity price volatility and ceramic vacuum bottle supply disruptions represent specific revision risks. Practitioners should keep alternative scenarios live as environmental regulation around SF6 phase-down and green finance taxonomy alignment evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Campus Switches Market
Switches
Global Light Control Switches Market
Switches
India Reed Sensors Switches Market
Switches
Optical Switches Market
Switches
Differential Pressure Switches Market
Switches
North America Medium Voltage Switchgear Market
Switches
Reed Switches Sensors Market
Switches
Global High Voltage Switchgear Market
Switches
United States X by Wire Systems Market
Switches
Micro Switch Market
Switches
UAE Switchgear Market
Switches
Outdoor Boundary Vacuum Load Switch Market
Switches
Electromechanical Microwave Switch Market
Switches
Italy Reed Sensors Switches Market
Switches
Antenna Switch Module Market
Switches
Intelligent Power Switches Market