
 Dual Power Transfer Switches Market | 2026-2036
Dual Power Transfer Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Dual Power Transfer Switches Market Foresight
The EU Green Deal is repositioning dual power transfer switch procurement across European data centers and healthcare facilities. Eaton Corporation plc leverages its integrated electrical portfolio to dominate North American critical infrastructure projects. Schneider Electric SE anchors its competitive stance through deep specialization in electromechanical and static switch architectures. ABB Ltd. competes on manufacturing scale and IEC certification breadth across Asian and Middle Eastern markets.
Dual power transfer switches are electromechanical or static devices that automatically or manually shift electrical load between two independent power sources, typically achieving transfer times under 100 milliseconds for critical applications. These switches serve as backbone components for uninterrupted power supply in facilities where downtime carries operational or life-safety consequences. The automatic product category leads volume shipments due to mandated hands-free failover in hospitals and data centers, while static technology commands premium positioning where sub-cycle transfer speed proves essential. Hybrid technology is gaining traction as a fastest-growing segment by bridging the cost-performance gap between electromechanical reliability and static switching speed.
NFPA 110 in the United States, IEC 60947-6-1 in Europe, and the EPA's emissions compliance frameworks for backup generators collectively shape product design, testing protocols, and market access requirements for transfer switch manufacturers. OSHA electrical safety standards and the EU's F-Gas Regulation further constrain installation practices and refrigerant-based cooling integrations in switchgear enclosures. Stakeholders must monitor evolving grid interconnection standards and carbon disclosure mandates as these frameworks increasingly tie backup power system specifications to broader decarbonization commitments.
Market Dynamics
Data center operators are consolidating backup power architectures around sub-100-millisecond failover requirements, compressing procurement cycles and elevating static transfer switch specifications above legacy electromechanical alternatives.
Growth Catalysts
- NFPA 110 compliance mandates:United States hospitals and healthcare facilities must maintain automatic transfer capability for life-safety circuits, eliminating manual switchover options from new construction specifications.
- Electromechanical-to-static technology migration:Hyperscale data centers in Northern Virginia and Frankfurt are specifying solid-state switches for server rack protection, accepting 40-60% cost premiums for sub-cycle transfer speeds.
- Grid reliability investment waves:Germany's Network Expansion Acceleration Act is channeling federal funds into industrial backup infrastructure, with automotive manufacturing clusters in Bavaria and Baden-Württemberg driving automatic transfer switch installations.
Market Restraints
- Copper and silver contact material volatility:Electromechanical switch manufacturers face margin compression from precious metal price swings, with contact assemblies representing 25-35% of bill-of-materials costs.
- Static switch thermal management limitations:Silicon-controlled rectifier architectures generate substantial heat at continuous loads above 800A, restricting deployment in compact switchgear enclosures without forced cooling.
- EPA Tier 4 Final generator integration complexity:Emissions-compliant backup engines require extended crank cycles and sophisticated sequencing logic, complicating transfer switch controller programming and commissioning timelines.
Strategic Opportunities
- India's data center buildout acceleration:Mumbai and Chennai hyperscale projects under the country's Digital India initiative are specifying dual-source redundancy for the first time, creating greenfield demand for automatic transfer equipment.
- Hybrid electromechanical-static architectures:Vendors combining electromechanical durability for routine transfers with static bypass for fault conditions are capturing mid-market data center segments previously priced out of all-solid-state solutions.
- EU Green Deal procurement criteria:European healthcare and public sector tenders now weight embodied carbon and circular design in switchgear evaluations, favoring suppliers with modular, repairable product platforms.
Industry Challenges
- Power systems commissioning engineer scarcity:The specialized skill set for programming transfer switch controllers, coordinating with generator paralleling gear, and validating sequence-of-operation documentation commands 40% salary premiums in competitive labor markets.
- IEC 60947-6-1 type-testing bottlenecks:European certification timelines for new static switch ratings extend 14-18 months, delaying product launches and freezing development roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dual Power Transfer Switches Market |
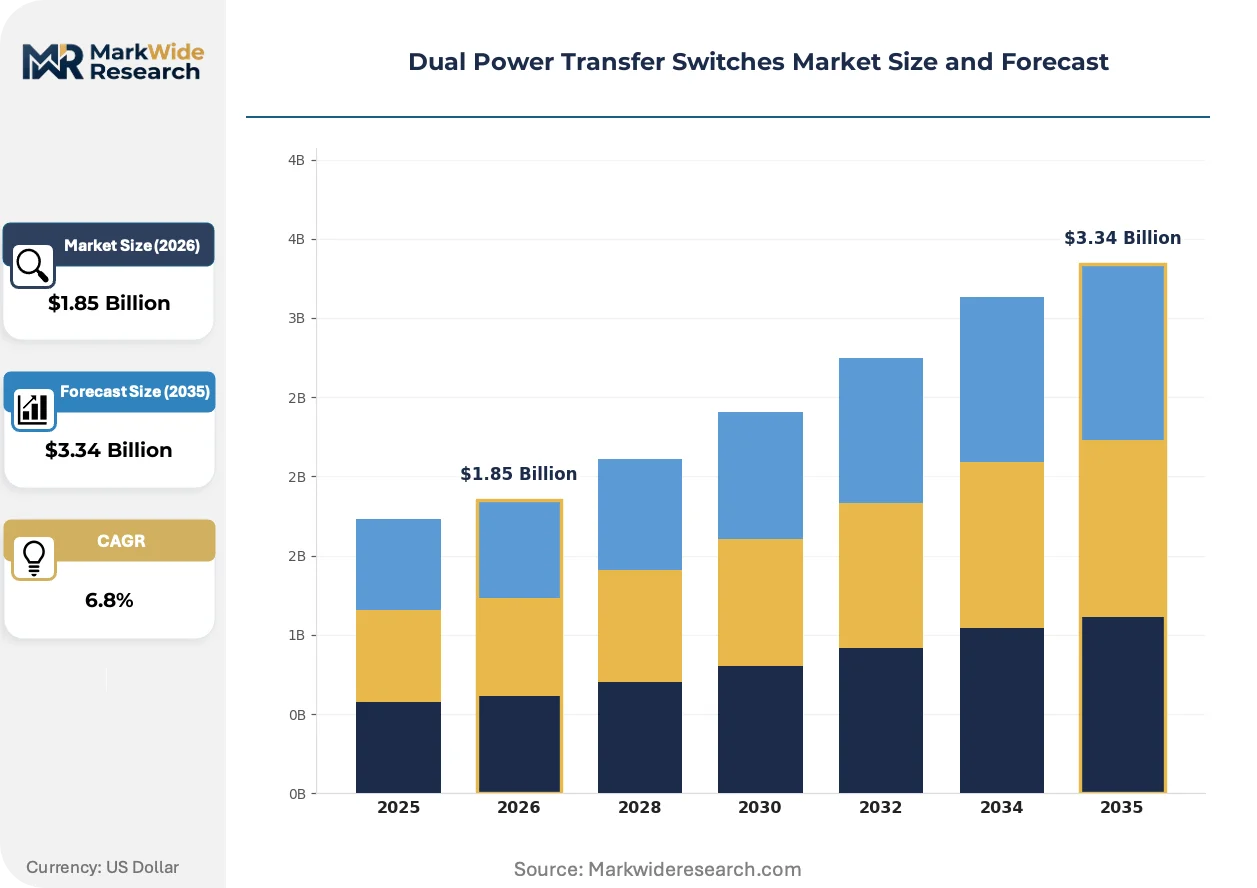
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
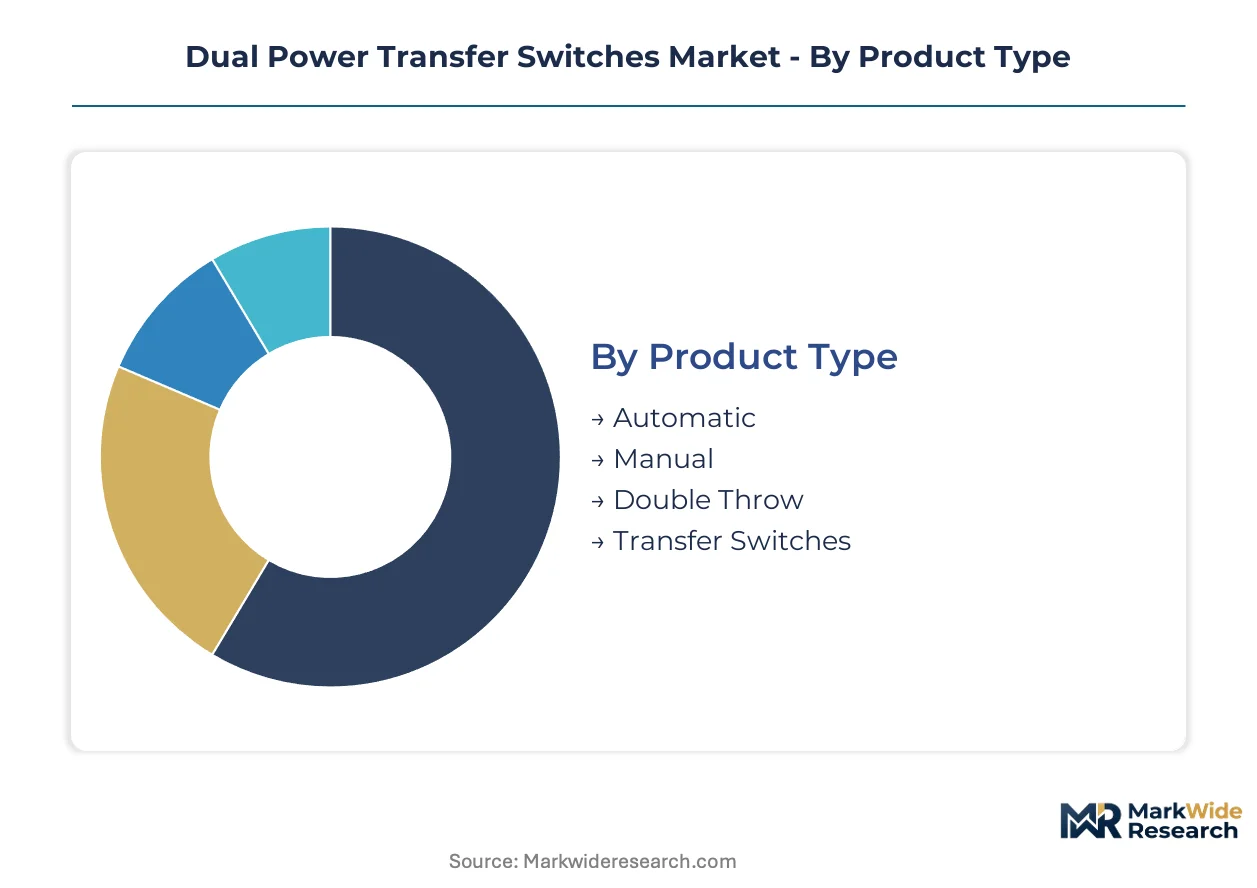
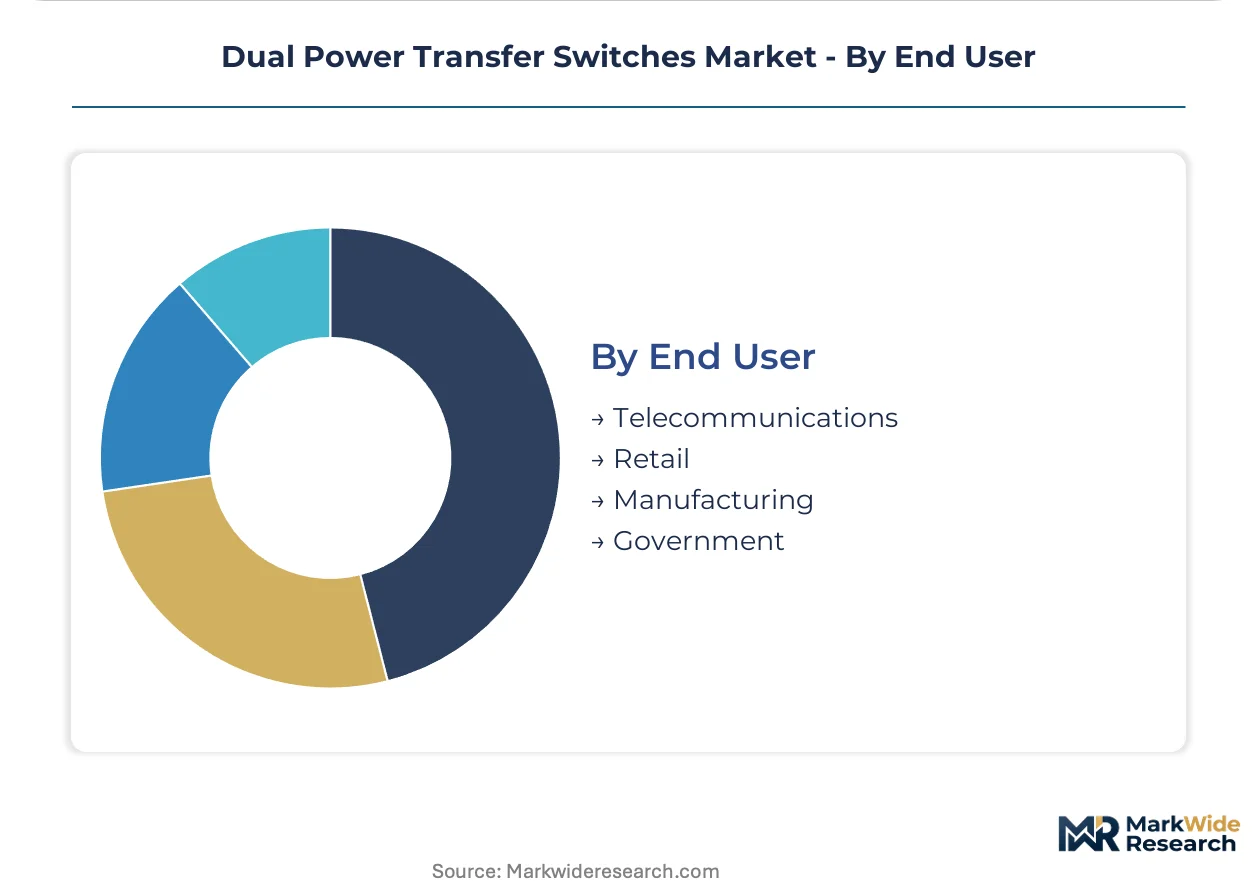
| Segmentation | Product Type: Automatic, Manual, Double Throw, Transfer Switches Application: Data Centers, Hospitals, Commercial Buildings, Industrial Facilities Technology: Electromechanical, Static, Hybrid, Relay Based End User: Telecommunications, Retail, Manufacturing, Government |
| Companies Covered | Eaton Corporation plc, Schneider Electric SE, ABB Ltd., Siemens AG, Cummins Inc., Generac Power Systems Inc., Vertiv Holdings Co., Socomec Group, Caterpillar Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dual Power Transfer Switches Market Shifts & Advancements
Transfer switch intelligence is migrating from standalone controllers into building management system architectures, collapsing maintenance interfaces and enabling predictive failover analytics through continuous waveform monitoring.
Digital twin simulation software is automating commissioning workflows for complex multi-source power distribution schemes. Engineering firms in Singapore and Texas are deploying virtual commissioning environments to validate transfer sequences before physical installation, compressing project timelines by 30-50% and reducing on-site startup failures. This capability is automating the traditional handoff between switchgear OEMs and systems integrators.
The EU F-Gas Regulation is accelerating refrigerant-free thermal management designs for static switch enclosures. Manufacturers serving German and French industrial markets are eliminating hydrofluorocarbon-based cooling systems in favor of liquid-cooled cold plates and ambient heat sinks, extending product lifecycles and simplifying end-of-life disposal compliance. Medical imaging facilities in Switzerland and Austria are prioritizing these configurations in tender specifications.
Buying committees at hyperscale operators are unbundling transfer switch procurement from packaged power plant contracts. Data center developers in Ashburn, Dublin, and Amsterdam are issuing separate RFPs for automatic transfer equipment, bypassing traditional electrical contractor markups and engaging directly with Eaton, Schneider Electric, and ABB specification teams. This disintermediation concentrates volume with manufacturers capable of direct engineering support and global spare parts logistics.
Dual Power Transfer Switches Market Segmentation
Dual power transfer switch procurement patterns diverge sharply across operational contexts. Facility uptime requirements, regulatory mandates, and thermal management constraints reshape buyer priorities across each segmentation dimension.
Product Type:
Buyers differentiate primarily by failover speed requirements and labor availability for switchover operations.
- Automatic:Microprocessor-controlled units execute source transfers without human intervention, achieving sub-100-millisecond response times through programmable logic controllers. NFPA 110 mandates automatic capability for life-safety circuits in United States hospitals, eliminating manual alternatives from new healthcare construction specifications.
- Manual:Operator-actuated switches rely on physical handle rotation or pushbutton engagement, trading speed for capital cost reduction and mechanical simplicity. Small commercial buildings in Germany and secondary industrial facilities in India specify manual transfer where qualified maintenance staff remain on-site and regulatory pressure permits.
- Double Throw:Mechanical interlock designs prevent simultaneous connection to both sources, ensuring break-before-make sequencing in compact footprints. These configurations dominate retrofit installations in older European manufacturing plants with constrained switchgear room dimensions.
- Transfer Switches:General-purpose category encompassing modular and enclosed designs for non-critical load applications. Municipal buildings in France and educational facilities in Spain deploy these units where extended transfer times pose minimal operational risk.
Automatic leads volumes today; Hybrid technology is expanding most quickly as data centers bridge cost-performance requirements.
Application:
End-use environments dictate thermal limits, seismic ratings, and electromagnetic compatibility specifications.
- Data Centers:Hyperscale facilities in Northern Virginia and Frankfurt demand sub-cycle transfer speeds to prevent server rack reboots during utility disturbances. Solid-state and hybrid architectures dominate procurement specifications, with operators accepting substantial cost premiums for uninterrupted compute continuity.
- Hospitals:Operating rooms and intensive care units require automatic failover for life-support equipment under Joint Commission and NFPA 99 standards. Electromechanical switches with silver-alloy contacts remain prevalent due to proven reliability in high-humidity environments and established service networks.
- Commercial Buildings:Office complexes and retail centers prioritize cost-optimized solutions with standard 100-200 millisecond transfer windows. Automatic transfer switches with integrated load shedding controllers capture procurement preference in United States mixed-use developments.
- Industrial Facilities:Heavy manufacturing plants in Bavaria and automotive clusters in Baden-Württemberg specify ruggedized enclosures with IP65 ratings and vibration-resistant contact assemblies. Extended temperature ranges accommodate unconditioned electrical rooms adjacent to production floors.
Data Centers command the steepest expansion trajectory; Commercial Buildings anchor current shipment volumes across all regions.
Technology:
Material science and semiconductor thermal limits differentiate performance ceilings and deployment contexts.
- Electromechanical:Solenoid-driven contact mechanisms utilize copper and silver alloys for current interruption, delivering proven durability across millions of mechanical operations. These switches dominate hospital and industrial applications in Germany where maintenance protocols emphasize component replaceability over speed.
- Static:Silicon-controlled rectifier and insulated-gate bipolar transistor architectures eliminate moving parts, achieving sub-cycle transfer speeds below 4 milliseconds. Hyperscale data centers in Ashburn and Dublin specify static switches exclusively for server rack protection despite 40-60% cost premiums.
- Hybrid:Combined architectures route routine transfers through electromechanical contacts while engaging solid-state bypass for fault conditions. Mid-market data center operators in Mumbai and Chennai adopt hybrid designs to access sub-100-millisecond performance without full static switch pricing.
- Relay Based:Electromechanical relay matrices provide basic transfer functionality for small commercial loads and telecommunications remote shelters. These units compete primarily on capital cost in price-sensitive developing markets.
Electromechanical technology retains volume leadership; Hybrid configurations are climbing the fastest as procurement committees optimize total cost of ownership.
End User:
Capital allocation cycles and regulatory scrutiny intensity reshape procurement committee composition and specification priorities.
- Telecommunications:Mobile network operators and fiber infrastructure providers require compact, fan-cooled switches for remote cell towers and edge data facilities. Tower companies in India specify dual-source redundancy under Digital India connectivity mandates.
- Retail:Big-box chains and grocery distribution centers prioritize automatic transfer for refrigeration continuity and point-of-sale uptime. United States retail procurement teams emphasize standardized specifications across multi-site rollouts to simplify maintenance training.
- Manufacturing:Continuous process industries including chemicals, pharmaceuticals, and semiconductors demand transfer switches with synchronized closing capability to prevent motor damage. German automotive suppliers specify IEC 60947-6-1 certified units with documented sequence-of-operation validation.
- Government:Defense installations, emergency operations centers, and critical infrastructure facilities require tamper-evident enclosures and cyber-secure controller architectures. United States federal procurement incorporates Buy American provisions and NIST cybersecurity framework compliance.
Manufacturing anchors current demand volumes; Telecommunications is gaining share fastest as 5G infrastructure deployment accelerates backup power investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized power systems commissioning engineers concentrate in Germany, the United States, and India, creating talent clusters that anchor regional demand patterns for dual power transfer switches.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth drives automatic transfer switch procurement. NFPA 110 mandates automatic failover capability for hospital life-safety circuits. The Ashburn-Loudoun County corridor hosts the world's densest concentration of cloud computing facilities requiring sub-cycle transfer speeds.
Germany
Automotive manufacturing clusters in Bavaria and Baden-Württemberg specify ruggedized transfer switches for production continuity. The Network Expansion Acceleration Act channels federal investment into industrial backup infrastructure. Siemens AG anchors electromechanical switch engineering expertise in Munich and Nuremberg.
China
Digital infrastructure buildout under national cloud computing initiatives creates demand for dual-source redundancy. GB standards and grid reliability mandates tighten performance specifications for critical facilities. The Yangtze River Delta data center corridor in Shanghai and surrounding provinces leads procurement volumes.
India
Mumbai and Chennai hyperscale projects under the Digital India initiative specify automatic transfer equipment for first-time dual-source redundancy. Central Electricity Authority regulations mandate backup power standards for telecommunications infrastructure. Tower companies accelerate installations across Maharashtra and Tamil Nadu.
United Kingdom
London and Southeast England data center operators prioritize static transfer switches for financial services continuity. The EU Green Deal influences procurement criteria even post-Brexit, weighting embodied carbon in switchgear evaluations. Slough and Docklands clusters concentrate demand for premium transfer equipment.
Dual Power Transfer Switches Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the dual power transfer switch landscape. The vendor base organizes around three strategic archetypes: integrated electrical conglomerates with captive distribution networks, specialized switchgear pure-plays with deep certification expertise, and power generation OEMs extending into downstream control equipment. Consolidation pressure intensifies as hyperscale operators disintermediate electrical contractors and contract directly with manufacturers. Geographic expansion and technology licensing dominate competitive moves, with European players seeking Asian certification breadth and Asian manufacturers pursuing IEC type-testing credentials.
Among integrated electrical conglomerates, Eaton Corporation plc and Schneider Electric SE exemplify the capital-intensive archetype with specification-engineering capabilities spanning multiple continents. ABB Ltd. occupies a position bridging manufacturing scale with IEC certification breadth across Asian and Middle Eastern markets. These three anchors represent distinct geographic and technological positioning within the competitive structure.
| Leading Market Players |
|---|
| Eaton Corporation plc |
| Schneider Electric SE |
| ABB Ltd. |
| Siemens AG |
| Cummins Inc. |
| Generac Power Systems Inc. |
| Vertiv Holdings Co. |
| Socomec Group |
| Caterpillar Inc. |
| Others |
Supply & Pricing Matrix
Static-electromechanical performance bifurcation separates premium sub-4-millisecond failover capability from commodity 100-200-millisecond alternatives, concentrating procurement budgets with IEC 60947-6-1 certified manufacturers while channeling volume through electrical contractor networks in Germany and direct OEM relationships in Northern Virginia data center corridors.
Pricing Analysis
Bundled power plant contracts historically captured transfer switch procurement through electrical contractor markups, though hyperscale operators in Ashburn and Dublin now unbundle specifications into direct RFPs. Price differentiation rests on certification grade—NFPA 110 compliance commands 25-35% premiums over non-certified alternatives—and after-sales service bundling. Cost compression in electromechanical tiers intensifies as copper and silver contact volatility squeezes margins. Small commercial buyers in Spain and municipal facilities in France exhibit highest price sensitivity; hyperscale data centers in Frankfurt accept substantial premiums for static switch performance.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand in the United States and Germany, while distributor networks serve secondary industrial markets in India and commercial construction in France. Manufacturing concentrates in Germany, China, and the United States, with Siemens AG and ABB Ltd. anchoring European production. Contact assemblies draw from copper and silver alloy suppliers, silicon-controlled rectifier fabricators, and microprocessor controller sources. Single-source vulnerability in semiconductor-grade silicon wafers for static switch fabrication presents structural risk. Distribution runs through electrical wholesalers for contractor-specified projects and direct specification engineering for data center developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory tailwinds into sustained demand, with NFPA 110 and IEC 60947-6-1 tightening transfer switch performance mandates across healthcare and data center construction cycles.
For Market Incumbents: Acquire commissioning engineering capabilities to offset talent scarcity commanding salary premiums in competitive labor markets. Incumbents should anchor defensive positioning through backward integration into contact assembly production, mitigating copper and silver price volatility that compresses margins. Certification investment in IEC 60947-6-1 type-testing capacity addresses 14-18-month bottlenecks freezing competitor development roadmaps. For New Entrants and Emerging Players: Begin with hybrid electromechanical-static architectures targeting mid-market data center operators in Mumbai and Chennai previously priced out of all-solid-state solutions. India's Digital India initiative creates greenfield dual-source redundancy specifications for first-time automatic transfer equipment procurement. Go-to-market positioning should emphasize liquid-cooled cold plate thermal management configurations compliant with EU F-Gas Regulation procurement criteria. For Investors and Strategic Acquirers: Consolidation pressure builds where hyperscale operators disintermediate electrical contractors and concentrate volume with manufacturers capable of direct engineering support. Long-term viability favors vertically integrated producers with captive IEC certification breadth and global spare parts logistics. Acquisition target archetype: specialized switchgear pure-plays with deep type-testing expertise and established relationships with German automotive manufacturing clusters. Monitor India's data center buildout acceleration as inflection indicator for greenfield demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 60947-6-1 Certification Investment | Accelerates European market access for static switch ratings amid 14-18-month testing bottlenecks. |
| Hybrid Technology Platform Launch | Captures mid-market data center segments in Mumbai and Chennai bridging cost-performance requirements. |
| Direct Engineering Support Expansion | Aligns with hyperscale disintermediation trends in Ashburn, Dublin, and Amsterdam procurement patterns. |
| Refrigerant-Free Thermal Management Transition | Secures German and French industrial tenders under EU F-Gas Regulation compliance mandates. |
| Commissioning Engineer Talent Acquisition | Addresses 40% salary premiums and project timeline compression in competitive labor markets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with data center infrastructure directors, hospital facilities engineers, electrical contractor procurement leads, and power systems commissioning specialists with secondary validation through SEC filings, EIA infrastructure databases, IEC certification registries, and customs trade records. Bottom-up shipment tracking across automatic, manual, and hybrid product categories triangulated against top-down facility construction pipeline analysis.
Historical reference periods anchored the projection horizon to documented NFPA 110 adoption waves and IEC 60947-6-1 implementation timelines across European healthcare construction. The analytical framework modeled segmentation dimensions spanning transfer speed tier, technology architecture, application environment, and end-user capital allocation cycle. CAGRs derived from facility investment intensity correlations with grid reliability mandate enforcement. Industry-specific forecast inputs included copper and silver price trajectory assumptions and data center power density evolution patterns.
Several conditions sit outside the modeled scope, including unannounced regulatory revisions to EPA Tier 4 Final generator integration requirements and geopolitical disruptions to semiconductor wafer supply chains. Forecasts reflect assumptions about sustained hyperscale construction activity in Northern Virginia and Frankfurt corridors. Periodic stress-testing of base assumptions is recommended against copper price volatility and power systems engineer labor market tightness.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Membrane Switch Market
Switches
Hazardous Location Limit Switches Market
Switches
India Switchgear Market
Switches
Fusible Switches Market
Switches
Asia Pacific Transfer Switches Market
Switches
Smart Circuit Breaker Market
Switches
Navigation Switches Market
Switches
Rotary Limit Switches Market
Switches
Australia Switchgear Market
Switches
Carrier Router Switch Market
Switches
Asia Pacific Safety Switches Market
Switches
Rocker Switch Market
Switches
Electromechanical Microwave Switch Market
Switches
Europe Low Voltage Switchgear Market
Switches
Argentina Automotive Reed Sensors Switches Market
Switches
Global Safety Switches Market