
 Residual Current Circuit Breaker Market | 2026-2036
Residual Current Circuit Breaker Market Size, Share, and Industry Trends Forecast 2026-2036
Residual Current Circuit Breaker Market Outlook
IEC 61009 certification for residual current operated circuit breakers with integral overcurrent protection is reorganizing competitive entry barriers across the supply base. Schneider Electric SE leverages its captive testing infrastructure to accelerate qualification timelines for new product families. Siemens AG anchors its position through deep backward integration into semiconductor trip units and electromagnetic actuators. ABB Group competes by sustaining broad voltage-grade coverage across modular and fixed-installation architectures.
A residual current circuit breaker detects earth fault currents and interrupts power to prevent electrocution or fire hazards, typically operating at sensitivity thresholds between 10 and 300 milliamperes with response times under 30 milliseconds. The device serves as mandatory protection in final distribution circuits across residential, commercial, and industrial electrical installations. RCBO units combining RCCB and miniature circuit breaker functions command premium positioning due to space-constrained panel designs and simplified installation labor. Wall-mounted configurations dominate retrofit activity while embedded installations gain traction in OEM electrical equipment. Industrial application demand outpaces residential replacement cycles where existing stock still meets legacy sensitivity standards.
The US National Electrical Code through NFPA 70 mandates GFCI and AFCI protection in increasingly broad circuit categories, directly expanding addressable unit demand. Europe's Ecodesign Directive and F-Gas Regulation indirectly shape product development priorities by pressuring energy efficiency and material substitution in electrical distribution equipment. India's BIS certification and CEA grid connectivity standards are tightening import qualification requirements for foreign manufacturers. Stakeholders must monitor evolving trip-curve harmonization between IEC and UL standards when allocating R&D resources across regional product platforms.
Market Dynamics
IEC 61008 and IEC 61009 certification tightening is compressing qualification timelines and forcing manufacturers to consolidate testing infrastructure around captive laboratories. This regulatory pressure is redistributing competitive advantage toward vertically integrated suppliers with in-house electromagnetic compatibility validation.
Growth Catalysts
- Data center electrification:Hyperscale computing facilities in Germany and the Netherlands are expanding RCCB procurement to protect critical power distribution infrastructure against earth fault risks.
- NFPA 70 circuit expansion:The US National Electrical Code mandates GFCI and AFCI protection in progressively broader circuit categories, directly expanding addressable unit demand across residential and commercial construction.
- Industrial retrofit cycles:Germany's building safety retrofit mandates are accelerating replacement of legacy residual current devices that fail to meet updated sensitivity thresholds.
Market Restraints
- Copper and silver price volatility:Electromagnetic trip units and conductor assemblies depend on precious metal inputs subject to commodity exchange fluctuations, compressing margin stability for mid-tier manufacturers.
- Semiconductor trip unit concentration:Advanced semiconductor-based detection circuits concentrate among three East Asian foundry suppliers, creating single-source vulnerability for European and North American assemblers.
- Legacy sensitivity grandfathering:Existing residential installations in France and Italy still comply with 300mA thresholds, delaying replacement demand despite 30mA mandates for new construction.
Strategic Opportunities
- India BIS certification tightening:The Bureau of Indian Standards and Central Electricity Authority are raising import qualification barriers, creating first-mover advantage for domestic manufacturing joint ventures.
- RCBO space convergence:Combined residual current and overcurrent protection units are capturing panel space in OEM electrical equipment where enclosure volume constraints dominate design priorities.
- Digital twin integration:Predictive maintenance platforms for industrial electrical infrastructure are creating attach-rate opportunities for smart RCCB variants with embedded current monitoring.
Industry Challenges
- IEC-UL trip curve harmonization:Manufacturers maintaining separate regional product platforms face duplicated R&D overhead as standards bodies diverge on electromagnetic compatibility test protocols.
- Electromagnetic actuator skill scarcity:Specialized winding and calibration expertise for high-speed trip mechanisms concentrates among aging technician cohorts in Germany and Switzerland.
- Embedded installation integration:OEM equipment manufacturers demand customized form factors that fragment production runs and complicate inventory management for standard product families.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residual Current Circuit Breaker Market |
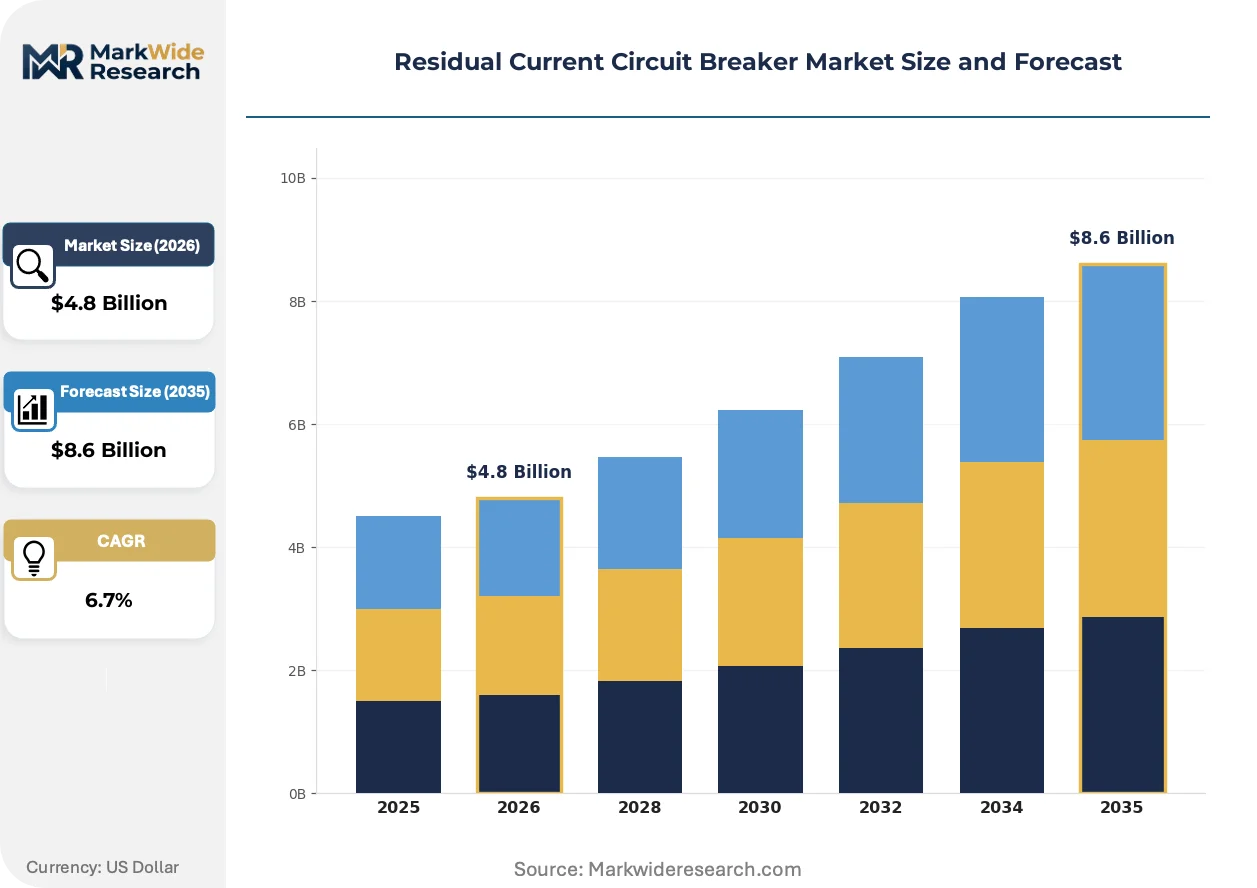
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Miniature Circuit Breakers, RCCB, RCBO, Isolators Application: Residential, Commercial, Industrial, Agriculture Installation: Panel Mounted, Wall Mounted, Portable, Embedded End User: Homeowners, Contractors, Manufacturers, Service Providers |
| Companies Covered | Schneider Electric SE, Siemens AG, ABB Group, Eaton Corporation, Legrand SA, Mitsubishi Electric Corporation, CHINT Group, Hager Group, Fuji Electric Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residual Current Circuit Breaker Market Strategic Shifts
Electromechanical detection architectures are yielding to semiconductor-based alternatives, compressing response times while introducing cybersecurity and functional safety validation requirements. This transition is redistributing value capture toward firmware and sensor suppliers.
Silicon-based residual current detection is bifurcating the market between premium smart units with embedded diagnostics and cost-optimized electromechanical alternatives for price-sensitive residential segments. Industrial buyers in Germany and Japan are specifying sub-10 millisecond response thresholds that only digital signal processing architectures can reliably achieve. Semiconductor trip units are compressing the addressable market for traditional toroidal transformer designs while expanding total available value through predictive maintenance integration.
The EU F-Gas Regulation and Ecodesign Directive are pressuring energy efficiency in electrical distribution equipment, indirectly accelerating material substitution in RCCB housings and contact assemblies. Manufacturers are reformulating thermoplastic compounds to eliminate halogenated flame retardants while maintaining IEC 61009 dielectric withstand requirements. German and French certification bodies are expanding scope 3 carbon accounting documentation demands that favor regional suppliers with localized polymer sourcing.
Specification authority is migrating from electrical contractors toward facility engineering departments with formalized total cost of ownership models. Data center operators in Virginia and Frankfurt are unbundling installation labor from device procurement, compressing distributor margins while expanding direct manufacturer relationships. This channel compression is most visible in North American hyperscale construction where single-project volumes justify factory-direct logistics arrangements bypassing traditional electrical wholesale networks.
Residual Current Circuit Breaker Market Segmentation
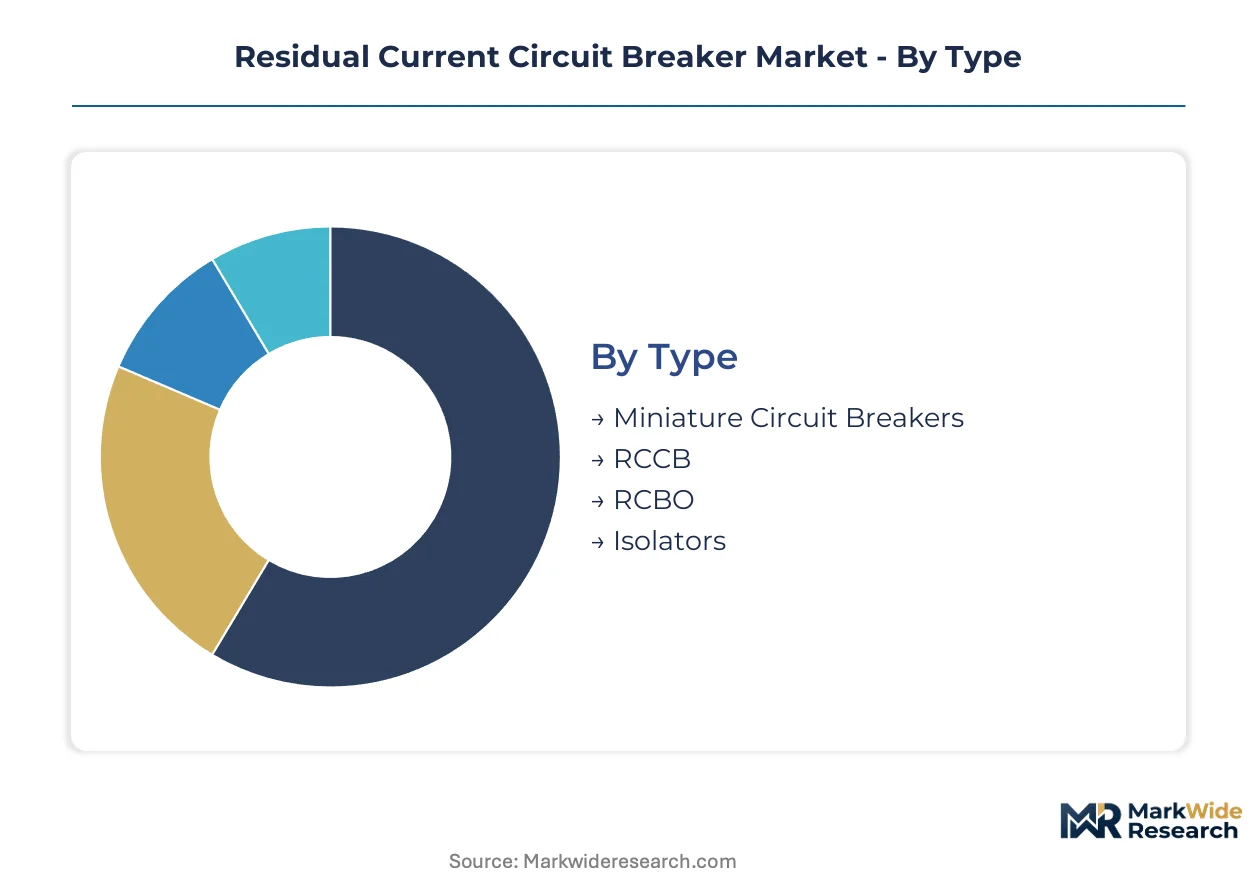
Segmentation in the residual current circuit breaker market reveals how protection requirements diverge across electrical infrastructure layers. Product type and installation method determine certification complexity, while end-user sophistication shapes channel economics and service attachment rates.
Type:
Semiconductor-based detection architectures are displacing electromechanical alternatives fastest in segments where response time precision commands premium positioning.
- RCBO:Combines residual current detection with integral overcurrent protection in a single modular housing. Data center operators in Germany and the Netherlands specify RCBO units to compress panel footprints while satisfying IEC 61009 certification for critical power distribution nodes.
- RCCB:Pure residual current detection without overcurrent protection, typically deployed upstream of final distribution circuits. Industrial retrofit cycles in Germany favor RCCB replacement where existing miniature circuit breakers remain serviceable but earth fault sensitivity requires upgrading.
- Miniature Circuit Breakers:Overcurrent protection devices without residual current detection, facing substitution pressure from combined-function alternatives in new construction.
- Isolators:Manual disconnect switches providing visible circuit isolation for maintenance safety, specified alongside RCCB units in agricultural and heavy industrial installations.
RCBO anchors the volume base while RCCB gains share at the steepest rate in industrial replacement activity.
Application:
Cost tier differentiation separates specification authority between electrical contractors with installation-labor models and facility engineers with total cost of ownership frameworks.
- Industrial:Manufacturing facilities, processing plants, and logistics centers demand sub-10 millisecond response thresholds. Japanese automotive and electronics manufacturers specify semiconductor trip units that only digital signal processing architectures can reliably achieve.
- Data Center:Hyperscale computing facilities require coordinated protection across redundant power distribution paths. Operators in Virginia and Frankfurt unbundle installation labor from device procurement, compressing distributor margins while expanding direct manufacturer relationships.
- Residential:Final distribution circuits in housing stock face delayed replacement where legacy 300mA sensitivity thresholds remain grandfathered compliant in France and Italy.
- Commercial:Office buildings, retail facilities, and hospitality infrastructure balance code compliance with aesthetic constraints on visible electrical equipment.
- Agriculture:Outdoor and livestock environments impose moisture and vibration exposure that favors sealed wall-mounted configurations over panel-integrated alternatives.
Industrial applications command the highest specification intensity while data center procurement is climbing the fastest as hyperscale construction accelerates.
Installation:
Volume concentration favors retrofit-accessible formats where existing electrical infrastructure determines mounting constraints rather than optimal protection architecture.
- Wall Mounted:Surface-mounted enclosures dominate residential and light commercial retrofit activity where existing distribution boards lack spare module slots. German building safety mandates accelerate replacement of legacy devices through this accessible format.
- Panel Mounted:DIN rail integration within distribution boards serves new construction and comprehensive electrical upgrades. OEM electrical equipment manufacturers in Japan and Germany specify panel-mounted RCBO units where enclosure volume constraints dominate design priorities.
- Embedded:Custom form factors integrated into factory-built electrical equipment fragment production runs and complicate inventory management for standard product families.
- Portable:Temporary power distribution for construction sites and outdoor events, subject to wear and environmental exposure that accelerates replacement cycles.
Wall mounted dominates replacement volume while panel mounted expands most quickly in new construction and data center greenfield projects.
End User:
Customer type determines whether procurement flows through electrical wholesale networks or bypasses toward direct manufacturer relationships.
- Contractors:Installation firms with recurring project relationships favor standardized product families that minimize truck stock complexity. North American electrical contractors face NFPA 70 expansion of GFCI and AFCI circuit coverage that directly expands unit demand.
- Manufacturers:OEM electrical equipment builders demand customized form factors and embedded installation integration that fragments production economics.
- Homeowners:Retail and e-commerce procurement of replacement devices, price-sensitive and dependent on contractor recommendation for brand selection.
- Service Providers:Maintenance and facility management firms with predictive maintenance platforms create attach-rate opportunities for smart RCCB variants with embedded current monitoring.
Contractors anchor procurement volume while manufacturers represent the steepest expansion trajectory as OEM equipment integration requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Building safety retrofits and industrial electrification mandates are accelerating residual current circuit breaker replacement cycles across major economies. National electrical codes and energy efficiency directives are tightening certification requirements and reshaping procurement patterns.
Germany
Industrial electrification and data center construction are driving RCBO demand in Frankfurt and the Rhine-Ruhr corridor. The country's national building regulator enforces updated sensitivity thresholds through DIN VDE standards that mandate 30mA protection in final distribution circuits. Bavarian automotive manufacturers specify semiconductor-based trip units for sub-10 millisecond response in production facilities.
United States
Hyperscale data center construction in Virginia and Texas is expanding GFCI and AFCI procurement for critical power infrastructure. The NFPA 70 National Electrical Code mandates expanded circuit protection categories in residential and commercial construction. Electrical contractors in the Pacific Northwest face accelerated replacement cycles as state-level amendments tighten grandfathering provisions for legacy installations.
India
Grid connectivity standards and building safety mandates are tightening import qualification barriers for foreign manufacturers. The Bureau of Indian Standards and Central Electricity Authority raise certification requirements for residual current devices in commercial and industrial installations. Manufacturing joint ventures in Gujarat and Maharashtra target first-mover positioning in domestic assembly of IEC-compliant units.
Japan
Automotive and electronics manufacturers specify digital signal processing architectures for sub-10 millisecond response thresholds. The Ministry of Economy, Trade and Industry enforces JIS standards that accelerate semiconductor trip unit adoption in precision manufacturing. Industrial clusters in Nagoya and Osaka drive panel-mounted RCBO specification for OEM electrical equipment integration.
Netherlands
Hyperscale computing facilities in Amsterdam and Rotterdam expand procurement for redundant power distribution protection. The Ecodesign Directive pressures energy efficiency requirements in electrical distribution equipment specification. Dutch certification bodies expand carbon accounting documentation demands that favor regional suppliers with localized polymer sourcing for housing assemblies.
Residual Current Circuit Breaker Market Competitive Environment
Player mix skews toward diversified electrical equipment conglomerates with captive testing infrastructure and semiconductor trip unit capabilities. Three archetypes dominate: vertically integrated European manufacturers with in-house electromagnetic compatibility validation, East Asian electronics specialists with semiconductor detection expertise, and emerging domestic assemblers in high-growth import substitution markets. Competitive moves concentrate on M&A for testing laboratory assets and strategic partnerships for foundry access to advanced trip unit semiconductors.
Among European-based diversified manufacturers, Schneider Electric SE, Siemens AG, and ABB Group occupy positions that exemplify the integrated archetype with captive certification infrastructure. These companies represent the premium-tier vector where backward integration into semiconductor trip units and electromagnetic actuators anchors competitive positioning. Their geographic distribution across France, Germany, and Switzerland reflects historical concentration of specialized winding and calibration expertise for high-speed trip mechanisms.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Siemens AG |
| ABB Group |
| Eaton Corporation |
| Legrand SA |
| Mitsubishi Electric Corporation |
| CHINT Group |
| Hager Group |
| Fuji Electric Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day lead times for semiconductor trip units concentrate pricing power with East Asian foundry suppliers while compressing margin flexibility for European and North American assemblers. Inventory buffers at distribution nodes in Germany and the Netherlands determine spot pricing responsiveness for emergency replacement orders.
Pricing Analysis
Certification level creates the primary spread between IEC 61009-compliant premium units and legacy-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects differential sensitivity thresholds, response time precision, and smart monitoring capabilities. Cost compression in economy-tier electromechanical units is intensifying because of copper and silver price volatility on commodity exchanges. Residential contractors exhibit the highest price sensitivity, while data center operators in Virginia and Frankfurt prioritize sub-10 millisecond response specifications over unit cost.
Supply Chain Analysis
East Asia anchors semiconductor trip unit fabrication, with Taiwan and South Korea supplying advanced detection circuits to European and North American assemblers. Germany and Switzerland concentrate specialized winding and calibration expertise for high-speed electromagnetic actuators. Raw material dependencies span copper conductor assemblies, silver contact points, and halogen-free thermoplastic compounds. Single-source vulnerability concentrates among three East Asian foundry suppliers. Distribution runs through electrical wholesale networks in residential and commercial segments, while hyperscale data center projects bypass toward direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance platforms for industrial electrical infrastructure expand service-attach revenue faster than hardware unit growth, creating recurring revenue layers around embedded current monitoring and remote diagnostics.
For Market Incumbents: Secure captive testing laboratory capacity to compress IEC 61009 qualification timelines as regulatory bodies tighten electromagnetic compatibility protocols. Deepen backward integration into semiconductor trip units to reduce single-source exposure to East Asian foundry concentration. Channel control through direct relationships with hyperscale data center operators defends margin position against distributor compression. For New Entrants and Emerging Players: Anchor in India's domestic manufacturing joint ventures as BIS certification tightening raises import barriers for foreign competitors. Target agricultural and heavy industrial applications where sealed wall-mounted configurations face less entrenched incumbent presence. Partner with regional electrical contractors on installation-labor bundling to bypass wholesale network gatekeeping. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because building safety mandates and sensitivity threshold upgrades drive replacement cycles independent of construction cyclicality. Acquisition targets should concentrate on testing laboratory assets and semiconductor trip unit design capabilities. Watch for divergence between IEC and UL trip curve harmonization as the signal for regional platform consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Testing Laboratory Acquisition | Captive IEC 61009 validation infrastructure compresses product launch cycles against regulatory tightening. |
| Semiconductor Trip Unit Partnership | Foundry access agreements reduce single-source vulnerability for advanced detection circuit supply. |
| Predictive Maintenance Platform Launch | Smart RCCB variants with embedded monitoring capture service-attach revenue from facility engineering departments. |
| Domestic Manufacturing Joint Venture | Local assembly in Gujarat and Maharashtra secures first-mover positioning under tightening BIS import rules. |
| Direct Data Center Channel Development | Factory-direct logistics arrangements bypass electrical wholesale networks in hyperscale construction projects. |
Study Parameters
Desk research of regulatory filing databases, customs trade records, and certification body documentation preceded structured interviews with electrical equipment procurement managers, distribution channel partners, aftermarket service heads, and OEM platform engineers. Primary fieldwork with plant engineers and maintenance directors at manufacturing facilities in Germany, Japan, and the United States validated sensitivity threshold specifications and replacement cycle timing. Secondary sources included IEC and UL standards documentation, national electrical code amendments, and hyperscaler capex disclosures for data center construction. Bottom-up unit demand modeling triangulated against top-down market value estimates.
Variance decomposition across product type, installation method, end-use application, and geographic regulatory cluster shaped the analytical framework over the projection horizon. Modeled segmentation dimensions included RCBO versus RCCB architecture, wall-mounted versus panel-mounted format, and industrial versus data center versus residential demand. CAGRs derived from regression analysis against macroeconomic construction indicators and electrification investment cycles. Industry-specific forecast inputs incorporated NFPA 70 circuit expansion mandates and DIN VDE sensitivity threshold enforcement.
Decision-makers should treat outputs as directional under assumptions of continued regulatory tightening and stable copper price bands; material deviation in commodity volatility or harmonization progress would warrant model refresh. Specific risk factors include semiconductor foundry supply disruptions, grandfathering extension for legacy sensitivity thresholds, and divergence between IEC and UL electromagnetic compatibility protocols. Recalibration cycles align with material shifts in national electrical code amendments and hyperscale data center construction announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Digital Crosspoint Switches Market
Switches
Reed Switches Sensors Market
Switches
Solid State Relay Market
Switches
Haptic Feedback Switch and Button Platforms Market
Switches
5G Electromechanical RF Switch Market
Switches
Micro Switch Market
Switches
India Switchgear Market
Switches
Europe Switchgear Market
Switches
Global Electrical Switches Market
Switches
Timer Switch Socket Market
Switches
Australia Switchgear Market
Switches
North America Low Voltage Switchgear Market
Switches
North America Medium Voltage Switchgear Market
Switches
Dual Power Transfer Switches Market
Switches
Electric Switch Market
Switches
Carrier Router Switch Market