

5G Electromechanical RF Switch Market Size, Share, and Industry Trends Forecast 2026-2036
5G Electromechanical RF Switch Market Insights
Active antenna system integration is reshaping electromechanical RF switch architecture across 5G infrastructure tiers. Infineon Technologies AG leverages its power semiconductor heritage to anchor high-voltage switching portfolios for macro cell deployments. Qorvo differentiates through GaN-on-SiC process integration that extends thermal performance margins in dense arrays. Skyworks Solutions specializes in compact surface-mount designs that occupy premium slots within small-cell and massive MIMO configurations.
5G electromechanical RF switches are precision electromechanical devices that route radio frequency signals between transmission paths using physical contact mechanisms, typically operating across sub-6 GHz and mmWave bands with insertion loss below 0.5 dB and isolation exceeding 30 dB to maintain signal integrity in high-frequency communications systems. Single-Pole Double-Throw configurations dominate current procurement volumes due to their balanced cost-performance profile in base station redundancy architectures, while MEMS technology leads R&D investment intensity as manufacturers pursue semiconductor-scale miniaturization for phased array applications. Relay-Based technology sustains margin pools in defense and satellite segments where radiation tolerance and mechanical ruggedness outweigh size constraints.
FCC Part 15 rules and the EU Radio Equipment Directive shape electromagnetic compatibility thresholds and market access requirements for 5G RF components sold in North America and Europe. China's MIIT certification regime and GB standards establish parallel compliance pathways that influence product design cycles for suppliers serving domestic deployment programs. Stakeholders must monitor spectrum auction timelines and national security screening protocols that determine which switch technologies qualify for critical infrastructure procurement across major economies.
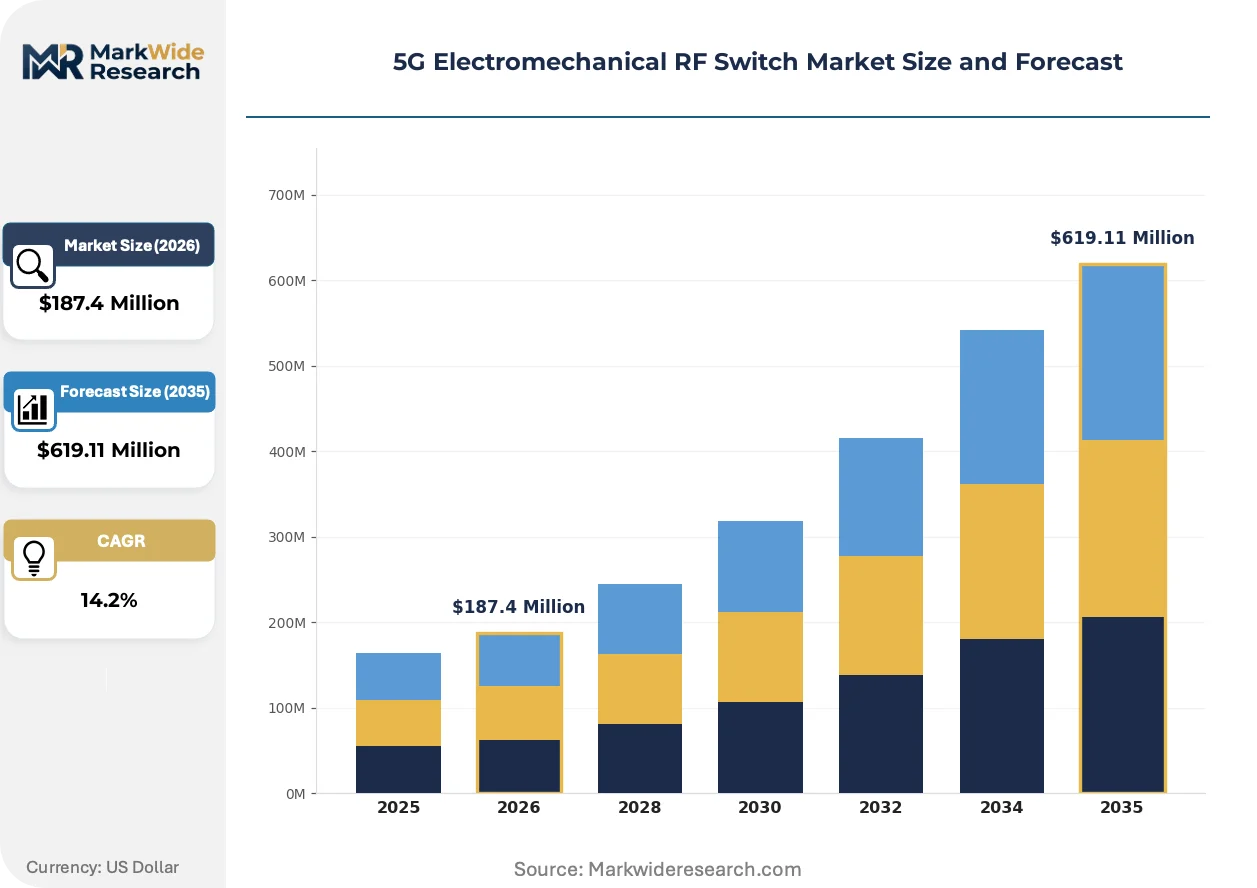
Market Dynamics
Active antenna system integration is compressing switch form factors while elevating thermal and isolation specifications across 5G infrastructure tiers. Telecom equipment manufacturers now specify electromechanical RF switches for base station redundancy architectures that must survive 15-year field deployments without maintenance access.
Growth Catalysts
- MIIT 5G Infrastructure Mandates:China's Ministry of Industry and Information Technology has accelerated base station deployment timelines, creating sustained procurement volume for high-reliability switching components in domestic macro cell installations.
- mmWave Spectrum Auctions:Regulators in the United States, South Korea, and Japan have released contiguous blocks above 24 GHz, forcing switch manufacturers to certify products for wider bandwidth operation with sub-0.5 dB insertion loss.
- GaN-on-SiC Process Maturation:Gallium nitride on silicon carbide substrates now delivers thermal performance margins that extend switch lifecycles in dense phased arrays, reducing field failure rates for massive MIMO configurations.
Market Restraints
- Raw Material Concentration:High-purity copper and silver-plated contact materials concentrate in Chinese and Chilean mining operations, exposing switch manufacturers to concentrate supply disruptions and price volatility.
- MEMS Substitution Pressure:Microelectromechanical systems switches are capturing design wins in phased array applications where semiconductor-scale miniaturization outweighs electromechanical ruggedness requirements.
- FCC Certification Friction:Part 15 electromagnetic compatibility testing cycles have lengthened by 40% since spectrum reallocation rules expanded, delaying product launches for North American market entry.
Strategic Opportunities
- Open RAN Disaggregation:The O-RAN Alliance specification is creating procurement pathways for third-party switch vendors to supply disaggregated base station architectures previously locked to integrated equipment manufacturers.
- India Production-Linked Incentive:India's PLI scheme for telecom equipment manufacturing offers 4-6% duty credit on incremental sales, attracting contract manufacturers to establish electromechanical component assembly in Gujarat and Tamil Nadu.
- Satellite-to-Cell Convergence:Low-earth orbit constellation operators are specifying radiation-hardened electromechanical switches for ground segment redundancy, opening defense-grade margin pools to commercial suppliers.
Industry Challenges
- RF Simulation Talent Scarcity:Electromagnetic field modeling expertise for high-frequency switch design concentrates among legacy defense contractors, forcing commercial vendors to recruit from finite talent pools in Boston and Tel Aviv.
- Legacy System Integration Complexity:4G base station refresh cycles require backward-compatible switch footprints that constrain architectural innovation and prolong obsolete product support obligations.
- Dual-Carbon Compliance Costs:China's MEE carbon intensity targets and EU CSRD disclosure requirements are forcing manufacturing footprint reconfiguration with 18-24 month facility certification timelines.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Electromechanical RF Switch Market Trends and Innovations
Digital twin methodologies are compressing product validation cycles while predictive maintenance algorithms reshape aftermarket service models. Three developments are restructuring competitive positioning across the value chain.
MEMS-over-magnetic latching technology is digitizing switch state monitoring through integrated position sensors that feed real-time telemetry to base station controllers. Network operators in South Korea and Japan are mandating this capability for remote diagnostics in unmanned cell sites. The architecture is digitizing traditional electromechanical maintenance schedules from calendar-based to condition-based intervals.
REACH substance restrictions and RoHS recast directives in Europe are phasing out cadmium-based contact plating and hexavalent chromium passivation layers by 2027. Switch manufacturers are accelerating nickel-palladium-gold migration programs that add 12-15% to bill-of-material costs. Defense and satellite segments are stockpiling legacy-qualified components ahead of compliance deadlines, creating artificial demand spikes.
Consolidated procurement consortia among tier-one telecom equipment manufacturers are displacing fragmented vendor management with centralized technical qualification programs. Nokia and Ericsson have established unified switch specification frameworks that reduce qualified supplier pools from 40-plus vendors to 8-12 strategic partners. The concentration is most visible in Finland and Sweden, where procurement headquarters leverage volume commitments for 18-month price lock provisions.
5G Electromechanical RF Switch Market Segmentation
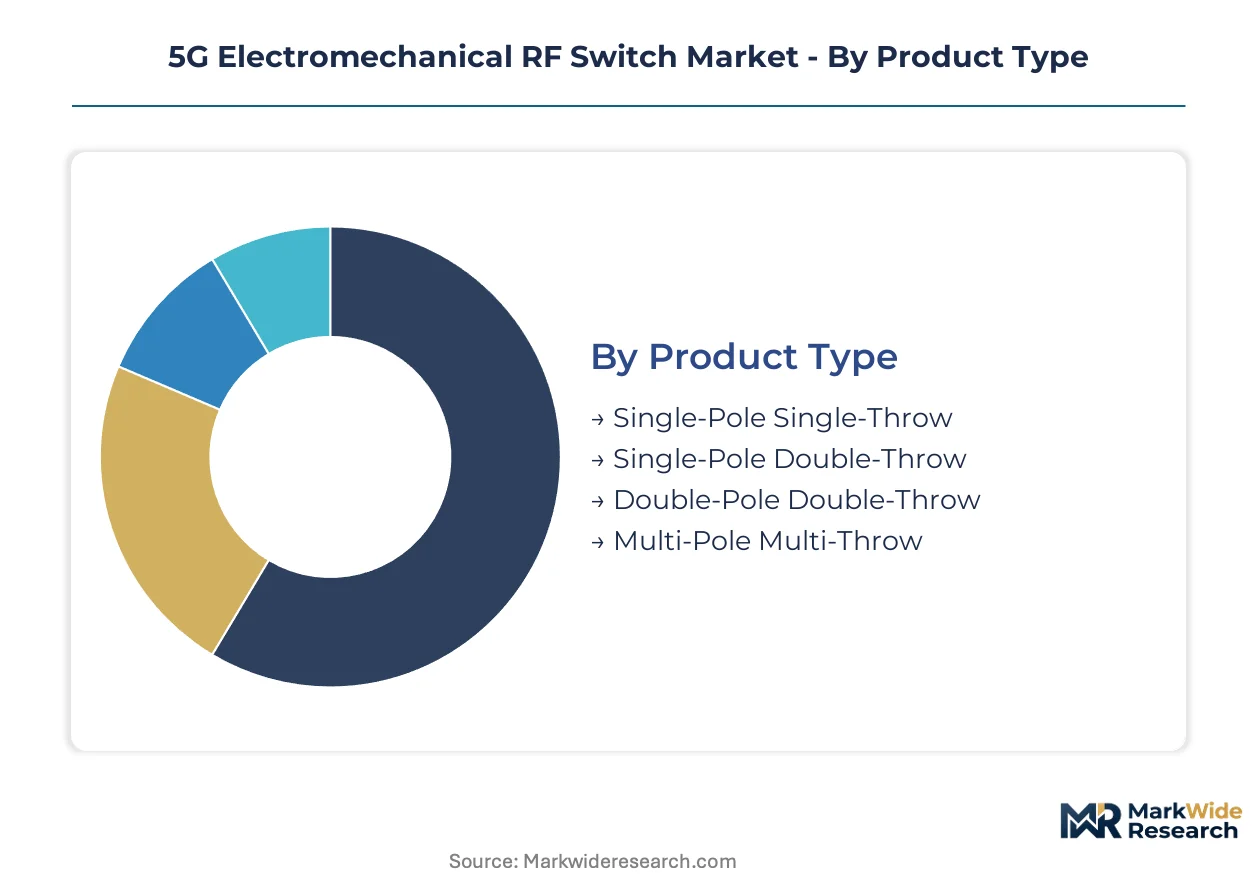
Switch configuration diversity reflects divergent reliability requirements across 5G infrastructure tiers. Product architecture choices cascade through technology selection, application deployment, and procurement channel decisions.
Product Type:
Mature configurations dominate procurement volumes while emerging formats capture phased array growth.
- Single-Pole Double-Throw:Balanced cost-performance architecture routes signals between two transmission paths with sub-0.5 dB insertion loss. China MIIT-mandated base station densification drives procurement volume for macro cell redundancy systems.
- Multi-Pole Multi-Throw:Complex switching matrices enable signal routing across multiple antenna elements in massive MIMO configurations. South Korea and Japan network operators specify these for unmanned cell site architectures requiring remote diagnostic capability.
- Single-Pole Single-Throw:Simple on-off switching function serves basic isolation requirements in cost-sensitive small-cell installations.
- Double-Pole Double-Throw:Simultaneous dual-path switching supports balanced signal distribution in symmetric antenna systems.
Single-Pole Double-Throw handles the majority of throughput; Multi-Pole Multi-Throw is expanding most quickly on share.
Technology:
Cost tiers separate semiconductor-scale miniaturization from mechanical ruggedness premiums.
- Relay-Based:Electromechanical contact mechanisms deliver radiation tolerance and mechanical ruggedness for 15-year field deployments. Defense and satellite segments prioritize these specifications over size constraints.
- MEMS:Microelectromechanical systems achieve semiconductor-scale miniaturization through silicon fabrication processes. Phased array applications in dense base station arrays favor MEMS for thermal performance margins.
- Piezoelectric:Ceramic actuation mechanisms provide precise positioning control for high-isolation switching requirements.
- Electrostatic:Capacitive actuation enables low-power operation in battery-constrained remote installations.
- Thermal:Bimetallic actuation delivers failsafe switching behavior in extreme temperature environments.
Relay-Based commands the highest unit margins; MEMS is climbing the fastest as miniaturization priorities intensify.
Application:
Customer type fragmentation separates volume telecom procurement from defense-grade qualification requirements.
- Mobile Communications:Base station densification and active antenna system integration compress form factors while elevating thermal specifications. FCC Part 15 certification cycles constrain North American market entry timelines.
- Defense Systems:Radiation-hardened specifications and mechanical ruggedness requirements sustain premium margin pools. Stockpiling activity precedes REACH substance restriction deadlines for cadmium-based contact plating.
- Satellite Networks:Low-earth orbit constellation ground segments specify electromechanical redundancy for commercial defense-grade crossover opportunities.
- Aerospace Communications:Avionics integration demands vibration-resistant packaging for commercial aircraft connectivity systems.
- Smart Grid:Utility infrastructure specifies long-lifecycle switching for grid modernization programs.
Mobile Communications absorbs the dominant procurement volume; Satellite Networks is gaining share fastest on constellation deployment acceleration.
End User:
Supply concentration among consolidated procurement consortia reshapes vendor qualification pathways.
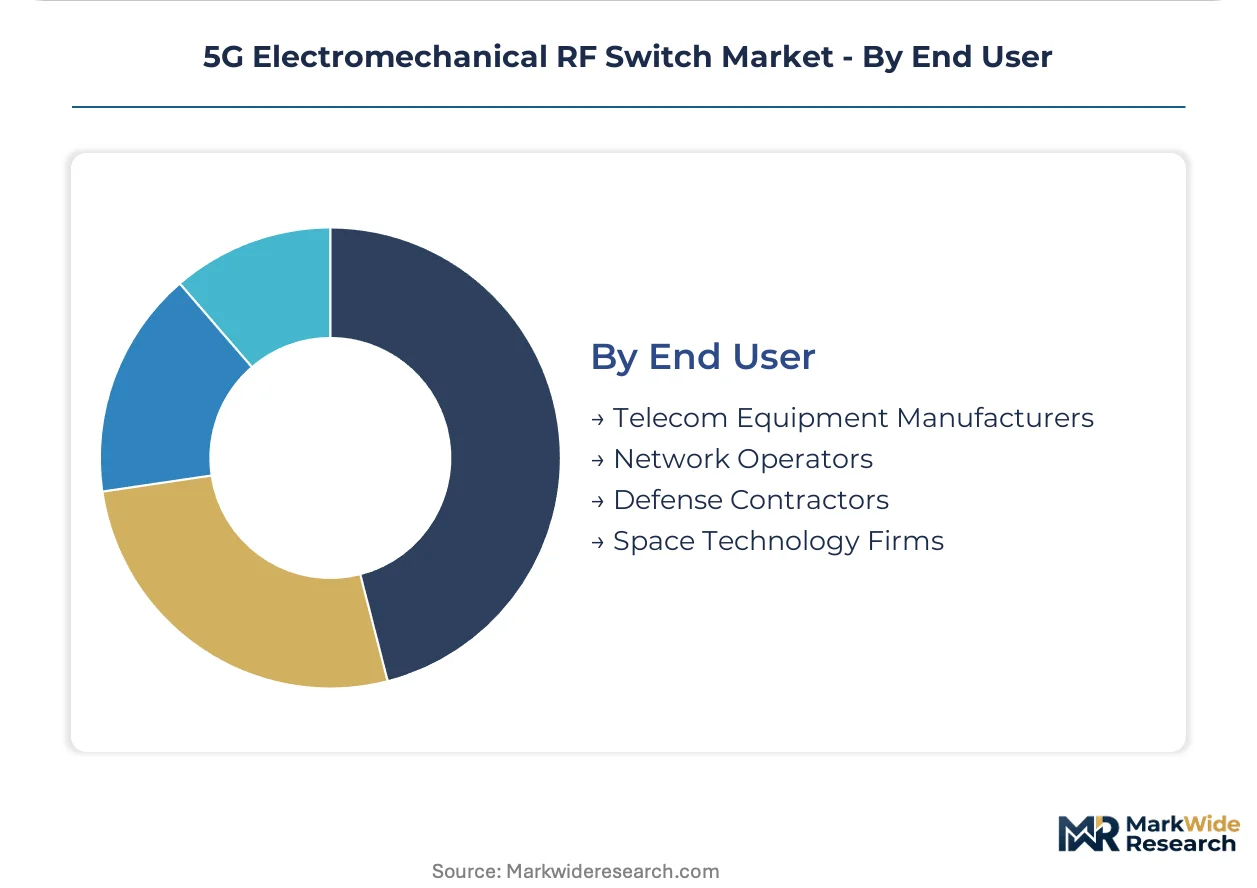
- Telecom Equipment Manufacturers:Nokia and Ericsson unified specification frameworks reduced qualified supplier pools from 40-plus vendors to 8-12 strategic partners. Finland and Sweden procurement headquarters leverage volume commitments for extended price lock provisions.
- Network Operators:South Korea and Japan operators mandate integrated position sensors for remote diagnostics in unmanned cell sites.
- Defense Contractors:National security screening protocols determine technology qualification for critical infrastructure procurement.
- Space Technology Firms:Low-earth orbit operators specify radiation-hardened switches for ground segment redundancy systems.
Telecom Equipment Manufacturers concentrate the largest procurement volumes; Network Operators are moving fastest on condition-based maintenance adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese electromechanical RF switch exports flow primarily to telecom equipment assembly hubs in Finland and Sweden, where Nokia and Ericsson consolidate component procurement for European and North American base station deployment.
United States
Verizon and AT&T base station densification programs drive procurement of high-reliability switching components for urban mmWave networks. FCC Part 15 electromagnetic compatibility testing cycles have lengthened substantially since spectrum reallocation rules expanded. Boston-area RF simulation talent clusters support defense contractors qualifying radiation-hardened switches for satellite-to-cell convergence applications.
China
MIIT-mandated 5G infrastructure timelines sustain volume procurement for macro cell redundancy architectures across three state-owned network operators. GB standards and MIIT certification regimes establish parallel compliance pathways that compress domestic product design cycles. Yangtze River Delta manufacturing corridors in Jiangsu and Zhejiang provinces concentrate electromechanical component assembly capacity serving both domestic and export demand.
Germany
Deutsche Telekom active antenna system deployments elevate thermal and isolation specifications for electromechanical switches in dense urban configurations. REACH substance restrictions and RoHS recast directives are phasing out cadmium-based contact plating by 2027, forcing nickel-palladium-gold migration programs. Bavaria's automotive-to-telecom supplier crossover clusters around Munich and Nuremberg are repurposing precision manufacturing capabilities for RF component production.
South Korea
SK Telecom and KT Corporation unmanned cell site architectures mandate integrated position sensors for remote diagnostics and condition-based maintenance schedules. MFDS-equivalent telecom equipment regulations align with international electromagnetic compatibility thresholds while maintaining domestic certification efficiency. Seoul Capital Area procurement headquarters leverage volume commitments for extended price lock provisions on high-reliability switching components.
India
Reliance Jio base station rollout acceleration creates procurement volume for cost-optimized switching configurations in small-cell installations. PLI scheme for telecom equipment manufacturing offers duty credits attracting contract manufacturers to establish assembly operations. Gujarat and Tamil Nadu industrial corridors are emerging as electromechanical component fabrication hubs serving both domestic deployment and re-export to Middle East markets.
5G Electromechanical RF Switch Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented vendor tiers. Nokia and Ericsson unified specification frameworks have reduced qualified supplier pools from 40-plus vendors to 8-12 strategic partners, consolidating procurement leverage among consolidated telecom equipment manufacturers. Three archetypes dominate: power semiconductor heritage players leveraging high-voltage switching portfolios, GaN-on-SiC process specialists extending thermal performance margins, and compact surface-mount designers occupying premium slots in small-cell configurations. Dominant competitive moves include strategic partnerships with active antenna system integrators and geographic expansion into India PLI-subsidized manufacturing corridors.
Within the power semiconductor heritage tier, Infineon Technologies AG anchors high-voltage switching portfolios for macro cell deployments. Qorvo occupies a position exemplifying GaN-on-SiC process integration specialists. Skyworks Solutions represents compact surface-mount designers targeting massive MIMO and small-cell configurations.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| Analog Devices |
| Qorvo |
| Skyworks Solutions |
| Broadcom |
| NXP Semiconductors |
| Murata Manufacturing Co. |
| Microchip Technology |
| TE Connectivity |
| Others |
Pricing and Supply Chain Analysis
Copper and silver-plated contact material concentration in Chinese and Chilean mining operations exposes switch manufacturers to simultaneous cost volatility and supply disruption risk, compressing margin tiers between relay-based ruggedized products and MEMS miniaturization alternatives while forcing procurement teams toward multi-source qualification programs.
Pricing Analysis
The technology-generation pricing gap separates mature relay-based architectures from emerging MEMS alternatives and next-generation GaN-on-SiC integrated solutions. Contract-based long-term offtake dominates procurement between consolidated telecom equipment manufacturers and qualified strategic partners, with price differentiation resting on certification tier—FCC Part 15 qualification for North American access versus MIIT GB standards compliance for Chinese domestic deployment—and volume scale commitments. Cost compression in standard-grade SPDT configurations is intensifying because India's PLI-subsidized contract manufacturers are absorbing margin pressure to secure qualification slots. Small-cell installers exhibit highest price sensitivity due to compressed capital budgets, while defense contractors tolerate premium positioning for radiation-hardened specifications.
Supply Chain Analysis
TE Connectivity and Foxconn EMS divisions hold dominant contract-manufacturing capacity for electromechanical RF switch assembly across the Yangtze River Delta and Tamil Nadu industrial corridors. Geographic supply concentration centers on China for precision-machined contact housings, Germany for nickel-palladium-gold plating chemistry, and Japan for ceramic actuator substrates. Raw material dependencies draw from high-purity copper cathodes, silver bullion for contact plating, and rare-earth elements for piezoelectric actuation mechanisms. Single-source vulnerability in Chinese rare-earth processing creates exposure to export restriction shocks. Distribution runs through direct OEM supply agreements with Nokia and Ericsson procurement headquarters, supplemented by authorized distributor networks serving tier-two telecom equipment manufacturers and defense contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open RAN disaggregation fragments procurement authority away from integrated equipment manufacturers, creating vendor qualification pathways for specialist switch suppliers previously locked out of tier-one supply chains.
For Market Incumbents: Build certification moats through accelerated FCC Part 15 and MIIT GB standards pre-qualification ahead of spectrum auction timelines. Defensive moves center on backward integration into high-purity contact material refining to offset Chilean copper concentrate volatility, and capacity addition in Gujarat PLI corridors to capture re-export demand to Middle East markets. MEMS substitution technology threatens relay-based margin pools in phased array applications. For New Entrants and Emerging Players: Satellite-to-cell convergence ground segment redundancy specifications represent the most penetrable entry point for defense-grade margin capture without legacy telecom qualification burdens. Secondary white-space targets include unmanned cell site architectures in South Korea and Japan requiring integrated position sensor telemetry. Go-to-market positioning as radiation-hardened specialists with commercial pricing discipline opens procurement pathways among low-earth orbit constellation operators. For Investors and Strategic Acquirers: REACH substance restriction deadlines reshapes the acquisition landscape by forcing nickel-palladium-gold migration capex commitments that strain undercapitalized component suppliers. Long-term viability across the projection horizon favors targets with completed RoHS recast compliance and established MIIT certification pathways. Acquisition target archetype: mid-cap relay-based specialists with defense qualification heritage and underutilized capacity in India PLI zones. Signal to watch: cadmium-based contact plating stockpiling activity preceding 2027 compliance deadlines as artificial demand spike indicator.| Strategic Initiative | Industry Significance |
|---|---|
| GaN-on-SiC Process Integration | Qorvo's thermal performance margins extend switch lifecycles in massive MIMO dense arrays. |
| India PLI Manufacturing Footprint | Gujarat and Tamil Nadu assembly corridors capture duty credits and Middle East re-export demand. |
| Active Antenna System Partnership | Infineon's high-voltage portfolios anchor macro cell procurement with integrated equipment manufacturers. |
| REACH Compliance Migration | Nickel-palladium-gold plating transition ahead of 2027 cadmium phase-out deadlines preserves market access. |
| Satellite Ground Segment Qualification | Radiation-hardened specifications open defense-grade margin pools to commercial switch suppliers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with RF component procurement directors at telecom equipment manufacturers, base station deployment engineers at network operators, and defense contractor qualification leads; and secondary validation through FCC equipment authorization databases, MIIT certification registries, and SEC filings from disclosed switch suppliers. Bottom-up triangulation aggregated component-level procurement volumes across SPDT, MPMT, and relay-based technology tiers, while top-down cross-checks referenced spectrum auction timelines and base station densification forecasts from national regulators.
Forecast inputs considered switch configuration adoption curves, thermal specification escalation in active antenna integrations, and regional procurement concentration among consolidated vendor pools. Segmentation dimensions modeled include product architecture, actuation technology, application tier, and end-user procurement authority across the analysis window. CAGRs derived from volume-weighted average price trajectories and unit shipment projections, with industry-specific adjustments for GaN-on-SiC process maturation timelines and Open RAN specification release cadence.
Macroeconomic conditions sit as an overlay; deviation in copper and silver commodity price bands, or rare-earth export restriction severity, would shift the trajectory for cost-sensitive small-cell tiers. Forecasts reflect documented assumptions regarding MIIT infrastructure mandate continuity and FCC certification cycle duration. Quarterly review of spectrum auction closure rates and REACH substance restriction enforcement intensity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.