
 Road Marking Paint Market | 2026-2036
Road Marking Paint Market Size, Share, and Industry Trends Forecast 2026-2036
Road Marking Paint Market Analytics
High-performance retroreflective specifications is unwinding legacy commodity supply chains across the road marking paint industry. PPG Industries leverages captive resin technology to control specification-grade formulation consistency. Sherwin-Williams Company anchors North American distribution through direct contractor channel partnerships. 3M differentiates on embedded glass-ceramic bead systems that exceed minimum retroreflectivity thresholds.
Road marking paint comprises pigmented binder systems—typically acrylic, alkyd, or hydrocarbon resins loaded with titanium dioxide and reflective microspheres—applied to bituminous or concrete substrates to delineate traffic lanes, pedestrian crossings, and hazard zones. Thermoplastic formulations dominate high-volume highway contracts due to superior wear resistance and embedded-glass-bead retention, while water-based acrylics capture parking lot and urban applications where VOC regulations restrict solvent content. Spray technology leads installation throughput on linear highway projects, though line layout systems command premium positioning on precision airfield markings where dimensional tolerance governs safety certification.
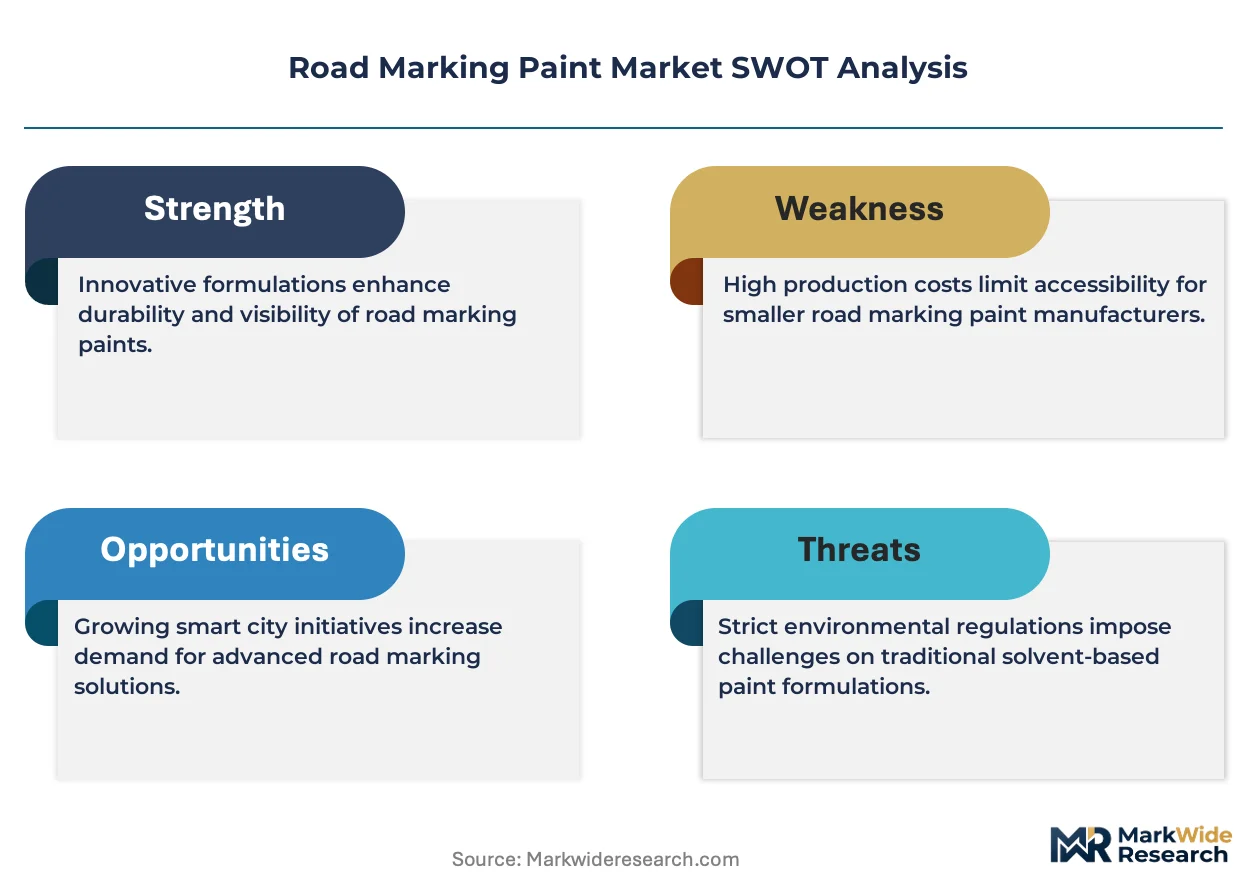
EU REACH restrictions on aromatic solvent content and US EPA VOC emissions standards for architectural and industrial maintenance coatings constrain formulation choices in developed markets, while China's MEE enforces parallel limits on hazardous air pollutants in provincial procurement tenders. India's BIS certification for retroreflective road studs and marking materials creates compliance gateways for imported specialty binders. Stakeholders must monitor divergence between emerging-market cost-driven procurement and specification-grade sustainability mandates as retrofit cycles accelerate on aging Western infrastructure.
Market Dynamics
Thermoplastic formulation technology is compressing commodity water-based segments as highway agencies specify embedded-glass-bead retention standards that only hot-applied systems reliably deliver. This technical specification cascade is redrawing competitive boundaries between resin suppliers and application contractors.
Growth Catalysts
- Retroreflectivity Mandates:NHTSA guidance on minimum pavement marking luminance is forcing state DOT rebidding cycles toward high-performance thermoplastics. Federal-aid highway funding eligibility now ties to measured performance thresholds.
- India National Highway Development:MoRTH's expressway buildout program generates contiguous lane-kilometer demand that favors tanker-delivered thermoplastic contracts over drum-packed alternatives. BIS certification requirements filter import competition.
- Dual Carbon Goals:China's MEE enforcement on solvent VOC limits redirects provincial procurement toward water-based acrylics in urban districts. Municipal tender documents now embed lifecycle carbon scoring.
Market Restraints
- Titanium Dioxide Volatility:Pigment feedstock concentration among Chinese sulfate-process producers exposes formulation costs to export duty fluctuations. Road marking paint margins compress when TiO2 spot prices spike.
- Application Equipment Concentration:Graco and Wirtgen Group dominate truck-mounted extrusion systems, creating vendor lock-in for highway contractors seeking OEM service networks. Equipment financing terms constrain smaller applicator entry.
- Alkyd Resin Substitution:Solventborne alkyd formulations face displacement by thermoplastics on durability grounds and by water-based systems on regulatory grounds. Alkyd capacity is idling across Western European resin plants.
Strategic Opportunities
- Airfield Precision Segment:FAA-certified grooved runway markings command specification premiums due to dimensional tolerance requirements. Line layout system integration with GPS-guided applicators creates contractor differentiation.
- EU Green Deal Procurement:CSRD-aligned public buyers are piloting environmental product declarations for road marking materials. Early EPD registry entrants capture tender preference scoring in German and Dutch highway maintenance.
- Glass-Bead Recycling Loops:Post-consumer reflective microsphere recovery from mill-and-overlay projects enables circular material claims. Closed-loop supply contracts appeal to sustainability-specified municipal buyers.
Industry Challenges
- Thermoplastic Applicator Certification:Proper bead embedment depth and temperature control require trained crews; skill scarcity limits contractor expansion speed. Union apprenticeship pipelines have not scaled to project velocity.
- Cross-Formulation Inventory Complexity:Stocking water-based, solvent-based, and thermoplastic SKUs with distinct resin systems strains distributor working capital. Seasonal demand spikes exacerbate obsolescence risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Road Marking Paint Market |
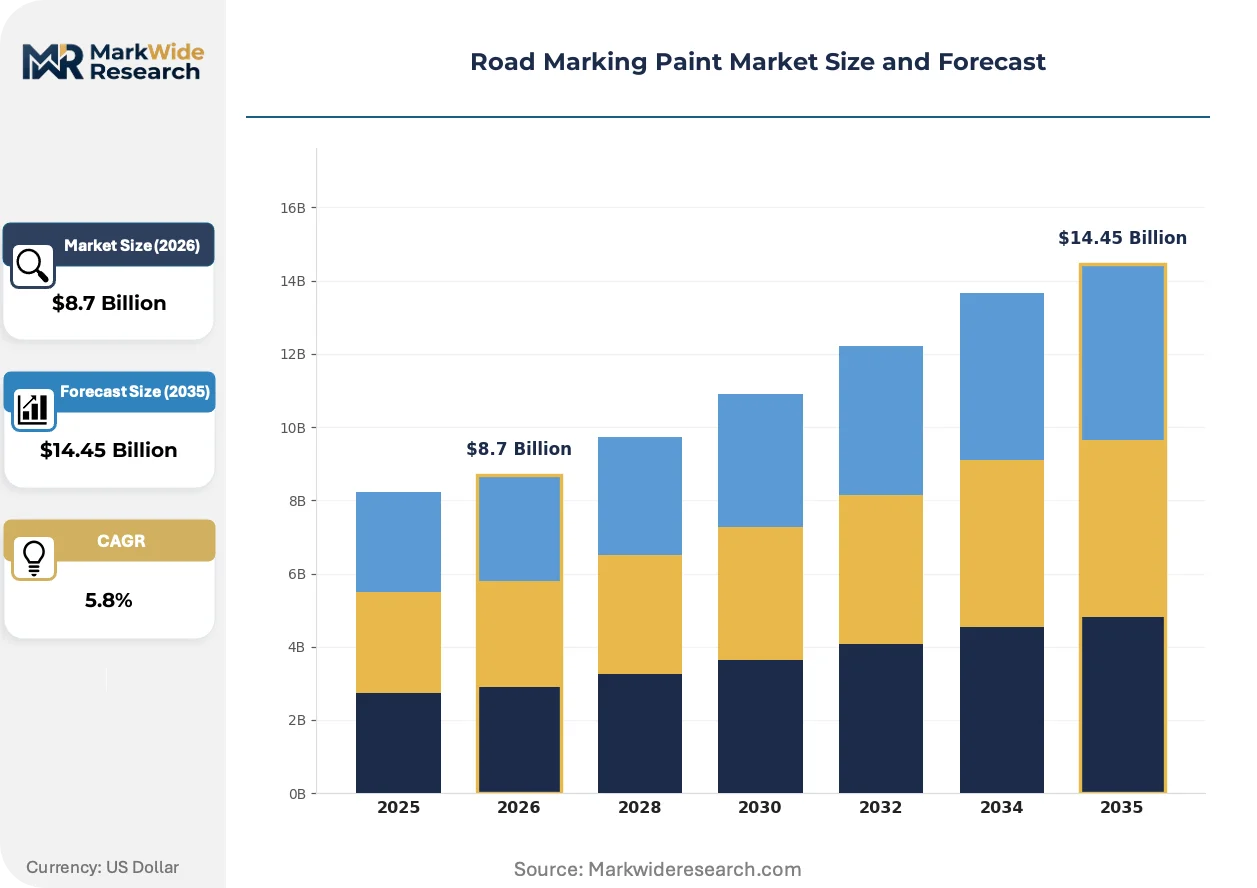
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastic, Water-Based, Solvent-Based, Vinyl Application: Highways, Parking Lots, Airports, Sports Tracks End User: Government, Contractors, Private Developers, Transportation Authorities Technology: Spray, Roller, Line Layout, Stencil |
| Companies Covered | SWARCO, PPG Industries, Sherwin-Williams Company, Asian Paints, Hempel, 3M, Ennis-Flint, Evonik Industries, Geveko Markings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Road Marking Paint Market Evolving Landscape
Specification-grade performance thresholds are fragmenting the supply base into technology-tiered competitive sets. Formulation chemistry, application equipment, and measurement protocols are evolving in lockstep.
Glass-ceramic bead technology is bifurcating the reflective materials segment. These higher-refractive-index microspheres deliver superior nighttime visibility under wet conditions. State DOTs in Michigan and Pennsylvania are specifying them for high-crash corridor treatments. The technology is bifurcating procurement into premium-specification and minimum-compliance supply tiers.
EU REACH Annex XVII restrictions on aromatic solvent content are eliminating naphtha-based formulations from cross-border tender eligibility. German KBA type-approval processes now require full substance disclosure for imported marking materials. Water-based acrylic suppliers with pre-registered REACH dossiers are capturing maintenance contract share from solventborne incumbents.
Performance-based contracting is displacing unit-price procurement for highway marking renewals. State agencies in Virginia and Ohio now pay contractors on measured retroreflectivity retention over 24-36 month periods. This payment model favors applicators with in-house formulation control and captive bead supply relationships.
Road Marking Paint Market Segmentation
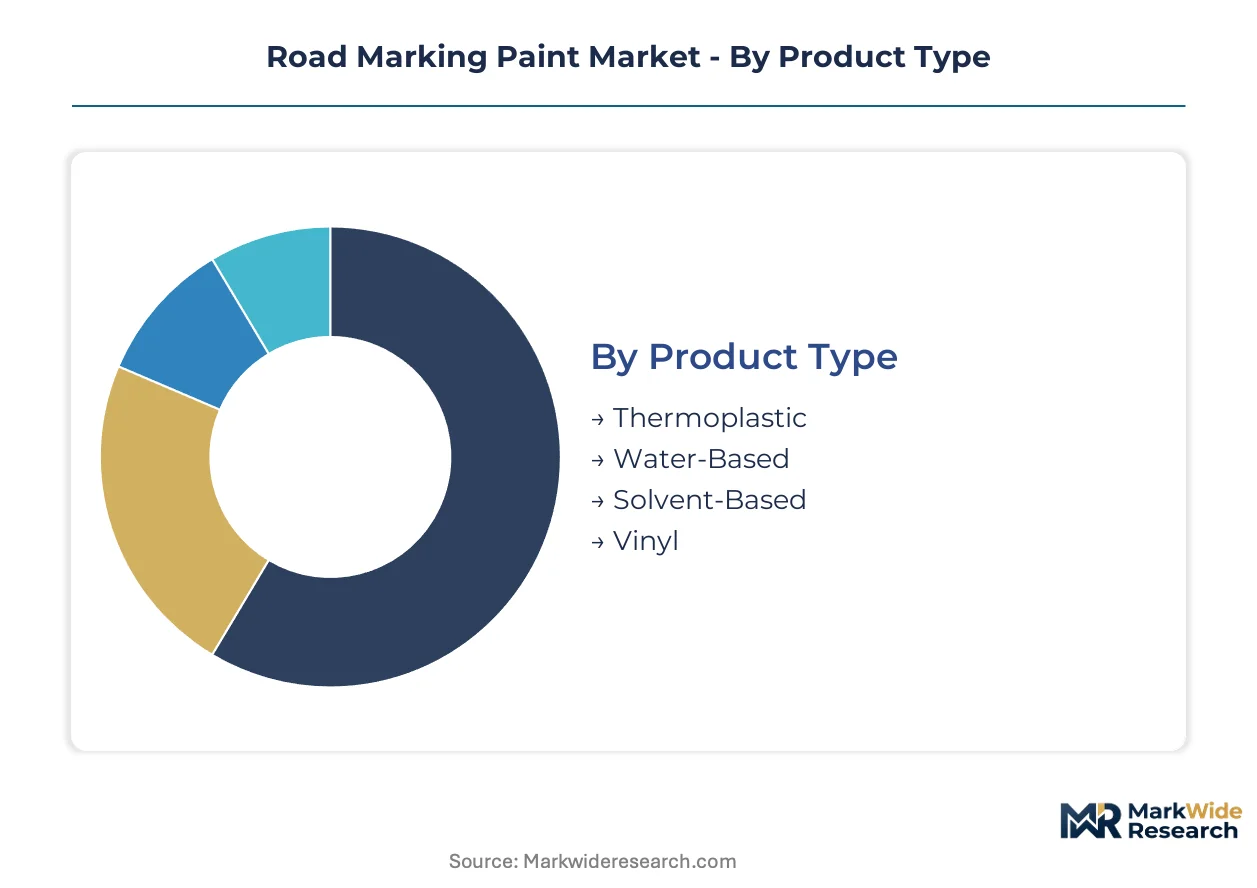
Road marking paint procurement fragments across formulation chemistry, installation method, and contracting authority. Specification-grade performance tiers now command premium positioning as highway agencies embed retroreflectivity retention into payment terms.
Product Type:
Margins concentrate in thermoplastic formulations where embedded-glass-bead retention creates specification lock-in for highway contracts.
- Thermoplastic:Hot-applied hydrocarbon or alkyd resin systems with superior wear resistance and bead embedment depth control. MoRTH's expressway buildout in India generates contiguous lane-kilometer demand favoring tanker-delivered contracts over drum-packed alternatives.
- Water-Based:Acrylic emulsion formulations capturing urban parking and municipal street applications where EU REACH and US EPA VOC limits restrict solvent content. China's MEE enforcement redirects provincial procurement toward these systems in municipal districts with lifecycle carbon scoring.
- Solvent-Based:Alkyd and chlorinated rubber systems facing displacement on dual regulatory and durability fronts. Western European resin capacity is idling as thermoplastics capture highway share.
- Vinyl:Preformed tape and sheet systems for temporary markings and precision airfield applications requiring dimensional tolerance certification.
Thermoplastic holds installed capacity. Water-based is rotating up the share rankings.
Application:
Volume concentrates in linear highway contracts where payment models are shifting toward measured retroreflectivity retention over multi-year periods.
- Highways:Federal-aid pavement marking programs across the United States, Germany, and India specify minimum luminance thresholds. NHTSA guidance forces state DOT rebidding cycles toward high-performance thermoplastics with measured performance certification.
- Parking Lots:Water-based acrylics dominate commercial and retail surface applications where seasonal re-striping cycles and VOC compliance drive formulation selection. Municipal tender documents in Chinese urban districts now embed lifecycle carbon scoring.
- Airports:FAA-certified grooved runway markings command specification premiums due to dimensional tolerance requirements. Line layout system integration with GPS-guided applicators creates contractor differentiation in this precision segment.
- Sports Tracks:Polyurethane and acrylic systems for athletic surface delineation with specialized friction and color-fastness requirements.
Highways hold installed capacity. Airports is rotating up the share rankings.
End User:
Procurement authority shapes specification stringency and contract scale more than formulation chemistry alone.
- Government:State DOTs and federal highway agencies with performance-based contracting models displacing unit-price procurement. Virginia and Ohio now pay on measured retroreflectivity retention over 24-36 month periods.
- Contractors:Highway application specialists with in-house formulation control and captive bead supply relationships capturing performance-based contract share.
- Private Developers:Commercial parking and industrial site owners prioritizing first-cost over lifecycle performance in non-regulated applications.
- Transportation Authorities:Transit agencies and port authorities with specialized marking requirements for bus lanes, rail crossings, and container terminal traffic control.
Government holds installed capacity. Contractors is rotating up the share rankings.
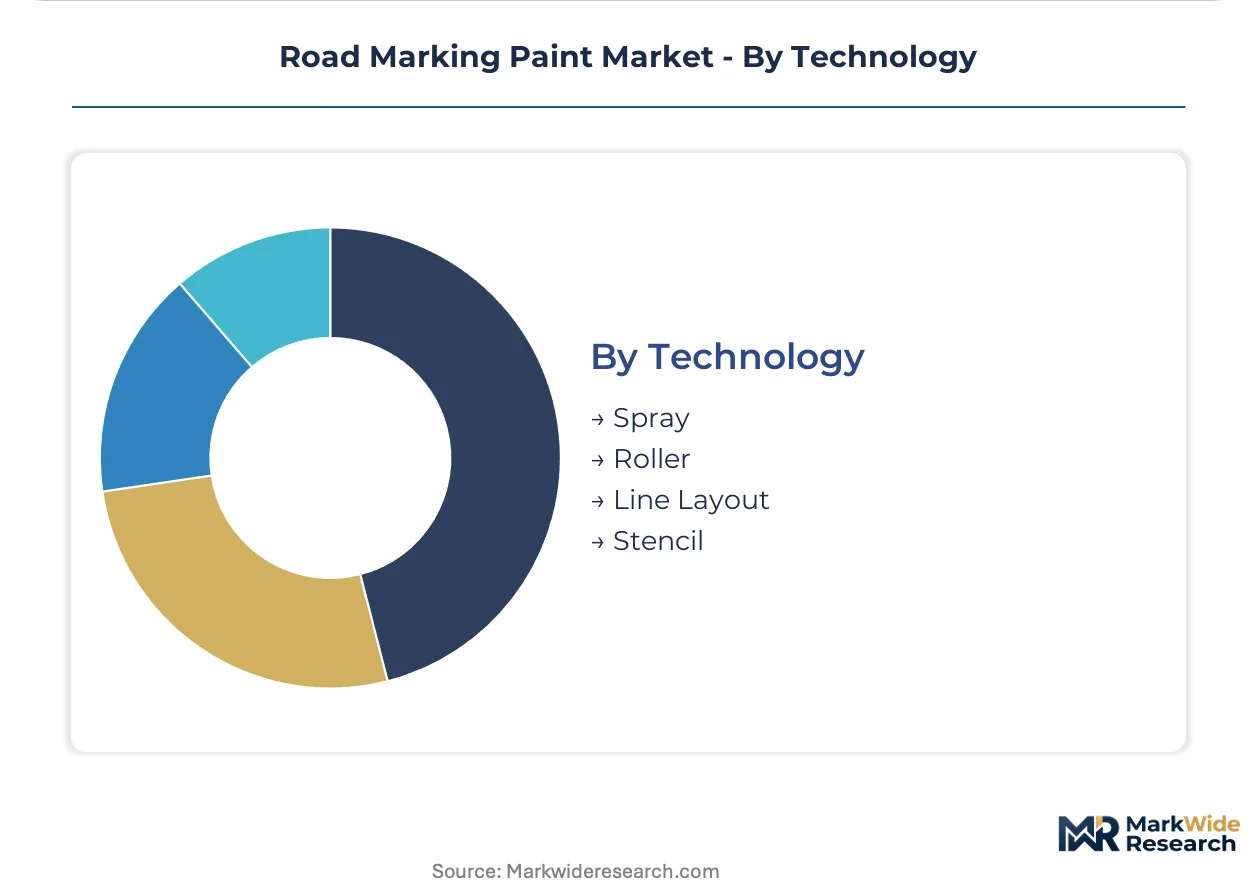
Technology:
Equipment concentration among Graco and Wirtgen Group creates vendor lock-in shaping contractor competitive positioning.
- Spray:Truck-mounted airless systems delivering highest throughput on linear highway projects. Application speed governs contract economics on contiguous lane-kilometer awards.
- Roller:Manual and walk-behind systems for parking lots, warehouse floors, and confined access areas where precision outweighs speed.
- Line Layout:GPS-guided and laser-controlled systems commanding premium positioning on airfield markings where dimensional tolerance governs FAA safety certification.
- Stencil:Template-based application for symbols, legends, and specialized markings requiring repeatability across multiple locations.
Spray holds installed capacity. Line layout is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemistry capabilities cluster in industrial corridors with captive resin supply and highway agency proximity. Thermoplastic production concentrates near major petrochemical hubs, while water-based acrylic capacity distributes closer to urban regulatory enforcement zones.
United States
Federal-aid highway funding eligibility now ties to NHTSA retroreflectivity thresholds, forcing state DOT rebidding cycles toward high-performance thermoplastics. Virginia and Ohio pioneered performance-based contracting models that pay on measured luminance retention over 24-36 month periods. The Gulf Coast petrochemical corridor anchors thermoplastic resin supply for tanker-delivered highway contracts.
Germany
KBA type-approval processes require full substance disclosure for imported marking materials, filtering non-compliant suppliers from cross-border tenders. The country's national highway regulator enforces EU REACH Annex XVII aromatic solvent restrictions that eliminate naphtha-based formulations. The Rhine-Ruhr industrial basin hosts water-based acrylic production facilities serving Dutch and Belgian maintenance contracts.
China
Provincial expressway buildouts in Sichuan and Yunnan generate contiguous lane-kilometer demand favoring tanker-delivered thermoplastic systems. MEE enforcement on solvent VOC limits redirects municipal procurement toward water-based acrylics in urban districts with lifecycle carbon scoring. The Yangtze River Delta concentrates reflective glass bead manufacturing for domestic highway contractors.
India
MoRTH's expressway buildout program generates demand patterns that favor bulk thermoplastic contracts over drum-packed alternatives. BIS certification for retroreflective road studs and marking materials creates compliance gateways for imported specialty binders. The Delhi-Mumbai Industrial Corridor anchors application contractor consolidation as performance specifications tighten.
United Arab Emirates
Municipal tenders for Dubai and Abu Dhabi road networks embed durability specifications that exceed minimum compliance thresholds common in other Gulf markets. The country's national standards body aligns procurement with evolving sustainability criteria for desert climate performance. Jebel Ali industrial zone hosts formulation facilities serving re-export demand across the broader Middle East region.
Road Marking Paint Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the road marking paint industry. Specification-grade thermoplastic formulation requires captive resin technology and embedded-glass-bead supply relationships that commodity water-based producers cannot replicate. The competitive structure separates into three strategic archetypes: integrated chemical conglomerates with backward resin control, specialized highway application contractors with in-house formulation, and regional distributors stocking multi-formulation portfolios. Dominant competitive moves include M&A to secure bead supply relationships and geographic expansion to capture performance-based highway maintenance contracts.
Within the integrated chemical tier, PPG Industries and Sherwin-Williams Company exemplify archetypes with captive technology control, while 3M occupies a position anchoring premium reflective materials specialization. These three players represent distinct competitive vectors: resin-integrated formulation consistency, North American distribution scale, and glass-ceramic bead system differentiation respectively.
| Leading Market Players |
|---|
| SWARCO |
| PPG Industries |
| Sherwin-Williams Company |
| Asian Paints |
| Hempel |
| 3M |
| Ennis-Flint |
| Evonik Industries |
| Geveko Markings |
| Others |
Value Network & Pricing Analysis
BIS certification requirements for retroreflective road studs and marking materials gate both supply qualification and price differentiation simultaneously, filtering import competition while creating tiered procurement access for domestic versus foreign formulation suppliers.
Pricing Analysis
EU REACH Annex XVII dictates the pricing tier structure across the road marking paint industry, eliminating naphtha-based solventborne formulations from cross-border tender eligibility while elevating water-based acrylic premiums. Pricing stratifies across specification-grade thermoplastics, certified water-based systems, and displaced solventborne commodities. Cost compression in commodity alkyd segments is intensifying because Western European resin capacity idles under dual regulatory and durability pressures. State DOTs and municipal buyers exhibit the sharpest price sensitivity in parking lot and urban maintenance contracts, while federal highway agencies prioritize measured retroreflectivity retention over first-cost in performance-based awards.
Supply Chain Analysis
Titanium dioxide sulfate-process concentration in China underwrites pigment cost volatility across global formulation networks. Thermoplastic resin production draws from Gulf Coast petrochemical corridors in the United States, Rhine-Ruhr industrial basins in Germany, and Yangtze River Delta manufacturing clusters. Raw material dependencies center on hydrocarbon resins, reflective glass microspheres, and TiO2 feedstocks. Single-source vulnerability concentrates in glass-ceramic bead supply relationships controlled by specialized reflective materials producers. Distribution runs through direct contractor channel partnerships for highway volume and regional distributor networks for municipal maintenance spot demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retroreflectivity mandates are accelerating specification-grade displacement of commodity formulations, creating high-growth disruption as performance-based contracting rewrites procurement economics across federal-aid highway programs.
For Market Incumbents: Compound formulation control advantages through captive resin technology and embedded-glass-bead supply relationships that performance-based contracts reward. Defend against water-based acrylic encroachment by accelerating thermoplastic durability certification in EU Green Deal procurement pilots. Prioritize capacity positioning near India's Delhi-Mumbai Industrial Corridor to capture MoRTH expressway buildout velocity. For New Entrants and Emerging Players: BIS certification fast-track programs offer the most penetrable gateway for imported specialty binder suppliers targeting India's National Highway Development project pipeline. Target airfield precision segments where FAA-certified grooved runway markings command specification premiums beyond commodity highway competition. Pursue GPS-guided line layout system integration as a differentiated go-to-market angle against established spray contractors. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed highway application contractors holding performance-based contract backlogs in Virginia and Ohio. Five-to-ten year viability hinges on embedded-glass-bead supply security and in-house formulation capabilities rather than distributor scale. Watch for thermoplastic applicator certification bottlenecks as an inflection signal for contractor consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive hydrocarbon resin supply secures specification-grade formulation consistency for PPG Industries and Sherwin-Williams. |
| Glass-Ceramic Bead Supply Agreement | 3M's embedded glass-ceramic systems exceed minimum retroreflectivity thresholds required by Michigan and Pennsylvania DOTs. |
| Performance-Based Contracting Expansion | Virginia and Ohio payment models reward measured luminance retention over 24-36 month periods. |
| EU Green Deal EPD Registry Entry | Environmental product declaration pilots in Germany and Dutch highway maintenance create tender preference scoring. |
| Airfield Precision Certification Investment | FAA-certified grooved runway markings command dimensional tolerance premiums beyond linear highway contracts. |
Research Methodology
Cross-validation between primary interviews with highway agency procurement officers, thermoplastic application contractors, resin plant managers, and reflective materials specialists anchors the qualitative findings against secondary validation. Regulatory filings from NHTSA, ECHA REACH dossiers, and MoRTH tender documents complement customs trade data and SEC 10-K disclosures from listed chemical conglomerates. Bottom-up lane-kilometer demand modeling and top-down formulation chemistry value triangulation converge on segment-level outputs.
Sensitivity analysis around TiO2 spot price volatility, bead embedment depth certification failure rates, and performance-based contract renewal probabilities shapes the analytical framework across the projection horizon. Segmentation dimensions include formulation chemistry, installation method, contracting authority, and regional regulatory cluster. CAGRs derive from historical lane-kilometer award patterns, retrofit cycle acceleration in aging Western infrastructure, and provincial expressway buildout trajectories in China and India.
Underlying assumptions cover NHTSA retroreflectivity guidance enforcement continuity, EU REACH aromatic solvent restriction expansion, and BIS certification gateway maintenance, with deviation risk concentrated in titanium dioxide export duty fluctuations and thermoplastic applicator skill scarcity limiting contractor expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Hybrid Paint Cans Market
Paints & Coatings
Germany Industrial Wood Coatings Market
Paints & Coatings
Low VOC Paint Market
Paints & Coatings
Asia-Pacific Paints and Coatings Additives Market
Paints & Coatings
Paint Buckets Market
Paints & Coatings
Cement Paints Market
Paints & Coatings
Automotive Paints and Coatings Market
Paints & Coatings
UAE Architectural Paints and Coatings Market
Paints & Coatings
Resins in Paints and Coatings Market
Paints & Coatings
Solar Paint Market
Paints & Coatings
Europe Paints and Coatings Market
Paints & Coatings
Global Construction Paints and Coatings Market
Paints & Coatings
Small Paint Pail Market
Paints & Coatings
Canvas Primer Market
Paints & Coatings
Polyurethane Resins Paints and Coatings Market
Paints & Coatings
Anti-Fungal and Anti-Bacterial Paints Market