
 Saudi Arabia Paints and Coatings Market | 2026-2036
Saudi Arabia Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Paints and Coatings Market Analytics
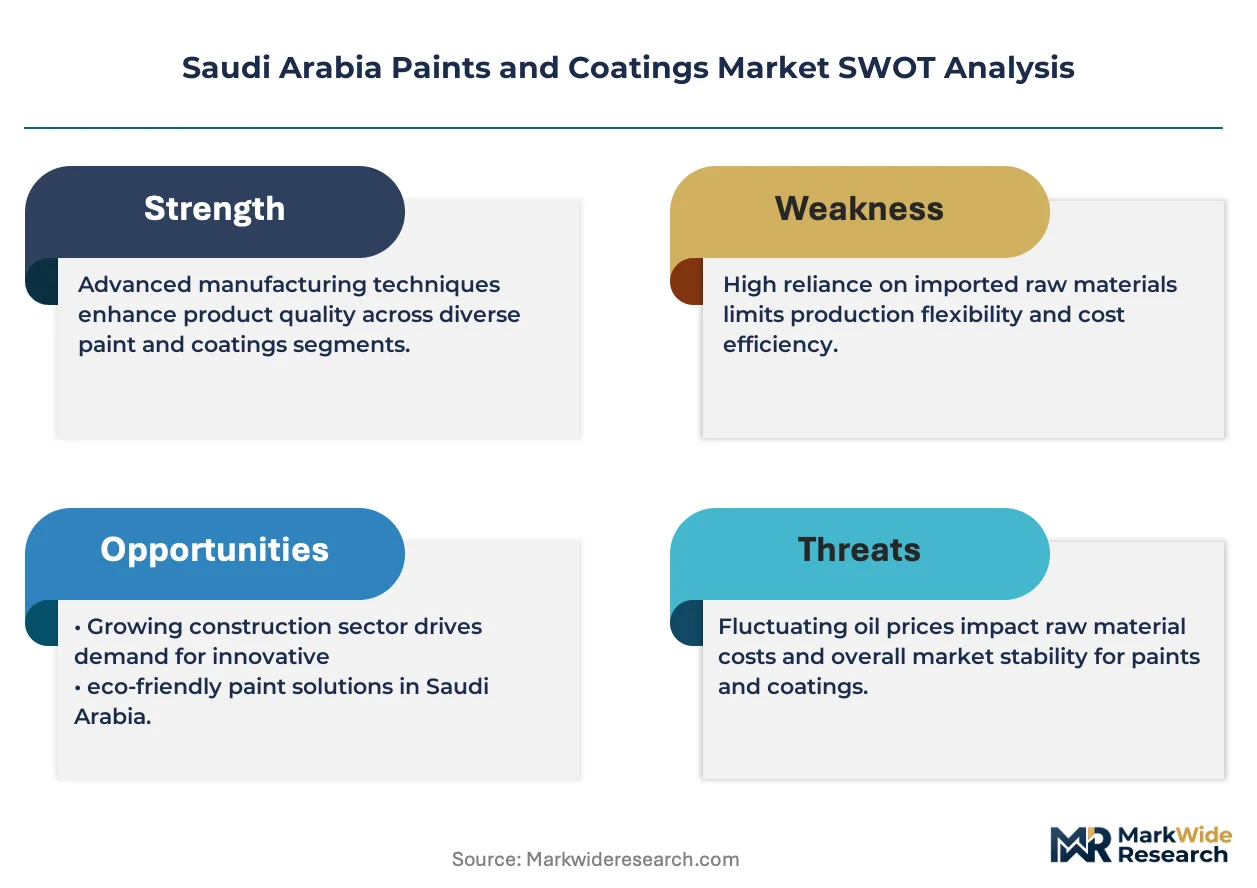
SFDA's tightening chemical safety protocols is repositioning the cost-of-entry calculus for new coatings suppliers. Jotun leverages its marine-grade expertise to dominate industrial protective segments across Jubail's petrochemical cluster. Akzo Nobel N.V. anchors its position through backward integration into specialty resins, insulating margin pools from raw material volatility. National Paints Factories Co. Ltd. competes on distribution density, sustaining channel control through direct sales networks in secondary cities.
Paints and coatings constitute formulated liquid, powder, or UV-curable systems comprising binders, pigments, solvents, and additives, applied to substrates for protection, decoration, or functional performance; waterborne acrylic-alkyd hybrids achieve VOC levels below 50 g/L while maintaining gloss retention in desert climates. Architectural coatings command the largest value share, reflecting sustained residential and commercial construction flows tied to giga-project pipelines. Industrial applications represent the fastest-expanding margin pool, driven by automotive assembly investments and aerospace MRO demand at King Abdulaziz International Airport's maintenance cluster. Powder coating technology gains share in metal fabrication, displacing solventborne alternatives under pressure from MEE-aligned environmental audits.
SFDA and SASO enforce progressive VOC ceilings and chemical registration requirements that filter out low-compliance imports, while MEE coordinates industrial emissions oversight affecting coating plant siting decisions. The Saudi Building Code's fire-resistance specifications for high-rise structures create differentiated demand for intumescent and specialty protective systems. Stakeholders must monitor how giga-project procurement consolidation reshapes distributor economics and whether local resin capacity investments alter import dependency structures.
Market Dynamics
Vision 2030 giga-projects are compressing procurement timelines and consolidating buyer power across Saudi Arabia's construction sector, forcing coatings suppliers to restructure distribution networks around direct-to-contractor channels and on-site technical service capabilities.
Growth Catalysts
- SFDA VOC Compliance Mandates:Tightening chemical safety protocols under SASO's updated standards are filtering out low-compliance imports and creating protected market space for certified domestic producers.
- Jubail Petrochemical Cluster Expansion:Industrial protective coatings demand is accelerating around Saudi Aramco's downstream integration investments and specialty chemical plant construction.
- Waterborne Acrylic-Alkyd Hybrids:Desert-climate formulation advances are enabling architectural coatings to achieve sub-50 g/L VOC levels without sacrificing gloss retention or durability performance.
Market Restraints
- Titanium Dioxide Import Dependency:Pigment supply concentrates in Chinese and Ukrainian production, exposing Saudi formulators to raw material volatility and currency fluctuation risks.
- Specialty Resin Capacity Gap:Local production of epoxy and polyurethane intermediates remains underdeveloped, forcing reliance on European and Asian resin suppliers with extended lead times.
- Desert Climate Performance Thresholds:Extreme thermal cycling and UV exposure create accelerated degradation patterns that exceed standard formulation lifecycles, demanding costly R&D adaptation.
Strategic Opportunities
- Asir Region Infrastructure Gap:Secondary city construction outside Riyadh-Jeddah corridors offers first-mover positioning for distributors establishing direct sales networks in Abha and surrounding mountain developments.
- Powder Coating Metal Fabrication:MEE-aligned environmental audits are accelerating solventborne displacement in industrial metal finishing, creating technology conversion contracts.
- Intumescent Fire-Resistance Systems:Saudi Building Code specifications for high-rise structures are generating differentiated demand for specialty protective coatings in commercial tower construction.
Industry Challenges
- Formulation Chemist Talent Scarcity:Waterborne technology transitions require specialized expertise in acrylic-alkyd hybrid chemistry that outpaces local technical education pipeline output.
- Giga-Project Certification Timelines:SFDA and SASO registration protocols for new chemical entities extend product approval cycles, compressing window for specification capture.
- Legacy Solventborne Equipment Stranding:Existing spray application infrastructure in secondary market fabricators requires capital-intensive conversion to support low-VOC formulation delivery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Paints and Coatings Market |
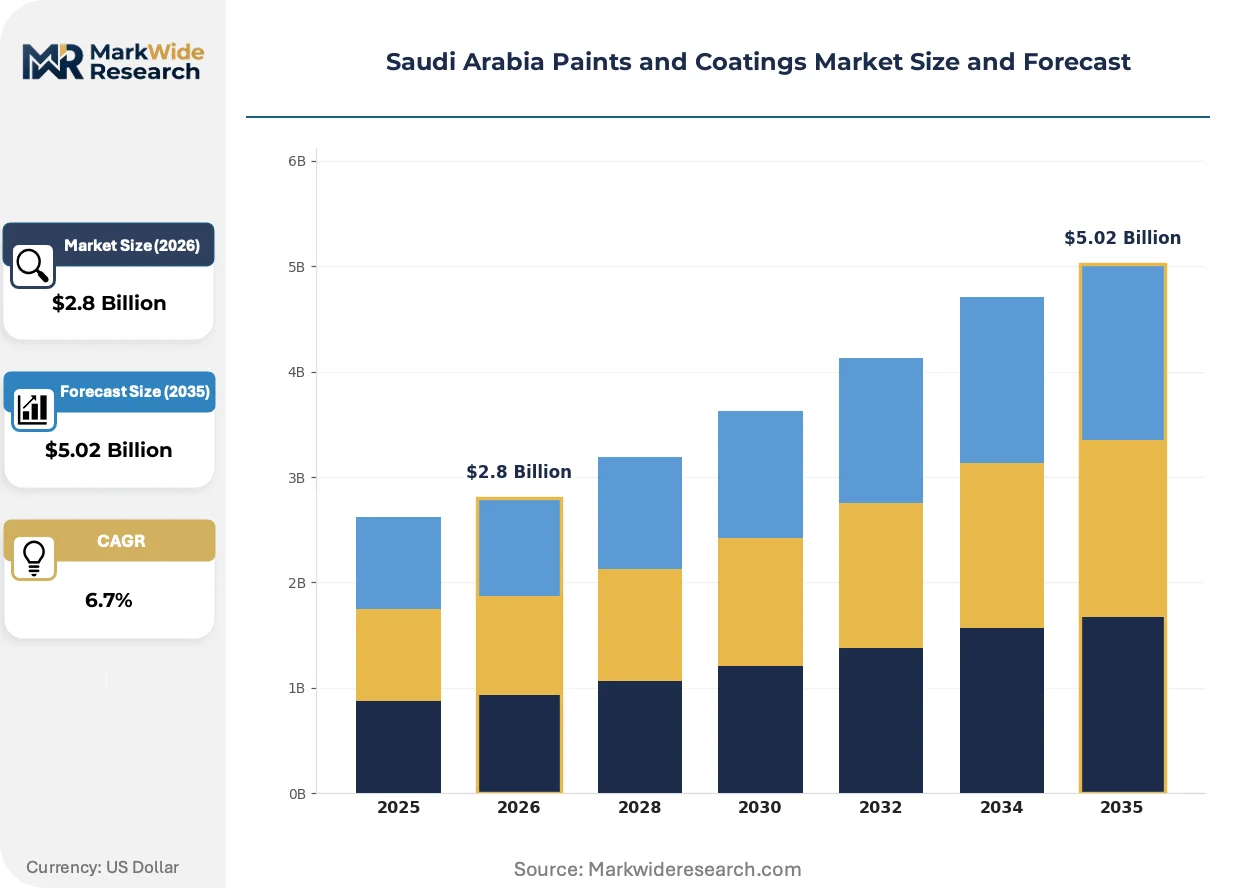
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Architectural, Industrial, Protective, Specialty Application: Construction, Automotive, Furniture, Aerospace Technology: Waterborne, Solventborne, Powder Coating, UV Coating Distribution Channel: Direct Sales, Distributors, Retail, E-commerce |
| Companies Covered | Jotun, Akzo Nobel N.V., Hempel A/S, Jazeera Paints, National Paints Factories Co. Ltd., Sigma Paints, Kansai Paint Co. Ltd., Axalta Coating Systems, Caparol Paints, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Paints and Coatings Market Evolving Landscape
Formulation chemistry and application technology are converging around climate-adapted performance requirements, with regulatory pressure and procurement consolidation acting as simultaneous accelerants across both architectural and industrial segments.
Waterborne acrylic-alkyd hybrid technology is converging with nano-pigment dispersion systems to deliver VOC-compliant architectural coatings that maintain color stability through Riyadh's extreme thermal cycling. Major giga-project contractors are specifying these formulations in master procurement agreements, compressing specification windows for traditional solventborne suppliers and rewarding technical service capabilities.
SASO's progressive VOC ceiling enforcement is eliminating import pathways for non-compliant coatings while creating protected domestic market space for certified producers. The regulatory friction most acutely affects decorative architectural segments, where price-competitive Asian imports previously dominated, and is forcing distributor restructuring around technical compliance documentation.
Buyer concentration around NEOM and Red Sea Project procurement offices is consolidating specification authority and compressing distributor margins. Direct-to-contractor technical sales models are displacing traditional stockist networks in Jeddah and Riyadh, with giga-project procurement teams demanding embedded formulation laboratories and on-site color matching capabilities rather than standard product catalogs.
Saudi Arabia Paints and Coatings Market Segmentation
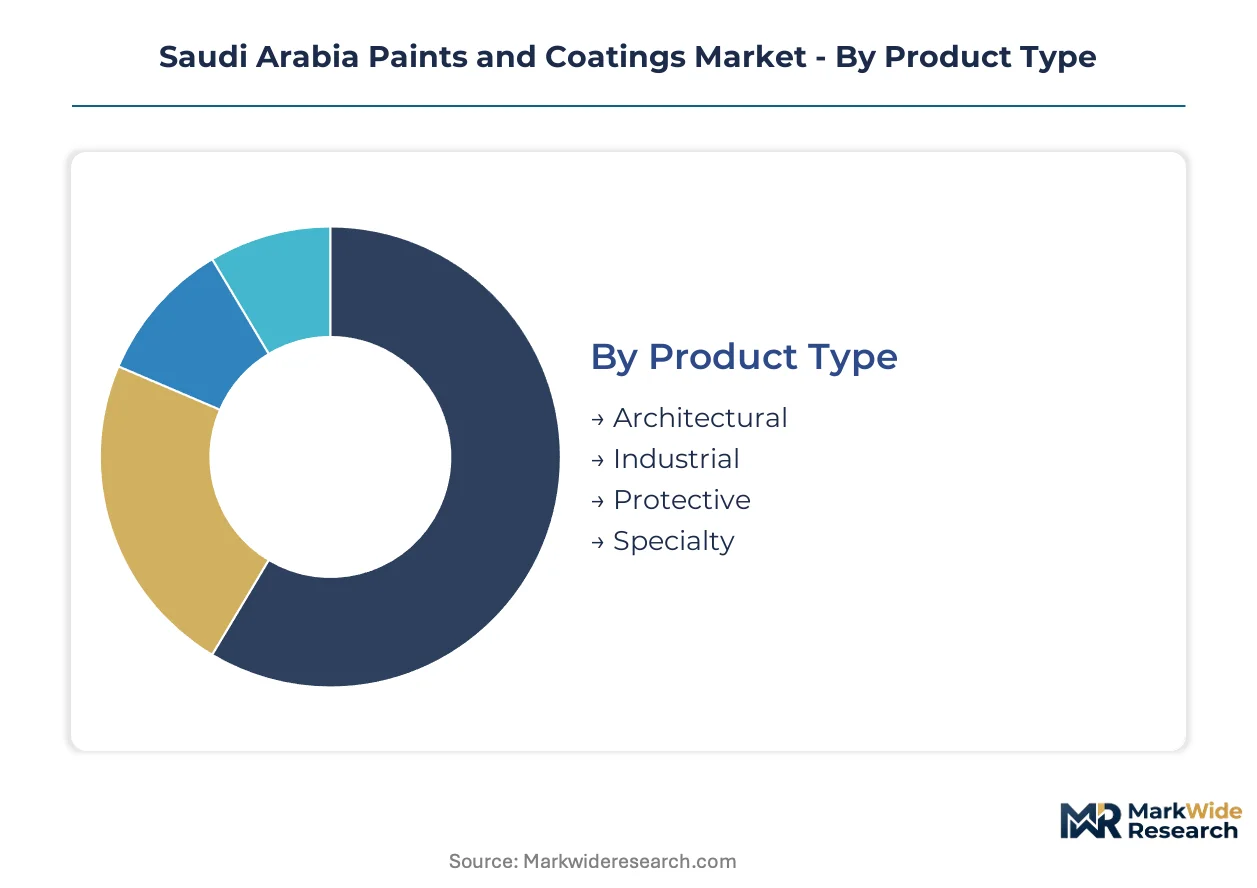
Segmentation in Saudi Arabia's paints and coatings market reveals how Vision 2030 megaprojects are reshaping procurement patterns across formulation types and delivery channels. Understanding these splits enables suppliers to align R&D investment and distribution restructuring with where buyer power is concentrating.
Product Type:
Architectural coatings dominate volume flows, while industrial and protective systems command premium pricing through specialized performance requirements.
- Architectural:Waterborne acrylic-alkyd hybrids formulated for desert UV exposure and thermal cycling anchor residential and commercial construction specifications. Demand concentrates in Riyadh's giga-project corridor where NEOM and Red Sea Project procurement offices mandate sub-50 g/L VOC compliance in master agreements.
- Industrial:Epoxy and polyurethane systems serve automotive assembly plants and metal fabrication facilities. Jubail's petrochemical cluster expansion is accelerating procurement of chemical-resistant tank linings and pipeline coatings with extended service lifecycles.
- Protective:Marine-grade and offshore platforms coatings for Saudi Aramco downstream assets.
- Specialty:Intumescent fire-resistance systems for Saudi Building Code high-rise compliance.
Mature deployment sits with Architectural coatings across established Riyadh-Jeddah construction. Newer deployment is concentrated in Protective systems around Jubail's expanding industrial base.
Application:
Construction absorbs the majority of formulation volumes, though automotive and aerospace applications are climbing the fastest as manufacturing investments deepen.
- Construction:Interior and exterior wall coatings, wood finishes, and concrete protection systems specified in giga-project master procurement agreements. Direct-to-contractor technical sales models are displacing traditional distributor networks as buyer power consolidates around NEOM and Red Sea Project procurement offices.
- Automotive:OEM assembly line coatings and refinish systems for expanding domestic vehicle production. King Abdullah Economic City's automotive cluster investments are generating specification demand for high-gloss clearcoats and electrodeposition primers with desert climate durability.
- Furniture:Wood coatings and decorative finishes for residential and commercial fit-out.
- Aerospace:MRO coatings and specialty primers for King Abdulaziz International Airport's maintenance operations.
Construction maintains the deepest specification entrenchment. Aerospace is gaining share fastest through airport expansion and maintenance cluster development.
Technology:
Waterborne formulations are displacing solventborne systems under SASO VOC enforcement, while powder coating gains industrial metal fabrication share.
- Waterborne:Acrylic, alkyd, and hybrid emulsion systems achieving regulatory compliance without sacrificing gloss retention. SASO's progressive VOC ceiling enforcement is eliminating import pathways for non-compliant alternatives while creating protected domestic market space for certified producers.
- Solventborne:High-performance industrial coatings in legacy applications requiring extended conversion timelines.
- Powder Coating:Thermoset epoxy and polyester systems for metal fabrication with zero VOC emissions. MEE-aligned environmental audits are accelerating solventborne displacement in Jubail industrial facilities and secondary city fabricators.
- UV Coating:Rapid-cure systems for furniture and specialty wood applications with limited local adoption.
Waterborne technology anchors new specification capture. Powder coating represents the steepest expansion trajectory as environmental audits intensify.
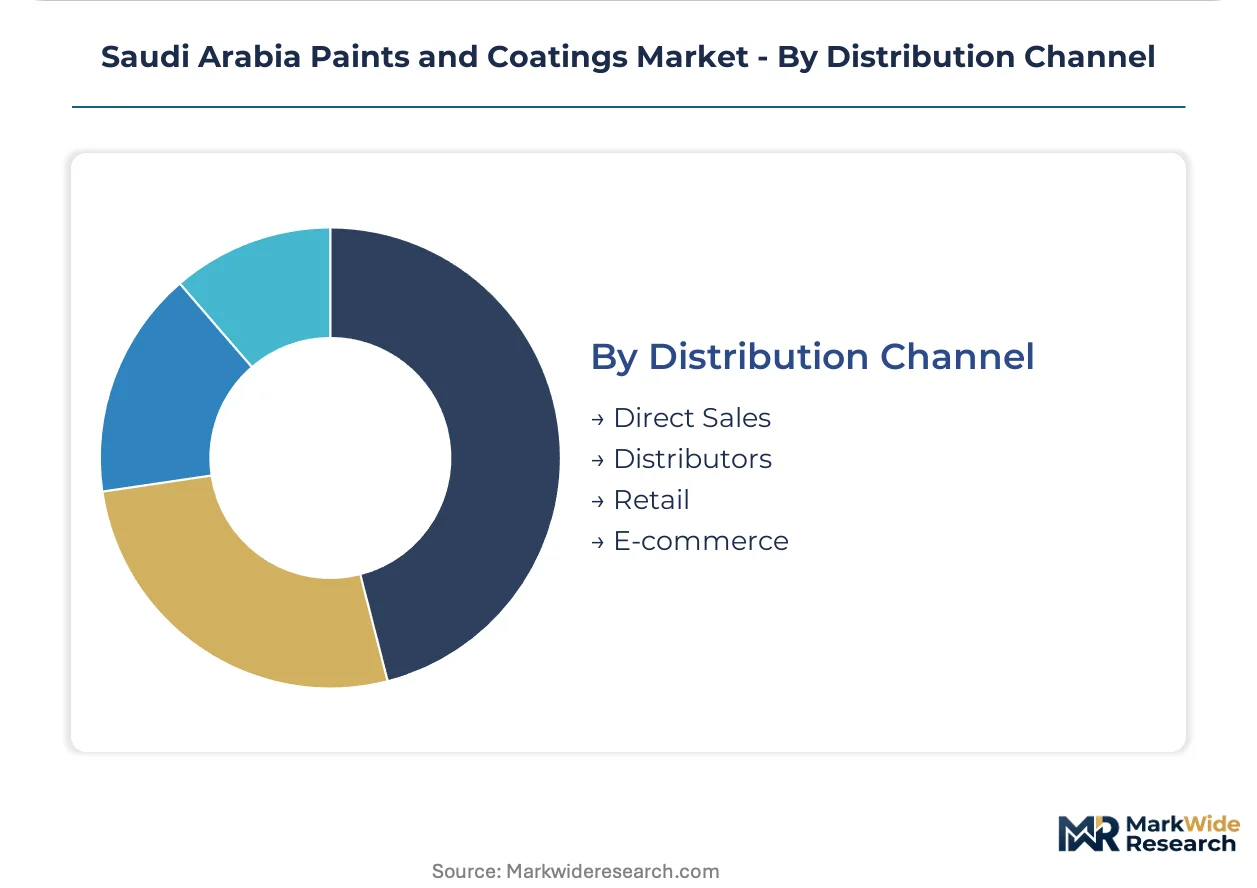
Distribution Channel:
Direct sales channels are consolidating power around giga-project procurement, while e-commerce remains nascent in this specification-heavy market.
- Direct Sales:Technical service teams embedded with major contractors and industrial end-users. Giga-project procurement teams demand on-site color matching laboratories and formulation customization rather than standard product catalogs.
- Distributors:Stockist networks facing margin compression as buyer concentration shifts to direct channels.
- Retail:Hardware stores and paint shops serving residential DIY and small contractor segments.
- E-commerce:Limited penetration constrained by specification complexity and color matching requirements.
Direct sales channels dominate premium specification capture. E-commerce shows minimal deployment given technical service dependencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
King Abdullah Economic City's special economic zone status is concentrating automotive and logistics coatings demand through tax-incentive structures that attract manufacturing investment. Regional performance varies sharply across Saudi Arabia's construction and industrial corridors.
Riyadh
NEOM and Red Sea Project procurement offices anchor the central construction corridor, driving waterborne architectural coating specifications through master agreements. SASO's VOC compliance mandates filter import pathways, protecting certified domestic producers. The Riyadh construction corridor concentrates giga-project specification authority and compresses distributor margins through direct-to-contractor channels.
Eastern Province
Jubail's petrochemical cluster expansion accelerates demand for chemical-resistant tank linings and pipeline coatings with extended service lifecycles. SFDA chemical safety protocols reposition cost-of-entry for industrial protective suppliers. Saudi Aramco downstream integration investments around Jubail Industrial City generate marine-grade and offshore platform coating procurement.
Western Region
King Abdulaziz International Airport's maintenance cluster drives aerospace MRO coatings demand alongside Jeddah's commercial construction flows. The Saudi Building Code's fire-resistance specifications generate differentiated demand for intumescent systems in high-rise towers. Red Sea Project coastal developments concentrate premium architectural coating specifications.
Asir Region
Secondary city construction outside Riyadh-Jeddah corridors offers first-mover positioning for distributors establishing direct sales networks in Abha. Mountain development projects create niche demand for climate-adapted exterior coatings. Local fabricators require capital-intensive equipment conversion to support low-VOC formulation delivery.
NEOM Northwest
The linear city's giga-project scale consolidates buyer power around centralized procurement offices demanding embedded formulation laboratories. MEE-coordinated environmental audits influence coating plant siting decisions across the development zone. On-site technical service capabilities displace traditional stockist networks in specification capture.
Saudi Arabia Paints and Coatings Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation types and end-use segments. Market structure tilts toward consolidation around giga-project procurement consolidation, with tiered differentiation between premium certified producers and price-competitive regional suppliers. Strategic archetypes include backward-integrated resin producers, distribution-dense local manufacturers, and marine-grade technical specialists. Dominant competitive moves center on direct-to-contractor channel restructuring and on-site technical service embedding.
Within the premium technical tier, Jotun exemplifies marine-grade specialization, while Akzo Nobel N.V. occupies a position as a diversified coatings conglomerate with captive resin capabilities. National Paints Factories Co. Ltd. anchors the local distribution-dense archetype through secondary city network control. These three represent contrasting strategic postures: technical specialization, upstream integration, and geographic density.
| Leading Market Players |
|---|
| Jotun |
| Akzo Nobel N.V. |
| Hempel A/S |
| Jazeera Paints |
| National Paints Factories Co. Ltd. |
| Sigma Paints |
| Kansai Paint Co. Ltd. |
| Axalta Coating Systems |
| Caparol Paints |
| Others |
Value Network & Pricing Analysis
Giga-project procurement offices concentrate buyer power around NEOM and Red Sea Project master agreements, compressing margins and forcing tiered pricing structures that separate certified domestic producers from price-competitive import alternatives. This buyer concentration reshapes how suppliers structure volume discounts and technical service bundles across the Saudi market.
Pricing Analysis
Short lead-time premiums dominate pricing for specialty resin intermediates and titanium dioxide pigments, where European and Asian supply distances compress specification windows. Three-tier pricing structure across premium certified, standard compliant, and economy import levels differentiates offerings, with SASO certification grade and embedded technical service as primary price drivers. Cost compression in economy tiers intensifies because low-compliance Asian imports face regulatory elimination. Small residential contractors show highest price sensitivity, while giga-project procurement teams prioritize compliance and service over unit cost.
Supply Chain Analysis
SFDA and SASO certification requirements gate supplier qualification, filtering import pathways and creating protected domestic market space. Raw material supply concentrates in China, Ukraine, and Germany for titanium dioxide pigments and specialty epoxy intermediates. Formulation chemists, acrylic resins, and polyurethane hardeners constitute critical input dependencies. Single-source vulnerability runs through Chinese pigment production exposed to currency fluctuation. Distribution runs through direct-to-contractor technical sales teams embedded with major construction and industrial end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty resin capacity constraints prop pricing power for backward-integrated suppliers, as local production gaps force reliance on extended-lead-time European and Asian sources. This supply bottleneck sustains margin pools for incumbents with captive resin capabilities.
For Market Incumbents: Cement specification authority through embedded formulation laboratories at giga-project sites, countering distributor margin compression. Deepen upstream control over acrylic-alkyd hybrid resin production to insulate margin pools from import volatility. Defend against emerging waterborne technology specialists by accelerating SFDA pre-registration of new chemical entities.
For New Entrants and Emerging Players: Secondary city fabricators in Asir Region represent the most penetrable buyer archetype, as legacy solventborne equipment stranding creates service gaps. Establish direct sales networks in Abha and surrounding mountain developments before incumbent channel restructuring reaches these markets. Lead with capital-light equipment conversion financing to unlock low-VOC formulation adoption among stranded asset owners.
For Investors and Strategic Acquirers: The window for entry favors resin-backward-integrated specialists with SASO certification infrastructure already deployed. Long-term viability hinges on positioning ahead of local specialty resin capacity investments that would erode import-dependent margin structures. Monitor King Abdullah Economic City automotive cluster procurement timelines as inflection indicator for industrial coatings demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Resins | Captive epoxy and polyurethane supply insulates margins from European lead-time volatility. |
| Direct-to-Contractor Channel Restructuring | Embedded technical service teams displace stockist networks at NEOM procurement offices. |
| SASO Pre-Registration Acceleration | Early chemical entity filing compresses competitor specification windows under SFDA protocols. |
| Desert-Climate Formulation R&D | UV-stable acrylic-alkyd hybrids command premium positioning in Riyadh thermal cycling exposure. |
| Asir Region Distribution Buildout | First-mover direct sales networks capture secondary city construction outside giga-project corridors. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews across plant managers at Jubail coating facilities, procurement leads at downstream petrochemical operators, distribution channel partners, and technical R&D directors at formulation houses. SASO standards documentation, SFDA chemical registration databases, and Saudi customs import classifications provided supply-side validation. Bottom-up project pipeline assessments and top-down construction spending forecasts underwent triangulation against giga-project procurement timelines.
Multiple data streams reconciled through segmentation across formulation technology, end-use application, and regional demand cluster. Product type splits, technology adoption curves, and channel migration patterns were modeled across the projection horizon. CAGRs derived from regression analysis of historical construction spending correlation with coatings consumption, adjusted for VOC regulatory inflection points and resin import dependency ratios.
Revisions become necessary when giga-project procurement consolidation accelerates, local resin capacity investments materialize, or SFDA registration protocols tighten further. Forecasts reflect assumptions about Vision 2030 construction commitment continuity and SASO enforcement consistency. A model refresh is warranted upon material change in Jubail petrochemical cluster expansion timelines or King Abdullah Economic City automotive investment flows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Asia-Pacific Architectural Coatings Market
Paints & Coatings
Paint Mixing Market
Paints & Coatings
Germany Industrial Wood Coatings Market
Paints & Coatings
Iraq Paints and Coatings Market
Paints & Coatings
India Paints and Coatings Market
Paints & Coatings
Canvas Primer Market
Paints & Coatings
Epoxy Paint Thinner Market
Paints & Coatings
North America Paints and Coatings Market
Paints & Coatings
Asia-Pacific Paints and Coatings Market
Paints & Coatings
Paint Thinner Market
Paints & Coatings
Italy Industrial Wood Coatings Market
Paints & Coatings
Iran Paints and Coatings Market
Paints & Coatings
Alkyd Coatings Market
Paints & Coatings
Automotive OEM Coatings Market
Paints & Coatings
Global Antifouling Paints and Coatings Market
Paints & Coatings
Fluorescent Paint Market