
 India Paints and Coatings Market | 2026-2036
India Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
India Paints and Coatings Market Outlook
The capital-intensity divergence between integrated resin producers and pure-formulation brands is rotating competitive advantage toward backward-linked players. Asian Paints Limited leverages captive manufacturing of key intermediates to sustain margin resilience across decorative coatings. Berger Paints India Limited anchors its position through deep distribution reach in eastern and northern India. Kansai Nerolac Paints Limited specializes in automotive OEM finishes, where technical specifications and color-matching precision dominate procurement criteria.
Paints and coatings constitute formulated liquid, paste, or powder systems comprising binders, pigments, solvents or water carriers, and functional additives that cure into adherent protective or decorative films. These materials serve primarily to shield substrates from corrosion, weathering, and chemical attack while delivering aesthetic and functional surface properties. Water-based technology leads volume in residential applications due to lower volatile organic compound emissions and faster drying characteristics, while high-performance coatings command premium positioning in industrial and marine end uses where extreme durability and chemical resistance define specification requirements. Powder coatings represent the fastest-expanding technology segment, driven by zero-solvent formulations and recovery efficiency in automated application lines.
BIS mandates on lead and chromium content in decorative paints, alongside CEA energy-efficiency guidelines for industrial coating operations, shape product reformulation and capital expenditure priorities across manufacturers. The PLI scheme for chemical manufacturing incentivizes domestic production of specialty resins and additives, reducing import dependence for formulation inputs. Stakeholders must monitor how evolving state-level building codes and green certification requirements for commercial construction redirect specification patterns toward low-emission and antimicrobial coating systems.
Market Dynamics
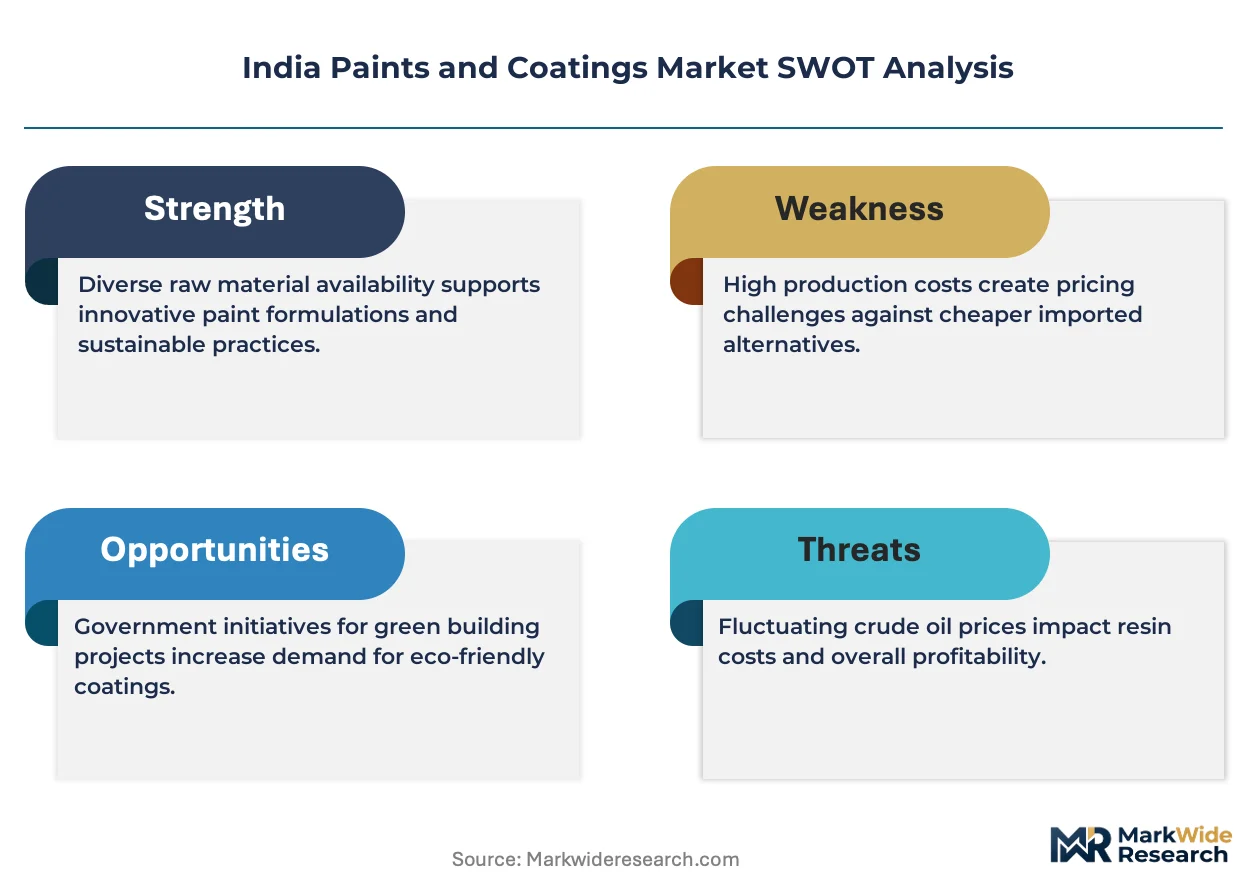
Backward integration into specialty resin production is compressing formulation margins for pure-play coating brands while rewarding integrated manufacturers with input cost stability. The PLI scheme for chemical manufacturing accelerates this structural shift by subsidizing domestic intermediate capacity.
Growth Catalysts
- Automotive OEM expansion:Passenger vehicle production growth in Pune, Chennai, and Gurugram clusters drives demand for high-durability finishes. Color-matching precision requirements favor technically sophisticated suppliers.
- BIS lead-free mandates:Mandatory certification for decorative paints eliminates non-compliant imports and forces domestic reformulation. This regulatory barrier protects established manufacturers with testing infrastructure.
- Tier-2 urbanization:Residential construction in Surat, Indore, and Coimbatore concentrates demand for water-based architectural coatings. These markets exhibit lower brand loyalty and higher price sensitivity than metro centers.
Market Restraints
- Titanium dioxide import dependence:Over 70 percent of white pigment supply originates from Chinese producers, exposing margins to freight volatility and currency fluctuation.
- Crude-linked solvent costs:Petroleum-derived aromatic thinners track Brent movements with limited hedging mechanisms available to mid-scale formulators.
- CEA energy-efficiency compliance:Industrial coating operations face mandated efficiency audits and capital-intensive equipment upgrades that extend payback periods.
Strategic Opportunities
- Antimicrobial commercial specification:Post-pandemic healthcare and educational infrastructure projects in Kerala and Tamil Nadu now require certified hygienic surface coatings.
- Powder coating penetration:Zero-VOC formulations with overspray recovery systems attract appliance and furniture manufacturers seeking automated application lines.
- PLI resin localization:Domestic acrylic and alkyd intermediate production reduces working capital cycles and import documentation burdens for formulation plants.
Industry Challenges
- Colorimetrist talent scarcity:Automotive and industrial segments face acute shortages of technicians capable of spectrophotometric matching and batch correction.
- BIS certification timelines:Lead and chromium testing protocols extend product launch cycles by 4-6 months, compressing seasonal selling windows.
- Legacy distributor credit systems:Tier-3 and rural channel partners resist digital payment platforms, constraining real-time sales visibility and inventory optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Paints and Coatings Market |
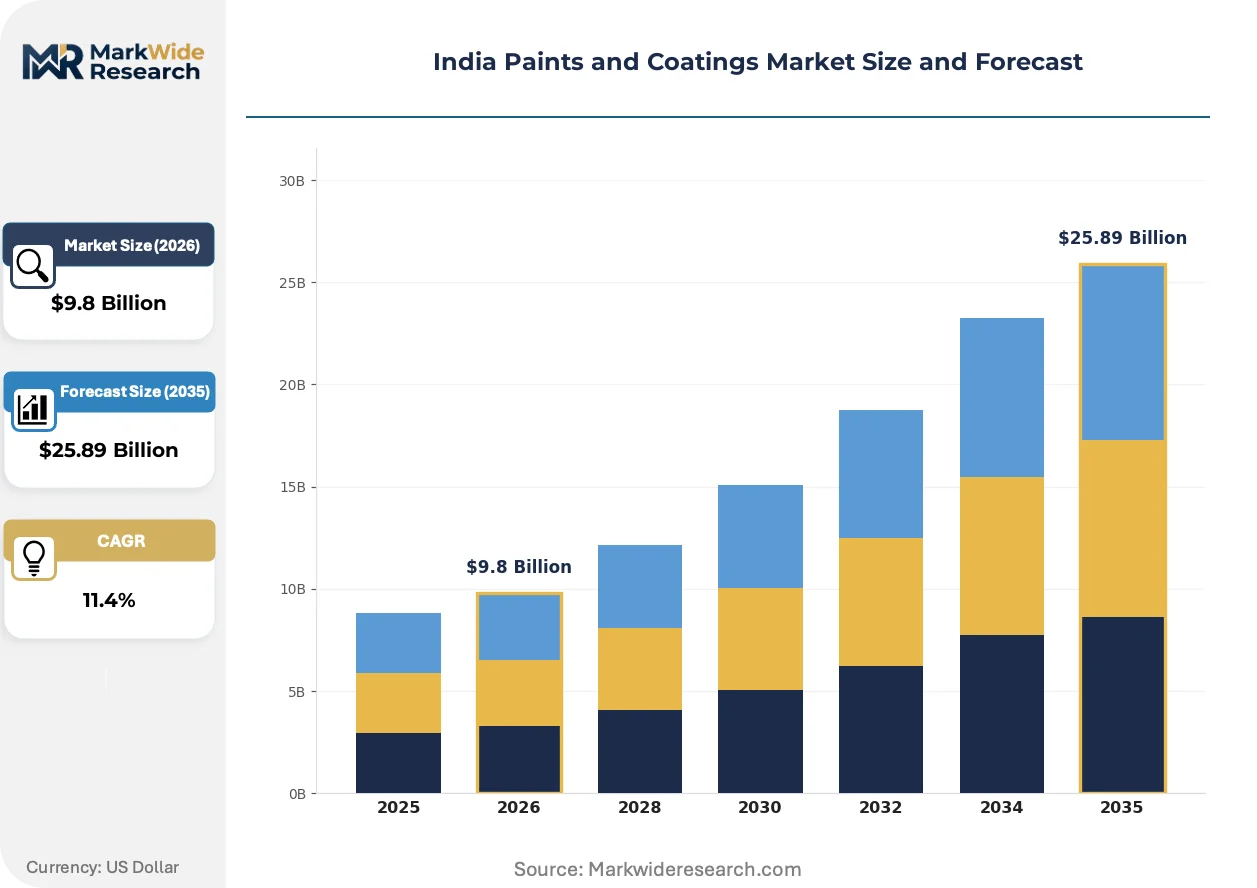
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $25.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Architectural Coatings, Industrial Coatings, Decorative Coatings, Specialty Coatings Application: Residential, Commercial, Automotive, Marine End User: Construction, Transportation, Consumer Goods, Furniture Technology: Water-Based, Solvent-Based, Powder Coatings, High-Performance Coatings |
| Companies Covered | Asian Paints Limited, Berger Paints India Limited, Kansai Nerolac Paints Limited, JSW Paints Private Limited, Birla Opus, Indigo Paints Ltd, Shalimar Paints, Nippon Paint Holdings Co. Ltd, Sirca Paints India Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Paints and Coatings Market Strategic Shifts
Formulation chemistry and application technology are diverging sharply between mass-market decorative segments and precision industrial coatings. This technological schism is fragmenting R&D investment patterns and reshaping competitive capabilities across the value chain.
Waterborne polyurethane technology is bifurcating the wood coatings segment. Furniture manufacturers in Jodhpur and Moradabad adopt these systems for faster line speeds and lower flash-fire risk. The technology is bifurcating supplier hierarchies by rewarding resin-integrated players while marginalizing formulation-only brands dependent on merchant resin supply.
BIS certification requirements for lead-free decorative paints entered mandatory enforcement in 2023. Testing laboratory capacity constraints in Mumbai and Delhi create bottlenecks for new market entrants. Maharashtra and Gujarat-based manufacturers with in-house quality infrastructure capture disproportionate share of reformulation-driven replacement cycles.
Project contractors in commercial real estate now specify coating systems by performance warranty rather than brand name. This behavior compresses distributor margins and forces direct engagement between manufacturers and engineering-procurement-construction firms. Bangalore and Hyderabad construction markets exhibit the most advanced specification-by-performance contracting patterns.
India Paints and Coatings Market Segmentation
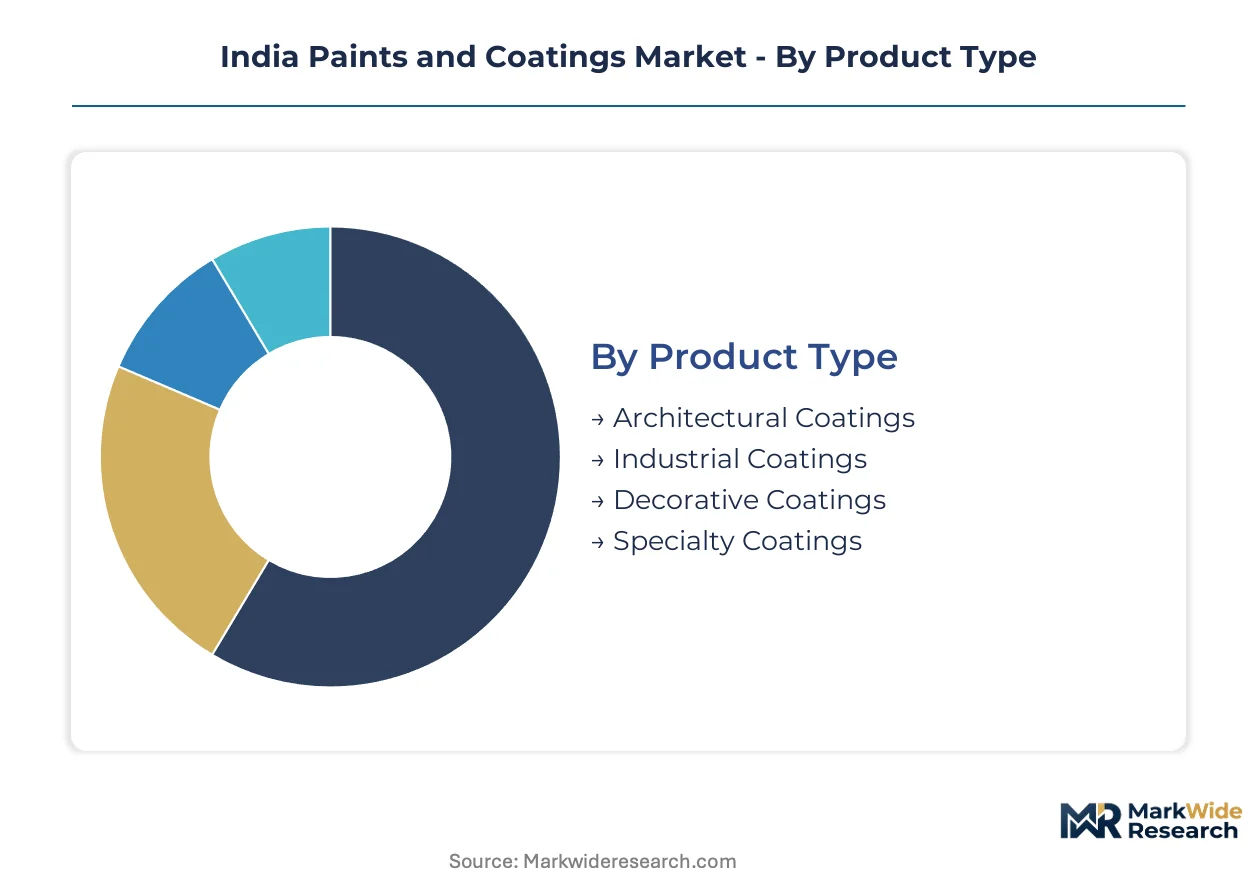
Segmentation in the India paints and coatings market reveals divergent margin structures and regulatory exposure across product categories. Manufacturers allocate capital differently depending on whether segments serve price-sensitive domestic construction or specification-driven industrial export channels.
Product Type:
Architectural and decorative coatings dominate domestic volume, while industrial and specialty grades sustain export-led pricing power through technical certification requirements.
- Architectural Coatings:These water-dispersed systems protect and finish exterior and interior building surfaces across residential and commercial projects. Demand concentrates in Maharashtra and Gujarat, where tier-2 city construction absorbs volume despite monsoon-constrained application windows.
- Industrial Coatings:High-build protective systems withstand chemical exposure, abrasion, and thermal cycling in manufacturing facilities and infrastructure. Pune and Chennai automotive clusters drive specification intensity, with OEM color-matching protocols filtering supplier eligibility.
- Decorative Coatings:Aesthetic-focused interior and exterior finishes prioritize tinting system breadth and distributor accessibility. Rural Karnataka and Tamil Nadu markets exhibit rising per-capita consumption as housing stock quality improves.
- Specialty Coatings:Functional formulations deliver fire resistance, antimicrobial properties, or thermal insulation for critical infrastructure. Kerala healthcare projects increasingly specify certified hygienic surface systems post-pandemic.
Architectural coatings command the established base. The steepest expansion runs through specialty coatings.
Application:
Application-based segmentation separates cyclical construction exposure from long-cycle industrial maintenance contracts with divergent working capital requirements.
- Residential:Interior and exterior finishing systems for individual homes and multi-unit housing. Surat and Indore construction activity absorbs water-based volume, though seasonal monsoon patterns compress effective selling periods.
- Commercial:High-durability coatings for offices, retail, and institutional buildings with performance warranty specifications. Bangalore contractors increasingly source directly from manufacturers rather than distributor networks.
- Automotive:OEM and refinish coatings requiring spectrophotometric color matching and chip resistance. Gurugram and Chennai production lines enforce technical qualification barriers that limit qualified supplier pools.
- Marine:Anti-corrosive and anti-fouling systems for shipbuilding and port infrastructure. Visakhapatnam and Kochi yard activity connects to export vessel contracts with extended qualification timelines.
Residential application anchors volume throughput. Commercial specification is gaining share fastest as warranty-based procurement spreads.
End User:
End-user segmentation maps capital expenditure cycles, with construction and transportation exhibiting inverse timing that stabilizes aggregate demand.
- Construction:New build and renovation activity across residential, commercial, and infrastructure verticals. State-level urban development missions in Madhya Pradesh and Rajasthan channel funding toward affordable housing finishes.
- Transportation:Automotive OEM, commercial vehicle, and railway rolling stock finishing requirements. Original equipment specifications favor suppliers with captive resin production and in-house colorimetry laboratories.
- Consumer Goods:Appliance, electronics, and packaging coatings with automated application compatibility. Powder coating penetration rises among refrigerator and air-conditioner manufacturers seeking VOC compliance.
- Furniture:Wood finishing systems for domestic and export-oriented manufacturing. Jodhpur and Moradabad clusters adopt waterborne polyurethane technology for faster line speeds and reduced flash-fire risk.
Construction end-use holds the volume base. Transportation procurement is climbing the fastest as passenger vehicle production expands.
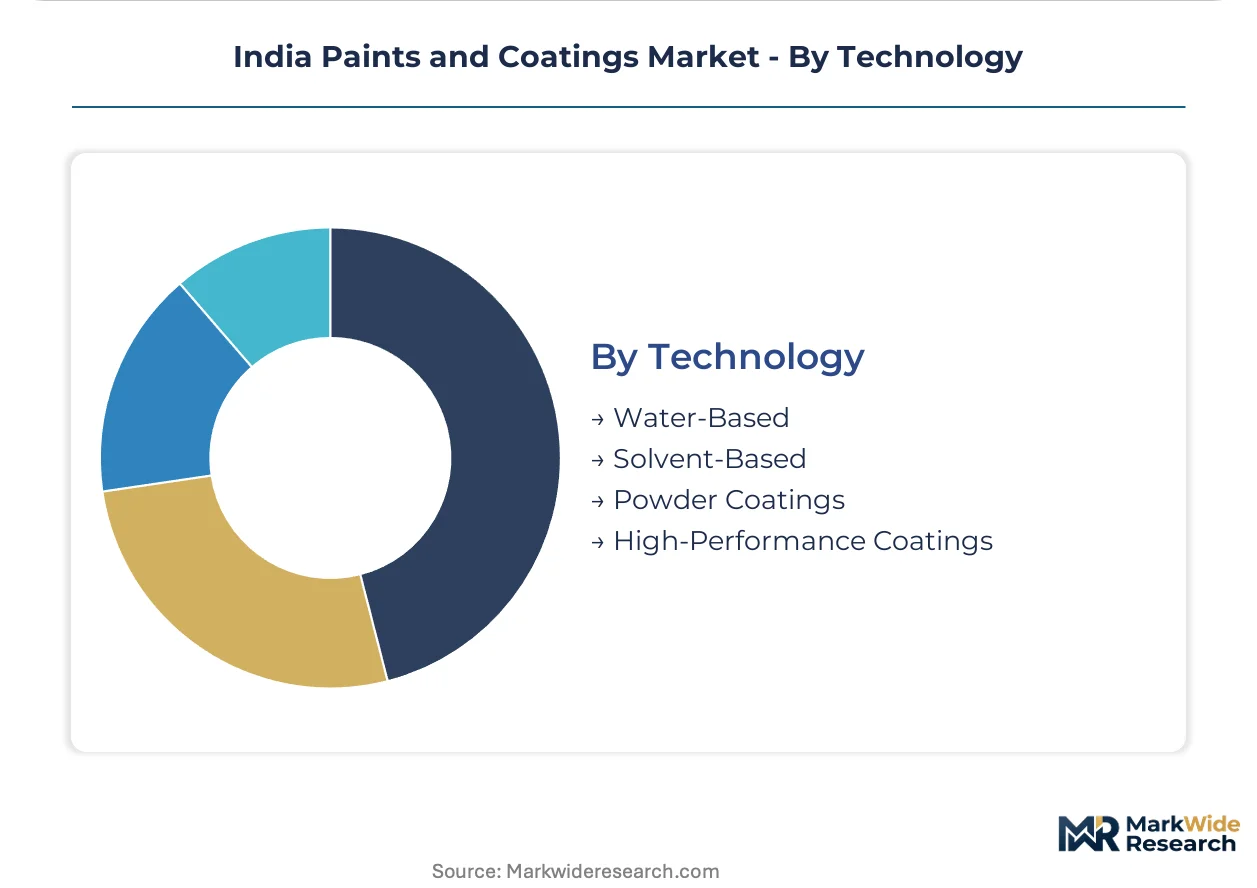
Technology:
Technology segmentation tracks regulatory pressure on solvent emissions and capital intensity of application equipment.
- Water-Based:Acrylic and polyurethane dispersions with low VOC profiles and ambient curing. Residential adoption in tier-2 cities accelerates as BIS lead-free mandates eliminate non-compliant alternatives.
- Solvent-Based:Alkyd and epoxy systems delivering superior gloss and chemical resistance for industrial maintenance. Crude-linked aromatic thinner costs expose margins to Brent volatility with limited hedging instruments.
- Powder Coatings:Thermosetting resin systems applied electrostatically with near-zero overspray waste. Appliance and furniture manufacturers in Gujarat adopt automated lines with recovery systems for regulatory compliance.
- High-Performance Coatings:Fluoropolymer, ceramic, and intumescent systems for extreme environment protection. Offshore infrastructure and chemical processing plants in Maharashtra specify these for extended maintenance intervals.
Water-based technology commands the installed base. Powder coatings are gaining share fastest as zero-VOC formulations attract capital investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Maharashtra and Gujarat exceeds Karnataka and Tamil Nadu by 12-15 percent due to resin manufacturing density and BIS laboratory proximity. Western India commands premium realization through captive intermediate supply and faster certification turnaround. Southern markets trade at narrower spreads as import-dependent formulators absorb higher logistics costs.
Maharashtra
Residential construction in Nagpur and Nashik drives water-based decorative volume, while Mumbai-Pune industrial corridors absorb high-performance automotive finishes. BIS certification bottlenecks favor established manufacturers with in-house testing infrastructure in Thane and Navi Mumbai. The Mumbai metropolitan region concentrates headquarters functions and R&D facilities for integrated resin producers.
Gujarat
Surat and Vadodara construction activity absorbs architectural coatings despite monsoon-compressed application windows. CEA energy-efficiency audits for industrial coating operations accelerate equipment upgrade cycles in Ankleshwar chemical clusters. The Dahej PCPIR corridor attracts PLI-subsidized acrylic resin plants reducing import dependence for formulation inputs.
Karnataka
Bangalore commercial real estate contractors specify coating systems by performance warranty rather than brand name, compressing distributor margins. The state's technology parks drive demand for antimicrobial finishes in healthcare and educational infrastructure. Mysuru furniture manufacturers adopt waterborne polyurethane systems for export-oriented wood finishing lines.
Tamil Nadu
Chennai automotive OEM clusters enforce spectrophotometric color-matching protocols that limit qualified supplier pools for refinish coatings. Coimbatore tier-2 residential construction exhibits rising per-capita consumption as housing stock quality improves. Kerala healthcare projects post-pandemic specify certified hygienic surface systems from Tamil Nadu-based specialty formulators.
Haryana
Gurugram passenger vehicle production lines anchor demand for high-durability OEM finishes with technical qualification barriers. The Delhi-NCR air quality regulations accelerate solvent-based to water-based conversion in decorative segments. Faridabad industrial coating operations face CEA-mandated efficiency audits extending capital payback periods.
India Paints and Coatings Market Competitive Environment
Concentration sits with integrated resin manufacturers who compress formulation margins for pure-play brands through captive intermediate supply. Three-tier competitive structure separates backward-linked national players, regional distributors with deep channel reach, and import-dependent specialty formulators. Dominant competitive moves include PLI-subsidized resin capacity expansion and direct engagement with engineering-procurement-construction firms bypassing traditional distribution.
Within the integrated-manufacturer tier, Asian Paints Limited and Kansai Nerolac Paints Limited exemplify archetypes of resin-captive competitive positioning. Berger Paints India Limited occupies a distinct geography-first position anchoring eastern and northern distribution networks. These three entities represent the structural divergence between input-cost-stable integrated players and channel-dependent formulation specialists.
| Leading Market Players |
|---|
| Asian Paints Limited |
| Berger Paints India Limited |
| Kansai Nerolac Paints Limited |
| JSW Paints Private Limited |
| Birla Opus |
| Indigo Paints Ltd |
| Shalimar Paints |
| Nippon Paint Holdings Co. Ltd |
| Sirca Paints India Limited |
| Others |
Value Chain & Pricing Dynamics
BIS lead-free certification requirements gate both supplier qualification and price differentiation simultaneously. Manufacturers with in-house testing infrastructure in Maharashtra and Gujarat command 12-15 percent premium realization over import-dependent formulators absorbing certification delays and logistics costs.
Pricing Analysis
Configured-to-order pricing for automotive OEM finishes spreads 25-40 percent above standard decorative coatings. Pricing stratifies across premium performance-warranty systems, standard BIS-certified formulations, and economy-grade unbranded alternatives. Cost compression in the economy tier is intensifying because titanium dioxide import dependence exposes margins to freight volatility. Tier-2 residential contractors exhibit highest price sensitivity; automotive OEM procurement teams prioritize technical qualification over unit cost.
Supply Chain Analysis
Port congestion on the Nhava Sheva-Mundra corridor and container availability constraints on the China-India trade lane elevate inbound logistics costs for white pigment and specialty resin imports. Raw material supply concentrates in China for titanium dioxide, in South Korea for high-grade acrylic monomers, and in Germany for automotive colorant intermediates. Formulation plants draw from petroleum-derived aromatic thinners tracking Brent movements with limited hedging mechanisms. Single-source vulnerability sits with Chinese titanium dioxide producers supplying over 70 percent of domestic white pigment demand. Distribution runs through three-tier networks of company depots, regional distributors, and rural stockists with legacy credit systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from integrated resin producers compressing formulation margins for pure-play brands. Defense requires structural repositioning around captive intermediate supply and direct specification engagement.
For Market Incumbents: Fortify backward integration into PLI-subsidized acrylic and alkyd resin capacity in Gujarat's Dahej corridor to neutralize input cost volatility. Deepen direct engagement with Bangalore and Hyderabad engineering-procurement-construction firms specifying by performance warranty rather than brand name, bypassing distributor margin compression. For New Entrants and Emerging Players: Post-pandemic antimicrobial coating specifications in Kerala and Tamil Nadu healthcare infrastructure represent underserved white-space demand. Target tier-2 city residential contractors in Surat, Indore, and Coimbatore with water-based decorative systems priced below established brand premiums. Build go-to-market through digital tinting platforms and contractor-direct service models that legacy distributors resist. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across specialty resin manufacturing as PLI subsidies attract capacity buildout. Long-term viability favors integrated manufacturers with captive intermediate supply over formulation-dependent brands facing margin compression. Acquisition target archetype: regional formulators with established BIS certification infrastructure and underutilized distribution networks in eastern and northern India. Monitor PLI disbursement velocity and resin plant commissioning timelines as inflection indicators for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Resins | PLI-subsidized acrylic capacity in Dahej reduces import dependence and stabilizes formulation margins. |
| Direct EPC Engagement | Bangalore contractors specifying by performance warranty reward technical qualification over distributor relationships. |
| Antimicrobial Certification Investment | Kerala healthcare projects post-pandemic require certified hygienic surface systems with premium pricing power. |
| Powder Coating Line Automation | Gujarat appliance manufacturers adopt zero-VOC systems with overspray recovery for regulatory compliance. |
| Digital Tinting Platform Deployment | Tier-2 residential contractors in Surat and Coimbatore favor real-time color matching and inventory visibility. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of BIS certification databases, CEA energy-efficiency audit records, customs trade data for titanium dioxide imports, and PLI scheme disbursement filings. Primary interviews engaged plant managers at integrated resin facilities, procurement leads at automotive OEM coating operations, distribution channel partners in Maharashtra and Gujarat, and technical R&D directors at formulation plants. Secondary validation drew from SEC 10-K disclosures of listed manufacturers, chemical industry association reports, and state-level urban development mission documentation. Bottom-up volume modeling triangulated against top-down market sizing across product categories.
Segmentation dimensions modeled include product type, application vertical, end-use industry, and technology platform across the projection horizon. Analytical framework incorporated resin cost pass-through elasticity, regulatory compliance cost burdens, and regional construction activity indices. CAGRs derived from trend extrapolation of historical volume data adjusted for PLI-induced capacity expansion and BIS mandate implementation timelines. Industry-specific forecast inputs encompassed automotive production cluster growth rates and tier-2 city housing stock quality improvement trajectories.
Forecasts assume regulatory continuity in BIS lead-free mandates and CEA energy-efficiency guidelines; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Middle East and Africa Paints and Coatings Market
Paints & Coatings
Metal Paint Tray Market
Paints & Coatings
GCC Paints and Coatings Market
Paints & Coatings
Asia-Pacific Architectural Coatings Market
Paints & Coatings
Global Antifouling Paints and Coatings Market
Paints & Coatings
Bahrain Paints and Coatings Market
Paints & Coatings
Interior Architectural Coatings Market
Paints & Coatings
Acrylic Paints Market
Paints & Coatings
Europe Architectural Coatings Market
Paints & Coatings
Global Exterior Architectural Coatings Market
Paints & Coatings
Global Decorative Coatings Market
Paints & Coatings
Sri Lanka Paints and Coatings Market
Paints & Coatings
South America Architectural Coatings Market
Paints & Coatings
India Automotive Paints and Coatings Market
Paints & Coatings
Bio-Based and Low VOC Paints Market
Paints & Coatings
Floor Paints Market