
 Food Grade Epoxy Paint Market | 2026-2036
Food Grade Epoxy Paint Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Epoxy Paint Market Analytics
Preventive maintenance subscription programs is hardening as a core revenue layer, shifting vendor-customer relationships from transactional coating sales to guaranteed surface-performance contracts. Sherwin-Williams leverages its national distribution network to bundle inspection services with material supply. PPG Industries anchors its position through R&D intensity in low-VOC formulations for cold-storage environments. AkzoNobel differentiates via color-stable systems that reduce re-coating frequency in high-acid food zones.
Food grade epoxy paint denotes a thermosetting polymer coating formulated from bisphenol-A or bisphenol-F epoxy resins cured with amine hardeners, achieving film thicknesses of 8-15 mils and temperature resistance from -40°F to 250°F to protect concrete and steel in hygienic processing environments. Two-component solvent-based systems dominate current volume owing to superior chemical resistance against caustic washdowns, while water-based formulations are capturing specification share where VOC thresholds tighten and contractors face restricted work windows. Industrial flooring applications generate the largest absolute demand within the application dimension, though food processing equipment coatings command premium pricing due to NSF certification requirements and direct food contact validation protocols.
FDA compliance mandates under 21 CFR 175.300, USDA facility sanitation guidelines, and ISO 22000 hazard management standards collectively determine product formulation boundaries and market access eligibility for coating suppliers serving North American food manufacturers. Regulatory divergence between EPA VOC rules at the state level and Health Canada PMRA chemical registration requirements creates formulation complexity for vendors operating across the US-Canada border. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as state-level prohibitions in California and Maine are already forcing reformulation of certain epoxy additive packages.
Market Dynamics
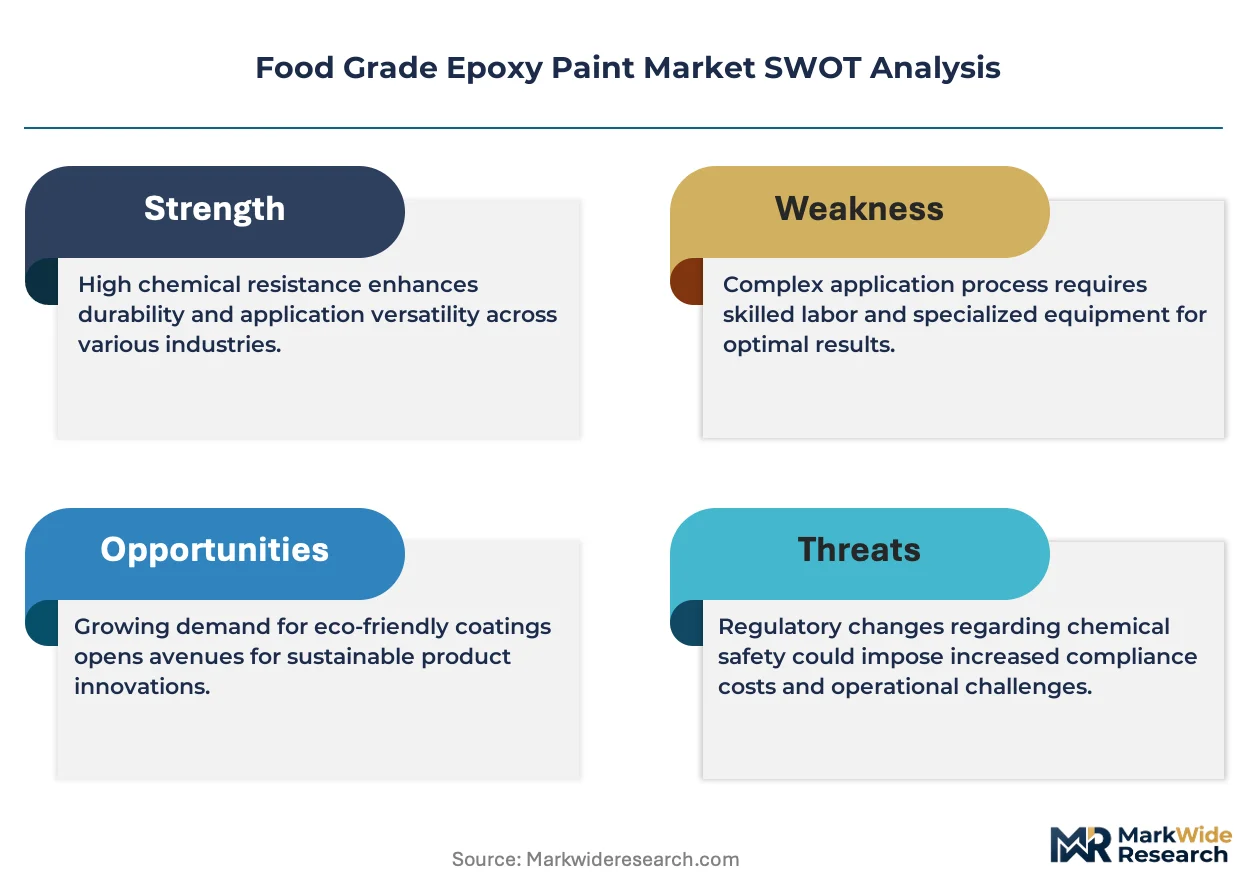
Preventive maintenance subscription programs harden vendor-customer relationships from transactional coating sales into guaranteed surface-performance contracts, locking recurring revenue streams for suppliers serving FDA-inspected facilities.
Growth Catalysts
- 21 CFR 175.300:FDA's resinous and polymeric coatings regulation tightens inspection protocols for direct food contact surfaces, forcing meat and dairy processors into accelerated recoating cycles.
- Cold-storage infrastructure expansion:Frozen food distribution centers in the American Midwest drive specification of low-temperature-cure epoxies with enhanced thermal shock resistance.
- Caustic washdown protocols:USDA facility sanitation guidelines mandate aggressive cleaning chemicals that degrade conventional paints, elevating demand for two-component solvent-based systems with superior chemical resistance.
Market Restraints
- Bisphenol-A feedstock volatility:Epoxy resin prices fluctuate with petrochemical supply disruptions, compressing coating manufacturers' margin buffers during contract negotiations.
- Amine hardener supply concentration:Specialty curing agent production clusters in coastal China create trans-Pacific logistics vulnerability for North American formulators.
- Water-based performance gap:Aqueous epoxy systems fail to match solvent-based chemical resistance in high-acid fruit processing zones, limiting specification in critical applications.
Strategic Opportunities
- California PFAS prohibitions:State-level restrictions on per- and polyfluoroalkyl substances force additive package reformulation, creating first-mover advantage for compliant epoxy suppliers.
- Color-stable system premiums:High-acid food zones in Wisconsin and Iowa dairy clusters reward coatings that reduce re-coating frequency through pigment technology advances.
- Inspection service bundling:National distribution networks enable coating vendors to integrate surface-performance monitoring with material supply, capturing maintenance budgets previously held by third-party contractors.
Industry Challenges
- NSF certification timelines:Direct food contact validation protocols extend product launch cycles by 12-18 months, delaying revenue recognition for new formulations.
- VOC compliance fragmentation:Divergent EPA state-level rules and Health Canada PMRA registration requirements force parallel formulation tracks for cross-border operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Epoxy Paint Market |
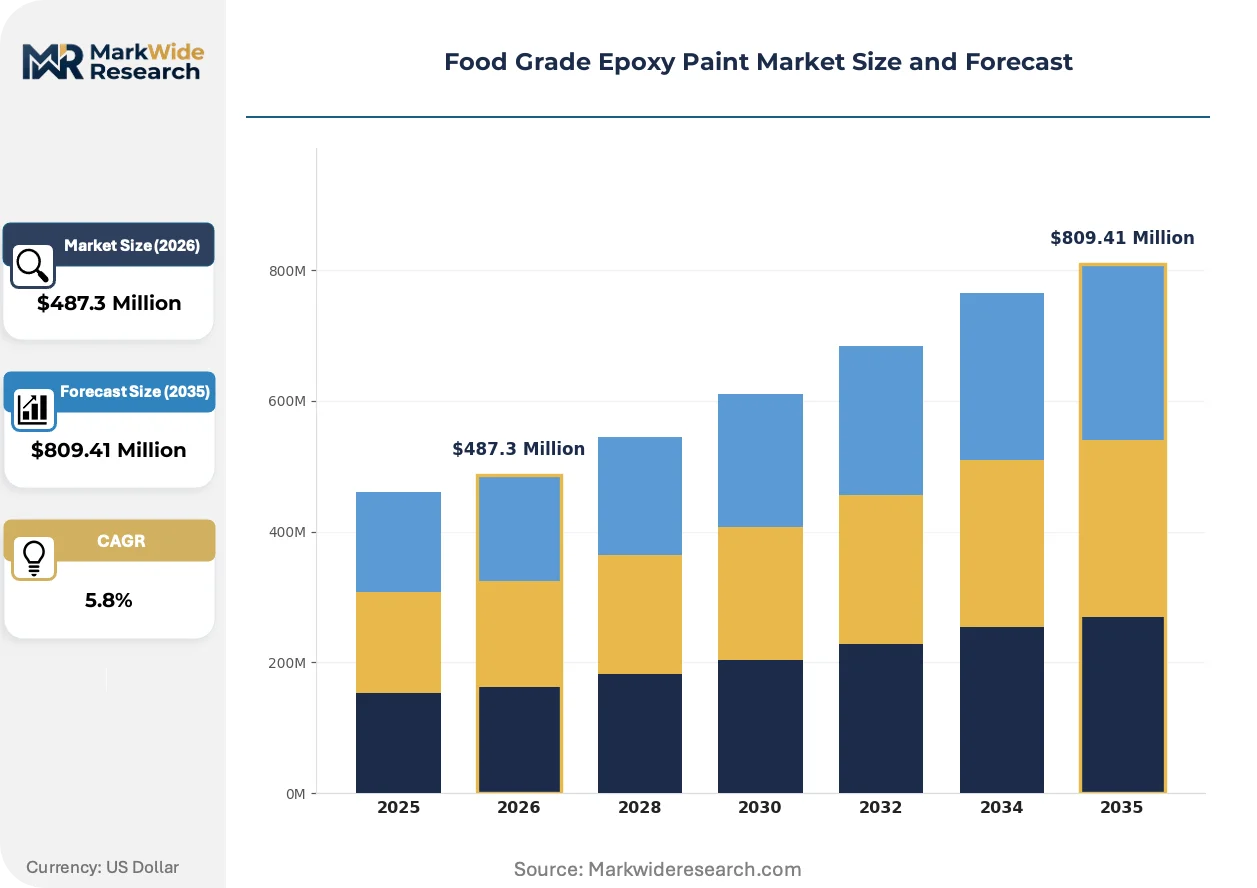
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Two-Component, Single-Component, Water-Based, Solvent-Based Application: Food Processing Equipment, Industrial Flooring, Storage Tanks, Food Packaging End User: Manufacturers, Distributors, Contractors, Food Service Operators Regulatory Compliance: FDA Compliant, USDA Approved, NSF Certified, ISO 22000 |
| Companies Covered | Rust-Oleum, Tnemec, Sherwin-Williams, Crossfield Products, Carboline, PPG Industries, Jotun, Resincoat Ltd, AkzoNobel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Epoxy Paint Market Evolving Landscape
Automated coating application systems and predictive surface monitoring reshape how food processors manage hygienic infrastructure, compressing labor-dependent maintenance windows into precision-scheduled interventions.
Robotic spray application technology is automating film thickness control in tank and vessel interiors, eliminating human error in achieving 8-15 mil specifications. Meat processing facilities in Nebraska and Kansas adopt these systems to reduce contractor exposure during confined-space entry. The technology is automating quality assurance documentation that FDA inspectors now demand during routine audits.
EPA state-level VOC thresholds tighten fastest in California and the Northeast, forcing water-based epoxy specification where solvent-based systems previously dominated. Contractors face restricted work windows in occupied food plants, accelerating demand for low-odor, fast-cure alternatives. Cold-storage operators respond by qualifying hybrid systems that balance emission compliance with thermal performance.
Subscription-based surface performance contracts displace spot-purchase procurement in multi-plant food manufacturers. Procurement departments bundle coating supply with guaranteed inspection intervals and warranty-backed durability metrics. This model concentrates most visibly in Midwest dairy cooperatives seeking to standardize facility hygiene across distributed processing networks.
Food Grade Epoxy Paint Market Segmentation
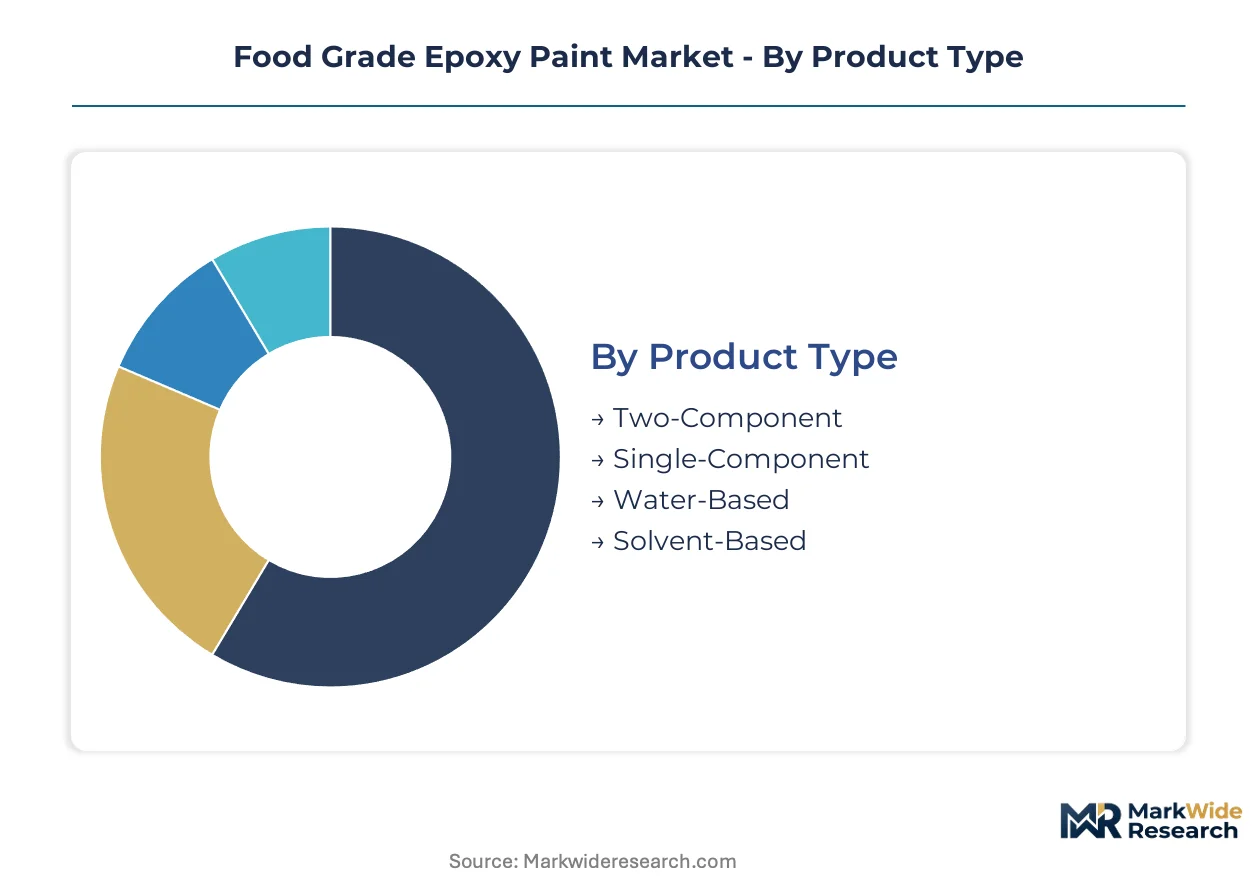
Segmentation in food grade epoxy paint tracks how formulation chemistry, application environment, and certification burden align to create distinct pricing tiers and procurement patterns. Buyers sort options by direct food contact validation requirements, thermal exposure limits, and contractor application constraints.
Product Type:
FDA 21 CFR 175.300 compliance obligations vary sharply across these chemistries, with direct food contact applications demanding resinous and polymeric coating validation that single-component systems rarely achieve.
- Two-Component:Bisphenol-A or bisphenol-F epoxy resins cured with amine hardeners deliver 8-15 mil film thickness and -40°F to 250°F thermal tolerance. Meat and dairy processors in Wisconsin and Iowa specify these for tank interiors where caustic washdowns degrade lesser formulations.
- Solvent-Based:Volatile organic compound content restricts work windows in occupied plants, though superior chemical resistance against acids and alkalis preserves specification share in fruit processing zones. California EPA thresholds force reformulation for contractors serving West Coast facilities.
- Single-Component:Pre-catalyzed moisture-cure urethane hybrids suit secondary containment and non-contact surfaces where NSF certification is unnecessary.
- Water-Based:Low-odor properties enable application during production hours, though performance gaps in high-acid environments limit penetration.
Two-Component sits at the top of the volume ranking, with Water-Based climbing the fastest.
Application:
Cost tier separation runs widest here, with direct food contact validation adding 40-60% pricing premiums over secondary infrastructure coatings.
- Industrial Flooring:Concrete protection in hygienic zones demands slip-resistant aggregates and thermal shock resistance for freezer-to-ambient transitions. Midwest meatpacking corridors in Nebraska and Kansas drive recurring recoating cycles from forklift abrasion and chemical exposure.
- Food Processing Equipment:Tank interiors, conveyor systems, and vessel surfaces require NSF certification and migration testing under FDA protocols. Equipment OEMs in Minnesota anchor premium pricing through specification lock-in during original fabrication.
- Storage Tanks:Exterior weathering protection and interior linings for liquid food ingredients balance cost against inspection interval extension.
- Food Packaging:Can lining and closure coating applications face tightening per- and polyfluoroalkyl substance scrutiny in California and Maine state regulations.
Industrial Flooring commands absolute volume leadership, while Food Processing Equipment captures the steepest margin expansion trajectory.
End User:
Procurement authority concentration determines contract structure, with multi-plant operators extracting subscription-based performance guarantees unavailable to fragmented contractor channels.
- Manufacturers:Food processing facility owners and equipment OEMs specify coatings during capital projects, locking formulation choices for 5-7 year depreciation cycles. Dairy cooperatives across the American Midwest standardize specifications across distributed plant networks.
- Contractors:Application specialists bundle surface preparation and quality documentation that FDA inspectors now demand during routine audits. Confined-space entry protocols in tank interiors favor robotic spray contractors with automated film thickness control.
- Distributors:Regional coating suppliers bridge national formulator networks with local contractor relationships, capturing specification influence in maintenance recoating decisions.
- Food Service Operators:Commercial kitchen and central commissary operators represent price-sensitive demand with limited technical specification involvement.
Manufacturers sit at the top of the volume ranking, with Contractors climbing the fastest.
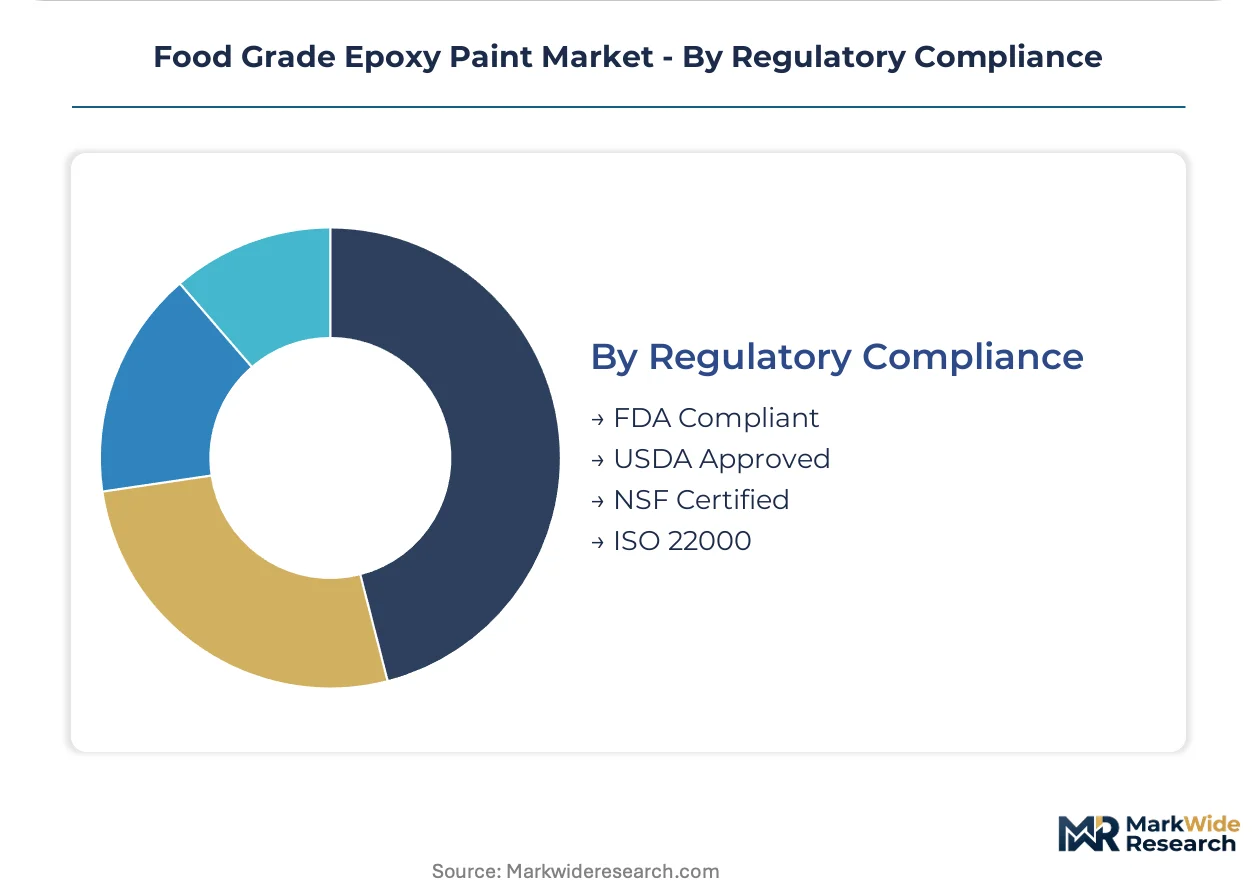
Regulatory Compliance:
Certification tier creates market access gates, with dual-validated products commanding supply priority during raw material allocation crunches.
- FDA Compliant:21 CFR 175.300 resinous and polymeric coatings regulation mandates extraction testing and migration limits for direct food contact surfaces. Compliance documentation accompanies every coating lot for meat and dairy processors under intensified inspection protocols.
- NSF Certified:NSF/ANSI 51 food equipment materials standard requires toxicological review and formulation disclosure that extends product launch timelines by 12-18 months. Certification maintenance demands annual facility audits of manufacturing plants.
- USDA Approved:Facility sanitation guideline alignment enables coating specification in federally inspected establishments without direct food contact validation.
- ISO 22000:Hazard management system certification appeals to exporters serving integrated supply chains with multinational audit requirements.
FDA Compliant sits at the top of the volume ranking, with NSF Certified climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's food processing equipment sector demands stricter migration testing protocols than Canada's dairy infrastructure, creating divergent certification timelines for coating suppliers operating across both markets.
United States
Meatpacking corridors in Nebraska and Kansas drive recurring recoating cycles from forklift abrasion and chemical exposure. FDA inspection protocols under 21 CFR 175.300 tighten compliance burdens for direct food contact surfaces. Wisconsin dairy cooperatives standardize specifications across distributed plant networks, locking formulation choices for multi-year depreciation cycles.
Canada
Cold-storage distribution centers in Ontario and Alberta specify low-temperature-cure epoxies with enhanced thermal shock resistance. Health Canada PMRA chemical registration requirements create formulation complexity for vendors operating across the US-Canada border. Quebec food processors face parallel compliance tracks with divergent EPA state-level rules.
Germany
Bavarian dairy equipment manufacturers anchor premium pricing through specification lock-in during original fabrication. ECHA REACH chemical registration mandates extraction testing for resinous coatings in hygienic zones. Baden-Württemberg industrial flooring contractors bundle surface preparation with quality documentation that EU auditors demand.
China
Shanghai and Guangdong food packaging facilities face tightening GB standards for direct contact coatings. SAMR registration requirements extend product launch timelines for imported epoxy systems. Yangtze River Delta meat processing clusters adopt automated spray application to reduce confined-space contractor exposure.
Brazil
São Paulo fruit processing zones specify coatings with superior chemical resistance against high-acid environments. ANVISA pharmaceutical-grade coating standards influence adjacent food equipment specifications. Minas Gerais dairy cooperatives seek NSF-certified systems to access export markets with multinational audit requirements.
Food Grade Epoxy Paint Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation-integrated players capturing premium tiers while regional distributors dominate maintenance recoating cycles. The vendor base concentrates around three strategic archetypes: multinational chemical conglomerates with R&D intensity, national distribution networks bundling inspection services, and regional specialists serving single-state contractor channels. Competitive moves center on preventive maintenance subscription programs and low-VOC formulation portfolios for emission-restricted work windows.
Among North American coating conglomerates, Sherwin-Williams, PPG Industries, and AkzoNobel exemplify the R&D-intensive tier. Sherwin-Williams leverages its national distribution footprint to integrate surface-performance monitoring with material supply. PPG Industries anchors its competitive position through formulation intensity in cold-storage environments. AkzoNobel occupies a differentiated slot via color-stable systems that reduce re-coating frequency in high-acid food zones.
| Leading Market Players |
|---|
| Rust-Oleum |
| Tnemec |
| Sherwin-Williams |
| Crossfield Products |
| Carboline |
| PPG Industries |
| Jotun |
| Resincoat Ltd |
| AkzoNobel |
| Others |
Value Network & Pricing Analysis
Amine hardener feedstock costs transmit directly from coastal China production clusters through to North American coating formulators, compressing margin buffers in two-component solvent-based systems while subscription-based service bundling absorbs volatility in premium tiers.
Pricing Analysis
Capacity additions in Southeast Asian epoxy resin production are reshaping price floors for bisphenol-A based formulations, though FDA 21 CFR 175.300 compliance documentation and NSF certification maintenance sustain premium-mid-economy pricing differentiation. Price differentiation hinges on direct food contact validation tier and thermal performance specification, with cold-storage grade systems commanding least price sensitivity from Midwest dairy cooperatives and commodity flooring coatings facing intense pressure from contractor procurement consolidation.
Supply Chain Analysis
Direct-to-OEM channels handle equipment manufacturer demand for NSF-certified tank linings, while national distribution networks serve maintenance recoating cycles through regional contractor relationships. Raw material sourcing draws from China for specialty amine hardeners, Germany for high-purity bisphenol-F resins, and domestic US production for commodity epoxy intermediates. Single-source vulnerability concentrates in trans-Pacific logistics for curing agent supply, with tariff exposure on Chinese chemical imports threatening formulation cost stability across North American production footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds value through regulatory tightening, with FDA inspection protocol intensification under 21 CFR 175.300 forcing accelerated recoating cycles that convert capital expenditure into recurring subscription revenue.
For Market Incumbents: To counter water-based formulation performance gaps in high-acid fruit processing zones, prioritize R&D intensity in hybrid low-VOC systems that preserve chemical resistance while meeting California EPA thresholds. Deepen backward integration into amine hardener supply through captive production or long-term offtake agreements with coastal Chinese manufacturers to hedge logistics vulnerability. For New Entrants and Emerging Players: The mid-tier price-point gap between Sherwin-Williams bundled service contracts and regional distributor commodity offerings creates entry space for inspection-integrated coating supply targeting Wisconsin and Iowa dairy cooperatives. Penetrate through preventive maintenance subscription pilots that standardize surface-performance metrics across distributed plant networks, leveraging robotic spray application partnerships to differentiate from labor-dependent incumbent models. For Investors and Strategic Acquirers: Consolidation pressure builds where NSF certification timelines and dual-track EPA-Health Canada formulation requirements create scale advantages for multi-product coating portfolios. Acquisition targets with validated cold-storage epoxy formulations and established Midwest meatpacking corridor relationships present strongest viability over extended holding periods. Monitor California PFAS prohibition enforcement as signal for additive package reformulation investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amine Hardener Supply | Captive sourcing from coastal Chinese production clusters mitigates trans-Pacific logistics vulnerability for North American formulators. |
| Low-VOC Hybrid Formulation Launch | California EPA threshold compliance opens specification share in emission-restricted work windows without sacrificing cold-storage performance. |
| Preventive Maintenance Subscription Rollout | Guaranteed surface-performance contracts convert transactional coating sales into recurring revenue streams with FDA-inspected facilities. |
| Robotic Spray Application Partnership | Automated film thickness control in confined-space tank interiors reduces contractor exposure while generating audit-compliant quality documentation. |
| NSF Certification Fast-Track Investment | Accelerated toxicological review and formulation disclosure processes compress 12-18 month product launch timelines for direct food contact validation. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with coating formulator R&D directors, FDA compliance officers at meat and dairy processors, contractor application specialists, and national distribution network managers with secondary validation from EPA VOC rule filings, Health Canada PMRA registration databases, NSF certification directories, and customs trade data on epoxy resin imports. Bottom-up demand modeling across application segments triangulated against top-down market sizing from coating manufacturer revenue disclosures.
Historical reference periods anchored volume and value projections across the analysis window, with segmentation dimensions spanning product chemistry type, direct food contact validation tier, thermal exposure specification, and regional regulatory cluster. CAGRs derived from trend extrapolation of recoating cycle frequencies, cold-storage infrastructure build rates, and preventive maintenance contract penetration curves informed the modeling framework alongside feedstock price elasticity assumptions for bisphenol-A and amine hardener inputs.
The model assumes a particular technology adoption path for water-based and hybrid low-VOC formulations; alternative pathways for solvent-based system retention in high-acid processing zones would alter the outlook through extended premium pricing persistence. Forecasts reflect documented assumptions on regulatory enforcement intensity, raw material supply stability, and contractor labor availability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
United Arab Emirates (UAE) Paints and Coatings Market
Paints & Coatings
Water-Borne Latex Paints Market
Paints & Coatings
Paints and Coatings Market
Paints & Coatings
Europe Architectural Coatings Market
Paints & Coatings
Global Primer Market
Paints & Coatings
Europe Paints and Coatings Additives Market
Paints & Coatings
Saudi Arabia Paints and Coatings Market
Paints & Coatings
Global Paints and Coatings Fillers Market
Paints & Coatings
South America Architectural Coatings Market
Paints & Coatings
Paint Curing Lamp Market
Paints & Coatings
Europe Paints and Coatings Market
Paints & Coatings
Global Decorative Coatings Market
Paints & Coatings
Insulating Paints and Coatings Market
Paints & Coatings
Cement Paints Market
Paints & Coatings
Mosquito-Repellent Paints Market
Paints & Coatings
Global Wood Coatings Market