
 Global Specialty Zeolites Market | 2026-2036
Global Specialty Zeolites Market Size, Share, and Industry Trends Forecast 2026-2036
Global Specialty Zeolites Market Foresight
Multi-source procurement for high-purity zeolite feedstocks is shifting toward vertically integrated supply arrangements among top producers. Albemarle Corporation leverages captive bauxite and lithium processing assets to secure alumina supply chains for synthetic zeolite manufacturing. BASF SE sustains broad catalysis portfolios that anchor its zeolite R&D spending across Ludwigshafen and Antwerp production hubs. Clariant AG competes through specialized molecular sieve formulations tailored to natural gas dehydration and air separation units.
Specialty zeolites are synthetic or naturally occurring crystalline aluminosilicates with ordered microporous frameworks, typically featuring pore diameters between 0.3 and 2 nanometers and SiO₂/Al₂O₃ ratios that determine acidity and thermal stability; manufacturers employ hydrothermal crystallization or sol-gel methods to achieve controlled phase purity for catalytic cracking, selective adsorption, and ion-exchange separations. Microporous zeolites dominate volume consumption in fluid catalytic cracking units across petrochemical refining, while mesoporous variants capture expanding margin pools in pharmaceutical intermediate synthesis and fine chemical production. Powder and extrudate forms split demand between batch-process chemical applications and continuous-flow fixed-bed reactor systems.
The EPA enforces emissions thresholds that push refiners toward higher-activity zeolite catalysts to improve conversion efficiency and reduce hydrogen consumption per barrel processed. REACH registration requirements in Europe mandate full toxicological dossiers for synthetic zeolite imports, elevating compliance costs for non-EU suppliers. ECHA substance evaluation protocols increasingly scrutinize nano-scale zeolite particulates in consumer and agricultural applications. Stakeholders must monitor evolving classification debates around crystalline silica content and their implications for product labeling and occupational exposure limits.
Market Dynamics
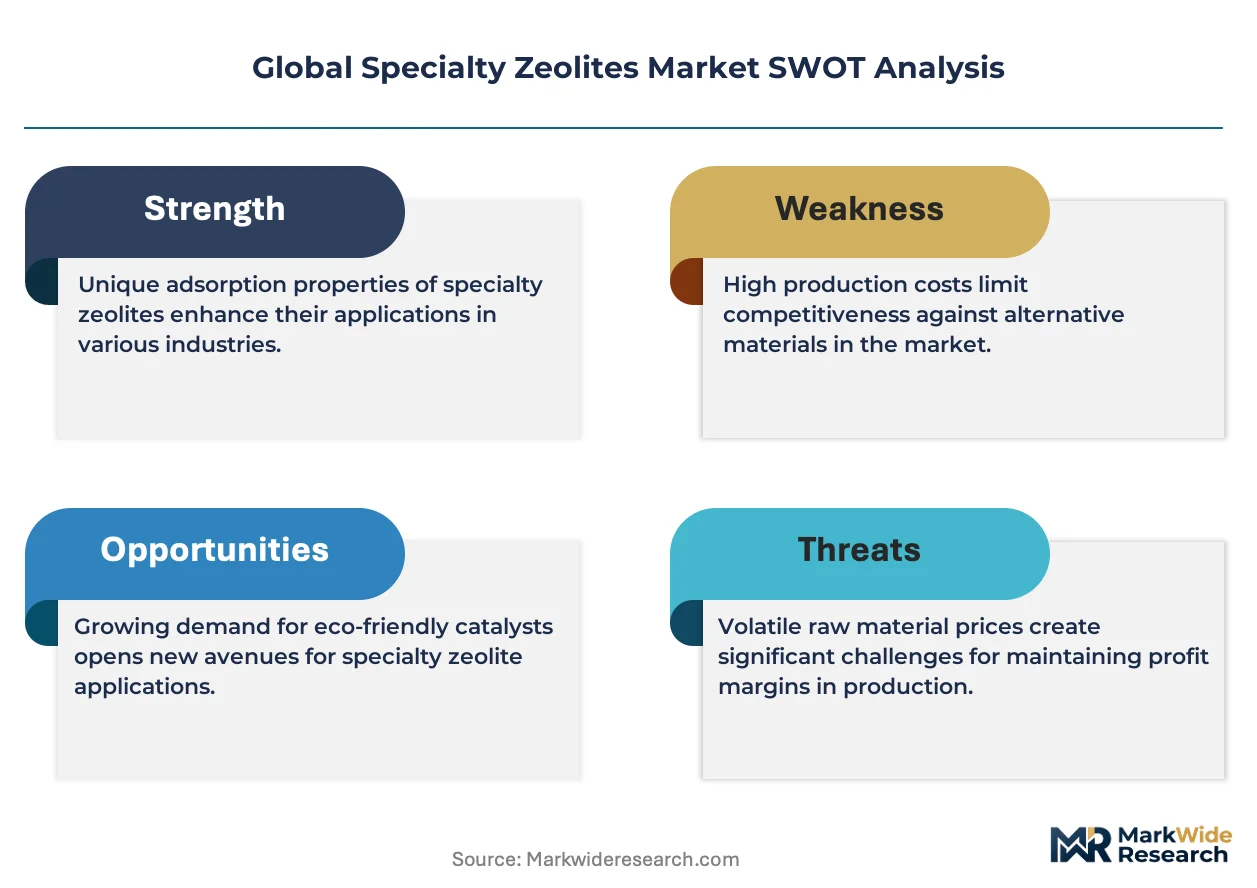
Refinery margins under EPA emissions thresholds are forcing catalyst replacement cycles toward higher-activity zeolite formulations, compressing the payback period for advanced molecular sieve investments across fluid catalytic cracking units.
Growth Catalysts
- REACH substance evaluation protocols:ECHA scrutiny of nano-scale zeolite particulates in consumer applications is accelerating demand for certified high-purity grades that command specification premiums from European formulators.
- Natural gas dehydration:Shale basins in the United States require molecular sieves with ultra-low dusting profiles to protect turbine integrity in expanding liquefaction train capacity.
- Hydrothermal crystallization advances:Continuous reactor designs from German equipment suppliers are reducing phase impurity defects that previously limited catalyst regeneration cycles.
Market Restraints
- Alumina supply concentration:Synthetic zeolite production depends on calcined alumina where Chinese bauxite processing controls marginal cost benchmarks, exposing non-integrated producers to input volatility.
- Silica gel substitution:Lower-cost amorphous desiccants capture volume in air separation pre-treatment where moisture specification tolerances permit non-crystalline alternatives.
- Energy intensity:Hydrothermal synthesis requires sustained thermal input that correlates directly with natural gas pricing, compressing margins for European manufacturers under EU ETS carbon cost pass-through.
Strategic Opportunities
- India petrochemical buildout:Reliance Industries and Indian Oil Corporation are expanding refinery complexity that requires specialty zeolite catalysts for residue upgrading units.
- Pharmaceutical chiral separations:Mesoporous zeolite variants with engineered pore mouth geometry are enabling enantiomeric resolution that silica-based stationary phases cannot achieve.
- EU Green Deal hydrogen mandates:Electrolyzer feed gas purification specifications are creating specification pull for molecular sieves with CO₂ breakthrough capacity below 1 ppm.
Industry Challenges
- Crystallographer talent scarcity:Zeolite structure solution requires specialized expertise in powder X-ray diffraction refinement that academic programs are not producing at replacement rates.
- REACH dossier maintenance:ECHA substance evaluation updates demand toxicological study renewals that consume 18-24 month compliance timelines for non-EU importers.
- Legacy fixed-bed reactor incompatibility:Next-generation hierarchical pore zeolites exhibit pressure drop characteristics that exceed design limits of 1980s-era refinery hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Specialty Zeolites Market |
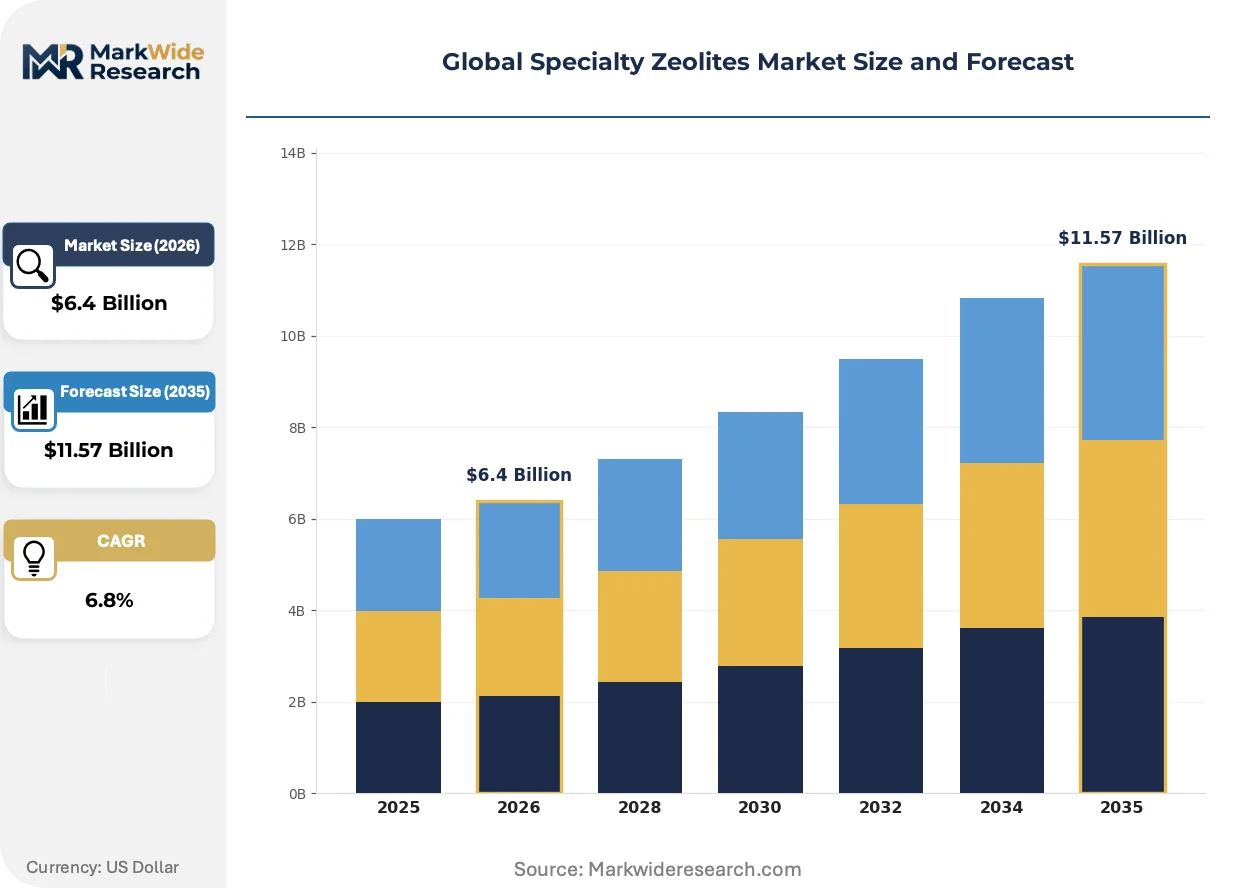
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $11.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microporous Zeolites, Mesoporous Zeolites, Layered Zeolites, Composite Zeolites, Nanocrystalline Zeolites Application: Adsorption, Catalysis, Ion Exchange, Gas Separation, Water Purification End User Industry: Chemical Processing, Petrochemical Refining, Environmental Protection, Agriculture, Animal Feed Form: Powder, Granules, Pellets, Extrudates, Beads |
| Companies Covered | Honeywell International Inc., BASF SE, Tosoh Corporation, Arkema S.A., Clariant AG, Zeochem AG, Zeolyst International, Albemarle Corporation, W. R. Grace & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Specialty Zeolites Market Shifts & Advancements
Zeolite innovation is pivoting from incremental acidity tuning toward architectural redesign of pore connectivity, with manufacturers competing on diffusion path length reduction rather than surface area metrics alone.
Core-shell zeolites with mesoporous silica coatings are electrifying FCC catalyst performance by shortening hydrocarbon residence time in micropore channels. Refiners in the US Gulf Coast are retrofitting units with these architectures to process heavier crudes without yield loss. The technology is compressing the performance gap between conventional Y-zeolites and expensive rare-earth stabilized alternatives.
EPA New Source Performance Standards for petroleum refineries are mandating lower combustion emissions that cascade into hydrogen consumption constraints. Refiners are responding by specifying higher-activity zeolite catalysts that improve conversion per pass and reduce recycle gas volumes. The regulation is reshaping catalyst procurement criteria toward hydrogen efficiency metrics rather than simple barrel throughput.
Long-term offtake agreements are displacing spot market purchasing for high-purity zeolite feedstocks as petrochemical operators seek supply security for multi-year refinery expansion projects. This contracting shift is concentrating procurement leverage among integrated producers with captive alumina assets. The pattern is most pronounced in Germany and the Netherlands where refinery margins are thinnest and input cost predictability carries premium value.
Global Specialty Zeolites Market Segmentation
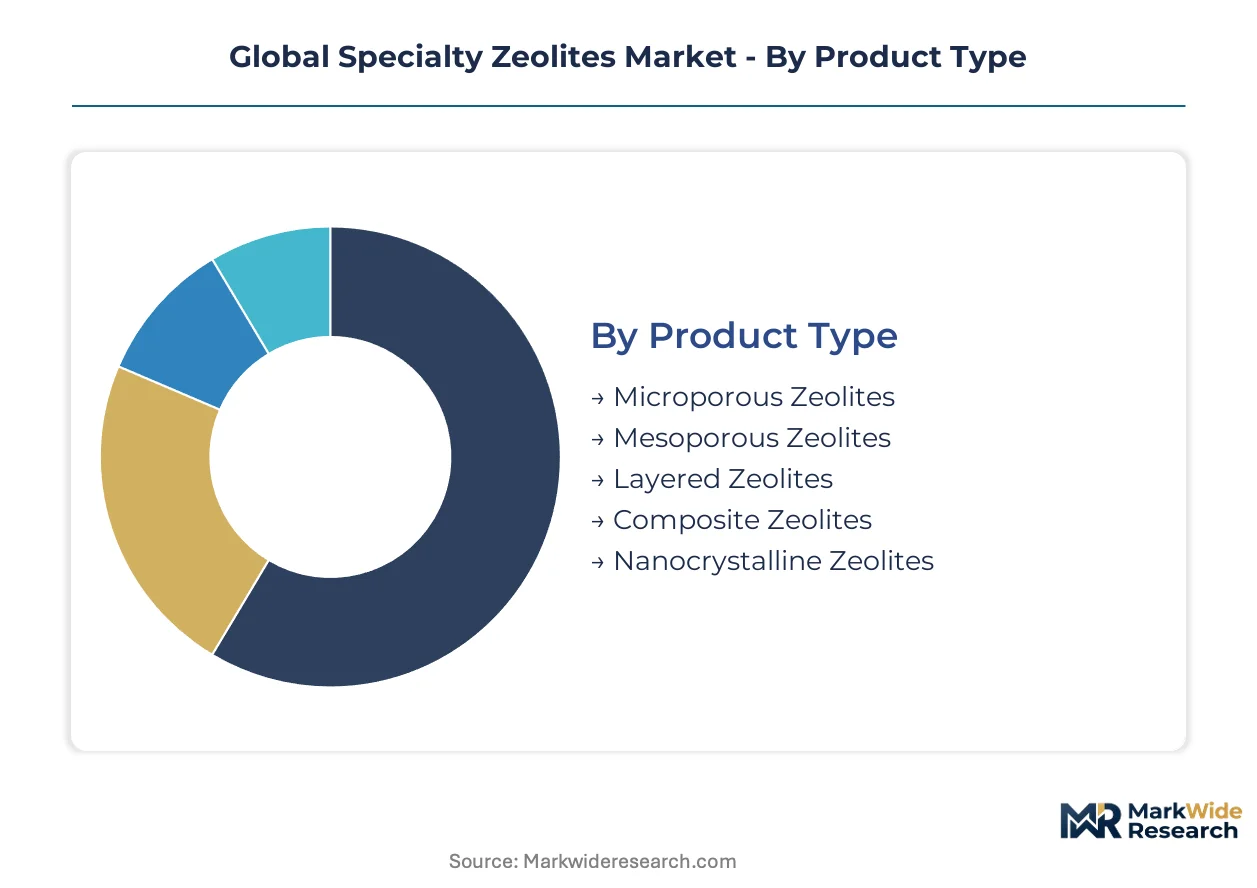
Specialty zeolite procurement patterns diverge sharply across structural categories. Pore architecture dictates performance specifications in catalytic applications, while physical form determines reactor compatibility and regeneration economics.
Product Type:
Purchasers in this category differentiate primarily by diffusion path length requirements and thermal stability thresholds.
- Microporous Zeolites:Crystalline frameworks with pore diameters below 2 nanometers dominate fluid catalytic cracking units in US Gulf Coast refineries. Hydrogen consumption efficiency under EPA New Source Performance Standards drives specification premiums for high-silica Y-zeolite variants.
- Mesoporous Zeolites:Engineered pore connectivity between 2 and 50 nanometers enables pharmaceutical intermediate synthesis and chiral separations. German fine chemical manufacturers specify hierarchical architectures to reduce pressure drop in legacy fixed-bed systems.
- Layered Zeolites:Two-dimensional sheet structures with tunable interlayer spacing suit ion-exchange membranes in Japanese water treatment installations.
- Composite Zeolites:Hybrid inorganic-organic frameworks combine zeolitic acidity with polymer flexibility for specialty adsorption in Chinese natural gas dehydration trains.
- Nanocrystalline Zeolites:Sub-100 nanometer crystal dimensions maximize external surface area for fast-adsorption air separation pre-treatment in Indian industrial gas facilities.
Microporous zeolites lead volumes today; mesoporous variants are gaining share fastest.
Application:
End-use specifications in this category split between continuous-flow industrial processes and batch chemical operations.
- Adsorption:Molecular sieves remove trace moisture and CO₂ from process streams. Shale gas processors in Texas require ultra-low dusting grades to protect liquefaction turbine integrity.
- Catalysis:Acidic sites in zeolite frameworks crack heavy hydrocarbons into lighter fractions. REACH-registered synthetic grades command specification premiums from European refiners facing ECHA substance evaluation protocols.
- Ion Exchange:Cation exchange capacity softens water and recovers heavy metals. Municipal utilities in Japan deploy clinoptilolite for radionuclide removal.
- Gas Separation:Kinetic diameter selectivity separates nitrogen from oxygen and linear from branched paraffins. Air separation units in Germany specify lithium-exchanged zeolites for oxygen enrichment.
- Water Purification:Ammonia and heavy metal capture in agricultural runoff. Chinese environmental regulations accelerate natural zeolite deployment in livestock wastewater treatment.
Catalysis anchors revenue concentration; gas separation is expanding most quickly.
End User Industry:
Customer maturity in this category ranges from specification-driven multinational refiners to price-sensitive agricultural distributors.
- Chemical Processing:Fine chemical and pharmaceutical manufacturers demand phase-pure synthetic grades with full toxicological dossiers. Swiss and German formulators pay certification premiums for ECHA-compliant imports.
- Petrochemical Refining:Integrated oil companies drive catalyst replacement cycles through refinery margin compression. US operators under EPA emissions thresholds specify higher-activity formulations to reduce hydrogen consumption.
- Environmental Protection:Remediation contractors and municipal utilities prioritize cost efficiency over performance margins. Natural zeolite deposits in Turkey and China supply volume demand.
- Agriculture:Soil amendment and slow-release fertilizer applications tolerate lower purity grades. Indian and Brazilian distributors negotiate on delivered cost per ton.
- Animal Feed:Mycotoxin binding in poultry and swine operations. EU feed additive regulations under EFSA guidance restrict nano-scale particulate content.
Petrochemical refining dominates procurement value; environmental protection is climbing the fastest.
Form:
Physical configuration in this category determines pressure drop characteristics and regeneration cycle economics.
- Powder:Fine particulates suit batch-process chemical synthesis and catalyst precursor manufacturing. BASF and Clariant compound powders into extruded catalysts at Ludwigshafen and Antwerp.
- Granules:Irregular particles for static bed applications with moderate mechanical stress. Natural gas dehydration units in the United States specify dust-resistant granule grades.
- Pellets:Uniform cylindrical shapes optimize packing density in pressure swing adsorption systems. Industrial gas suppliers in Germany standardize on 2-3 millimeter pellet dimensions.
- Extrudates:Continuous formed shapes with engineered porosity for fluid catalytic cracking. Albemarle manufactures rare-earth stabilized extrudates at captive alumina-integrated sites.
- Beads:Spherical forms minimize attrition in moving bed and slurry reactors. Petrochemical operators in India specify bead catalysts for residue upgrading units.
Extrudates command the highest unit values; beads are gaining adoption fastest in new-build capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping specialty zeolite production geography, with manufacturers relocating capacity to jurisdictions where REACH-equivalent compliance costs remain lower. The United States, Germany, China, India, and Japan concentrate both demand and supply-side investment.
United States
Shale gas liquefaction trains along the Gulf Coast drive molecular sieve consumption for ultra-low moisture specifications. EPA New Source Performance Standards tighten hydrogen efficiency requirements across refinery catalyst procurement. Houston and Port Arthur host the densest concentration of fluid catalytic cracking unit retrofits.
Germany
Ludwigshafen and Antwerp production hubs anchor European synthetic zeolite supply for REACH-registered catalysis grades. ECHA substance evaluation protocols elevate compliance timelines for nano-scale particulate imports. The country's industrial gas sector specifies lithium-exchanged zeolites for oxygen enrichment systems.
China
Petrochemical buildouts in Zhejiang and Jiangsu provinces expand residue upgrading capacity requiring specialty catalysts. The country's dual carbon goals pressure refiners toward higher-activity zeolite formulations. Captive bauxite processing controls marginal alumina cost benchmarks for regional manufacturers.
India
Reliance Industries and Indian Oil Corporation expand refinery complexity across Gujarat and Maharashtra. BIS standards for catalyst imports remain less stringent than REACH equivalents, attracting procurement interest. Mumbai and Jamnagar clusters concentrate new-build FCC unit installations.
Japan
Clinoptilolite deposits support municipal radionuclide removal applications in water treatment infrastructure. METI efficiency mandates push industrial gas suppliers toward optimized molecular sieve regeneration cycles. Osaka and Nagoya industrial corridors specialize in layered zeolite membrane fabrication.
Global Specialty Zeolites Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical-grade specialization and regional supply security. The market structure consolidates around integrated chemical conglomerates with captive alumina assets, while mid-scale specialists defend niche positions in natural gas dehydration. Three archetypes dominate: upstream-integrated refiners, application-focused formulators, and technology-licensing intermediaries. Capacity expansion and backward integration into bauxite processing represent the primary competitive vectors.
Among diversified chemical conglomerates, BASF SE and Clariant AG exemplify the integrated formulator archetype, combining captive R&D with multi-site production footprints. Albemarle Corporation anchors the upstream-integrated tier through control over alumina supply chains. These three entities represent distinct strategic postures: broad catalysis portfolio depth, specialized molecular sieve formulation, and raw material backward integration respectively.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| BASF SE |
| Tosoh Corporation |
| Arkema S.A. |
| Clariant AG |
| Zeochem AG |
| Zeolyst International |
| Albemarle Corporation |
| W. R. Grace & Co. |
| Others |
Supply & Pricing Matrix
Captive alumina production at Albemarle Corporation and BASF SE anchors both supply security and pricing power across synthetic zeolite manufacturing. These upstream-integrated producers command specification premiums from European refiners facing REACH compliance timelines while insulating margins from Chinese bauxite price volatility.
Pricing Analysis
Distributor margins compress as direct long-term offtake agreements displace spot purchasing for high-purity zeolite feedstocks. Contract-based long-term offtake dominates the pricing model, with differentiation driven by REACH certification grade and volume scale. Pricing pressure stems from silica gel substitution in air separation pre-treatment where moisture tolerances permit non-crystalline alternatives. Agricultural distributors in India and Brazil exhibit highest price sensitivity; Swiss pharmaceutical formulators show least.
Supply Chain Analysis
Freight costs for calcined alumina feedstocks escalate when Chinese bauxite processing disruptions reroute supply through Atlantic Basin ports. Synthetic zeolite production draws from alumina, sodium silicate, and rare-earth stabilizers concentrated in China, Germany, and the United States. Single-source vulnerability in Chinese bauxite processing exposes non-integrated producers to input volatility. Distribution runs through integrated chemical conglomerates with captive alumina assets and specialized molecular sieve formulators serving regional refinery clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty zeolite procurement functions as a geographic-arbitrage play where BIS standards in India attract procurement interest away from REACH-registered European supply, compressing compliance-cost differentials into pricing power.
For Market Incumbents: Lock in backward integration into bauxite processing or captive alumina supply to defend against Chinese marginal cost benchmarks. Secure REACH dossier maintenance capabilities to extend compliance timelines as ECHA substance evaluation protocols tighten. Capacity addition in Gujarat or Maharashtra refinery corridors captures Indian petrochemical buildout demand before standards converge. For New Entrants and Emerging Players: BIS standards in India open a window for specification-grade imports at certification discounts to REACH equivalents. Target pharmaceutical chiral separations where mesoporous zeolite architectures enable enantiomeric resolution silica phases cannot achieve. Pursue electrolyzer feed gas purification specifications under EU Green Deal hydrogen mandates as a go-to-market anchor. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale molecular sieve specialists because crystallographer talent scarcity limits organic R&D replication. Five-to-ten year viability hinges on backward integration depth and REACH registration portfolio breadth. Watch ECHA classification debates around crystalline silica content as an inflection signal for occupational exposure limit revisions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina | Captive bauxite processing at Albemarle insulates margin from Chinese price volatility. |
| REACH Dossier Expansion | ECHA-compliant registrations command specification premiums from European fine chemical formulators. |
| Core-Shell Zeolite R&D | Mesoporous silica coatings at US Gulf Coast retrofits compress rare-earth catalyst substitution economics. |
| India Refinery Cluster Partnership | Reliance Industries residue upgrading units require specialty catalyst supply security. |
| Pharmaceutical-Grade Certification | Swiss and German formulators pay premiums for phase-pure synthetic grades with toxicological dossiers. |
Research Methodology
Bottom-up petrochemical refining modeling reconciled against top-down alumina supply tracking forms the analytical core of this study. Primary interviews with catalyst procurement managers at integrated oil companies, technical R&D directors at molecular sieve formulators, and plant engineers at fluid catalytic cracking units combined with secondary validation from customs trade data, SEC 10-K filings, and ECHA registration databases. Triangulation across these sources ensures supply-side and demand-side estimates converge.
Input-output matrices map synthetic zeolite production capacity against refinery catalyst consumption across grade tier, end-use industry, and regional production hub dimensions. CAGRs derive from regression analysis of historical replacement cycle frequencies and projected petrochemical buildout timelines. Forecast inputs include EPA New Source Performance Standards compliance deadlines and EU ETS carbon cost pass-through assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under alumina supply disruption or REACH classification revision scenarios. Model assumptions reflect documented catalyst procurement patterns and hydrothermal synthesis energy intensity trends. A model refresh is warranted upon material change in ECHA nano-scale particulate classification protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Compounds Market
Specialty Compounds
Triallyl Isocyanurate Market
Specialty Compounds
North America Customized Premixes Market
Specialty Compounds
Polypropylene Compounds Market
Specialty Compounds
Conductive Plastic Compounds Market
Specialty Compounds
Global Powder Injection Molding (PIM) Market
Specialty Compounds
EPDM Sealing Strip Market
Specialty Compounds
Acetyl Serine Market
Specialty Compounds
Neohespiridine Market
Specialty Compounds
Organosulfur Compounds Market
Specialty Compounds
Lithium Compound Market
Specialty Compounds
US Non-Commercial Acrylic Paints Market
Specialty Compounds
Potassium Gluconate Market
Specialty Compounds
Thermoset Molding Compounds Market
Specialty Compounds
Methyl Anthranilate Market
Specialty Compounds
Automated Compound Storage and Retrieval (ACSR) Market