
 Expandable Microspheres Market | 2026-2036
Expandable Microspheres Market Size, Share, and Industry Trends Forecast 2026-2036
Expandable Microspheres Market Analysis
Single-source procurement for specialty polymer additives is restructuring into multi-source agreements as buyers seek supply security for expandable microspheres. Sekisui Chemical leverages captive acrylonitrile supply chains to anchor its position in Asia-Pacific thermoplastic formulations. Nouryon competes through controlled-release microsphere technology for high-performance coatings. Matsumoto Yushi-Seiyaku dominates Japan's domestic market with precision-engineered particle size distributions for automotive sealants.
Expandable microspheres are thermoplastic hollow particles, typically 10 to 50 micrometers in diameter, encapsulating a low-boiling hydrocarbon blowing agent that expands upon heating to create closed-cell foam structures. Their primary commercial purpose is density reduction and dimensional stability in manufactured goods without compromising surface finish or mechanical integrity. Polystyrene microspheres lead volume consumption in coatings applications where opacity and crack resistance command premium formulations. Polypropylene variants represent the fastest-growing product category, driven by automotive interior panels requiring heat resistance above 120 degrees Celsius. Chemical foaming technology retains the largest installed base, though physical foaming methods are gaining share in European packaging applications seeking elimination of residual blowing agent traces.
EPA regulations under the Toxic Substances Control Act restrict perfluorinated blowing agents, redirecting formulation development toward hydrocarbon-encapsulated alternatives. REACH registration requirements for polymer additives above one ton annually shape market access conditions for non-European suppliers. Japan's METI chemical substance reporting mandates create additional compliance layers for imported microsphere formulations. Stakeholders must monitor evolving flammability standards for automotive interior materials, as regulators in multiple jurisdictions tighten smoke density and toxicity thresholds that directly affect microsphere selection criteria.
Market Dynamics
Automotive lightweighting mandates in Germany and Japan are compressing formulation cycles for thermoplastic microspheres, forcing suppliers to reconcile heat resistance thresholds with volatile organic compound restrictions under REACH and EPA frameworks.
Growth Catalysts
- EPA Toxic Substances Control Act restrictions:Bans on perfluorinated blowing agents redirect R&D investment toward hydrocarbon-encapsulated microsphere architectures, opening substitution windows for compliant formulations.
- Automotive interior panels:Heat resistance requirements above 120 degrees Celsius in passenger compartments pull polypropylene microsphere adoption ahead of polystyrene alternatives in thermoplastic formulations.
- East Asian manufacturing clusters:China's coastal provinces and South Korea's petrochemical corridors concentrate demand density for density-reduction additives in consumer electronics housings.
Market Restraints
- Acrylonitrile supply concentration:Captive supply chains at major Asian producers create barriers for new entrants lacking backward integration into nitrile rubber feedstocks.
- REACH registration thresholds:Polymer additives above one ton annually trigger compliance costs that filter non-European suppliers from formulation partnerships with EU-based automotive Tier 1s.
- Chemical foaming agent residuals:Physical foaming methods eliminate trace contamination but require capital-intensive equipment retrofits that compress margins at mid-scale coating operations.
Strategic Opportunities
- European packaging applications:Elimination of residual blowing agent traces creates specification openings for physical foaming microspheres in food-contact and pharmaceutical barrier films.
- Japan METI chemical substance reporting:Import compliance layers disadvantage foreign suppliers, creating partnership opportunities for domestic formulators with established regulatory infrastructure.
- Controlled-release architectures:Convergence of microencapsulation technology with high-performance coating specifications enables premium pricing in aerospace and marine protective layers.
Industry Challenges
- Particle size distribution engineering:Precision tolerances for automotive sealant applications require specialized extrusion and classification equipment that locks smaller compounders out of OEM qualification programs.
- Flammability standard harmonization:Divergent smoke density and toxicity thresholds across NHTSA, ECE R118, and Japan's automotive safety regulations force parallel certification tracks that extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Expandable Microspheres Market |
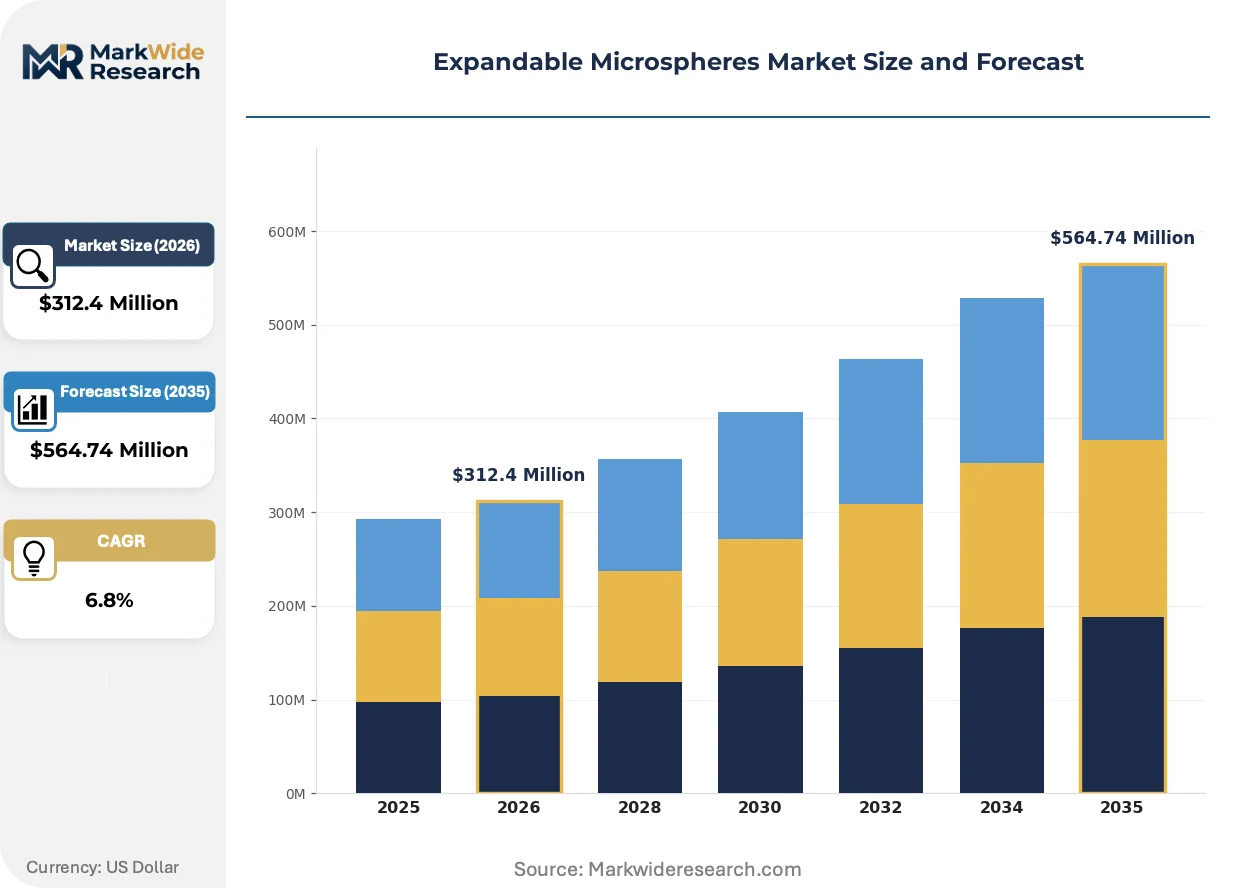
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polystyrene, Polypropylene, Phenolic, Others End User: Construction, Automotive, Packaging, Cosmetics Application: Coatings, Plastics, Adhesives, Insulation Technology: Chemical Foaming, Physical Foaming, Mechanical, Others |
| Companies Covered | Sekisui Chemical, AkzoNobel N.V., Nouryon, The Kish Company, Kumyang, Matsumoto Yushi-Seiyaku, Chase Corporation, Crerax, Kureha Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Expandable Microspheres Market Emerging Trajectories
Formulation chemistry and procurement architecture are shifting in parallel as buyers restructure supply agreements and regulators tighten encapsulant safety protocols across multiple jurisdictions.
Polypropylene microspheres are absorbing thermal load requirements previously assigned to denser mineral fillers in automotive interior applications. Tier 1 suppliers in Germany and Japan are qualifying these formulations for dashboard and door panel substrates under compressed development cycles. The technology is absorbing market share from conventional glass microbeads in weight-critical structural components.
REACH registration requirements for polymer additives are reshaping supplier qualification protocols for European automotive OEMs. Formulators must document substance volumes and hazard profiles above one-ton thresholds to maintain market access. Coating manufacturers in Italy and Spain are consolidating supplier bases to reduce compliance audit burdens.
Multi-source procurement agreements are displacing single-source contracts for specialty polymer additives as buyers seek supply security. Automotive compounders in South Korea and Germany are splitting volumes across two or three qualified microsphere suppliers. This pattern is most visible in thermoplastic formulations for electric vehicle battery housings where qualification timelines create switching friction.
Expandable Microspheres Market Segmentation
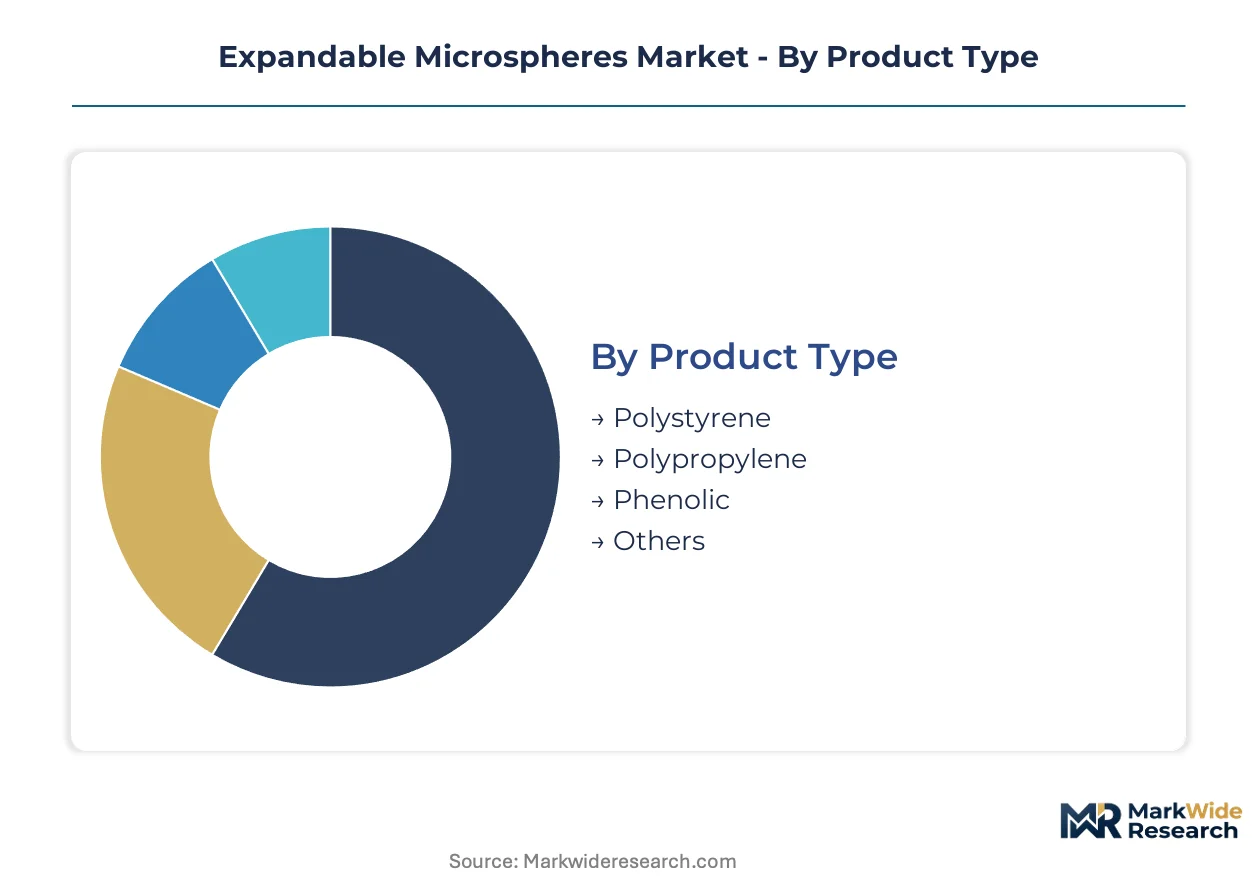
Segmentation in expandable microspheres reveals distinct performance envelopes across polymer chemistries and activation methods. Formulators select segments based on thermal thresholds, surface finish requirements, and regulatory constraints on residual blowing agents.
Product Type:
Standalone thermoplastic microspheres function as discrete density-reduction additives, while embedded variants integrate into masterbatch systems for compounder convenience.
- Polystyrene:These microspheres encapsulate isobutane or isopentane within styrene-acrylonitrile copolymer shells, expanding at 80–110 degrees Celsius. Coatings manufacturers in Germany specify polystyrene grades for crack-resistant architectural finishes where opacity and surface smoothness command premium formulations. REACH registration thresholds for styrene-based additives constrain supplier qualification timelines for non-European producers.
- Polypropylene:Polypropylene shells withstand processing temperatures exceeding 150 degrees Celsius, enabling direct incorporation into automotive interior substrates without thermal degradation. Japanese Tier 1 suppliers specify these grades for dashboard and door panel applications where heat resistance above 120 degrees Celsius is mandatory. The segment absorbs thermal load requirements previously assigned to denser mineral fillers.
- Phenolic:Phenolic microspheres deliver flame-retardant characteristics alongside density reduction, serving aerospace and marine protective coating specifications.
- Others:Specialty polymer variants including polyethylene terephthalate and polymethyl methacrylate address niche optical and barrier film applications.
Volume placements concentrate in polystyrene formulations; the faster expansion belongs to polypropylene microspheres.
End User:
Customer segments separate by qualification rigor, with automotive and aerospace demanding extensive OEM certification against construction and packaging's faster specification cycles.
- Construction:Cementitious and gypsum-based systems incorporate microspheres for thermal insulation and crack resistance in facade coatings. Italian and Spanish formulators specify expandable microspheres for lightweight render systems where Ecodesign compliance drives density reduction targets.
- Automotive:Interior panel substrates and sealant formulations absorb the majority of high-temperature polypropylene microsphere volumes. German OEMs compress development cycles for thermoplastic formulations under lightweighting mandates.
- Packaging:Food-contact and pharmaceutical barrier films specify physical foaming microspheres to eliminate residual blowing agent traces. European converters lead adoption where EFSA migration limits constrain chemical foaming alternatives.
- Cosmetics:Microsphere additives create texture and optical effects in color cosmetic formulations, with Japan's domestic suppliers dominating precision particle size requirements.
Automotive applications anchor premium pricing tiers; packaging segments climb the fastest on physical foaming substitution.
Application:
Application segments diverge by surface finish sensitivity and structural load requirements.
- Coatings:Architectural and industrial coatings represent the largest installed base, with opacity enhancement and crack resistance driving polystyrene microsphere adoption. German and Japanese automotive OEMs specify high-solids coating systems where microsphere additives reduce volatile organic compound emissions.
- Plastics:Thermoplastic compounding for automotive interior panels and consumer electronics housings absorbs heat-resistant polypropylene grades. South Korean petrochemical corridors concentrate compounding capacity for smartphone and tablet chassis applications.
- Adhesives:Pressure-sensitive and structural adhesive formulations leverage microspheres for gap-filling and stress distribution. Automotive sealant applications in Japan require precision-engineered particle size distributions.
- Insulation:Building thermal insulation systems specify phenolic microspheres for combined density reduction and fire resistance.
Coatings retain the largest volume footprint; plastics applications gain share fastest on automotive lightweighting.
Technology:
Technology segments separate by capital intensity and residual contamination profiles.
- Chemical Foaming:Hydrocarbon-encapsulated microspheres dominate current volumes, with established supply chains and lower equipment thresholds. EPA Toxic Substances Control Act restrictions on perfluorinated blowing agents redirect formulation development toward compliant hydrocarbon alternatives.
- Physical Foaming:Nitrogen or carbon dioxide expansion eliminates residual blowing agent traces, serving European packaging applications where EFSA migration limits apply. Capital-intensive equipment retrofits compress margins at mid-scale coating operations.
- Mechanical:Direct gas injection systems for high-volume extrusion operations offer precise density control in continuous processes.
- Others:Emerging supercritical fluid methods address pharmaceutical and medical device applications with stringent purity requirements.
Chemical foaming retains the dominant volume position; physical foaming methods expand most quickly in food-contact specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian manufacturing corridors concentrate the densest demand for expandable microspheres, with China's coastal provinces and South Korea's petrochemical belts absorbing the majority of volume placements for automotive and electronics applications.
China
Automotive lightweighting programs and consumer electronics manufacturing pull substantial microsphere volumes into Jiangsu and Zhejiang provinces. The Ministry of Ecology and Environment enforces dual carbon goals that restrict perfluorinated blowing agents in chemical foaming operations. Shanghai and Ningbo host compounding facilities serving electric vehicle battery housings where heat-resistant polypropylene grades dominate specifications.
Germany
Dashboard and door panel substrates for premium automotive OEMs absorb high-temperature polypropylene microsphere volumes across Baden-Württemberg and Bavaria. REACH registration thresholds above one ton annually filter non-European suppliers from Tier 1 formulation partnerships. The KBA coordinates with ECHA on flammability standard harmonization for interior materials, compressing qualification timelines for sealant applications.
Japan
Precision-engineered particle size distributions for automotive sealants concentrate demand in Aichi Prefecture and the broader Chubu industrial corridor. METI chemical substance reporting mandates create compliance layers that disadvantage imported formulations. Osaka-based compounders dominate domestic supply chains for thermoplastic microspheres in electric vehicle lightweighting programs.
South Korea
Smartphone and tablet chassis manufacturing in Gyeonggi Province drives consumption of heat-resistant microsphere additives for consumer electronics housings. The MFDS regulates residual blowing agent traces in food-contact applications, redirecting packaging converters toward physical foaming specifications. Ulsan's petrochemical complexes anchor backward integration into acrylonitrile feedstocks for captive microsphere production.
United States
Automotive interior panel specifications and aerospace protective coatings distribute demand across Michigan's manufacturing belt and Southern Tier automotive corridors. EPA Toxic Substances Control Act restrictions on perfluorinated blowing agents redirect formulation R&D toward hydrocarbon-encapsulated alternatives. Detroit-area compounders qualify multi-source procurement agreements to secure supply continuity for thermoplastic formulations.
Expandable Microspheres Market Vendor Landscape
Capacity expansion dominates the current landscape as established producers scale hydrocarbon-encapsulated microsphere output to capture substitution windows from banned perfluorinated alternatives. The vendor base separates into three tiers: integrated petrochemical conglomerates with captive feedstock positions, specialty additive houses with precision particle engineering capabilities, and regional compounders serving construction and packaging segments. Two strategic archetypes command attention—backward-integrated Asian producers leveraging acrylonitrile supply chains, and European formulators with REACH-registered portfolios for automotive qualification. Competitive intensity concentrates on multi-source procurement negotiations and qualification timeline compression for electric vehicle applications.
Among Japanese specialists, Matsumoto Yushi-Seiyaku Co., Ltd. and Kureha Corporation exemplify precision particle engineering archetypes with established domestic regulatory infrastructure. Sekisui Chemical Co., Ltd. anchors the integrated producer tier with captive supply chain advantages in acrylonitrile feedstocks. Nouryon occupies a position within the European specialty additive segment, representing controlled-release technology capabilities for high-performance coating specifications.
| Leading Market Players |
|---|
| Sekisui Chemical |
| AkzoNobel N.V. |
| Nouryon |
| The Kish Company |
| Kumyang |
| Matsumoto Yushi-Seiyaku |
| Chase Corporation |
| Crerax |
| Kureha Corporation |
| Others |
Supply Flow & Price Mechanics
Acrylonitrile feedstock costs cascade through three distinct pricing tiers for expandable microspheres, with captive supply chain control at Asian integrated producers enabling margin capture that contract-manufacturing compounders in Southern Europe cannot match. The path from nitrile rubber feedstock to automotive-qualified polypropylene grades concentrates pricing power among backward-integrated suppliers serving Germany and Japan's Tier 1 qualification programs.
Pricing Analysis
High-volume polystyrene microsphere contracts trade at compressed margins, while precision-engineered polypropylene grades for automotive interiors command premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered formulations from unregistered imports and commodity construction grades. Pricing pressure stems from multi-source procurement negotiations as buyers split volumes across qualified suppliers. Packaging converters exhibit highest price sensitivity due to physical foaming equipment retrofit costs, whereas aerospace coating specifications show lowest sensitivity given performance-critical applications.
Supply Chain Analysis
Specialized polymer engineering talent scarcity in Jiangsu and Zhejiang provinces constrains expansion timelines for microsphere production facilities serving electric vehicle battery housings. Manufacturing concentrates in China, Japan, and South Korea, with acrylonitrile monomer, hydrocarbon blowing agents, and precision extrusion equipment as critical inputs. Single-source vulnerability runs through Japanese producers dominating automotive sealant particle size specifications. Distribution runs through qualified masterbatch compounders before reaching Tier 1 automotive and electronics OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH registration thresholds above one ton annually erect compliance cost barriers that filter non-European suppliers, creating durable moats for registered incumbents serving German automotive OEMs. This cost-of-compliance dynamic rewards early investment in regulatory infrastructure.
For Market Incumbents: Extend REACH-registered formulation portfolios into electric vehicle battery housing applications before qualification timelines lock in supplier positions. Add polypropylene microsphere capacity in Baden-Württemberg to compress delivery lead times for German OEMs facing compressed development cycles. Capacity proximity to automotive clusters anchors multi-source procurement selections. For New Entrants and Emerging Players: Enter via physical foaming microsphere production for European food-contact packaging, where EFSA migration limits disadvantage incumbent chemical foaming suppliers lacking retrofit capital. Target Italian and Spanish coating formulators consolidating supplier bases to reduce REACH audit burdens. Partner with established masterbatch compounders to bypass direct OEM qualification timelines. For Investors and Strategic Acquirers: METI chemical substance reporting compliance infrastructure acquisition is the leading indicator that domestic Japanese formulators will capture import-replacement volume as regulatory layers deepen. Five-to-ten year viability hinges on captive acrylonitrile integration or precision particle engineering capabilities. Watch for multi-source procurement agreement announcements from South Korean automotive compounders as inflection signals for supplier consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylonitrile Feedstocks | Captive supply chains at Sekisui Chemical and Korean producers lock in margin capture against spot-market exposed competitors. |
| REACH Registration Investment | Documentation above one-ton thresholds enables qualification partnerships with EU-based automotive Tier 1 suppliers. |
| Physical Foaming Capacity Buildout | Elimination of residual blowing agent traces opens EFSA-compliant specifications for European pharmaceutical barrier films. |
| Precision Particle Size Engineering | Specialized extrusion capabilities qualify suppliers for Japanese automotive sealant applications requiring tight tolerances. |
| Multi-Source Procurement Agreements | Volume-splitting contracts with South Korean and German compounders secure supply continuity for electric vehicle programs. |
Methodological Framework
Trade flow databases, ECHA registration filings, and automotive supplier qualification records formed the secondary backbone, cross-referenced with primary interviews across plant managers at microsphere production facilities, procurement leads at German and Japanese Tier 1 automotive suppliers, distribution channel partners serving construction coating formulators, and technical R&D directors at specialty additive houses. Bottom-up volume builds from identified production capacity and utilization rates triangulated against top-down demand estimates from end-use consumption patterns.
Bottom-up modeling of polymer shell chemistry, activation temperature thresholds, and end-use qualification requirements converged with top-down macroeconomic drivers across the analysis window. Segmentation dimensions included polymer type, foaming technology, application surface finish sensitivity, and regional regulatory cluster. CAGRs derived from slope-intercept fitting of historical volume trajectories against projected lightweighting mandate compliance timelines and electric vehicle platform rollouts.
Revisions become necessary when EPA enforcement actions on residual blowing agents intensify, REACH registration thresholds expand to lower volume tiers, or automotive flammability standard harmonization accelerates parallel certification requirements. Material deviation in these triggers warrants pause and re-evaluation of supplier positioning assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Middle East and Africa Specialty Chemicals Market
Specialty Compounds
Metasulphite Market
Specialty Compounds
Asia-Pacific Collagen Market
Specialty Compounds
Gulf Collagen Market
Specialty Compounds
North America Polyphenylene Sulfide Compounds Market
Specialty Compounds
Propylene Trimer Market
Specialty Compounds
Strontium Nitrate Market
Specialty Compounds
Strontium Chloride Market
Specialty Compounds
Phenylacetyl Chloride Market
Specialty Compounds
Filler Masterbatch Market
Specialty Compounds
Nonene (Propylene Trimer) and Tetramer Market
Specialty Compounds
Specialty Sorbents Market
Specialty Compounds
Sodium Stannate Market
Specialty Compounds
Polypropylene Compounds Market
Specialty Compounds
Silicone Masterbatches Market
Specialty Compounds
Air-Laid Product Market