
 Asia-Pacific Chromatography Resins Market | 2026-2036
Asia-Pacific Chromatography Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Chromatography Resins Market Outlook
Protein A agarose is repositioning synthetic polymer matrices as the preferred capture medium for monoclonal antibody purification, compressing cost-per-gram targets for bioprocessors. KANEKA Corporation leverages its Japanese manufacturing base to supply high-purity agarose backbones across the region. Merck KGaA anchors its position through integrated resin and column hardware portfolios. Sunresin New Materials Co., Ltd. competes on cost-engineered ion exchange chemistries for domestic Chinese biopharma customers.
Chromatography resins comprise porous, functionalized particles—typically cross-linked agarose, synthetic copolymers, or silica—engineered with controlled pore size distributions between 50 and 400 nanometers and ligand densities optimized for target biomolecule selectivity. These materials separate, purify, and analyze complex biological mixtures in regulated manufacturing environments. Affinity resins, led by Protein A formats for antibody capture, command the dominant margin pool due to proprietary ligand chemistry and validation requirements. Ion exchange resins represent the highest volume category across bioprocessing workflows, while reversed-phase formats sustain specialized analytical and preparative applications in peptide and oligonucleotide purification.
China's NMPA enforces Good Manufacturing Practice standards for biologics that mandate validated purification processes, directly driving resin qualification documentation and supplier audit intensity. Japan's PMDA and South Korea's MFDS impose comparable bioprocessing material standards that restrict sourcing to audited resin manufacturers with established Drug Master Files. Stakeholders must monitor how China's SAMR implements evolving GB standards for biopharmaceutical raw materials, as these rules will determine which foreign and domestic resin suppliers retain market access.
Market Dynamics
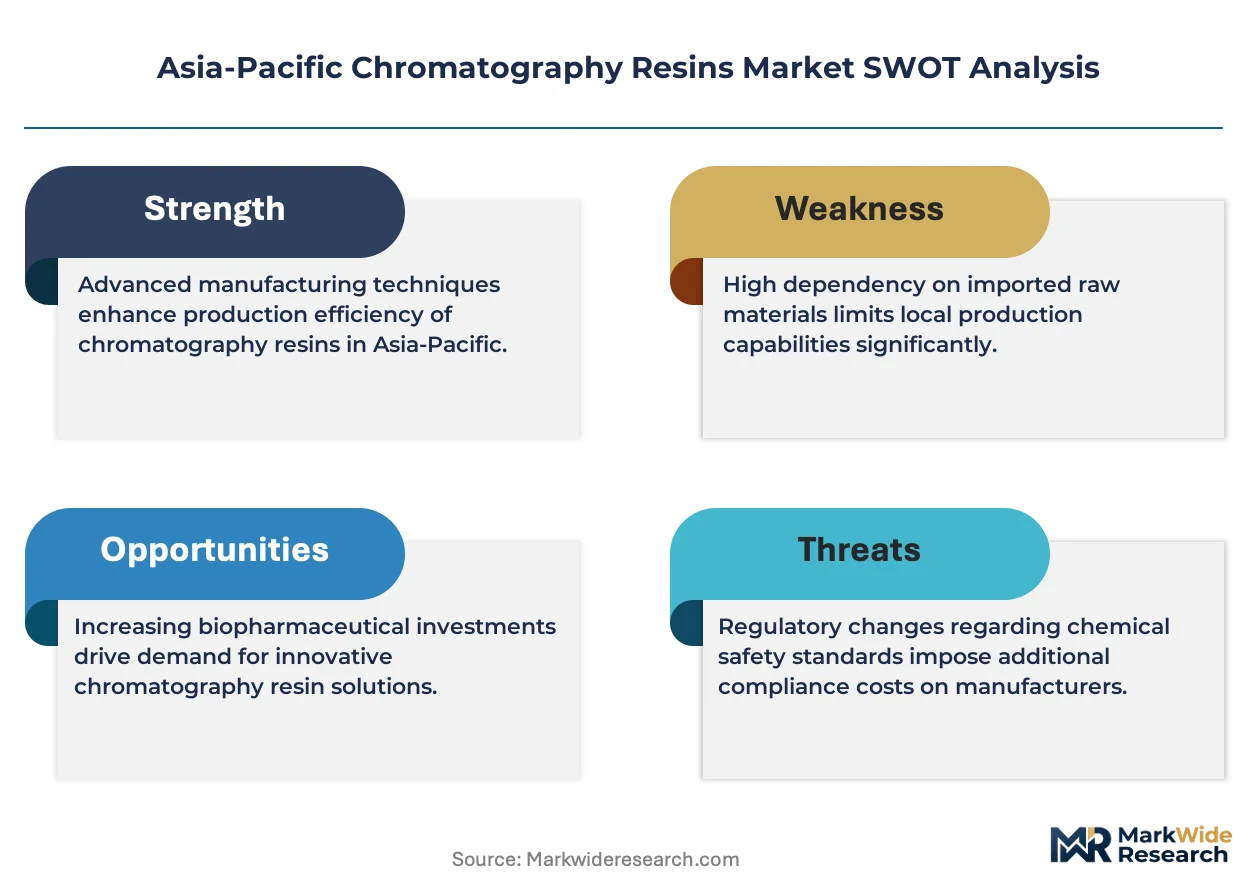
China's dual carbon goals and stricter environmental compliance standards are reshaping manufacturing requirements for resin producers, forcing capital reallocation toward cleaner production processes and validated supply chains.
Growth Catalysts
- Biopharmaceutical Purification Scale-Up:Monoclonal antibody production expansion across China's biologics manufacturing corridor spanning Shanghai and Suzhou drives captive purification capacity investments.
- NMPA GMP Enforcement:China's national pharmaceutical regulator mandates validated purification processes for biologics, directly driving resin qualification documentation and supplier audit intensity.
- Protein A Agarose Chemistry:Superior capture efficiency for antibody purification is compressing cost-per-gram targets and repositioning synthetic polymer matrices as secondary options.
Market Restraints
- Proprietary Ligand Cost Structure:Affinity resin chemistry patents held by concentrated Western suppliers create input cost volatility for downstream bioprocessors.
- Single-Source Agarose Dependency:High-purity agarose backbone supply concentrates in Japanese manufacturing bases, exposing buyers to geographic concentration risk.
- SAMR Raw Material Standards:China's evolving GB standards for biopharmaceutical raw materials create regulatory friction that threatens market access for unaudited foreign suppliers.
Strategic Opportunities
- Domestic Chinese Resin Manufacturing:Cost-engineered ion exchange chemistries from local producers address price sensitivity among domestic biopharma customers.
- Peptide and Oligonucleotide Purification:Reversed-phase formats sustain specialized analytical and preparative applications in emerging synthetic biology workflows.
- PMDA-MFDS Regulatory Alignment:Converging bioprocessing material standards between Japan and South Korea create cross-border qualification efficiencies for audited resin manufacturers.
Industry Challenges
- Drug Master File Compilation:Bioprocessors face extended certification timelines when qualifying new resin suppliers for regulated antibody production.
- Process Analytical Technology Integration:Legacy purification infrastructure requires capital-intensive retrofitting to accommodate continuous chromatography platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Chromatography Resins Market |
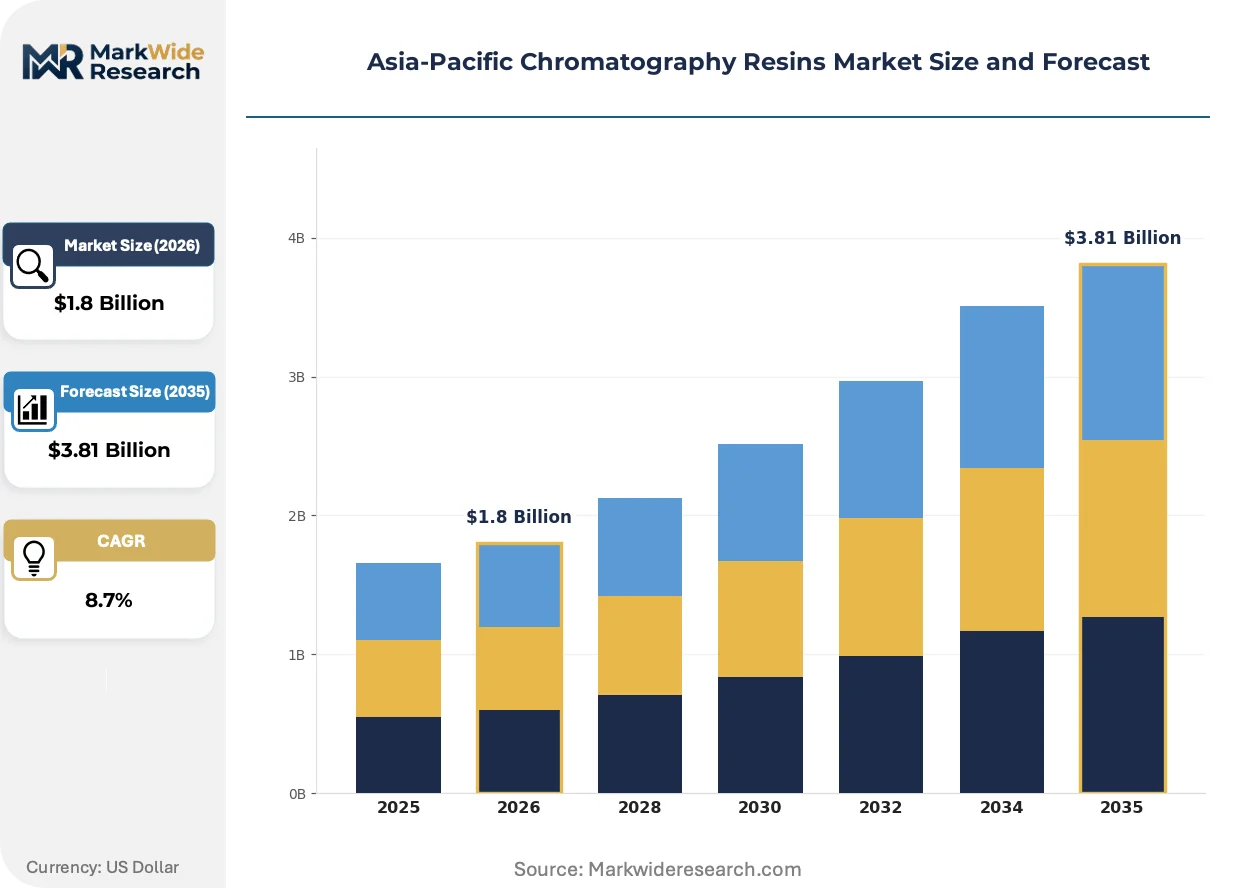
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ion Exchange Resins, Affinity Resins, Reversed-Phase Resins, Size Exclusion Resins Application: Pharmaceuticals, Biotechnology, Environmental Testing, Food & Beverage End User: Research Laboratories, Academic Institutions, Pharmaceutical Manufacturers, Contract Research Organizations Packaging Type: Bulk Bags, Bottles, Cartridges, Pouches |
| Companies Covered | KANEKA Corporation, Merck KGaA, Tosoh Corporation, Shimadzu Corporation, Thermo Fisher Scientific, Mitsubishi Chemical Corporation, Danaher Corporation, Qingdao Shenghan Chromatograph Technology Co., Ltd., Sunresin New Materials Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Chromatography Resins Market Strategic Shifts
Continuous processing platforms and single-use technologies are compressing batch cycle times while regulatory pressure on carbon intensity forces resin producers to reengineer manufacturing footprints.
Protein A agarose is consolidating its position as the dominant capture medium for monoclonal antibody purification. Bioprocessors across China's Shanghai-Suzhou corridor are adopting high-capacity formats at accelerated pace. This chemistry shift is consolidating margin pools around proprietary ligand suppliers while compressing synthetic polymer market share.
China's SAMR implementation of evolving GB standards for biopharmaceutical raw materials is tightening market access requirements. Foreign resin manufacturers must establish Drug Master Files and submit to intensified supplier audits. Domestic biologics producers are responding by dual-sourcing from audited global suppliers and emerging local qualifiers.
Bioprocessors are unbundling after-sales technical support from resin supply contracts and procuring validation services through specialized third-party consultancies. This channel disintermediation is most visible among mid-cap Chinese drugmakers building first-time antibody manufacturing capacity.
Asia-Pacific Chromatography Resins Market Segmentation
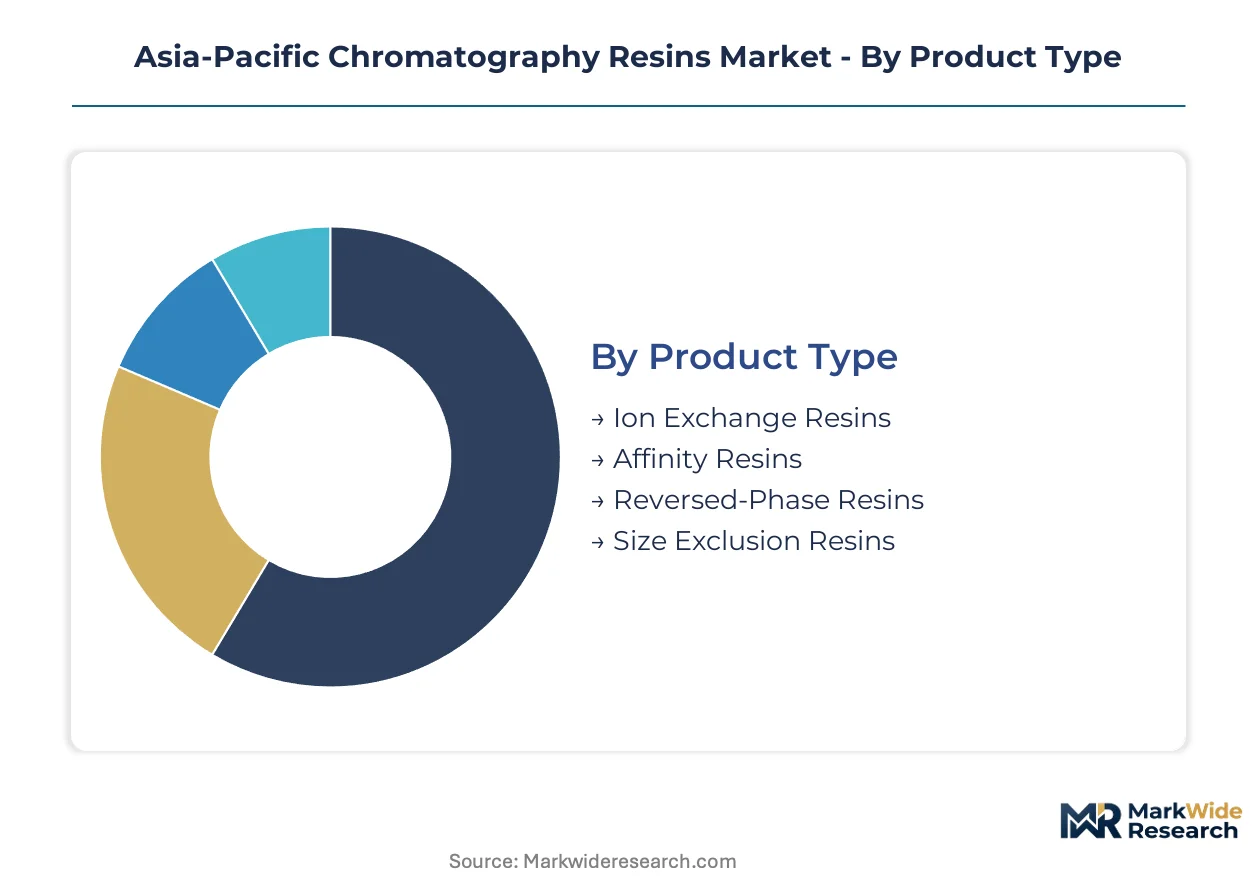
Segmentation in the Asia-Pacific chromatography resins market reveals how purification chemistry, application intensity, and procurement scale interact with NMPA, PMDA, and MFDS compliance requirements. Each dimension carries distinct certification burdens and margin structures that determine supplier positioning across the region.
Product Type:
Affinity resins demand the most intensive Drug Master File documentation under China's NMPA and Japan's PMDA, while ion exchange formats face lighter qualification thresholds but higher volume procurement scrutiny.
- Ion Exchange Resins:Functionalized with cationic or anionic ligands on cross-linked agarose or synthetic polymer matrices. Chinese pharmaceutical manufacturers in the Shanghai-Suzhou corridor are scaling captive ion exchange capacity for downstream polishing steps, driven by cost-per-gram compression targets in biosimilar production.
- Affinity Resins:Protein A agarose dominates antibody capture applications with proprietary ligand chemistries requiring validated supply chains. NMPA GMP enforcement and MFDS bioprocessing material standards restrict sourcing to audited manufacturers with established regulatory files, concentrating margin pools around Japanese and Western suppliers.
- Reversed-Phase Resins:Silica-based or polymer matrices with hydrophobic ligands for peptide and oligonucleotide purification.
- Size Exclusion Resins:Porous beads fractionating molecules by hydrodynamic volume for aggregate removal and buffer exchange.
Ion exchange resins sit at the top of the volume ranking, with affinity resins climbing the fastest as monoclonal antibody production scales across the region.
Application:
Pharmaceutical applications command premium pricing tiers tied to NMPA-validated processes, while environmental testing and food segments operate under lighter GB standard compliance.
- Pharmaceuticals:Monoclonal antibody purification, vaccine downstream processing, and plasma fractionation under strict NMPA, PMDA, and MFDS oversight. China's biologics manufacturing corridor is expanding captive capacity here, with domestic drugmakers dual-sourcing resins to mitigate supplier audit risk.
- Biotechnology:Cell and gene therapy vectors, recombinant proteins, and synthetic biology workflows. South Korean CDMOs are scaling continuous chromatography platforms for this segment, creating demand for high-capacity affinity and ion exchange formats.
- Environmental Testing:Water quality analysis and pollutant detection using reversed-phase and ion exchange chemistries.
- Food & Beverage:Contaminant screening, vitamin purification, and quality control applications with moderate regulatory intensity.
Pharmaceuticals generates the dominant revenue share, with biotechnology gaining share fastest on cell therapy manufacturing expansion.
End User:
Pharmaceutical manufacturers and contract research organizations drive qualification-heavy procurement with mandatory supplier audits, while academic laboratories operate with streamlined purchasing protocols.
- Research Laboratories:Discovery-stage purification and analytical method development. Japanese research institutes are adopting pre-packed cartridge formats to reduce resin handling complexity.
- Academic Institutions:Teaching and fundamental research applications with price-sensitive bulk purchasing patterns.
- Pharmaceutical Manufacturers:Commercial-scale bioprocessing under NMPA GMP and PMDA enforcement. China's domestic drugmakers are building first-time antibody capacity here, intensifying demand for validated resin supply with complete documentation packages.
- Contract Research Organizations:Flexible manufacturing services for biotech clients across the Asia-Pacific region. South Korean and Singaporean CDMOs are expanding multi-product facilities with platform purification processes.
Pharmaceutical manufacturers anchor procurement volume, with contract research organizations expanding most quickly on outsourcing trends.
Packaging Type:
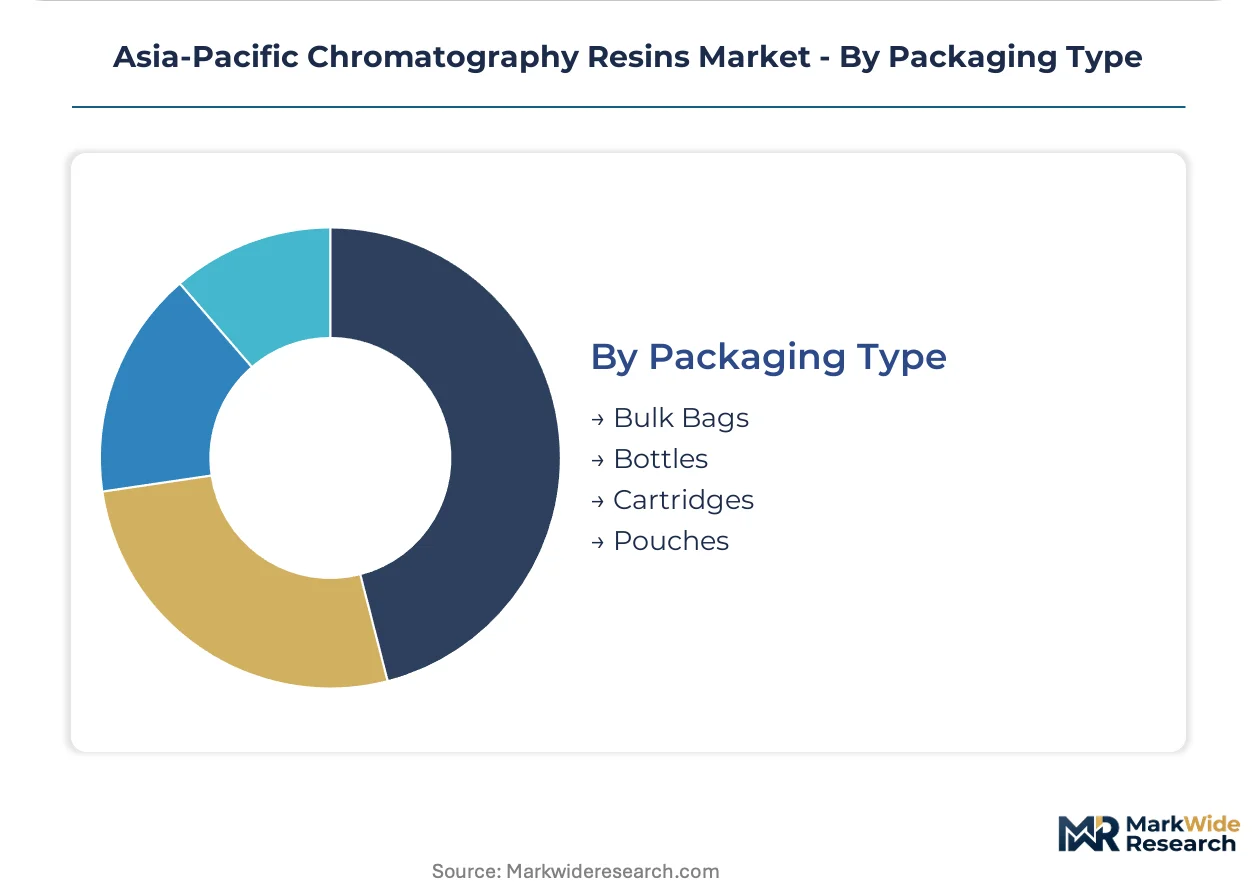
Cartridges and pre-packed columns reduce handling contamination risk for GMP-regulated bioprocessing, while bulk bags serve cost-optimized academic and environmental testing segments.
- Bulk Bags:Large-volume resin supply for industrial-scale purification and cost-sensitive applications. Chinese environmental testing labs favor this format for high-throughput screening workflows.
- Bottles:Standard laboratory packaging for research-scale method development and small-batch processing.
- Cartridges:Pre-packed, disposable formats eliminating cleaning validation requirements. NMPA-regulated bioprocessors in China's Shanghai-Suzhou corridor are accelerating adoption here to compress batch turnaround times and reduce cross-contamination risk.
- Pouches:Flexible single-use packaging for specialized applications and field-deployable testing equipment.
Cartridges are capturing share fastest on single-use bioprocessing adoption, with bulk bags retaining volume leadership in environmental and academic segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Suzhou biologics manufacturing corridor anchors regional demand for chromatography resins, with monoclonal antibody production scaling driving captive purification investments across Asia-Pacific markets. NMPA, PMDA, and MFDS regulatory enforcement shapes procurement patterns, concentrating supplier qualification activity in validated manufacturing clusters.
China
Domestic biopharma manufacturers in the Yangtze River Delta are expanding antibody production capacity at accelerated pace. NMPA GMP enforcement mandates validated Drug Master Files for resin suppliers, intensifying audit requirements for foreign and local producers alike. Shanghai's Zhangjiang Hi-Tech Park hosts the densest concentration of biologics manufacturing facilities, where domestic drugmakers are dual-sourcing resins to mitigate supplier qualification risk.
Japan
Japanese bioprocessors maintain stringent PMDA compliance standards that restrict resin sourcing to audited manufacturers with established regulatory files. KANEKA Corporation leverages domestic manufacturing bases to supply high-purity agarose backbones across the region. The Kanto region around Tokyo anchors precision biomanufacturing operations, where continuous chromatography platform adoption is compressing batch cycle times.
South Korea
MFDS bioprocessing material standards align with Japanese PMDA requirements, creating cross-border qualification efficiencies for audited resin suppliers. CDMOs in the Seoul Capital Area are scaling multi-product facilities with platform purification processes for cell and gene therapy vectors. Busan-Ulsan industrial complexes support bulk chemical production feeding downstream bioprocessing applications.
India
CDSCO oversight of biologics manufacturing is tightening documentation requirements for imported raw materials including chromatography resins. Maharashtra and Gujarat pharmaceutical clusters are expanding biosimilar production capacity, driving demand for cost-engineered ion exchange chemistries. Bangalore's biotechnology corridor attracts contract research organizations seeking flexible manufacturing services for global clients.
Singapore
The city-state's advanced manufacturing ecosystem supports regional headquarters for multinational bioprocessing suppliers seeking Asia-Pacific market access. Singapore's Economic Development Board incentives have attracted continuous processing technology providers establishing technical service centers. Tuas Biomedical Park concentrates biologics manufacturing investments from global drugmakers requiring validated resin supply chains.
Asia-Pacific Chromatography Resins Market Competitive Environment
Global majors compete with regional champions across technology tiers and regulatory qualification depth, creating a stratified supplier landscape. Western players dominate affinity resin chemistry through proprietary ligand portfolios, while Asian manufacturers capture ion exchange volume with cost-optimized offerings. Three archetypes define positioning: integrated life science conglomerates with hardware-software-resin portfolios; specialized agarose backbone producers with Japanese manufacturing heritage; and emerging Chinese cost-engineered chemistry specialists. Competitive moves concentrate on capacity expansion in validated manufacturing zones and strategic partnerships for continuous processing platform integration.
Among Japanese chemical conglomerates, KANEKA Corporation and Tosoh Corporation occupy positions anchored in domestic high-purity agarose production. Mitsubishi Chemical Corporation exemplifies diversified materials science players extending into bioprocessing applications. Merck KGaA represents integrated life science suppliers combining resin chemistries with column hardware and analytical instrumentation. Sunresin New Materials Co., Ltd. sits within the emerging tier of Chinese specialists competing on engineered ion exchange formats for domestic biopharma customers. These named entities illustrate how geographic manufacturing concentration and regulatory file depth determine competitive positioning across the region's NMPA, PMDA, and MFDS compliance environments.
| Leading Market Players |
|---|
| KANEKA Corporation |
| Merck KGaA |
| Tosoh Corporation |
| Shimadzu Corporation |
| Thermo Fisher Scientific |
| Mitsubishi Chemical Corporation |
| Danaher Corporation |
| Qingdao Shenghan Chromatograph Technology Co., Ltd. |
| Sunresin New Materials Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
High-purity agarose backbone costs flow from Japanese manufacturing bases through three-tier pricing structures separating NMPA-validated Protein A resins from standard ion exchange formats and economy-grade synthetic polymers, with bioprocessors in China's Shanghai-Suzhou corridor absorbing premium tiers for antibody capture while domestic drugmakers drive cost compression in polishing chemistries.
Pricing Analysis
Input-cost pass-through from proprietary ligand chemistry patents anchors contract-based long-term offtake agreements for affinity resins, while spot procurement dominates ion exchange volume. Price differentiation separates Drug Master File-validated tiers from unaudited alternatives, with certification level and after-sales technical support bundling as key drivers. Margins are tightening in synthetic polymer matrices as Protein A agarose displaces share in monoclonal antibody workflows. Domestic Chinese biopharma manufacturers exhibit highest price sensitivity, while multinational drugmakers in Singapore and Japan prioritize validated supply chains over unit cost.
Supply Chain Analysis
Regional distribution centers in Yokohama, Shanghai, and Singapore anchor hub-and-spoke patterns serving bioprocessors across the Asia-Pacific region. Manufacturing concentrates in Japan, China, and South Korea, with high-purity agarose production drawing from seaweed harvesting operations and synthetic polymer matrices resting on petrochemical feedstocks. Single-source vulnerability runs through Japanese agarose backbone supply, exposing buyers to geographic concentration risk. Distribution runs through direct technical service relationships for GMP-validated resins and distributor networks for research-grade materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific chromatography resins market functions as a stable compounder, with biopharmaceutical purification demand from monoclonal antibody production scaling providing durable revenue visibility across regulatory cycles.
For Market Incumbents: Deploy Drug Master File depth as a moat against emerging Chinese cost-engineered competitors by accelerating qualification documentation for NMPA, PMDA, and MFDS convergence. Anchor capacity in validated manufacturing zones near the Shanghai-Suzhou corridor to compress lead times for domestic biologics producers. Counter Sunresin's ion exchange pricing pressure with integrated resin-column hardware bundles that raise switching costs. For New Entrants and Emerging Players: Mid-cap Chinese drugmakers building first-time antibody capacity represent the most penetrable buyer archetype, as these manufacturers unbundle after-sales technical support from resin supply contracts and procure validation services through specialized third-party consultancies. Target peptide and oligonucleotide purification workflows in South Korean CDMOs where reversed-phase format demand outpaces established supplier coverage. Lead with pre-packed cartridge formats that eliminate cleaning validation requirements and compress batch turnaround times. For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory file depth concentrates margin pools around Japanese and Western incumbents while domestic Chinese specialists capture commoditized ion exchange volume. The market supports long-term viability for integrated life science conglomerates with hardware-software-resin portfolios and specialized agarose backbone producers with established PMDA compliance histories. Monitor SAMR implementation of evolving GB standards for biopharmaceutical raw materials as the inflection indicator determining which foreign suppliers retain market access versus face exclusion.| Strategic Initiative | Industry Significance |
|---|---|
| Drug Master File Expansion | NMPA-validated documentation secures access to China's Shanghai-Suzhou biologics corridor. |
| Continuous Processing Platform Integration | High-capacity affinity resin formats compress batch cycle times for monoclonal antibody manufacturers. |
| Backward Integration into Agarose Production | In-house seaweed processing secures high-purity backbone supply against Japanese geographic concentration. |
| Pre-Packed Cartridge Manufacturing Scale-Up | Single-use formats eliminate cleaning validation burdens for first-time Chinese antibody producers. |
| Regulatory Qualification Partnership | Third-party validation services capture disintermediated technical support spend from mid-cap biopharma. |
Study Parameters
Direct dialogue with bioprocess engineers, regulatory affairs managers at resin manufacturers, procurement leads at CDMOs, and quality assurance directors at domestic Chinese drugmakers grounded qualitative insights, cross-referenced with NMPA GMP guidance documents, PMDA bioprocessing material standards, MFDS regulatory filings, and customs trade data for chromatography resin imports, with bottom-up facility capacity assessments triangulated against top-down biologics production forecasts.
Segment-level revenue and volume trajectories across the projection horizon reflect modeled interactions between purification chemistry type, application intensity, and procurement scale, with CAGRs derived from regression analysis of historical biopharmaceutical capital expenditure patterns and monoclonal antibody pipeline progression rates through clinical stages.
Inputs from primary stakeholder interviews and disclosed regulatory filings were available through the study window; gaps in real-time CDSCO enforcement intensity and evolving SAMR GB standard implementation timelines introduce uncertainty bands around India and China demand forecasts. Stakeholders should weight assumptions against their own operating context and regulatory engagement history.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Plasma Powder Market
Specialty Compounds
Europe Microencapsulation Market
Specialty Compounds
Global Powder Injection Molding (PIM) Market
Specialty Compounds
Scratch-Resistant Compound Market
Specialty Compounds
Organoclay Market
Specialty Compounds
Superacids Market
Specialty Compounds
Metasulphite Market
Specialty Compounds
Global Specialty Zeolites Market
Specialty Compounds
Polypeptide Market
Specialty Compounds
Acetyl Tyrosine Market
Specialty Compounds
Propoxylates Market
Specialty Compounds
Potassium Gluconate Market
Specialty Compounds
Tosyl Chloride Market
Specialty Compounds
Potting Compound Market
Specialty Compounds
India Sealants Market
Specialty Compounds
Small Molecules Innovator Contract Development and Manufacturing Organization Market