
 Europe Microencapsulation Market | 2026-2036
Europe Microencapsulation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Microencapsulation Market Insights
German specialty chemical producers is broadening microencapsulation capacity for pharmaceutical and nutraceutical clients across the continent. BASF SE leverages its polymer science heritage to dominate complex-wall encapsulation for agrochemical and healthcare applications. Evonik Industries AG anchors high-value pharmaceutical delivery systems through advanced lipid and polymer matrix technologies. GAT Microencapsulation GmbH specializes in precision spray-congealing processes for food and beverage fortification clients.
Microencapsulation encloses active substances within protective shells measuring 1–1000 micrometres, typically employing biopolymers, lipids, or inorganic matrices to enable controlled release, taste masking, or environmental protection. The technique relies on coacervation, spray drying, or fluidized bed processes to achieve precise payload distribution and shell integrity. Spray drying technology leads volume throughput for food and nutraceutical applications due to scalable continuous processing and lower capital intensity. Coacervation commands premium positioning in pharmaceutical segments where exact release kinetics determine therapeutic efficacy and regulatory approval pathways.
EMA guidelines on bioequivalence and the EU Medical Device Regulation shape shell-material selection and validation protocols for drug delivery systems. REACH restricts certain synthetic polymers, redirecting R&D investment toward carbohydrate and lipid-based encapsulation matrices. The F-Gas Regulation and CSRD reporting obligations further constrain solvent-based manufacturing routes in European facilities. Stakeholders must monitor evolving ECHA substance evaluations and EMA quality guidance to anticipate material substitution timelines and compliance-driven reformulation cycles.
Market Dynamics
REACH substance restrictions and the EU Green Deal are forcing rapid substitution of petroleum-derived encapsulation polymers with bio-based alternatives, compressing reformulation cycles for pharmaceutical and agrochemical formulators across the continent.
Growth Catalysts
- Controlled-release pharmaceuticals:EMA bioequivalence guidelines incentivize microencapsulated active ingredients for precise therapeutic kinetics in German and French manufacturing clusters.
- EU F-Gas Regulation:Solvent phase-out mandates accelerate investment in aqueous and supercritical CO2 encapsulation processes for compliant European production.
- Nutraceutical fortification:Food manufacturers in Spain and Italy deploy spray-congealed vitamins and omega-3 oils to mask oxidation-prone flavors and extend shelf stability.
Market Restraints
- Specialized polymer supply concentration:High-purity shell materials for pharmaceutical-grade encapsulation originate from a narrow base of German and Swiss chemical suppliers, creating input vulnerability.
- Capital intensity of coacervation equipment:Precision fluid-handling systems for complex-wall formation require substantial upfront investment, limiting mid-scale facility expansion.
- Protein substitute threat:Advanced liposomal delivery systems for intravenous applications compete directly with polymer-based microcapsules in oncology and vaccine adjuvant segments.
Strategic Opportunities
- Eastern European manufacturing expansion:Poland and Czech Republic offer lower-cost production bases with improving logistics connectivity to Western European pharmaceutical distribution networks.
- CSRD reporting integration:Corporate sustainability disclosure mandates create demand for carbon-footprint-verified encapsulation services that quantify bio-based content and process emissions.
- Biopolymer-lipid hybrid matrices:Convergence of alginate-chitosan shells with phospholipid coatings enables dual-trigger release mechanisms for colon-targeted drug delivery applications.
Industry Challenges
- Formulation chemist scarcity:European universities produce insufficient graduates trained in encapsulation process engineering and scale-up validation, constraining R&D throughput.
- EMA quality guidance variability:Evolving documentation requirements for novel shell materials extend regulatory approval timelines by 18-36 months for first-in-class delivery systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Microencapsulation Market |
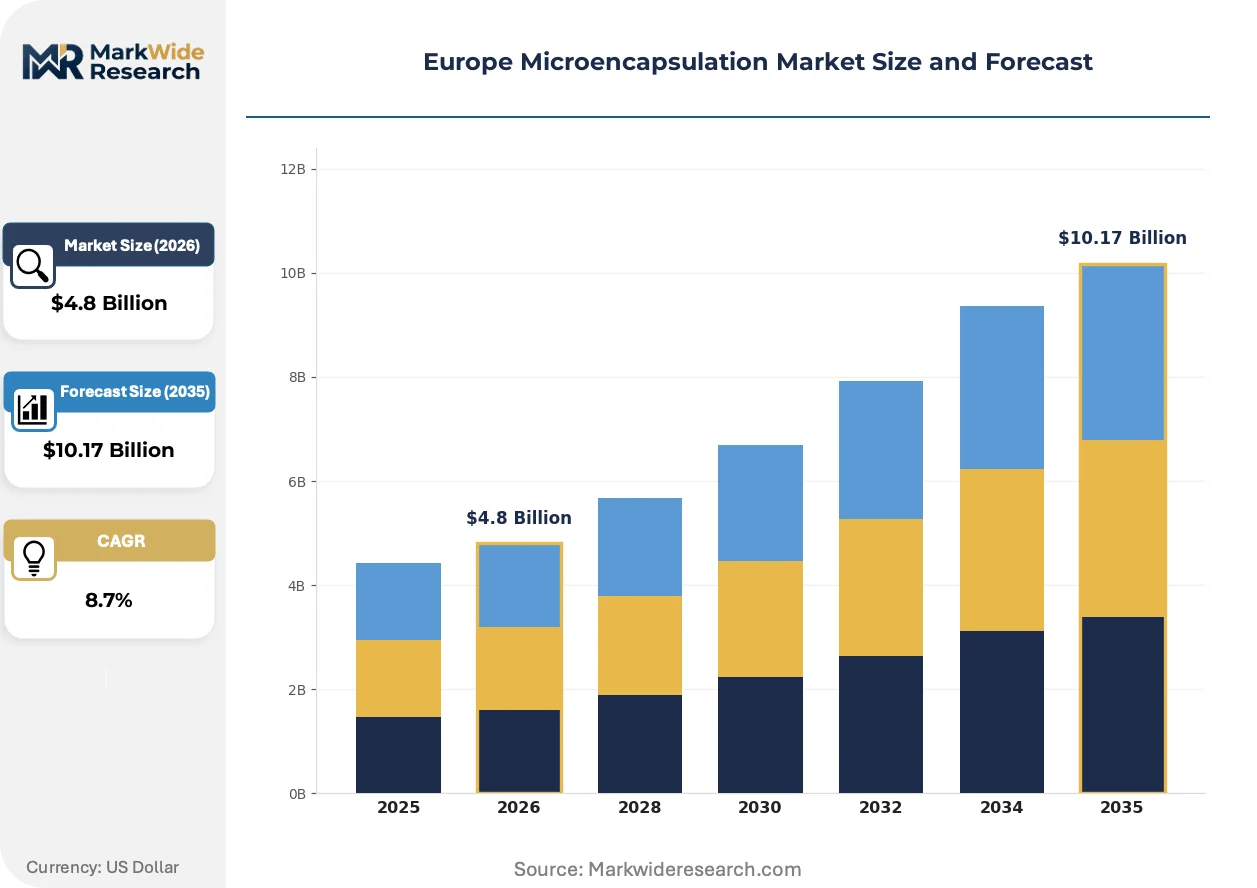
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymers, Lipids, Carbohydrates, Inorganic Materials Application: Pharmaceuticals, Food & Beverage, Cosmetics, Agriculture Technology: Spray Drying, Coacervation, Fluidized Bed, Electrospraying End User: Healthcare, Nutraceuticals, Consumer Goods, Agrochemical |
| Companies Covered | BASF SE, Evonik Industries AG, Balchem, AVEKA Group, GAT Microencapsulation GmbH, Capsulae, LycoRed Group, Bayer AG, Ronald T. Dodge Co., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Microencapsulation Market Trends and Innovations
Process intensification and closed-loop manufacturing systems are compressing batch cycle times while regulatory pressure on solvent emissions accelerates equipment replacement across European contract manufacturing facilities.
Electrospray encapsulation is automating droplet generation and shell formation through precision voltage-controlled nozzles that achieve sub-10-micrometre particle uniformity. Agrochemical formulators in the Netherlands and Belgium adopt these systems to replace conventional spray dryers for pesticide microcapsule production. The technology is automating quality control integration, reducing manual sampling and enabling real-time release testing that shortens batch certification timelines.
REACH Annex XIV authorization requirements for certain phthalate-based plasticizers redirect shell-material R&D toward citrate and adipate ester alternatives. Polymer suppliers in Germany reformulate existing encapsulation grades to maintain mechanical integrity while eliminating restricted substances. Pharmaceutical clients face accelerated validation protocols as ECHA substance evaluations advance, compressing the window for compliant material qualification.
Direct procurement relationships between nutraceutical brands and specialized encapsulation houses displace traditional distributor intermediaries in Southern European markets. Spanish and Italian food manufacturers now contract directly with German and Austrian toll manufacturers for custom vitamin and mineral premixes. This channel consolidation concentrates volume with fewer service providers, intensifying price negotiation leverage among large-scale buyers.
Europe Microencapsulation Market Segmentation
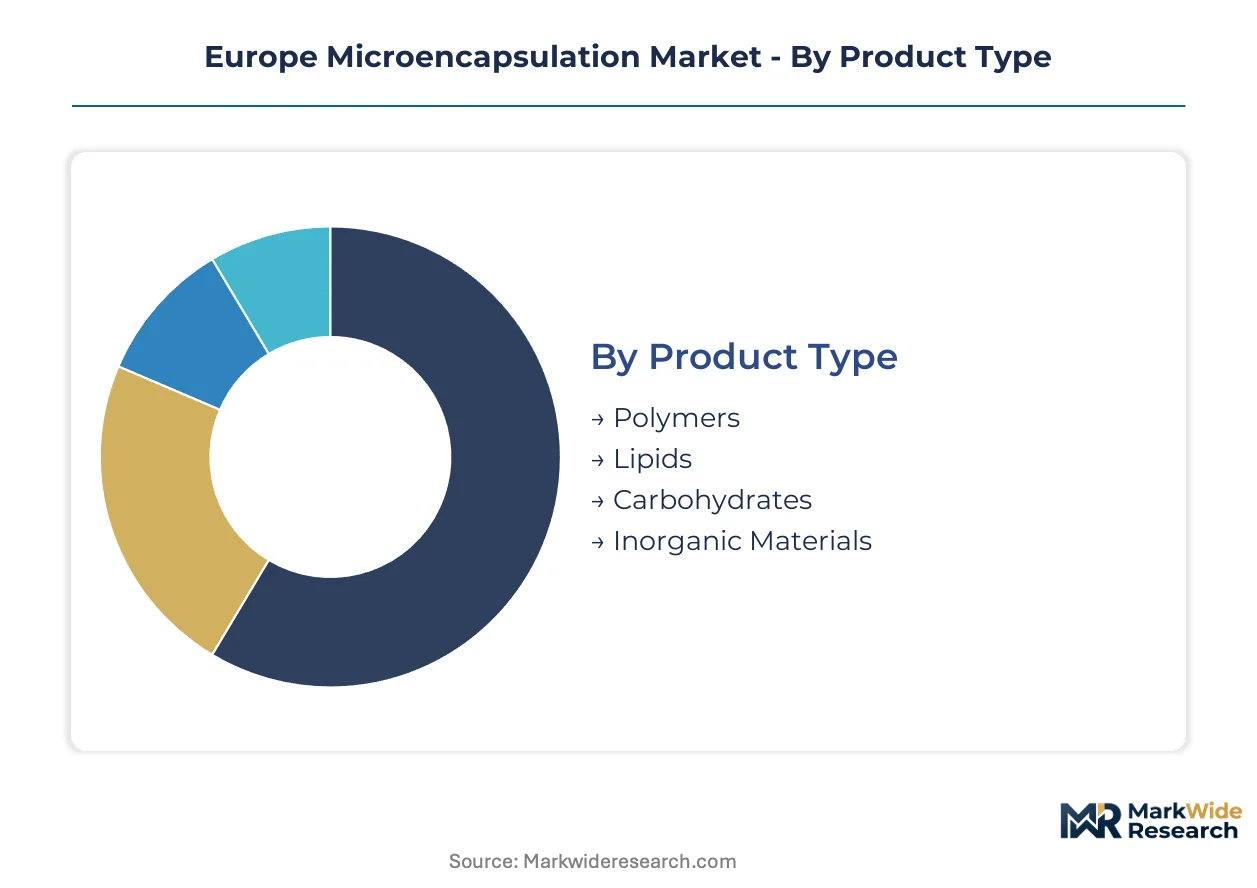
Microencapsulation markets fragment across material chemistry, process technology, and end-use specifications that determine shell integrity, release kinetics, and regulatory compliance pathways. Each segmentation axis carries distinct margin profiles and capital requirements that shape supplier positioning across European manufacturing clusters.
Product Type:
Shell material selection determines mechanical stability, biocompatibility, and biodegradation rates that dictate application eligibility under REACH and EMA frameworks.
- Polymers:Synthetic and semi-synthetic matrices including PLGA, ethyl cellulose, and polyvinyl alcohol dominate pharmaceutical controlled-release formulations requiring precise dissolution profiles. German chemical producers concentrate supply of pharmaceutical-grade polymer resins for EMA-compliant drug delivery systems facing REACH substance evaluation timelines.
- Lipids:Triglyceride, phospholipid, and wax-based shells enable gastric-resistant and lymphatic-targeting delivery mechanisms. French and Swiss formulators deploy lipid encapsulation for parenteral nutrition and vaccine adjuvants where polymer immunogenicity poses regulatory risks.
- Carbohydrates:Alginate, chitosan, and starch derivatives offer bio-based alternatives to petroleum-derived shells under EU Green Deal mandates.
- Inorganic Materials:Silica, calcium carbonate, and clay matrices provide thermal and oxidative stability for agrochemical and industrial catalyst applications.
Mature deployment sits with polymers. Newer deployment is concentrated in carbohydrates.
Application:
End-use sectors impose divergent validation burdens and batch size requirements that segment manufacturing infrastructure across the continent.
- Pharmaceuticals:Injectable and oral dosage forms requiring EMA bioequivalence documentation and GMP-certified production lines. Basel and Lyon manufacturing clusters anchor European capacity for complex-wall encapsulation of oncology APIs and biologics.
- Food & Beverage:Vitamin, mineral, and omega-3 fortification systems prioritize oxidative stability and taste masking over precision release kinetics. Italian and Spanish food manufacturers drive volume demand for spray-congealed nutritional premixes with extended shelf life.
- Cosmetics:Fragrance encapsulation and active ingredient protection for dermal delivery systems.
- Agriculture:Pesticide and fertilizer microcapsules enabling controlled environmental release and reduced application frequency.
Installed capacity concentrates in pharmaceuticals. Capacity expansion is climbing fastest in food and beverage.
Technology:
Process selection governs particle size distribution, payload efficiency, and solvent emissions that determine regulatory compliance and capital recovery timelines.
- Spray Drying:Continuous atomization and thermal dehydration of feed solutions achieves high throughput for food and nutraceutical powders. Austrian and German toll manufacturers operate scalable spray drying trains for vitamin and mineral premixes at lower capital intensity than pharmaceutical-grade alternatives.
- Coacervation:Phase separation of hydrocolloid solutions around active cores enables sub-micron shell thickness control for injectable pharmaceuticals. Swiss and German specialists command premium pricing for complex-wall systems serving EMA-regulated oncology and hormone therapies.
- Fluidized Bed:Air-suspension coating of solid particles with molten or dissolved shell materials.
- Electrospraying:Voltage-driven droplet generation achieving sub-10-micrometre uniformity for agrochemical and precision medicine applications.
Volume leadership belongs to spray drying. Technology investment is concentrating in electrospraying.
End User:
Customer category determines technical service intensity, validation documentation depth, and contract duration structures across European service providers.
- Healthcare:Hospital and clinical settings requiring sterile, pyrogen-free encapsulation for parenteral and implantable drug delivery. German and French pharmaceutical manufacturers specify healthcare-grade encapsulation for EMA-approved controlled-release injectables and implantable devices.
- Nutraceuticals:Dietary supplement brands demanding direct procurement relationships with toll manufacturers to displace distributor intermediaries. Spanish and Italian nutraceutical companies now contract German and Austrian encapsulation houses for custom vitamin premixes with verified bio-based content.
- Consumer Goods:Personal care and household product formulators.
- Agrochemical:Crop protection companies seeking environmental stability and controlled release for pesticide formulations.
Contract value concentrates with healthcare. Procurement velocity is accelerating fastest in nutraceuticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petroleum-derived polymer feedstocks from the Rhine-Ruhr chemical corridor supply shell-material precursors for pharmaceutical-grade encapsulation across the continent.
Germany
Controlled-release pharmaceutical demand from BASF SE and Evonik Industries AG drives complex-wall encapsulation investment. REACH substance evaluations force rapid reformulation of phthalate-based plasticizers toward citrate ester alternatives. The Basel-adjacent Baden-Württemberg cluster anchors EMA-compliant production lines for oncology drug delivery systems.
France
Lipid-based parenteral nutrition and vaccine adjuvant applications concentrate demand in Lyon and Paris-Saclay biotech corridors. ANSM quality guidance shapes validation protocols for sterile encapsulation processes. The Auvergne-Rhône-Alpes region hosts specialized formulators serving EMA-regulated hormone therapy markets.
Switzerland
Swissmedic oversight and proximity to Basel pharmaceutical headquarters position the country for high-value contract manufacturing. CSRD reporting obligations drive carbon-footprint verification for bio-based encapsulation services. The Basel-Stadt canton concentrates precision coacervation capacity for oncology API delivery.
Italy
Spray-congealed vitamin premix demand from nutraceutical brands accelerates direct procurement relationships with toll manufacturers. F-Gas Regulation compliance pressures solvent-based coating operations toward aqueous process conversion. The Emilia-Romagna food manufacturing belt drives volume growth for oxidation-stable omega-3 encapsulation.
Poland
Lower-cost production bases attract Western European pharmaceutical distribution contracts with improving logistics connectivity. EU Green Deal bio-based material mandates redirect R&D investment toward carbohydrate matrix development. The Warsaw-Łódź corridor emerging as a toll manufacturing hub for standard-grade nutraceutical encapsulation.
Europe Microencapsulation Market Competitive Landscape
Global majors compete with regional champions across technology specialization tiers, with polymer science conglomerates holding complex-wall pharmaceutical segments while mid-scale houses capture food and nutraceutical volumes. The vendor base stratifies into three archetypes: integrated chemical conglomerates with captive polymer supply, specialized encapsulation houses with process-specific expertise, and toll manufacturers serving brand-direct procurement relationships. Capacity expansion and strategic technology licensing represent the dominant competitive moves as EMA quality guidance tightens validation requirements.
Among German chemical conglomerates, BASF SE and Evonik Industries AG occupy positions as archetype anchors for polymer-science-based encapsulation, while GAT Microencapsulation GmbH exemplifies the specialized process house tier focused on precision spray-congealing applications. These three entities represent distinct strategic positioning vectors within the regional competitive structure.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Balchem |
| AVEKA Group |
| GAT Microencapsulation GmbH |
| Capsulae |
| LycoRed Group |
| Bayer AG |
| Ronald T. Dodge Co. |
| Others |
Pricing and Supply Chain Analysis
Electrospray encapsulation equipment adoption in the Netherlands and Belgium is compressing per-unit processing costs while concentrating manufacturing capability among toll houses capable of voltage-controlled precision. This technology transition simultaneously reduces batch certification timelines and raises capital barriers for mid-scale entrants, reshaping how pharmaceutical and agrochemical buyers negotiate contract terms across Western European clusters.
Pricing Analysis
Service bundling separates pharmaceutical-grade coacervation with EMA validation support from standard spray-drying with basic documentation. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity, with GMP-compliant complex-wall systems commanding substantial premiums over food-grade alternatives. Cost compression in standard nutraceutical encapsulation is intensifying because direct procurement relationships concentrate volume with fewer toll manufacturers. Food and beverage brands exhibit highest price sensitivity, while oncology drug developers prioritize release-kinetic precision over unit economics.
Supply Chain Analysis
EU Green Deal domestic-content mandates for bio-based shell materials are redirecting sourcing patterns toward European carbohydrate and lipid suppliers. Pharmaceutical-grade polymer precursors draw from German and Swiss chemical corridors, while phospholipid coatings feed from French and Dutch lipid processors. Single-source vulnerability concentrates in high-purity PLGA resins subject to REACH substance evaluation timelines. Distribution runs through direct brand-toll manufacturer contracts displacing traditional distributor intermediaries in Southern European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe Microencapsulation Market is transitioning from solvent-based coacervation to aqueous and supercritical CO2 processes as F-Gas Regulation compliance hardens. This technology replacement cycle favors suppliers with validated alternative platforms and disadvantages legacy equipment holders.
For Market Incumbents: Cement control over complex-wall pharmaceutical segments through captive biopolymer-lipid hybrid matrix development for colon-targeted delivery. Invest in backward integration into alginate and chitosan supply to secure bio-based content verification for CSRD reporting clients. Electrospray automation threatens conventional spray-drying margins; preemptive capacity conversion in Basel-adjacent facilities preserves pricing power.
For New Entrants and Emerging Players: REACH Annex XIV authorization timelines in Germany open a window for citrate ester plasticizer specialists to capture reformulation contracts from phthalate-dependent incumbents. Poland and Czech Republic toll manufacturing for standard-grade nutraceutical encapsulation offers lowest competitive density. Target direct procurement relationships with Spanish and Italian food manufacturers seeking carbon-footprint-verified omega-3 premixes.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to polymer science conglomerates seeking EMA-compliant delivery system capabilities. Mid-term viability rests on differentiation through regulatory validation depth rather than commodity scale. Watch EMA quality guidance publication schedules as inflection indicators for material substitution investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Coacervation Equipment Automation | Voltage-controlled electrospray systems reduce batch certification timelines for agrochemical clients in the Netherlands. |
| Biopolymer Matrix Development | Alginate-chitosan hybrid shells enable dual-trigger release mechanisms for colon-targeted drug delivery applications. |
| Backward Integration into Bio-based Feedstocks | Captive carbohydrate supply secures CSRD-verified carbon footprint claims for nutraceutical contract manufacturers. |
| Eastern European Capacity Expansion | Polish and Czech toll facilities capture Western European pharmaceutical distribution with lower operating cost bases. |
| Regulatory Validation Investment | EMA bioequivalence documentation capabilities differentiate complex-wall suppliers in oncology and hormone therapy segments. |
Research Methodology
Independent corroboration across formulation chemists at German and Swiss pharmaceutical manufacturers, procurement leads at Spanish and Italian food companies, and plant managers at Austrian toll houses underwrites the qualitative findings. Secondary validation draws from EMA quality guidance documents, ECHA substance evaluation registers, Cefic chemical industry reports, and customs trade data for encapsulation polymer imports. Bottom-up capacity estimates from individual manufacturing facilities triangulate against top-down demand projections from end-use sector consumption patterns.
Rate-of-change decomposition separates volume growth from price evolution across shell material chemistry, process technology, and end-use application dimensions. The analytical framework models pharmaceutical controlled-release, food fortification, and agrochemical delivery as distinct demand clusters with divergent regulatory compliance burdens. CAGRs derive from segmented trend extrapolation moderated by capacity constraint analysis and technology substitution elasticity estimates. Forecast inputs include REACH substance restriction timelines and EMA bioequivalence guidance evolution.
The model assumes a particular technology adoption path; alternative pathways for supercritical CO2 encapsulation would alter the outlook if equipment cost curves steepen faster than projected. Forecasts reflect assumptions about F-Gas Regulation enforcement intensity and ECHA evaluation acceleration that could compress material qualification windows. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Plasma Powder Market
Specialty Compounds
Microcapsules Market
Specialty Compounds
Air-Laid Product Market
Specialty Compounds
Acetyl Serine Market
Specialty Compounds
Film Dressing Market
Specialty Compounds
Global Customized Premixes Market
Specialty Compounds
Pneumatic Seal Market
Specialty Compounds
Global Engineering Plastic Compounds Market
Specialty Compounds
Potassium Derivatives Market
Specialty Compounds
Silicone Masterbatches Market
Specialty Compounds
Opacifiers Market
Specialty Compounds
Global Zinc Phosphate Market
Specialty Compounds
Thiocolchicoside Market
Specialty Compounds
Organosulfur Compounds Market
Specialty Compounds
3-Hydroxyphenyl Phosphinyl Propanoic Acid Market
Specialty Compounds
Arsenical Compounds Market