
 Vegetable Proteins Market | 2026-2036
Vegetable Proteins Market Size, Share, and Industry Trends Forecast 2026-2036
Vegetable Proteins Market Analytics
ISO 22000 certification is rotating as the decisive gate for suppliers seeking entry into European and North American branded food channels. Cargill Incorporated leverages its oilseed crushing footprint to secure upstream supply of soy and canola protein streams. Roquette Frères anchors its position through dedicated pea protein extraction facilities in France and Canada. Archer Daniels Midland competes via integrated carbohydrate and protein refining complexes across the US Midwest.
Vegetable proteins denote nitrogenous macromolecules extracted from legumes, oilseeds, and cereals through aqueous or mechanical fractionation, typically achieving protein content ranging from fifty percent in concentrates to ninety percent in isolates. These ingredients function primarily as functional replacers for animal-derived proteins in emulsified, gelled, or foamed food matrices. Soy protein isolate commands mature volume pools in beverage and meat-extension applications, while pea protein isolate captures accelerating share in allergen-free and non-GMO positioned products. Hydrolyzed vegetable proteins concentrate margin pools in savory flavor base and nutraceutical peptide segments where enzymatic processing creates differentiation.
The FDA governs protein quality claims through PDCAAS scoring requirements, while the EU enforces novel food authorization under EFSA guidelines for emerging sources such as hemp and insect-adjacent proteins. China's SAMR implements GB standards for plant protein beverage labeling that restrict amino acid fortification claims. Stakeholders must monitor divergence between US and EU protein quality metrics as this determines which fractionation investments unlock premium positioning versus commodity supply roles.
Market Dynamics
Protein quality scoring divergence between FDA PDCAAS requirements and EFSA novel food frameworks is forcing dual-track fractionation investments as suppliers seek premium positioning in both North American and European branded channels.
Growth Catalysts
- Clean-label ingredient mandates:Retailers across Germany and France are delisting artificial additives, redirecting formulation spend toward minimally processed pea and fava protein concentrates.
- FDA protein quality labeling:Updated PDCAAS scoring requirements are accelerating isolate procurement for beverage fortification claims in the US sports nutrition segment.
- Extrusion technology maturation:High-moisture extrusion lines in China and Brazil are closing the textural gap between plant-based and animal muscle proteins.
Market Restraints
- Input cost volatility:Yellow pea prices swing with Canadian prairie drought cycles, compressing margin predictability for isolate producers.
- Supply concentration risk:Over half of global soy protein isolate capacity sits within US Midwest crushing complexes, creating single-point vulnerability.
- Regulatory friction:China's SAMR GB standards restrict amino acid fortification claims, blocking premium positioning for fortified plant beverages.
Strategic Opportunities
- Underpenetrated bakery applications:Egg replacement in European laminated doughs remains underdeveloped as functional protein suppliers target this white space.
- EU Green Deal procurement:Public sector foodservice tenders in France and the Netherlands now mandate carbon footprint disclosures, advantaging regional pulse processors.
- Precision fermentation convergence:Hybrid formulations combining extracted isolates with fermentation-derived proteins are opening novel texture profiles for alt-seafood.
Industry Challenges
- ISO 22000 certification timelines:European branded channels demand 12-18 month audit cycles that strain mid-tier supplier cash conversion.
- Extrusion operator scarcity:High-moisture extrusion requires specialized rheology expertise that outpaces vocational training pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegetable Proteins Market |
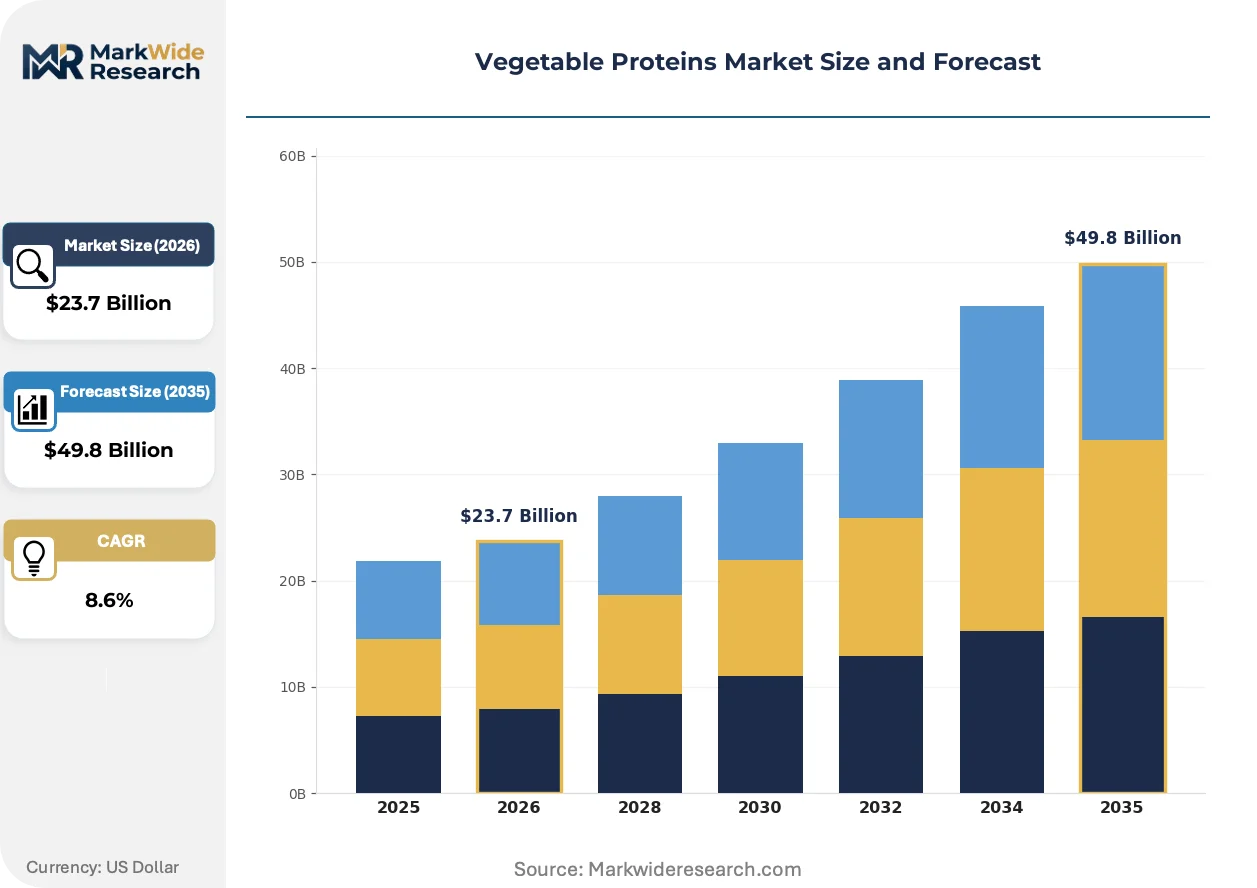
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pea Protein, Soy Protein, Rice Protein, Hemp Protein End Use Industry: Food & Beverages, Animal Feed, Nutraceuticals, Cosmetics Form: Concentrate, Isolate, Textured, Hydrolyzed Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland, Roquette Frères, Ingredion Incorporated, International Flavors & Fragrances, Bunge Limited, Kerry Group, The Scoular Company, Wilmar International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegetable Proteins Market Evolving Landscape
Fractionation technology advances and regulatory quality frameworks are compressing commodity-isolate margins while opening premium tiers for certified, traceable, and functionally differentiated protein ingredients.
Membrane filtration cascades for pea protein extraction are fragmenting the competitive landscape. Mid-sized processors in Canada and France are deploying ceramic microfiltration to bypass traditional acid-precipitation steps, cutting water intensity by half. This technology is fragmenting volume concentration among regional players previously locked out of isolate-grade supply.
EFSA novel food authorization requirements for emerging protein sources are tightening market entry pathways. Hemp and single-cell proteins now face 18-24 month safety assessment windows that favor established dossier compilers. European alt-dairy startups are responding by pivoting toward already-authorized soy and pea bases rather than pioneering novel sources.
Direct-procurement relationships between ingredient suppliers and foodservice operators are shortening traditional distribution chains. Large European bakery and meat-processing groups are signing multi-year offtake agreements with French and Dutch fractionators, bypassing ingredient distributors. This pattern is most visible in Germany's industrial bakery sector where cost transparency pressures are disintermediating legacy traders.
Vegetable Proteins Market Segmentation
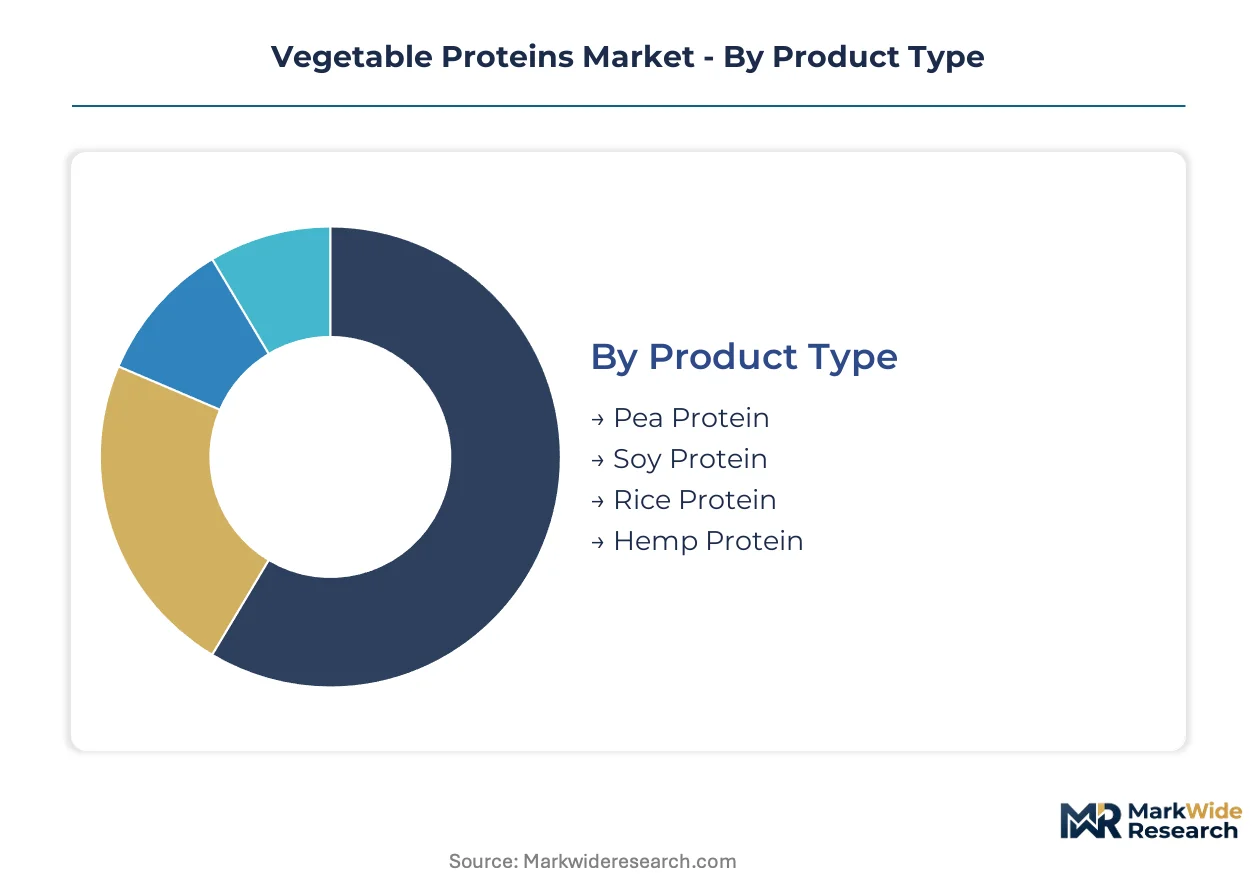
Segmentation in vegetable proteins reveals how extraction technology and end-use specifications create divergent margin structures. Buyers select protein grades based on functional requirements rather than commodity pricing, fragmenting procurement patterns across isolate, concentrate, and hydrolyzed tiers.
Product Type:
Soy protein faces the strongest substitution pressure from pea and emerging pulse proteins as allergen-free positioning gains formulation priority.
- Pea Protein:Yellow and green pea isolates achieve 80-90% protein content through wet fractionation and membrane filtration. German and Dutch alt-dairy formulators are accelerating procurement of non-GMO pea isolates to meet EU Green Deal carbon disclosure mandates.
- Soy Protein:Defatted soybean flakes yield isolates, concentrates, and textured forms through aqueous extraction. US Midwest crushing complexes supply mature volume pools for beverage fortification, though PDCAAS scoring requirements are tightening quality thresholds for premium positioning.
- Rice Protein:Brown rice protein concentrates at 70-80% content serve hypoallergenic nutrition applications where soy and pea trigger sensitivities.
- Hemp Protein:Cold-pressed hemp seed cake retains fiber and omega fatty acids alongside 50% protein content in minimally processed formats.
Soy protein retains volume leadership; pea protein holds the steepest expansion curve.
End Use Industry:
Cost tier stratification separates commodity feed applications from pharmaceutical-grade nutraceutical specifications.
- Food & Beverages:Meat extenders, dairy alternatives, and sports nutrition beverages drive isolate demand where emulsification and gelation properties determine formulation suitability. Chinese processors are scaling high-moisture extrusion lines to close textural gaps in plant-based meat.
- Nutraceuticals:Hydrolyzed vegetable proteins deliver bioactive peptides for functional food and supplement applications where enzymatic processing creates differentiation through specific molecular weight fractions.
- Animal Feed:Soy and canola meal concentrates serve aquaculture and livestock rations at lower protein specifications than human-grade isolates.
- Cosmetics:Rice and hemp protein hydrolysates enter hair and skin conditioning formulations where film-forming properties replace synthetic polymers.
Food and beverage applications dominate procurement volume; nutraceuticals command the highest per-kilogram pricing tier.
Form:
Application requirements determine whether processors target concentrate economics or isolate purity premiums.
- Isolate:90% protein content through isoelectric precipitation and membrane filtration enables neutral flavor profiles for beverage fortification. FDA PDCAAS scoring requirements are redirecting US sports nutrition procurement toward isolate grades that qualify for complete protein claims.
- Concentrate:50-70% protein content retains native fiber and carbohydrate fractions for bakery and meat-extension applications where cost sensitivity exceeds functional purity demands.
- Textured:Thermoplastic extrusion of soy and pea concentrates creates fibrous structures for plant-based meat analogs.
- Hydrolyzed:Enzymatic cleavage reduces molecular weight for savory flavor bases and rapid-absorption peptide formulations.
Isolate commands the premium pricing tier; textured forms are expanding most quickly through alt-meat capacity additions.
Distribution Channel:
Customer type fragmentation separates bulk industrial procurement from branded retail positioning.
- Direct Sales:Multi-year offtake agreements between fractionators and European industrial bakery or meat-processing groups are disintermediating legacy ingredient distributors. German bakery chains now negotiate volume contracts directly with Dutch pea protein processors.
- Supermarkets:Packaged protein powders and fortified foods reach consumers through conventional grocery retail where clean-label positioning drives shelf placement decisions.
- Online Retail:Direct-to-consumer sports nutrition brands bypass traditional wholesale tiers through subscription models and performance marketing.
- Health Stores:Specialty retailers curate organic and non-GMO certified proteins for allergen-conscious and lifestyle-positioned buyers.
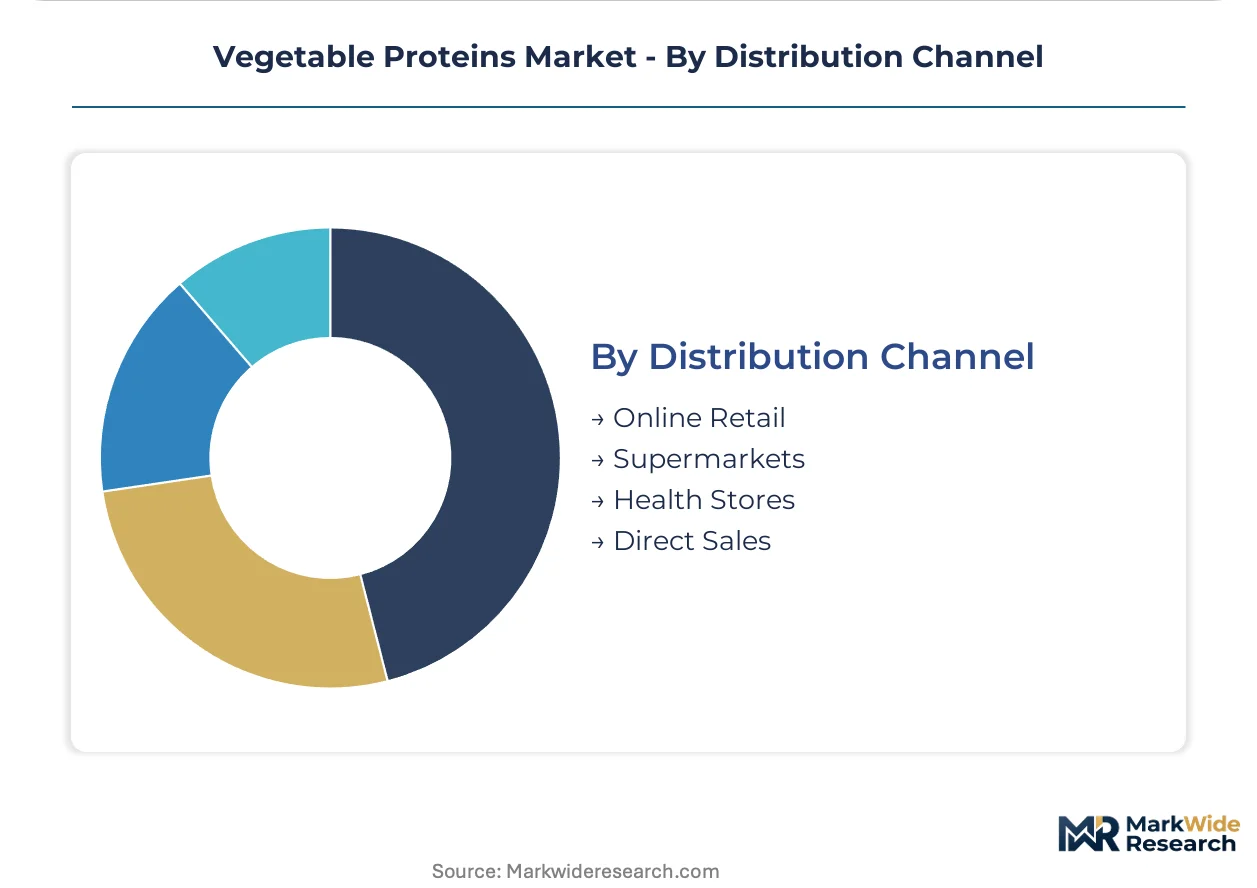
Direct sales capture the largest contract volumes; online retail channels are gaining share fastest among emerging brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal procurement mandates and China's dual carbon goals are redirecting fractionation investments toward regional pulse processors. Germany, China, Brazil, France, and Canada concentrate capacity expansion as local regulations tighten carbon disclosure and protein quality labeling requirements.
Germany
Alt-dairy formulators in Berlin and Hamburg are accelerating procurement of non-GMO pea isolates to meet EU Green Deal carbon footprint disclosure mandates for public sector foodservice tenders. The country's Federal Office for Agriculture enforces strict origin labeling for plant protein ingredients. North Rhine-Westphalia hosts expanding extrusion facilities where industrial bakery groups negotiate direct multi-year offtake agreements with Dutch fractionators.
China
Domestic processors in Shandong and Jiangsu provinces are scaling high-moisture extrusion lines to close textural gaps in plant-based meat analogs for local consumption. SAMR implements GB standards for plant protein beverage labeling that restrict amino acid fortification claims. The Yangtze River Delta cluster concentrates new fractionation capacity as local brands seek to reduce import dependency for soy protein isolates.
Brazil
São Paulo-based meat processors are integrating textured vegetable proteins into extended product lines to manage input cost volatility in conventional beef supply. ANVISA governs novel food ingredient approvals through safety assessment pathways that parallel EFSA timelines. The southern states of Rio Grande do Sul and Paraná are deploying extrusion technology to supply both domestic food manufacturers and export markets.
France
Roquette Frères anchors dedicated pea protein extraction facilities in Lestrem that supply European alt-dairy and sports nutrition channels. EFSA novel food authorization requirements for emerging protein sources favor already-cleared soy and pea bases over hemp or single-cell alternatives. The Hauts-de-France region concentrates membrane filtration investments as mid-sized processors deploy ceramic microfiltration to bypass traditional acid-precipitation steps.
Canada
Prairie processors in Manitoba and Saskatchewan face margin pressure from yellow pea price swings tied to drought cycles across the Canadian prairies. Health Canada and PMRA coordinate on plant protein ingredient safety assessments that align with FDA PDCAAS frameworks for cross-border product positioning. The Port of Vancouver corridor supports export-oriented isolate production for Asian markets seeking allergen-free protein alternatives.
Vegetable Proteins Market Competitive Landscape
Player mix skews toward integrated agribusiness conglomerates with upstream oilseed crushing footprints. The competitive structure concentrates around three strategic archetypes: multinational traders with captive protein streams, dedicated fractionators with membrane filtration specialization, and diversified ingredient houses with flavor and texture system integration. Dominant competitive moves include backward integration into pulse processing assets and geographic expansion through regional extraction joint ventures.
Among North American integrated processors, Cargill Incorporated and Archer Daniels Midland occupy positions that exemplify the oilseed-crushing-to-isolate value chain archetype. Roquette Frères anchors the dedicated fractionator tier with specialized pea protein infrastructure. These three entities represent contrasting pathways to market presence: trading house verticality, agricultural processing scale, and targeted extraction technology respectively.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland |
| Roquette Frères |
| Ingredion Incorporated |
| International Flavors & Fragrances |
| Bunge Limited |
| Kerry Group |
| The Scoular Company |
| Wilmar International |
| Others |
Value Network & Pricing Analysis
Pea protein displacement of soy isolates in European alt-dairy formulations is redrawing procurement geography while compressing margin pools for Midwest crushing complexes that long dominated supply. This substitution dynamic simultaneously elevates Canadian prairie processors and fragments pricing power previously concentrated among integrated oilseed traders.
Pricing Analysis
Certification level creates the primary spread between commodity-grade concentrates and premium isolates qualified for FDA PDCAAS scoring and EU Green Deal carbon disclosure mandates. Pricing stratifies across premium isolates, standard concentrates, and economy-grade feed meals based on protein purity and functional performance. Cost compression in standard-tier pea concentrates is intensifying because membrane filtration technology is lowering entry barriers for regional processors. Industrial bakery groups in Germany exhibit the highest price sensitivity due to volume procurement and direct offtake negotiations, while sports nutrition brands in the US show least sensitivity when isolate grades enable complete protein claims.
Supply Chain Analysis
Canadian prairie drought cycles constitute the dominant chokepoint for yellow pea availability, transmitting price volatility downstream to European and Asian isolate buyers. Geographic supply concentrates in Canada, the US Midwest, and France, with emerging capacity additions in China and Brazil. Raw material dependencies center on yellow pea cultivation, defatted soybean flake supply, and enzymatic processing inputs for hydrolyzed grades. Single-source vulnerability runs through the US Midwest soy protein isolate complexes that anchor global beverage fortification supply. Distribution runs through direct multi-year offtake agreements between fractionators and industrial food processors, disintermediating legacy ingredient traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among European industrial bakery and meat-processing groups that negotiate direct volume contracts, squeezing margin capture for mid-tier suppliers dependent on distributor channels.
For Market Incumbents: Compound defensible positions by securing captive pea protein supply through backward integration into Canadian prairie processing assets and accelerating ISO 22000 certification investments to maintain European branded channel access. Threats from membrane filtration-enabled regional entrants and SAMR amino acid fortification restrictions in China demand proactive quality-tier positioning rather than commodity volume defense. For New Entrants and Emerging Players: Custom extrusion services for plant-based meat startups represent a service-layer gap where established players under-serve mid-scale brands lacking in-house rheology expertise. Target European laminated dough egg replacement applications and Chinese high-moisture extrusion contract manufacturing as the most penetrable white spaces. A technical service-led go-to-market angle emphasizing texture system integration rather than isolate commodity supply unlocks pricing power unavailable to volume traders. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-cap fractionators in Canada and France that deployed ceramic microfiltration ahead of incumbent acid-precipitation infrastructure. Long-term viability favors processors with demonstrated EFSA novel food dossier compilation capabilities and established direct procurement relationships with European industrial food groups. Watch for inflection when China's Yangtze River Delta fractionation cluster achieves import substitution thresholds for soy protein isolates currently sourced from US Midwest suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulse Processing | Cargill and ADM leverage oilseed crushing footprints to secure upstream soy and canola protein streams. |
| Membrane Filtration Technology Deployment | Roquette Frères anchors dedicated pea protein extraction facilities in France and Canada through specialized infrastructure. |
| Direct Offtake Agreement Expansion | German industrial bakery groups negotiate multi-year contracts with Dutch fractionators, bypassing legacy traders. |
| ISO 22000 Certification Investment | European branded channels demand 12-18 month audit cycles that strain mid-tier supplier cash conversion. |
| High-Moisture Extrusion Capacity Addition | Chinese processors in Shandong and Jiangsu scale lines to close textural gaps in plant-based meat analogs. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with ingredient procurement managers at European industrial bakery groups, alt-dairy formulators in Germany and France, and fractionation technology directors at Canadian and Chinese processors; and secondary validation through FDA PDCAAS guidance documents, EFSA novel food authorization registers, SAMR GB standards filings, and trade flow data from customs records. Bottom-up volume modeling triangulated against top-down market sizing from oilseed crushing capacity disclosures and membrane filtration installation tracking.
Across the analysis window, projections segment by product type (pea, soy, rice, hemp protein), form (isolate, concentrate, textured, hydrolyzed), end-use industry, and distribution channel. CAGRs derive from elasticity-adjusted demand curves incorporating substitution dynamics between protein sources and regulatory quality threshold shifts. Forecast inputs include Canadian prairie precipitation indices affecting yellow pea yield variance and EU Green Deal procurement mandate implementation timelines.
Forecasts assume regulatory continuity in FDA PDCAAS frameworks, EFSA novel food pathways, and SAMR GB standards; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as China's dual carbon goals and EU carbon border adjustment mechanisms evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Mock Meat Market
Alternative Food Sources
Mycoprotein Market
Alternative Food Sources
Fat Replacers Market
Alternative Food Sources
Dunaliella Salina Market
Alternative Food Sources
Egg Substitutes Market
Alternative Food Sources
Low Calorie Rice Market
Alternative Food Sources
Global Alternative Protein Market
Alternative Food Sources
Gluten Replacer Market
Alternative Food Sources
Mycoprotein Products Market
Alternative Food Sources
Algae Products Market
Alternative Food Sources
Meat Alternative Market
Alternative Food Sources
Synthetic Food Market
Alternative Food Sources
North America Fat Replacers Market
Alternative Food Sources
Upcycled Food Products Market
Alternative Food Sources
Global Algae Market
Alternative Food Sources
Fish Meal Alternative Market