
 Bioengineered Food Market | 2026-2036
Bioengineered Food Market Size, Share, and Industry Trends Forecast 2026-2036
Bioengineered Food Market Outlook
Buyer concentration among large-scale food processors and animal feed compounders is hardening across the bioengineered food value chain. Bayer AG leverages its integrated seed-to-trait platform to sustain supply commitments to major grain purchasers. BASF SE anchors its position through specialized nutritional ingredient formulations derived from engineered oilseeds. Syngenta competes by extending its geographic footprint across multiple breeding-climate zones.
Bioengineered food comprises agricultural commodities and derived ingredients whose genetic material has been altered through molecular techniques to express targeted traits such as herbicide tolerance, pest resistance, or enhanced nutritional profiles. These modifications serve industrial buyers seeking yield stability, input cost reduction, and compositional consistency for downstream processing. The technology dimension shows CRISPR and gene editing approaches capturing expanding R&D allocation as regulatory clarity improves in select jurisdictions, while transgenic methods retain manufacturing scale advantages in commodity grain and oilseed production. Application activity clusters in animal feed formulation and nutritional supplements, where engineered amino acid profiles and vitamin precursors command premium positioning over conventional sources.
The United States FDA and USDA oversee pre-market consultation and deregulation pathways that determine commercialization timelines for new bioengineered traits. Brazil's ANVISA and CTNBio administer parallel approval processes that influence South American export flows to Asian markets. China's NMPA and Ministry of Agriculture maintain import authorization requirements that shape multinational breeding priorities. Stakeholders must monitor regulatory reciprocity developments between major producing and consuming nations to anticipate trait approval synchronization or fragmentation.
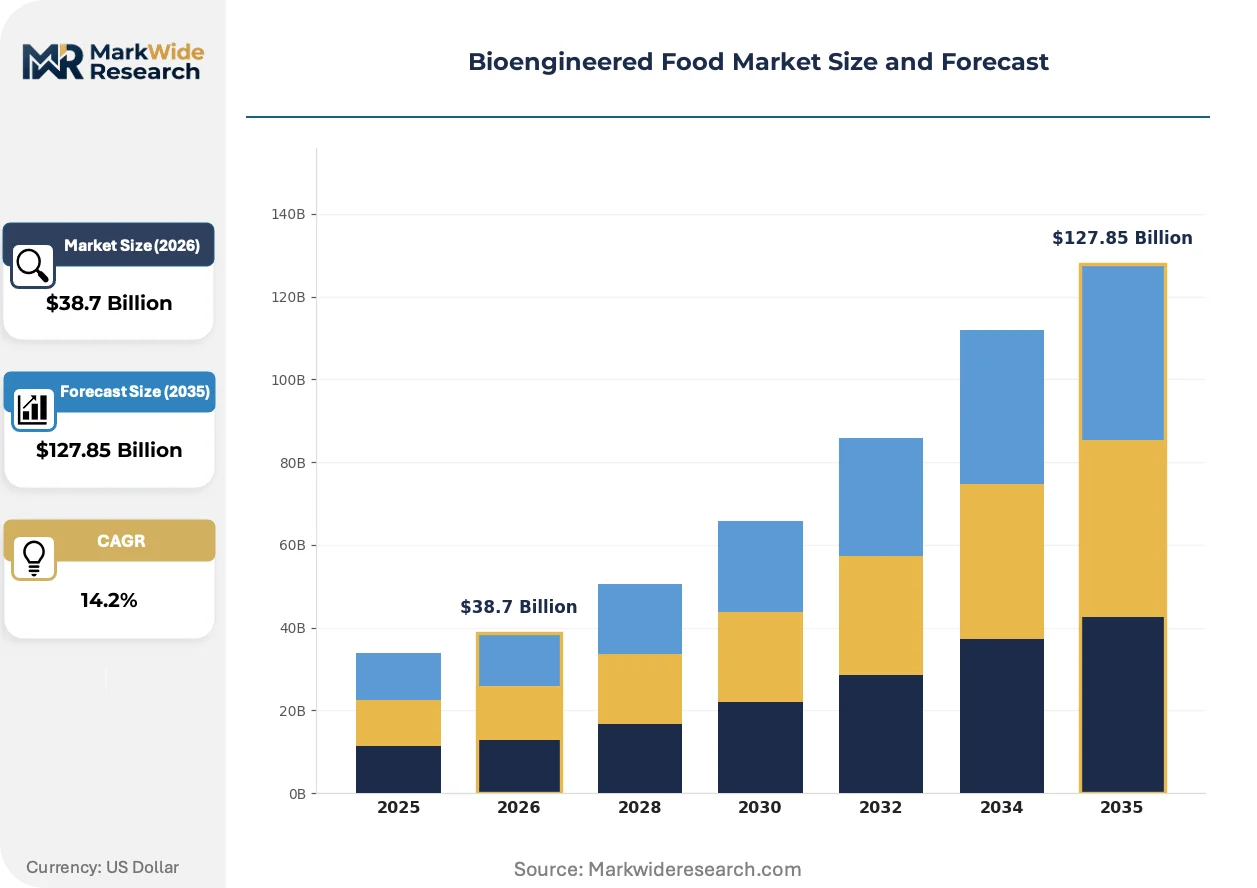
Market Dynamics
CRISPR-based gene editing is compressing trait development timelines from a decade to under five years, forcing seed companies to restructure R&D budgets and breeding station networks around editing platforms rather than transgenic pipelines.
Growth Catalysts
- Herbicide-tolerant trait stacking:Soybean processors in Brazil and Argentina are securing multi-year contracts for stacked-trait varieties that reduce spray passes and labor costs during critical planting windows.
- FDA streamlined consultation:The United States FDA's voluntary pre-market consultation pathway for gene-edited foods accelerates commercialization timelines compared to transgenic notification requirements.
- Animal feed amino acid fortification:Poultry and swine integrators are specifying engineered high-lysine corn and enhanced-oil soybeans to reduce supplemental amino acid purchases from fermentation suppliers.
Market Restraints
- Regulatory fragmentation across major importers:China's NMPA maintains separate authorization requirements for each bioengineered event, creating inventory segregation costs for exporters serving multiple Asian markets.
- Trait licensing concentration:Three technology providers control the majority of stacked-trait patents, extracting per-acre technology fees that compress margins for independent seed distributors.
- Consumer labeling mandates:The United States USDA's National Bioengineered Food Disclosure Standard requires QR codes or text disclosures, adding packaging redesign costs and retail scanner system upgrades.
Strategic Opportunities
- Gene-edited specialty oilseeds:High-oleic soybeans and low-linolenic canola engineered through CRISPR-Cas9 are penetrating premium frying oil and shelf-stable food formulations without transgenic regulatory burdens in several jurisdictions.
- Indoor vertical farming integration:Controlled-environment agriculture operators are trialing compact-stature bioengineered lettuce varieties optimized for automated harvesting and LED spectrum efficiency.
- Carbon intensity scoring alignment:Brazil's RenovaBio program credits low-carbon biofuel feedstocks, creating premium pricing corridors for drought-tolerant sugarcane and engineered soybean varieties with reduced nitrogen input requirements.
Industry Challenges
- Molecular breeding talent scarcity:Seed companies face recruitment gaps for computational biologists capable of integrating genomic selection models with field trial data across multiple agroclimatic zones.
- Event-specific testing infrastructure:Grain elevators and processors must maintain separate handling lines and PCR testing protocols for each authorized bioengineered trait, complicating logistics at high-throughput export terminals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioengineered Food Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Grains, Oilseeds Application: Animal Feed, Pharmaceuticals, Crop Protection, Nutritional Supplements Technology: Crispr, Transgenic, Gene Editing, RNA Interference End User: Agriculture, Biotechnology Firms, Food Processing, Research Institutions |
| Companies Covered | Bayer AG, BASF SE, Syngenta, Corteva Agriscience, DuPont de Nemours, Dow Chemical Company, Monsanto, Sakata, DSM-Firmenich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioengineered Food Market Strategic Shifts
Gene editing platforms are migrating from research tools to commercial breeding infrastructure, while regulatory authorities in major producing nations issue divergent guidance on edited versus transgenic classification.
CRISPR-Cas9 multiplex editing is expanding into stacked trait development for complex agronomic outcomes like simultaneous disease resistance and photosynthetic efficiency enhancement. Large-scale row crop seed producers are adopting editing workflows for commodity soybean and corn varieties, displacing slower backcrossing methods. This acceleration is compressing competitive windows between multinational breeding programs and specialized gene editing service providers.
REACH authorization requirements in the European Union are extending to novel genomic techniques, creating uncertainty for exporters seeking to serve specialty ingredient markets. The industrial consequence is a bifurcation in breeding priorities, with some firms prioritizing transgenic-free edited varieties for EU-adjacent markets while others double down on stacked transgenic events for Americas and Asia-Pacific feed channels. Specialty oilseed processors are most affected, redirecting R&D toward fatty acid profile modifications achievable through editing alone.
Compound feed manufacturers are consolidating ingredient specifications around bioengineered grains with guaranteed compositional ranges, displacing spot-market commodity purchasing. This specification tightening is forcing grain handlers to invest in identity-preserved supply chains with segregated storage and certified testing protocols. The shift is most visible in United States Midwest pork production corridors and Brazilian poultry integration zones, where feed cost precision outweighs commodity price volatility tolerance.
Bioengineered Food Market Segmentation
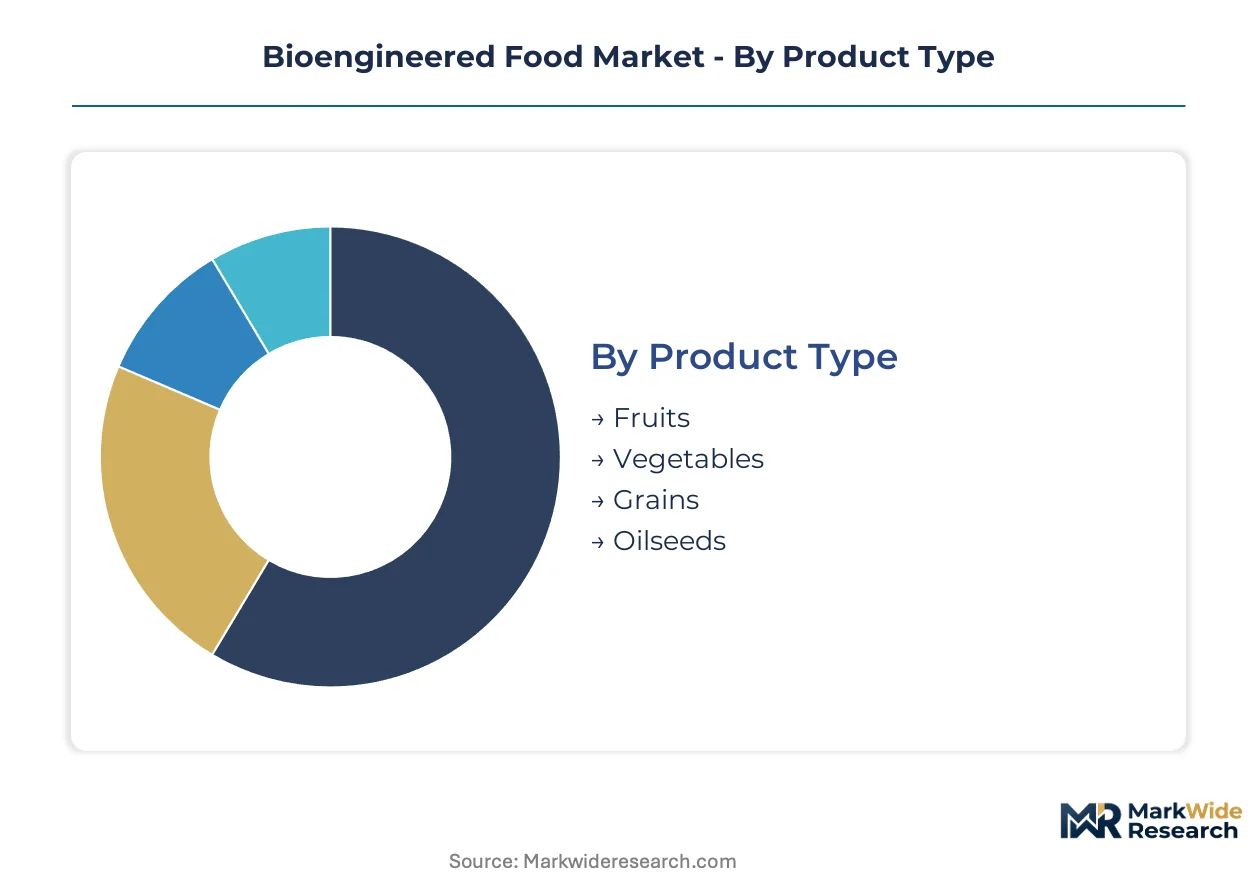
Segmentation in bioengineered food markets exposes divergent value capture across standalone commodity production versus embedded ingredient systems. Trait developers configure R&D portfolios differently for direct-to-farmer seed sales versus captive supply arrangements with integrated processors.
Product Type:
Integration depth varies sharply: oilseeds and grains flow into massive downstream processing infrastructure, while fruits and vegetables often reach consumers with minimal transformation.
- Grains:Engineered corn and wheat varieties dominate acreage deployment, with herbicide-tolerant and insect-resistant traits embedded in multi-stack configurations. Demand concentrates in United States Midwest pork and poultry integration corridors where feed mills specify guaranteed amino acid and energy densities.
- Oilseeds:Soybean and canola varieties engineered for fatty acid profiles serve standalone crushing operations and embedded food formulations simultaneously. Brazilian processors in Mato Grosso and Paraná are securing dedicated supply contracts for high-oleic soybeans destined for premium frying oil channels.
- Fruits:Gene-edited apples with non-browning phenotypes reach retail with minimal processing, bypassing complex regulatory pathways in select jurisdictions.
- Vegetables:CRISPR-developed lettuce and tomato varieties optimize for controlled-environment agriculture and automated harvesting systems.
Grains lead volumes today; oilseeds are gaining share fastest through specialty fatty acid premiumization.
Application:
Cost tier stratification separates commodity-scale animal feed from high-margin pharmaceutical and supplement applications requiring identity-preserved handling.
- Animal Feed:Engineered corn and soybeans with enhanced protein and oil content displace synthetic amino acid supplementation in poultry and swine rations. United States integrators in Iowa and North Carolina are locking in multi-year supply agreements for high-lysine corn varieties.
- Nutritional Supplements:Bioengineered vitamin precursors and omega-3 fatty acids from modified oilseeds command formulation premiums in human nutrition products. Chinese supplement manufacturers are increasing procurement of engineered DHA-rich canola to reduce marine oil dependency.
- Pharmaceuticals:Plant-made pharmaceuticals and therapeutic proteins from engineered tobacco and rice require contained production facilities with strict molecular containment protocols.
- Crop Protection:RNA interference traits delivered through engineered plants provide novel pest resistance modes, attracting development investment from agrochemical firms pivoting from synthetic chemistry.
Animal feed dominates absolute volume; nutritional supplements expand most quickly on margin-driven formulation demand.
Technology:
Maturity curves separate established transgenic platforms with regulatory clarity from emerging editing approaches still navigating approval heterogeneity.
- Transgenic:Recombinant DNA methods retain manufacturing scale advantages in commodity grain and oilseed production, with stacked-trait events commanding technology fees across millions of acres. United States and Brazilian regulatory pathways offer established deregulation precedents.
- CRISPR:Cas9-mediated editing compresses trait development timelines and enables precision modifications without foreign DNA insertion, attracting R&D reallocation as FDA and USDA issue edited-food guidance. Japanese regulators under METI frameworks are accelerating edited-food consultations.
- Gene Editing:TALEN and zinc-finger platforms serve specialized applications requiring targeted base modifications with reduced off-target risk profiles.
- RNA Interference:dsRNA-based trait expression provides pest resistance through novel biological modes, with regulatory classification still evolving in major importing jurisdictions.
Transgenic platforms anchor current production volumes; CRISPR systems are climbing the fastest on accelerated development timelines.
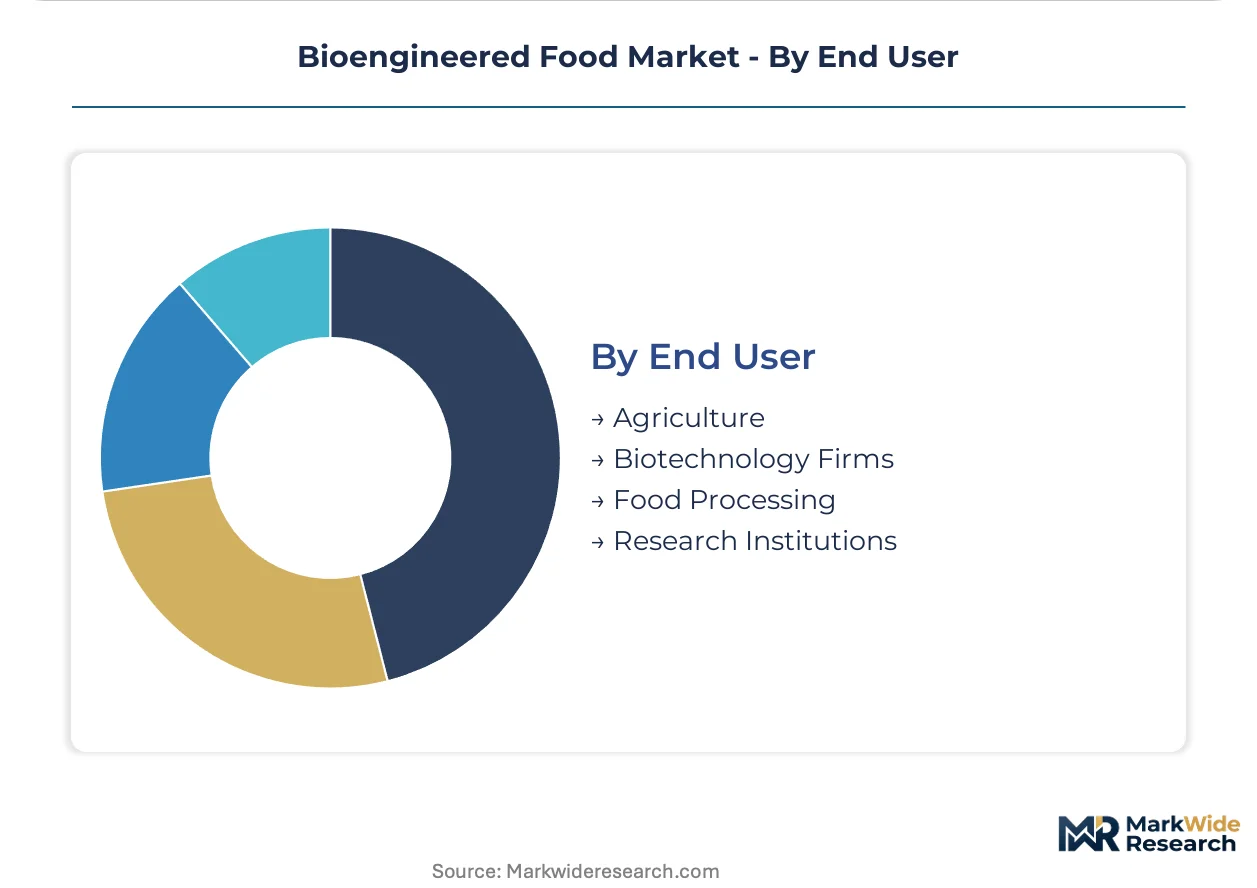
End User:
Customer type determines contracting structure: agriculture and food processing favor volume commitments with compositional guarantees, while biotechnology firms and research institutions prioritize trait access and IP licensing flexibility.
- Food Processing:Integrated grain processors and oilseed crushers specify engineered varieties with guaranteed compositional ranges for downstream ingredient consistency. United States and Brazilian soy processors are consolidating procurement around drought-tolerant, high-yield varieties with predictable oil and protein levels.
- Biotechnology Firms:Gene editing service providers and trait development specialists license platform technologies to seed companies lacking in-house editing capabilities.
- Agriculture:Commercial farming operations adopt engineered seeds through dealer networks, with technology fee structures varying by trait complexity and stacked-event configurations.
- Research Institutions:Public breeding programs and academic consortia access editing tools for pre-commercial trait validation and germplasm development.
Food processing channels drive the largest contract volumes; biotechnology firms represent the steepest expansion trajectory on platform licensing demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's stacked-trait soybean corridors attract multi-year processor contracts while the United States maintains regulatory clarity advantages for gene-edited approvals. Divergent authorization timelines between importing nations force exporters to maintain segregated supply chains.
United States
Midwest pork and poultry integrators lock in volume commitments for high-lysine corn varieties with guaranteed amino acid densities. The FDA's streamlined pre-market consultation pathway accelerates commercialization timelines for CRISPR-edited foods compared to transgenic notification requirements. Iowa and North Carolina feed mill clusters consolidate procurement around engineered grain specifications that displace synthetic amino acid supplementation.
Brazil
Mato Grosso and Paraná soy processors secure dedicated supply contracts for drought-tolerant, high-oleic soybean varieties destined for premium frying oil channels. ANVISA and CTNBio administer parallel approval processes that influence South American export flows to Asian markets. The RenovaBio program credits low-carbon biofuel feedstocks, creating premium pricing corridors for engineered varieties with reduced nitrogen input requirements.
China
Domestic supplement manufacturers increase procurement of engineered DHA-rich canola to reduce marine oil dependency in nutritional formulations. The NMPA and Ministry of Agriculture maintain import authorization requirements that shape multinational breeding priorities. Processing corridors in coastal provinces face inventory segregation costs as separate authorization requirements apply to each bioengineered event.
Argentina
Soybean processors in the Pampas region secure multi-year contracts for stacked-trait varieties that reduce spray passes and labor costs during critical planting windows. The national agricultural biotechnology regulator coordinates with Brazilian and Uruguayan counterparts on regional trait approval harmonization. Buenos Aires province crushing facilities invest in identity-preserved handling lines to serve differentiated European and Asian export channels.
Japan
Food manufacturers trial CRISPR-edited high-oleic soybeans for shelf-stable formulations under METI frameworks that accelerate edited-food consultations. Domestic regulators distinguish between transgenic and gene-edited products, reducing compliance burdens for precision-modified varieties without foreign DNA insertion. Tokyo-area ingredient formulators partner with Australian and Canadian exporters to secure supply of edited oilseeds not classified as genetically modified.
Bioengineered Food Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across trait development, seed production, and downstream ingredient formulation. Market structure shows tiered consolidation with three technology providers controlling majority stacked-trait patents and extracting per-acre licensing fees. Strategic archetypes include integrated seed-to-trait platforms, specialized nutritional ingredient formulators, and gene editing service providers licensing platform technologies. Dominant competitive moves center on breeding station network restructuring around editing platforms and geographic footprint extension across multiple agroclimatic zones.
Among diversified chemical and life science conglomerates, Bayer AG and BASF SE occupy positions spanning germplasm ownership through downstream ingredient systems. Bayer anchors integrated seed-to-trait supply commitments to major grain purchasers. BASF exemplifies specialized nutritional ingredient positioning through engineered oilseed derivatives. Syngenta sits within the geographic expansion archetype, competing through breeding-climate zone diversification rather than captive processing integration.
| Leading Market Players |
|---|
| Bayer AG |
| BASF SE |
| Syngenta |
| Corteva Agriscience |
| DuPont de Nemours |
| Dow Chemical Company |
| Monsanto |
| Sakata |
| DSM-Firmenich |
| Others |
Value Chain & Pricing Dynamics
CBOT corn futures and soybean price indices cascade through bioengineered seed value chains into three-tier pricing structures across premium, standard, and economy levels. Trait licensing fees from concentrated technology providers anchor input costs, while identity-preserved handling premiums separate high-oleic and high-lysine varieties from commodity grades.
Pricing Analysis
Capacity additions in Brazil and Argentina are reshaping price floors for stacked-trait soybeans as Mato Grosso processors expand crushing infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates CRISPR-edited specialty oilseeds from transgenic commodity grades, with fatty acid profile certification as the primary differentiation driver. Pricing pressure stems from per-acre technology fees that compress independent distributor margins. Animal feed compounders exhibit highest price sensitivity; nutritional supplement manufacturers absorb premiums for guaranteed compositional ranges.
Supply Chain Analysis
Regional distribution centers in Iowa, Mato Grosso, and Shandong province anchor hub-and-spoke patterns for engineered grain flows. Supply concentration centers on the United States, Brazil, and China for germplasm development and commodity processing. Raw material dependencies include CRISPR reagent supplies, proprietary trait germplasm, and synthetic amino acid fermentation feedstocks. Single-source vulnerability runs through three dominant stacked-trait patent holders. Distribution runs through identity-preserved channels with segregated storage and PCR-certified handling protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in bioengineered food rests on CRISPR platform cost-down trajectories compressing trait development timelines and premium-tier shifts toward gene-edited specialty oilseeds.
For Market Incumbents: Anticipate regulatory fragmentation between FDA streamlined pathways and China's event-specific authorization requirements by diversifying breeding station networks across multiple approval jurisdictions. Defend against independent gene editing service providers by consolidating platform licensing agreements. Vertical integration into identity-preserved handling infrastructure secures premium channel access. For New Entrants and Emerging Players: Launch via CRISPR-based specialty oilseed development targeting Japanese METI-edited food consultations and premium frying oil channels. White-space targets include compact-stature lettuce for vertical farming automation and drought-tolerant sugarcane for Brazil's RenovaBio carbon credits. Direct partnerships with controlled-environment agriculture operators bypass established seed distribution networks. For Investors and Strategic Acquirers: Asymmetric upside sits with gene editing service providers licensing platform technologies to seed companies lacking in-house CRISPR capabilities. Long-term viability favors specialists with regulatory navigation expertise across FDA, USDA, and divergent import authorization frameworks. Watch for trait approval synchronization between major producing and consuming nations as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR Platform Licensing | Accelerates trait development timelines for seed companies lacking in-house editing capabilities under FDA guidance. |
| Identity-Preserved Supply Chain Investment | Enables premium positioning for high-oleic soybeans through segregated handling lines at Mato Grosso crushing facilities. |
| Regulatory Navigation Specialization | Reduces approval lag between USDA deregulation and China's NMPA import authorization for stacked-trait events. |
| Vertical Farming Germplasm Partnership | Captures controlled-environment agriculture demand for compact-stature lettuce optimized under LED spectrum efficiency. |
| Carbon-Intensity Alignment | Secures RenovaBio premium pricing corridors for engineered varieties with reduced nitrogen input requirements in Brazil. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with seed company R&D directors, grain elevator procurement managers, FDA regulatory affairs specialists, and compound feed formulators with secondary validation. Secondary sources included USDA deregulation petitions, FDA pre-market consultation filings, ANVISA and CTNBio approval registers, and customs trade data for engineered grain flows. Bottom-up acreage deployment estimates and top-down processor capacity assessments were triangulated.
Historical reference periods anchored volume and value projections across the analysis window. Segmentation dimensions modeled include product type, application, technology platform, and end-user channel, with regulatory classification clusters as an additional bioengineered food-specific dimension. CAGRs were derived from trend extrapolation of trait adoption curves and processor capacity expansion schedules, incorporating CRISPR platform maturation timelines and import authorization reciprocity developments as industry-specific inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory fragmentation scenarios or breakthrough non-GMO breeding advances. Forecasts reflect documented assumptions on approval pathway convergence and trait licensing fee structures. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Plant-Based Squalene Market
Alternative Food Sources
Vegan Tuna Market
Alternative Food Sources
Vegan Caviar Market
Alternative Food Sources
Africa Potato Protein Market
Alternative Food Sources
Flaxseed Based Egg Market
Alternative Food Sources
Insect-Based Pet Food Market
Alternative Food Sources
Low Carbs Vegan Food Market
Alternative Food Sources
Asia-Pacific Meat Substitutes Market
Alternative Food Sources
Global Meal Replacement Shakes Market
Alternative Food Sources
Seitan Market
Alternative Food Sources
Low Calorie Rice Market
Alternative Food Sources
Europe Algae Protein Market
Alternative Food Sources
Global Alternative Protein Market
Alternative Food Sources
Egg Substitutes Market
Alternative Food Sources
Monoprotein Market
Alternative Food Sources
Algae Products Market