
 North America Meal Products Replacement Market | 2026-2036
North America Meal Products Replacement Market Size, Share, and Industry Trends Forecast 2026-2036
North America Meal Products Replacement Market Analytics
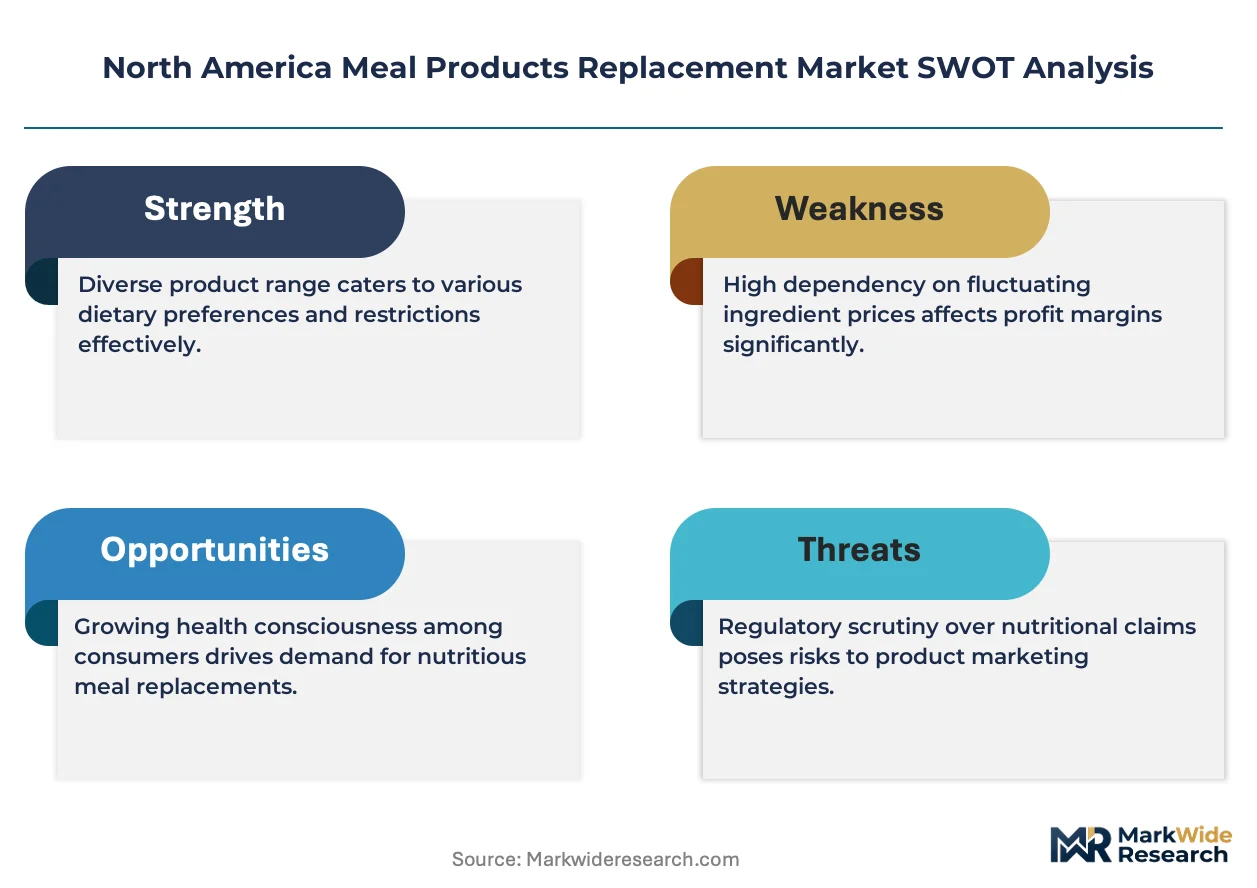
Subscription-based replenishment models is recalibrating what consumers purchase in the North America Meal Products Replacement Market. Abbott Laboratories leverages its clinical nutrition heritage to anchor hospital-to-home transition segments. Soylent specializes in engineered complete-nutrition formulations for tech-sector professionals. Huel competes through direct-to-consumer scale and formula transparency across its powdered and ready-to-drink lines.
Meal Products Replacement encompasses formulated or pre-portioned food systems designed to substitute traditional prepared meals, typically delivering controlled macronutrient profiles through freeze-dried, retort-processed, or chilled-ready formats with shelf stability ranging from seven days to twenty-four months. The category serves industrial cafeterias, remote workforce feeding programs, and individual consumers seeking time-compressed nutrition solutions. Ready-to-Eat formats dominate volume through convenience-store and vending penetration, while Meal Kits capture premium margin pools via recurring revenue architecture. Plant-Based ingredient types register the fastest trajectory as foodservice operators reformulate menus to meet sustainability procurement mandates.
The FDA oversees nutrition content claims and GRAS determinations for novel proteins, while Health Canada enforces front-of-package sodium and saturated fat warning labels that compress formulation flexibility. The USDA's Bioengineered Food Disclosure Standard adds traceability costs for soy and corn-derived inputs. Stakeholders must monitor evolving state-level extended producer responsibility laws for packaging waste that threaten single-serve unit economics.
Market Dynamics
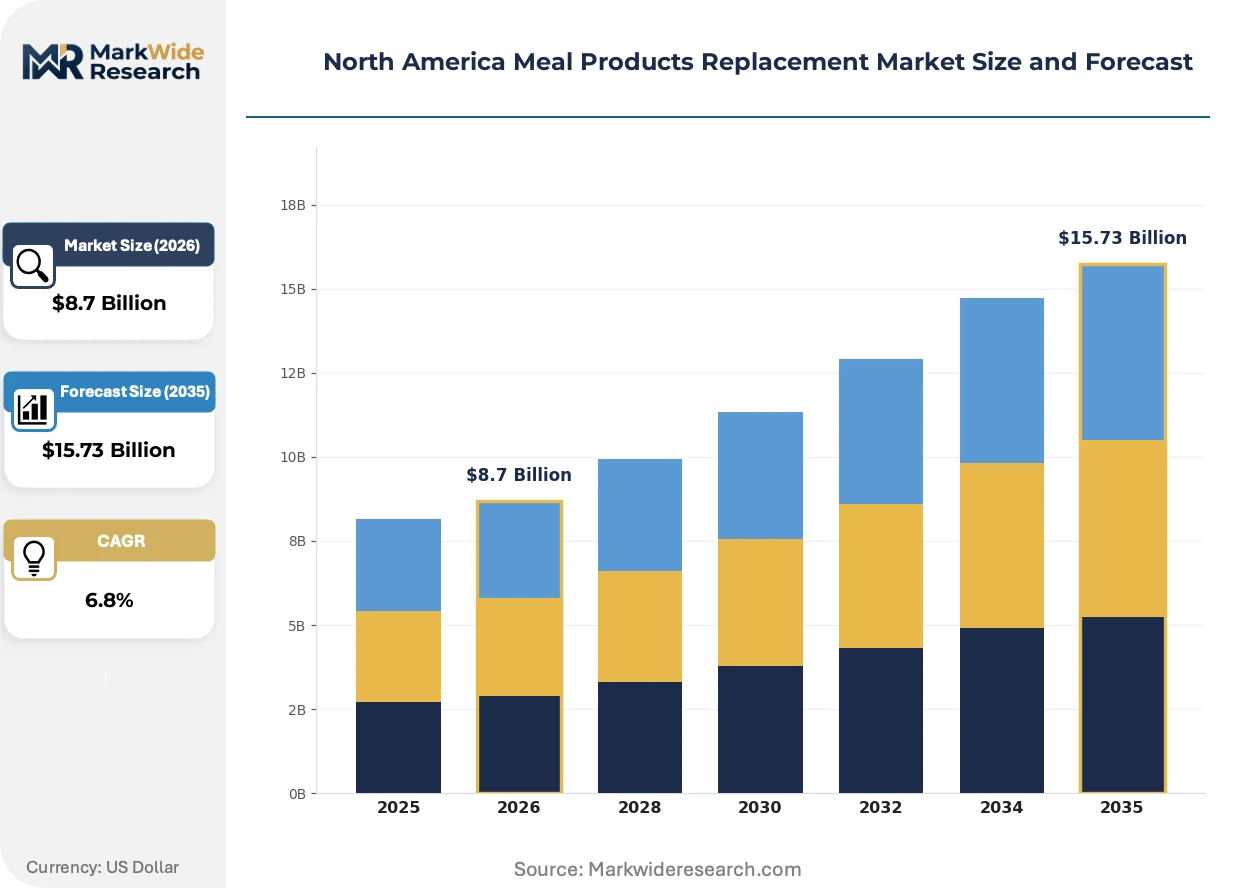
Subscription replenishment architecture is compressing traditional retail velocity while FDA and Health Canada labeling mandates force simultaneous formula reformulation across the North American manufacturing base.
Growth Catalysts
- Health Canada's front-of-package sodium warning symbols:These labeling requirements accelerate clean-label innovation among reformulation teams seeking preemptive compliance before potential US adoption.
- Freeze-dried ingredient technology:Extended shelf stability without artificial preservatives opens military and disaster-preparedness procurement channels previously inaccessible to meal replacement formats.
- California's innovation corridor concentration:Dense clustering of food-tech venture capital and pilot production facilities shortens product development cycles for novel protein platforms.
Market Restraints
- Input cost volatility:Pea protein isolate and oat milk powder prices swing with drought cycles in the Canadian prairies and upper Midwest growing regions.
- Supply concentration risk:Retort pouch manufacturing capacity concentrates in Mexico's border industrial zones, creating single-point vulnerability for shelf-stable format producers.
- Technical limitation:Current extrusion technologies cannot replicate the mouthfeel of slow-cooked proteins, capping premium pricing potential for whole-food-positioned lines.
Strategic Opportunities
- Underpenetrated remote workforce feeding:Canada's northern mining camps and Alaska's oilfield operations lack consistent fresh food logistics, creating demand for ambient-stable complete nutrition.
- USDA Bioengineered Food Disclosure Standard:Early compliance with traceability requirements positions suppliers for preferential procurement by institutional foodservice operators with sustainability mandates.
- Direct-to-employer channel innovation:Corporate wellness programs in Texas and Florida tech hubs are piloting subsidized meal replacement subscriptions as productivity benefits.
Industry Challenges
- Food safety certification timelines:SQF and BRCGS audits for novel protein processing facilities average fourteen months, delaying commercialization of fermentation-derived ingredient streams.
- Refrigerated last-mile reconfiguration:Chilled ready-to-drink formats require cold-chain density that conflicts with existing parcel network economics in the Mountain West and Great Plains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Meal Products Replacement Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Meals, Meal Kits, Ready-to-Eat, Snack Bars Ingredient Type: Plant-Based, Meat Alternatives, Dairy Substitutes, Whole Grains Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Specialty Stores Consumer Demographic: Health-Conscious, Busy Professionals, Families, Students |
| Companies Covered | Abbott Laboratories, Nestlé S.A., Glanbia plc, Herbalife Nutrition Ltd., The Simply Good Foods Company, General Mills Inc., Soylent, Huel, Kellanova, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Meal Products Replacement Market Evolving Landscape
Precision fermentation and cellular agriculture are migrating from ingredient supply into finished meal replacement formats, while regulatory clarity on novel protein safety claims remains the binding constraint on commercial velocity.
Precision fermentation-derived whey proteins are expanding into powdered meal replacement bases, delivering functional nutrition without conventional dairy supply chain volatility. Sports nutrition and clinical recovery segments in the US Northeast are adopting these ingredients at twice the rate of mass-market channels. This biotechnology is expanding into price-competitive positioning against commodity protein isolates.
Health Canada's mandatory front-of-package nutrition symbol regulations compress formulation flexibility for products exceeding sodium or saturated fat thresholds. Manufacturers must reformulate legacy recipes or accept prominent warning labels that degrade retail shelf performance. Ready-to-eat ambient formats face the steepest compliance burden, driving accelerated R&D spending in Toronto-area food-tech clusters.
Employer-subsidized subscription models are displacing individual direct-to-consumer acquisition in metropolitan markets. Corporate benefits administrators in Austin, Denver, and Vancouver negotiate volume contracts that bundle meal replacements with mental health and fitness perks. This channel shift concentrates buyer power and compresses brand loyalty cycles among younger professional demographics.
North America Meal Products Replacement Market Segmentation
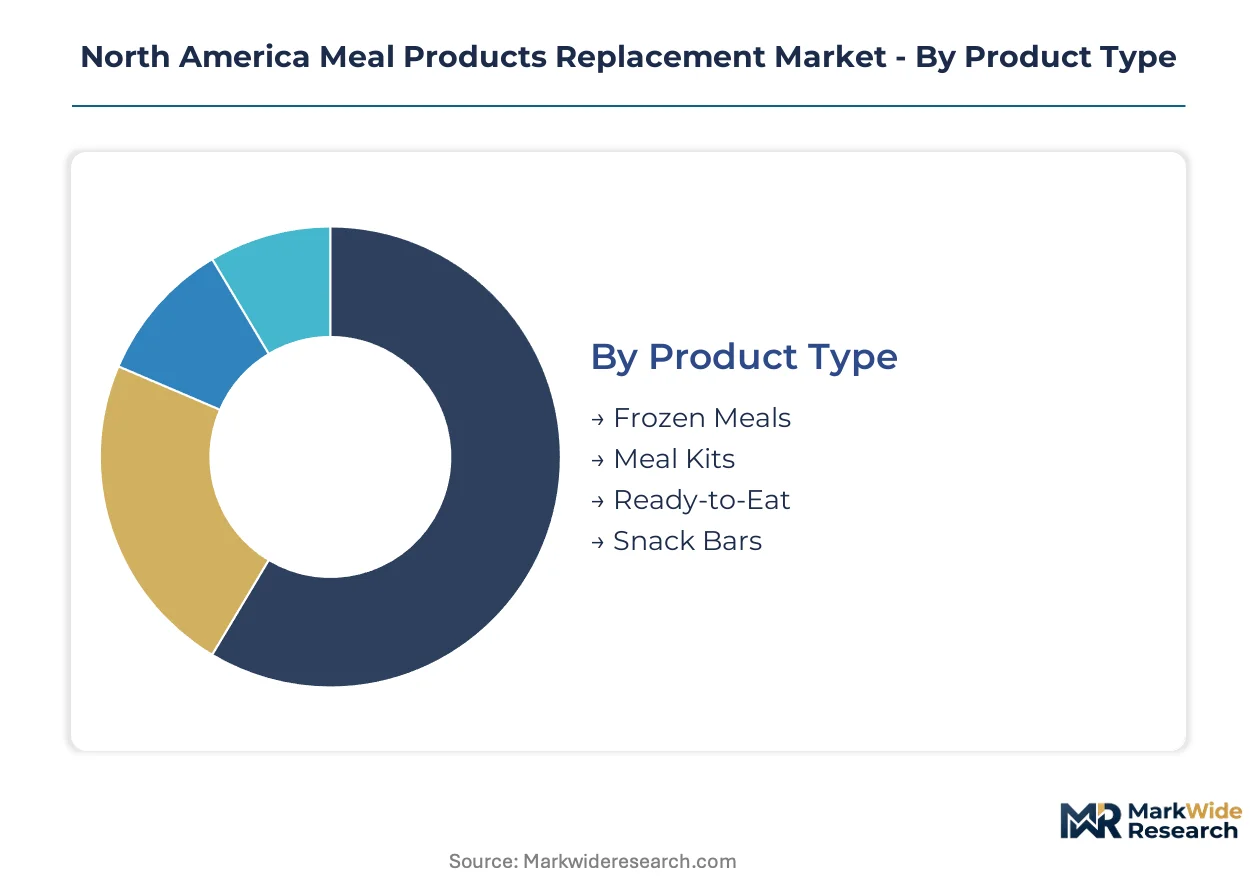
Segmentation in the North America Meal Products Replacement Market reveals distinct operational requirements across product formats, ingredient sourcing strategies, and channel economics. Each dimension carries specific regulatory, logistical, and margin implications that shape competitive positioning.
Product Type:
Standardization dominates frozen and ready-to-eat formats, while meal kits retain customization latitude through modular ingredient selection.
- Meal Kits:Pre-portioned ingredient bundles with recipe cards requiring consumer assembly. Demand concentrates in Austin, Denver, and Vancouver corporate wellness programs where employer-subsidized subscriptions displace individual acquisition.
- Ready-to-Eat:Ambient or chilled single-serve formats with complete nutritional profiles. FDA's updated Nutrition Facts labeling rules and Health Canada's front-of-package sodium warnings force simultaneous reformulation across manufacturing bases.
- Frozen Meals:Retort-processed or blast-frozen complete dishes with extended shelf stability.
- Snack Bars:Compressed nutrient-dense formats targeting between-meal consumption occasions.
Leading the category by volume: Ready-to-Eat. Expanding most quickly: Meal Kits.
Ingredient Type:
Cost tiers separate commodity grain bases from precision-fermented proteins with biotechnology premiums.
- Plant-Based:Formulations built on pea protein isolates, oat milk powders, and legume derivatives. Procurement swings with drought cycles in the Canadian prairies and upper Midwest growing regions, creating input cost volatility.
- Meat Alternatives:Mycoprotein and extruded vegetable protein systems designed to replicate animal protein functionality. Sports nutrition and clinical recovery segments in the US Northeast adopt these at twice the rate of mass-market channels.
- Dairy Substitutes:Precision fermentation-derived whey proteins entering powdered meal replacement bases.
- Whole Grains:Ancient grain and sprouted seed formulations targeting glycemic control positioning.
Steepest expansion trajectory: Plant-Based. Highest margin concentration: Meat Alternatives.
Distribution Channel:
Volume flows through traditional retail while subscription architectures capture recurring revenue premiums.
- Online Retailers:Direct-to-consumer platforms with replenishment algorithms and personalized nutrition profiling. Corporate benefits administrators negotiate volume contracts that bundle meal replacements with mental health and fitness perks.
- Supermarkets:Mass-market penetration dependent on shelf placement fees and promotional calendar coordination. Chilled ready-to-drink formats require cold-chain density that conflicts with existing parcel network economics in the Mountain West and Great Plains.
- Convenience Stores:Impulse-oriented single-serve placement for ambient-stable formats.
- Specialty Stores:Curated selection targeting ingredient transparency and sustainability certification.
Gaining share fastest: Online Retailers. Dominating absolute volume: Supermarkets.
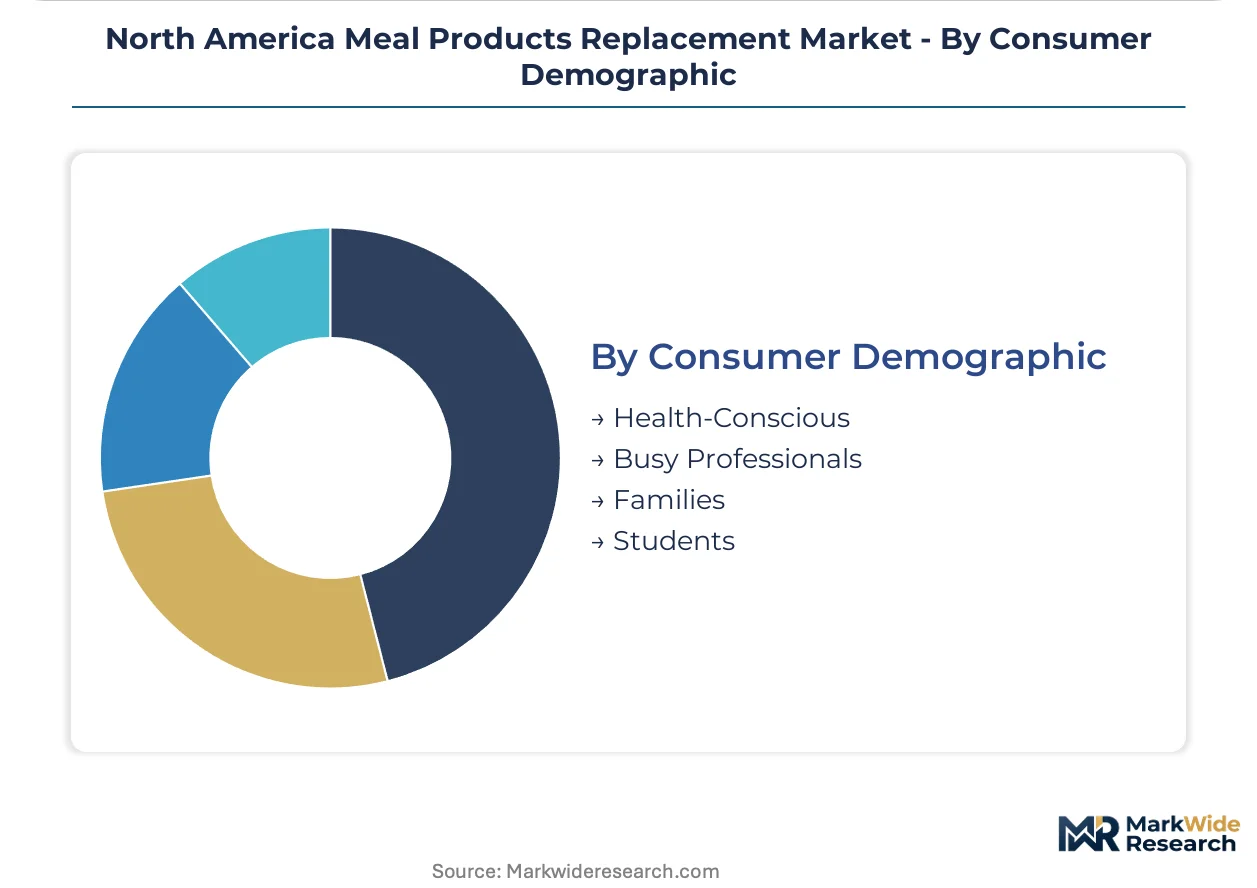
Consumer Demographic:
Application context separates institutional procurement from individual subscription behavior.
- Busy Professionals:Time-compressed nutrition seekers driving subscription-based meal kit adoption. California's innovation corridor and the Greater Toronto Area's food-tech cluster concentrate venture capital and pilot production facilities serving this segment.
- Health-Conscious:Macro-tracking consumers prioritizing clean-label transparency and controlled sodium profiles. Health Canada's front-of-package warning symbols accelerate reformulation among manufacturers targeting preemptive compliance.
- Families:Multi-portion procurement seeking convenience without sacrificing meal occasion structure.
- Students:Price-sensitive demand concentrated in shelf-stable and bulk formats.
Generating highest revenue per user: Busy Professionals. Climbing the fastest: Health-Conscious.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the majority of North American meal replacement volume, yet manufacturing capacity concentrates along the Canadian border and Mexican industrial zones. This geographic split between demand centers and production nodes shapes logistics costs and regulatory compliance burdens across the value chain.
United States
California's innovation corridor hosts dense clusters of food-tech venture capital and pilot production facilities serving busy professionals. The FDA's updated Nutrition Facts labeling rules force simultaneous reformulation across manufacturing bases. Texas and Florida tech hubs pilot employer-subsidized meal replacement subscriptions as productivity benefits.
Canada
Health-conscious consumers in the Greater Toronto Area drive demand for clean-label transparency and controlled sodium profiles. Health Canada's front-of-package nutrition symbols compress formulation flexibility for products exceeding thresholds. Toronto-area food-tech clusters accelerate R&D spending on ambient-stable format compliance.
Mexico
Retort pouch manufacturing capacity concentrates in border industrial zones, creating single-point vulnerability for shelf-stable format producers. The country's proximity to US distribution networks supports export-oriented production. Northern mining camps and remote workforce feeding programs represent underpenetrated demand pockets.
North America Meal Products Replacement Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the North America Meal Products Replacement Market. The vendor base fragments across clinical nutrition heritage, direct-to-consumer scale plays, and engineered complete-nutrition specialists. Three strategic archetypes dominate: hospital-to-home transition anchors, tech-sector professional targeting, and subscription-based replenishment platforms. Capacity expansion and formula reformulation constitute the dominant competitive moves as FDA and Health Canada labeling mandates force simultaneous compliance investments.
Within the clinical nutrition heritage tier, Abbott Laboratories anchors hospital-to-home transition segments. Soylent occupies a position exemplifying engineered complete-nutrition formulations for tech-sector professionals. Huel represents direct-to-consumer scale and formula transparency across powdered and ready-to-drink lines.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Nestlé S.A. |
| Glanbia plc |
| Herbalife Nutrition Ltd. |
| The Simply Good Foods Company |
| General Mills Inc. |
| Soylent |
| Huel |
| Kellanova |
| Others |
Value Network & Pricing Analysis
Precision fermentation scale-up simultaneously compresses protein input costs and concentrates biotechnology capacity in California's innovation corridor and the Greater Toronto Area, redistributing pricing power toward novel ingredient suppliers while legacy commodity processors face margin compression.
Pricing Analysis
Margin tightening in ready-to-eat ambient formats reflects Health Canada's front-of-package sodium warning compliance costs and simultaneous FDA label redesign investments. Three-tier pricing structure across premium precision-fermented, standard plant-based isolate, and economy grain-protein tiers separates clinical nutrition positioning from mass-market penetration. Pricing pressure intensifies as employer-subsidized subscription channels concentrate buyer power in Austin, Denver, and Vancouver corporate wellness programs. Students and price-sensitive remote workforce segments exhibit highest elasticity, while busy professionals in tech corridors show lowest sensitivity to subscription premiums.
Supply Chain Analysis
Reverse logistics for temperature-compromised chilled ready-to-drink formats remains underdeveloped across the Mountain West and Great Plains, forcing write-offs that inflate net landed costs. Manufacturing capacity concentrates in Mexico's border industrial zones for retort pouches, California's food-tech clusters for precision fermentation, and the Canadian prairies for pea protein isolate extraction. Raw material flows draw from upper Midwest oat growing regions, Canadian legume processors, and fermentation bioreactor networks. Single-source vulnerability in Mexican retort pouch capacity threatens shelf-stable format producers during cross-border disruption. Distribution runs through direct-to-employer subscription platforms, supermarket cold-chain requirements, and convenience store ambient-stable placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retort pouch manufacturing capacity constraints in Mexico's border zones prop pricing power for shelf-stable format holders, creating supply-constrained conditions that favor incumbents with secured production slots.
For Market Incumbents: Extend formulation R&D partnerships with Toronto-area food-tech clusters to preempt Health Canada sodium warning compliance before potential US regulatory convergence. Secure backward integration into pea protein isolate processing through offtake agreements with Canadian prairie processors, defending margin position against input cost volatility from drought cycles. For New Entrants and Emerging Players: Enter via underpenetrated remote workforce feeding channels in Canada's northern mining camps and Alaska's oilfield operations, where ambient-stable complete nutrition lacks consistent fresh food logistics competition. Target employer-subsidized corporate wellness programs in Texas and Florida tech hubs with direct-to-benefits-administrator sales models. For Investors and Strategic Acquirers: Re-rating potential sits with precision fermentation-derived protein platforms given FDA GRAS determination velocity and sports nutrition segment adoption at twice mass-market rates. Acquisition focus should center on biotechnology-enabled ingredient suppliers with hospital-to-home transition channel relationships. Monitor FDA novel protein safety claim clarity as inflection signal for commercial velocity acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Expands functional protein supply without conventional dairy volatility for clinical recovery segments. |
| Retort Pouch Capacity Expansion | Reduces single-point vulnerability in Mexico border zones for shelf-stable format producers. |
| Direct-to-Employer Channel Development | Captures recurring revenue through Austin and Denver corporate wellness program integration. |
| Health Canada Preemptive Compliance | Positions formulations for potential US FDA front-of-package warning adoption. |
| Freeze-Dried Technology Licensing | Opens military and disaster-preparedness procurement channels previously inaccessible to meal replacement formats. |
Research Methodology
Multi-period observation of employer-subsidized subscription adoption rates, precision fermentation capacity buildouts, and Health Canada compliance timelines anchored the trend analysis, supplemented by interviews with food-tech venture capital principals, Toronto-area R&D directors, corporate benefits administrators, retort pouch manufacturing executives, and FDA regulatory affairs specialists. Secondary validation drew from USDA Bioengineered Food Disclosure Standard filings, Health Canada front-of-package regulation impact assessments, SEC 10-K nutrition segment disclosures, and customs trade data on pea protein isolate flows. Bottom-up channel volume estimates triangulated against top-down macroeconomic consumption projections.
Input-output matrices mapped ingredient cost structures through formulation tiers, distribution channel economics, and end-use segment price elasticities across the projection horizon. Segmentation dimensions modeled included product format, ingredient technology platform, procurement channel architecture, and consumer demographic application context. CAGRs derived from fitted trend extrapolation against historical subscription growth curves and regulatory compliance investment cycles. Industry-specific forecast inputs incorporated drought-cycle probability distributions for Canadian prairie growing regions and FDA novel protein GRAS determination pipeline velocity.
Revisions become necessary when Health Canada expands front-of-package warning categories, precision fermentation achieves cost parity with commodity isolates, or employer-subsidized subscription channels experience buyer consolidation. Forecasts reflect documented assumptions on regulatory adoption timelines and biotechnology scale-up trajectories. Practitioners should monitor FDA GRAS determination velocity, Mexican border industrial zone capacity utilization, and corporate wellness program procurement centralization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Carragean Alternatives Market
Alternative Food Sources
Emergency Food Market
Alternative Food Sources
Quinoa Protein Market
Alternative Food Sources
Mealworms Market
Alternative Food Sources
Flaxseed Based Egg Market
Alternative Food Sources
Algae Products Market
Alternative Food Sources
Teff Products Market
Alternative Food Sources
Dunaliella Salina Market
Alternative Food Sources
Vegan Eggs Market
Alternative Food Sources
North America Algae Protein Market
Alternative Food Sources
Africa Potato Protein Market
Alternative Food Sources
Global Alternative Protein Market
Alternative Food Sources
Food Cultures Market
Alternative Food Sources
Spirulina Market
Alternative Food Sources
Middle East and Africa Edible Insects Market
Alternative Food Sources
Seitan Market