
 North America Textile Films Market | 2026-2036
North America Textile Films Market Size, Share, and Industry Trends Forecast 2026-2036
North America Textile Films Market Analytics
Healthcare procurement groups is unwinding legacy purchasing patterns from general industrial buyers as hospitals prioritize breathable barrier films for surgical gowns and drapes. Berry Global Group Inc. leverages its blown film capacity across multiple U.S. states to serve this shift. SWM International specializes in precision-calendered films for wound care and transdermal delivery. Schweitzer-Mauduit International Inc. anchors its position through backward integration into fine paper and nonwoven substrates that pair with textile film laminates.
North America textile films are thin, flexible polymer sheets engineered from polyethylene, polypropylene, nylon, or polyester resins, typically manufactured via blown or cast film extrusion to achieve controlled permeability, tensile strength, and heat-sealability for protective, structural, or adhesive functions in finished goods. Polyethylene dominates volume across packaging and construction moisture barriers due to cost-efficient extrusion and chemical resistance. Medical and automotive applications command premium positioning as FDA-validated films and lightweight acoustic laminates require tighter gauge control and lot traceability. Cast film extrusion leads in optical clarity segments, while coating and laminating technologies capture margin in multi-layer healthcare composites.
The EPA regulates volatile organic compound emissions from solvent-based coating operations, pushing converters toward waterborne and hot-melt adhesive systems. FDA 21 CFR compliance for indirect food contact and medical device films shapes resin selection and migration testing protocols across U.S. manufacturing. OSHA workplace exposure limits for thermal decomposition products during extrusion influence capital equipment decisions and plant location. Stakeholders must weigh compliance cost trajectories against specialty film margin pools when allocating capacity between commodity construction wraps and regulated healthcare grades.
Market Dynamics
Healthcare procurement groups are unwinding legacy purchasing patterns from general industrial buyers as hospitals prioritize breathable barrier films for surgical gowns and drapes. This demand bifurcation is compressing capacity allocation decisions across Midwest manufacturing corridors where automotive and medical supply chains overlap.
Growth Catalysts
- FDA 21 CFR Compliance:Indirect food contact and medical device validation protocols are pulling converters toward higher-margin healthcare grades with mandatory lot traceability.
- Automotive Lightweighting:Acoustic laminate demand from electric vehicle manufacturers is absorbing precision-calendered film capacity across the U.S. manufacturing belt.
- Blown Film Extrusion:Cost-efficient polyethylene processing is sustaining volume growth in construction moisture barriers and protective packaging applications.
Market Restraints
- Petrochemical Feedstock Volatility:Ethylene and propylene price swings compress margins on commodity-grade polyethylene films used in construction wraps.
- EPA VOC Regulations:Solvent-based coating operations face emissions caps that force capital-intensive conversions to waterborne and hot-melt adhesive systems.
- Medical-Grade Gauge Control:FDA-validated films require tighter thickness tolerances that slow line speeds and reduce effective extrusion capacity.
Strategic Opportunities
- Transdermal Drug Delivery:Precision-calendered films for patch applications represent underpenetrated white space with premium pricing potential.
- Canadian Healthcare Procurement:Provincial hospital buying consortiums are consolidating supplier lists, creating entry points for validated U.S. manufacturers.
- Cast Film Optical Clarity:High-transparency segments in medical packaging and display laminates command margin premiums over blown film alternatives.
Industry Challenges
- Polymer Compounding Expertise:Formulating breathable barrier films with controlled permeability requires specialized knowledge that commands salary premiums in tight labor markets.
- Multi-Layer Lamination Integration:Pairing textile films with nonwoven substrates demands capital equipment and process control capabilities that strain mid-tier converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Textile Films Market |
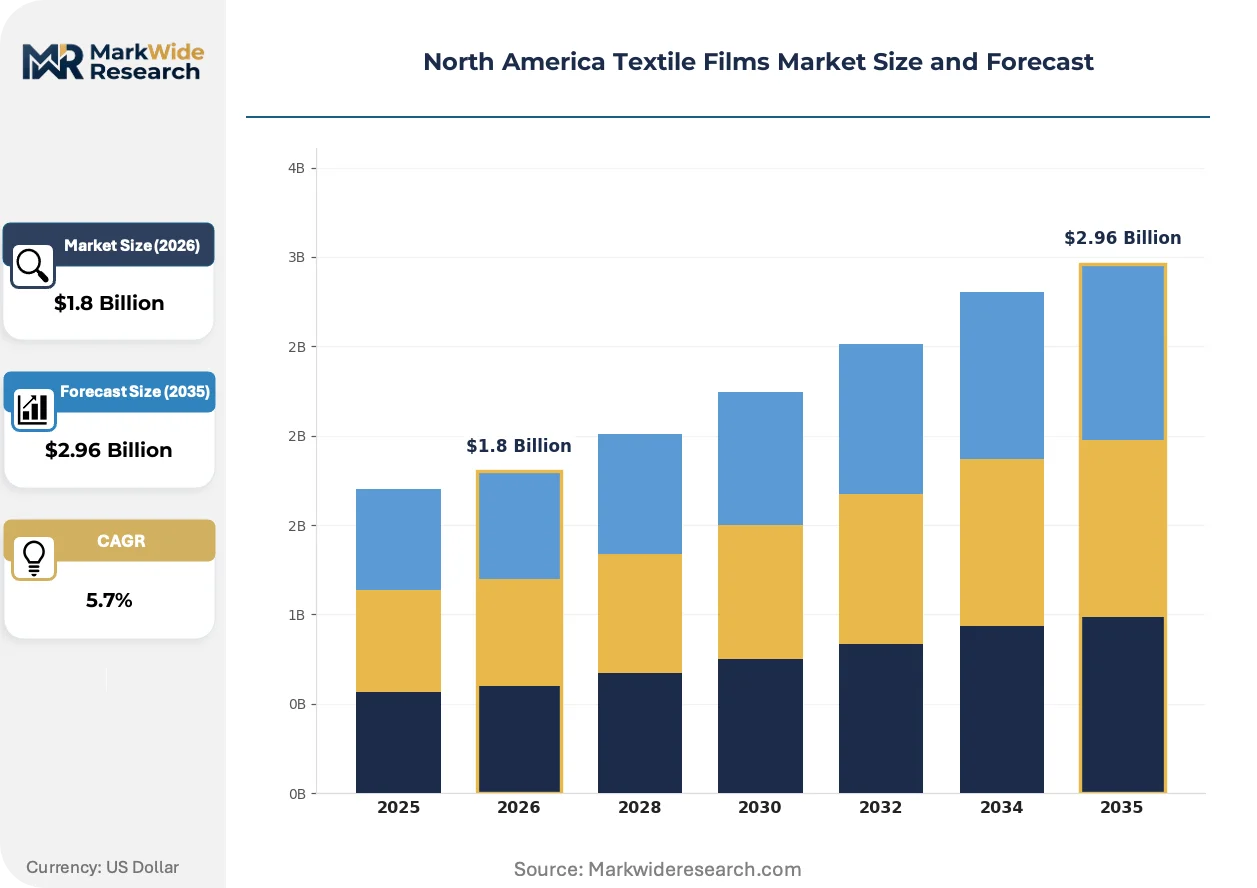
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Nylon, Polyester Application: Medical, Automotive, Construction, Packaging End User: Consumer Goods, Industrial, Healthcare, Agriculture Technology: Blown Film Extrusion, Cast Film Extrusion, Coating, Laminating |
| Companies Covered | Berry Global Group Inc., American Polyfilm Inc., SWM International, RKW North America Inc., Arkema S.A., Covestro AG, Schweitzer-Mauduit International Inc., 3M Company, Avery Dennison Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Textile Films Market Evolving Landscape
Active reshaping in North American textile films centers on regulatory-driven material transitions, precision manufacturing advances, and healthcare procurement consolidation. These forces are compressing legacy commodity positions while elevating validated specialty grades.
Coextrusion barrier technology is miniaturizing layer thicknesses in medical packaging films while maintaining seal integrity. Hospitals and surgical centers are accelerating qualification timelines for these structures. The technology is miniaturizing material usage per unit area, reducing resin consumption without sacrificing performance specifications.
EPA volatile organic compound rules are forcing solvent-to-waterborne adhesive conversions across coating operations. This industrial consequence extends cure times and requires oven retrofits that absorb capital budgets. Medical device laminators in the U.S. Midwest are responding with hybrid hot-melt systems that bypass solvent chemistry entirely.
Hospital buying groups are consolidating vendor lists around validated suppliers with backward-integrated substrate control. Distributor networks that previously served fragmented regional accounts are losing share to direct manufacturer contracts. This concentration is most visible in the U.S. Southeast, where health system mergers have collapsed ten-state purchasing into three regional procurement hubs.
North America Textile Films Market Segmentation
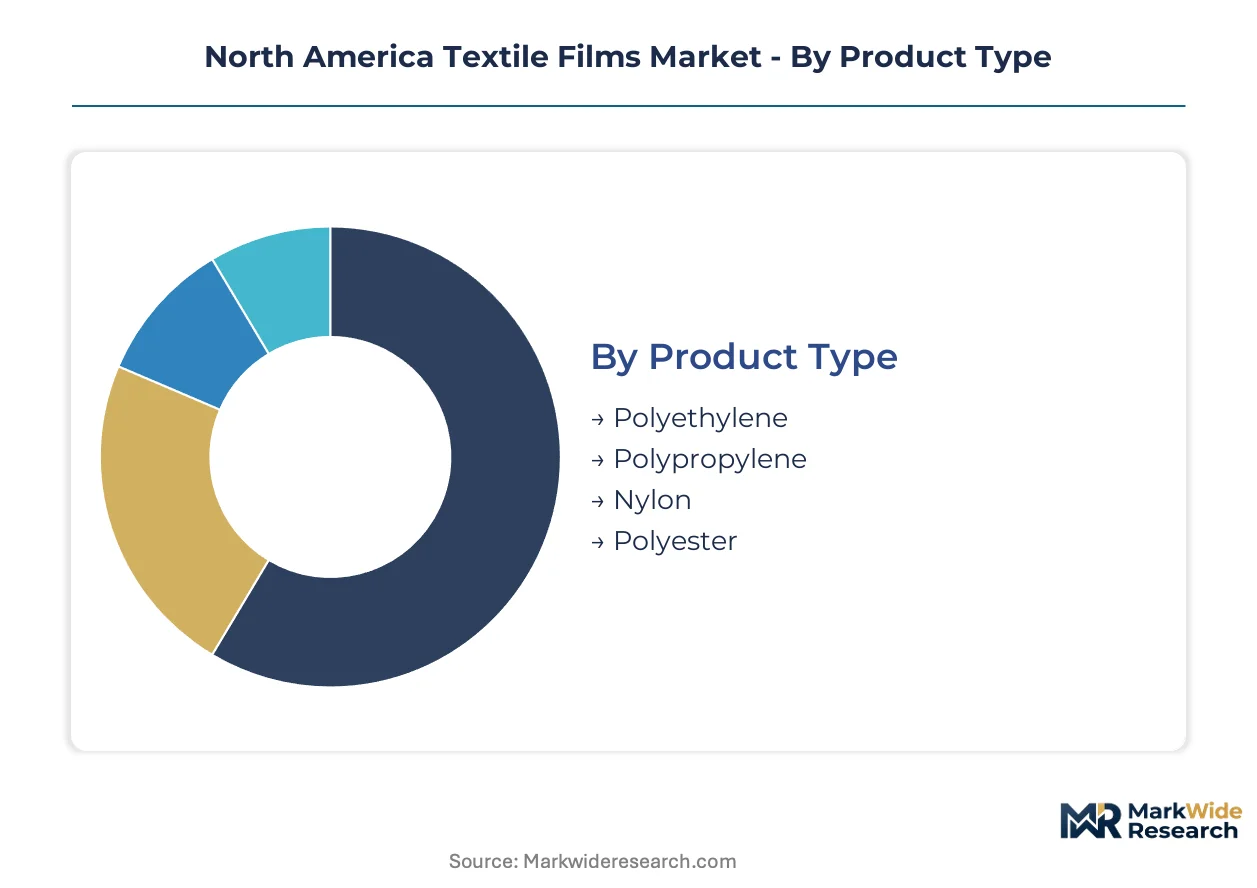
Segmentation in North American textile films reveals how resin chemistry, manufacturing technology, and end-use validation requirements create distinct margin tiers. Buyers channel procurement through different supplier relationships depending on whether applications demand commodity construction wraps or FDA-validated medical grades.
Product Type:
Polyethylene and polypropylene flow through distributor networks serving construction and packaging accounts, while nylon and polyester command direct manufacturer relationships in automotive and medical channels where lot traceability matters.
- Polyethylene:Low-density and linear low-density formulations dominate blown film extrusion for moisture barriers and protective packaging. Midwest construction buyers absorb volume through regional distributors, though resin price volatility compresses margins on standard grades.
- Polypropylene:Cast film and biaxially oriented structures deliver higher heat resistance and clarity for medical packaging and automotive interior laminates. Precision gauge control requirements pull this resin toward specialty converter relationships rather than commodity channels.
- Nylon:Polyamide films provide puncture resistance and thermal stability for automotive acoustic composites and industrial belting applications.
- Polyester:PET-based films serve high-clarity medical packaging and transdermal patch substrates where dimensional stability under sterilization conditions is non-negotiable.
Polyethylene dominates installed base. Polyester is where expansion concentrates.
Application:
Cost tier stratification separates medical and automotive applications, which absorb premium pricing for validated grades, from construction and packaging segments competing on resin efficiency and throughput.
- Medical:Surgical gowns, drapes, wound care dressings, and transdermal delivery systems require breathable barrier films with controlled moisture vapor transmission rates. FDA 21 CFR compliance mandates lot traceability and migration testing that eliminate commodity suppliers from qualified vendor lists.
- Automotive:Electric vehicle manufacturers deploy precision-calendered films in acoustic laminates and lightweight interior composites. The U.S. manufacturing belt from Michigan through Ohio concentrates demand for films meeting OEM specifications for flame resistance and fogging performance.
- Construction:Polyethylene housewraps and underlayment films compete on price per square foot through building material distributors.
- Packaging:Industrial shrink films and protective wraps prioritize seal strength and clarity over specialized performance attributes.
Construction commands volume share. Medical is climbing the fastest.
End User:
Customer type determines whether procurement flows through consolidated hospital buying groups, fragmented agricultural co-ops, or industrial distributors serving manufacturing accounts.
- Healthcare:Hospital systems and surgical centers are consolidating vendor lists around backward-integrated suppliers capable of substrate-to-film laminate control. Regional procurement hubs in the U.S. Southeast now span multiple former state-level buying organizations.
- Industrial:Automotive Tier 1 suppliers and appliance manufacturers specify film performance attributes but rarely source directly from resin converters, instead relying on laminate fabricators.
- Consumer Goods:Apparel and home textile brands specify film-backed fabrics for waterproofing and structure, though actual procurement flows through finished goods manufacturers.
- Agriculture:Greenhouse films and crop protection sheeting serve fragmented regional markets with limited specification requirements.
Industrial buyers represent legacy volume concentration. Healthcare procurement is gaining share fastest.
Technology:
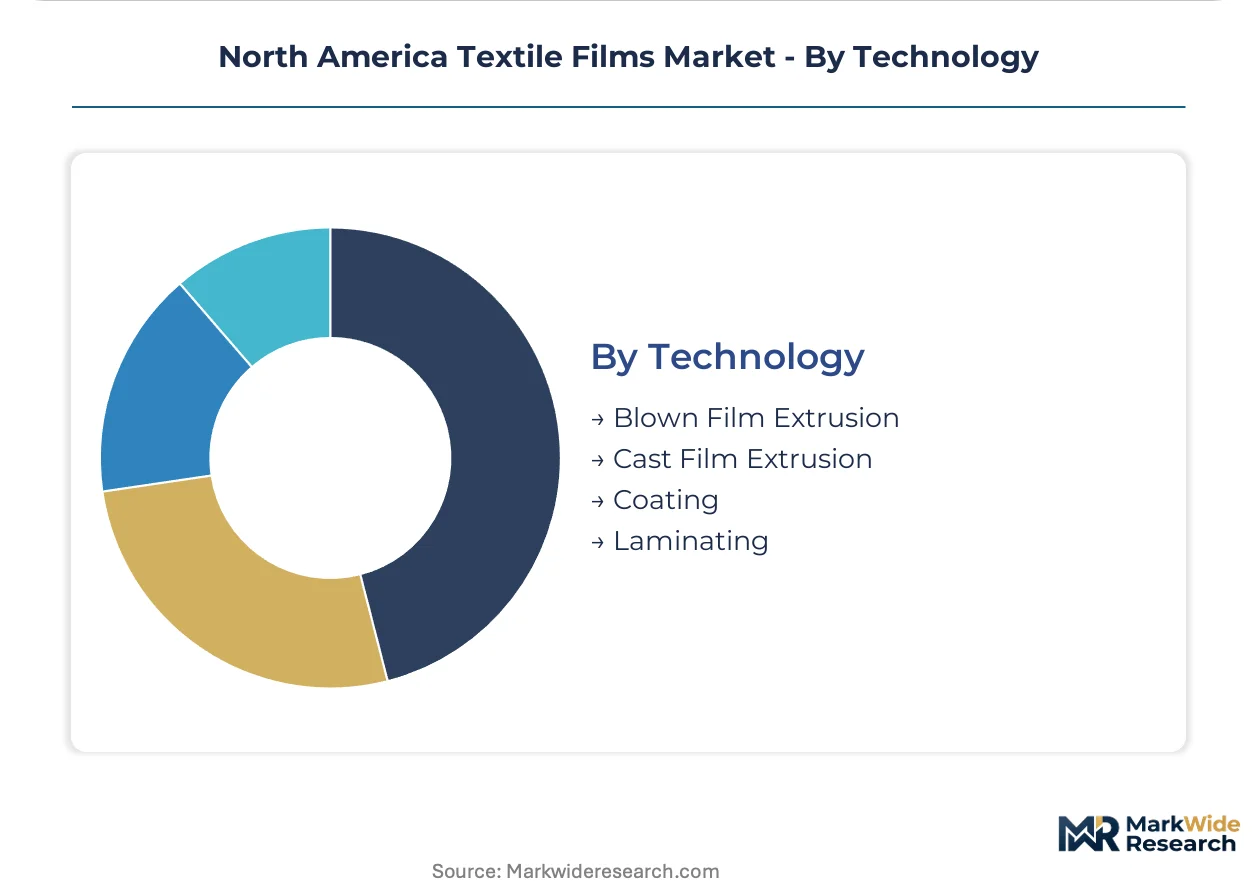
Process maturity and capital intensity separate established extrusion methods from coating and laminating operations requiring specialized adhesive expertise and emissions compliance.
- Blown Film Extrusion:Tubular film production dominates polyethylene processing for construction and agricultural applications. Cost-efficient equipment and operational simplicity sustain this technology's grip on high-volume, lower-margin segments despite slower line speeds versus cast alternatives.
- Cast Film Extrusion:Chill-roll casting delivers superior optical clarity and gauge uniformity for medical packaging and display laminates. Higher capital costs and tighter process control requirements restrict this technology to specialty converters serving premium end uses.
- Coating:Solvent-based and waterborne adhesive coating operations face EPA VOC regulations forcing capital-intensive system conversions or hybrid hot-melt adoption.
- Laminating:Multi-layer composite production pairs textile films with nonwoven substrates for surgical barriers and wound care applications.
Blown film anchors capacity base. Cast film is where technology investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mississippi River freight corridor and Great Lakes rail network underpin North American textile film distribution, connecting Midwest resin producers to East Coast medical device manufacturers and Mexican automotive assembly plants.
United States
FDA 21 CFR compliance mandates and EPA VOC regulations are reshaping converter operations across the industrial Midwest. Hospital buying groups in the Southeast have collapsed multi-state procurement into three regional hubs. The Ohio-Michigan manufacturing belt concentrates blown and cast film extrusion capacity serving overlapping automotive and medical supply chains.
Canada
Provincial healthcare consortiums in Ontario and Quebec are consolidating supplier lists around validated U.S. manufacturers with established Health Canada registrations. The country's national pharmaceutical regulator maintains alignment with FDA biocompatibility standards for medical device films. Toronto-area converters specialize in precision-calendered structures for wound care applications.
Mexico
Automotive acoustic laminate demand from electric vehicle assembly plants in Nuevo León and Mexico City is absorbing precision film capacity. The country's national environmental regulator enforces emissions standards that push coating operations toward waterborne adhesive systems. Border state manufacturing clusters increasingly serve dual U.S.-Mexico supply chains for medical packaging films.
North America Textile Films Market Competitive Landscape
Concentration sits with diversified material conglomerates and specialty film converters. The vendor base spans three tiers: resin-integrated multinationals with backward substrate control, precision extrusion specialists serving validated healthcare grades, and regional distributors handling commodity construction wraps. Two competitive moves dominate: hospital procurement consolidation favoring direct manufacturer contracts over distributor networks, and EPA-driven capital conversion from solvent-based to hot-melt coating systems.
Among North American fabricators, Berry Global Group Inc., SWM International, and Schweitzer-Mauduit International Inc. occupy positions across the specialty-to-commodity spectrum. Berry exemplifies scale-driven blown film capacity distributed across multiple U.S. states. SWM represents precision-calendered film expertise anchored in medical and transdermal delivery applications. Schweitzer-Mauduit demonstrates backward integration into fine paper and nonwoven substrates that pair with textile film laminates for surgical barrier applications.
| Leading Market Players |
|---|
| Berry Global Group Inc. |
| American Polyfilm Inc. |
| SWM International |
| RKW North America Inc. |
| Arkema S.A. |
| Covestro AG |
| Schweitzer-Mauduit International Inc. |
| 3M Company |
| Avery Dennison Corporation |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between polyethylene resin suppliers and Midwest blown film converters lock in feedstock access and insulate medical-grade producers from ethylene price spikes while exposing commodity construction wrap manufacturers to spot market volatility. These contractual structures concentrate pricing power with backward-integrated resin producers and validated healthcare film specialists who can command premium positioning through FDA 21 CFR compliance.
Pricing Analysis
Volume-discount tiering structures stratify across premium validated medical grades, standard industrial laminates, and economy construction moisture barriers. Three-tier pricing separates FDA-validated films with lot traceability from automotive acoustic laminates and commodity polyethylene housewraps. Price differentiation hinges on certification grade and gauge control precision. Cost compression in commodity construction tiers intensifies because resin price volatility transfers directly to undifferentiated buyers. Healthcare procurement groups exhibit lowest price sensitivity due to patient safety liability exposure, while agricultural greenhouse film buyers absorb maximum pricing pressure.
Supply Chain Analysis
Inventory cycles extending eight to fourteen weeks for specialty polyester and nylon grades strain just-in-time medical device laminators who cannot tolerate production interruptions. Geographic supply concentration centers on the United States, Canada, and Mexico, with the Ohio-Michigan manufacturing belt anchoring blown and cast film extrusion capacity. Raw material dependencies draw from Gulf Coast ethylene crackers, Canadian propylene supply, and imported specialty polyamide feedstocks. Single-source vulnerability in precision-calendered film equipment creates bottlenecks when automotive and medical demand peaks simultaneously. Distribution runs through consolidated hospital buying groups in the U.S. Southeast, regional building material distributors for construction applications, and Tier 1 automotive laminate fabricators serving electric vehicle assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and validation support packages represent faster-expanding revenue layers than base film sales as hospital buying groups consolidate around suppliers offering substrate-to-laminate quality assurance and regulatory filing assistance.
For Market Incumbents: Consolidate substrate control through captive nonwoven production or exclusive supply partnerships with fine paper specialists, eliminating qualification risks that expose multi-layer laminate producers to FDA audit failures. Defend against emerging precision-calendered film specialists by embedding field application engineers directly with hospital procurement committees and surgical gown manufacturers, converting transactional supply relationships into sticky technical partnerships that resist vendor list compression. For New Entrants and Emerging Players: Transdermal drug delivery patch substrates represent a service-layer gap where incumbents under-serve pharmaceutical clients lacking in-house polymer compounding expertise. Target Canadian provincial healthcare consortiums in Ontario and Quebec where Health Canada registration requirements favor validated U.S. manufacturers with existing FDA compliance infrastructure. Penetrate through toll-coating partnerships with established medical device laminators, avoiding capital-intensive extrusion equipment while building process credibility and customer references. For Investors and Strategic Acquirers: Precision-calendered film specialists with Health Canada registrations and existing pharmaceutical patch qualifications offer the strongest acquisition target archetype for portfolio exposure to transdermal delivery growth. Long-term viability favors converters with hybrid coating capabilities spanning solvent-free hot-melt and waterborne adhesive systems, positioned for EPA regulatory tightening without stranded capital. Watch for inflection signals in electric vehicle acoustic laminate specifications, where OEMs migrating to lighter interior composites will accelerate qualification timelines for new film suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nonwoven Substrates | Captive supply of fine paper and spunbond materials secures surgical barrier laminate margins against substrate shortages. |
| Hot-Melt Coating Capacity Conversion | EPA VOC compliance investments position converters for hospital procurement consolidation around solvent-free suppliers. |
| Health Canada Registration Acquisition | Provincial buying consortium consolidation in Ontario and Quebec rewards early regulatory positioning with preferred vendor status. |
| Transdermal Patch Substrate Development | Pharmaceutical patch growth outpaces traditional wound care, attracting premium pricing for precision-calendered polyester films. |
| Direct Hospital System Partnerships | Southeast regional procurement hub consolidation collapses distributor intermediaries, rewarding direct manufacturer contracts with volume commitments. |
Research Methodology
A standing panel of blown film plant managers, hospital GPO contracts managers, automotive Tier 1 procurement directors, and FDA regulatory consultants provided ongoing calibration across primary interview waves. Secondary validation drew from EPA enforcement actions, FDA 510(k) filings, Health Canada medical device licenses, and ACC resin production data. Bottom-up capacity modeling triangulated against top-down healthcare procurement spend analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled resin chemistry tiers, manufacturing technology types, end-use validation requirements, and geographic production clusters. CAGRs derived from segment-level demand elasticity and capacity utilization trajectories. Forecast inputs incorporated electric vehicle production ramps, hospital merger activity, and EPA regulatory implementation timelines.
Material uncertainties — petrochemical feedstock disruptions, healthcare procurement consolidation pace, and automotive platform standardization shifts — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory continuity and resin supply chain stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Global Textile Colorant Market
Textile Chemicals, Dyes, and Finishing
Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Oil Colors Market
Textile Chemicals, Dyes, and Finishing
Industrial Dyes Market
Textile Chemicals, Dyes, and Finishing
Silicone Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Laminated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Chemicals Market
Textile Chemicals, Dyes, and Finishing
PVC Tarpaulin Sheets Market
Textile Chemicals, Dyes, and Finishing
Global Textile Enzymes Market
Textile Chemicals, Dyes, and Finishing
Cationic Dyes Market
Textile Chemicals, Dyes, and Finishing
Global Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
PVC Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Dye Sublimation Printing Market
Textile Chemicals, Dyes, and Finishing
Textile Auxiliaries Market
Textile Chemicals, Dyes, and Finishing
Waterless Textile Dyeing Services Market
Textile Chemicals, Dyes, and Finishing
Leather Dyes Market