
 Shellac Market | 2026-2036
Shellac Market Size, Share, and Industry Trends Forecast 2026-2036
Shellac Market Analytics
EU REACH registration requirements for natural resin imports is hardening compliance costs for Asian exporters. D. Manoharlal (Shellac) Pvt. Ltd. leverages its integrated lac cultivation and processing operations across Bihar to sustain cost advantages. Mantrose-Haeuser Co., Inc. dominates North American distribution through its specialized food and pharmaceutical coating divisions. Stroever GmbH & Co. KG anchors European supply with its Hamburg-based refining and technical service capabilities.
Shellac is a natural thermoplastic resin secreted by lac insects (Kerria lacca), composed primarily of aleuritic acid and shellolic acid with melting points between 65°C and 80°C; it functions as a moisture barrier, gloss enhancer, and adhesive across food, pharmaceutical, and industrial applications. Shellac flakes leads product type volumes due to standardized dissolution rates preferred by food and drug formulators. Pharmaceutical companies represent the fastest-expanding end user category as enteric coating demand rises for controlled-release drug delivery systems.
The US FDA maintains strict specifications for shellac used in food and drug coatings under 21 CFR 175.105, while India's BIS mandates IS 348-1966 quality grades for domestic and export certification. EMA's updated excipient guidelines require enhanced heavy metal and pesticide residue documentation from natural resin suppliers. Stakeholders must monitor evolving pharmaceutical excipient monographs and food additive purity thresholds to maintain market access across regulated jurisdictions.
Market Dynamics
The shellac market operates under acute supply-side concentration, with lac insect cultivation confined to specific agro-climatic zones in India. This geographic lock-in creates structural dependency on monsoon-dependent harvest cycles and rural labor availability.
Growth Catalysts
- EU REACH registration:Natural resin importers face escalating compliance documentation requirements for heavy metal and pesticide residues. Food-grade shellac suppliers investing in certified refining capacity capture premium positioning in European pharmaceutical and confectionery supply chains.
- Pharmaceutical enteric coating:Controlled-release drug delivery systems require moisture-barrier coatings that shellac provides. FDA specifications under 21 CFR 175.105 mandate purity thresholds that favor established processors with analytical capabilities.
- Bihar-Jharkhand cultivation clusters:Traditional lac farming communities supply the majority of global raw sticklac. Seasonal harvesting patterns and artisanal collection methods sustain genetic diversity of Kerria lacca strains preferred by high-specification buyers.
Market Restraints
- Input cost volatility:Crude lac prices fluctuate with monsoon reliability and forest host tree availability. Processors lack forward-contracting mechanisms with dispersed tribal collectors.
- Supply concentration risk:Over 70% of global raw material originates from eastern Indian states. Climate anomalies or pest outbreaks in this narrow belt transmit immediately to downstream coating industries.
- Synthetic polymer substitution:Zein, hydroxypropyl methylcellulose, and polyvinyl acetate phthalate compete in pharmaceutical and food glazing applications. These alternatives offer batch-to-batch consistency that natural resins struggle to match.
Strategic Opportunities
- Brazilian import market:ANVISA's evolving excipient guidelines create first-mover advantage for shellac suppliers establishing local technical partnerships. Brazilian generic pharmaceutical manufacturers seek natural coating alternatives for export qualification.
- Cosmetic nail care formulations:Clean beauty positioning drives demand for plant-derived film formers. Shellac-based nail products command shelf space in prestige retail channels resistant to petroleum-derived competitors.
- India PLI scheme alignment:Production-linked incentives for active pharmaceutical ingredient manufacturing extend to excipient localization. Domestic shellac processors qualifying under the scheme gain cost parity with imported refined grades.
Industry Challenges
- Analytical chemist scarcity:Shellac processors require specialists capable of aleuritic acid profiling and shellolic acid quantification under ISO 17025 protocols. Rural processing locations struggle to retain qualified laboratory personnel.
- EMA excipient master file timelines:European regulatory dossier preparation extends 18-24 months for new shellac refining facilities. Capital deployed remains unproductive during documentation and inspection phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shellac Market |
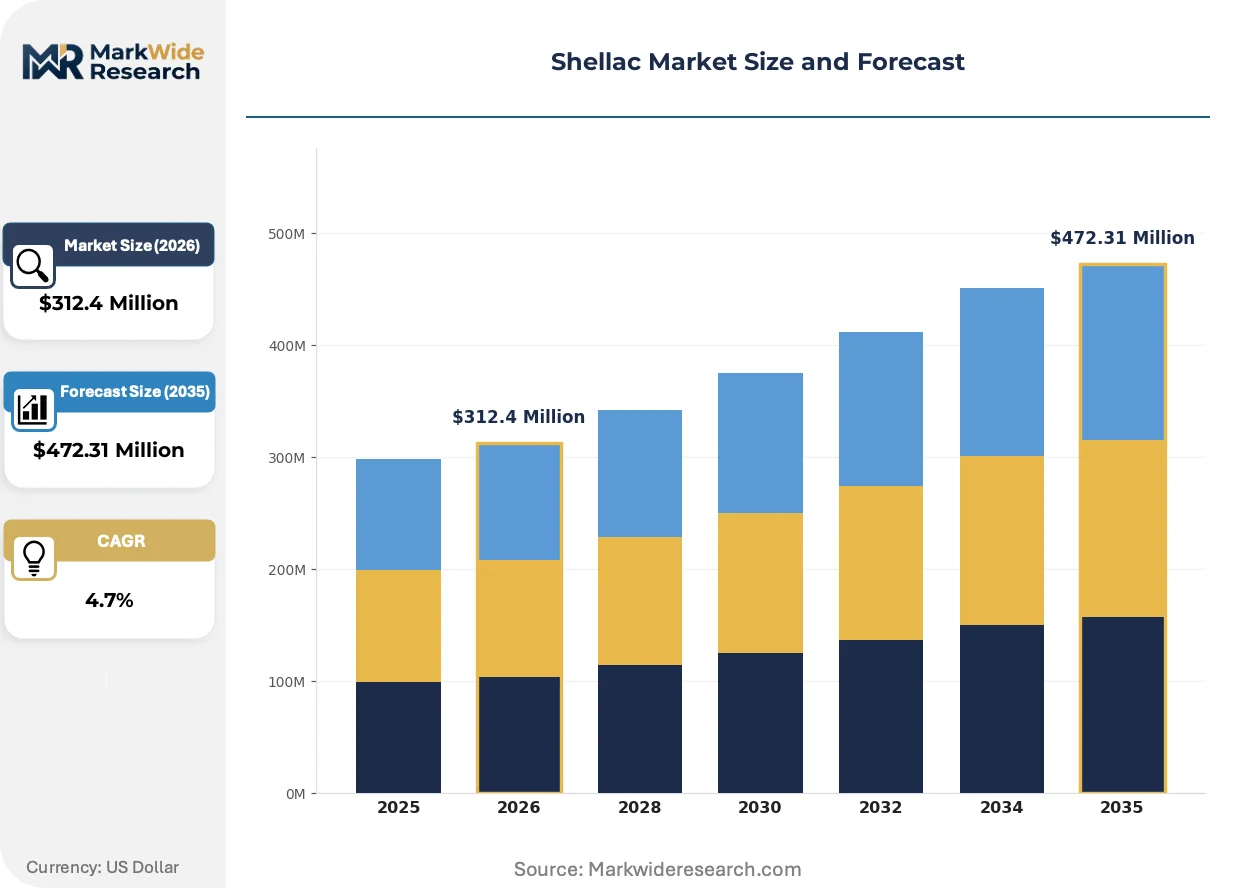
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seed Lac, Button Lac, Plate Lac, Shellac Flakes Application: Food Coating, Pharmaceuticals, Cosmetics, Wood Finishing End User: Food Industry, Cosmetic Manufacturers, Pharmaceutical Companies, Furniture Makers Form: Granular, Powdered, Liquid, Tablet |
| Companies Covered | D. Manoharlal (Shellac) Pvt. Ltd., Vishnu Shellac Factory, Mantrose-Haeuser Co., Inc., Rust-Oleum, Hind Suter Shellac Pvt. Ltd., Stroever GmbH & Co. KG, A.F. Suter & Company Ltd, Gifu Shellac Manufacturing Co., Ltd, Chuxiong DES Shellac Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shellac Market Evolving Landscape
Refining technology and regulatory documentation standards are compressing the supplier base toward integrated operators. Quality assurance capabilities now determine market access more than raw material procurement scale.
Advanced solvent extraction systems with closed-loop hexane recovery are overtaking traditional heat-fusion methods for dewaxed shellac production. Pharmaceutical formulators in Germany and Switzerland specify sub-0.2% wax content for enteric coating applications. This specification compression is marginalizing small-batch refiners lacking chromatographic purification capacity.
EMA's updated excipient guidelines mandate enhanced heavy metal and pesticide residue documentation from natural resin suppliers. European pharmaceutical manufacturers now require third-party analytical certificates for every lot. Shellac exporters to the EU are responding by installing in-house ICP-MS instrumentation rather than relying on external laboratory turnaround.
Confectionery manufacturers are consolidating supplier relationships around processors offering dual food-grade and pharmaceutical certifications. Buyers in the United States and Western Europe increasingly reject single-certification suppliers to simplify vendor qualification overhead. This preference compression favors integrated refiners with multi-jurisdictional regulatory dossiers already on file.
Shellac Market Segmentation
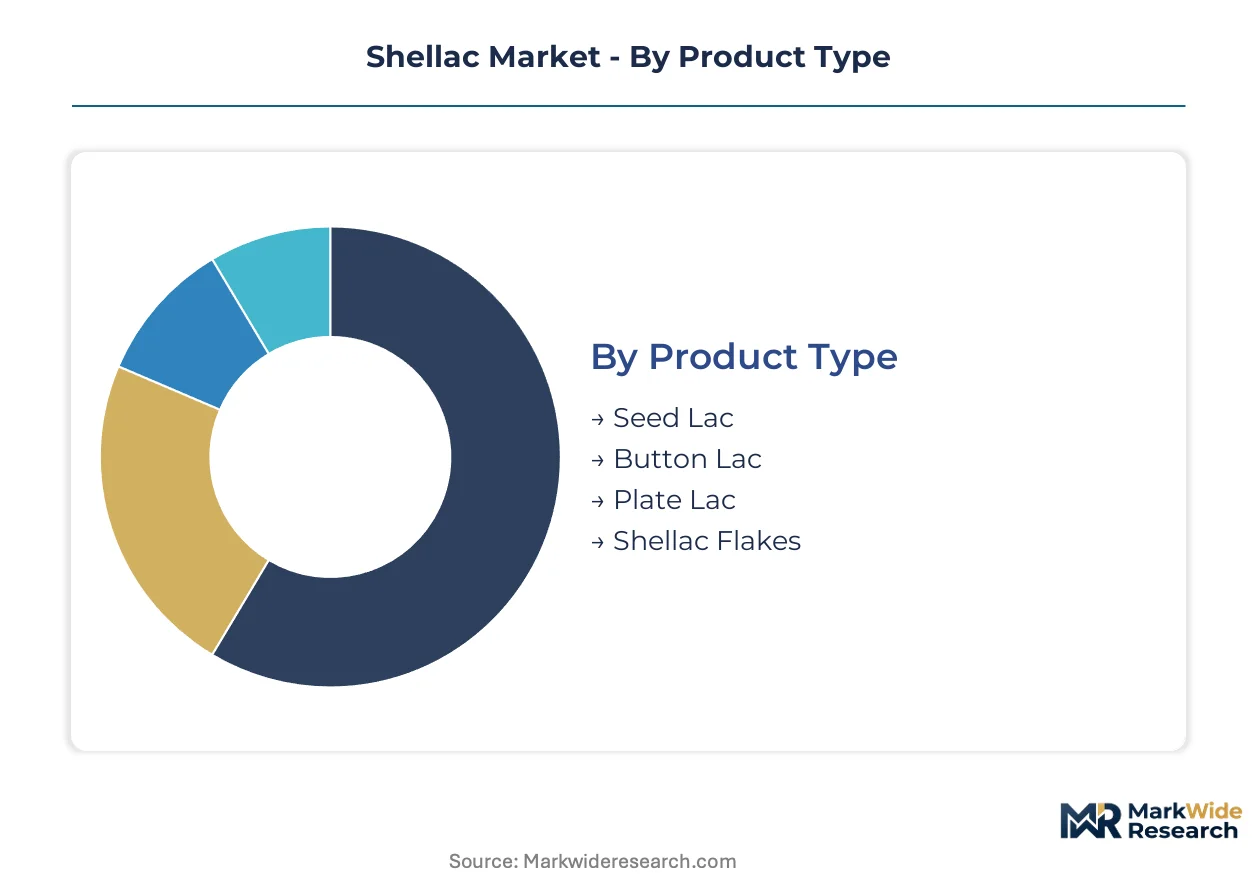
Shellac processors configure capital deployment differently across each segment dimension. Product form determines refining equipment requirements, while end-use specifications dictate analytical chemistry investments needed for regulatory compliance.
Product Type:
Capital intensity peaks in dewaxed flake production, where solvent extraction systems and closed-loop hexane recovery infrastructure dominate cost structures.
- Shellac Flakes:Standardized dissolution rates from controlled dewaxing protocols meet FDA 21 CFR 175.105 and EMA excipient specifications. Pharmaceutical formulators in Germany and Switzerland specify sub-0.2% wax content, concentrating demand among processors with chromatographic purification capacity.
- Button Lac:Heat-fusion molding into circular discs preserves higher wax content suitable for industrial adhesive applications. Furniture manufacturers in India and Vietnam prefer this grade for cost-sensitive wood finishing where moisture barrier performance outweighs clarity requirements.
- Seed Lac:Crude resin mechanically separated from twig fragments serves as feedstock for downstream refining.
- Plate Lac:Flat-sheet casting yields intermediate purity grades for food glazing applications.
Shellac Flakes absorbs the bulk of installed capacity; Shellac Flakes is expanding most quickly.
Application:
Margin profiles diverge sharply between regulated pharmaceutical coatings and commodity wood finishing markets.
- Pharmaceuticals:Enteric coating for controlled-release drug delivery requires heavy metal and pesticide residue documentation under EMA updated guidelines. Swissmedic and TGA-registered suppliers capture premium positioning through excipient master file maintenance.
- Food Coating:Confectionery manufacturers replace synthetic glazes with natural alternatives, driving FSSAI and BIS IS 348-1966 certification demand across Bihar-Jharkhand supply chains.
- Cosmetics:Clean beauty nail care formulations favor plant-derived film formers in prestige retail channels.
- Wood Finishing:Traditional lacquer applications compete with polyurethane substitutes on durability metrics.
Pharmaceuticals commands the highest unit margins; Food Coating is climbing the fastest.
End User:
Procurement sophistication varies from tribal collector networks serving furniture makers to qualified supplier programs at multinational drug manufacturers.
- Pharmaceutical Companies:FDA-specified purity thresholds and lot-level analytical certificates mandate ICP-MS instrumentation at processor sites. CDSCO-registered facilities in India align with PLI scheme incentives for excipient localization.
- Food Industry:Confectionery consolidation around dual-certified suppliers simplifies vendor qualification overhead for European and North American buyers.
- Cosmetic Manufacturers:Clean beauty positioning drives specification of aleuritic acid-rich grades for nail enamel durability.
- Furniture Makers:Artisanal woodworkers in Southeast Asia source button lac through regional trading networks.
Pharmaceutical Companies imposes the steepest compliance burden; Pharmaceutical Companies is gaining share fastest.
Form:
Physical state determines logistics economics and customer formulation labor.
- Liquid:Pre-dissolved shellac in ethanol solution eliminates in-house dissolution equipment for small-scale pharmaceutical and cosmetic formulators.
- Powdered:Micronized particle sizes enable direct compression in tablet coating operations.
- Granular:Intermediate dissolution kinetics suit mid-scale food coating operations.
- Tablet:Unit-dose packaging serves analytical reference standard and laboratory reagent markets.
Liquid captures the highest logistics cost premium; Powdered is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bihar and Jharkhand's lac cultivation belt supplies the majority of global raw sticklac, with seasonal harvesting patterns dictating downstream availability across pharmaceutical and food coating industries worldwide.
India
Bihar and Jharkhand's tribal collector networks feed crude lac into processing corridors around Kolkata and Mumbai. BIS mandates IS 348-1966 certification for food-grade exports, tightening purity documentation across supply chains. CDSCO-registered refiners in Maharashtra align with PLI scheme incentives for pharmaceutical excipient localization.
Germany
Pharmaceutical formulators in Hamburg and Frankfurt specify sub-0.2% wax content for enteric coating applications. EMA's updated excipient guidelines demand ICP-MS-verified heavy metal documentation from every lot. Stroever GmbH & Co. KG anchors European refining capacity with technical service capabilities serving Swiss and Austrian drug manufacturers.
United States
Confectionery manufacturers in Chicago and New Jersey replace synthetic glazes with natural shellac alternatives for clean-label positioning. FDA specifications under 21 CFR 175.105 mandate batch-level purity thresholds that favor established processors with analytical capabilities. Mantrose-Haeuser Co., Inc. dominates North American distribution through specialized food and pharmaceutical coating divisions.
Switzerland
Swissmedic-registered suppliers capture premium positioning in controlled-release drug delivery markets. Swiss pharmaceutical manufacturers require excipient master file maintenance and third-party analytical certificates for every shipment. Basel and Zurich serve as qualification hubs for shellac entering EU and TGA-regulated supply chains.
Brazil
ANVISA's evolving excipient guidelines create first-mover opportunities for shellac suppliers establishing local technical partnerships. São Paulo's generic pharmaceutical manufacturers seek natural coating alternatives for export qualification to regulated markets. Brazilian distributors increasingly demand dual food-grade and pharmaceutical certifications from Asian exporters.
Shellac Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification and analytical capability tiers. The supplier base compresses toward integrated operators with multi-jurisdictional regulatory dossiers already filed. Three archetypes dominate: cultivation-integrated Indian processors, European refiners with pharmaceutical excipient master files, and North American distributors with specialized coating divisions. Competitive moves center on chromatographic purification capacity expansion and backward integration into Bihar-Jharkhand collector networks.
Among cultivation-integrated processors, D. Manoharlal (Shellac) Pvt. Ltd. represents the Indian archetype with operations spanning Bihar's lac belt. European refining specialists exemplify the quality-tier position, with Stroever GmbH & Co. KG occupying a position in Hamburg-based technical service. North American distribution concentration sits with Mantrose-Haeuser Co., Inc., which anchors the regional food and pharmaceutical coating supply chain.
| Leading Market Players |
|---|
| D. Manoharlal (Shellac) Pvt. Ltd. |
| Vishnu Shellac Factory |
| Mantrose-Haeuser Co., Inc. |
| Rust-Oleum |
| Hind Suter Shellac Pvt. Ltd. |
| Stroever GmbH & Co. KG |
| A.F. Suter & Company Ltd |
| Gifu Shellac Manufacturing Co., Ltd |
| Chuxiong DES Shellac Co., Ltd. |
| Others |
Value Network & Pricing Analysis
EU REACH registration requirements for natural resin imports gate both qualified supply and premium-tier pricing access, as pharmaceutical and food coating buyers reject uncertified processors regardless of raw material cost advantages. Compliance documentation for heavy metal and pesticide residues separates price-takers from price-makers across European and North American markets.
Pricing Analysis
Pharmaceutical yield-per-batch anchors value-based pricing for dewaxed shellac flakes, with Swissmedic-registered suppliers capturing substantial premiums over industrial-grade button lac processors. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade levels reflects certification investment and chromatographic purification capability. Cost compression in industrial wood finishing tiers intensifies because polyurethane substitutes erode volume leverage. Furniture manufacturers in Vietnam exhibit highest price sensitivity; German drug formulators demonstrate lowest sensitivity due to excipient master file switching costs.
Supply Chain Analysis
Reverse-logistics infrastructure for solvent recovery and dewaxing residue processing distinguishes integrated refiners from toll-dependent operators competing on thin conversion margins. Raw sticklac supply concentrates in India, Thailand, and Myanmar, with Bihar-Jharkhand cultivation clusters feeding downstream corridors around Kolkata and Mumbai. Crude lac availability draws from monsoon-dependent forest host tree ecosystems and dispersed tribal collector networks. Single-source vulnerability in eastern Indian states transmits climate anomaly shocks immediately to pharmaceutical coating supply chains. Distribution runs through Hamburg and Rotterdam pharmaceutical hubs for European formulators, Mumbai-JNPT corridor for Asian processors, and Chicago-New Jersey axis for North American confectionery manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into Bihar-Jharkhand collector networks constitutes the decisive upstream lever in this vertical-integration race, as processors securing captive raw material access insulate margin structures from monsoon volatility and intermediary markups.
For Market Incumbents: Extend chromatographic purification capacity to meet sub-0.2% wax pharmaceutical specifications, locking in Swiss and German drug manufacturer contracts before EMA excipient master file timelines marginalize smaller competitors. Defend against hydroxypropyl methylcellulose substitution in enteric coating by embedding analytical chemists directly at customer formulation sites, converting technical service relationships into switching-cost moats.
For New Entrants and Emerging Players: Begin with ANVISA pre-qualification partnerships in São Paulo's generic pharmaceutical corridor, where Brazilian manufacturers seek natural coating alternatives for export market access without incumbent supplier switching costs. Target cosmetic nail care formulations in prestige retail channels resistant to petroleum-derived competitors, leveraging clean beauty positioning to bypass established pharmaceutical certification barriers.
For Investors and Strategic Acquirers: CDSCO registration under India's PLI scheme for excipient localization is the leading indicator that domestic processors will achieve cost parity with imported refined grades, compressing import-dependent distributor margins. Long-term viability hinges on cultivation-integrated processors with established collector networks and multi-jurisdictional regulatory dossiers already filed. Watch for ICP-MS instrumentation installation announcements as the inflection signal separating quality-tier consolidators from commodity-margin casualties.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collector Networks | Captive raw material supply from Bihar-Jharkhand tribal networks insulates processors from monsoon price spikes. |
| ICP-MS Instrumentation Installation | In-house heavy metal verification under EMA guidelines eliminates external laboratory turnaround delays for EU exporters. |
| Dual Certification Investment | Simultaneous FDA 21 CFR 175.105 and BIS IS 348-1966 qualification opens both pharmaceutical and confectionery procurement channels. |
| Excipient Master File Maintenance | Swissmedic and TGA registration creates switching-cost barriers against synthetic polymer substitutes in controlled-release drug delivery. |
| Solvent Recovery System Deployment | Closed-loop hexane recovery infrastructure reduces variable costs in dewaxed flake production for pharmaceutical specifications. |
Research Methodology
Document review covered BIS certification records, CDSCO registration filings, and EMA excipient master file databases, complemented by interviews with shellac refinery plant managers, pharmaceutical procurement leads at German and Swiss drug manufacturers, confectionery category buyers in Chicago and New Jersey, and tribal collector network coordinators in Bihar. Secondary validation drew from customs trade data for natural resin shipments, SEC filings of North American coating distributors, and FSSAI compliance audit reports. Bottom-up volume estimates from cultivation belt harvest data triangulated against top-down pharmaceutical excipient consumption models.
Historical export volume trajectories from Indian customs authorities cross-referenced against panel input from European pharmaceutical formulators established baseline growth parameters across the projection horizon. Segmentation modeling incorporated product form, application tier, end-user sophistication, and regional regulatory cluster dimensions. CAGRs derived from elasticity-adjusted demand curves for enteric coating applications and clean-label confectionery substitution rates. Forecast inputs included monsoon reliability indices for Bihar-Jharkhand and ANVISA regulatory timeline assumptions for Brazilian market entry.
Underlying measurement precision varies by segment; pharmaceutical-grade shellac carries tighter precision than industrial button lac due to documented lot-level analytical certificates. Forecasts reflect assumptions regarding EMA guideline stability and PLI scheme continuity for Indian excipient localization. Material deviation in monsoon patterns, Kerria lacca pest outbreaks, or synthetic polymer substitution acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Textile Printing Market
Textile Chemicals, Dyes, and Finishing
Textile Auxiliaries Market
Textile Chemicals, Dyes, and Finishing
Textile Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Asia Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Chemicals Market
Textile Chemicals, Dyes, and Finishing
Textile Colors Market
Textile Chemicals, Dyes, and Finishing
Waterless Textile Dyeing Services Market
Textile Chemicals, Dyes, and Finishing
Leather Dyes Market
Textile Chemicals, Dyes, and Finishing
Dyes Market
Textile Chemicals, Dyes, and Finishing
Dye Sublimation Printing Market
Textile Chemicals, Dyes, and Finishing
FD and C Dyes Market
Textile Chemicals, Dyes, and Finishing
Global Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
PVC Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Lining Fabric Market
Textile Chemicals, Dyes, and Finishing
Textile Leveling Agent Market
Textile Chemicals, Dyes, and Finishing
3-Layer Seam Tapes Market