
 Silicone Textile Chemicals Market | 2026-2036
Silicone Textile Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Silicone Textile Chemicals Market Analytics
Polydimethylsiloxane is broadening its addressable market as textile mills phase out hydrocarbon-based softeners on sustainability and performance grounds. Dow leverages captive silicone monomer supply to anchor pricing stability across emulsion grades. Momentive competes through specialized antistatic formulations for synthetic fiber processors. Wacker Chemie AG sustains European leadership with ISO-certified liquid silicone systems for technical textiles.
Silicone textile chemicals encompass organosilicon compounds formulated as emulsions, powders, pastes, or liquids to impart softness, water repellency, antistatic properties, or surfactant functionality to natural and synthetic fibers; these formulations typically contain 15-35% active silicone content with viscosity ranges from 1,000 to 100,000 cSt depending on the desired hand-feel and durability profile. The primary commercial purpose centers on modifying fabric surface energy and tactile properties without compromising breathability or colorfastness. Softening agents occupy the largest volume share as apparel brands standardize silicone finishing for premium cotton and blended knits. Water repellent agents represent the fastest-expanding category as automotive upholstery specifications tighten against fluorinated alternatives. Emulsion forms dominate formulation flexibility for continuous pad-dry-cure processes, while powder grades serve niche industrial fabric applications requiring thermal stability above 180°C.
REACH compliance through ECHA governs silicone emulsion imports into European Union member states, while EPA oversight under TSCA Section 5 affects new silicone chemistry introductions in United States textile chemical portfolios. China's GB standards through SAMR establish emission thresholds for silicone volatile organic compounds in finishing operations. India BIS certification requirements for textile auxiliaries create compliance checkpoints for silicone antistatic agent imports. Stakeholders must monitor regulatory divergence between perfluorinated compound bans and silicone substitution pathways across major textile manufacturing jurisdictions.
Market Dynamics
REACH restrictions on perfluorinated compounds in Europe are redirecting formulation investment toward silicone water repellents, while sportswear brands now specify silicone softening agents for performance fabrics.
Growth Catalysts
- Perfluorinated compound bans:REACH restrictions in Europe eliminate fluorinated water repellents, forcing mills to adopt silicone alternatives for technical textiles and outdoor apparel.
- Synthetic fiber processing:Polyester and nylon manufacturers require antistatic silicone formulations to manage electrostatic buildup during high-speed spinning operations.
- China, India, and Vietnam:These countries concentrate new textile finishing capacity, creating concentrated demand hubs for silicone emulsion supply.
Market Restraints
- D4/D5/D6 siloxane volatility:Raw material costs for cyclic siloxanes fluctuate with energy prices, compressing margin stability for emulsion producers.
- Specialized technical talent:Formulation chemists with organosilicon expertise concentrate in Germany, Japan, and the United States, limiting R&D scalability elsewhere.
- Polyurethane softener competition:Hydrophilic polyurethane alternatives compete on cost for mid-tier cotton knit applications where premium hand-feel is not specified.
Strategic Opportunities
- India technical textiles:The country's BIS certification requirements create compliance checkpoints that favor established silicone suppliers with testing infrastructure.
- Automotive upholstery specifications:Tier-1 seating suppliers are tightening water repellency standards against fluorinated alternatives, opening specification wins for silicone systems.
- Digital textile printing compatibility:Silicone softening agents that maintain ink adhesion are capturing share as mills retrofit for on-demand production workflows.
Industry Challenges
- ISO 17025 laboratory accreditation:Mills require certified testing partners for silicone durability validation, creating bottlenecks in supplier qualification timelines.
- Legacy pad-dry-cure equipment:Continuous finishing lines designed for hydrocarbon softeners require retrofitting for silicone emulsion viscosity profiles and curing temperatures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicone Textile Chemicals Market |
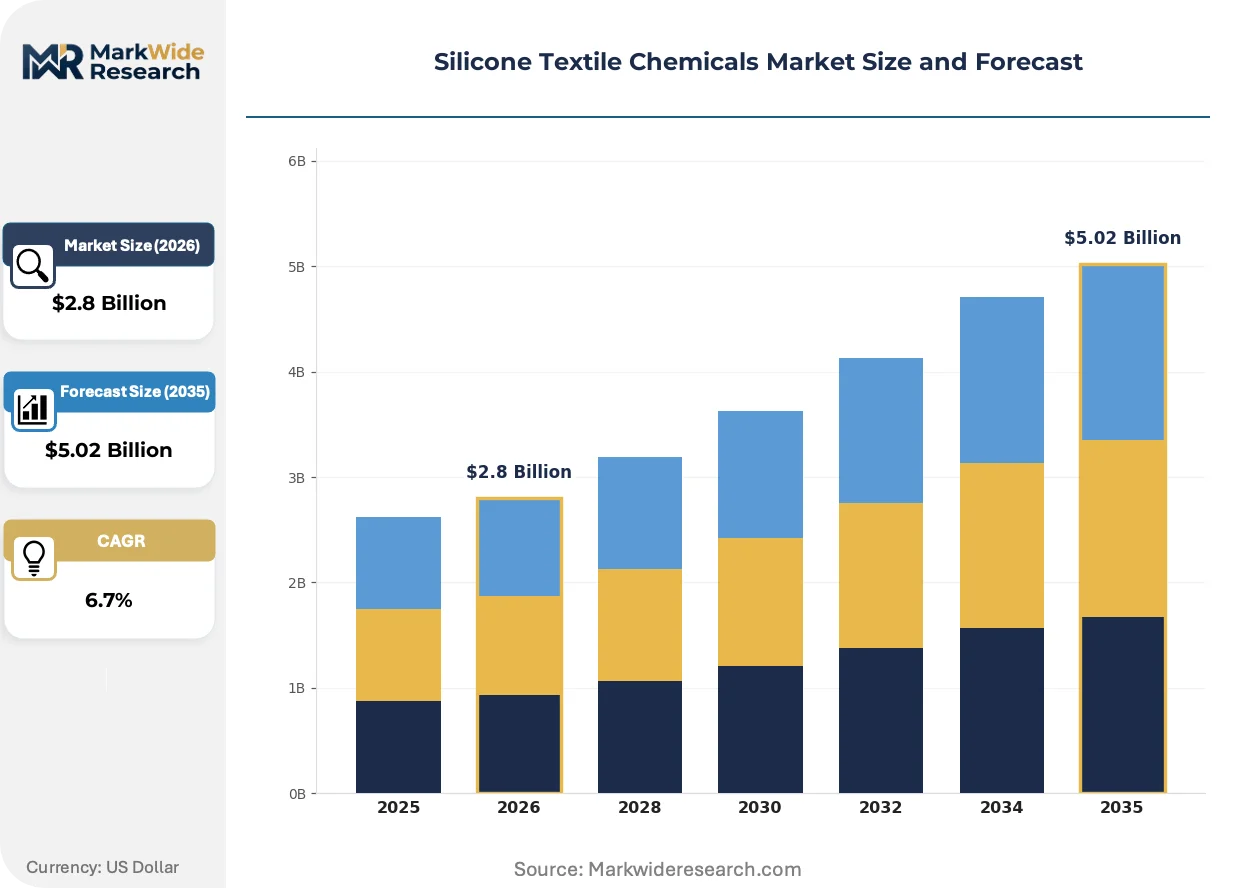
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Softening Agents, Water Repellent Agents, Antistatic Agents, Surfactants Application: Apparel, Home Textiles, Automotive Upholstery, Industrial Fabrics End User: Textile Manufacturers, Apparel Brands, Distributors, Retailers Form: Emulsion, Powder, Paste, Liquid |
| Companies Covered | Momentive, Evonik Industries AG, Wacker Chemie AG, Huntsman International LLC, Mitsubishi Chemical Corporation, Shin-Etsu Chemical Co., Ltd., Elkem ASA, CHT Germany GmbH, Dow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicone Textile Chemicals Market Evolving Landscape
Formulation chemistry is pivoting toward bio-based silicone precursors and low-temperature curing systems that reduce energy intensity in finishing operations.
Microemulsion silicone technology is decentralizing supply chain dependencies for textile mills. These sub-micron particle systems deliver superior fiber penetration compared to conventional macroemulsions. Denim laundries in Turkey and Mexico are adopting microemulsion softeners to achieve premium hand-feel without multiple finishing passes. The technology is decentralizing production geography by enabling smaller regional formulators to compete with integrated suppliers on performance parity.
China's GB standards through SAMR establish emission thresholds for silicone volatile organic compounds in finishing operations. These rules force mills to install vapor recovery systems or switch to low-VOC emulsion grades. Guangdong and Zhejiang provinces enforce the strictest interpretations, accelerating capital expenditure cycles for compliance upgrades.
Brand-led chemical management is compressing supplier qualification cycles. Apparel brands now mandate ZDHC MRSL conformance for silicone auxiliaries, shifting procurement evaluation from price-per-kilogram to total chemical footprint scoring. This pattern is most visible in Bangladesh and Vietnam, where vertically integrated manufacturers must maintain multiple certification streams to serve European and North American retail channels simultaneously.
Silicone Textile Chemicals Market Segmentation
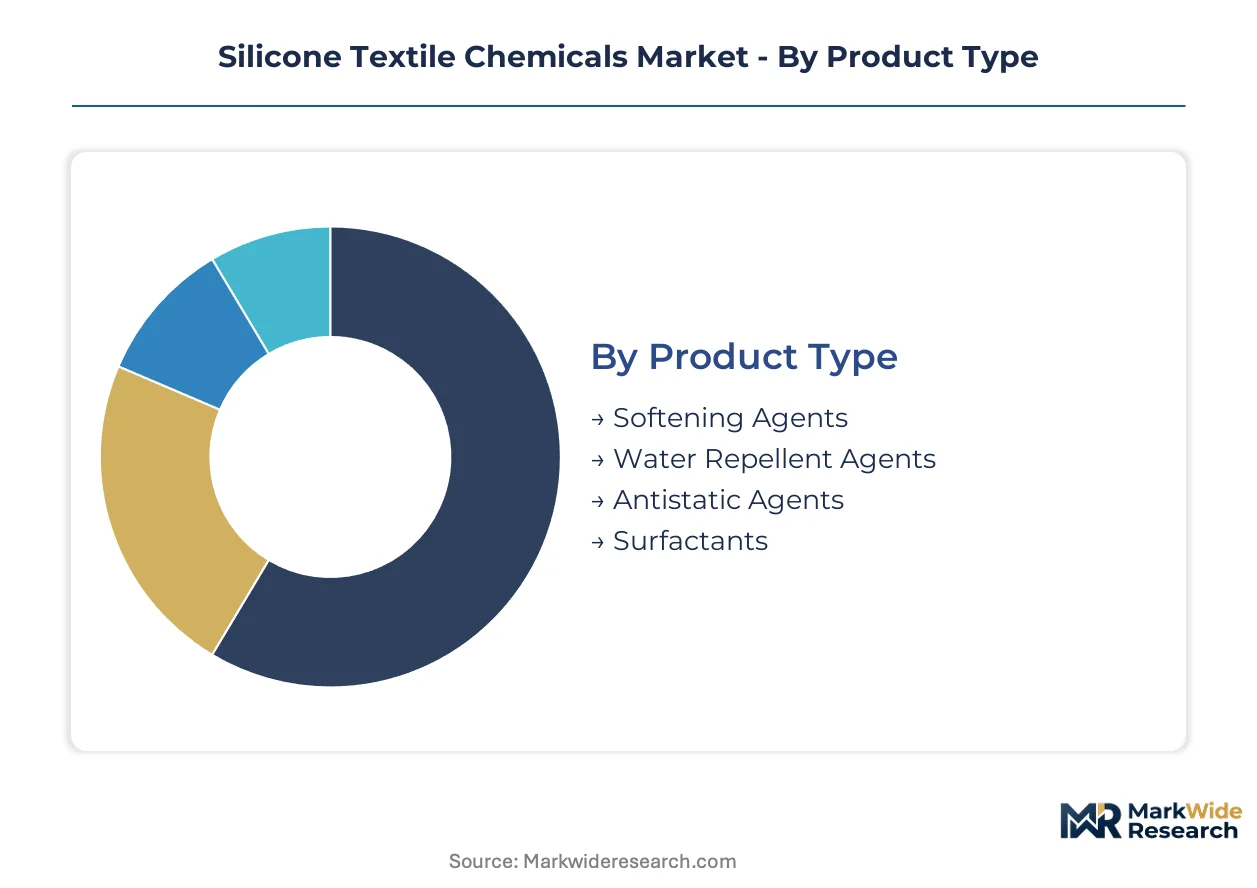
Silicone textile chemicals serve divergent performance requirements across fiber types and finishing processes. Segmentation reveals how formulation chemistry, delivery form, and customer procurement patterns create distinct competitive arenas with different margin structures and technical barriers.
Product Type:
Volume concentrates in commodity softening agents while premium pricing accrues to specialized repellent and antistatic formulations.
- Softening Agents:Polydimethylsiloxane-based emulsions dominate cotton and blended knit finishing, with 15-35% active silicone content delivering calibrated hand-feel. Demand concentrates in Bangladesh and Vietnam as vertically integrated apparel manufacturers standardize silicone finishing for premium retail channels. REACH restrictions on hydrocarbon alternatives reinforce specification stickiness.
- Water Repellent Agents:Amino-functional silicone polymers create durable hydrophobic surfaces without fluorinated chemistry. Automotive upholstery specifications in Germany and tier-1 seating supplier audits in the United States are displacing perfluorinated compounds fastest, opening specification wins for silicone systems with verified durability above 50 wash cycles.
- Antistatic Agents:Cationic silicone formulations manage electrostatic buildup in polyester and nylon high-speed spinning operations.
- Surfactants:Silicone-polyether copolymers function as wetting agents and foam controllers in dyeing and printing processes.
Today's leader: Softening Agents. Tomorrow's challenger: Water Repellent Agents.
Application:
Apparel commands the largest volume footprint while automotive and industrial applications extract premium pricing through specification intensity.
- Apparel:Sportswear brands in the United States and European Union now mandate silicone softening agents for performance fabrics, with ZDHC MRSL conformance becoming a non-negotiable procurement filter. Digital textile printing compatibility is emerging as a secondary selection criterion as mills retrofit for on-demand workflows.
- Home Textiles:Bed linen and towel manufacturers specify silicone finishing for premium hand-feel and absorbency balance.
- Automotive Upholstery:Tier-1 seating suppliers in Germany, the United States, and Japan are tightening water repellency standards against fluorinated alternatives. OEM durability specifications require ISO 17025 laboratory accreditation for supplier qualification, creating compliance bottlenecks that favor established silicone formulators with captive testing infrastructure.
- Industrial Fabrics:Technical textiles for filtration, medical, and protective applications require thermal stability above 180°C.
Automotive Upholstery claims the steepest expansion trajectory as fluorinated compound bans accelerate silicone substitution.
End User:
Procurement authority is fragmenting as apparel brands centralize chemical management while textile manufacturers retain formulation selection for undifferentiated applications.
- Textile Manufacturers:Continuous finishing lines in China, India, and Vietnam drive emulsion demand through pad-dry-cure processes. These operators face capital expenditure pressure from China's GB standards through SAMR, which enforce vapor recovery systems or low-VOC emulsion switches in Guangdong and Zhejiang provinces.
- Apparel Brands:Chemical footprint scoring now dominates procurement evaluation for European and North American retail channels. Bangladeshi and Vietnamese vertically integrated manufacturers must maintain multiple certification streams simultaneously, compressing supplier qualification cycles from months to weeks.
- Distributors:Regional formulators in Turkey and Mexico leverage microemulsion technology to compete with integrated suppliers on performance parity.
- Retailers:Private label specifications increasingly reference ZDHC conformance for silicone auxiliaries.
Textile Manufacturers control volume flows. Apparel Brands control specification standards.
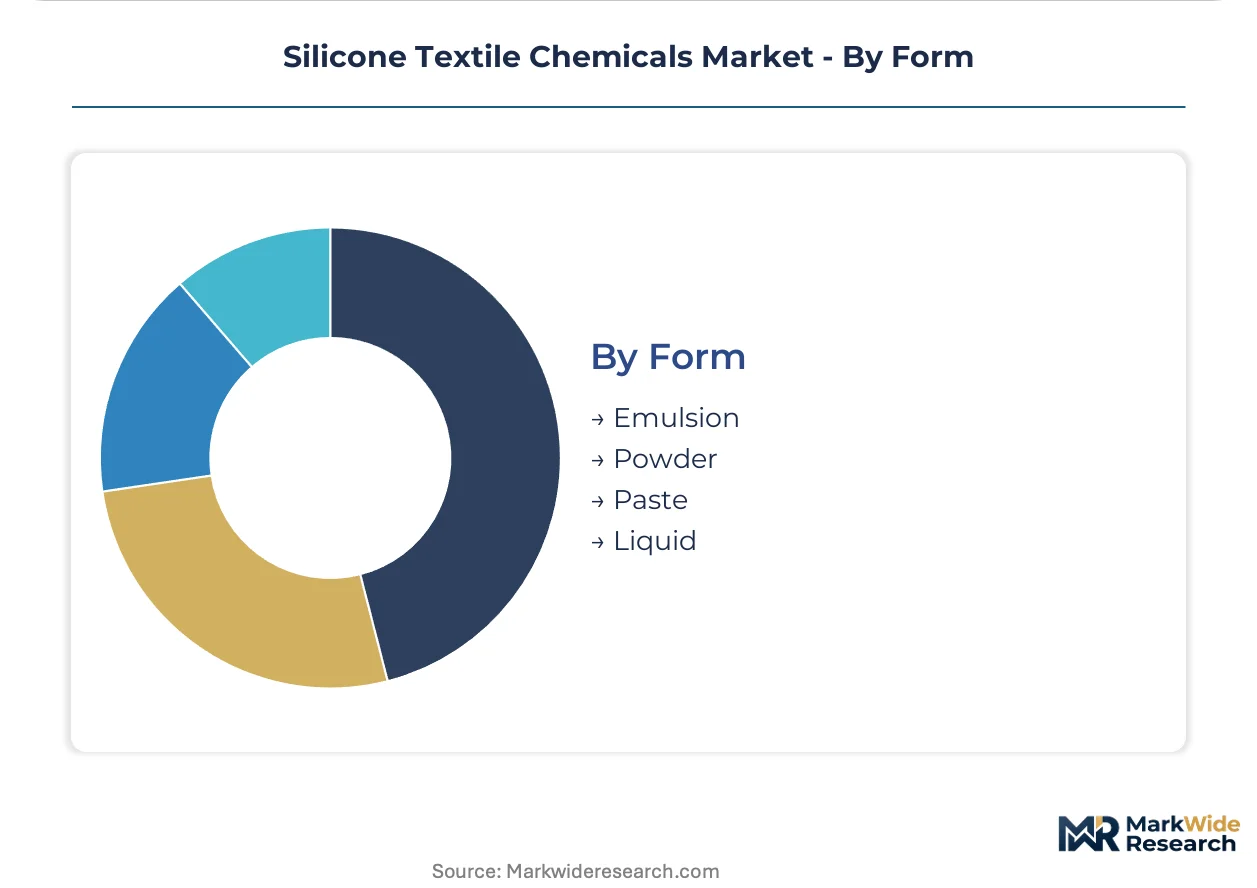
Form:
Emulsion dominates continuous processing while powder and liquid formats serve niche thermal and precision application requirements.
- Emulsion:Macroemulsion and microemulsion systems deliver formulation flexibility for pad-dry-cure operations, with sub-micron particle sizes achieving superior fiber penetration. Denim laundries in Turkey and Mexico are adopting microemulsion softeners to achieve premium hand-feel without multiple finishing passes.
- Powder:Thermal stability above 180°C serves industrial fabric applications where liquid carriers degrade.
- Paste:High-viscosity formulations enable targeted application in garment finishing and localized treatment.
- Liquid:ISO-certified liquid silicone systems from German suppliers anchor European technical textile specifications.
Emulsion maintains volume leadership. Microemulsion technology is decentralizing production geography fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta and Pearl River Delta anchor global silicone textile chemical consumption as apparel manufacturers consolidate finishing capacity. Textile clusters in Bangladesh and Vietnam absorb emulsion supply for vertically integrated sportswear production. REACH compliance in Europe and GB standards enforcement in Guangdong reshape formulation requirements across major demand centers.
China
Guangdong and Zhejiang provinces enforce the strictest GB standard interpretations through SAMR, forcing mills to install vapor recovery systems or switch to low-VOC silicone emulsion grades. Polyester and nylon manufacturers in the Yangtze River Delta require antistatic formulations for high-speed spinning operations. Denim laundries in Guangzhou are retrofitting continuous finishing lines for silicone emulsion viscosity profiles.
India
Technical textile specifications from automotive seating suppliers in Pune and Chennai drive specification-grade silicone demand. BIS certification requirements for textile auxiliaries create compliance checkpoints that favor established suppliers with captive testing infrastructure. Maharashtra and Gujarat textile clusters face capital expenditure pressure as mills upgrade pad-dry-cure equipment for silicone compatibility.
Germany
REACH restrictions through ECHA eliminate fluorinated water repellents, redirecting formulation investment toward amino-functional silicone polymers for technical textiles. OEM durability specifications from tier-1 automotive seating suppliers in Stuttgart require ISO 17025 laboratory accreditation for supplier qualification. Bavarian chemical formulators anchor European leadership with ISO-certified liquid silicone systems.
United States
EPA oversight under TSCA Section 5 affects new silicone chemistry introductions in textile chemical portfolios. Sportswear brands in the Pacific Northwest and Southeast now mandate silicone softening agents for performance fabrics with ZDHC MRSL conformance. Tier-1 seating supplier audits in Michigan and Ohio are displacing perfluorinated compounds fastest in automotive upholstery applications.
Vietnam
Vertically integrated apparel manufacturers in Ho Chi Minh City and Binh Duong must maintain multiple certification streams simultaneously to serve European and North American retail channels. Procurement evaluation has shifted from price-per-kilogram to total chemical footprint scoring under brand-led chemical management protocols. Local mills retrofit continuous finishing lines originally designed for hydrocarbon softeners to accommodate silicone emulsion curing temperatures.
Silicone Textile Chemicals Market Competitive Landscape
Global majors compete with regional champions across formulation technology and certification infrastructure. The vendor base clusters around three strategic archetypes: integrated silicone monomer producers with captive emulsion supply, specialized textile auxiliary formulators with regional testing networks, and diversified chemical conglomerates with portfolio diversification into organosilicon chemistry. Dominant competitive moves include backward integration into silicone monomer production and geographic expansion through distribution partnerships in high-growth Asian markets.
Within the integrated producer tier, Dow and Wacker Chemie AG exemplify archetypes anchored by captive silicone monomer supply chains. Momentive occupies a position representing specialized antistatic formulation capabilities for synthetic fiber processors. These three companies collectively illustrate how raw material security and certification infrastructure determine competitive positioning in specification-intensive end uses.
| Leading Market Players |
|---|
| Momentive |
| Evonik Industries AG |
| Wacker Chemie AG |
| Huntsman International LLC |
| Mitsubishi Chemical Corporation |
| Shin-Etsu Chemical Co., Ltd. |
| Elkem ASA |
| CHT Germany GmbH |
| Dow |
| Others |
Value Network & Pricing Analysis
Tier-1 automotive seating suppliers in Germany and the United States anchor contract-based pricing with ISO 17025 accreditation premiums, while Bangladeshi apparel mills negotiate spot emulsion purchases on active silicone content metrics.
Pricing Analysis
Cyclic siloxane volatility in D4/D5/D6 feedstocks compresses margin stability for emulsion producers, with cost pass-through lagging energy price swings by one to two procurement cycles. Three-tier pricing structure across premium certified, standard industrial, and economy bulk grades differentiates on REACH compliance and ZDHC MRSL conformance. Pricing pressure stems from polyurethane softener competition in mid-tier cotton knits where hand-feel specifications remain undemanding. Textile manufacturers in Vietnam and India exhibit highest price sensitivity, while automotive OEMs in Stuttgart and Detroit absorb certification premiums without volume elasticity.
Supply Chain Analysis
India's BIS certification requirements for textile auxiliaries are reshaping sourcing toward domestic formulators with captive testing infrastructure in Maharashtra and Gujarat. Silicone textile chemical supply concentrates in Germany, China, and the United States, with raw material dependencies on metallurgical-grade silicon, methanol, and chloromethane. Single-source vulnerability runs through Yangtze River Delta monomer production exposed to energy rationing directives. Distribution runs through regional specialty chemical distributors in Ho Chi Minh City, Dhaka, and Istanbul who blend and certify emulsions for local mill specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Silicone Textile Chemicals Market functions as a geographic-arbitrage play where REACH compliance costs in Europe exceed GB standard adaptation expenses in Guangdong by a factor that rewards dual-registered suppliers.
For Market Incumbents: Anchor specification stickiness through captive ISO 17025 laboratory accreditation that accelerates automotive OEM qualification timelines. Deepen backward integration into silicone monomer production to neutralize D4/D5/D6 price volatility threatening emulsion margins. Prioritize low-VOC emulsion registration under China's SAMR enforcement corridors in Guangdong and Zhejiang before local competitors achieve formulation parity. For New Entrants and Emerging Players: Regional denim laundries in Turkey and Mexico represent the most penetrable buyer archetype, as microemulsion technology enables performance parity without integrated supply chain scale. Target technical textile specifications for medical and filtration fabrics above 180°C thermal stability where powder-grade silicone commands premium positioning. Pursue distribution partnerships with established specialty chemical channels in Binh Duong and Ho Chi Minh City rather than direct mill sales. For Investors and Strategic Acquirers: Specialty chemical conglomerates seeking organosilicon portfolio diversification are the most active acquirer in this space, with valuation premiums attaching to BIS-certified testing infrastructure in India. The acquisition target archetype combines regional formulator scale with automotive upholstery specification wins against fluorinated alternatives. Watch for REACH expansion of perfluorinated compound restrictions beyond water repellents into broader textile auxiliary categories as the inflection signal for silicone substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Monomer Production | Dow and Wacker Chemie AG neutralize feedstock volatility through captive chlorosilane supply. |
| ISO 17025 Laboratory Accreditation Investment | German and Indian suppliers compress automotive OEM qualification timelines from months to weeks. |
| Low-VOC Emulsion Registration under SAMR | Guangdong and Zhejiang mills face forced switching as vapor recovery capex exceeds formulation upgrade costs. |
| Microemulsion Technology Licensing | Turkish and Mexican regional formulators achieve performance parity with integrated suppliers. |
| ZDHC MRSL Certification Stream Maintenance | Bangladeshi and Vietnamese vertically integrated manufacturers retain European and North American retail access. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with textile chemical procurement managers, silicone emulsion plant operators, automotive tier-1 supplier quality directors, and REACH compliance consultants with secondary validation. Trade data from customs authorities, SEC filings from integrated chemical producers, GB standard enforcement notices from SAMR, and ZDHC conformance databases anchored the quantitative foundation. Bottom-up emulsion volume estimates triangulated against top-down silicone monomer consumption patterns.
Historical reference periods spanning pre-pandemic baseline, supply disruption trough, and recovery normalization anchored the forecast window across the projection horizon. Segmentation modeling incorporated product type, application end-use, delivery form, and regional production hub dimensions. CAGRs derived from elasticity-adjusted demand curves reflecting synthetic fiber processing rates, REACH regulatory phase-in schedules, and automotive upholstery specification migration timelines.
Underlying measurement precision varies by segment; automotive upholstery and technical textiles carry tighter precision than commodity apparel softening due to specification documentation density. Forecasts reflect assumptions on perfluorinated compound ban expansion velocity, energy price stabilization in siloxane production, and BIS certification enforcement consistency in India. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Textile Colors Market
Textile Chemicals, Dyes, and Finishing
Cationic Dyes Market
Textile Chemicals, Dyes, and Finishing
Fabric Odor Eliminator Market
Textile Chemicals, Dyes, and Finishing
Waterless Textile Dyeing Services Market
Textile Chemicals, Dyes, and Finishing
Oil Colors Market
Textile Chemicals, Dyes, and Finishing
Textile Wax Market
Textile Chemicals, Dyes, and Finishing
Europe Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Embroidery Thread Market
Textile Chemicals, Dyes, and Finishing
Antimicrobial Textile Additive Market
Textile Chemicals, Dyes, and Finishing
Global Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Global Sulfur Dye Market
Textile Chemicals, Dyes, and Finishing
Carmine Color Market
Textile Chemicals, Dyes, and Finishing
Fiberglass Coated Fabric Market
Textile Chemicals, Dyes, and Finishing
Disperse Dyes Market
Textile Chemicals, Dyes, and Finishing
Dye Sublimation Printing Market
Textile Chemicals, Dyes, and Finishing
Textile Printing Market