
 Textile Dyestuff Market | 2026-2036
Textile Dyestuff Market Size, Share, and Industry Trends Forecast 2026-2036
Textile Dyestuff Market Intelligence
The OEKO-TEX STANDARD 100 certification is bifurcating the competitive landscape, separating suppliers who can meet stringent human-ecological safety requirements from those who cannot. Archroma leverages its portfolio of sustainable dyestuff solutions to capture premium segments. Huntsman International LLC competes on its global manufacturing scale and extensive distribution network, particularly in reactive and disperse dyes. This creates a clear divide between innovators and commodity producers.
Textile dyestuff comprises synthetic or natural colorants that chemically bond with fiber substrates like cotton, polyester, and wool. These substances achieve coloration through processes involving covalent or ionic bonds, ensuring colorfastness during washing and light exposure. Reactive dyes maintain a dominant share for cellulosic fibers used in apparel, while the disperse dye category is essential for coloring synthetic polyester fabrics. Demand within the technical textiles application for durable and functional coloration is expanding faster than traditional home textiles.
Regulatory frameworks, including the EU's REACH legislation and directives from China's MEE, are reshaping the chemical composition of dyestuffs by restricting hazardous substances. In the United States, the EPA's regulations on wastewater discharge from dyeing units impose significant compliance costs and influence process technology choices. Suppliers must decide whether to invest in developing eco-friendly, compliant dyestuffs for premium markets or compete on volume in less stringent regions.
Market Dynamics
The central dynamic in the textile dyestuff market is the conflict between stringent environmental regulations and the performance demands of technical textiles. This pressure is forcing a bifurcation between suppliers investing in compliant, high-performance chemistries and those competing on volume.
Growth Catalysts
- Technical Textile Demand:The automotive and protective clothing sectors require dyestuffs offering high durability, UV resistance, and specific functional properties, driving development of advanced colorant systems beyond traditional apparel applications.
- Waterless Dyeing Innovation:Technologies such as supercritical CO2 dyeing are gaining traction as they eliminate water consumption and wastewater treatment costs, aligning with stricter environmental mandates from regulators like the US EPA.
- Manufacturing Consolidation:Production is increasingly concentrated in textile hubs like India and Bangladesh, creating efficiencies in the supply chain and providing dyestuff manufacturers with direct access to high-volume customers.
Market Restraints
- Feedstock Price Volatility:The market is vulnerable to price fluctuations in petrochemical-based raw materials, such as benzene and naphthalene derivatives, which are essential precursors for most synthetic dyes and directly impact production costs.
- Regulatory Compliance Burden:Adherence to chemical safety regulations, including the EU's REACH framework, requires extensive testing and documentation, creating significant barriers to entry and adding costs for existing producers.
- Natural Dye Performance Gaps:While demand for natural dyes is present, their limitations in color range, scalability, and colorfastness compared to synthetic counterparts restrict their use in high-performance and mass-market applications.
Strategic Opportunities
- Bio-Based Dyestuffs:Developing colorants from renewable sources like algae, bacteria, or agricultural waste presents an opportunity to capture demand from brands committed to circular economy principles and sustainable material sourcing.
- Digital Textile Printing:The expansion of digital inkjet printing creates a market for specialized, high-purity dye inks that enable on-demand manufacturing, reduce waste, and allow for intricate designs not possible with conventional dyeing.
- Expansion in African Markets:Emerging textile manufacturing centers in countries like Ethiopia and Kenya offer new growth frontiers for dyestuff suppliers as these regions build out their industrial apparel production capacity.
Industry Challenges
- Certification Timelines:Obtaining third-party certifications like OEKO-TEX STANDARD 100 or bluesign is a lengthy and resource-intensive process that can delay the market entry of new and innovative dyestuff formulations.
- Intellectual Property Protection:Safeguarding novel dye chemistries and sustainable process technologies from infringement is a persistent challenge, particularly in jurisdictions with less rigorous IP enforcement frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textile Dyestuff Market |
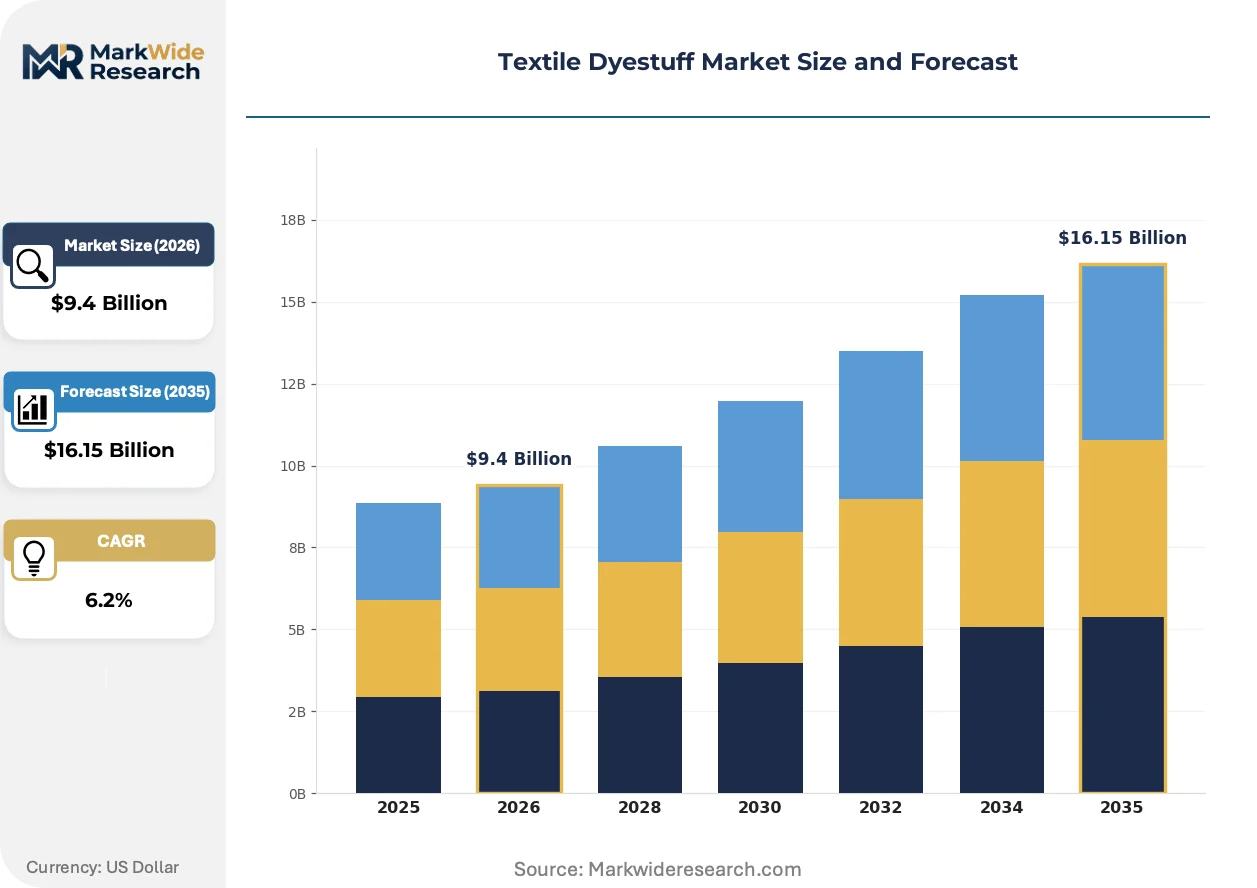
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.15 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reactive, Acid, Direct, Vat, Disperse, Sulfur Application: Woven Fabrics, Knitted Fabrics, Nonwoven Fabrics, Technical Textiles, Home Textiles, Apparel End User Industry: Textile Mills, Garment Manufacturers, Textile Printing Firms, Dyeing Units, Fabric Traders Form: Powder, Granules, Liquid, Paste, Cake |
| Companies Covered | Archroma, Huntsman International LLC, BASF SE, LANXESS, Kiri Industries Ltd, DyStar, Zhejiang Longsheng Group Co., Ltd., Clariant, Atul Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textile Dyestuff Market Strategic Shifts & Innovations
The market's evolution is defined by a push towards sustainable chemistry and process efficiency. Innovations are focused on reducing environmental impact through new technologies and formulations, while regulatory frameworks are forcing a re-evaluation of legacy chemical compositions across the industry.
Micro-encapsulation technology encloses dyestuffs within a functional polymer shell for controlled, targeted release. The performance apparel and smart textiles sectors are adopting this for thermochromic, photochromic, or antimicrobial functionalities. This approach is miniaturizing the delivery mechanism, allowing complex properties to be embedded into fibers without degrading fabric texture or breathability.
China's Ministry of Ecology and Environment (MEE) is enforcing stricter GB standards for wastewater discharge from dyeing facilities. This policy mandates significant upgrades to effluent treatment systems, increasing operational costs for mills using conventional, low-fixation dyes. The disperse and reactive dye segments are most affected, accelerating a shift toward higher-fixation products that minimize dye hydrolysis and effluent load.
A definitive behavioral shift sees apparel brands demanding full chemical traceability and transparency from their suppliers. This is disrupting opaque, multi-layered distribution channels in favor of providers offering certified chemical inventories and digital product passports. This trend is most visible among European and North American fashion retailers responding to consumer and regulatory pressure for verifiable sustainability claims.
Textile Dyestuff Market Segmentation
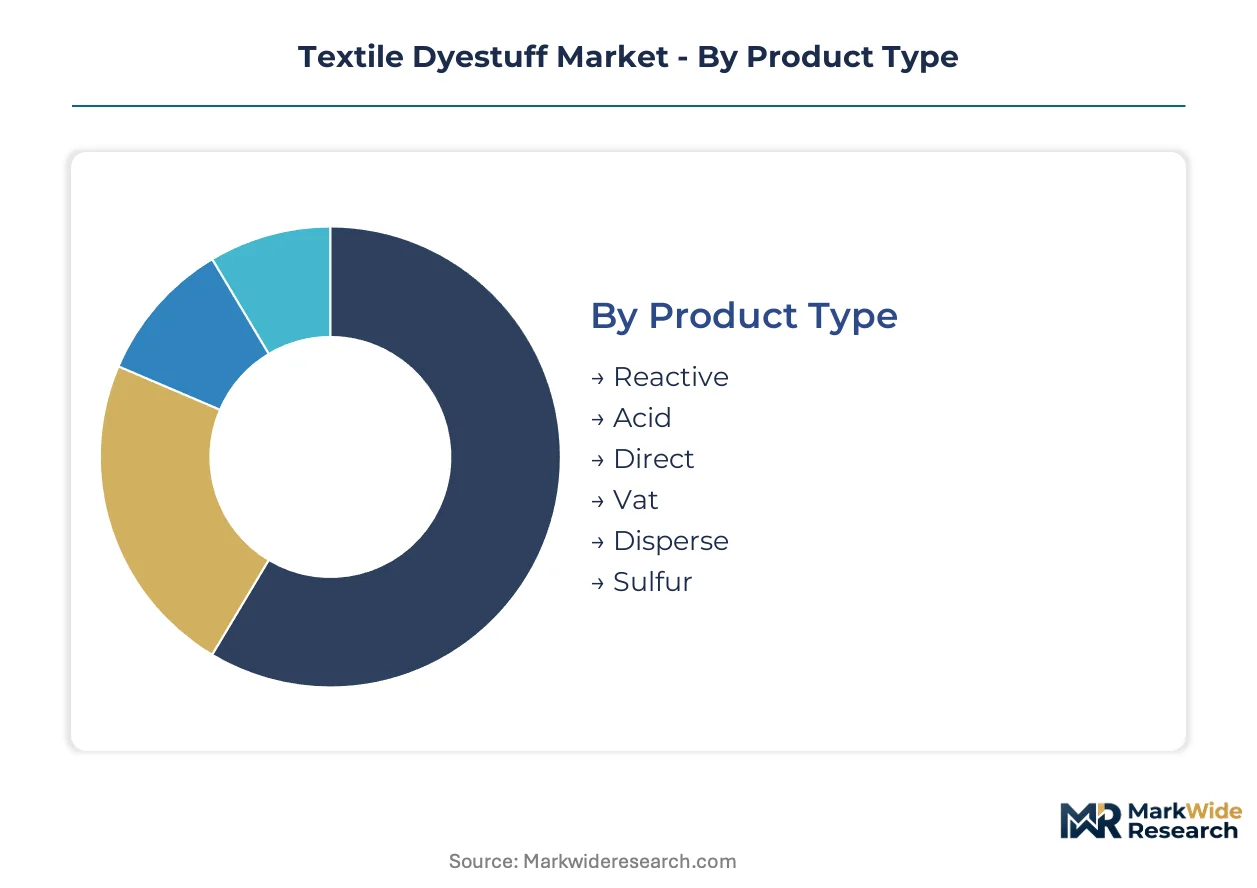
The textile dyestuff market's segmentation reveals how diverse fiber types, application methods, and end-user demands shape product development and competitive strategies. Understanding these distinct segments is crucial for suppliers to align their portfolios with evolving regulatory landscapes and performance requirements across the value chain.
Product Type:
Dyestuffs facing intense substitution pressure from eco-friendly alternatives or regulatory restrictions define the competitive dynamics within this product type category.
- Reactive:These dyes form covalent bonds with cellulosic fibers like cotton, ensuring high wash fastness and bright shades for textiles. Demand concentrates in apparel manufacturing hubs like India and Bangladesh, driven by the need for durable coloration in everyday wear.
- Disperse:Disperse dyes are non-ionic, finely ground pigments applied to hydrophobic synthetic fibers such as polyester and acetate. The technical textiles sector, particularly in automotive interiors and sportswear, drives demand for their excellent light and sublimation fastness.
- Acid:Acid dyes are anionic colorants primarily used for protein fibers like wool, silk, and nylon, requiring an acidic bath for absorption.
- Direct:Direct dyes are applied directly to cellulosic fibers from a neutral or alkaline bath, offering simplicity but generally lower wash fastness.
- Vat:Vat dyes are water-insoluble, requiring reduction to a soluble leuco form before application, known for exceptional fastness properties in heavy-duty textiles.
- Sulfur:Sulfur dyes are complex organic compounds primarily used for cellulosic fibers, providing cost-effective dark shades with good fastness.
Reactive dyes anchor the volume base for cellulosic applications while disperse dyes gain share at the steepest rate due to synthetic fiber growth.
Application:
Cost-tier considerations significantly influence dyestuff selection across various textile applications, balancing performance requirements with budget constraints.
- Technical Textiles:This segment includes high-performance fabrics for automotive, medical, and protective clothing, demanding dyestuffs with extreme durability and functional properties. European markets drive innovation for advanced colorant systems in technical textiles due to stringent safety and performance standards.
- Apparel:The apparel sector encompasses a vast range of clothing items, utilizing dyestuffs for diverse fiber types and fashion trends. Consumer preferences for sustainable and traceable coloration methods influence dyestuff choices for major fashion brands in the United States.
- Woven Fabrics:Woven fabrics, such as denim and shirting, require dyestuffs that ensure even penetration and consistent shade across complex structures.
- Knitted Fabrics:Knitted fabrics, including jersey and fleece, demand dyestuffs offering flexibility and color retention through stretching and washing cycles.
- Nonwoven Fabrics:Nonwoven fabrics, used in hygiene products and geotextiles, require specialized dyestuffs for uniform coloration without compromising material integrity.
- Home Textiles:Home textiles, like bedding and upholstery, prioritize dyestuffs with high lightfastness and resistance to repeated laundering.
The apparel application accounts for the largest volume consumption, while technical textiles exhibit the steepest expansion trajectory.
End User Industry:
Volume requirements and operational scale largely dictate the dyestuff procurement strategies of end-user industries within the textile value chain.
- Textile Mills:Integrated textile mills conduct spinning, weaving, and dyeing operations in-house, requiring bulk quantities of dyestuffs for continuous production. Large-scale textile mills in China and India demand cost-effective and high-volume dyestuff supplies to maintain competitive pricing.
- Dyeing Units:Specialized dyeing units focus solely on the coloration process for fabrics and yarns, often serving multiple textile manufacturers. Wastewater discharge regulations from the US EPA significantly influence process technology choices and dyestuff selection for these units.
- Garment Manufacturers:Garment manufacturers primarily purchase pre-dyed fabrics but may use dyestuffs for garment dyeing or specialized finishes.
- Textile Printing Firms:Textile printing firms utilize specialized dyestuff inks for digital and conventional printing methods, focusing on color vibrancy and print definition.
- Fabric Traders:Fabric traders act as intermediaries, sourcing and distributing dyed fabrics, indirectly influencing dyestuff demand based on market trends.
Textile mills represent the foundational demand segment, while specialized dyeing units are adapting quickly to environmental mandates.
Form:
The physical form of dyestuffs directly impacts their handling, dissolution, and application efficiency across various dyeing processes.
- Liquid:Liquid dyestuffs offer convenience, ease of handling, and precise dosing in automated dyeing systems, minimizing dust and improving workplace safety. European dyeing facilities increasingly prefer liquid forms to optimize process control and reduce environmental impact during handling.
- Powder:Powder dyestuffs are highly concentrated and cost-effective for transportation and storage, requiring dissolution before application. Textile manufacturers in India and Bangladesh widely use powder forms for their economic advantages in high-volume, traditional dyeing operations.
- Granules:Granular dyestuffs reduce dusting compared to powders, offering improved handling and faster dissolution rates in dyeing baths.
- Paste:Paste dyestuffs are semi-liquid forms, often used in printing applications for their specific rheological properties and color intensity.
- Cake:Cake dyestuffs are highly concentrated, semi-solid forms requiring further processing or dissolution before use, typically for specific industrial applications.
Powder forms maintain a significant market presence due to cost-effectiveness, while liquid dyestuffs are gaining traction for process efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stricter environmental regulations and sustainability mandates are significantly influencing the textile dyestuff market across key global regions. These policies drive demand for eco-friendly formulations and advanced dyeing technologies. Manufacturers and textile mills worldwide must adapt to evolving compliance requirements.
China
Demand for high-fixation disperse and reactive dyes is strong due to its vast textile production capacity. China's Ministry of Ecology and Environment (MEE) enforces stringent GB standards for wastewater discharge, accelerating the shift to cleaner chemistries. Textile manufacturing clusters in Zhejiang and Guangdong provinces are investing in advanced effluent treatment systems.
India
The apparel manufacturing sector in India drives significant consumption of reactive dyes for cellulosic fibers. The Bureau of Indian Standards (BIS) regulates chemical safety and quality for dyestuffs used in domestic and export-oriented textiles. Production hubs like Ahmedabad and Tirupur are witnessing increased adoption of water-saving dyeing processes.
Germany
Technical textiles and high-performance apparel sectors in Germany require specialized dyestuffs with superior functional properties. The EU's REACH legislation sets strict limits on hazardous substances, compelling manufacturers to develop safer alternatives. Research and development centers in cities like Frankfurt are at the forefront of bio-based dyestuff innovation.
United States
Consumer preferences for sustainable products influence dyestuff choices for apparel brands and home textiles in the United States. The EPA's regulations on wastewater discharge impose compliance costs on dyeing units, encouraging process technology upgrades. Textile finishing plants in states like North Carolina are exploring waterless dyeing solutions.
Bangladesh
Rapid expansion of the ready-made garment industry in Bangladesh fuels consistent demand for cost-effective reactive dyes. Government initiatives support the textile sector's growth, including incentives for modernizing dyeing facilities. Manufacturing zones around Dhaka and Chittagong are concentrating on high-volume production for export markets.
Textile Dyestuff Market Key Industry Players
Listed leaders compete with private specialists across portfolio breadth and regional market access within the textile dyestuff market. The market exhibits a tiered structure, with a few global chemical giants alongside numerous regional players. Innovators focusing on sustainable chemistries represent one strategic archetype, while commodity producers competing on price form another. Companies primarily engage in capacity expansion and strategic partnerships to secure raw material supply and expand distribution networks, seeking to optimize supply chain efficiencies.
Within the premium segments focused on sustainable solutions, Archroma exemplifies a key innovator, leveraging its specialized portfolio for stringent human-ecological safety requirements. Huntsman International LLC, a prominent global entity, anchors the market through its extensive distribution network and broad product portfolio, particularly for reactive and disperse dyes. Zhejiang Longsheng Group Co., Ltd., as a China-based enterprise, occupies a position among high-volume dyestuff manufacturers, serving large textile production hubs with cost-effective solutions.
| Leading Market Players |
|---|
| Archroma |
| Huntsman International LLC |
| BASF SE |
| LANXESS |
| Kiri Industries Ltd |
| DyStar |
| Zhejiang Longsheng Group Co., Ltd. |
| Clariant |
| Atul Ltd |
| Others |
Cost & Logistics Intelligence
The OEKO-TEX STANDARD 100 certification gates dyestuff supply qualification and simultaneously drives price differentiation for compliant, human-ecological safe products. This framework influences both production costs and market access.
Pricing Analysis
Certification level, such as OEKO-TEX STANDARD 100 or bluesign, creates the primary spread in dyestuff pricing. Premium-mid-economy pricing differentiation exists, driven by quality grade, performance properties for technical textiles, and geographic delivery costs. Pricing softness runs through commodity segments due to oversupply from China. Garment manufacturers typically exhibit the highest price sensitivity, while technical textile producers prioritize performance over cost.
Supply Chain Analysis
Inventory management and lead-time reliability are critical in the dyestuff supply chain, particularly for high-volume textile mills. Supply concentrates in China, India, and Bangladesh, which are major textile manufacturing hubs. The industry draws from petrochemical-based raw materials like benzene and naphthalene derivatives, making it vulnerable to commodity price volatility. Distribution runs through direct sales to large integrated mills and regional distributors for smaller dyeing units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The textile dyestuff market presents a significant service-attach opportunity, with technical support and compliance consulting expanding faster than basic product sales. This offers a pathway for sustained revenue streams.
For Market Incumbents:Fortify existing market positions by investing in advanced R&D for bio-based and waterless dyeing technologies. This counters the threat of stricter environmental regulations and rising feedstock costs. Deepen vertical integration into specialized dyestuff intermediates to secure supply and control quality. Pursue strategic partnerships with technical textile innovators to capture high-performance segments.
For New Entrants and Emerging Players:Anchor in niche segments demanding full chemical traceability and digital product passports. Target emerging textile manufacturing centers in African markets like Ethiopia and Kenya, which are building out industrial apparel capacity. Focus on providing specialized, high-purity dye inks for digital textile printing, offering a clear go-to-market angle against conventional methods. Emphasize sustainable formulations to attract brands committed to circular economy principles.
For Investors and Strategic Acquirers:The EU's REACH legislation and China's GB standards reshape the acquisition landscape, favoring firms with compliant, eco-friendly portfolios. Long-term viability rests on sustainable dyestuff innovation and process efficiency improvements. Target specialized firms holding patents in waterless dyeing technologies or bio-based colorant platforms. The signal to watch is accelerating corporate sustainability commitments from major apparel brands.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Reduces environmental footprint for dyestuff production under China's MEE standards. |
| Long-term Supply Agreement | Secures petrochemical feedstock supply against price volatility for dyestuff manufacturers. |
| Joint Venture | Accelerates development of supercritical CO2 dyeing technologies with specialized partners. |
| Capacity Expansion | Supports growing apparel manufacturing hubs in India and Bangladesh. |
| Product Launch | Introduces new bio-based dyestuffs to capture premium sustainable segments in Europe. |
Research Approach
Operator-level perspectives from plant managers, R&D directors, procurement leads, and sustainability officers anchored the qualitative base. Primary interviews with industry stakeholders were triangulated with extensive secondary validation. Secondary sources included EU REACH documents, China GB standards, US EPA reports, and industry association publications. Both bottom-up and top-down approaches ensured comprehensive data coverage.
Sensitivity analysis was applied to project market trajectories across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end-user industry, form, and regional regulatory trends. Compound Annual Growth Rates were derived from historical trends and future projections. Key forecast inputs included technical textile adoption rates and environmental compliance investment.
Material uncertainties — such as unforeseen regulatory shifts or geopolitical trade disruptions — sit outside the modeled envelope. Forecasts reflect assumptions documented at the time of publication. Raw material supply shocks also pose revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Textile Transfer Paper Market
Textile Chemicals, Dyes, and Finishing
Dyes Market
Textile Chemicals, Dyes, and Finishing
Unbleached Twill Tapes Market
Textile Chemicals, Dyes, and Finishing
Fabric Stain Remover Market
Textile Chemicals, Dyes, and Finishing
Asia Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Waterless Textile Dyeing Services Market
Textile Chemicals, Dyes, and Finishing
Pre-Treater Laundry Products Market
Textile Chemicals, Dyes, and Finishing
Textile Printing Market
Textile Chemicals, Dyes, and Finishing
Textile Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Disperse Dyes Market
Textile Chemicals, Dyes, and Finishing
Global Sulfur Dye Market
Textile Chemicals, Dyes, and Finishing
Textile Auxiliaries Market
Textile Chemicals, Dyes, and Finishing
Embroidery Thread Market
Textile Chemicals, Dyes, and Finishing
PVC Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Europe Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Fabric Odor Eliminator Market