
 Asia-Pacific Beauty Drinks Market | 2026-2036
Asia-Pacific Beauty Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Beauty Drinks Market Outlook
E-commerce distribution across Tmall, Lazada, and brand-direct storefronts is fragmenting as live-streaming commerce and social selling disrupt traditional retail hierarchies. Shiseido Co. Ltd anchors its position through pharmacy and department store networks in Japan while building digital-first sub-brands for Southeast Asia. Kinohimitsu leverages its Malaysian manufacturing base to supply halal-certified collagen drinks across Indonesia and Malaysia. AmorePacific Corp competes through beauty-tech integration, linking skin diagnostic apps to personalized supplement subscriptions.
Beauty drinks comprise ingestible liquid or powdered formulations containing bioactive compounds—collagen peptides, hyaluronic acid, ceramides, and antioxidant extracts—processed through enzymatic hydrolysis and microencapsulation to preserve molecular stability and enhance bioavailability. These products target dermal hydration, elasticity, and oxidative stress reduction from within, operating at the intersection of nutraceutical science and cosmetic dermatology. Collagen dominates product type revenue due to established clinical validation and consumer familiarity, though antioxidant blends gain traction among urban professionals seeking pollution-defense positioning. Ready-to-drink formats lead form category volume through convenience alignment with commuter consumption patterns, while powdered mixes capture fitness enthusiast segments seeking dose customization and transportability.
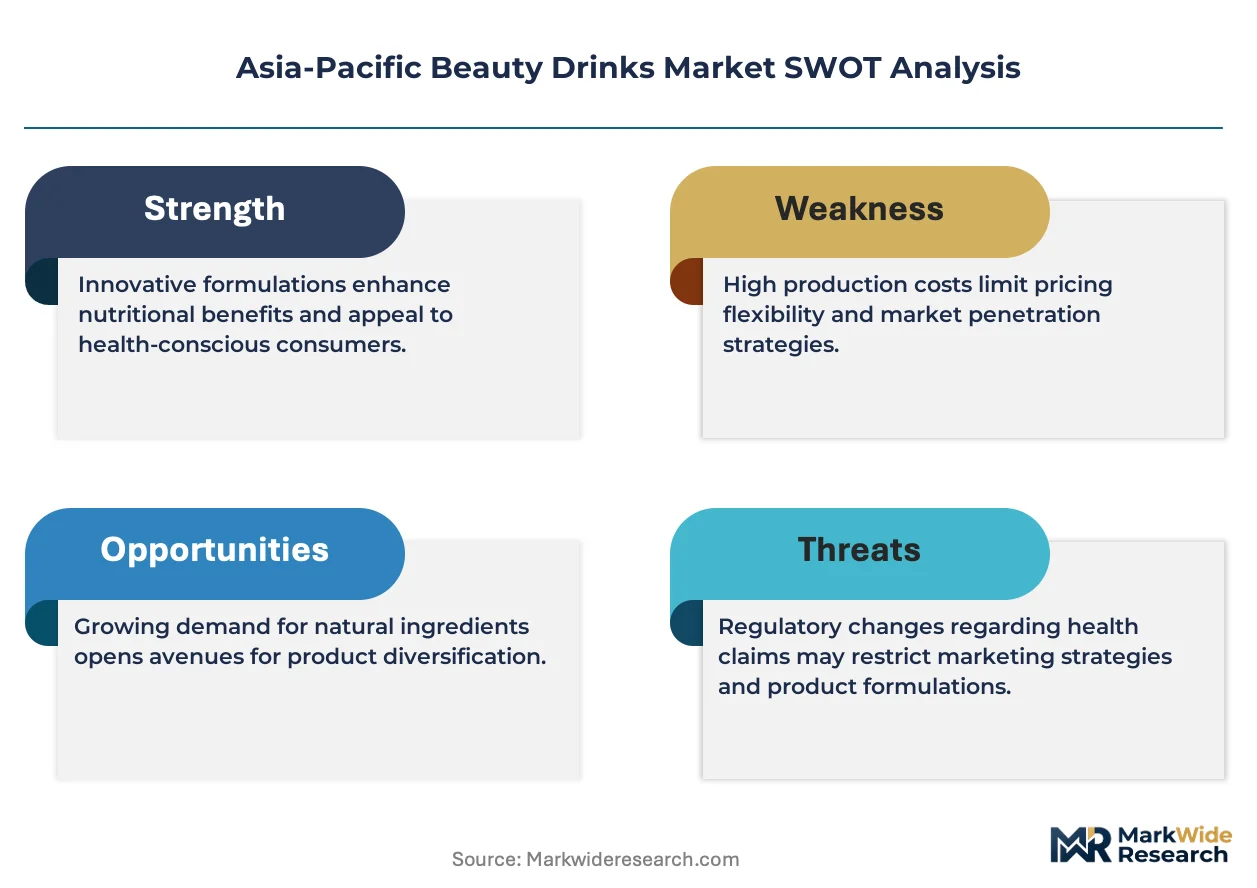
Japan's Consumer Affairs Agency enforces strict functional claim substantiation under Foods with Function Claims regulations, requiring human intervention studies for skin benefit assertions. China's SAMR mandates blue-hat health food registration for products making beauty-related efficacy claims, creating multi-year approval timelines that favor established players with regulatory affairs capacity. Australia's TGA oversees complementary medicine listing requirements that influence export strategies for ASEAN-bound Australian brands. Stakeholders must monitor evolving cross-border e-commerce duty thresholds and emerging ASEAN harmonization frameworks that could reshape import compliance burdens and channel economics across the region.
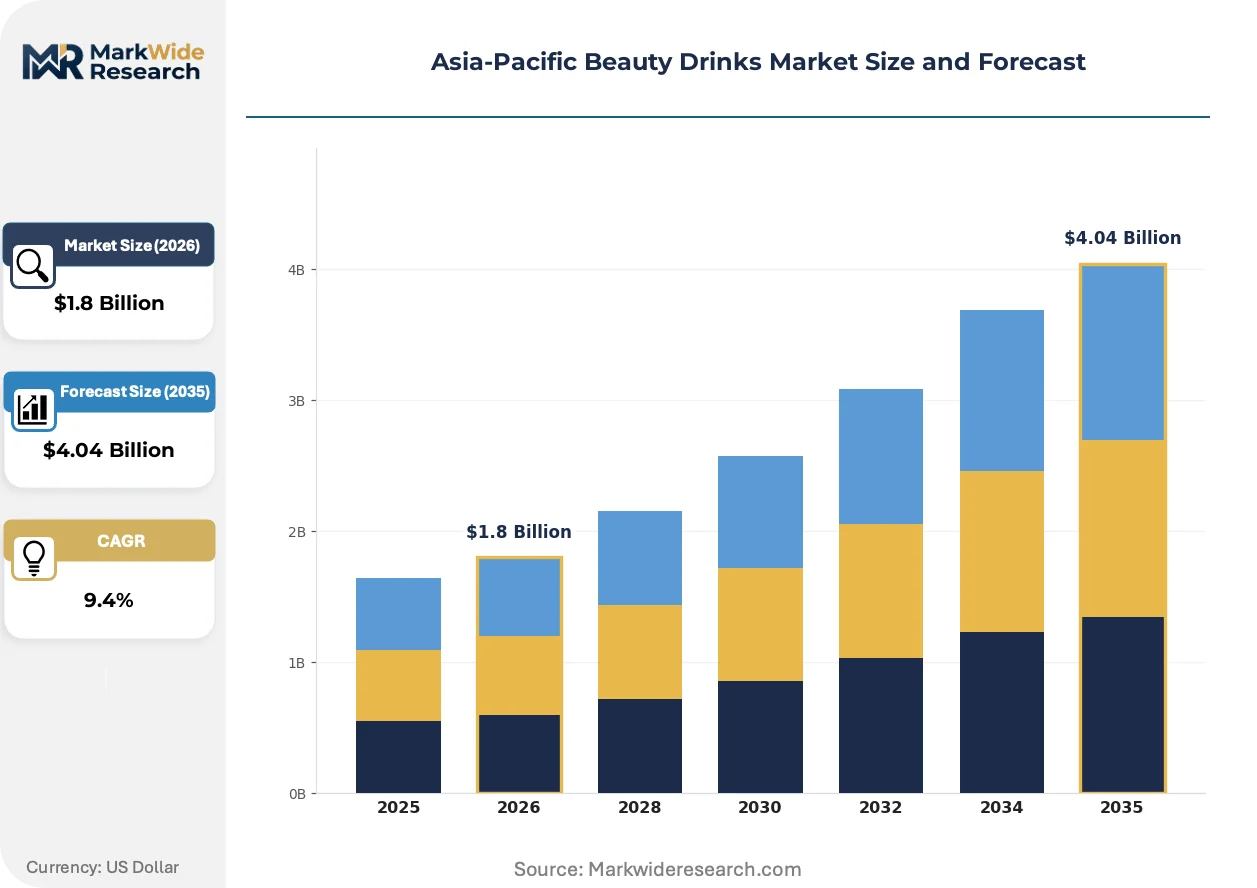
Market Dynamics
Live-streaming commerce in Seoul and Shanghai is fragmenting traditional retail hierarchies, forcing brands to rebuild distribution around influencer-driven conversion rather than shelf-space dominance. This shift compresses margin structures while accelerating product lifecycle velocity across the region.
Growth Catalysts
- Japan's Foods with Function Claims framework:Clear substantiation pathways for skin benefit assertions enable faster product launches versus China's multi-year blue-hat registration, attracting R&D investment to Tokyo and Osaka clusters.
- Halal certification expansion:Kinohimitsu's Malaysian manufacturing base supplies Indonesia's Muslim consumer base, unlocking access to 230 million potential buyers previously excluded from collagen RTD consumption.
- Beauty-tech integration:Skin diagnostic apps linked to personalized supplement subscriptions create recurring revenue models that bypass traditional retail margin stacking entirely.
Market Restraints
- Marine collagen supply concentration:Over 60% of hydrolyzed peptide feedstock originates from Southeast Asian fishery processors, exposing formulators to El Niño-driven raw material volatility and price spikes.
- China SAMR registration timelines:Blue-hat health food approvals for beauty-related efficacy claims extend 18-36 months, freezing new entrant pipelines while incumbents defend shelf position.
- Hyaluronic acid bioavailability ceiling:Gastric degradation limits systemic absorption of orally administered HA below dermatologically effective thresholds, constraining clinical validation and premium pricing power.
Strategic Opportunities
- Vietnam's underpenetrated urban corridor:Ho Chi Minh City and Hanoi present first-mover potential for collagen RTD distribution before domestic manufacturing capacity localizes and margin compression follows.
- ASEAN harmonization frameworks:Emerging mutual recognition agreements for functional food standards could slash multi-country compliance costs, favoring regional supply chain consolidation over fragmented national registrations.
- Powdered mix fitness crossover:Gym and yoga studio channels in Bangkok and Sydney offer direct-to-consumer sampling infrastructure that RTD formats cannot replicate, capturing dose-customization preferences among athletic demographics.
Industry Challenges
- Cross-border e-commerce duty threshold volatility:China's fluctuating de minimis rules for direct-to-consumer imports force continuous logistics reconfiguration and inventory repositioning across bonded warehouses.
- Clinical substantiation talent scarcity:Human intervention study design expertise for skin biomarker validation concentrates in Tokyo and Singapore, creating recruitment bottlenecks for brands seeking FFC compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Beauty Drinks Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collagen, Antioxidants, Vitamins, Mineral Blends Distribution Channel: Specialty Stores, Online Retail, Supermarkets, Health Shops End User: Women, Men, Fitness Enthusiasts, Health Conscious Individuals Form: Ready-to-Drink, Powdered Mix, Bottled Form, Gels |
| Companies Covered | FUJIFILM Holdings Corporation, Kinohimitsu, Shiseido Co. Ltd, Lacka Foods Limited, AmorePacific Corp, Sappe Public Company Limited, Kino Biotech, Vital Proteins LLC, Hangzhou Nutrition Biotechnology Co. Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Beauty Drinks Market Strategic Shifts
Enzymatic hydrolysis and microencapsulation advances are compressing the gap between nutraceutical bioavailability and cosmetic efficacy claims, reshaping how formulators demonstrate measurable skin outcomes to skeptical urban consumers.
Liposomal encapsulation technology protects collagen peptides from gastric degradation and delivers intact molecules to intestinal absorption sites. Premium brands in Shanghai and Seoul are adopting this at scale for 2024 product refreshes. Conventional unprotected peptide powders are rendering obsolete among consumers with dermatologist relationships and outcome expectations.
Japan's Consumer Affairs Agency tightened FFC substantiation requirements for "skin moisture retention" claims in 2023, mandating transepidermal water loss measurements across minimum 12-week intervention periods. This regulatory elevation is filtering out undercapitalized competitors unable to fund compliant clinical trials. Mid-tier brands without pharmacy network access are retreating to generic "beauty support" positioning without structural claims.
Urban professionals in China's tier-one cities are abandoning traditional Tmall flagship stores for Douyin live-streaming sessions where dermatologists demonstrate real-time skin hydration measurements. This channel migration is disintermediating brand-controlled messaging and transferring purchase authority to KOL-converted audiences. Seoul-based brands with embedded influencer networks are capturing disproportionate share of this behavioral shift.
Asia-Pacific Beauty Drinks Market Segmentation
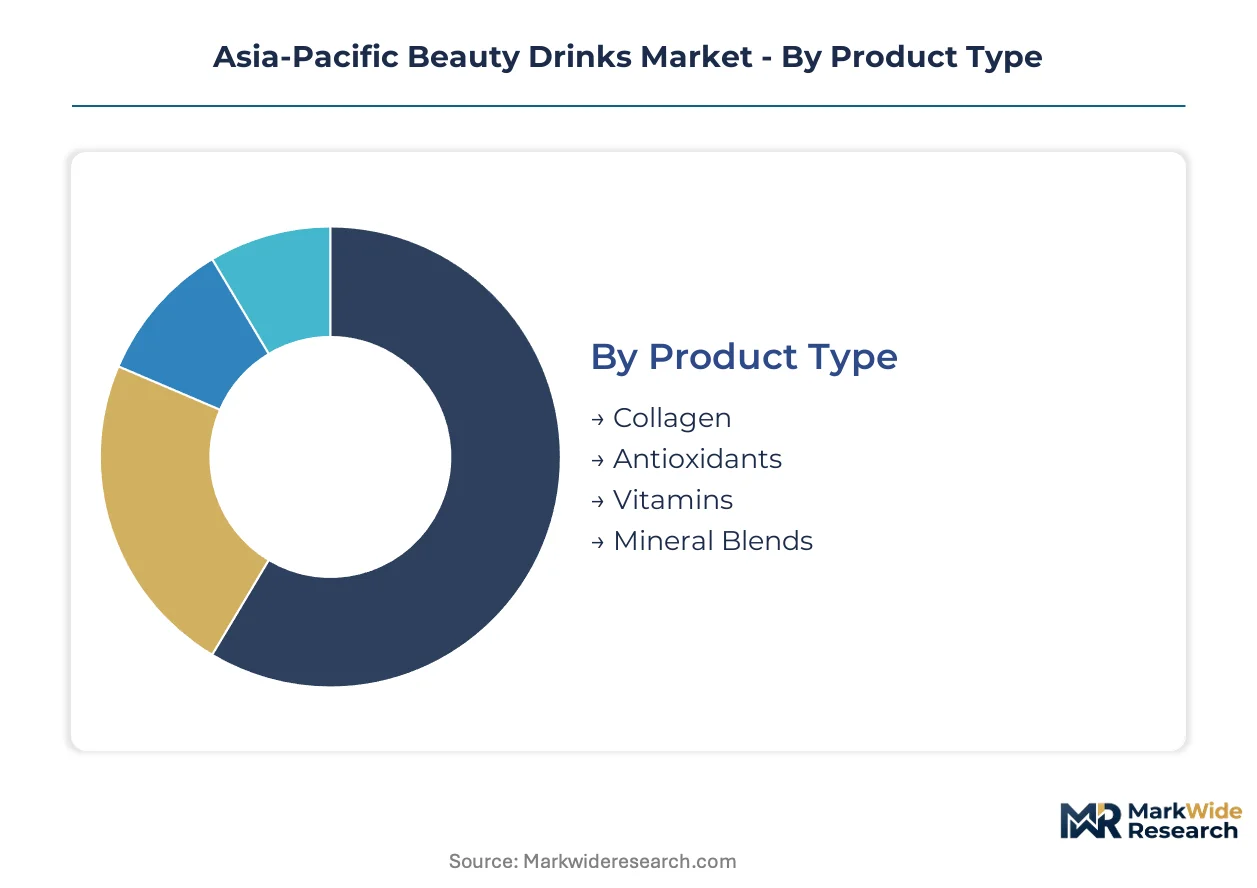
Beauty drinks span distinct consumption occasions from commuter convenience to fitness customization, requiring brands to align formulation science with channel-specific purchase behavior. Segmentation reveals where bioavailability investments translate to margin capture versus commodity competition.
Product Type:
Beauty drinks serve preventive maintenance, active correction, and performance optimization use cases across urban professional cohorts.
- Collagen:Hydrolyzed peptide formulations processed through enzymatic hydrolysis deliver 2,000-5,000 Dalton molecular weights for intestinal absorption. Demand concentrates in Shanghai and Seoul where pharmacy networks and dermatologist endorsements sustain premium positioning against unverified alternatives.
- Antioxidants:Polyphenol-rich extracts from green tea, grape seed, and pomegranate target pollution-defense positioning among outdoor workers in Bangkok and Jakarta. Pollution-index marketing correlates with seasonal haze events to drive replenishment cycles.
- Vitamins:B-complex and C formulations support metabolic skin health with lower technical barriers to entry.
- Mineral Blends:Zinc-selenium combinations target acne-prone demographics through sebum regulation claims.
Established volume favors collagen; emerging adoption favors antioxidants.
Distribution Channel:
Channel selection determines margin structure and claim substantiation requirements across the region.
- Specialty Stores:Department store beauty halls and pharmacy chains in Tokyo and Osaka provide clinical credibility through trained consultant staff. Japan's FFC framework compliance becomes a visible differentiator on shelf.
- Online Retail:Tmall, Lazada, and Douyin live-streaming fragment traditional hierarchies with KOL-converted purchase authority. Cross-border duty thresholds force continuous logistics reconfiguration for direct-to-consumer imports.
- Supermarkets:Mass-market penetration in China's tier-one cities through Hema and 7Fresh stores trades margin for volume scale.
- Health Shops:Gym-adjacent and yoga studio channels in Sydney and Bangkok capture fitness crossover demand with sampling infrastructure.
Specialty stores anchor premium positioning; online retail captures the steepest expansion trajectory.
End User:
User archetypes align bioactive priorities with lifestyle integration patterns.
- Women:Core demographic driving collagen RTD volume through skin elasticity and anti-aging positioning. Urban millennials in Seoul and Shanghai prioritize convenience and visible clinical validation.
- Men:Emerging segment targeted through hair and stress-resistance formulations in metropolitan Japan and South Korea. Gender-neutral packaging expands addressable base beyond traditional cosmetic framing.
- Fitness Enthusiasts:Athletic demographics in Bangkok and Sydney favor powdered mixes for dose customization and transportability.
- Health Conscious Individuals:Prevention-focused buyers respond to holistic wellness positioning linking skin health to systemic inflammation markers.
Women sustain revenue concentration; men represent the fastest-climbing adoption curve.
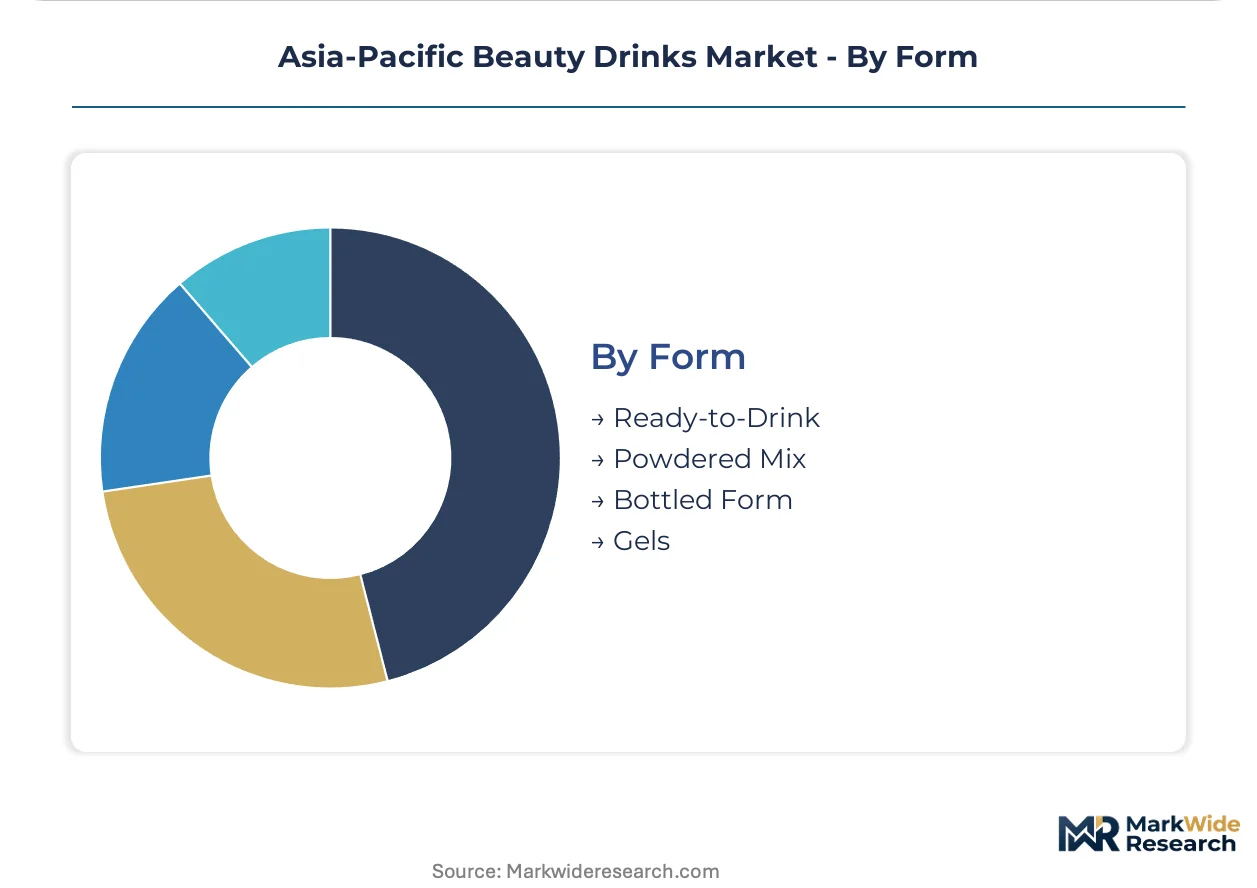
Form:
Format engineering balances bioavailability protection against consumption context constraints.
- Ready-to-Drink:Liposomal encapsulation and aseptic processing preserve peptide integrity for commuter consumption in Shanghai and Tokyo. Shelf-stable formats dominate pharmacy and convenience store distribution.
- Powdered Mix:Sachet and tub formats enable dose titration and flavor customization for home and gym use. Lower shipping costs support cross-border e-commerce economics.
- Bottled Form:Glass and premium PET packaging signal luxury positioning in department store channels.
- Gels:Concentrated delivery systems for travel and on-the-go segments with portability advantages.
Ready-to-Drink commands volume leadership; Powdered Mix gains share fastest among athletic demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's Consumer Affairs Agency anchors regulatory architecture across the Asia-Pacific beauty drinks sector through its Foods with Function Claims framework, establishing clinical substantiation benchmarks that neighboring jurisdictions reference. National market trajectories diverge based on registration pathway efficiency, halal certification penetration, and e-commerce infrastructure maturity.
Japan
Pharmacy network density in Tokyo and Osaka sustains premium collagen RTD distribution, with trained beauty consultants converting clinical validation into purchase decisions. The Consumer Affairs Agency mandates 12-week transepidermal water loss studies for moisture retention claims, elevating compliance costs that favor capitalized incumbents. Kanto and Kansai clusters concentrate formulation R&D investment as brands seek faster FFC approval timelines versus China's SAMR process.
China
Urban millennials in Shanghai and Beijing drive live-streaming commerce adoption through Douyin dermatologist demonstrations featuring real-time skin hydration measurements. SAMR blue-hat health food registration extends 18-36 months for beauty efficacy claims, freezing new entrant pipelines while established players defend Hema and 7Fresh shelf positions. Yangtze River Delta manufacturing bases supply liposomal encapsulation capacity for 2024 product refreshes targeting pharmacy credibility.
South Korea
Seoul's influencer-embedded brand networks capture disproportionate share of cross-border e-commerce traffic into China through embedded KOL conversion infrastructure. MFDS functional food standards provide intermediate regulatory clarity between Japanese rigor and Chinese procedural delays. Seoul Capital Area beauty-tech integration links skin diagnostic applications to personalized supplement subscriptions, creating recurring revenue models bypassing traditional retail margins.
Indonesia
Kinohimitsu's Malaysian halal-certified manufacturing base unlocks access to 230 million Muslim consumers previously excluded from collagen RTD consumption. BPOM registration requirements for functional claims create compliance bottlenecks that favor regional supply chain consolidation over fragmented national registrations. Jakarta and Surabaya urban corridors present expansion targets for halal-certified antioxidant blends positioned against seasonal haze pollution indices.
Australia
TGA complementary medicine listing requirements influence export strategies for ASEAN-bound brands seeking regulatory credibility transfer. Sydney and Melbourne gym-adjacent health shops provide powdered mix sampling infrastructure capturing fitness enthusiast dose-customization preferences. Powdered format manufacturing concentrates in Victoria for cross-border e-commerce duty optimization into Southeast Asian markets.
Asia-Pacific Beauty Drinks Market Competitive Environment
Integrated beauty conglomerates and specialized nutraceutical manufacturers split the Asia-Pacific beauty drinks market between pharmacy-network credibility and digital-native agility. Market structure tilts toward consolidation in Japan through department store and pharmacy channel control, while Southeast Asian penetration rewards halal-certified regional manufacturing scale. Two dominant competitive moves are reshaping positioning: beauty-tech integration linking diagnostic applications to subscription revenue, and backward integration into marine collagen feedstock to secure supply against El Niño-driven volatility.
Within the integrated conglomerate tier, Shiseido Co. Ltd and AmorePacific Corp exemplify pharmacy-network anchoring combined with digital sub-brand development for Southeast Asian expansion. Kinohimitsu occupies a distinct position as a halal-certified regional manufacturer supplying Indonesia and Malaysia from its Malaysian production base. FUJIFILM Holdings Corporation represents the diversified technology conglomerate archetype leveraging imaging-derived skin analysis capabilities into ingestible beauty positioning.
| Leading Market Players |
|---|
| FUJIFILM Holdings Corporation |
| Kinohimitsu |
| Shiseido Co. Ltd |
| Lacka Foods Limited |
| AmorePacific Corp |
| Sappe Public Company Limited |
| Kino Biotech |
| Vital Proteins LLC |
| Hangzhou Nutrition Biotechnology Co. Ltd |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Southeast Asian marine collagen processing is compressing peptide feedstock costs while simultaneously eroding supplier pricing power across enzymatic hydrolysis tiers, forcing formulators to absorb margin pressure or accelerate liposomal encapsulation upgrades to defend premium positioning.
Pricing Analysis
Shanghai pharmacy shelves command 40-60% premiums over Jakarta supermarket equivalents for identical collagen RTD formulations. Three-tier pricing structure across premium, standard, and economy levels separates liposomal-encapsulated pharmacy products from conventional convenience-store formats and unbranded e-commerce imports. Cost compression in economy tiers is intensifying because cross-border duty threshold volatility forces inventory repositioning into bonded warehouses. Mass-market buyers in Indonesia and Vietnam exhibit highest price sensitivity, while Japanese department store consumers demonstrate inelastic demand for FFC-substantiated moisture retention claims.
Supply Chain Analysis
Contract manufacturing concentration sits with Kinohimitsu's Malaysian halal-certified facility and Yangtze River Delta liposomal encapsulation specialists serving Shiseido and AmorePacific sub-brands. Geographic supply concentration centers on Malaysia, Indonesia, and coastal China for hydrolyzed peptide processing. Raw material dependencies draw from Southeast Asian fishery processors for marine collagen, Japanese enzymatic catalyst suppliers, and Korean microencapsulation equipment providers. Single-source vulnerability in marine collagen feedstock exposes formulators to El Niño-driven supply disruptions. Distribution runs through pharmacy networks in Tokyo and Osaka, live-streaming commerce platforms in Seoul and Shanghai, and halal-certified channels across Jakarta and Surabaya.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Beauty drinks function as a service-attach opportunity where personalized supplement subscriptions and skin diagnostic app integrations expand recurring revenue faster than transactional RTD unit sales, rewarding brands that convert one-time buyers into platform-locked members.
For Market Incumbents: Insulate pharmacy network positions in Tokyo and Osaka by accelerating FFC-compliant clinical trial investments that mid-tier competitors cannot fund, while securing backward integration into marine collagen feedstock to neutralize El Niño-driven raw material volatility threatening margin stability. For New Entrants and Emerging Players: Pursue Vietnam's underpenetrated urban corridor before domestic manufacturing capacity localizes and triggers margin compression, leveraging powdered mix formats for gym-adjacent sampling infrastructure in Ho Chi Minh City and Hanoi that established RTD players cannot replicate. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among beauty-tech integrated platforms linking diagnostic applications to personalized subscriptions, indicating superior long-term viability over transactional commodity brands; acquisition targets should demonstrate halal certification capacity for Indonesia expansion and liposomal encapsulation technology differentiation; quarterly review of SAMR blue-hat approval timelines and ASEAN harmonization framework progress is advised to detect regulatory inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Expansion | Kinohimitsu's Malaysian base unlocks Indonesia's 230 million Muslim consumer base previously excluded from collagen RTD consumption. |
| Beauty-Tech Platform Integration | Seoul-based skin diagnostic apps linked to supplement subscriptions create recurring revenue models bypassing traditional retail margin stacking. |
| Liposomal Encapsulation Scale-Up | Yangtze River Delta manufacturing investments preserve peptide integrity against gastric degradation for pharmacy credibility in Shanghai. |
| Direct-to-Consumer Live-Streaming Launch | Douyin dermatologist demonstrations with real-time hydration measurements transfer purchase authority from brand-controlled messaging to KOL-converted audiences. |
| Backward Integration into Marine Collagen | Captive supply of hydrolyzed peptide feedstock neutralizes El Niño-driven price spikes from Southeast Asian fishery processor concentration. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with brand managers at integrated beauty conglomerates, regulatory affairs specialists navigating FFC and SAMR frameworks, pharmacy chain category buyers, and halal certification officers; alongside secondary validation through Japan Consumer Affairs Agency FFC filings, China SAMR blue-hat registration databases, BPOM Indonesia functional food approvals, and ASEAN customs trade records. Bottom-up volume triangulation across product type, distribution channel, and end-user segments was cross-checked against top-down market sizing from regional manufacturing capacity and channel throughput estimates.
Forecast inputs considered enzymatic hydrolysis technology adoption curves, live-streaming commerce penetration rates in Seoul and Shanghai, and halal certification expansion timelines across Indonesia and Malaysia. Segmentation dimensions modeled include product type hierarchy, form factor preferences, distribution channel economics, and geographic regulatory cluster differentiation. CAGRs were derived from fitted growth curves calibrated to historical approval timeline data and channel shift velocity indicators.
Sensitivities concentrate around SAMR registration timeline extensions, El Niño recurrence patterns affecting marine collagen supply, and ASEAN harmonization framework implementation delays. Forecasts reflect assumptions on regulatory pathway efficiency and consumer channel migration stickiness. Quarterly review of FFC substantiation requirement updates, cross-border e-commerce duty threshold adjustments, and beauty-tech platform subscriber retention metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Yeast Beta Glucan Market
Functional Food and Beverage
Fisetin Market
Functional Food and Beverage
Beauty Drinks Market
Functional Food and Beverage
Galacto Oligosaccharides (GOS) Market
Functional Food and Beverage
Botanical Infusions Market
Functional Food and Beverage
Keto Diet Market
Functional Food and Beverage
North America Probiotic Drinks Market
Functional Food and Beverage
Global Functional Proteins Market
Functional Food and Beverage
Keto Ice Cream Market
Functional Food and Beverage
Spain Probiotic Drinks Market
Functional Food and Beverage
Antioxidant Beverages Market
Functional Food and Beverage
Saudi Arabia Protein Bar Market
Functional Food and Beverage
Functional Coffee Market
Functional Food and Beverage
Low Fat Product Market
Functional Food and Beverage
Asia-Pacific Functional Beverages Market
Functional Food and Beverage
Prebiotic Fiber Market