
 Hybrid Propellants Market | 2026-2036
Hybrid Propellants Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Propellants Market Foresight
Domestic rocket motor production in the United States is shifting toward reusable architectures that accommodate hybrid propellant chemistries. Northrop Grumman leverages its Minotaur and OmegA heritage to sustain government contract pipelines for strategic defense applications. Sierra Space Corporation anchors commercial crew and cargo missions with Dream Chaser propulsion systems designed around hybrid motor safety profiles. Firehawk Aerospace Inc. differentiates through patented 3D-printed fuel grain technology that reduces manufacturing variability in small-lift vehicles.
Hybrid propellants combine a solid fuel grain—typically hydroxyl-terminated polybutadiene or paraffin-based formulations—with a liquid or gaseous oxidizer such as nitrous oxide or liquid oxygen, enabling throttle control and motor shutdown unavailable in pure solid systems while avoiding cryogenic storage burdens of all-liquid engines. Composite propellant formulations occupy the highest-margin tier within the Propellant Type dimension due to customized binder-oxidizer ratios demanded by defense interceptors and upper-stage applications. The Space Exploration application segment leads absolute volume as lunar lander and orbital transfer vehicle programs specify hybrid systems for their mission-abort capabilities and reduced range-safety footprints.
FAA launch licensing requirements and NASA safety standards govern U.S. propellant handling and flight qualification, while EU REACH restrictions on ammonium perchlorate precursors shape European supply chain configurations. China's GB standards and MIIT spacecraft regulations constrain technology transfer and localize propellant sourcing for domestic launch providers. Stakeholders must monitor evolving EPA emissions thresholds for stratospheric chlorine release and assess oxidizer selection against emerging state-level clean-propulsion procurement mandates.
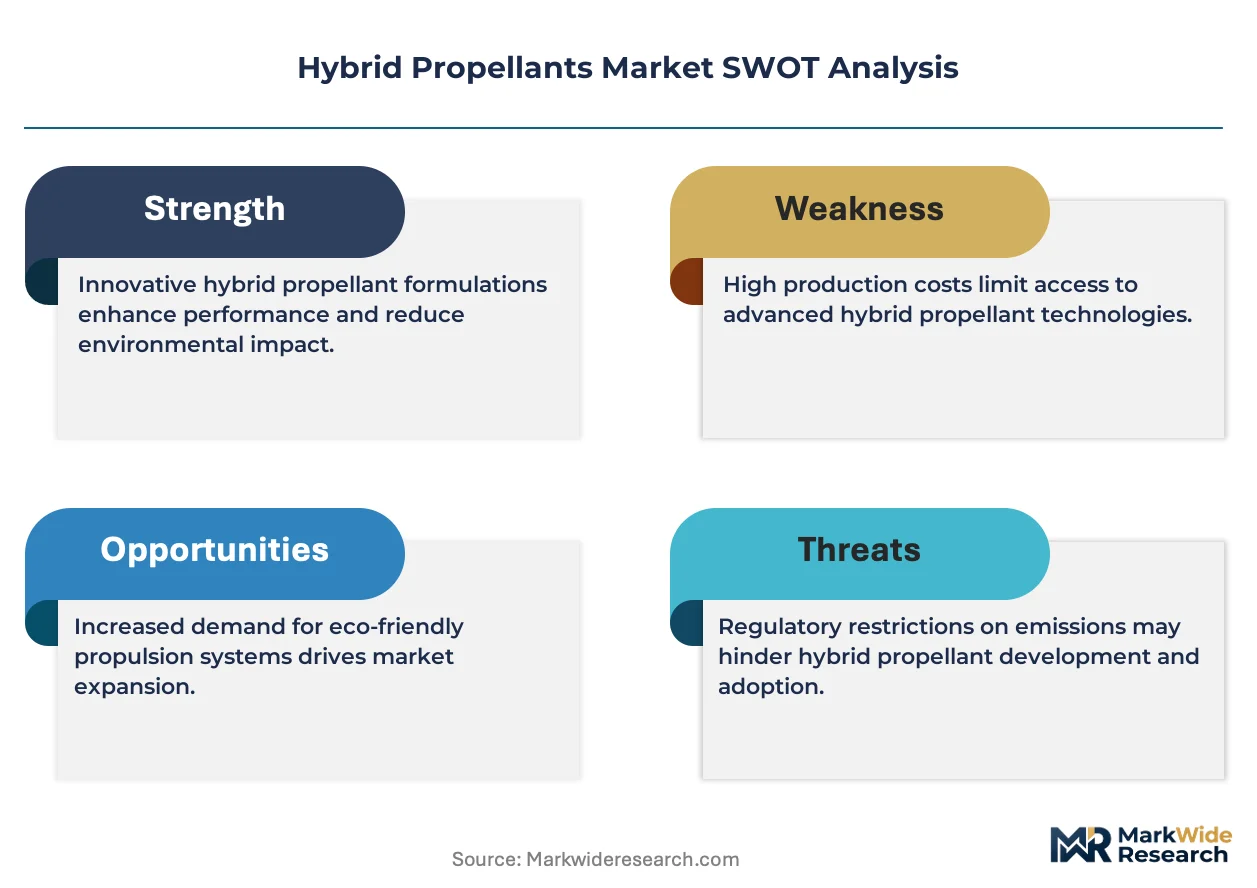
Market Dynamics
Launch cadence compression from commercial constellation operators is forcing hybrid propulsion architectures into the mainstream, as throttleable motors reduce range-safety footprints and enable mission-abort capabilities that pure solid systems cannot deliver.
Growth Catalysts
- EPA Stratospheric Emissions Standards:Updated thresholds for chlorine release are accelerating oxidizer substitution toward nitrous oxide and liquid oxygen formulations in U.S. launch vehicle development.
- Paraffin-Based Fuel Grains:Regression-rate improvements over hydroxyl-terminated polybutadiene are expanding hybrid applicability to upper-stage and lunar lander propulsion.
- Space Coast Infrastructure Concentration:Florida's testing and integration facilities anchor domestic hybrid motor qualification pipelines for defense and commercial programs.
Market Restraints
- Ammonium Perchlorate Supply Concentration:REACH restrictions on precursor chemicals in Europe have consolidated oxidizer feedstock sourcing to a handful of North American and Asian suppliers.
- Fuel Grain Manufacturing Variability:Traditional casting processes introduce combustion instability risks that increase qualification timelines and motor rejection rates.
- Cryogenic Oxidizer Integration Costs:Liquid oxygen handling infrastructure requirements offset hybrid simplicity advantages for small-lift vehicle operators.
Strategic Opportunities
- India's PLI Scheme for Space Manufacturing:Production-linked incentives for domestic launch vehicle components are opening hybrid propulsion localization pathways for international technology partners.
- Orbital Transfer Vehicle Demand:Satellite servicing and debris removal missions require restartable hybrid stages that bridge the gap between solid boosters and electric propulsion.
- 3D-Printed Fuel Grain Convergence:Additive manufacturing integration with automated oxidizer injection systems is collapsing development cycles for custom motor configurations.
Industry Challenges
- Propellant Chemist Talent Scarcity:Specialized expertise in solid-liquid interface combustion modeling remains concentrated in legacy defense contractor and national laboratory pipelines.
- FAA Launch Licensing Timelines:Novel hybrid configurations face extended safety review periods as regulators develop precedent for throttleable solid-liquid systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Propellants Market |
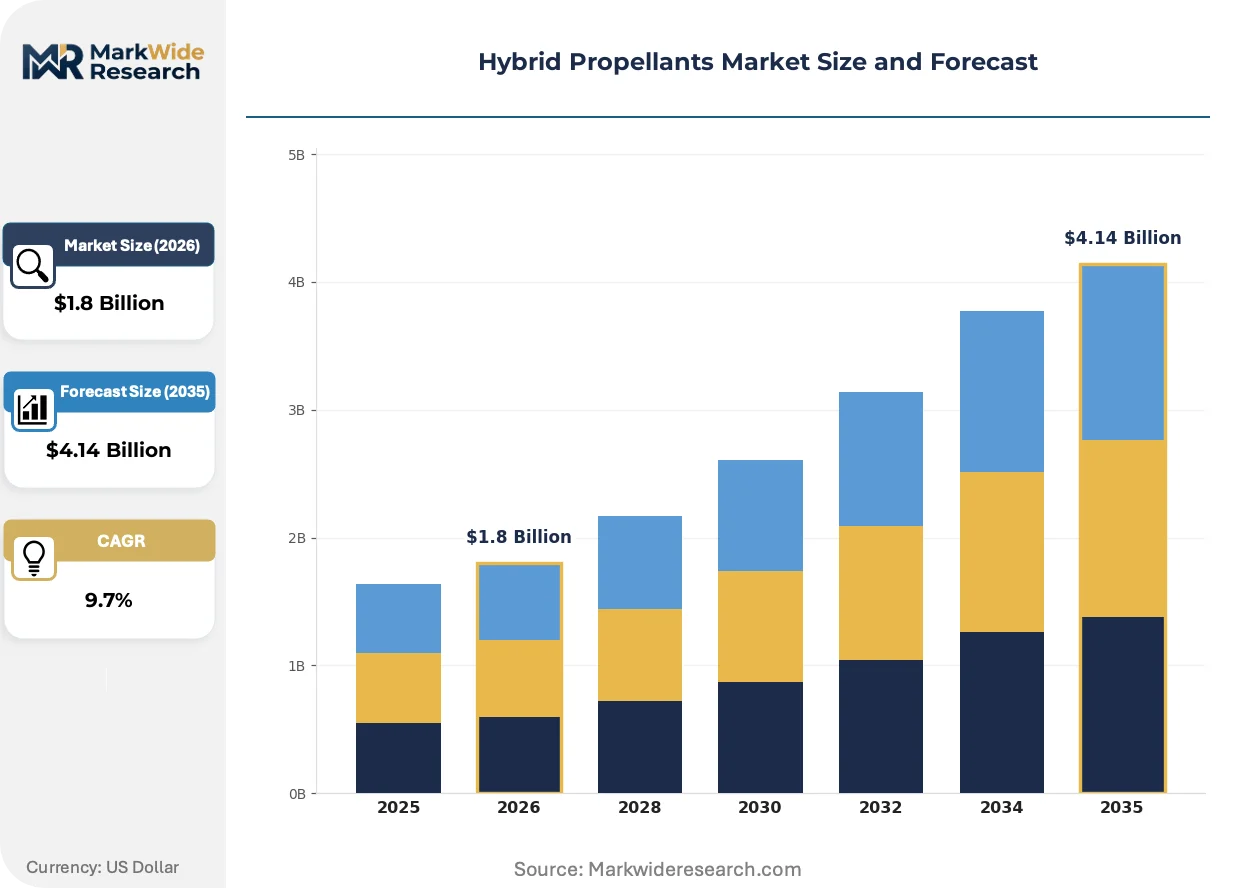
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Propellant Type: Solid, Liquid, Gel, Composite Application: Aerospace, Defense, Space Exploration, Research End User: Government, Private Sector, Research Institutions, Contractors Delivery Mode: System Integration, Ground Launch, Airborne Launch, Others |
| Companies Covered | Virgin Galactic, HyImpulse, HyPrSpace, Raytheon Technologies Corporation, China Aerospace Science and Technology Corporation, Northrop Grumman, Firehawk Aerospace Inc., Pulsar Fusion, Sierra Space Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Propellants Market Shifts & Advancements
Material science breakthroughs and regulatory emissions tightening are converging to reposition hybrid propulsion from niche safety demonstrations to primary launch architecture. The competitive frontier now centers on manufacturing repeatability and oxidizer selection flexibility.
3D-printed fuel grain fabrication is rewriting combustion predictability in hybrid motor design. Additive processes deposit paraffin or thermoplastic formulations with controlled porosity gradients that standard casting cannot replicate. Small-lift vehicle developers are adopting these grains to compress motor qualification from years to months, collapsing the traditional barrier between prototype and production units.
EU REACH restrictions on ammonium perchlorate precursors are redirecting European oxidizer supply chains toward nitrous oxide and hydrogen peroxide alternatives. Formulation houses in Germany and France are reformulating binder-oxidizer ratios to accommodate these substitutes without sacrificing specific impulse. Upper-stage applications face the steepest reformulation burden, as performance margins narrow with cleaner oxidizer selections.
Constellation operators are consolidating procurement around flight-proven hybrid stages with standardized interface specifications. Vertical integration between satellite manufacturers and propulsion providers is displacing arm's-length motor sourcing for rideshare missions. This concentration is most visible in the United States, where Space Coast co-location enables integrated vehicle-stage development timelines that distributed supply chains cannot match.
Hybrid Propellants Market Segmentation
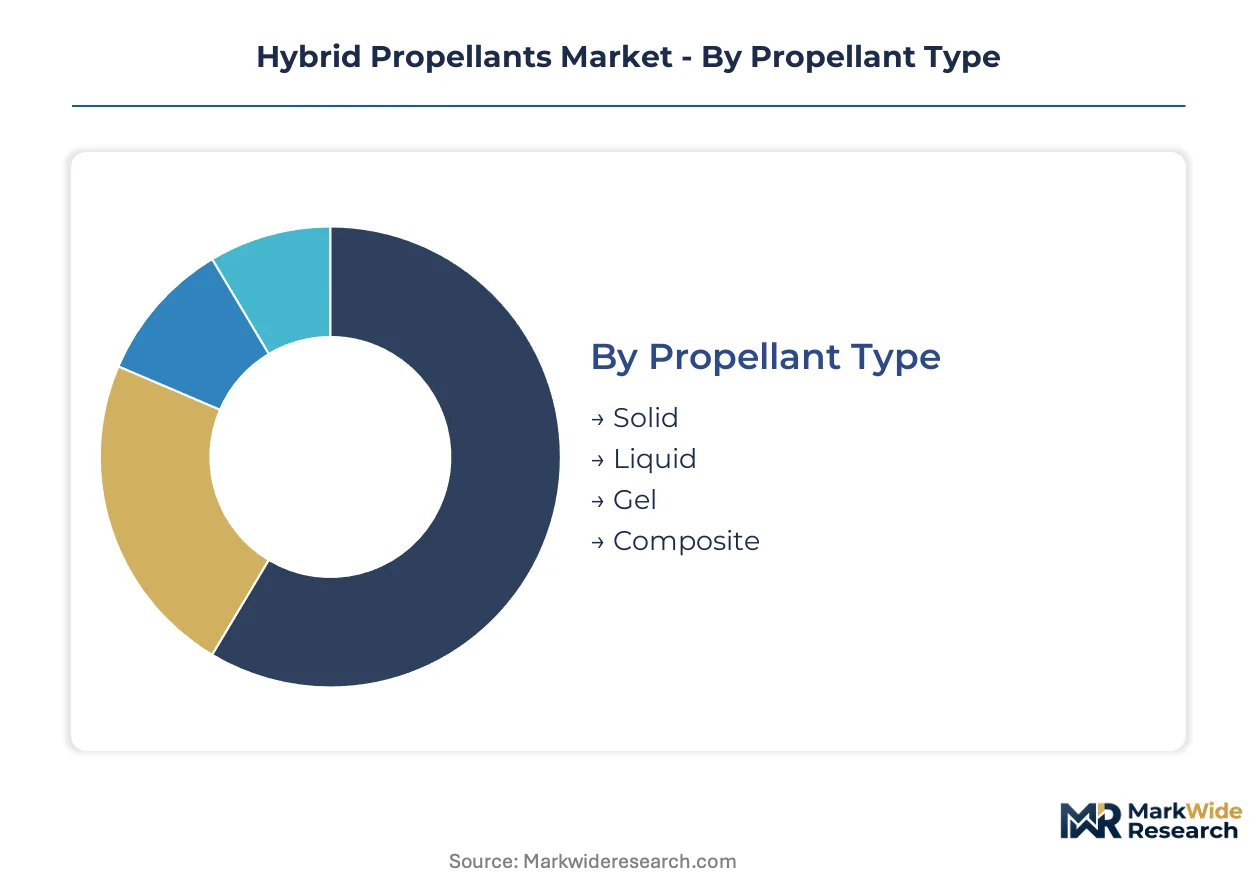
Hybrid propellant architectures fragment across formulation chemistry, mission profile, and procurement channel. Each segmentation axis carries distinct capital requirements and qualification timelines that shape vendor positioning and contract capture strategies.
Propellant Type:
Capital intensity peaks with composite formulations demanding precision binder-oxidizer integration and extensive ground-test campaigns before flight qualification.
- Composite:Customized binder-oxidizer ratios enable mission-specific energy density tuning. Defense interceptors and upper-stage applications in the United States concentrate procurement here, driven by NASA safety standards for crewed mission abort capabilities. Composite propellants absorb the bulk of installed capacity; paraffin-based variants within this tier are expanding most quickly.
- Solid:Hydroxyl-terminated polybutadiene fuel grains anchor legacy strategic defense systems. Manufacturing infrastructure at Space Coast facilities in Florida sustains government contract pipelines through established casting and curing processes.
- Liquid:Nitrous oxide and liquid oxygen oxidizers reduce stratospheric chlorine release under EPA emissions thresholds. Cryogenic handling infrastructure requirements elevate upfront investment for small-lift vehicle operators.
- Gel:Thixotropic formulations combining solid fuel suspensions with liquid oxidizers occupy niche tactical applications. Limited flight heritage constrains adoption outside experimental defense programs.
Composite formulations command premium pricing through performance customization; gel systems remain commercially underdeveloped.
Application:
Mission criticality varies sharply across end-use, with crew-rated systems imposing the steepest qualification burdens and longest development cycles.
- Space Exploration:Lunar lander and orbital transfer vehicle programs specify hybrid systems for restart capability and reduced range-safety footprints. NASA's Artemis infrastructure requirements in the United States anchor demand concentration here. Space Exploration carries the heaviest regulatory load; satellite servicing missions within this segment are climbing the fastest.
- Defense:Strategic interceptors and tactical boosters leverage throttle control for mission flexibility. U.S. defense procurement cycles through Space Coast integration facilities sustain long-term supply agreements.
- Aerospace:Suborbital tourism vehicles and high-altitude research platforms adopt hybrid motors for operational simplicity. FAA launch licensing timelines extend development cycles for novel configurations.
- Research:University and national laboratory programs drive formulation innovation with lower flight-rate requirements. Limited procurement scale constrains vendor participation.
Defense applications dominate contract value; Space Exploration is gaining share fastest through constellation deployment timelines.
End User:
Procurement authority and budget cycle predictability fragment demand across institutional categories with divergent risk tolerances.
- Government:NASA and Department of Defense programs specify hybrid stages through multi-year appropriations. U.S. federal procurement regulations govern contract structures and milestone payments. Government buyers command the deepest qualification resources; private sector counterparts are scaling fastest.
- Private Sector:Commercial constellation operators compress development timelines through vertical integration with propulsion providers. Space Coast co-location enables integrated vehicle-stage development.
- Contractors:Tier-1 defense primes and emerging launch vehicle developers bridge government specifications with commercial manufacturing. Fixed-price contract exposure concentrates financial risk.
- Research Institutions:University laboratories and federally funded research centers advance combustion modeling and materials science. Limited production scale restricts supply chain leverage.
Government programs anchor baseline demand; private sector procurement is expanding most aggressively.
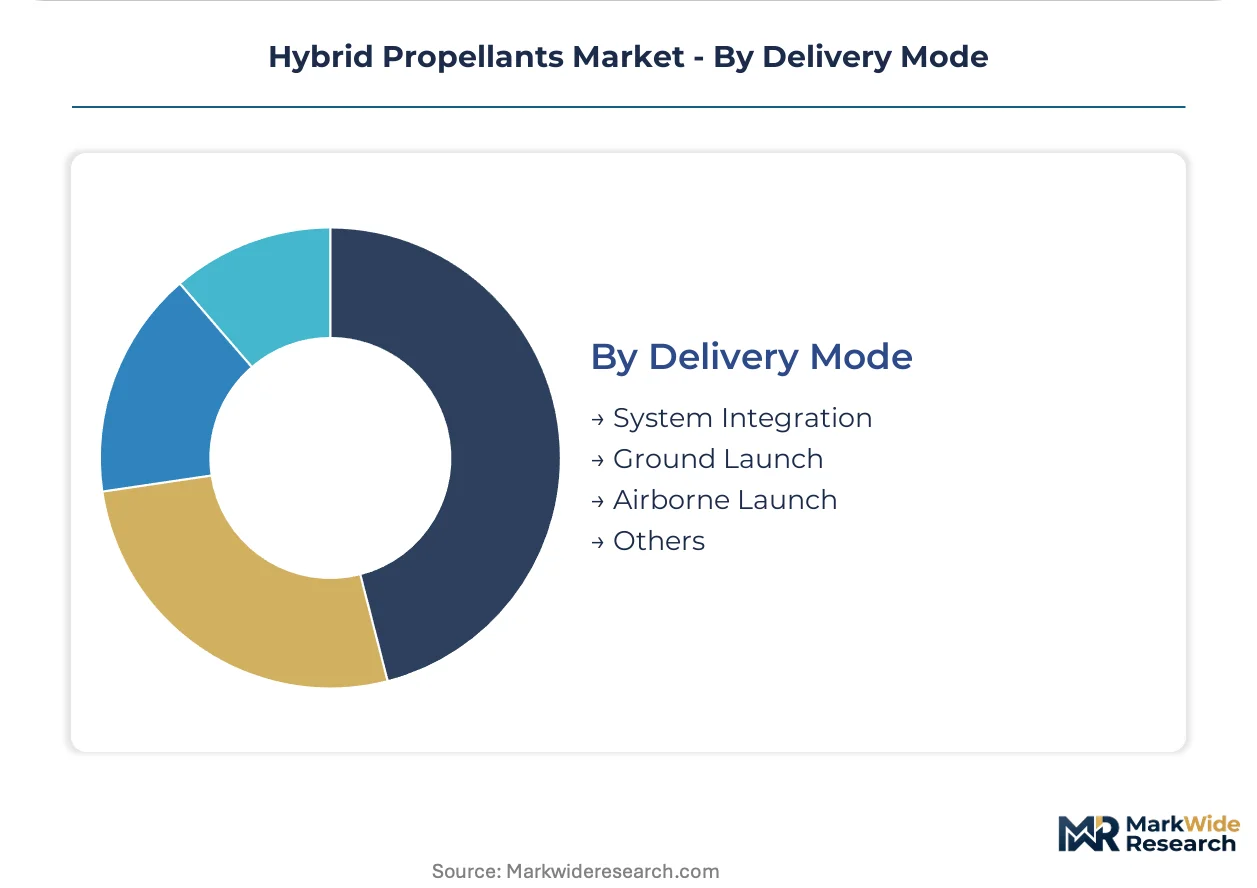
Delivery Mode:
Integration depth and customer proximity determine margin capture and recurring revenue potential across service models.
- System Integration:Turnkey propulsion stage delivery including fuel grain fabrication, oxidizer system design, and vehicle interface qualification. U.S. commercial crew programs in Florida concentrate demand for this full-service model. System Integration commands the highest contract values; airborne launch configurations are gaining traction fastest.
- Ground Launch:Fixed-site launch infrastructure services tied to Space Coast facilities and comparable ranges. Established regulatory precedents reduce licensing uncertainty.
- Airborne Launch:Carrier aircraft deployment of hybrid-powered vehicles for orbital insertion flexibility. Reduced range-safety footprint appeals to congested launch licensing environments.
- Others:Maritime launch platforms and mobile ground systems serving emerging spaceports. Limited operational heritage constrains insurance and financing availability.
System Integration absorbs dominant contract value; Airborne Launch is scaling fastest through mobility advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paraffin feedstock availability and Space Coast infrastructure anchor hybrid propellant development in the United States, while REACH restrictions in Europe redirect oxidizer supply chains toward cleaner alternatives. Defense procurement cycles and constellation launch cadence requirements concentrate demand across distinct national regulatory environments.
United States
Commercial satellite operators and NASA Artemis programs drive hybrid stage procurement at unprecedented rates. FAA launch licensing requirements and EPA stratospheric emissions standards govern oxidizer selection toward nitrous oxide formulations. Florida's Space Coast testing facilities anchor qualification pipelines for defense and commercial motors alike.
China
Domestic launch providers expand hybrid propulsion procurement under MIIT spacecraft regulations and GB standards that localize technology sourcing. The country's national space administration constrains technology transfer while accelerating captive production of fuel grain formulations. Yangtze River Delta manufacturing clusters concentrate binder chemistry development for tactical booster applications.
Germany
EU REACH restrictions on ammonium perchlorate precursors force reformulation toward hydrogen peroxide oxidizers in upper-stage development. ECHA compliance timelines extend qualification cycles for defense interceptors and orbital transfer vehicles. Bavaria's aerospace engineering corridor hosts formulation houses adapting binder-oxidizer ratios to cleaner chemistries.
India
Production-linked incentives under the PLI scheme for space manufacturing attract international technology partners to localize hybrid motor fabrication. ISRO procurement specifications and BIS quality standards govern domestic qualification protocols. Bengaluru's satellite manufacturing cluster integrates propulsion stage development with constellation deployment timelines.
United Kingdom
Orbital transfer vehicle programs and satellite servicing missions specify restartable hybrid stages for debris removal applications. The country's national space regulator oversees launch licensing for emerging spaceport operations in Scotland and Cornwall. Harwell's space cluster anchors propulsion testing partnerships between research institutions and commercial developers.
Hybrid Propellants Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue additive manufacturing and clean oxidizer specializations. The vendor base stratifies across defense prime contractors with multi-decade government relationships, commercial space ventures with vertical integration strategies, and technology specialists leveraging patented fabrication methods. Three archetypes dominate: heritage defense suppliers sustaining strategic contract pipelines, commercial launch developers compressing development cycles through co-location, and materials innovators collapsing manufacturing variability through automated production. Competitive moves concentrate on strategic partnerships for oxidizer supply security and geographic expansion toward emerging spaceport jurisdictions.
Within the heritage defense tier, Northrop Grumman and Raytheon Technologies Corporation exemplify sustained government contract capture through established casting infrastructure and qualification heritage. Sierra Space Corporation represents the commercial crew and cargo vector, anchoring propulsion system integration with human-rated safety profiles. Firehawk Aerospace Inc. occupies the manufacturing innovation archetype, with Zhengzhou-based China Aerospace Science and Technology Corporation and HyImpulse exemplifying regional specialization in domestic launch vehicle development.
| Leading Market Players |
|---|
| Virgin Galactic |
| HyImpulse |
| HyPrSpace |
| Raytheon Technologies Corporation |
| China Aerospace Science and Technology Corporation |
| Northrop Grumman |
| Firehawk Aerospace Inc. |
| Pulsar Fusion |
| Sierra Space Corporation |
| Others |
Supply & Pricing Matrix
Nitrous oxide spot pricing and ammonium perchlorate precursor indices cascade through hybrid propellant supply chains into three distinct procurement tiers. Composite formulation contracts absorb volatility through long-term offtake agreements with defense primes, while commercial constellation operators negotiate volume-scaled spot arrangements that expose them to oxidizer feedstock swings.
Pricing Analysis
Ground-test campaign bundling separates premium-tier composite propellant contracts from unbundled research-grade deliveries. Three-tier pricing structure across mission-certified, flight-proven, and experimental formulations dominates procurement, with NASA safety qualification and EPA emissions compliance as primary differentiation drivers. Pricing pressure stems from REACH-restricted oxidizer sourcing consolidation in Europe, compressing margins for non-vertically integrated blenders. Government programs exhibit lowest price sensitivity due to appropriation-backed multi-year commitments; small-lift vehicle developers face acute cost compression.
Supply Chain Analysis
Dual-sourcing mandates from U.S. defense procurement officers require qualified backup suppliers for nitrous oxide and hydroxyl-terminated polybutadiene feedstocks. Manufacturing concentrates in the United States, Germany, and China, with paraffin binder chemistry anchored in Florida's Space Coast and Bavaria's aerospace corridor. Supply chains draw from specialized chemical precursors, precision casting equipment, and cryogenic handling infrastructure. Single-source vulnerability concentrates in European ammonium perchlorate precursor networks disrupted by ECHA compliance timelines. Distribution runs through integrated vehicle-stage developers and tier-1 defense primes with captive qualification facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid propellant markets occupy a technology-transition phase where 3D-printed fuel grain fabrication displaces traditional casting processes. Paraffin-based additive manufacturing is collapsing development cycles and rewriting combustion predictability standards.
For Market Incumbents: To counter additive manufacturing entrants collapsing motor qualification timelines, Northrop Grumman and heritage defense primes should accelerate in-house production of automated fuel grain deposition systems. Certification investment in restartable hybrid stages for lunar lander applications anchors government contract retention against emerging commercial challengers.
For New Entrants and Emerging Players: The premium-to-economy pricing gap in orbital transfer vehicle propulsion opens white-space entry for flight-proven hybrid stages with standardized interface specifications. India's PLI scheme localization pathways and U.K. satellite servicing missions represent the most penetrable demand clusters. Go-to-market execution should prioritize Space Coast co-location for integrated vehicle-stage development partnerships.
For Investors and Strategic Acquirers: Distressed-cycle entries favor materials innovators with patented additive manufacturing methods in the United States and Germany. Long-term viability over a multi-year horizon hinges on oxidizer supply security and regulatory compliance positioning. The signal to watch is FAA launch licensing precedent development for throttleable solid-liquid configurations as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| 3D-Printed Fuel Grain Scale-Up | Additive manufacturing integration collapses motor qualification timelines for commercial constellation operators. |
| Nitrous Oxidizer Supply Agreement | Long-term offtake contracts with feedstock suppliers mitigate REACH-driven precursor sourcing concentration. |
| Space Coast Co-Location Partnership | Florida testing facility proximity accelerates integrated vehicle-stage development for crew-rated programs. |
| Restartable Stage Certification | NASA Artemis qualification opens lunar lander and orbital transfer vehicle procurement pipelines. |
| India PLI Localization Joint Venture | Bengaluru satellite manufacturing cluster integration captures production-linked incentive space manufacturing demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this hybrid propellants analysis. Primary interviews with propulsion system engineers, defense procurement officers, FAA licensing specialists, and chemical formulation scientists combined with bottom-up and top-down triangulation. Secondary sources encompassed EPA emissions filings, ECHA REACH compliance databases, NASA contract award announcements, and ISRO procurement specifications. Customs records tracked nitrous oxide and ammonium perchlorate precursor trade flows across U.S., German, and Indian ports.
Segment-level granularity modeled propellant type, application mission profile, end-user procurement authority, and delivery mode integration depth across the projection horizon. Propulsion stage unit economics, launch cadence requirements from constellation operators, and defense appropriation cycles informed value derivation. CAGRs were computed from installed capacity assessments and contract pipeline visibility. Forecast inputs included FAA licensing timeline distributions, paraffin regression-rate improvement curves, and 3D-printed fuel grain adoption trajectories.
Inputs from propulsion test facility operators and defense prime contract disclosure filings were available through the study window; gaps in emerging spaceport operational data and classified interceptor program specifications introduce uncertainty bands around defense segment projections. Deviation in EPA stratospheric chlorine emissions threshold enforcement or ECHA REACH precursor restriction expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Bunker Fuel Market
Fuels
Global Chemical Logistics Market
Fuels
Japan Bunker Fuel Market
Fuels
China Coal Market
Fuels
Refuse Derived Fuel Market
Fuels
Europe Firewood Market
Fuels
Europe Gas Market
Fuels
Briquette Market
Fuels
Brazil Bunker Fuel Market
Fuels
Mobile Fuel Delivery Market
Fuels
Brazil LNG Market
Fuels
Global Liquid Gas Cylinder (LGC) Market
Fuels
Europe Black and Wood Pellets Market
Fuels
Smart Gas Solutions Market
Fuels
Singapore Bunker Fuel Market
Fuels
India Petrol Station Market