
 Global Oilfield Stimulation Chemicals Market | 2026-2036
Global Oilfield Stimulation Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oilfield Stimulation Chemicals Market Foresight
A shortage of petroleum chemists with deep unconventional reservoir expertise is redrawing competitive boundaries across the sector. Halliburton leverages its integrated service model to capture bundled chemical-plus-execution contracts in North American shale plays. BASF SE anchors European supply through its specialty surfactant manufacturing complexes in Ludwigshafen. Dow competes on scale, sustaining cost advantages in synthetic polymer production for high-volume friction reducer programs.
Oilfield stimulation chemicals encompass acids, gelling agents, friction reducers, and surfactants formulated to enhance hydrocarbon flow from tight formations through hydraulic fracturing and acidizing operations. These formulations typically operate at concentrations between 0.1% and 5% by volume, with viscosity targets spanning 1–50 cP depending on formation permeability and proppant loading requirements. Friction reducers dominate product type revenue due to their indispensable role in slickwater fracturing, while acidizing formulations command premium margins in carbonate reservoir applications. Hydraulic fracturing technology leads volume consumption, though enhanced oil recovery represents the fastest-growing application segment as mature fields seek tertiary recovery methods.
The EPA mandates chemical disclosure under the Toxic Substances Control Act, while Saudi Arabia's national environmental regulator imposes strict wastewater reinjection standards that filter permissible additive chemistries. China's MEE enforces GB standards on drilling fluid biodegradability, creating compliance costs for imported formulations. Stakeholders must monitor evolving fracturing fluid restrictions across multiple jurisdictions to anticipate reformulation investments and qualify for operator procurement programs.
Market Dynamics
Unconventional reservoir depletion rates in the Permian Basin and Sichuan Basin are forcing operators to intensify fracturing stage counts per well, which drives chemical consumption intensity even as rig counts plateau.
Growth Catalysts
- US EPA disclosure mandates:Chemical transparency requirements under the Toxic Substances Control Act are accelerating demand for pre-approved, documented formulations that streamline operator permitting.
- Enhanced oil recovery:Mature carbonate fields in Saudi Arabia and the United Arab Emirates are expanding acidizing programs to sustain plateau production.
- Polyacrylamide supply localization:Domestic manufacturing of friction reducer base polymers in China and the United States is shortening lead times for high-volume slickwater programs.
Market Restraints
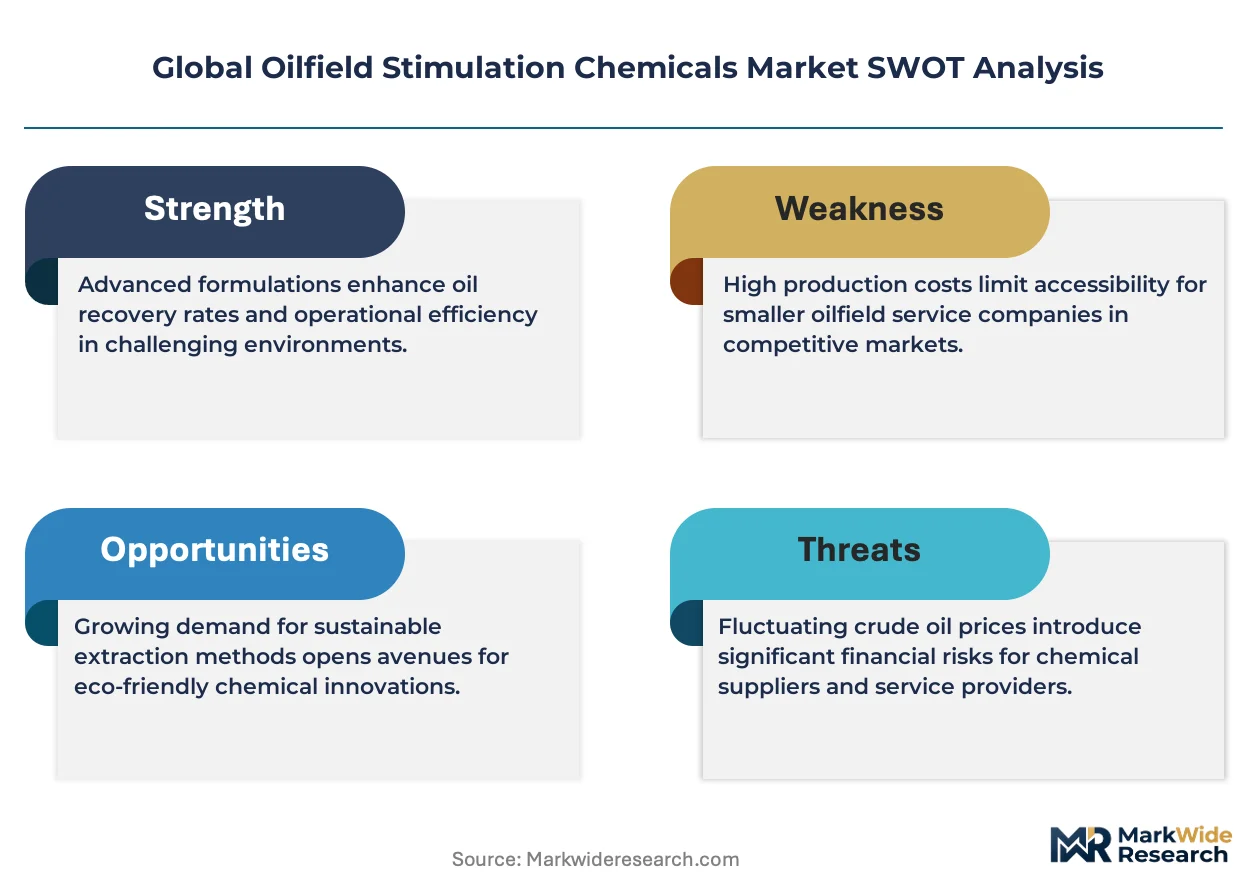
- Guar gum price volatility:Weather-dependent harvests in India create input cost instability for crosslinked gel systems used in high-viscosity fracturing.
- Specialty surfactant supply concentration:European manufacturing clusters in Germany and Belgium control critical anionic surfactant supply for high-salinity tolerant formulations.
- Biocide efficacy limitations:Sulfate-reducing bacteria resistance in recycled produced water is constraining water reuse rates in the Permian Basin.
Strategic Opportunities
- Argentina Vaca Muerta development:Underexploited shale formations require complete stimulation chemical supply chain buildout as drilling activity scales.
- CO2-based fracturing fluids:Convergence of carbon capture infrastructure and energized fluid technology opens low-permeability reservoir access with reduced water intensity.
- Direct chemical-to-pad distribution:Bulk liquid delivery networks bypass traditional distributor markups in high-density North American shale plays.
Industry Challenges
- Reservoir engineer specialization:Scarcity of professionals combining petrophysics expertise with chemical formulation knowledge delays field optimization.
- Biodegradability certification timelines:China's MEE GB standard approval processes for imported green surfactants extend product qualification cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oilfield Stimulation Chemicals Market |
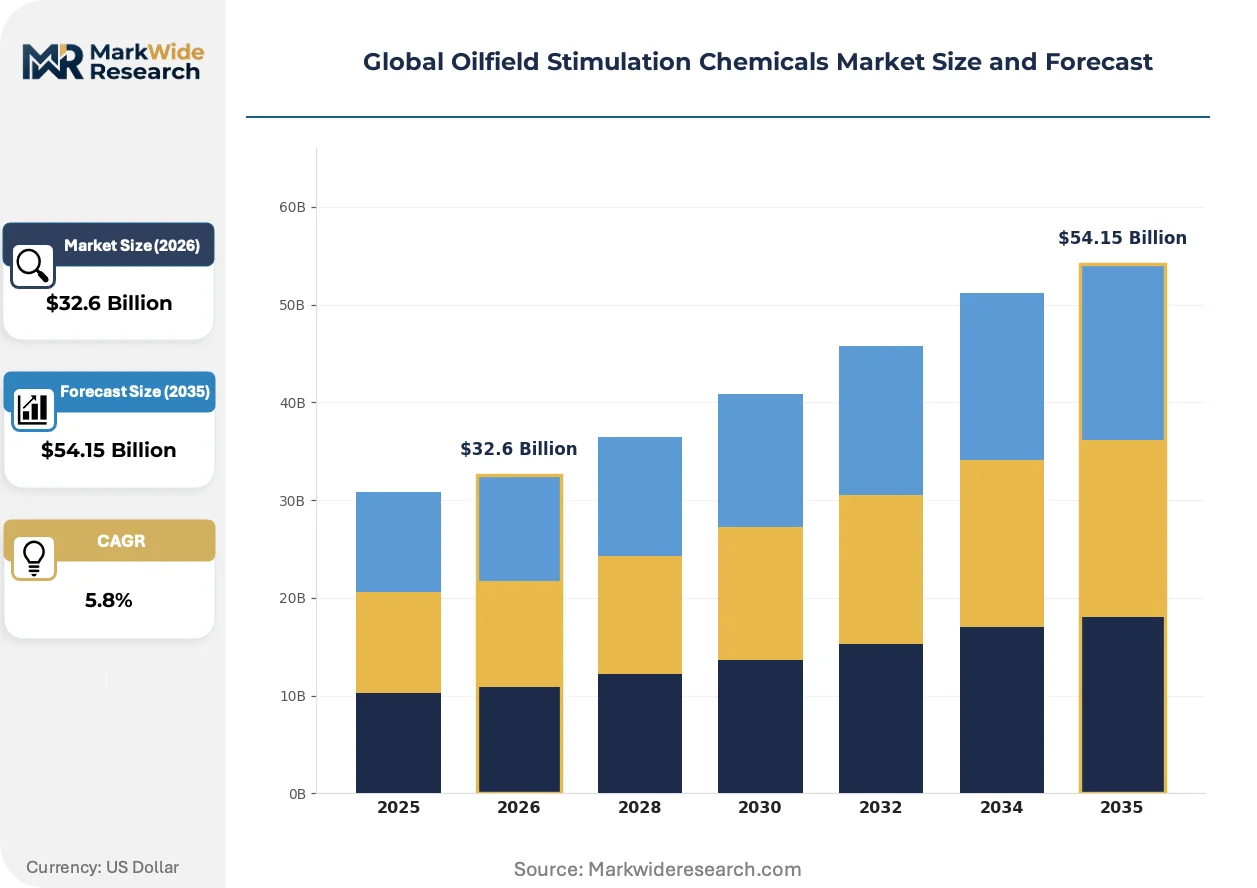
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $54.15 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acids, Friction Reducers, Gels, Surfactants Technology: Hydraulic Fracturing, Acidizing, Foam Stimulation, Others Application: Onshore, Offshore, Enhanced Oil Recovery, Gas Wells End User: Oil Producers, Service Companies, Mining Operations, Contractors |
| Companies Covered | BASF SE, Halliburton, Schlumberger Limited, Clariant, Dow, Solvay, Ecolab Inc., Baker Hughes Company, Nouryon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oilfield Stimulation Chemicals Market Shifts & Advancements
Formulation chemistry is pivoting toward high-salinity tolerance and rapid biodegradability as operators confront produced water reuse mandates and stricter environmental discharge limits across multiple jurisdictions.
Nano-silica proppant flowback control additives are fragmenting traditional resin-coated sand markets. Shale operators in Texas and New Mexico are deploying these materials in 30% of new Permian completions. The technology is fragmenting established supply relationships by enabling independent chemical suppliers to bypass legacy proppant-chemical bundling arrangements.
EU REACH authorization requirements for persistent, bioaccumulative, and toxic substances are forcing reformulation of biocide packages used in European geothermal and oilfield applications. Industrial consequence includes accelerated substitution of glutaraldehyde-based products with quaternary ammonium alternatives. Nordic geothermal operators are responding fastest, with Norway and Denmark completing biocide transitions ahead of continental deadlines.
Integrated service contracting is compressing standalone chemical procurement cycles. Exploration and production companies in the United States are consolidating vendors under single-source stimulation service agreements that embed chemical supply within execution pricing. This behavior is most visible in the Eagle Ford Shale, where operator procurement teams have reduced qualified chemical suppliers by 40% since 2022.
Global Oilfield Stimulation Chemicals Market Segmentation
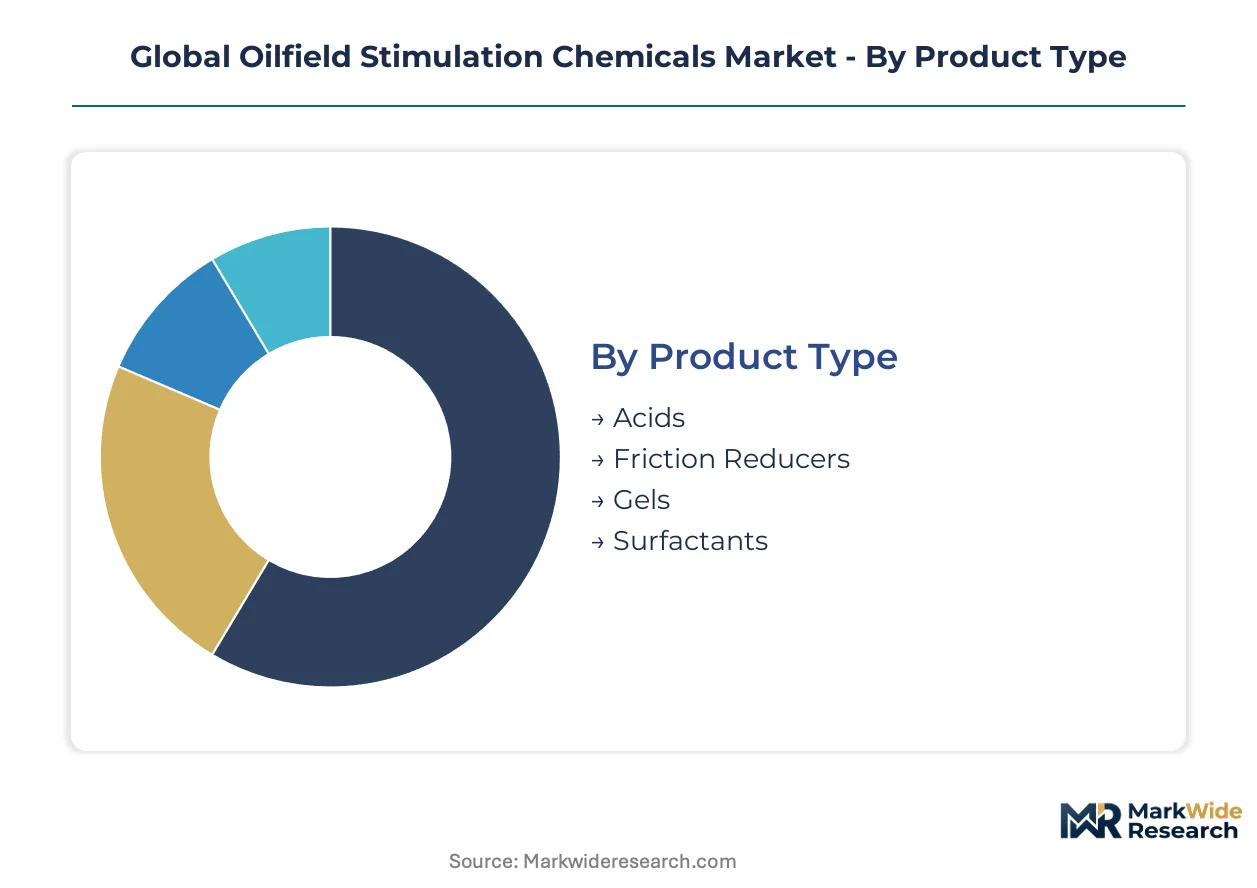
Segmentation in oilfield stimulation chemicals reveals distinct procurement patterns across product types and technologies. Operators bundle formulations differently depending on reservoir characteristics and regulatory environments.
Product Type:
Friction reducers and acids move through high-volume distributor networks in North American shale plays, while specialty surfactants route through technical service channels in Middle East carbonate fields.
- Friction Reducers:Polyacrylamide-based polymers reduce pumping pressures in slickwater fracturing, typically dosed at 0.5–2.0 gallons per thousand gallons. Demand concentrates in Permian Basin horizontal wells where stage counts per lateral now exceed 50, driving chemical intensity even as rig counts flatten.
- Acids:Hydrochloric and hydrofluoric formulations dissolve carbonate matrix and bypass wellbore damage. Saudi Aramco's mature carbonate fields sustain premium consumption for matrix acidizing and fracture acidizing programs targeting sustained plateau production.
- Gels:Guar-derived and synthetic polymer systems suspend proppant in high-viscosity fracturing fluids.
- Surfactants:Anionic and non-ionic formulations reduce interfacial tension in complex brine chemistries.
By volume, friction reducers lead. By margin expansion, surfactants are climbing fastest as high-salinity tolerant formulations command technical premiums.
Technology:
Technology selection tracks reservoir permeability and water availability constraints across operating basins.
- Hydraulic Fracturing:Slickwater and gelled fluid systems create conductive fractures in tight formations. Sichuan Basin shale operators in China deploy these technologies under MEE wastewater reinjection standards that filter permissible additive chemistries.
- Acidizing:Matrix and fracture acidizing restore or enhance natural permeability in carbonate reservoirs. UAE onshore fields are expanding acidizing programs as tertiary recovery methods gain priority in mature asset portfolios.
- Foam Stimulation:Energized fluids using nitrogen or carbon dioxide reduce water intensity in water-sensitive formations.
- Others:Emerging chemistries including chelating agents and nanoparticle dispersions.
Hydraulic fracturing dominates current throughput. Acidizing is expanding most quickly as carbonate field maturity accelerates intervention frequency.
Application:
Application mix varies by basin geology and infrastructure access, with onshore operations driving formulation standardization.
- Onshore:Land-based drilling and completion operations in shale and tight sandstone formations. Texas and New Mexico operators deploy nano-silica proppant flowback control additives in 30% of new Permian completions, fragmenting traditional resin-coated sand supply relationships.
- Enhanced Oil Recovery:Tertiary recovery methods including chemical flooding and gas injection. This segment is gaining share fastest as mature fields seek production maintenance beyond primary and secondary recovery.
- Offshore:Deepwater and shelf operations requiring logistics-intensive supply chains.
- Gas Wells:Coalbed methane and tight gas stimulation programs.
Onshore operations anchor current volumes. Enhanced oil recovery shows the steepest expansion trajectory as decline rates intensify across legacy basins.
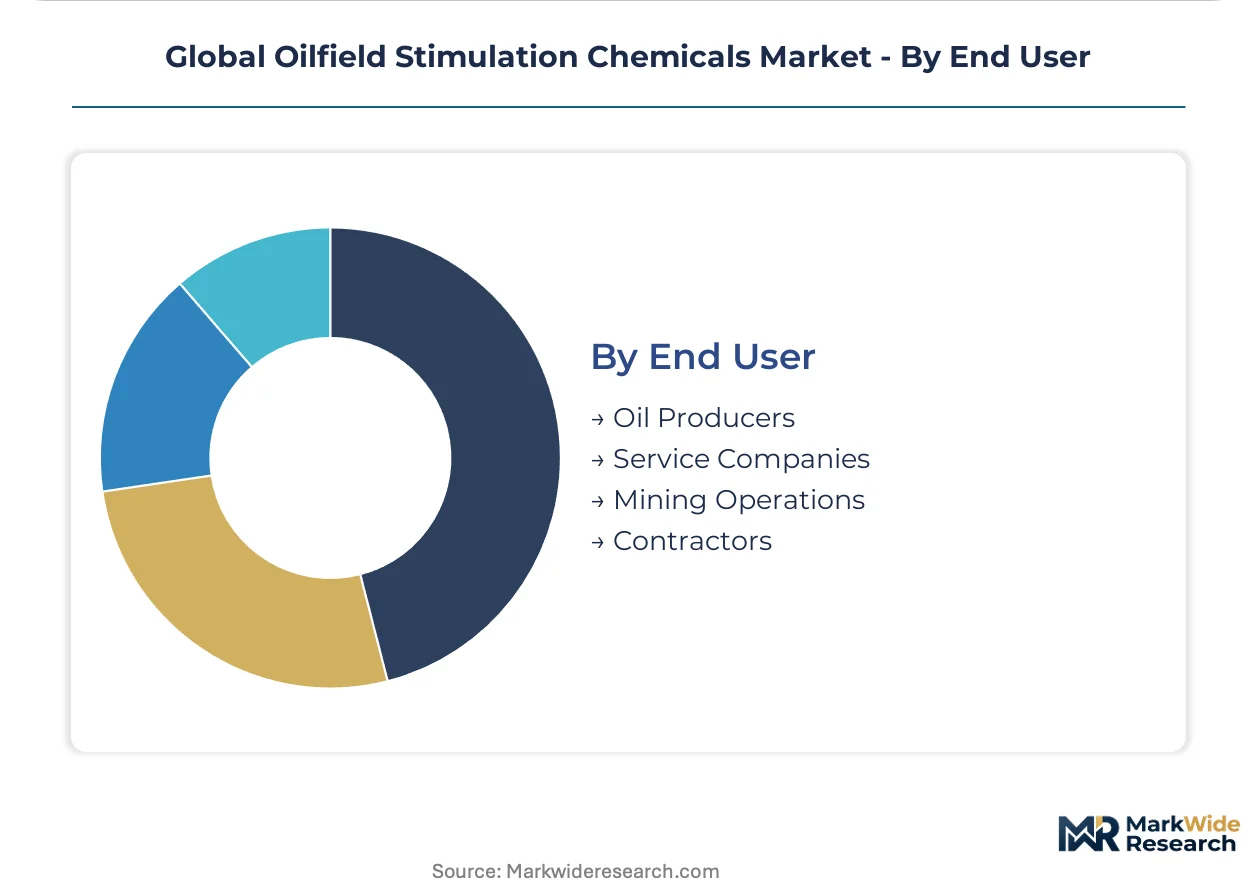
End User:
End-user structure is consolidating under integrated service contracting that compresses standalone chemical procurement cycles.
- Service Companies:Halliburton and Schlumberger affiliates bundle chemical supply within execution pricing. Eagle Ford Shale operators have reduced qualified chemical suppliers by 40% since 2022 through single-source stimulation service agreements.
- Oil Producers:National oil companies and independents with direct procurement functions. Saudi Aramco and ADNOC maintain stringent qualification programs that filter formulation approvals through national environmental regulators.
- Contractors:Drilling and completion subcontractors purchasing spot chemical requirements.
- Mining Operations:Non-petroleum extraction applications including geothermal and solution mining.
Service companies control the largest procurement volumes. Oil producers are gaining negotiating leverage fastest through consolidated vendor rationalization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA disclosure mandates under the Toxic Substances Control Act anchor chemical procurement patterns in the United States, while Saudi Arabia's national environmental regulator and China's MEE impose parallel wastewater management standards that filter formulation approvals across major producing regions.
United States
Permian Basin shale operators drive friction reducer consumption through intensified stage counts per lateral. EPA chemical disclosure requirements accelerate demand for pre-approved, documented formulations that streamline operator permitting. Midland-Odessa chemical distribution hubs now bypass traditional distributor markups through direct bulk liquid delivery networks.
Saudi Arabia
Mature carbonate fields sustain premium acidizing consumption as Saudi Aramco targets sustained plateau production. The national environmental regulator imposes strict wastewater reinjection standards that filter permissible additive chemistries. Eastern Province manufacturing clusters anchor specialty surfactant supply for high-salinity tolerant formulations.
China
Sichuan Basin shale operators deploy hydraulic fracturing technologies under MEE wastewater reinjection standards. GB standards on drilling fluid biodegradability create compliance costs for imported formulations. Domestic polyacrylamide manufacturing in Sichuan-Chongqing is shortening lead times for high-volume slickwater programs.
United Arab Emirates
Onshore fields expand acidizing programs as tertiary recovery methods gain priority in mature asset portfolios. ADNOC maintains stringent qualification programs that filter formulation approvals through national environmental regulators. Abu Dhabi industrial zones concentrate biocide package reformulation activity ahead of regional compliance deadlines.
Argentina
Vaca Muerta shale formations require complete stimulation chemical supply chain buildout as drilling activity scales. The country's national environmental regulator is developing fracturing fluid restrictions that will shape future formulation investments. Neuquén Basin logistics infrastructure is attracting international chemical distributors for pad-direct distribution models.
Global Oilfield Stimulation Chemicals Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the stimulation chemicals sector. Integrated oilfield service providers bundle chemical supply within execution pricing, compressing standalone procurement cycles for high-volume fracturing programs. Specialty chemical multinationals anchor premium formulation supply through captive surfactant and polymer manufacturing. Three archetypes dominate: integrated service providers with bundled chemical-plus-execution contracts, specialty chemical manufacturers with backward integration into base polymer production, and regional distributors with direct-to-pad logistics networks. Competitive moves center on strategic partnerships for localized polymer manufacturing and portfolio diversification into biodegradable surfactant formulations.
Among integrated service providers, Halliburton and Baker Hughes Company exemplify the bundled contracting archetype that has reduced qualified chemical suppliers by 40% in active shale plays since 2022. BASF SE anchors the specialty chemical multinational tier through its Ludwigshafen manufacturing complexes. These three entities occupy positions spanning the service-chemical interface, with Halliburton and Baker Hughes representing execution-integrated models while BASF SE exemplifies formulation-scale supply.
| Leading Market Players |
|---|
| BASF SE |
| Halliburton |
| Schlumberger Limited |
| Clariant |
| Dow |
| Solvay |
| Ecolab Inc. |
| Baker Hughes Company |
| Nouryon |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Permian Basin operators and friction reducer suppliers lock in polyacrylamide supply access while anchoring price visibility against guar gum volatility. These arrangements bundle volume commitments with EPA-compliant formulation documentation, transferring regulatory qualification costs upstream while insulating buyers from spot market swings in synthetic polymer feedstocks.
Pricing Analysis
Price spreads between Midland-Odessa bulk delivery and Neuquén Basin imports exceed transport-cost differentials alone, reflecting supply localization premiums. Three-tier pricing structure across premium, standard, and economy levels segments by salinity tolerance certification and biodegradability grade. Cost compression in standard-tier friction reducers is intensifying because domestic Sichuan-Chongqing polyacrylamide capacity is displacing imported base polymer. Independent shale producers exhibit highest price sensitivity, while Saudi Aramco's integrated qualification programs absorb premium surfactant costs without volume negotiation.
Supply Chain Analysis
Inventory cycles for anionic surfactants stretch 8-12 weeks longer than friction reducer polymers due to European manufacturing cluster concentration in Ludwigshafen and Belgian chemical complexes. Supply concentrates in the United States, China, and Germany for base polymer production, while India anchors guar gum cultivation. Raw material dependencies include acrylamide monomer, guar seed harvests, and hydrofluoric acid feedstocks. Single-source vulnerability runs through specialty surfactant intermediates subject to EU REACH authorization delays. Distribution runs through direct-to-pad bulk liquid networks in North American shale plays, bypassing traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment: EPA disclosure mandates and Saudi wastewater reinjection standards create formulation qualification barriers that delay competitor entry by 12-18 months.
For Market Incumbents: Secure captive surfactant manufacturing capacity in the Eastern Province to defend margin position against European supply concentration risks. Deepen backward integration into Sichuan-Chongqing polyacrylamide production to shorten lead times for high-volume slickwater programs. Lock in long-term offtake agreements with Permian operators before Argentina Vaca Muerta supply chain buildout matures. For New Entrants and Emerging Players: Direct-to-pad logistics under-service in the Neuquén Basin offers entry where Halliburton and Baker Hughes distribution networks remain thin. Target biodegradable surfactant qualification under China's MEE GB standards, where approval timelines have filtered imported formulations and created white space for patient capital. Partner with Argentine national oil company procurement teams ahead of fracturing fluid restriction finalization. For Investors and Strategic Acquirers: Regional distributors with pad-direct logistics networks in high-density shale plays represent the most defensible acquisition archetype, combining asset-light working capital efficiency with operator relationship lock-in. Long-term viability hinges on water reuse mandate acceleration across multiple jurisdictions. Watch biocide package reformulation activity in Abu Dhabi industrial zones as signal of regional compliance deadline convergence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Polymer Production | Sichuan-Chongqing polyacrylamide manufacturing shortens lead times for Permian slickwater programs. |
| Biodegradable Surfactant Certification Investment | China MEE GB standard approval opens procurement access to Sichuan Basin shale operators. |
| Direct-to-Pad Distribution Network Buildout | Neuquén Basin logistics infrastructure captures Vaca Muerta drilling activity scaling. |
| Long-term Supply Agreement with National Oil Companies | Saudi Aramco and ADNOC qualification programs filter competitors through environmental regulator entrenchment. |
| High-Salinity Tolerance Formulation R&D | Eastern Province manufacturing clusters command technical premiums in mature carbonate field acidizing. |
Research Methodology
Desk research of trade flow databases, EPA chemical disclosure filings, and Saudi environmental regulator wastewater standards preceded structured interviews with stimulation service company procurement directors, oil producer completion engineers, and specialty chemical plant managers. Primary fieldwork with Permian Basin chemical distribution operators and Sichuan shale development teams validated secondary estimates of friction reducer consumption intensity. Bottom-up well-count modeling and top-down polymer demand aggregation were cross-referenced against customs data and industry association capacity disclosures.
Variance decomposition across technology segments, product type tiers, and regional regulatory clusters shaped the analytical framework over the projection horizon. Segmentation dimensions included reservoir permeability class, fracturing fluid chemistry family, and environmental compliance grade. CAGRs were derived from stage-count intensity curves and well-completion forecasts, with inputs from produced water reuse rate assumptions and tertiary recovery program expansion timelines in mature carbonate fields.
Underlying assumptions cover regulatory enforcement continuity, polymer supply localization trajectories, and unconventional reservoir depletion rate stability, with deviation risk concentrated in China MEE approval timeline extensions and Argentina fracturing fluid restriction finalization. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
North America Oil and Gas Line Pipe Market
Oil & Gas
Oil and Gas Security Services Market
Oil & Gas
Floating Liquefied Natural Gas (FLNG) Terminals Market
Oil & Gas
Gabon Oil and Gas Market
Oil & Gas
Wellhead System Market
Oil & Gas
Southeast Asia Oil and Gas EPC Market
Oil & Gas
Global Oilfield Communications Market
Oil & Gas
Latin America Coiled Tubing Market
Oil & Gas
Middle-East and Africa Liner Hanger System Market
Oil & Gas
South Korea Oil and Gas Market
Oil & Gas
Saudi Arabia Drilling Services Market
Oil & Gas
Middle East and Africa Digital Oilfield Market
Oil & Gas
United States Oil and Gas Upstream Market
Oil & Gas
India Natural Gas Market
Oil & Gas
Logging While Drilling (LWD) Market
Oil & Gas
Deepwater and Ultra-Deepwater Exploration and Production Market