
 Europe Cheese Market | 2026-2036
Europe Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cheese Market Intelligence
Precision fermentation is narrowing the gap between conventional dairy and alternative protein methods for cheese production across European manufacturing facilities. Groupe Lactalis leverages its extensive dairy cooperative network to dominate raw milk sourcing in France and Italy. Arla Foods amba anchors its position through farmer-owned cooperative structures spanning Denmark, Sweden, and Germany. Hochland Holding GmbH & Co. KG specializes in processed and branded cheese segments, competing through retail channel control in Central and Eastern Europe.
Cheese comprises milk proteins coagulated through enzymatic or acid-based processes, aged under controlled temperature and humidity conditions to develop texture, flavor profiles, and microbial stability for human consumption and food manufacturing. The product type dimension shows Cheddar and Mozzarella occupying the largest volume positions due to industrial foodservice demand, while Gouda and Feta sustain premium positioning through PDO protections and regional heritage claims. Distribution channel dynamics reveal Supermarkets controlling mainstream volume flows, with Online Retail representing the fastest structural expansion as direct-to-consumer platforms capture specialty and subscription-based cheese sales.
EFSA governs food safety and nutritional labeling standards that constrain product formulation and marketing claims across all member states, while the EU Green Deal's Farm to Fork Strategy mandates methane reduction targets and sustainable feed requirements that reshape dairy farm economics. REACH and CE marking protocols apply to processing equipment and packaging materials, affecting capital investment cycles for producers. Stakeholders must monitor how evolving EU-wide carbon accounting rules for livestock agriculture will alter cost structures and sourcing strategies for milk suppliers and finished cheese manufacturers.
Market Dynamics
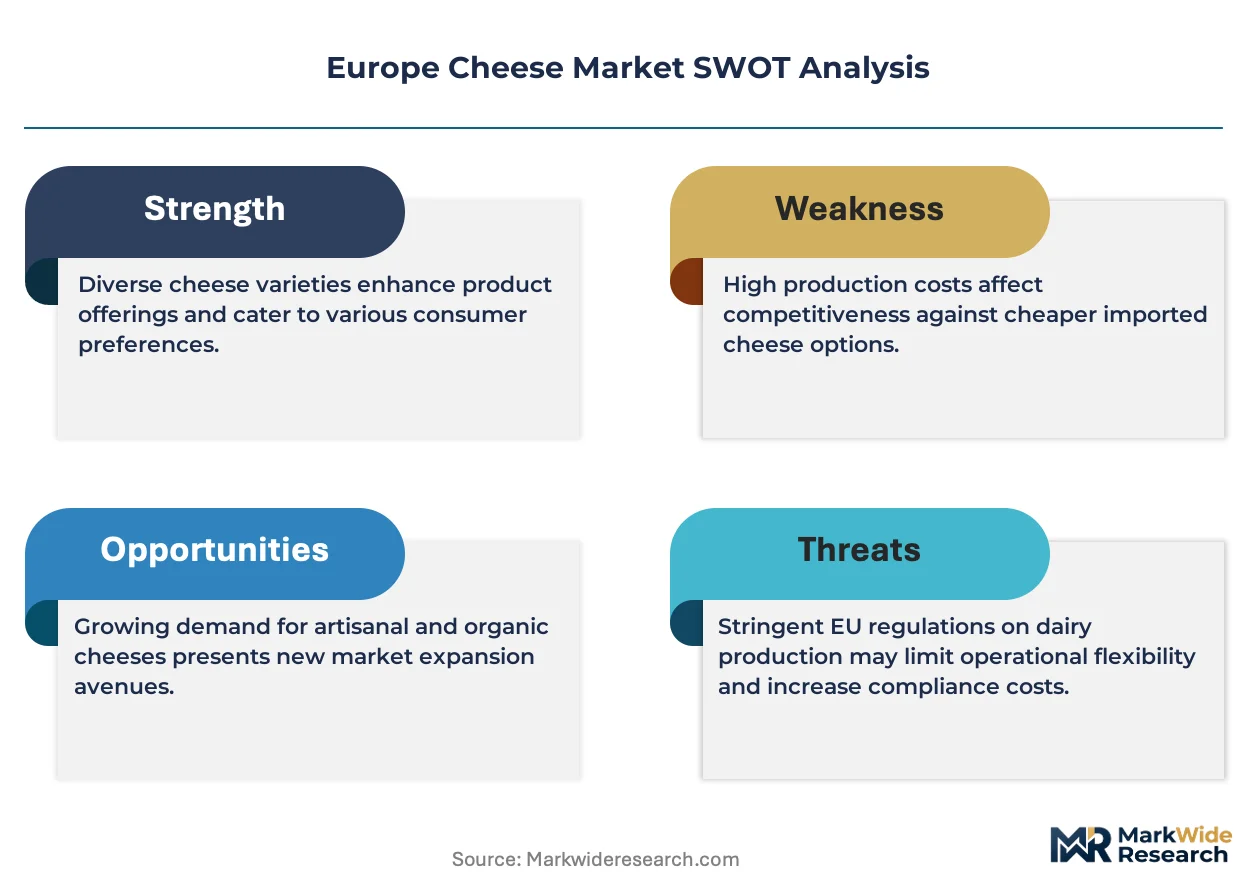
Precision fermentation is compressing traditional dairy economics while EFSA methane mandates force farm-level restructuring across France, Italy, and Spain. Supply concentration among French dairy cooperatives collides with German retail channel consolidation.
Growth Catalysts
- EU Farm to Fork Strategy:Methane reduction targets and sustainable feed requirements are accelerating capital deployment into low-emission dairy infrastructure across member states.
- Foodservice channel expansion:Operators in Germany and Italy are adding cheese-centric menu sections, pulling volume through mozzarella and cheddar procurement.
- PDO heritage premiums:Protected designation of origin frameworks in France, Spain, and Italy sustain price premiums for Comté, Manchego, and Parmigiano-Reggiano.
Market Restraints
- Raw milk supply concentration:French dairy cooperatives control upstream sourcing, limiting independent processor access to volume contracts.
- REACH compliance costs:Processing equipment and packaging material certification under ECHA protocols extends capital investment cycles.
- Plant-based protein substitution:Oat and almond-derived alternatives capture lactose-intolerant and flexitarian consumers in urban German and Dutch markets.
Strategic Opportunities
- Direct-to-consumer platforms:Online retail channels in Poland and Romania enable subscription-based specialty cheese access beyond supermarket distribution.
- Carbon accounting integration:EU-wide livestock emissions tracking creates first-mover advantage for farms deploying methane-capture digesters.
- Artisanal segment whitespace:Underpenetrated premium positioning in Central European markets allows heritage brand expansion.
Industry Challenges
- Aging farmer demographics:Succession gaps in French and Italian dairy cooperatives threaten operational continuity and raw milk quality consistency.
- CE marking delays:Processing equipment certification timelines under EU machinery directives extend facility upgrade schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cheese Market |
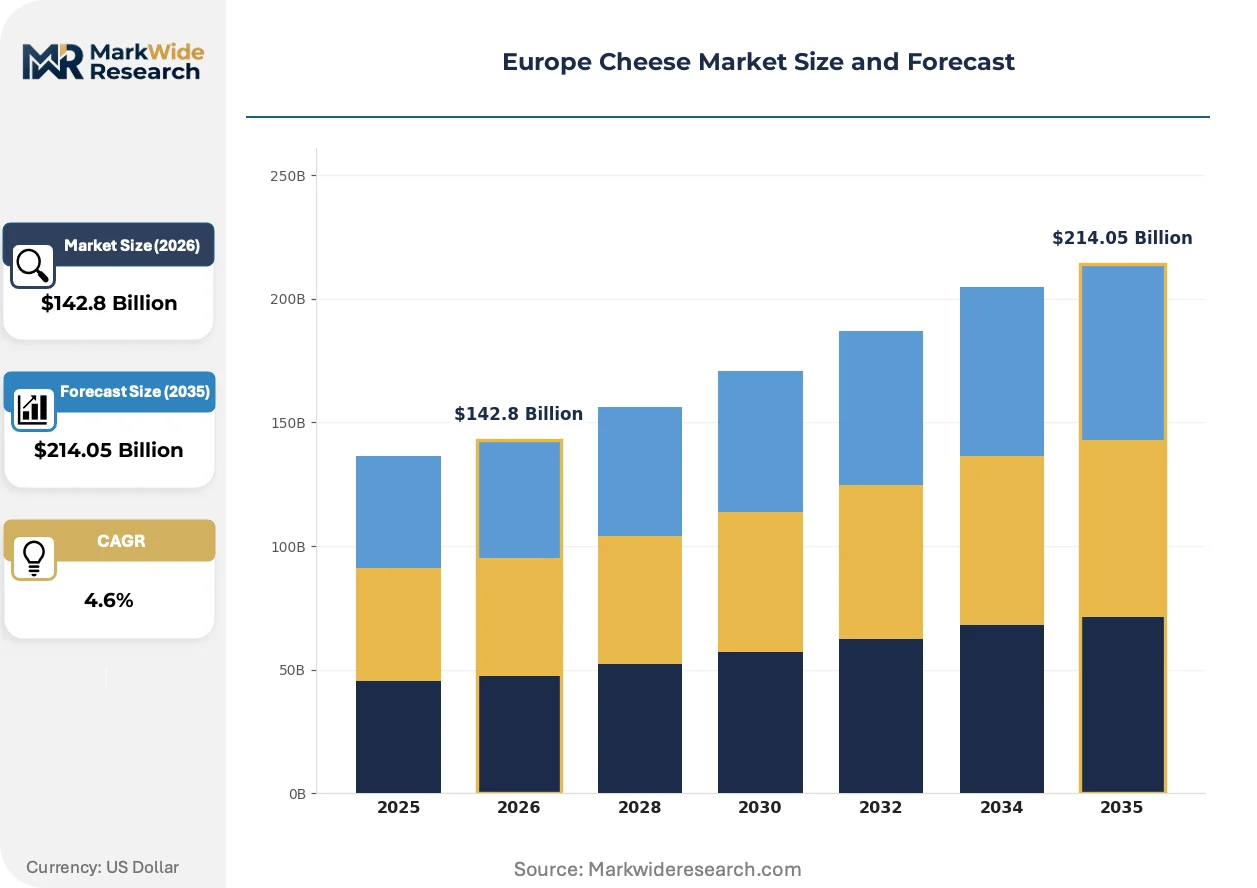
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $214.05 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cheddar, Mozzarella, Gouda, Feta Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Foodservice End User: Consumers, Restaurants, Cafés, Hospitality Price Tier: Premium, Mid-Range, Economy, Bulk |
| Companies Covered | Arla Foods amba, Groupe Lactalis, Hochland Holding GmbH & Co. KG, Saputo Inc., The Kraft Heinz Company, Bel Group, SAVENCIA SA, FrieslandCampina, Granarolo SpA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cheese Market Strategic Shifts & Innovations
Biotechnology and regulatory carbon accounting are converging to reshape production economics. Channel fragmentation and direct-to-consumer platforms are redistributing margin capture away from traditional retail.
Precision fermentation using whey protein isolates and casein alternatives is hybridizing conventional dairy processing with biotech manufacturing. Specialty cheese producers in Denmark and the Netherlands are piloting these methods to reduce feed-to-protein conversion costs. The technology is hybridizing asset-light production models with heritage brand positioning.
EFSA nutritional labeling revisions and EU Green Deal carbon border adjustments are tightening formulation disclosure requirements. Manufacturers must now document Scope 3 emissions from feed cultivation through retail distribution. Small-scale PDO producers in Italy and Spain face disproportionate compliance burdens relative to integrated French cooperatives.
Foodservice procurement teams are consolidating supplier relationships into fewer, deeper partnerships with traceability guarantees. Independent distributors in Germany and Austria are losing share to cooperative-owned logistics networks. This consolidation is most visible in institutional catering contracts across Nordic public sector buyers.
Europe Cheese Market Segmentation
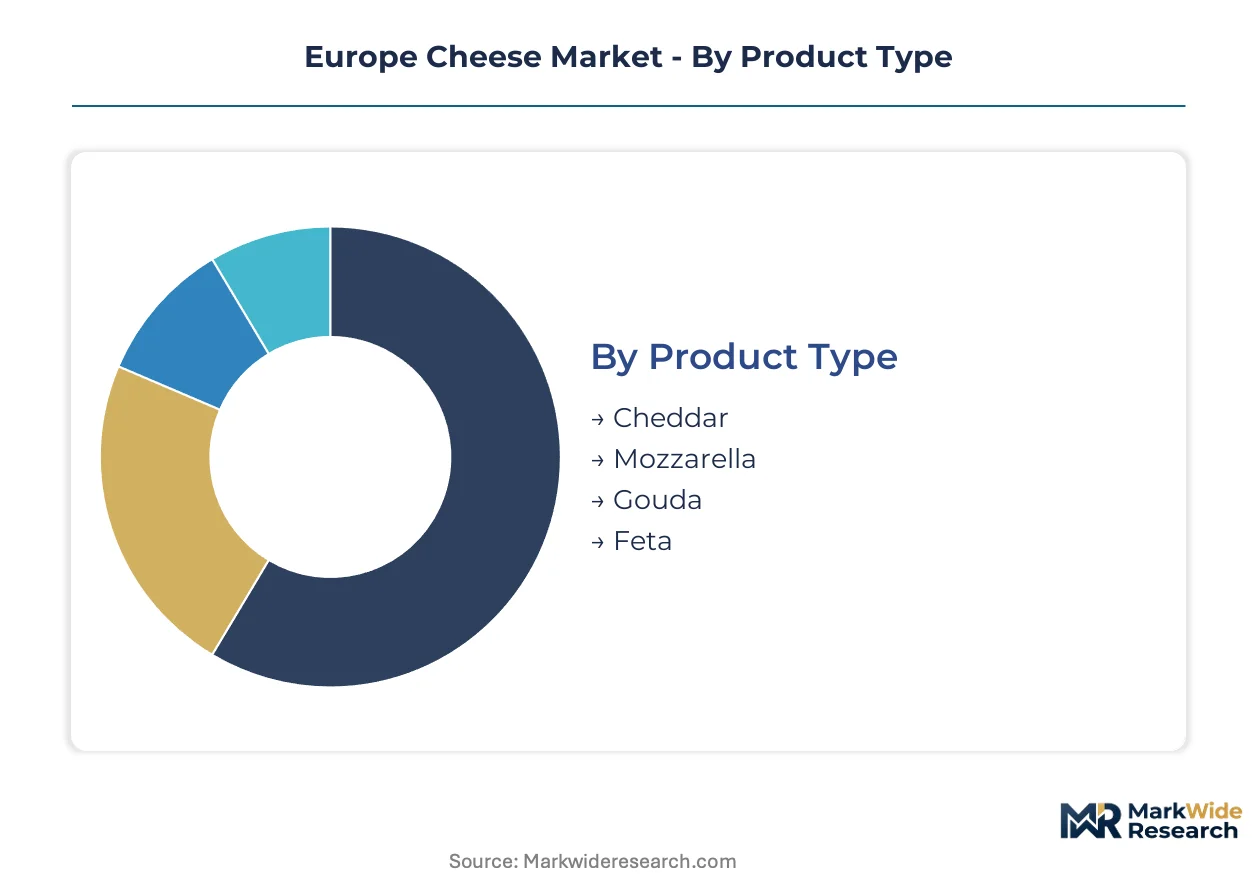
Cheese segmentation in Europe tracks divergent velocity patterns across product lifecycles and channel throughput. Understanding which segments rotate inventory fastest versus which accumulate aged stock determines working capital efficiency and margin capture for processors and distributors.
Product Type:
Cheddar and Mozzarella turn inventory fastest through industrial foodservice pipelines, while Gouda and Feta extend aging cycles that tie up capital longer.
- Cheddar:Hard cheese with annatto coloring and 9-24 month aging profiles delivers melt consistency for burger chains and ready-meal manufacturers. German and British foodservice operators pull volume through centralized procurement hubs serving QSR networks.
- Mozzarella:Pasta filata stretching process yields elastic texture optimized for pizza applications requiring stretch and moisture retention. Italian pizzeria chains and frozen pizza manufacturers in Germany concentrate demand through specification-grade contracts with moisture and fat content thresholds.
- Gouda:Dutch-origin washed-curd cheese with wax rind aging develops crystalline texture profiles commanding heritage premiums in Dutch and Belgian retail.
- Feta:Brined white cheese with PDO protections in Greece and Bulgaria supplies salad manufacturers and Mediterranean restaurant segments across France and Germany.
Cheddar dominates installed base across European food manufacturing. Mozzarella is where expansion concentrates as pizza delivery platforms scale.
Distribution Channel:
Channel economics split between high-velocity supermarket throughput and emerging direct-to-consumer margin structures that bypass traditional wholesale markups.
- Supermarkets:Multi-temperature logistics networks and category management fees structure access for branded and private-label cheese portfolios. French and German retail consolidation through E. Leclerc, REWE, and Carrefour concentrates volume allocation decisions among fewer buyers.
- Online Retail:Temperature-controlled last-mile delivery and subscription models capture specialty and artisanal segments with higher per-unit margins. Dutch and Polish platforms are climbing the fastest as urban consumers seek direct access to PDO and farmstead varieties bypassing supermarket assortment limits.
- Specialty Stores:Curated aging cellars and cut-to-order service command premium positioning for Comté, Parmigiano-Reggiano, and Manchego in Paris, Milan, and Madrid retail corridors.
- Foodservice:Institutional procurement contracts and distributor rebates shape volume flows to restaurant groups, hotel chains, and catering operators across Nordic and Central European markets.
Supermarkets dominate installed base. Online Retail is where expansion concentrates.
End User:
User segmentation maps consumption occasions from daily household preparation to commercial food preparation at scale.
- Consumers:Household purchasers selecting retail formats for home cooking and entertaining occasions drive volume through mozzarella and cheddar staples.
- Restaurants:Full-service operators specifying cheese for menu execution concentrate demand in Italian, French, and Spanish independent and chain establishments.
- Cafés:Limited-menu operators focusing on breakfast and light meal applications pull processed and fresh cheese varieties through broadline distributors.
- Hospitality:Hotel banquet and room service operations procure through group purchasing organizations with sustainability and traceability requirements.
Consumers dominate installed base. Restaurants are where expansion concentrates.
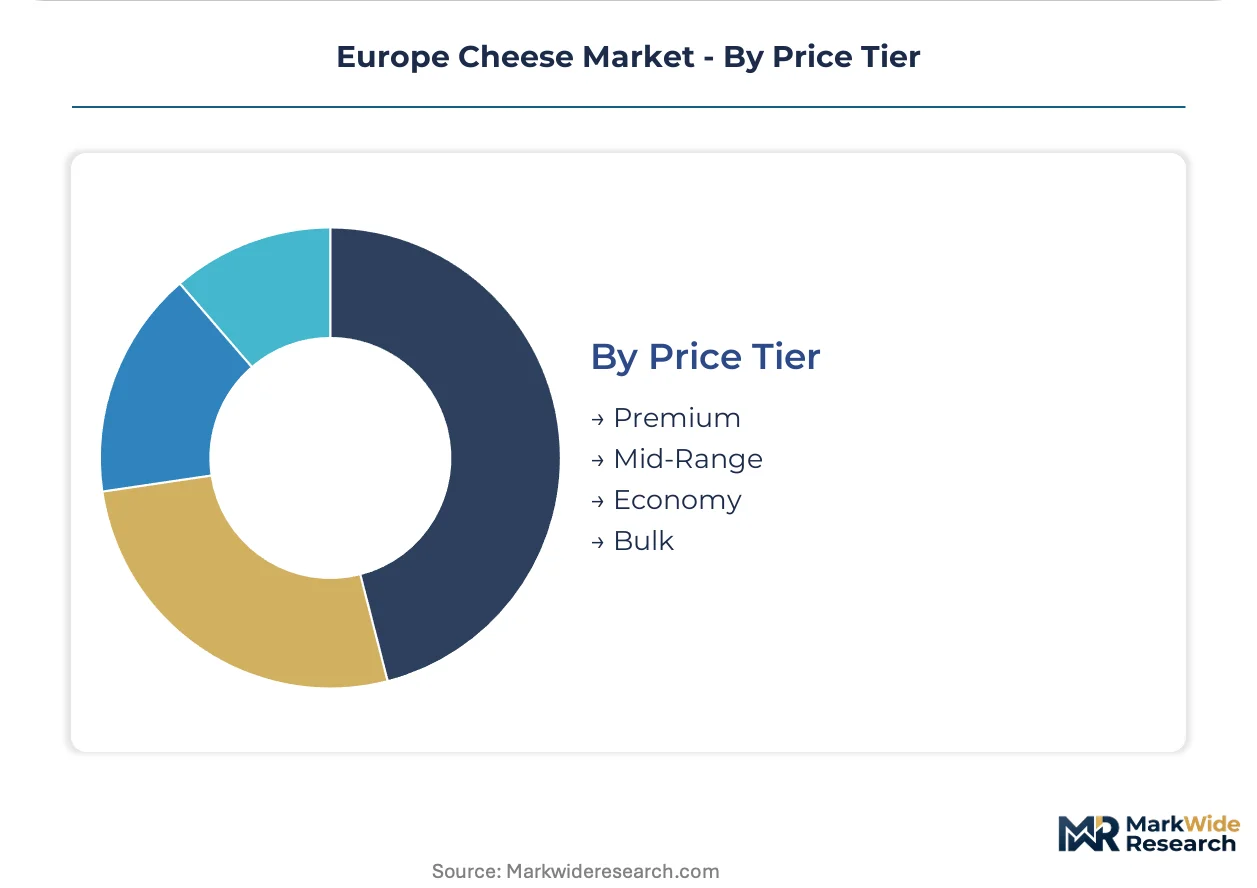
Price Tier:
Pricing stratification reflects input cost structures, aging duration, and certification premiums rather than manufacturing scale alone.
- Premium:PDO-protected varieties and extended aging protocols command three-to-five-fold multiples over commodity equivalents through provenance claims and limited production.
- Mid-Range:Branded processed and semi-hard varieties balance quality signaling with accessibility for mainstream retail and foodservice procurement.
- Economy:Private-label and basic processed cheese delivers functional melt and flavor at minimum cost thresholds for price-sensitive retail segments.
- Bulk:Industrial food manufacturing and ingredient supply contracts purchase unbranded blocks and shreds through negotiated volume agreements with cooperative processors.
Mid-Range dominates installed base. Premium is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics across Europe favor surplus producers in France and the Netherlands while import-dependent markets in Germany and the United Kingdom absorb cross-border volumes. Trade flows concentrate through Rotterdam and Calais logistics corridors, with EFSA sanitary standards governing intra-EU movements.
France
Domestic consumption of Comté, Roquefort, and Camembert sustains artisanal production networks across Auvergne-Rhône-Alpes and Normandy. The EU Farm to Fork Strategy mandates methane reduction targets that reshape dairy cooperative economics in these regions. Lactalis leverages its cooperative network to dominate raw milk sourcing in the northwestern production belt.
Germany
Foodservice operators in Bavaria and North Rhine-Westphalia are expanding cheese-centric menu sections, pulling mozzarella and cheddar through centralized procurement hubs. REACH compliance costs for processing equipment certification extend capital investment cycles for mid-sized processors. Berlin-based distributors are losing share to cooperative-owned logistics networks serving institutional catering contracts.
Italy
PDO-protected Parmigiano-Reggiano and Grana Padano command heritage premiums through limited production in Emilia-Romagna and Lombardy. Aging farmer demographics in Po Valley dairy cooperatives threaten operational continuity for raw milk quality consistency. Milan retail corridors sustain specialty store demand for cut-to-order aged varieties.
Netherlands
Gouda and Edam production concentrates in Noord-Holland and Friesland, with wax-rind aging protocols developing crystalline texture profiles for Belgian and German export markets. Precision fermentation pilots in Wageningen food technology clusters are hybridizing conventional dairy processing with biotech manufacturing methods.
Spain
Manchego PDO protections in Castilla-La Mancha sustain price premiums through regional heritage claims for Mediterranean restaurant segments across France and Germany. EFSA labeling standards constrain product formulation disclosure for small-scale producers relative to integrated French cooperatives. Madrid retail corridors anchor domestic specialty cheese distribution.
Europe Cheese Market Key Industry Players
On the supply side, the industry is consolidating around cooperative-owned structures and integrated dairy networks that control upstream raw milk access. French and Danish cooperative models dominate volume procurement, while German and Swiss processors compete through retail channel control and branded positioning. Two strategic archetypes prevail: cooperative-integrated giants with captive milk supply and specialist processors focused on PDO heritage premiums. Competitive moves concentrate on vertical integration into raw milk sourcing and direct-to-consumer platform expansion to bypass wholesale markups.
Within the cooperative-integrated tier, Groupe Lactalis and Arla Foods amba exemplify the farmer-owned structure spanning multiple member states. Hochland Holding GmbH & Co. KG occupies a position among Central European specialists competing through processed and branded cheese segments. These three anchors represent divergent strategic positions: Lactalis with its extensive French and Italian cooperative network, Arla through its Denmark-Sweden-German farmer ownership model, and Hochland via retail channel concentration in Eastern European markets.
| Leading Market Players |
|---|
| Arla Foods amba |
| Groupe Lactalis |
| Hochland Holding GmbH & Co. KG |
| Saputo Inc. |
| The Kraft Heinz Company |
| Bel Group |
| SAVENCIA SA |
| FrieslandCampina |
| Granarolo SpA |
| Others |
Cost & Logistics Intelligence
Rotterdam-Calais freight corridors anchor cost dynamics across the Europe Cheese Market, where dairy cooperative concentration in France and the Netherlands amplifies upstream pricing power while downstream buyers face tiered premiums for PDO-certified varieties.
Pricing Analysis
Conventional dairy processing, precision fermentation pilots, and hybrid biotech methods stratify production cost structures across the Europe Cheese Market. Three-tier pricing separates PDO-protected heritage varieties from branded mid-range offerings and private-label economy tiers, with certification grade and aging duration as primary differentiation drivers. Cost compression in commodity cheddar and mozzarella intensifies as foodservice procurement teams consolidate supplier relationships. Independent restaurants and cafés exhibit highest price sensitivity, while hospitality group purchasing organizations absorb premium positioning for traceability guarantees.
Supply Chain Analysis
EFSA sanitary standards and EU Green Deal carbon border mechanisms constrain cross-border cheese flows between member states. Raw milk sourcing concentrates in France, the Netherlands, and Italy through cooperative-owned structures. Feed cultivation, dairy herd management, and aging cellar infrastructure anchor production dependencies. Single-source vulnerability threatens processors locked out of French cooperative networks. Distribution runs through supermarket centralized procurement hubs and emerging direct-to-consumer temperature-controlled platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Cheese Market functions as a recurring-revenue opportunity where subscription-based direct-to-consumer platforms and foodservice specification contracts expand faster than commodity spot sales.
For Market Incumbents: Harden cooperative network exclusivity through captive raw milk contracting in France and Italy to defend against precision fermentation entrants. Deepen aging cellar infrastructure for PDO-protected varieties to sustain heritage premiums. EFSA methane mandates threaten operational continuity for farms lacking digester deployment. For New Entrants and Emerging Players: Central European markets with underpenetrated artisanal positioning represent the most penetrable entry point for heritage brand expansion. Direct-to-consumer subscription models in Poland and Romania bypass supermarket category management barriers. Foodservice distributor partnerships with sustainability traceability guarantees accelerate procurement access. For Investors and Strategic Acquirers: Specialist processors with PDO certification portfolios and established aging protocols offer acquisition targets with defensible margin structures. Long-term viability hinges on carbon accounting integration and methane-capture infrastructure deployment across the analysis window. Watch for EU-wide livestock emissions tracking implementation as inflection indicator for cost structure divergence between integrated cooperatives and independent processors.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | Subscription models in Dutch and Polish markets bypass supermarket margin capture. |
| Methane-Capture Infrastructure Deployment | Digesters in French and Italian cooperatives secure EU Farm to Fork compliance. |
| PDO Certification Portfolio Expansion | Heritage protections for Comté and Parmigiano-Reggiano sustain price premiums. |
| Foodservice Procurement Consolidation | Deep partnerships with German and Nordic institutional buyers secure volume. |
| Precision Fermentation Pilot Investment | Wageningen and Danish biotech clusters reduce feed-to-protein conversion costs. |
Research Approach
A standing panel of dairy cooperative procurement directors, foodservice chain menu developers, EFSA regulatory affairs specialists, and specialty cheese retail buyers provided ongoing calibration across the study. Primary fieldwork combined structured interviews with secondary validation from EU Farm to Fork Strategy documentation, EFSA labeling standards filings, and customs trade flow records. Bottom-up volume modeling triangulated against top-down macroeconomic indicators across member states.
Scenario-bracketing framed low, base, and high cases across the projection horizon. Segmentation dimensions spanned product type, distribution channel, end user, and price tier, with regional regulatory cluster as an additional cheese-specific dimension. CAGRs derived from historical trajectory analysis adjusted for policy intervention timing and technology adoption curves. Feed cost volatility and cooperative consolidation pace served as key forecast inputs.
Practitioners should monitor EU carbon border adjustment implementation and precision fermentation scale-up milestones for early signals of structural shift. Forecasts reflect assumptions regarding methane reduction target enforcement and aging farmer demographic succession. Material shifts in EFSA nutritional labeling revisions or French cooperative network restructuring would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Non-GMO Yogurt Market
Dairy Products
United States Milk Protein Market
Dairy Products
Mascarpone Cheese Market
Dairy Products
Dairy Based Dressings Market
Dairy Products
Indonesia Whey Protein Market
Dairy Products
Asia-Pacific Cow Milk Minerals Market
Dairy Products
North America Sour Cream Market
Dairy Products
Canada Milk Protein Market
Dairy Products
Saudi Arabia Camel Dairy Market
Dairy Products
Asia-Pacific Flavored Milk Market
Dairy Products
UHT Milk Market
Dairy Products
Global Yogurt Powder Market
Dairy Products
Probiotic Fermented Milk Market
Dairy Products
Africa Dairy Protein Market
Dairy Products
Cheese Concentrate Market
Dairy Products
UAE Camel Dairy Market