
 Dairy Dessert and Yogurt Market | 2026-2036
Dairy Dessert and Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy Dessert and Yogurt Market Analysis
Plant-based alternatives are expanding their presence in dairy dessert formulations as oat and coconut bases replace conventional milk solids in premium frozen yogurt lines. Danone leverages its fermented foods expertise to sustain European distribution density for high-protein skyr variants. Yili Group anchors Chinese supply chains through captive dairy farming partnerships and cold-chain infrastructure. Chobani differentiates in the US natural channel with strained yogurt textures and limited-ingredient positioning.
Dairy dessert and yogurt comprises fermented milk products and chilled sweet preparations manufactured through controlled bacterial culture, thermal processing, and homogenization at 3.0–4.6 pH, serving nutritional, indulgence, and digestive health functions in retail and foodservice channels. Frozen yogurt occupies mature volume pools in North American convenience retail, while exotic blends within flavor profiles command premium shelf placement in Asian urban markets. Pouches in packaging type represent the fastest-growing format for on-the-go child and fitness enthusiast segments across Latin American convenience stores.
FDA standards for Grade A pasteurized milk and EU REACH frameworks on food contact materials shape permissible additive ranges and labeling claims across export markets, with China's SAMR enforcing stricter protein content thresholds for fermented milk designations. Stakeholders must monitor evolving national dairy standards and fermentation technology patents to secure formulation flexibility and cross-border market access.
Market Dynamics
Fermentation technology patents and clean-label ingredient regulations are compressing formulation flexibility, forcing manufacturers to rebuild supply chains around probiotic stability and plant-based fat mimics while urban middle-class demand concentrates in Chinese metropolitan clusters.
Growth Catalysts
- EU REACH frameworks:Clean-label mandates on food contact materials accelerate reformulation toward natural stabilizers and pectin-based gelling agents in premium dessert lines.
- Urban Chinese households:Domestic dairy processors scale cold-chain infrastructure to capture probiotic yogurt demand from fitness-oriented consumers in tier-1 cities.
- Precision fermentation:Microbial protein production reduces reliance on conventional milk solids while maintaining texture profiles in frozen yogurt applications.
Market Restraints
- Skim milk powder volatility:Global dairy commodity auctions concentrate pricing power among Oceania cooperative exporters, squeezing margin predictability for European dessert manufacturers.
- Probiotic strain IP concentration:Patent thickets around Lactobacillus rhamnosus GG and comparable clinically validated cultures limit independent formulation options for mid-tier processors.
- SAMR protein thresholds:China's stricter fermented milk designations reclassify lower-protein products as "milk beverages," restricting shelf placement and pricing authority.
Strategic Opportunities
- Southeast Asian convenience retail:Pouch-format yogurt penetration remains below 15 percent in Indonesian and Vietnamese urban centers, creating first-mover whitespace for aseptic filling investments.
- US FDA qualified health claims:Emerging pathways for live-and-active-culture digestive health positioning enable premium pricing in natural grocery channels.
- Oat-coconut base convergence:Hybrid plant-fat systems replicate mouthfeel of dairy lipids while meeting EU-origin labeling requirements for blended frozen desserts.
Industry Challenges
- Food safety culture certification:BRCGS and FSSC 22000 audit backlogs delay market entry for new entrants targeting EU retail multiples, extending capital lockup periods.
- Legacy ERP integration:Batch-level traceability requirements for fermented products clash with dated manufacturing execution systems at family-owned dairy operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy Dessert and Yogurt Market |
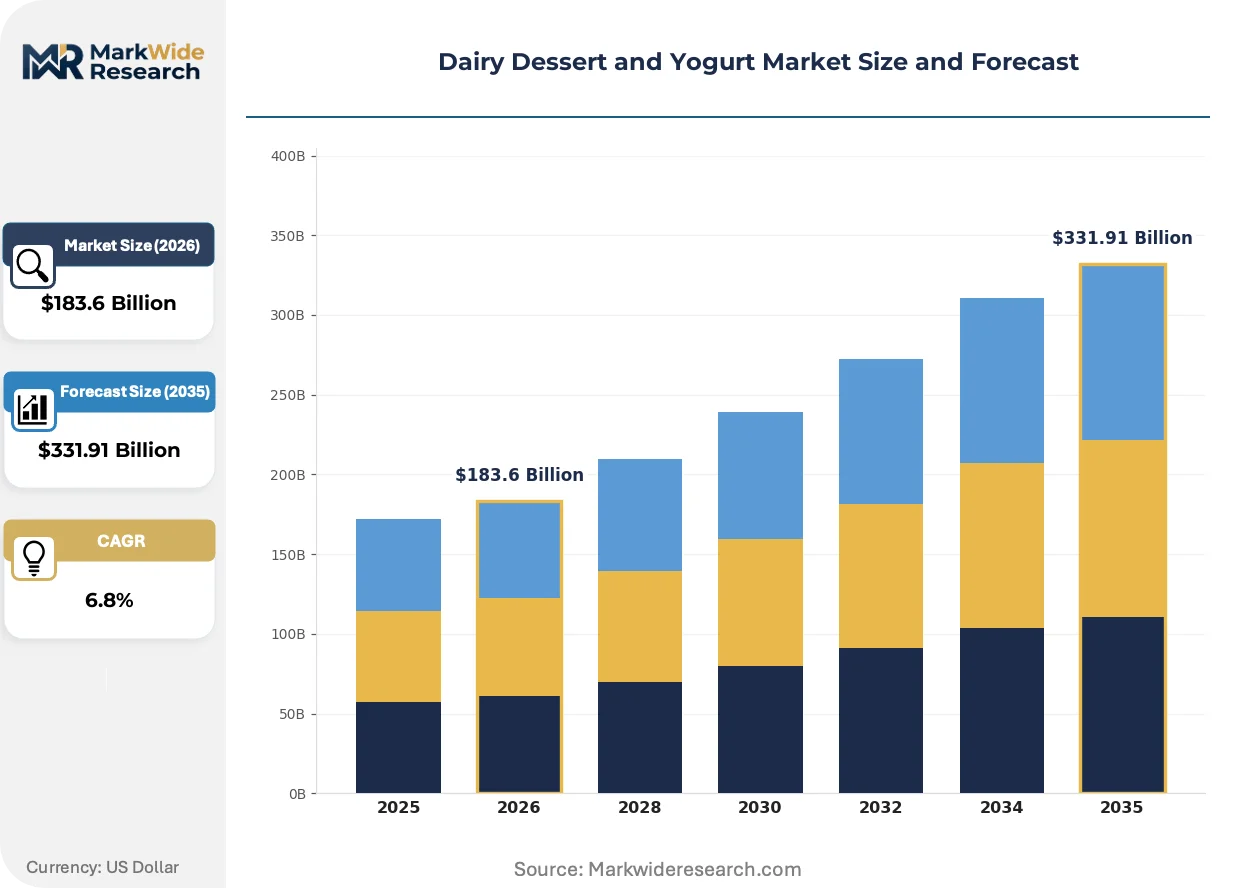
| Market Size in 2026 | $183.6 Billion |
| Market Size in 2035 | $331.91 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Yogurt, Parfaits, Cheese Cakes, Puddings Consumer Type: Health-Conscious Consumers, Families, Children, Fitness Enthusiasts Flavor Profile: Fruit-Flavored, Chocolate, Vanilla, Exotic Blends Packaging Type: Cups, Tubs, Pouches, Jars |
| Companies Covered | Lactalis, Grupo Lala, Danone, Mengniu Dairy, Yili Group, Chobani, Muller, FAGE International, General Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy Dessert and Yogurt Market Emerging Trajectories
Controlled bacterial culture automation and cold-chain digitization are compressing production cycles while regulatory divergence between major economies fragments formulation standardization.
Continuous-flow fermentation systems equipped with real-time pH and titratable acidity sensors are automating culture propagation in industrial yogurt production. Mid-scale dairy cooperatives in the Netherlands and Denmark adopt these systems to reduce batch-to-batch variation. This automation is compressing skilled technician requirements while accelerating time-to-market for seasonal flavor rotations.
EU F-Gas Regulation phase-down schedules for hydrofluorocarbon refrigerants force cold-chain operators to retrofit transport and storage infrastructure with CO2 transcritical systems. Dessert manufacturers dependent on frozen distribution face capital intensity spikes during the 2025-2030 compliance window. Greek-style and high-protein skyr variants with shorter frozen holding requirements gain formulation priority as hedges against refrigeration cost inflation.
Direct-to-gym subscription models for high-protein, portion-controlled yogurt packs displace traditional supermarket bulk purchasing among fitness enthusiasts in US coastal metropolitan areas. Locker-based refrigerated pickup points at boutique fitness studios replace convenience store impulse buys. This channel rotation concentrates brand loyalty with subscription-native entrants rather than legacy dairy processors.
Dairy Dessert and Yogurt Market Segmentation
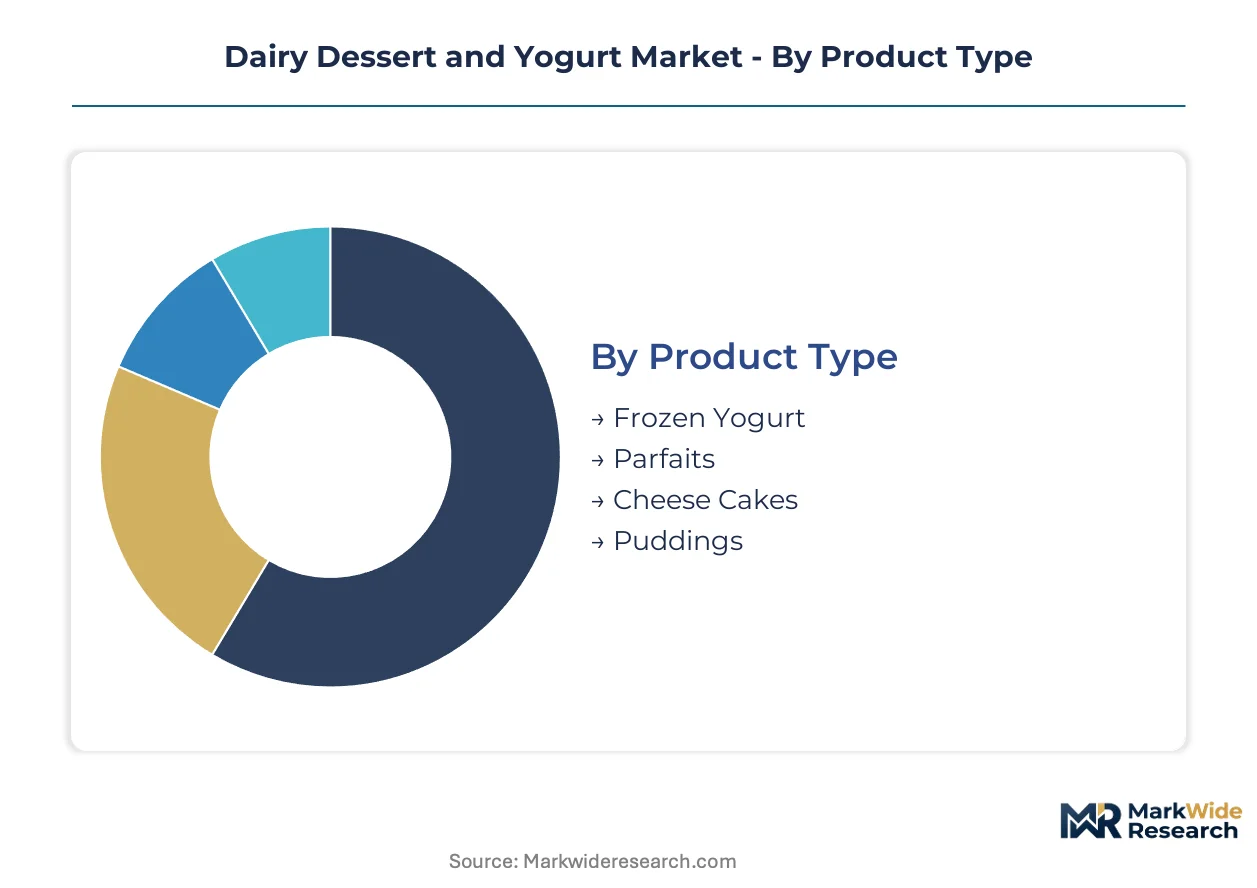
Segmentation in dairy desserts and yogurt tracks divergent consumption occasions—from post-workout protein delivery to family sharing formats—that command distinct formulation investments and cold-chain configurations. Manufacturers align R&D spending and packaging machinery against these purchase triggers rather than demographic proxies alone.
Product Type:
Buyers select product types based on consumption temperature requirements and preparation convenience, which dictates cold-chain intensity and margin structure.
- Frozen Yogurt:Aerated dairy base stabilized with pectin or guar gum, flash-frozen at -18°C to maintain overrun and scoopability. US convenience retail and Southeast Asian shopping mall kiosks concentrate volume, though EU F-Gas refrigeration cost spikes are compressing frozen distribution economics.
- Parfaits:Layered assemblies of strained yogurt, granola, and fruit compote requiring refrigerated—not frozen—holding at 2-4°C. North American natural grocery channels and Chinese tier-1 city convenience stores drive demand as grab-and-go breakfast substitutes.
- Cheese Cakes:Chilled dairy desserts with cream cheese or quark bases, often stabilized with gelatin or carrageenan for slice integrity.
- Puddings:Thermally processed starch-thickened milk desserts with ambient shelf stability, prevalent in European retail and Latin American school feeding programs.
Volume sits with frozen yogurt; growth tilts toward parfaits.
Consumer Type:
Consumer type segmentation reflects protein targeting intensity and permissible sugar thresholds that cascade into formulation specifications.
- Health-Conscious Consumers:Buyers prioritizing live cultures, reduced lactose, or added fiber with willingness to pay 40-60% premiums over standard formats. Chinese urban professionals and US coastal metropolitan households concentrate demand, with SAMR protein thresholds and FDA qualified health claim pathways shaping permissible positioning.
- Fitness Enthusiasts:High-protein seekers consuming 20g+ per serving, often through direct-to-gym subscription channels displacing traditional retail. Strained skyr and Greek-style variants with shorter frozen holding requirements gain preference as hedges against refrigeration cost inflation.
- Families:Multi-serve purchasers prioritizing value formats and child-acceptable flavor profiles in supermarket channels.
- Children:Single-serve pouch and tube formats with fortified calcium and vitamin D, regulated by strict EU additive frameworks and Chinese school nutrition standards.
Revenue concentrates with health-conscious consumers; steepest expansion trajectory belongs to fitness enthusiasts.
Flavor Profile:
Flavor selection signals indulgence versus functional positioning and determines fruit sourcing geography and natural colorant regulatory compliance.
- Exotic Blends:Fusion combinations incorporating matcha, yuzu, lychee, or turmeric, commanding premium placement in Asian urban markets and US coastal natural channels. EFSA novel food assessments and FDA GRAS self-determinations create divergent approval timelines for botanical inclusions.
- Fruit-Flavored:Strawberry, blueberry, and peach variants using either fruit preparation or natural-identical flavor systems, with EU origin labeling requirements pressing disclosure of fruit source percentages.
- Chocolate:Cocoa-based formulations with fat bloom control challenges in frozen applications, prevalent in European dessert traditions and Latin American treat cultures.
- Vanilla:Standard base flavor with Madagascar Bourbon and Tahitian varietals distinguishing premium from economy tiers through extract versus vanillin labeling.
Share clusters in fruit-flavored; premium expansion favors exotic blends.
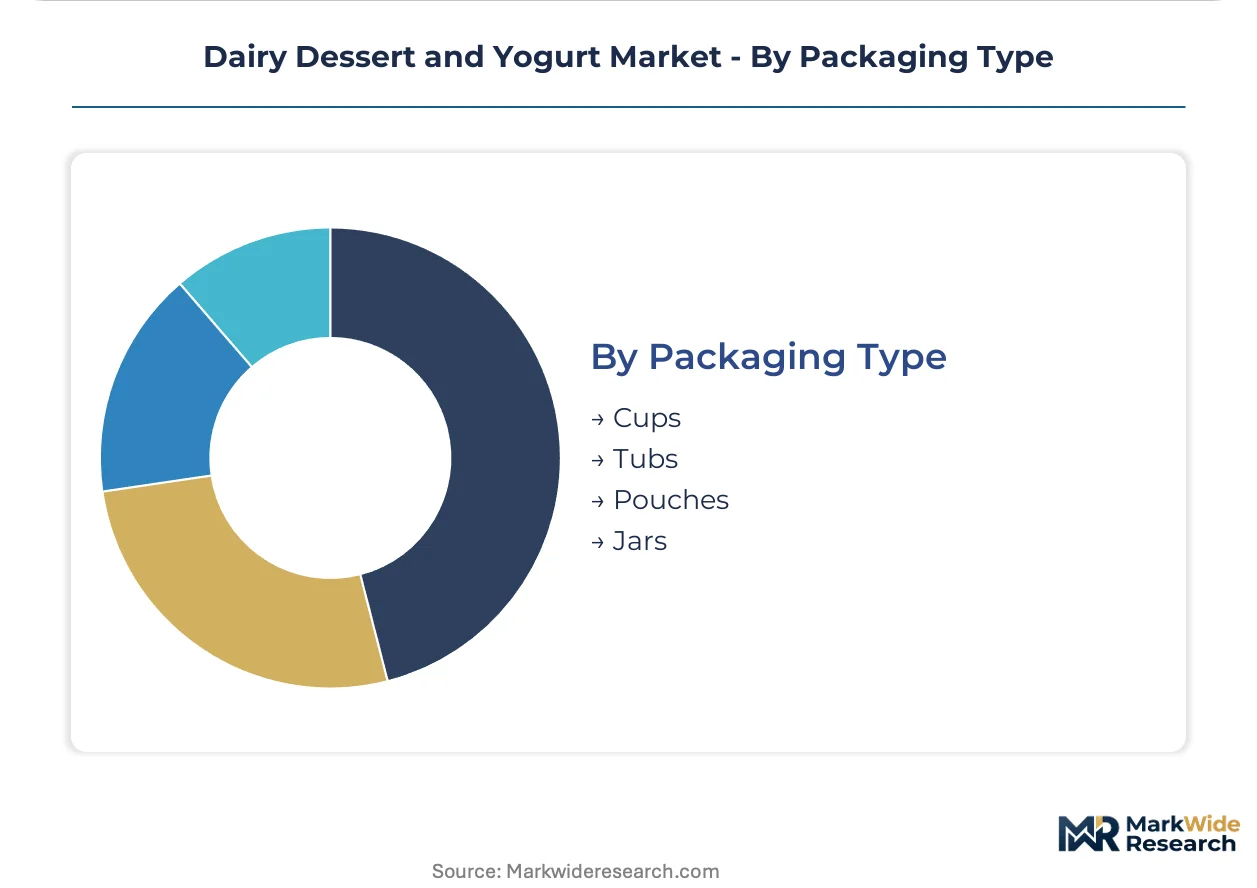
Packaging Type:
Packaging selection balances shelf-life extension, portion control, and consumption occasion mobility against material cost and recycling compliance.
- Pouches:Flexible multilayer laminates with spout fitments enabling one-handed consumption without refrigeration post-opening. Indonesian and Vietnamese urban convenience stores show under-15% penetration, creating whitespace for aseptic filling investments targeting fitness and child segments.
- Cups:Single-serve polystyrene or polypropylene containers with foil lidding, dominant in US and European supermarket yogurt sections.
- Tubs:Multi-serve polypropylene vessels for family and foodservice volumes, facing EU SUP directive pressures on virgin plastic content.
- Jars:Glass containers for premium dessert positioning and reuse appeal, concentrated in European organic channels and gift-oriented formats.
Installed base favors cups; pouch formats are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese urban households concentrate probiotic yogurt demand as domestic processors scale cold-chain infrastructure for tier-1 cities. Fitness-oriented consumers in Shanghai and Beijing drive premium skyr and Greek-style adoption. SAMR protein thresholds reclassify lower-protein products, reshaping formulation standards for export-oriented manufacturers.
United States
FDA qualified health claims for live-and-active cultures enable digestive health positioning in natural grocery channels. Direct-to-gym subscription models displace traditional retail among coastal metropolitan fitness enthusiasts. Chobani anchors strained yogurt texture differentiation through limited-ingredient positioning in the natural channel.
China
Yili Group leverages captive dairy farming partnerships to secure raw milk supply for probiotic and Greek-style production. SAMR enforces stricter protein content thresholds that reclassify products as "milk beverages" below specified levels. Domestic processors in Beijing and Shanghai metropolitan clusters scale cold-chain infrastructure for urban middle-class distribution.
Germany
EU REACH frameworks on food contact materials accelerate reformulation toward natural stabilizers and pectin-based gelling agents. Continuous-flow fermentation systems with real-time pH sensors automate culture propagation in Dutch and Danish cooperatives. Bavarian dairy operations face BRCGS and FSSC 22000 audit backlogs that delay EU retail multiple entry.
Indonesia
Pouch-format yogurt penetration remains below 15 percent in urban convenience stores, creating whitespace for aseptic filling investments. Fitness and child segments drive demand for flexible multilayer laminates with spout fitments. Jakarta and Surabaya metropolitan clusters concentrate first-mover expansion opportunities for portable breakfast substitutes.
France
Danone sustains European distribution density for high-protein skyr variants through fermented foods expertise. EU F-Gas Regulation phase-down schedules force cold-chain retrofitting with CO2 transcritical systems during 2025-2030. Paris and Lyon retail multiples prioritize clean-label ingredient compliance for premium dessert line placement.
Dairy Dessert and Yogurt Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with scale-driven multinationals commanding refrigerated retail distribution while regional cooperatives dominate fresh format proximity sourcing. The vendor base organizes around three strategic archetypes: diversified dairy conglomerates with captive farming assets, fermentation-technology specialists leveraging precision culture IP, and private-label contract manufacturers serving retail multiples. Consolidation pressure intensifies as protein threshold regulations and cold-chain capital requirements raise entry barriers. Competitive moves concentrate on M&A for probiotic strain portfolios and strategic partnerships for Southeast Asian cold-chain access.
Within the diversified conglomerate tier, Danone and Lactalis exemplify scale-driven players with integrated supply chain control, while Yili Group represents Chinese domestic champions leveraging backward integration into captive dairy farming. Chobani occupies a distinct position as a US-based specialist in strained yogurt textures and limited-ingredient clean-label positioning. These three anchors illustrate divergent geographic and segment strategies across the competitive landscape.
| Leading Market Players |
|---|
| Lactalis |
| Grupo Lala |
| Danone |
| Mengniu Dairy |
| Yili Group |
| Chobani |
| Muller |
| FAGE International |
| General Mills |
| Others |
Supply Flow & Price Mechanics
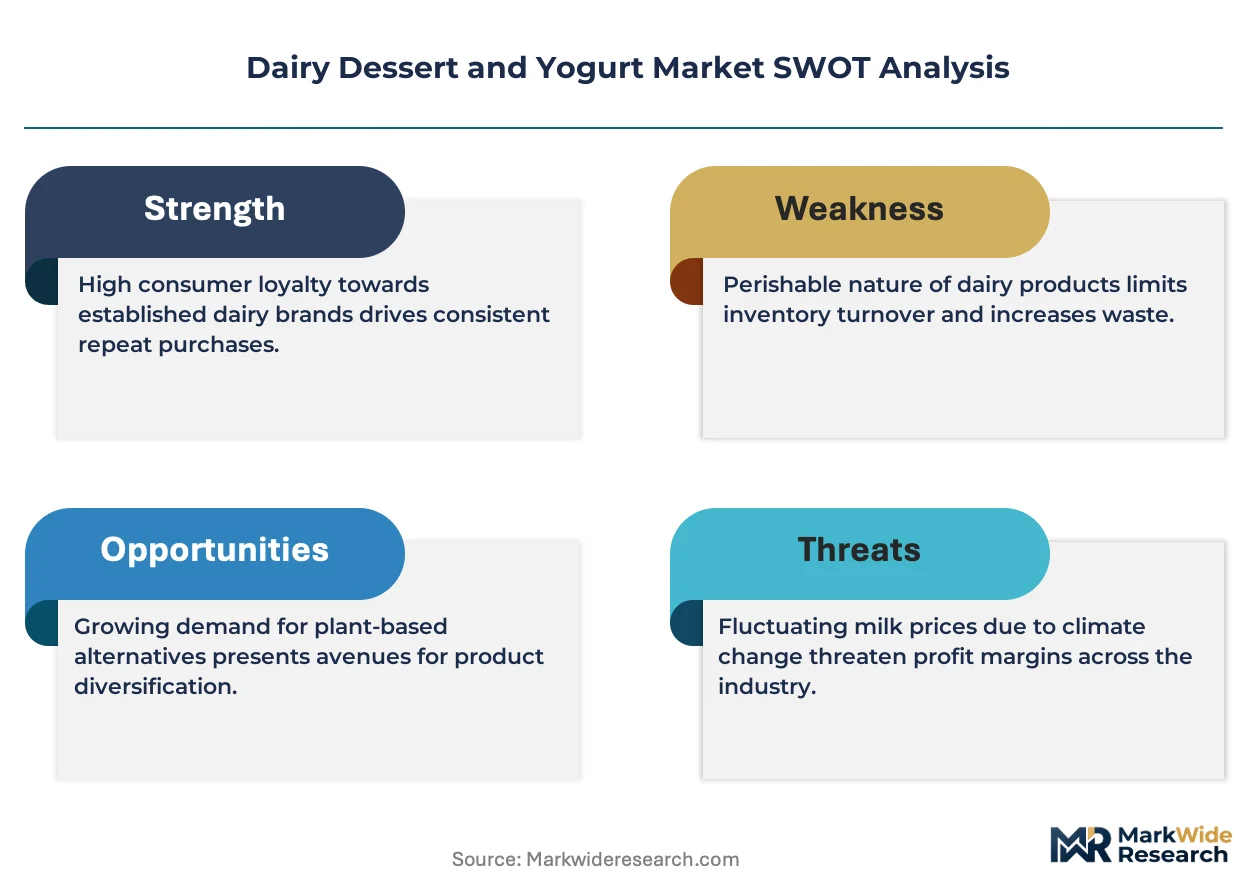
Premium-protein certification divergence separates Greek-style and skyr variants from standard fermented milk beverages, concentrating pricing power with processors meeting SAMR thresholds while compressing margins for reclassified products denied premium shelf placement. This bifurcation feeds directly into supply chain configurations: high-protein lines demand captive dairy farming partnerships and precision fermentation IP, while commodity-tier processors absorb skim milk powder auction volatility from Oceania cooperatives.
Pricing Analysis
Volume concentrates in standard cups and tubs where price sensitivity runs highest among family purchasers, while margin expansion sits with subscription-native entrants capturing fitness enthusiasts through direct-to-gym channels. Three-tier pricing structure across premium, standard, and economy levels reflects protein content thresholds, live culture certification, and cold-chain intensity. Pricing pressure stems from SAMR reclassification rules that strip lower-protein products of fermented milk designation. Health-conscious consumers in Chinese tier-1 cities and US coastal metros show least price sensitivity; family segments in Latin American supermarkets absorb maximum cost compression.
Supply Chain Analysis
Regional distribution centers in Shanghai, Jakarta, and Rotterdam anchor hub-and-spoke patterns for temperature-controlled last-mile delivery to convenience retail and fitness studio pickup points. Raw milk sourcing concentrates in China through Yili Group's captive farming, in the Netherlands through cooperative structures, and in New Zealand through Oceania auction systems. Probiotic strain IP concentration around Lactobacillus rhamnosus GG creates single-source vulnerability for mid-tier processors. Distribution runs through cold-chain operators retrofitting CO2 transcritical systems under EU F-Gas Regulation mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermented milk production capacity bottlenecks at precision fermentation scale prop pricing premiums, constraining supply expansion faster than fitness-oriented demand accumulates in Chinese and US metropolitan clusters.
For Market Incumbents: Deepen backward integration into probiotic strain portfolios through targeted acquisitions, insulating formulation flexibility from patent thickets. Defend margin position by accelerating cold-chain infrastructure investments in tier-1 Chinese cities ahead of domestic processor scaling. Channel control through direct-to-gym subscription platforms displaces traditional retail loyalty among fitness enthusiasts. For New Entrants and Emerging Players: Capture whitespace in Indonesian and Vietnamese pouch-format penetration below 15 percent through aseptic filling investments targeting child and fitness segments. Target Southeast Asian convenience retail with portable breakfast substitutes before incumbent dairy conglomerates establish distribution density. Go-to-market leverage rests on spout-fitment laminates enabling one-handed consumption without refrigeration post-opening. For Investors and Strategic Acquirers: Re-rating potential sits with precision fermentation technology specialists given microbial protein production reducing conventional milk solid dependence. Long-term viability over the analysis window favors processors with integrated strain IP and cold-chain assets. Acquisition target archetype: regional cooperatives with BRCGS certification backlog clearance and batch-level traceability systems. Signal to watch: EU F-Gas Regulation compliance cost spikes accelerating consolidation among frozen distribution-dependent dessert manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Microbial protein production reduces Oceania skim milk powder dependence while maintaining texture profiles. |
| Probiotic Strain Portfolio Acquisition | Patent access to Lactobacillus rhamnosus GG and clinically validated cultures unlocks premium formulation positioning. |
| Southeast Asian Cold-Chain Partnership | CO2 transcritical retrofit investments in Jakarta and Surabaya capture pouch-format whitespace before incumbent saturation. |
| Direct-to-Gym Subscription Platform | Locker-based refrigerated pickup at boutique fitness studios displaces convenience store impulse purchasing among coastal metros. |
| SAMR Protein Threshold Compliance | Reformulation to fermented milk designation secures premium shelf placement and pricing authority in Chinese retail. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with dairy processing executives, cold-chain logistics operators, retail category buyers, and fermentation technology R&D directors. FDA GRAS determinations, EFSA novel food assessments, SAMR protein threshold notifications, and EU REACH compliance databases provided formulation and labeling benchmarks. Bottom-up volume modeling across product types and consumer segments triangulated against top-down macroeconomic drivers.
Granularity-level modeling tracked frozen yogurt, parfait, and pudding formats separately by protein content tier, packaging type, and distribution channel intensity across the analysis window. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points including EU F-Gas phase-down schedules and SAMR reclassification enforcement. Forecast inputs incorporated cold-chain capital expenditure cycles, probiotic strain patent expiration timelines, and precision fermentation capacity buildout announcements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Oceania dairy commodity auction volatility, EU refrigeration retrofit compliance costs, and Chinese domestic processor scaling rates. Outputs reflect documented assumptions around protein threshold enforcement timing and cold-chain infrastructure investment pacing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Donkey Milk Market
Dairy Products
Fermented Dairy Ingredients Market
Dairy Products
Flavored Yogurt Market
Dairy Products
Malted Milk Powder Market
Dairy Products
Low Temperature Pasteurized Milk Market
Dairy Products
US Cheese Market
Dairy Products
Middle East and Africa Whey Protein Market
Dairy Products
United Kingdom Dairy Market
Dairy Products
Clotted Cream Market
Dairy Products
Citrus Yogurt Market
Dairy Products
Africa Dairy Protein Market
Dairy Products
Asia-Pacific Milk Protein Market
Dairy Products
Global Yogurt Powder Market
Dairy Products
Dairy Blends Market
Dairy Products
Solidified Yogurt Market
Dairy Products
Cream Powder Market