
 Frozen Pork Belly Market | 2026-2036
Frozen Pork Belly Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Pork Belly Market Analytics
Food service procurement is recalibrating toward pre-portioned frozen pork belly to reduce kitchen labor and standardize portion costs across chain outlets. JBS S.A. leverages its integrated Brazilian-to-Asian supply corridor to dominate bulk frozen exports. WH Group anchors its position through captive cold-chain assets connecting Smithfield Foods Inc. processing plants to Asian wholesale channels. Tyson Foods Inc. competes on brand recognition with food service distributors seeking traceable sourcing documentation.
Frozen pork belly comprises pork abdominal tissue, typically 12-18% intramuscular fat, that is blast-frozen at minus 18 degrees Celsius or below to arrest enzymatic activity and extend shelf life to 12-24 months for industrial food manufacturing and food service preparation. Raw pork belly leads volume due to its versatility across roasting, braising, and smoking applications, while smoked pork belly commands premium positioning in specialty store channels where flavor differentiation supports margin expansion. Vacuum packs capture the bulk of food service and processor demand because oxygen-exclusion packaging reduces freezer burn incidence and supports extended inventory cycles.
The USDA Food Safety and Inspection Service mandates pathogen reduction performance standards and continuous inspection presence at establishments producing frozen pork for interstate commerce, while HACCP protocols shape operational compliance costs. China's SAMR enforces GB standards for frozen meat labeling and cold chain integrity that condition import eligibility for foreign packers. Stakeholders must monitor evolving antibiotic residue thresholds and carbon-accounting requirements that are beginning to condition market access and procurement specifications across major importing jurisdictions.
Market Dynamics
Pre-portioned frozen pork belly formats are compressing traditional whole-carcass procurement as food service chains prioritize labor reduction and portion consistency. Cold chain infrastructure investments and HACCP-aligned processing standards are consolidating packer capacity toward integrated operators with captive freezing assets.
Growth Catalysts
- Hot pot chain expansion:China's barbecue and hot pot restaurant segments are driving bulk frozen belly imports through standardized menu specifications that favor frozen over fresh supply.
- Blast freezing at minus 18°C:Industrial freezing technology extends shelf life to 24 months, enabling intercontinental shipment economics that fresh pork cannot match.
- USDA FSIS pathogen standards:Continuous inspection mandates at interstate processing facilities are legitimizing frozen pork safety credentials for institutional buyers.
Market Restraints
- Feed grain price volatility:Corn and soybean meal input costs swing packer margins unpredictably, compressing willingness to hold frozen inventory.
- Single-origin supply concentration:Brazilian and Danish packers control disproportionate export-ready frozen belly volume, creating bottleneck risk.
- Antibiotic residue thresholds:China's SAMR GB standards and EU EFSA maximum residue limits are disqualifying conventional production systems from premium import channels.
Strategic Opportunities
- Vietnam food service penetration:Underdeveloped cold chain infrastructure in secondary Vietnamese cities offers first-mover positioning for pre-portioned frozen formats.
- Carbon-accounting procurement specifications:Emerging Scope 3 emissions disclosure requirements from EU CSRD-aligned buyers are creating premium segmentation for low-carbon frozen supply.
- Blockchain-IoT convergence:Immutable temperature logging combined with real-time cold chain monitoring is enabling insurance products and financing instruments for frozen inventory.
Industry Challenges
- HACCP plan validation timelines:New packer entrants face 12-18 month certification cycles before USDA FSIS grants interstate shipping eligibility.
- Legacy ERP integration:Frozen inventory lot tracking and shelf-life management systems require expensive retrofitting of processor accounting software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Pork Belly Market |
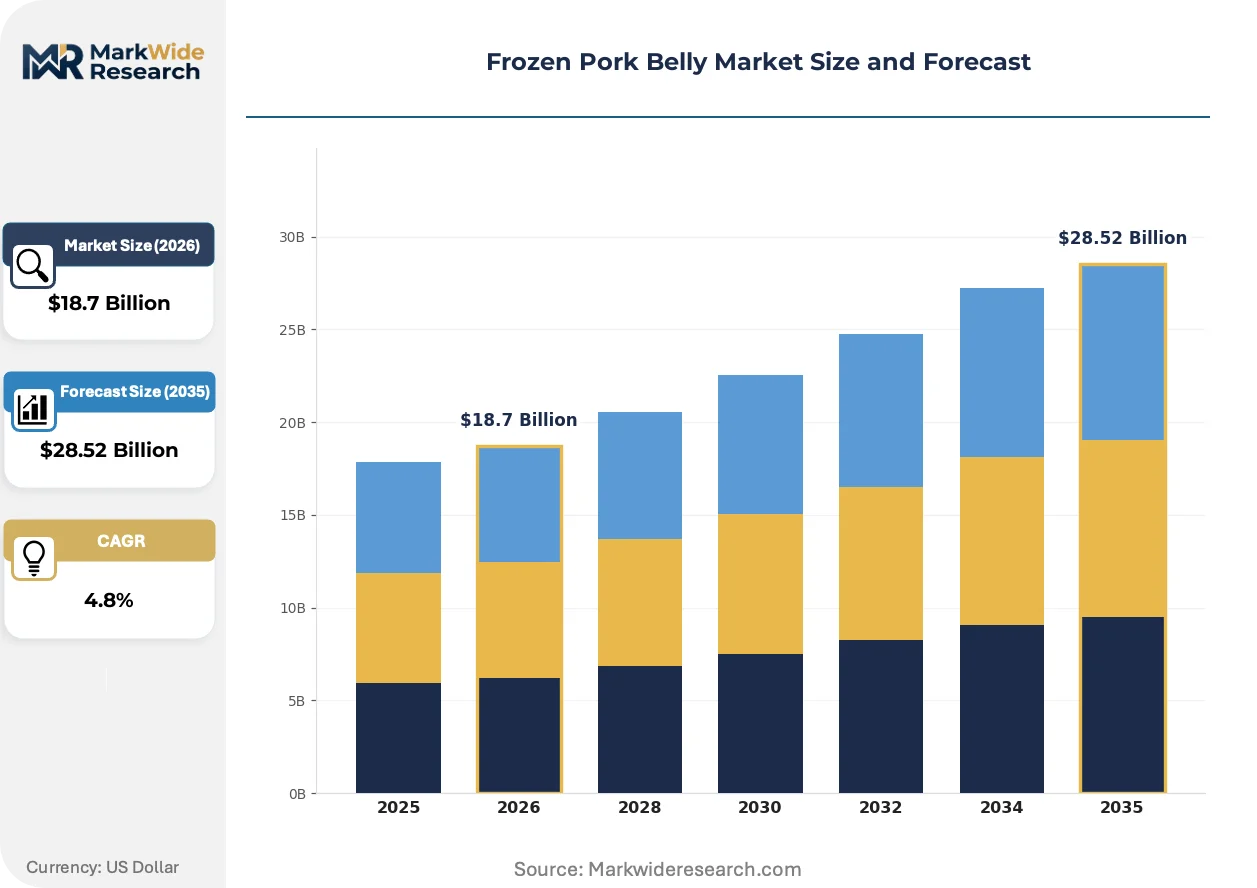
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Pork Belly, Cooked Pork Belly, Smoked Pork Belly, Seasoned Pork Belly Packaging Type: Vacuum Packs, Bulk Packs, Retail Packs, Cans Distribution Channel: Online Retailers, Supermarkets, Wholesale Distributors, Specialty Stores End User: Food Service, Retail Consumers, Exporters, Processors |
| Companies Covered | JBS S.A., WH Group, Tyson Foods Inc., Smithfield Foods Inc., BRF, Vall Companys Grupo, Cooperl Arc, CP Group, The Maschoffs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Pork Belly Market Evolving Landscape
Blast freezing and vacuum packaging technologies are reshaping how pork belly moves from slaughter to skillet. Processing innovation now centers on preserving texture and fat integrity through extended frozen storage cycles.
High-pressure processing (HPP) post-freeze is absorbing pathogen reduction burdens that thermal pasteurization once handled, enabling clean-label positioning without ingredient additives. Premium food service distributors in Japan and South Korea are adopting HPP-treated frozen belly for raw-consumption applications. The technology is absorbing liability risk from Listeria and Salmonella while compressing insurance premiums for high-volume handlers.
China's SAMR enforcement of GB 7718 labeling standards for frozen meat is mandating origin disclosure and cold chain integrity documentation at import clearance. Foreign packers must now embed QR-code traceability on retail-facing packaging to maintain wholesale channel access. Frozen belly shipments lacking compliant labeling face detention at Shanghai and Tianjin ports, redirecting volume toward compliant operators.
Direct procurement from packers is displacing traditional protein distributor intermediation among mid-sized restaurant chains with sufficient volume to justify container-load purchases. These buyers are establishing annual contracts with Brazilian and Danish freezing plants, bypassing domestic cold storage layers. The shift is most visible in Southeast Asian markets where port infrastructure improvements reduce landed cost variance against traditional channel supply.
Frozen Pork Belly Market Segmentation
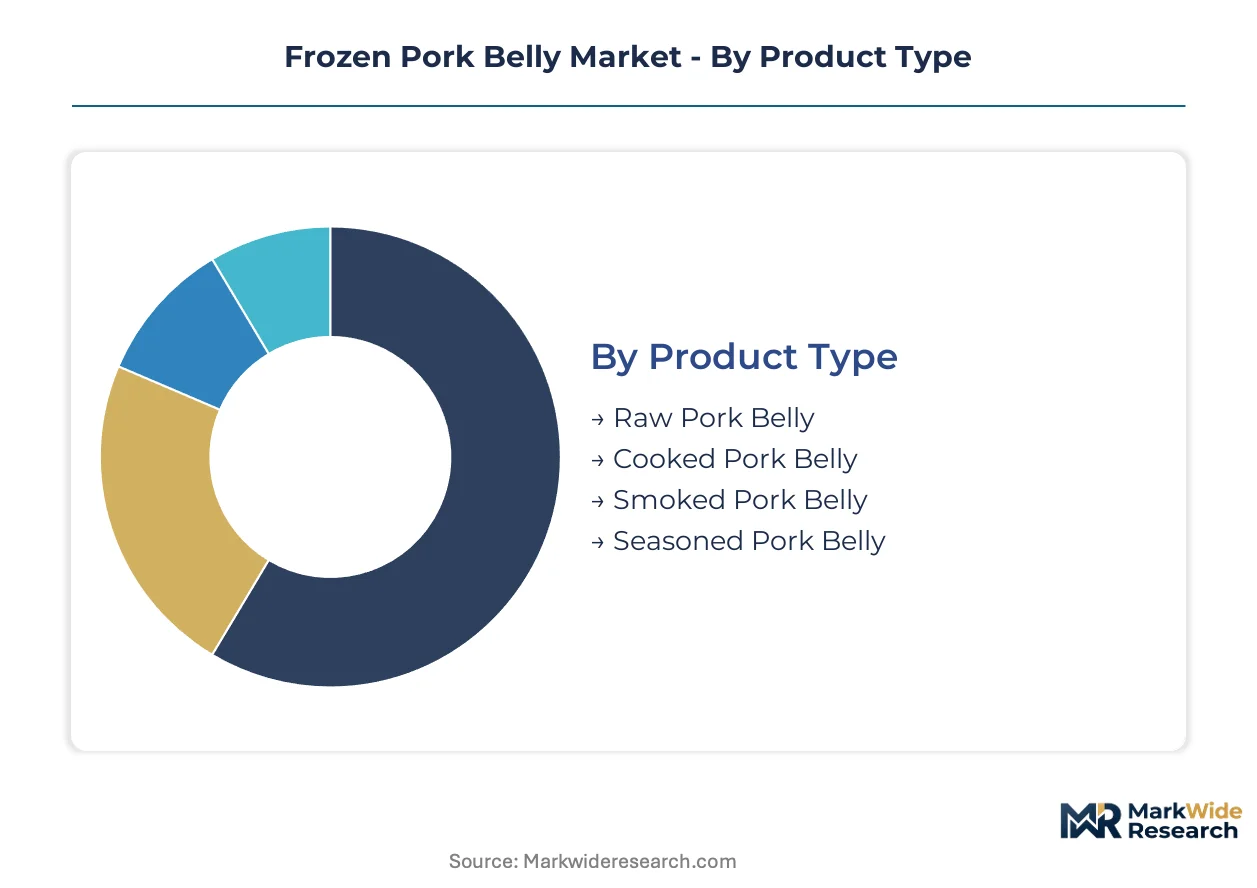
Segmentation in frozen pork belly reveals how processing depth, packaging technology, and channel economics partition value capture across the supply chain. Each dimension shapes margin structures and capital requirements differently.
Product Type:
Supply concentration tilts toward unprocessed formats where packer scale economies dominate, while value-added segments fragment across specialty processors.
- Raw Pork Belly:Unprocessed abdominal tissue with 12-18% intramuscular fat, blast-frozen at minus 18°C for 12-24 month shelf stability. China's hot pot chains and barbecue restaurants absorb container-load volumes, driven by labor cost pressures that favor kitchen-controlled preparation over pre-cooked alternatives.
- Smoked Pork Belly:Cold-smoked or liquid-smoked tissue with enhanced flavor profiles requiring dedicated smokehouse infrastructure or imported smoke concentrate supply. Japanese and South Korean premium food service distributors concentrate demand here, as HPP-treated variants enable raw-consumption positioning without thermal pasteurization.
- Cooked Pork Belly:Thermal-processed tissue for ready-meal integration, typically braised or roasted before freezing.
- Seasoned Pork Belly:Marinated or spice-rubbed tissue targeting ethnic cuisine preparation, common in Southeast Asian retail channels.
Raw pork belly absorbs the bulk of installed capacity; smoked pork belly is expanding most quickly.
Packaging Type:
Cost tier differentiation separates industrial-scale formats from retail-ready configurations, with oxygen-exclusion technology commanding premium positioning.
- Vacuum Packs:Oxygen-exclusion packaging that reduces freezer burn incidence and extends inventory cycles for food service and processor procurement. Wholesale distributors in China and Vietnam prioritize this format for container-load shipments where cold chain integrity varies.
- Bulk Packs:Large-format industrial packaging for processor input, typically 10-20kg blocks without individual portioning.
- Retail Packs:Consumer-facing portion sizes with GB 7718-compliant labeling for Chinese import clearance.
- Cans:Thermally processed shelf-stable formats for emergency stockpiling and military supply.
Vacuum packs dominate volume throughput; retail packs gain share fastest as direct procurement from packers displaces traditional distributor intermediation.
Distribution Channel:
Customer type fragmentation splits between institutional procurement with contract pricing and fragmented retail with spot-market dynamics.
- Wholesale Distributors:Traditional protein intermediaries with cold storage assets connecting packers to mid-sized restaurant chains. Southeast Asian markets show this channel eroding as port infrastructure improvements enable direct container-load purchasing.
- Supermarkets:Multi-format retail with private-label frozen meat programs requiring traceable sourcing documentation.
- Online Retailers:E-commerce platforms with last-mile cold chain requirements, expanding in Chinese tier-2 cities.
- Specialty Stores:Ethnic grocers and premium butchers with curated import selections and origin-specific merchandising.
Wholesale distributors retain the largest volume footprint; online retailers are climbing the fastest as urban delivery infrastructure matures.
End User:
Application maturity varies across preparation settings, with food service standardization driving format innovation and retail remaining comparatively fragmented.
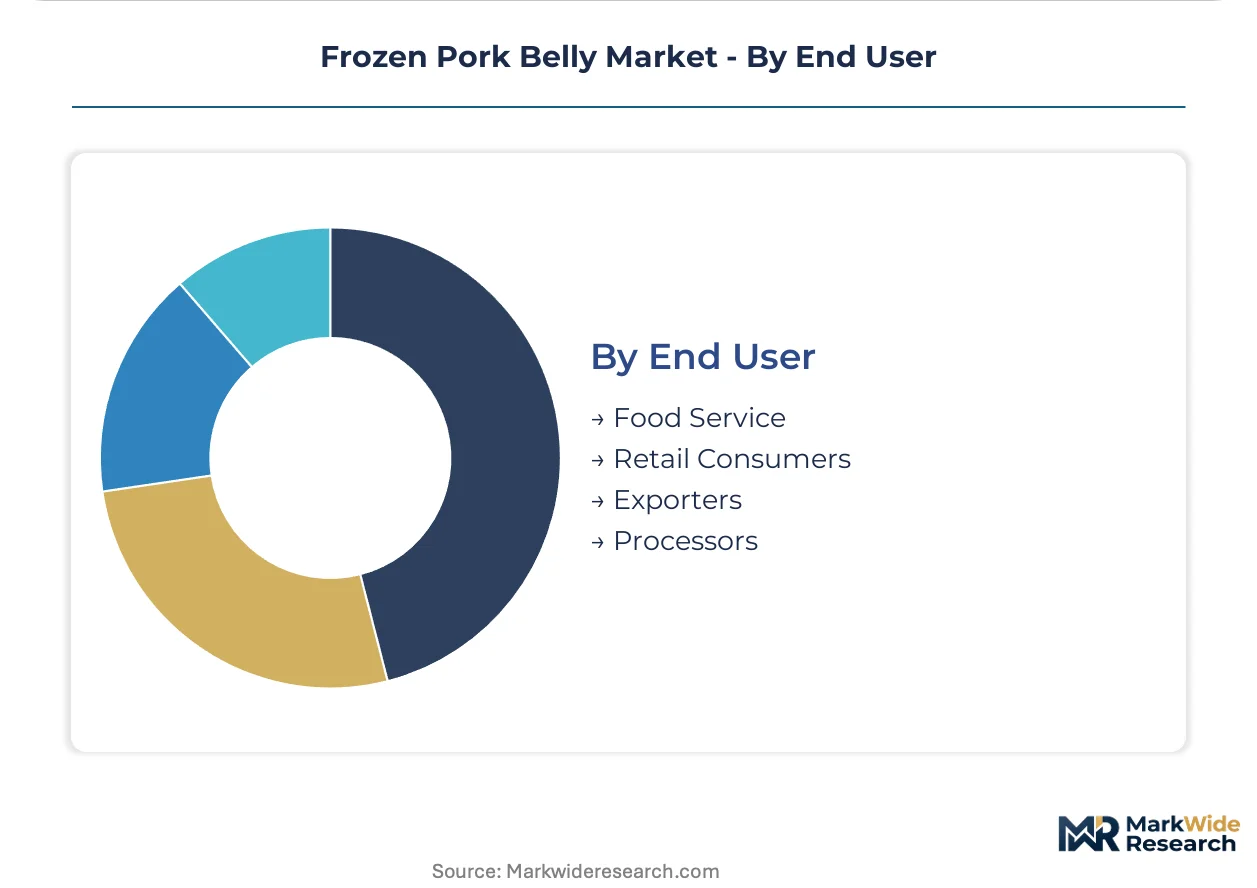
- Food Service:Restaurant chains, hot pot operators, and barbecue establishments requiring pre-portioned consistency and labor reduction. China's SAMR enforcement of cold chain documentation conditions import eligibility, favoring packers with captive freezing assets and HACCP-aligned processing.
- Processors:Industrial manufacturers of bacon, ready meals, and further-processed pork products with formulation flexibility requirements.
- Retail Consumers:Household purchasers with variable preparation skill and price sensitivity.
- Exporters:Trading companies managing cross-border logistics and regulatory compliance for third-party markets.
Food service captures the dominant demand share; processors show the steepest expansion trajectory as pre-portioned formats compress whole-carcass procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones along China's coastal provinces and Brazil's export processing corridors concentrate frozen pork belly capacity. These designated areas offer tariff exemptions and streamlined customs that lower landed costs for intercontinental shipment. Cold chain infrastructure investments cluster where these fiscal incentives intersect with port modernization programs.
China
Hot pot chains and barbecue restaurants in Shanghai, Beijing, and Chengdu absorb container-load volumes of frozen pork belly for standardized menu preparation. SAMR enforces GB 7718 labeling standards and cold chain documentation that condition import clearance at Shanghai and Tianjin ports. Yangtze River Delta cold storage clusters near Nantong and Taicang handle the bulk of Brazilian and Danish reefer cargo.
Brazil
Integrated packers in Mato Grosso and Santa Catarina supply the majority of export-ready frozen belly volume bound for Asian markets. The national agricultural regulator MAPA aligns sanitary protocols with USDA FSIS and China's SAMR to maintain eligibility in premium import channels. São Paulo state hosts the largest concentration of blast-freezing facilities serving the Santos port export corridor.
United States
Smithfield Foods Inc. processing plants in Virginia and North Carolina anchor domestic frozen belly production for food service distributor networks. USDA FSIS mandates continuous inspection presence and HACCP validation at interstate facilities, creating 12-18 month certification timelines for new entrants. Midwest cold storage hubs in Iowa and Illinois connect packer output to Pacific Northwest reefer terminals serving Asian export routes.
Vietnam
Ho Chi Minh City and Hanoi restaurant chains are adopting pre-portioned frozen formats as labor costs rise in urban food service operations. Underdeveloped cold chain infrastructure in secondary cities like Da Nang and Hai Phong creates first-mover positioning for direct packer procurement models. Port improvements at Cai Mep are reducing landed cost variance against traditional wholesale distributor channels.
Japan
Premium food service distributors in Tokyo and Osaka source HPP-treated frozen belly for raw-consumption applications in high-end dining. MFDS-aligned import standards and traceability requirements favor packers with captive freezing assets and documented cold chain integrity. Kyushu regional processors specialize in smoked pork belly variants for specialty retail channels.
Frozen Pork Belly Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated packers controlling bulk frozen exports and regional processors capturing value-added niches. The vendor base concentrates around operators with captive cold-chain assets and multi-jurisdictional HACCP certification. Three archetypes dominate: Brazilian-Danish scale exporters, Asian conglomerates with backward integration into processing, and North American brand-recognized distributors. Competitive moves center on port-adjacent freezing capacity expansion and direct annual contracting with restaurant chains.
Within the integrated exporter tier, JBS S.A. and BRF represent Brazilian scale operators with South American-to-Asian supply corridor dominance. WH Group anchors the Asian conglomerate archetype through captive cold-chain assets connecting processing plants to wholesale channels. Tyson Foods Inc. occupies the North American branded distributor position, competing on traceable sourcing documentation for institutional buyers seeking USDA FSIS-aligned safety credentials.
| Leading Market Players |
|---|
| JBS S.A. |
| WH Group |
| Tyson Foods Inc. |
| Smithfield Foods Inc. |
| BRF |
| Vall Companys Grupo |
| Cooperl Arc |
| CP Group |
| The Maschoffs |
| Others |
Value Network & Pricing Analysis
Family-owned Brazilian packers with generational control over Mato Grosso and Santa Catarina freezing plants anchor supply discipline through long-term contract preferences, insulating spot-market volatility while compressing margins for trader intermediaries lacking captive cold-chain assets.
Pricing Analysis
Short lead-time premiums dominate contract negotiations, with food service chains paying elevated rates for 30-day container availability versus 90-day forward commitments that secure standard-tier positioning. Three-tier pricing structure across premium HPP-treated, standard vacuum-packed, and economy bulk formats reflects cold chain integrity documentation and origin traceability under China's SAMR GB standards. Pricing pressure stems from feed grain cost volatility, with corn and soybean meal swings compressing packer willingness to hold frozen inventory. Mid-sized restaurant chains exhibit highest price sensitivity as they bypass wholesale distributors for direct annual contracting, while premium Japanese and South Korean food service distributors show least sensitivity due to raw-consumption liability requirements.
Supply Chain Analysis
Dual-sourcing mandates from institutional buyers require qualification of both Brazilian and Danish packers to mitigate single-origin concentration risk in export-ready frozen belly volume. Supply draws from integrated operators in Brazil's Mato Grosso-Santa Catarina corridor, Danish cooperative processing clusters, and select US Midwest facilities with Pacific Northwest reefer terminal access. Raw material dependencies center on live hog supply contracts, blast-freezing equipment with minus 18°C capability, and vacuum packaging film with oxygen-exclusion properties. Tariff exposure at Chinese port clearance creates structural vulnerability, as SAMR enforcement of GB 7718 labeling standards redirects non-compliant shipments toward detention. Distribution runs through annual direct contracts between packers and container-load buyers, displacing traditional cold storage intermediation in Southeast Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blast freezing at minus 18°C is displacing slower conventional freezing methods, compressing shelf-life variance and enabling intercontinental shipment economics that reshape procurement patterns across food service chains.
For Market Incumbents: Anticipate margin compression from direct packer-to-restaurant contracting by deepening backward integration into captive freezing assets at port-adjacent locations in Santos and Nantong. Secure HACCP validation timelines of 12-18 months ahead of competitor entry attempts. Prioritize blockchain-IoT temperature logging investments to meet emerging Scope 3 emissions disclosure requirements from EU CSRD-aligned buyers. For New Entrants and Emerging Players: Capture first-mover positioning in Vietnam's secondary cities where underdeveloped cold chain infrastructure delays incumbent penetration. Target Da Nang and Hai Phong food service clusters with pre-portioned frozen formats that reduce kitchen labor costs. Establish direct annual contracting relationships with Brazilian freezing plants to bypass legacy wholesale distributor markups. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap Brazilian packers with MAPA-aligned sanitary protocols and existing Asian export eligibility during feed cost spike periods. Long-term viability hinges on carbon-accounting procurement specification readiness across the analysis window. Watch antibiotic residue threshold tightening by China's SAMR and EU EFSA as inflection indicators for premium channel access contraction.| Strategic Initiative | Industry Significance |
|---|---|
| Port-Adjacent Freezing Capacity Expansion | Santos and Nantong clusters reduce landed cost variance for Brazilian-to-Asian shipments. |
| HACCP Certification Investment | USDA FSIS validation timelines of 12-18 months create defensive moats against new entrants. |
| Blockchain-IoT Cold Chain Integration | Immutable temperature logging enables insurance products for frozen inventory financing. |
| Direct Annual Contracting with Restaurant Chains | Mid-sized Southeast Asian buyers bypass wholesale distributors for container-load procurement. |
| Carbon-Accounting Documentation Program | Scope 3 emissions disclosure meets EU CSRD-aligned buyer procurement specifications. |
Research Methodology
Multi-period observation of container-load shipment volumes, cold storage utilization rates, and SAMR import clearance data anchored the trend analysis, supplemented by interviews with plant managers at Brazilian freezing facilities, procurement leads at Chinese hot pot chains, regulatory affairs specialists navigating GB standard compliance, and food service distributors in Tokyo and Osaka. Secondary validation drew from USDA FSIS inspection records, China customs trade statistics, MAPA sanitary protocol filings, and SEC 10-K disclosures from publicly traded protein processors. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Input-output matrices mapped live hog supply flows through blast-freezing capacity to end-use demand across food service, processor, and retail channels over the projection horizon. Segmentation dimensions included product type depth, packaging technology tier, distribution channel structure, and end-user application maturity. CAGRs were derived from fitted growth curves applied to base-year volume estimates, with cross-validation against trade flow trajectories and cold chain infrastructure investment pipelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to feed grain price volatility, antibiotic residue threshold adjustments, and carbon-accounting regulatory expansion. Deviation in China's SAMR enforcement intensity at Shanghai and Tianjin ports would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Indonesia Frozen Food Market
Processed and Frozen Foods
Dehydrated Potato Products Market
Processed and Frozen Foods
Frozen Cheese Market
Processed and Frozen Foods
Cambodia Frozen Food Market
Processed and Frozen Foods
Europe Freeze-Dried Products Market
Processed and Frozen Foods
Frozen Soup Market
Processed and Frozen Foods
Popsicle Market
Processed and Frozen Foods
Freeze Dried Tropical Fruits Market
Processed and Frozen Foods
Frozen Sardine Market
Processed and Frozen Foods
US Frozen Dessert Market
Processed and Frozen Foods
Vegan Frozen Food Market
Processed and Frozen Foods
Refrigerated & Frozen Soup Market
Processed and Frozen Foods
Vegan Frozen Pizza Market
Processed and Frozen Foods
Middle East and Africa Frozen Food Market
Processed and Frozen Foods
Global Chilled and Deli Foods Market
Processed and Frozen Foods
Freeze Dried Melt Market