
 Pork Belly Meat Market | 2026-2036
Pork Belly Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Pork Belly Meat Market Insights
Commodity trading margins in pork belly futures and spot contracts is fragmenting across regional exchanges and direct processor-retailer agreements. WH Group Ltd. leverages its vertically integrated Chinese operations to control slaughter-to-retail flows. Tyson Foods Inc. competes through large-scale fresh processing capacity in the US Midwest. Danish Crown A/S anchors European supply with cooperative-structured farmer networks and export-grade curing facilities.
Pork belly denotes the boneless, skin-on ventral section of a hog carcass, typically comprising 15-20% intramuscular fat by weight and processed through dry-curing, hot-smoking, or blast-freezing for shelf-life extension. Fresh belly cuts serve restaurant kitchens requiring customizable portion control, while cured and smoked segments command premium positioning in retail and foodservice channels. The distribution channel dimension shows supermarkets and wholesale markets still occupying volume leadership, though online retail is extending fastest as direct-to-consumer cold-chain logistics mature.
The USDA enforces pathogen reduction and hazard analysis standards for domestic pork processing, while the EU's EFSA and national regulators such as Germany's BfR mandate trichinae testing and nitrite limits in cured products. China's SAMR and GB standards govern import inspection and domestic cold-chain hygiene, shaping market access for foreign suppliers. Stakeholders must monitor divergence between antibiotic-use restrictions in European production systems and conventional practices in major exporting countries.
Market Dynamics
Food processors are consolidating procurement around pre-cured and portion-controlled belly cuts to reduce kitchen labor costs and standardize quick-service restaurant output, compressing traditional fresh-cut supply relationships into direct processor-foodservice contracts.
Growth Catalysts
- EU Green Deal cold-chain mandates:The F-Gas Regulation is accelerating retrofit investment in low-emission refrigeration for meat transport, expanding demand for blast-frozen belly cuts that tolerate extended supply chains.
- Quick-service restaurant portion standardization:Chains in China are locking in multi-year supply contracts for pre-sliced belly with specified fat-to-lean ratios, pulling volume through contracted processing rather than spot markets.
- Smoking and curing automation:Continuous thermal processing systems are reducing batch-to-batch variation in bacon and pancetta output, enabling private-label retail programs that previously required artisan scale.
Market Restraints
- Feed grain price volatility:Corn and soybean meal costs constitute the dominant variable in hog production economics, transmitting directly to belly cut pricing with a 6-8 month lag through live animal markets.
- Slaughter capacity concentration in China:WH Group and three domestic processors control over half of national processing volume, creating procurement bottlenecks for foreign suppliers seeking market access.
- Antibiotic-use divergence:The EU's ban on growth-promoting antibiotics in livestock creates non-tariff barriers for conventional US and Brazilian pork entering European cured-meat channels.
Strategic Opportunities
- Direct-to-consumer cold-chain maturation:Refrigerated last-mile logistics in urban China now support subscription-based premium belly box deliveries, bypassing traditional wholesale layers.
- Carbon-labeling alignment:Processors adopting lifecycle assessment protocols can access EU retail contracts where the EU Green Deal's farm-to-fork transparency requirements are becoming procurement filters.
- Plant-based hybrid formulations:Blended meat-vegetable belly analogs are penetrating flexitarian segments in Germany and the Netherlands where regulators permit blended product labeling under EFSA guidance.
Industry Challenges
- Trichinae testing compliance timelines:EU and US divergence in serological versus microscopic testing protocols creates dual-certification burdens for exporters serving both markets.
- Cold-chain capex intensity:Compliance with tightening F-Gas and EPA refrigerant phase-down rules requires fleet and facility replacement cycles that compress processor margins before volume efficiencies materialize.
- Artisan curing skill scarcity:Traditional dry-curing expertise for premium pancetta and guanciale production is not reproducing at scale, constraining expansion in protected-origin segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pork Belly Meat Market |
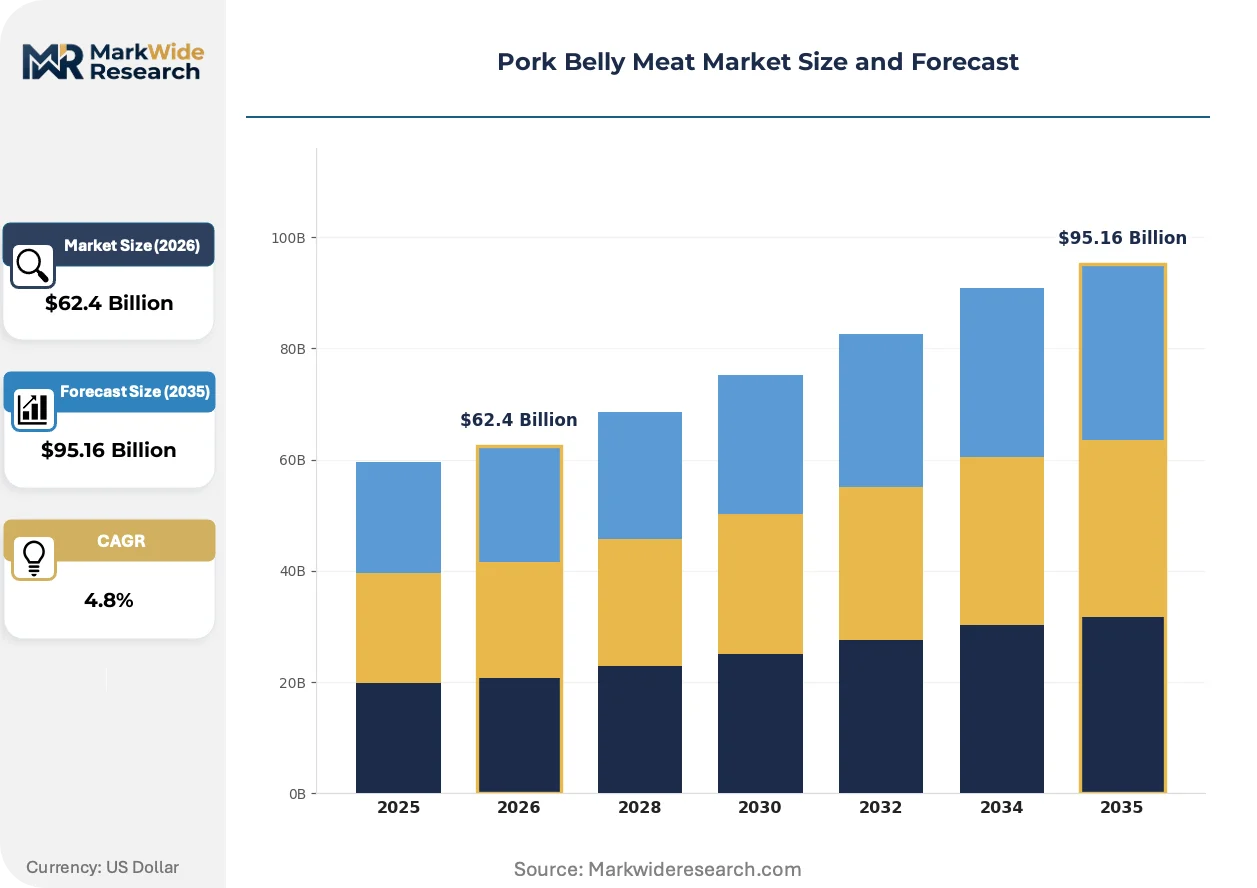
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $95.16 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh, Cured, Smoked, Frozen Source: Heritage Breed, Conventional, Organic, Free Range Distribution Channel: Online Retail, Supermarkets, Wholesale Markets, Local Butchers End User: Restaurants, Catering Services, Household Consumers, Food Processors |
| Companies Covered | SYSCO Corp., WH Group Ltd., Tyson Foods Inc., Cargill Incorporated, Danish Crown A/S, JBS USA Holdings Inc., Hormel Foods Corp., Tönnies Holding GmbH & Co. KG, Smithfield Foods Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pork Belly Meat Market Trends and Innovations
Processing technology and regulatory pressure are converging to reshape how belly cuts move from slaughter to final preparation, with automation and emissions compliance becoming simultaneous constraints and differentiators.
High-pressure processing systems for fresh belly cuts are hybridizing with modified-atmosphere packaging to extend retail case-life without freezing damage. Supermarket chains in Japan and South Korea are adopting these formats for premium fresh bacon displays. The technology is compressing traditional fresh-distribution windows and enabling longer sourcing radii from regional processors.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is forcing cold-chain operators to retrofit transport and storage infrastructure. Meat logistics providers are responding by consolidating loads and extending frozen versus chilled product ratios. German and Dutch processors are most advanced in fleet conversion, creating first-mover advantage in carbon-accounted retail contracts.
Foodservice buyers are unbundling specification-setting from physical procurement, retaining third-party auditors to enforce fat-content and slice-thickness standards while sourcing through multiple processors. This pattern is most visible in China's quick-service restaurant expansion, where Yum China and domestic chains maintain approved supplier lists with interchangeable volume allocation. The shift is compressing processor margins while raising compliance infrastructure requirements.
Pork Belly Meat Market Segmentation
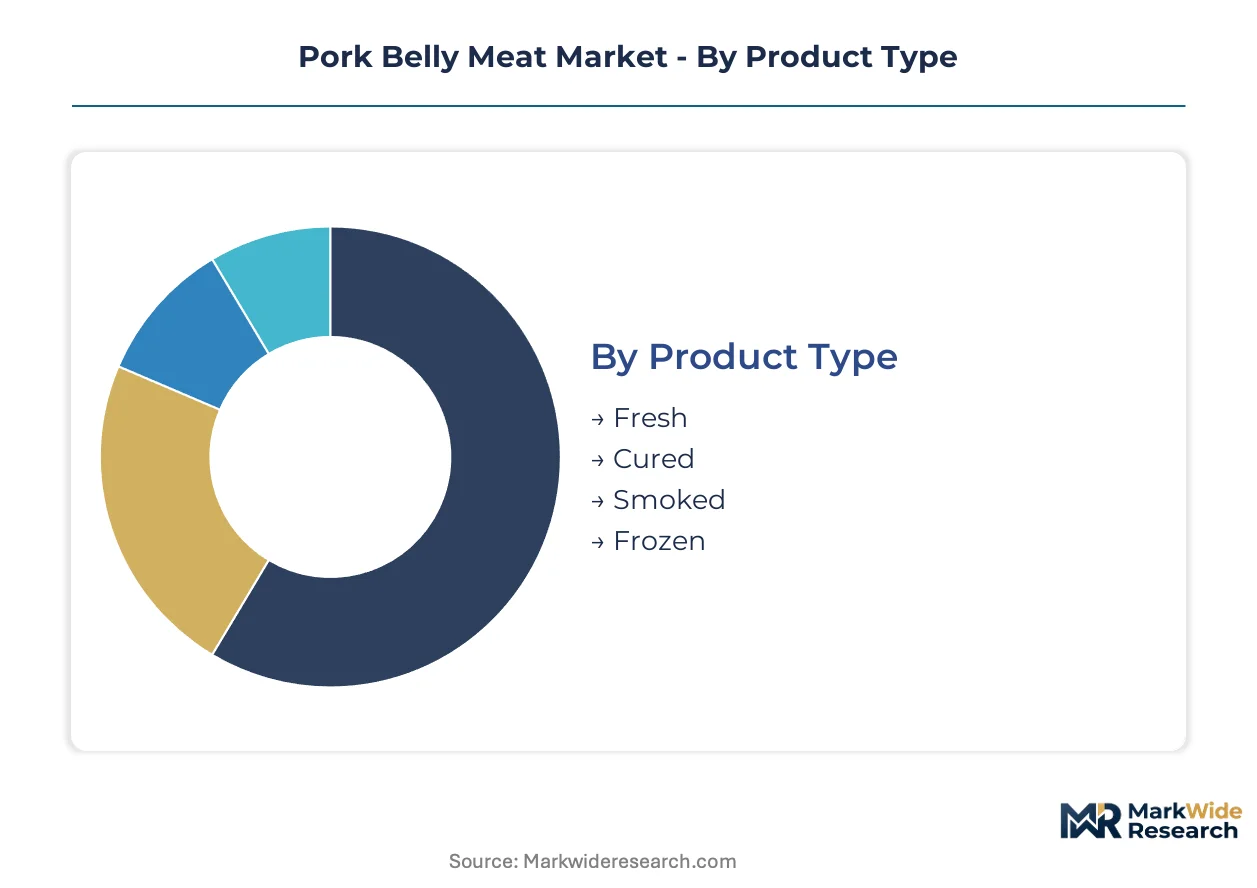
Pork belly segmentation reflects divergent velocity profiles across preservation states and sourcing tiers. Cycle times compress from days for fresh cuts to months for dry-cured inventories, reshaping working capital requirements and margin capture across each stratum.
Product Type:
Fresh belly turns over in 3-7 days through foodservice channels, while cured and smoked inventories age 30-180 days before revenue recognition.
- Fresh:Unprocessed ventral cuts with 15-20% intramuscular fat sustain restaurant kitchens requiring customizable portioning. Demand clusters in China's quick-service chains where Yum China enforces fat-to-lean ratio specifications through approved supplier lists.
- Cured:Salt and nitrite-treated bellies aged under controlled humidity command retail premiums through extended shelf stability. EU Green Deal cold-chain mandates are accelerating blast-frozen cured shipments that tolerate refrigerant retrofit delays in transport fleets.
- Smoked:Thermal-processed cuts with 4-6 hour smoke cycles serve breakfast protein and charcuterie applications. Continuous thermal systems at Danish Crown facilities reduce batch variation for private-label retail programs.
- Frozen:Blast-frozen at -18°C for 12-24 month storage windows, these cuts absorb F-Gas Regulation compliance costs through consolidated long-haul logistics. German processors lead fleet conversion to CO2 cascade refrigeration.
Fresh anchors the volume base while cured gains share at the steepest rate as food processors consolidate procurement around pre-cured specifications.
Source:
Cost tier stratification separates heritage premiums from conventional commodity flows, with organic and free-range occupying mid-tier positioning.
- Heritage Breed:Berkshire, Duroc, and Iberian genetics yield denser marbling and slower growth cycles. Spain's dehesa system supplies protected-origin jamón adjacent markets through cooperative farmer networks.
- Conventional:Commercial hybrid genetics dominate slaughter volumes at WH Group and Tyson Midwest facilities. Antibiotic-use divergence creates non-tariff barriers for US conventional pork entering EU cured-meat channels.
- Organic:Certified feed and housing protocols add 30-40% production cost premiums. German and Dutch retail chains source organic bellies for carbon-accounted contract compliance under EU Green Deal farm-to-fork transparency requirements.
- Free Range:Outdoor access mandates satisfy welfare-scoring protocols in UK and Scandinavian markets. Premium positioning depends on third-party audit verification rather than regulatory mandate alone.
Conventional supplies the cost floor for foodservice procurement while heritage expands most quickly in direct-to-consumer subscription channels.
Distribution Channel:
Volume concentration versus margin extraction splits across channel types, with wholesale markets compressing per-unit economics through scale aggregation.
- Online Retail:Refrigerated last-mile logistics in urban China now support subscription-based premium belly box deliveries. JD.com and Tmall cold-chain partnerships bypass traditional wholesale layers for household consumers.
- Supermarkets:Modified-atmosphere packaging extends retail case-life for fresh bacon displays in Japanese and South Korean chains. High-pressure processing adoption enables longer sourcing radii from regional processors.
- Wholesale Markets:Spot-price liquidity for fresh cuts serves independent restaurants and catering operators. Price discovery fragments across regional exchanges as direct processor-retailer agreements displace auction volumes.
- Local Butchers:Artisan curing expertise for pancetta and guanciale production constrains expansion in protected-origin segments. Skill scarcity limits output scaling despite retail premium capture.
Wholesale markets retain volume leadership while online retail climbs the fastest as direct-to-consumer cold-chain logistics mature.
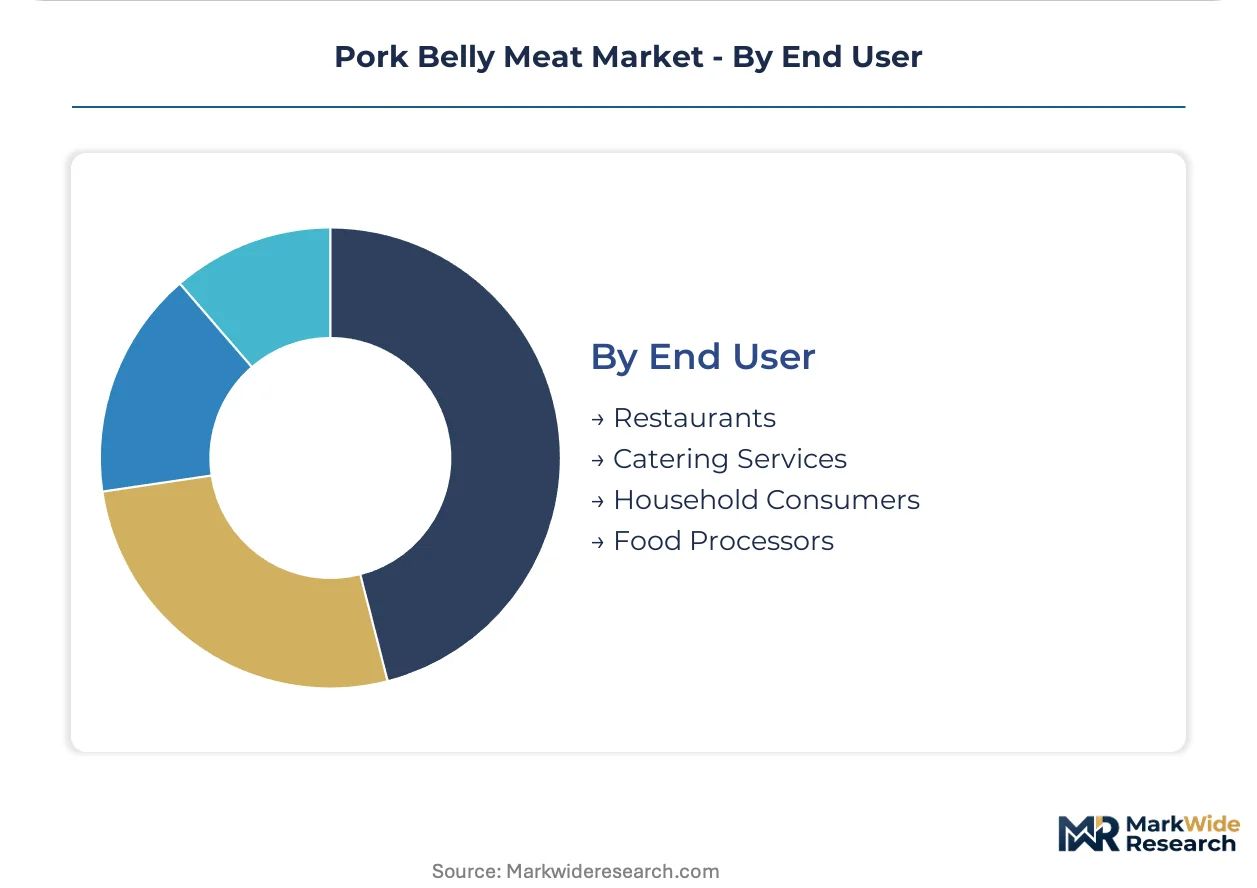
End User:
Specification control versus procurement execution separates food processors from foodservice operators, with household consumers occupying the most price-sensitive tier.
- Restaurants:Independent kitchens demand fresh cuts with customizable portion control, while chain operators lock in multi-year contracts for pre-sliced belly with standardized fat ratios.
- Catering Services:Volume volatility and menu flexibility requirements favor frozen inventory positions with 30-60 day forward coverage. Margin pressure from labor cost inflation drives pre-cured procurement consolidation.
- Household Consumers:Retail bacon and pancetta purchases show highest price elasticity among end-user tiers. E-commerce penetration concentrates in urban China and German metropolitan corridors.
- Food Processors:Ready-meal manufacturers specify blast-frozen belly cuts that tolerate extended supply chains during F-Gas refrigeration retrofits. Procurement is shifting from spot markets to direct processor contracts with volume commitments.
Restaurants anchor demand volume while food processors gain share at the steepest rate through pre-cured supply contract consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes pork belly predominantly through quick-service restaurant channels with pre-sliced specifications, while European demand centers on artisan-cured retail formats and US foodservice buyers prioritize customizable fresh cuts for independent kitchens.
China
Quick-service chains lock in multi-year contracts for pre-sliced belly with specified fat-to-lean ratios, pulling volume through contracted processing. SAMR and GB standards govern import inspection and domestic cold-chain hygiene, shaping market access for foreign suppliers. Henan and Sichuan provinces concentrate slaughter capacity where WH Group and domestic processors dominate national processing volume.
United States
Foodservice distributors and independent restaurants drive demand for fresh cuts requiring customizable portion control. USDA enforces pathogen reduction and hazard analysis standards for domestic pork processing. Iowa and Illinois anchor Midwest processing clusters where Tyson Foods operates large-scale fresh processing facilities serving regional distribution networks.
Germany
Retail chains source organic bellies for carbon-accounted contract compliance under EU Green Deal farm-to-fork transparency requirements. The F-Gas Regulation mandates trichinae testing and nitrite limits in cured products through BfR oversight. North Rhine-Westphalia and Lower Saxony host cooperative-structured farmer networks supplying Danish Crown export-grade curing facilities.
Spain
Protected-origin jamón adjacent markets sustain heritage breed premiums through cooperative farmer networks in the dehesa system. EFSA mandates align with national regulators on cured product standards. Extremadura and Andalusia concentrate Iberian genetics production where slower growth cycles yield denser marbling for premium positioning.
Japan
Supermarket chains adopt high-pressure processing with modified-atmosphere packaging for premium fresh bacon displays. METI and national food safety frameworks govern import protocols and domestic handling standards. Kanto and Kansai regions concentrate cold-chain logistics investment enabling extended sourcing radii from regional processors.
Pork Belly Meat Market Competitive Landscape
Capability concentration sits with vertically integrated processors controlling slaughter-to-retail flows; scale advantage sits with diversified protein conglomerates operating across multiple species and geographies. The market structures around three tiers: multinational meatpackers with integrated cold-chain assets, cooperative-structured European processors with farmer-owned governance, and regional specialists in heritage curing. Dominant competitive moves include backward integration into hog production and strategic partnerships with quick-service restaurant chains for specification-locked supply contracts.
Among US-based protein conglomerates, Tyson Foods Inc. and Hormel Foods Corp. exemplify scale-driven positioning across fresh and processed pork channels. WH Group Ltd. anchors the Asia-centric integrated tier through its Chinese operations controlling slaughter-to-retail flows. Danish Crown A/S represents the cooperative archetype with farmer-owned governance structures and export-grade curing facilities serving European retail contracts.
| Leading Market Players |
|---|
| SYSCO Corp. |
| WH Group Ltd. |
| Tyson Foods Inc. |
| Cargill Incorporated |
| Danish Crown A/S |
| JBS USA Holdings Inc. |
| Hormel Foods Corp. |
| Tönnies Holding GmbH & Co. KG |
| Smithfield Foods Inc. |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Rotterdam maritime corridor absorbs F-Gas Regulation compliance costs through consolidated frozen belly shipments, transmitting cold-chain capex intensity into three-tier pricing structure across premium, standard, and economy levels while WH Group's slaughter concentration in Henan province shapes processor bargaining power against foodservice buyers.
Pricing Analysis
Long-term offtake contracts dominate procurement between quick-service chains and integrated processors, with spot markets fragmenting across regional wholesale exchanges. Price differentiation hinges on fat-to-lean ratio certification and volume scale commitments. Pricing pressure stems from feed grain volatility transmitting through 6-8 month lags. Household consumers show highest price sensitivity; food processors locked in multi-year agreements demonstrate lowest elasticity.
Supply Chain Analysis
Feedstock corn and soybean meal markets in the United States, Brazil, and Argentina anchor hog production economics, with Chinese processors drawing from domestic grain reserves and imported protein meal. Live animal flows depend on slaughter capacity concentration in Henan and Sichuan provinces. Single-source vulnerability sits with WH Group's national processing dominance. Distribution runs through processor-direct foodservice contracts displacing traditional wholesale auction volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant-based hybrid analogs present a substitution threat that pork belly incumbents must navigate through specification-locked supply contracts and carbon-accounted positioning.
For Market Incumbents: Entrench contract structures by locking quick-service chains into multi-year pre-sliced belly agreements with interchangeability clauses. Capture carbon-labeling premiums through EU Green Deal farm-to-fork compliance investment. Defend against blended meat-vegetable entrants by emphasizing intramuscular fat ratios that analogs cannot replicate. For New Entrants and Emerging Players: Scandinavian free-range channels offer underpenetration where welfare-scoring protocols command retail premiums without incumbent scale requirements. Target direct-to-consumer subscription tiers in German metropolitan corridors with heritage breed positioning. Bypass wholesale layers through cold-chain partnerships with JD.com and Tmall logistics networks. For Investors and Strategic Acquirers: Carve-out targets emerge from cooperative-structured European processors seeking capital for F-Gas fleet conversion. Long-term viability favors facilities with blast-freezing capacity that tolerates refrigerant retrofit delays. Monitor EU retail procurement filters shifting from price to lifecycle assessment compliance as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hog Production | WH Group's captive breeding operations insulate margin from feed grain spot volatility. |
| Cold-Chain Fleet Retrofit | Danish Crown's CO2 cascade refrigeration conversion secures EU Green Deal contract eligibility. |
| Direct-to-Consumer Channel Launch | Subscription belly box deliveries bypass wholesale margin compression in urban China. |
| Heritage Breed Certification Program | Spain's dehesa cooperative network commands protected-origin premiums through Iberian genetics. |
| Pre-Cured Specification Standardization | Yum China's approved supplier lists with fat-ratio enforcement reduce kitchen labor costs. |
Research Methodology
The analysis maps fresh, cured, smoked, and frozen belly segments, each validated through procurement directors at quick-service chains, plant managers at integrated processors, cold-chain logistics operators, and retail category buyers. Primary interview findings triangulate against USDA livestock reports, EU F-Gas implementation tracking, Chinese customs trade data, and SEC protein conglomerate filings. Bottom-up volume builds from slaughter capacity and processing throughput; top-down validation draws from retail scanner data and foodservice distributor panel estimates.
Assumptions hold feed grain price corridors within historical volatility bands while varying F-Gas retrofit compliance timelines and quick-service expansion trajectories across the analysis window. Segmentation dimensions span preservation state, source tier, distribution channel, and end-user specification intensity. CAGRs derive from weighted average of processor capacity expansion plans and channel shift elasticity coefficients. Model inputs incorporate hog-to-carcass yield ratios and cold-chain cost pass-through coefficients.
The forecast holds incumbent behavior within observed patterns; aggressive moves by plant-based hybrid specialists or accelerated EU carbon-border adjustments would shift outcomes. Cross-checking against USDA livestock slaughter reports and EU cured meat trade statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Non-Veg Rte and Rtc Market
Meat Products
Hams Market
Meat Products
Brazil Meat Products Market
Meat Products
Asia-Pacific Red Meat Market
Meat Products
North America Red Meat Market
Meat Products
Organic Beef Meat Market
Meat Products
Middle-East and Africa Animal-Based Meat and Dairy Products Market
Meat Products
United States Animal Protein Market
Meat Products
Bacon Slicers Market
Meat Products
Europe Edible Meat Market
Meat Products
Organic Halal Meat Market
Meat Products
Europe Canned Meat Market
Meat Products
United Arab Emirates Edible Meat Market
Meat Products
Beef Bouillon Market
Meat Products
South Africa Processed Meat Market
Meat Products
Edible Offal Market