
 Refrigerated & Frozen Soup Market | 2026-2036
Refrigerated & Frozen Soup Market Size, Share, and Industry Trends Forecast 2026-2036
Refrigerated & Frozen Soup Market Insights
North America is tilting toward expanded refrigerated soup production capacity as retailers demand shorter lead times for fresh-format inventory. Campbell Soup Company leverages its chilled distribution network to sustain shelf presence across club and conventional grocery channels. Blount Fine Foods anchors premium food service supply with chef-crafted formulations that command placement in white-tablecloth and fast-casual operations. Amy's Kitchen differentiates through organic ingredient positioning that resonates with health-focused consumers scanning clean labels.
Refrigerated and frozen soup comprises thermally processed, pre-cooked liquid food products preserved through controlled chilling or freezing to maintain microbiological stability and sensory quality; formulations typically achieve water activity below 0.85 or receive time-temperature lethality treatments exceeding 70°C core temperatures to ensure pathogen elimination, with primary commercial purpose centered on reducing scratch-cooking labor in food service and delivering meal solutions for time-constrained retail consumers. Chunky soup variants dominate retail dollar contribution due to perceived satiety and whole-food ingredient visibility, while puree formats capture margin pools in healthcare and senior nutrition channels where texture-modified diets are prescribed. Tetra Pak packaging for ambient-stable broths is encroaching on frozen bag formats in European retail, though North American frozen containers still control cold-case real estate through established distributor relationships.
The FDA's Food Safety Modernization Act preventive controls and USDA FSIS inspection protocols for meat-containing SKUs shape formulation decisions, facility certification requirements, and supplier qualification timelines across the refrigerated soup value chain. State-level cottage food exemptions and California's Proposition 65 warning label mandates add compliance layers that favor scaled manufacturers with dedicated regulatory affairs functions over emerging entrants. Stakeholders must monitor how FDA's proposed traceability rule for high-risk foods will force lot-level digital tracking investments that reshape cost structures for private-label and branded producers alike.
Market Dynamics
Rising labor costs across food service operations are compressing scratch-cooking economics and accelerating refrigerated soup adoption as a viable labor substitute. Cold-chain infrastructure investments by distributors are simultaneously expanding addressable retail territory for chilled formats.
Growth Catalysts
- Preventive Controls Rule:FDA's Food Safety Modernization Act mandates are standardizing documentation protocols that favor scaled manufacturers with dedicated compliance infrastructure over cottage producers.
- Club Channel Expansion:Warehouse retailers are allocating incremental cold-case footage to refrigerated soup SKUs as meal-solution traffic drivers in suburban formats.
- QSR Partnership Velocity:Quick-service operators are integrating refrigerated soup into limited-time offers as labor arbitrage against in-house broth production.
Market Restraints
- Energy Input Volatility:Natural gas and electricity price swings directly compress blast-freezing and continuous-chilling margins for frozen soup production.
- Single-Geography Cold-Chain Concentration:Midwest distributor networks control frozen soup warehousing capacity, creating regional supply vulnerability.
- Tetra Pak Substitution:Aseptic carton formats for ambient broths are capturing price-sensitive retail volume that frozen bags historically owned.
Strategic Opportunities
- Senior Nutrition Channels:Texture-modified puree soups for healthcare and assisted-living facilities command premium placement with limited competitive density.
- Organic Certification Tailwind:USDA Organic label requirements are creating shelf-space preference rotations that favor certified refrigerated entrants.
- Direct-to-Restaurant Platforms:Food service broadline distributors are piloting vendor-managed inventory programs that bypass traditional retail slotting barriers.
Industry Challenges
- HACCP Certification Timelines:New facility approvals for refrigerated meat-containing soups face extended USDA FSIS inspection backlogs that delay market entry.
- Legacy ERP Integration:Lot-level traceability mandates require cold-chain operators to retrofit inventory systems for real-time temperature logging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refrigerated & Frozen Soup Market |
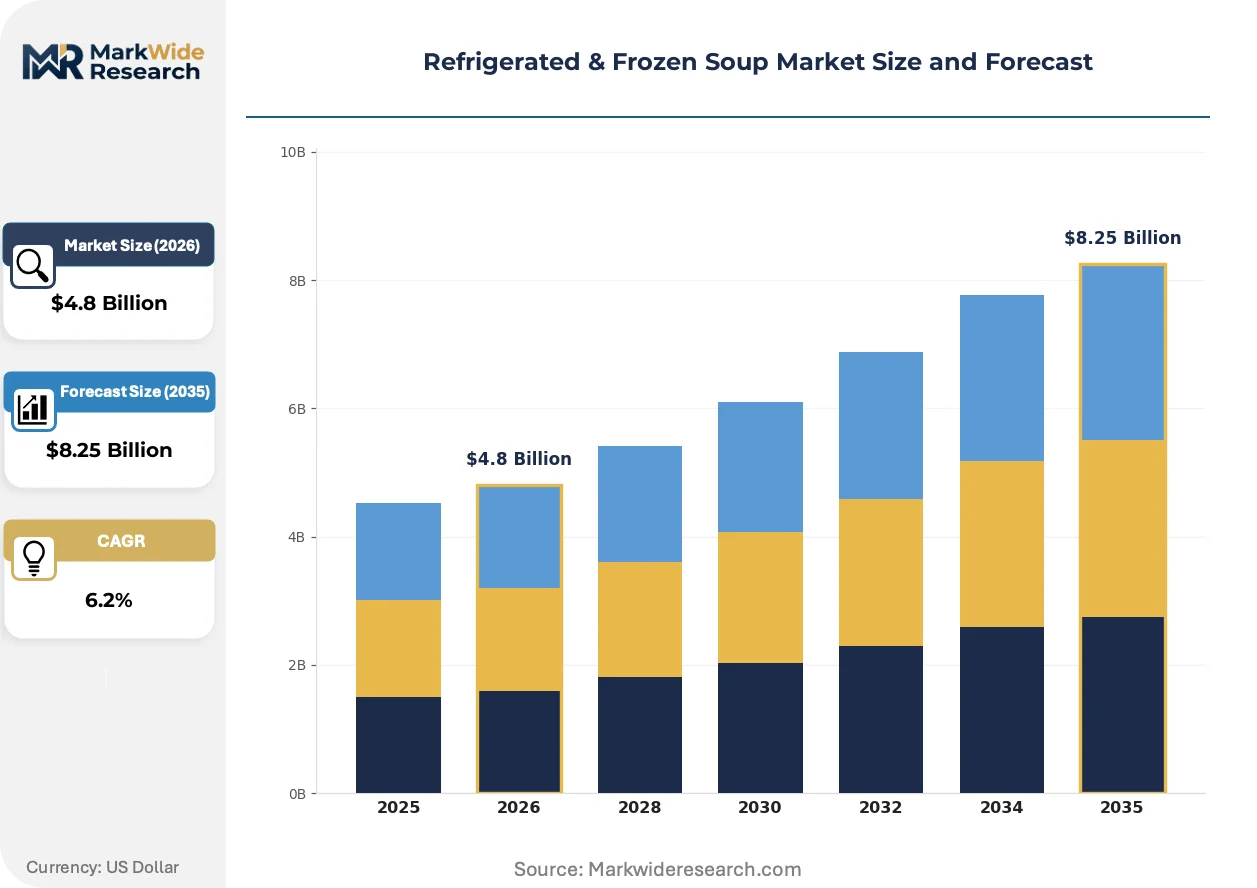
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chunky Soup, Puree Soup, Broth, Bisque Ingredient Type: Vegetable, Meat, Seafood, Legume Packaging Type: Bag, Container, Tetra Pak, Can Distribution Channel: Supermarket, Online Store, Food Service, Convenience Store |
| Companies Covered | Nestlé, Blount Fine Foods, Campbell Soup Company, Amy's Kitchen, Kettle Cuisine, Conagra Brands, General Mills, Hain Celestial Group, Kraft Heinz Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refrigerated & Frozen Soup Market Trends and Innovations
Digital cold-chain monitoring is compressing quality-assurance overhead while enabling precision inventory management across distributed production networks. Three developments are restructuring competitive capability requirements.
High-pressure processing equipment is virtualizing thermal lethality steps for refrigerated soups. Premium organic producers are adopting HPP systems to extend refrigerated shelf life without nutrient degradation from conventional retort temperatures. This virtualization is collapsing the capital barrier between refrigerated and frozen format economics.
California's Proposition 65 warning label mandates are forcing reformulation of tomato-based and seafood-containing SKUs to eliminate listed chemical exposures. Manufacturers are relocating production to Nevada and Arizona facilities to escape California's direct jurisdiction while maintaining West Coast distribution reach. White-tablecloth food service accounts are demanding Proposition 65-compliant documentation as a procurement qualifier.
Buyer consolidation among healthcare group purchasing organizations is compressing supplier rosters for texture-modified nutrition products. Senior dining operators are unbundling soup procurement from full-line food contracts and awarding dedicated refrigerated soup agreements to specialized manufacturers. This pattern concentrates procurement leverage in the Southeast and Southwest retirement corridor markets.
Refrigerated & Frozen Soup Market Segmentation
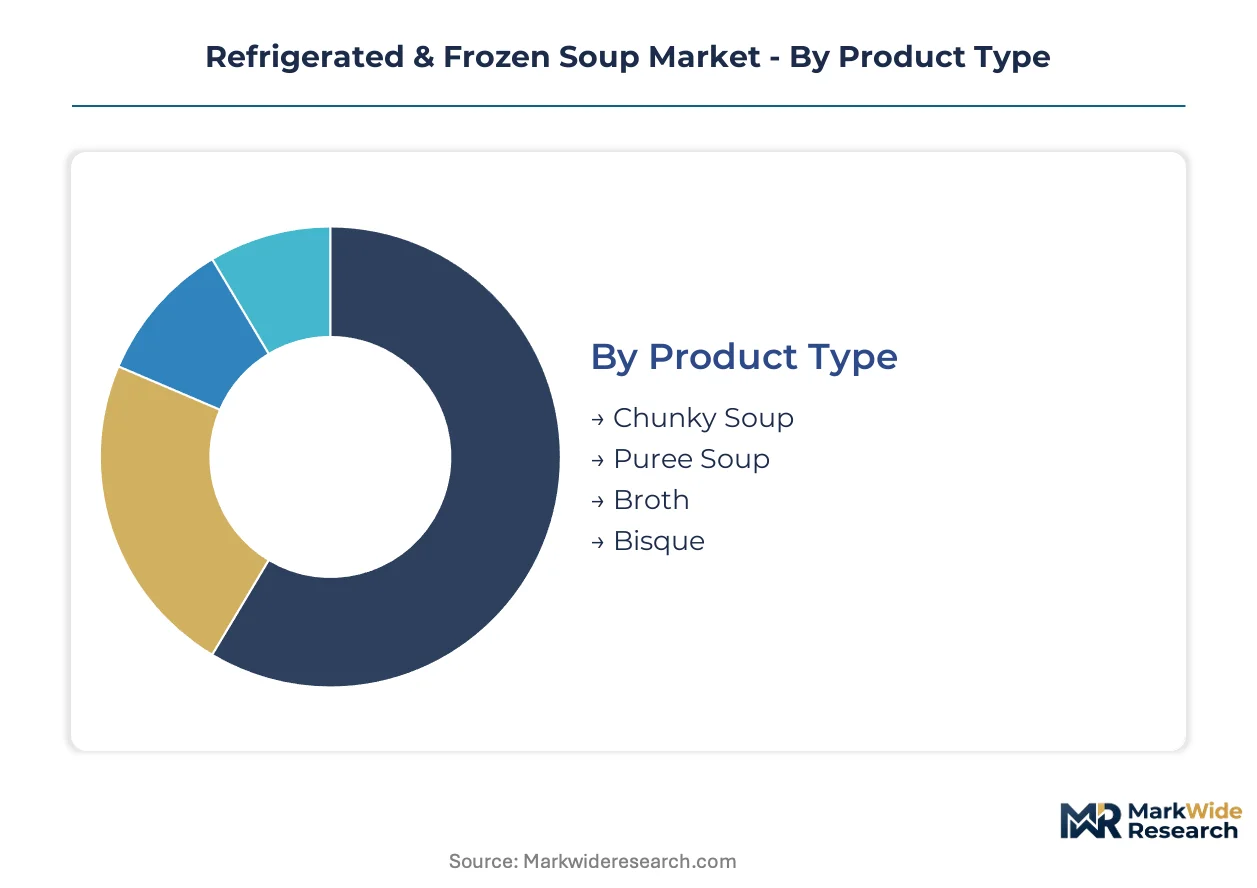
Refrigerated and frozen soup manufacturers calibrate formulation, thermal processing intensity, and cold-chain specifications against distinct consumption occasions and procurement channels. Segment boundaries determine margin capture, with texture-modified formats commanding healthcare premiums and club-channel SKUs optimizing volume throughput.
Product Type:
Cost tier differentiation separates labor-substitute formats from premium-positioned varieties, with viscosity and particulate density driving production economics and shelf-life engineering.
- Chunky Soup:High-viscosity formulations carrying discrete vegetable and protein particulates above 8mm require controlled ice-crystal formation during blast freezing to preserve textural integrity. Demand concentrates in United States club retailers where multi-serve tubs function as meal-solution traffic drivers for suburban households seeking satiety signals from visible whole-food ingredients.
- Puree Soup:Homogeneous, texture-modified formulations achieve smooth rheology through high-shear processing and fine-milling of cooked bases, enabling compliance with IDDSI Level 4 standards for dysphagia management. Healthcare and senior nutrition channels in the Southeast United States retirement corridor are rotating procurement toward dedicated puree suppliers as GPOs unbundle soup categories from full-line contracts.
- Broth:Clarified liquid stocks with dissolved protein and mineral content serve as ingredient inputs for scratch-cooking reduction and home-prepared meal bases.
- Bisque:Cream-thickened shellfish or vegetable emulsions targeting white-tablecloth food service accounts with elevated butterfat content and extended finishing requirements.
Chunky formats hold installed capacity across Midwest production facilities. Puree soups are rotating up the share rankings in institutional procurement.
Ingredient Type:
Application-specific nutrition claims and allergen management protocols segment raw material sourcing, with protein pathway determining regulatory inspection jurisdiction and label declaration burden.
- Vegetable:Plant-forward formulations leveraging root vegetable, allium, and leafy green bases achieve clean-label positioning through minimal ingredient declarations and organic certification eligibility. United States retail scanners seeking Proposition 65 compliance are concentrating demand in tomato and butternut squash varieties reformulated to eliminate listed chemical exposures.
- Meat:Poultry, beef, and pork-containing SKUs trigger USDA FSIS inspection protocols, extending facility certification timelines but enabling placement in protein-forward meal occasions. Food service operators in the United States QSR segment are integrating refrigerated meat-based soups as limited-time offers to arbitrage labor costs against in-house broth production.
- Seafood:Shellfish and finfish formulations face elevated cold-chain sensitivity and histamine control requirements, constraining distribution radius.
- Legume:Bean and lentil bases deliver fiber-forward nutrition claims with cost advantages in commodity procurement cycles.
Vegetable platforms hold installed capacity across organic-certified production lines. Meat-containing varieties are rotating up the share rankings in food service partnerships.
Packaging Type:
Volume throughput and cold-case real estate economics determine format selection, with barrier properties and consumer convenience features trading off against unit cost and environmental compliance.
- Bag:Flexible multilayer films with nylon or EVOH oxygen barriers enable efficient cube utilization in frozen distribution, though puncture vulnerability limits retail handling. United States frozen soup warehousing networks in the Midwest continue to favor bag formats for institutional volume despite Tetra Pak encroachment in European retail.
- Container:Rigid polypropylene or PET tubs with tamper-evident lidding dominate refrigerated case presentation, supporting spoon-ready consumption and resealability. Club channel expansion in United States suburban formats is concentrating demand in multi-serve container SKUs with extended refrigerated shelf life through modified atmosphere packaging.
- Tetra Pak:Aseptic carton formats with ambient stability are capturing price-sensitive retail volume historically owned by frozen bags.
- Can:Metal container formats persist in value-tier frozen soup segments with established retort compatibility.
Container formats hold installed capacity across chilled distribution networks. Bag formats are rotating up the share rankings in private-label frozen programs.
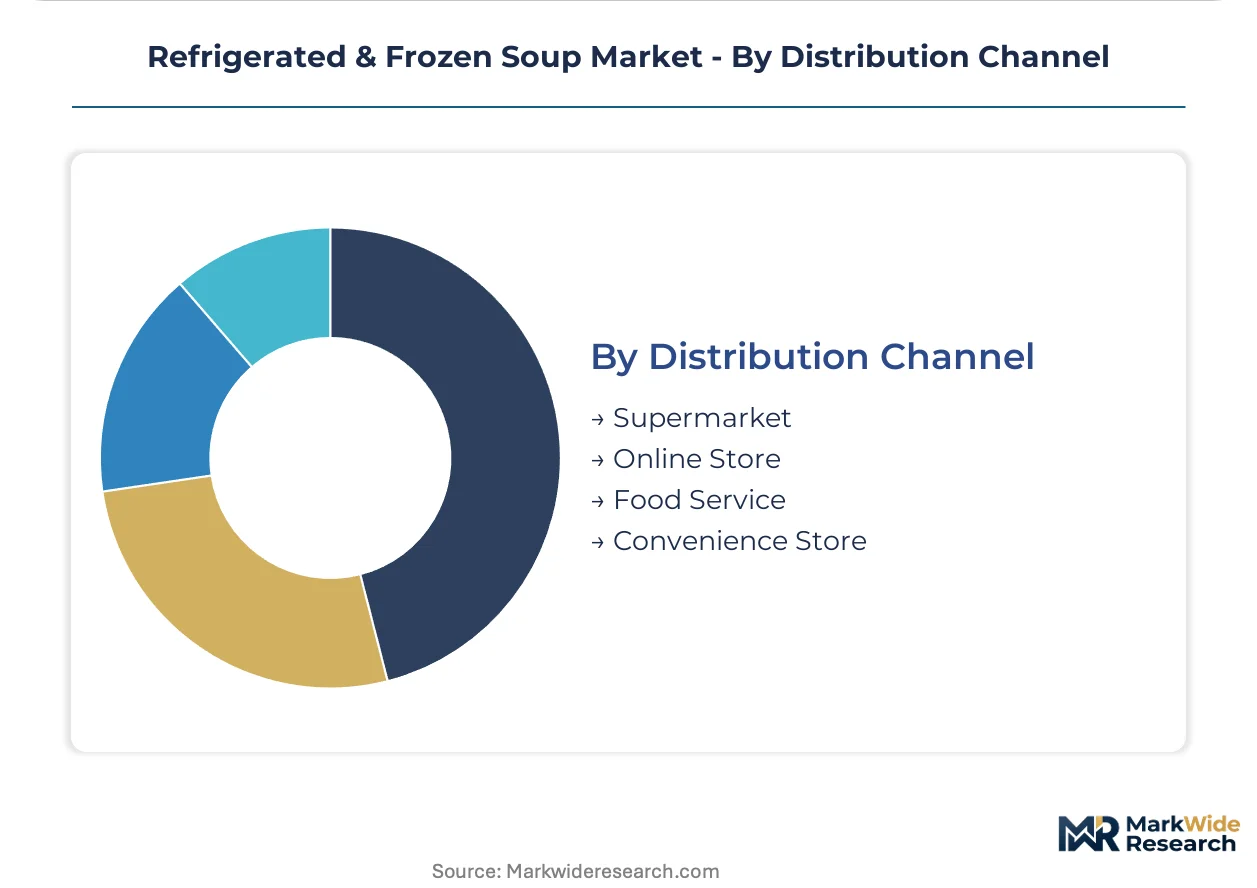
Distribution Channel:
Customer type determines service level requirements, with temperature verification protocols and slotting fee structures varying across self-service retail and assisted procurement environments.
- Supermarket:Conventional grocery formats with dedicated cold-case footage require weekly replenishment cycles and promotional support for feature ad placement. United States retailers are demanding shorter lead times for fresh-format inventory, tilting procurement toward regional refrigerated soup production capacity.
- Food Service:Broadline distributor relationships with vendor-managed inventory programs bypass traditional retail slotting barriers for direct-to-restaurant supply. White-tablecloth and fast-casual operators are sourcing chef-crafted formulations through specialized manufacturers with HACCP-certified facilities.
- Online Store:Direct-to-consumer fulfillment requires insulated packaging and frozen gel pack configurations that compress margin structures.
- Convenience Store:Grab-and-go refrigerated placement targets immediate consumption occasions with single-serve portioning.
Supermarket channels hold installed capacity across branded and private-label portfolios. Food service direct platforms are rotating up the share rankings in procurement innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA preventive controls and USDA FSIS inspection protocols anchor United States market dynamics, with cold-chain infrastructure investments expanding refrigerated soup distribution reach across suburban retail formats.
United States
Club channel expansion and QSR partnership velocity drive refrigerated soup demand in suburban formats. California's Proposition 65 warning label mandates force tomato-based and seafood-containing SKU reformulations. Midwest distributor networks control frozen soup warehousing capacity, creating regional supply concentration around Chicago and Minneapolis logistics hubs.
Germany
Food service operators adopt refrigerated soup programs as labor costs rise across hospitality sectors. EFSA cold-chain documentation requirements align with EU Food Safety Modernization Act implementation timelines. Bavaria-based production facilities leverage automated high-pressure processing equipment to extend refrigerated shelf life for organic-certified formulations.
United Kingdom
Convenience-oriented retail formats drive category velocity through dedicated cold-case footage allocation. Food Standards Agency traceability mandates for high-risk foods force lot-level digital tracking investments. Greater London logistics clusters concentrate refrigerated distribution capacity for chef-crafted food service supply.
France
White-tablecloth restaurant accounts demand Proposition 65-compliant documentation as procurement qualifiers for imported formulations. ANSM labeling requirements add compliance layers favoring scaled manufacturers with dedicated regulatory affairs functions. Île-de-France production basins anchor premium bisque and broth manufacturing for European export.
Canada
Healthcare group purchasing organization consolidation compresses supplier rosters for texture-modified nutrition products. Health Canada preventive controls for human foods standardize documentation protocols across provincial jurisdictions. Ontario-based cold-chain operators retrofit inventory systems for real-time temperature logging to meet traceability mandates.
Refrigerated & Frozen Soup Market Competitive Landscape
Capability concentration sits with specialized chilled distribution networks and chef-crafted formulation expertise; scale advantage sits with diversified packaged food conglomerates with multi-category retail presence. The market structures around three archetypes: premium organic specialists, food service supply specialists, and mass-market branded portfolios. Consolidation pressures favor scaled manufacturers with dedicated compliance infrastructure over cottage producers. Competitive moves center on cold-chain infrastructure partnerships and organic certification shelf-space rotations.
Within the premium organic tier, Amy's Kitchen and Hain Celestial Group exemplify clean-label positioning that resonates with health-focused consumers scanning ingredient declarations. Blount Fine Foods anchors the food service specialist vector with chef-crafted formulations commanding placement in white-tablecloth and fast-casual operations. Campbell Soup Company occupies a position bridging mass-market scale with chilled distribution network leverage across club and conventional grocery channels.
| Leading Market Players |
|---|
| Nestlé |
| Blount Fine Foods |
| Campbell Soup Company |
| Amy's Kitchen |
| Kettle Cuisine |
| Conagra Brands |
| General Mills |
| Hain Celestial Group |
| Kraft Heinz Company |
| Others |
Pricing and Supply Chain Analysis
Midwest frozen soup warehousing concentration around Chicago and Minneapolis logistics hubs directly determines where margin pools accumulate downstream, with distributor gatekeeping power compressing manufacturer pricing leverage in institutional procurement channels while regional production proximity to these hubs unlocks freight-cost advantages for club-channel volume plays.
Pricing Analysis
Geographic price spreads between United States club-channel multi-serve tubs and European Tetra Pak ambient broths exceed thirty percent on a per-liter basis. Three-tier pricing structure across premium chef-crafted, standard refrigerated, and economy frozen bag levels separates organic-certified puree formats from conventional chunky varieties. Pricing pressure stems from energy input volatility in blast-freezing operations, with natural gas price swings compressing margins for frozen production tiers. Food service operators exhibit lowest price sensitivity due to labor-arbitrage value capture, while price-sensitive retail volume migrates toward aseptic carton substitutes.
Supply Chain Analysis
Contract manufacturing concentration sits with Blount Fine Foods, Kettle Cuisine, and regional co-packers holding USDA FSIS-certified refrigerated capacity across New England and Pacific Northwest production basins. Geographic supply concentration centers on United States Midwest freezing infrastructure, Canadian Ontario cold-chain retrofit investments, and Bavaria-based German high-pressure processing facilities. Raw material dependencies include organic vegetable procurement from California Central Valley suppliers, Midwest commodity poultry contracts, and EVOH barrier film resins from petrochemical suppliers. Single-geography cold-chain concentration in Midwest distributor networks creates regional supply vulnerability from weather disruptions. Distribution runs through broadline food service distributors with vendor-managed inventory programs bypassing traditional retail slotting barriers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refrigerated and frozen soup represents a high-growth disruption as FDA's proposed traceability rule for high-risk foods forces lot-level digital tracking investments that reshape cost structures and favor scaled compliance infrastructure over cottage producers.
For Market Incumbents: Insulate market position through backward integration into organic vegetable supply from California Central Valley growers and captive high-pressure processing equipment deployment to collapse format economics between refrigerated and frozen tiers. HACCP certification timeline extensions for meat-containing SKUs threaten new facility approvals; incumbents should leverage existing USDA FSIS inspection relationships to accelerate competitor exclusion. Channel control through club-channel exclusive multi-serve formulations reinforces shelf presence against Tetra Pak ambient encroachment. For New Entrants and Emerging Players: Southeast United States retirement corridor healthcare procurement presents underpenetrated white-space as GPOs unbundle texture-modified nutrition categories from full-line contracts. Direct-to-restaurant platforms bypass retail slotting fee barriers that concentrate incumbent advantage in conventional grocery. Senior dining operators seeking dedicated puree soup agreements offer the most penetrable entry vector; vendor-managed inventory partnerships with regional broadline distributors provide the optimal go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward food service supply specialists with chef-crafted formulation expertise and HACCP-certified facility assets rather than mass-market branded portfolios facing Tetra Pak substitution pressure. Long-term viability across the analysis window hinges on cold-chain infrastructure partnerships and organic certification shelf-space rotations. The signal to watch is FDA traceability rule implementation pace, which will force digital tracking investments and consolidate procurement leverage toward scaled manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Partnership | Midwest distributor network alliances expand addressable territory for chilled formats beyond legacy frozen strongholds. |
| Organic Certification Investment | USDA Organic label requirements create shelf-space preference rotations favoring certified refrigerated entrants. |
| High-Pressure Processing Equipment Deployment | Bavaria-based automated HPP systems extend refrigerated shelf life without retort nutrient degradation for premium organic producers. |
| Vendor-Managed Inventory Program | Broadline food service distributors pilot direct-to-restaurant supply bypassing traditional retail slotting barriers. |
| Proposition 65 Compliance Reformulation | California warning label mandates force tomato-based and seafood-containing SKU relocation to Nevada and Arizona facilities. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with food service procurement directors, refrigerated soup brand managers, USDA FSIS compliance officers, and club-channel category buyers. Secondary validation drew from FDA Food Safety Modernization Act documentation, USDA FSIS inspection protocol filings, Nielsen retail audit data for cold-case velocity metrics, and customs records tracking frozen soup import flows. Bottom-up volume modeling across product type, ingredient category, packaging format, and distribution channel segments was triangulated against top-down market sizing from producer capacity disclosures.
Calibration against historical CAGRs from adjacent chilled prepared food categories anchored growth trajectory assumptions across the projection horizon. Segmentation dimensions modeled include product viscosity tier, protein pathway regulatory jurisdiction, barrier packaging technology, and customer procurement channel with associated service level requirements. CAGRs were derived from weighted average of category velocity trends and capacity expansion announcements. Industry-specific forecast inputs incorporated cold-chain infrastructure investment pipelines and FDA traceability rule implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by private-label retailers or venture-backed direct-to-consumer entrants would shift outcomes beyond modeled ranges. Cross-checking against IRI retail scanner data and food service broadline distributor volume reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Refrigerated Liquid Eggs Market
Processed and Frozen Foods
Scandinavia Frozen Food Market
Processed and Frozen Foods
Germany Frozen Snack Market
Processed and Frozen Foods
US Frozen Dessert Market
Processed and Frozen Foods
North America Frozen Pizza Market
Processed and Frozen Foods
Frozen Meat Grinder Market
Processed and Frozen Foods
Frozen Yogurt Market
Processed and Frozen Foods
Frozen Fruit Bars Market
Processed and Frozen Foods
Chocolate Ice Cream Market
Processed and Frozen Foods
Popsicle Market
Processed and Frozen Foods
Canned Vegetables Market
Processed and Frozen Foods
North America Frozen Finger Chips Market
Processed and Frozen Foods
Middle East and Africa Freeze-Dried Product Market
Processed and Frozen Foods
Asia Pacific Freeze Dried Product Market
Processed and Frozen Foods
Freeze Dried Melt Market
Processed and Frozen Foods
Turkey Cold Storage Market