
 Vegan Frozen Pizza Market | 2026-2036
Vegan Frozen Pizza Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Frozen Pizza Market Analytics
Market Context
Premium clean-label certification is bifurcating the competitive landscape into mass-market and specialty tiers. Amy's Kitchen leverages its organic supply chain heritage to sustain pricing power in natural retail channels. Daiya Foods differentiates through proprietary vegan cheese formulations that anchor its product lineup across North American supermarkets. Banza competes by extending legume-based crust innovation into mainstream freezer sections previously dominated by wheat alternatives.
Technical Definition and Segment Structure
Vegan frozen pizza denotes a plant-based, ready-to-bake flatbread product formulated without animal-derived ingredients, typically featuring water, wheat or alternative flour, vegetable oils, and cultured non-dairy cheese analogs, manufactured through flash-freezing after par-baking to preserve texture and extend shelf life. Its primary commercial purpose is delivering convenience-oriented, ethically positioned meal solutions to consumers restricting animal product consumption. Gluten-free variants command disproportionate margin pools due to ingredient cost premiums and medical-necessity purchasing patterns among celiac and gluten-sensitive households. Online retail channels represent the fastest-growing distribution pathway as direct-to-consumer cold-chain logistics mature. Legume-based crusts occupy an emerging structural position where chickpea and lentil formulations attract protein-seeking buyers beyond traditional vegan demographics.
Regulatory Framework
The FDA governs allergen labeling and dairy identity standards that constrain vegan cheese nomenclature in the United States, while the EU Green Deal and EFSA novel food regulations shape ingredient approval timelines for emerging protein sources across European markets. USDA Organic certification and Non-GMO Project verification function as parallel gatekeeping mechanisms that influence retailer acceptance and consumer trust thresholds. Stakeholders must monitor evolving precision-fermentation regulatory classifications that could redefine clean-label positioning and trigger reformulation decisions across existing product portfolios.
Market Dynamics
The EU Green Deal's sustainable food system targets are compressing reformulation timelines across European supply chains, forcing manufacturers to accelerate ingredient sourcing transitions ahead of regulatory enforcement windows.
Growth Catalysts
- Precision fermentation scale-up:Cultured non-dairy protein production is achieving cost parity with conventional cheese analogs, enabling broader retail distribution.
- Plant-based meal kit integration:Subscription services in Germany and the United Kingdom are creating dedicated freezer sections for certified vegan frozen products.
- Clean-label certification expansion:USDA Organic and Non-GMO Project verification are unlocking shelf space in natural retail channels previously inaccessible to conventional frozen pizza.
Market Restraints
- Cold-chain logistics cost volatility:Diesel price fluctuations and refrigerated transport capacity constraints inflate last-mile delivery expenses for direct-to-consumer channels.
- Ingredient supply concentration:Cashew and coconut oil sourcing clusters in Southeast Asia create vulnerability to climate-related crop yield variability.
- EFSA novel food approval timelines:Emerging protein sources from precision fermentation face extended safety assessment periods before European market entry.
Strategic Opportunities
- Legume-based crust penetration:Chickpea and lentil formulations attract protein-seeking buyers beyond traditional vegan demographics in North American mainstream freezer sections.
- Direct-to-consumer cold-chain maturation:Specialized logistics providers are enabling nationwide frozen delivery without traditional retail intermediation.
- IRA clean energy incentives:Renewable energy tax credits reduce operational costs for domestic manufacturing facilities in the United States.
Industry Challenges
- Refrigerated warehouse capacity scarcity:Cold storage construction lags demand growth, creating inventory bottlenecks during peak seasonal periods.
- Cross-contamination certification complexity:Gluten-free and allergen-free production line segregation requires capital-intensive facility reconfiguration.
Report Scope
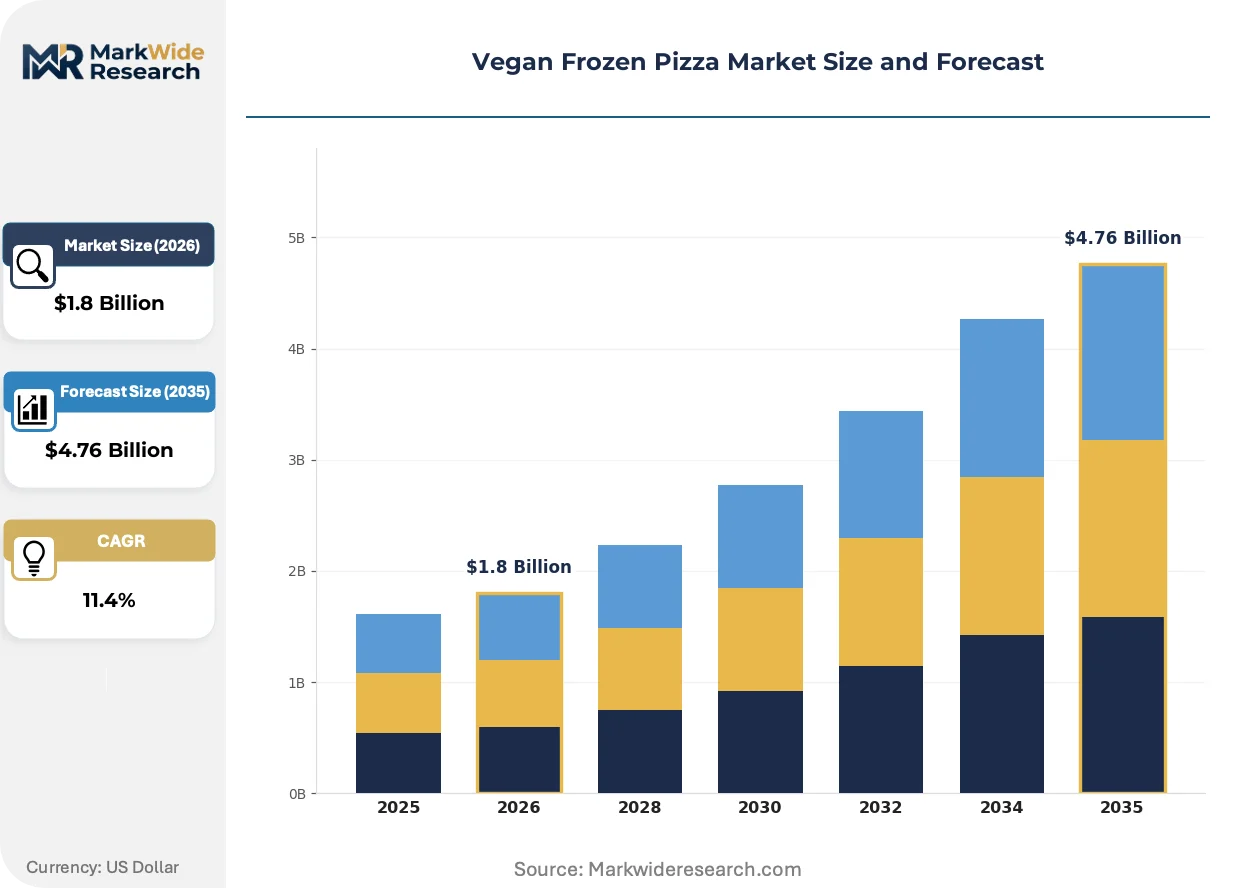
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Frozen Pizza Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Garden Style, Italian Style, Gluten-Free, Stuffed Crust Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Specialty Stores End User: Households, Restaurants, Cafes, Meal Kits Ingredient Type: Vegetable Toppings, Vegan Cheese, Legume-Based Crusts, Others |
| Companies Covered | The White Rabbit Pizza Co., Blackbird Foods, Amy's Kitchen, 365 by Whole Foods Market, Banza, Daiya Foods, Tofurky Company, American Flatbread, Sweet Earth Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Frozen Pizza Market Evolving Landscape
Formulation science and regulatory alignment are converging to reshape competitive positioning, with texture replication and supply chain transparency emerging as the primary battlegrounds for differentiation.
Cell-cultured casein is supplanting starch-based cheese analogs in premium product tiers. Protein-seeking flexitarian households in Germany and the United Kingdom are driving adoption at triple-digit velocity in specialty retail. This shift is compressing margin structures for legacy vegetable-oil-and-starch formulations while opening pricing headroom for fermentation-derived alternatives.
REACH chemical safety registrations are tightening emulsifier and stabilizer approval pathways for European manufacturers. Reformulation costs are rising as suppliers phase out legacy additives ahead of sunset dates. Frozen pizza producers targeting EU distribution are accelerating clean-label transitions to preempt compliance-driven supply disruptions.
Subscription-based replenishment models are displacing impulse freezer-aisle purchases among urban millennial and Gen Z households. Direct-to-consumer platforms with customizable flavor rotations are capturing loyalty previously owned by supermarket brands. This behavioral shift is most concentrated in metropolitan areas of the United States and Germany where cold-chain infrastructure supports reliable home delivery.
Vegan Frozen Pizza Market Segmentation
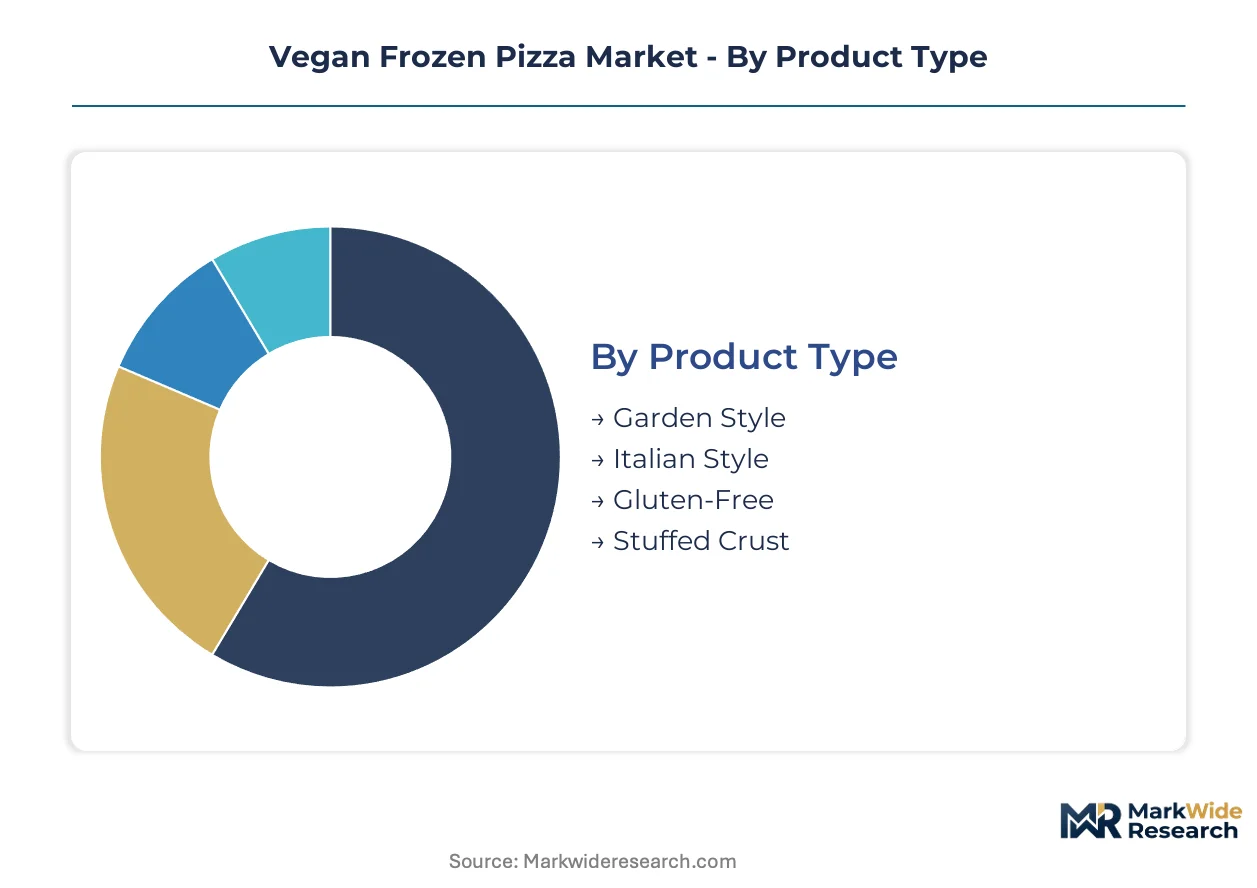
Vegan frozen pizza segmentation reflects divergent certification requirements and cold-chain capabilities across distribution pathways. Product differentiation increasingly hinges on clean-label positioning and protein source innovation rather than traditional flavor variety.
Product Type:
FDA dairy identity standards and USDA Organic certification create tiered compliance burdens that separate mass-market from specialty formulations.
- Gluten-Free:Formulated with rice flour, tapioca starch, or almond meal to eliminate wheat proteins. Celiac households in Germany and the United States drive disproportionate margin capture due to medical-necessity purchasing and limited substitution options.
- Legume-Based Crusts:Chickpea and lentil flour formulations deliver elevated protein content and glycemic index advantages. Protein-seeking flexitarians in North American mainstream retail channels favor these alternatives over traditional wheat bases.
- Garden Style:Vegetable-forward topping configurations emphasizing seasonal produce combinations.
- Italian Style:Classic marinara and herb profiles targeting conventional pizza palates transitioning to plant-based options.
- Stuffed Crust:Vegan cheese-filled perimeter formulations requiring specialized par-baking equipment.
Established volume favors Garden Style; emerging adoption favors Legume-Based Crusts.
Distribution Channel:
Cold-chain maturity and last-mile cost structures concentrate margin capture in channels with captive logistics infrastructure.
- Online Retail:Direct-to-consumer platforms with subscription replenishment models bypass traditional retail slotting fees. Metropolitan households in the United States and Germany with reliable frozen delivery infrastructure favor this channel for customizable flavor rotations.
- Health Food Stores:Natural retail channels gate entry through Non-GMO Project and organic certification requirements. These outlets command premium pricing power with ethically motivated consumers seeking supply chain transparency.
- Supermarkets:Mass-market freezer sections with established refrigerated warehouse networks.
- Specialty Stores:Ethnic and gourmet retailers curating premium imported selections.
Transaction density concentrates in Supermarkets; margin expansion concentrates in Online Retail.
End User:
Volume scale and customization requirements split manufacturing priorities between standardized retail packs and foodservice specifications.
- Meal Kits:Subscription services integrate vegan frozen pizza into rotating weekly menus with precise portion control. Plant-based meal kit providers in Germany and the United Kingdom dedicate expanding freezer capacity to certified vegan frozen products.
- Households:Individual and family-size retail packs dominate absolute volume.
- Restaurants:Foodservice distributors supply quick-service and casual dining operators.
- Cafes:Smaller-format venues with limited kitchen equipment favor par-baked convenience.
Absolute volume flows to Households; subscription velocity favors Meal Kits.
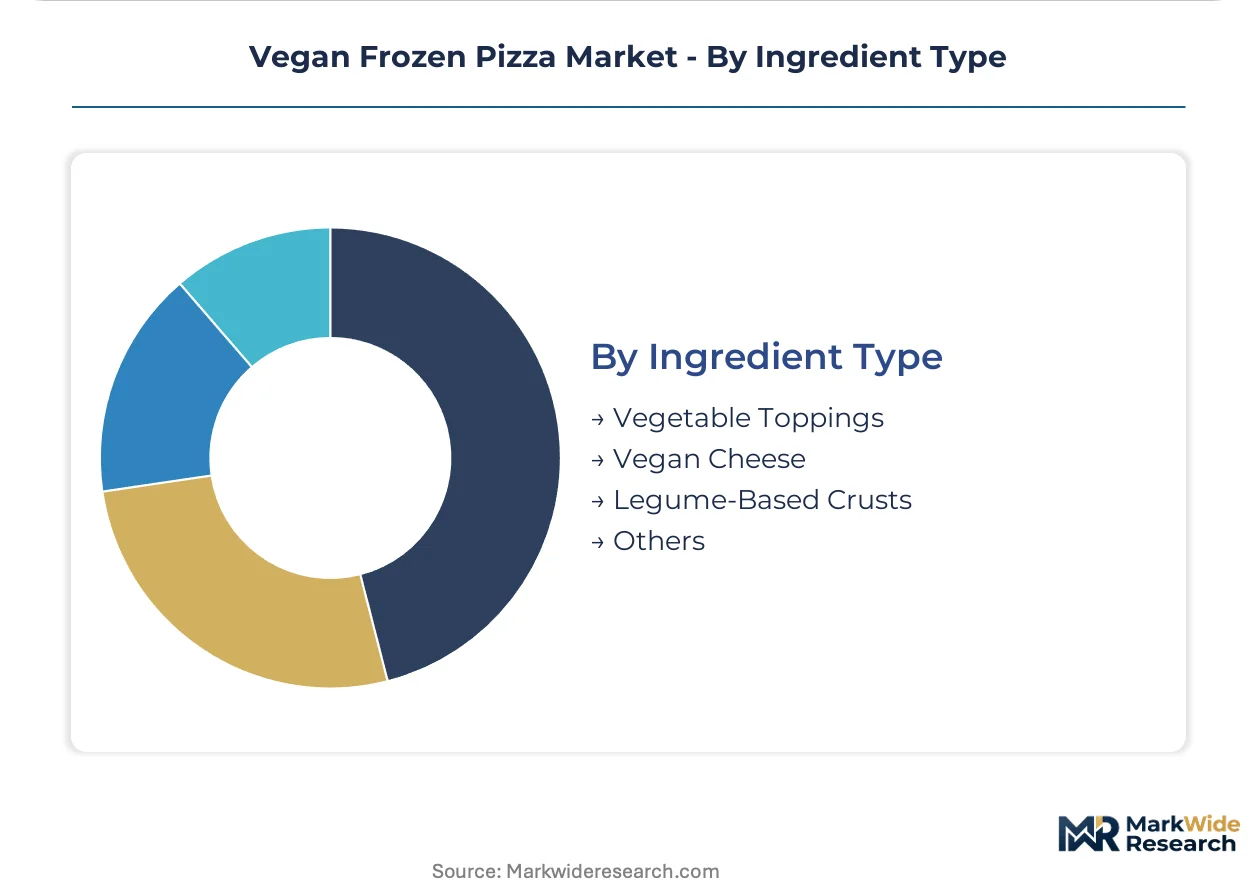
Ingredient Type:
EFSA novel food approval timelines and REACH chemical registrations reshape sourcing strategies for European formulation.
- Vegan Cheese:Precision-fermented casein analogs and cultured nut-based formulations replace starch-and-oil legacy options. Cell-cultured protein production achieving cost parity enables broader retail distribution in premium tiers.
- Legume-Based Crusts:Chickpea, lentil, and fava bean flours deliver complete protein profiles and fiber advantages. Protein-seeking households beyond traditional vegan demographics favor these formulations in North American and German retail.
- Vegetable Toppings:Roasted and fire-charred produce configurations emphasizing umami depth.
- Others:Emerging protein sources including mycelium and algae-derived ingredients awaiting regulatory clearance.
Formulation investment concentrates on Vegan Cheese; clean-label positioning drives Legume-Based Crusts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ingredient sourcing clusters in Southeast Asia and precision-fermentation scale-up in North America concentrate supply-side leverage for vegan cheese analogs. Retail expansion dynamics diverge sharply between mature cold-chain markets and emerging direct-to-consumer corridors.
United States
Subscription replenishment models capture loyalty among urban millennial and Gen Z households in metropolitan corridors. The FDA dairy identity standards constrain vegan cheese nomenclature while USDA Organic certification unlocks natural retail shelf space. Cold-chain logistics maturation in the Northeast and California enables nationwide frozen delivery without traditional retail intermediation.
Germany
Protein-seeking flexitarian households drive triple-digit adoption velocity for cell-cultured casein formulations in specialty retail. The EU Green Deal's sustainable food system targets compress reformulation timelines ahead of regulatory enforcement windows. Berlin and Munich anchor expanding freezer capacity dedicated to certified vegan frozen products across plant-based meal kit services.
United Kingdom
Direct-to-consumer platforms with customizable flavor rotations displace impulse freezer-aisle purchases in London and metropolitan hubs. EFSA novel food regulations shape approval timelines for emerging protein sources entering European distribution. Subscription services integrate vegan frozen pizza into rotating weekly menus with precise portion control specifications.
Canada
Health food store channels gate entry through Non-GMO Project verification requirements that influence consumer trust thresholds. Health Canada and PMRA govern allergen labeling standards that parallel FDA constraints on dairy identity claims. Toronto and Vancouver concentrate natural retail expansion where ethically motivated consumers seek supply chain transparency.
Australia
Gluten-free variants command disproportionate margin pools due to medical-necessity purchasing patterns among celiac households. The TGA regulates novel food ingredient assessments that align with EFSA timelines for precision-fermentation proteins. Sydney and Melbourne anchor cold-storage infrastructure supporting direct-to-consumer frozen delivery expansion.
Vegan Frozen Pizza Market Competitive Landscape
Concentration sits with organic supply chain heritage players and proprietary vegan cheese formulators occupying distinct tier positions. The vendor base stratifies across mass-market freezer sections, natural retail channels, and direct-to-consumer subscription corridors. Three archetypes dominate: legacy organic brands leveraging certification equity, dairy-alternative specialists commanding formulation science, and legume-based innovators extending protein positioning beyond traditional vegan demographics. Competitive moves center on clean-label certification expansion and precision-fermentation scale-up partnerships.
Within the organic heritage tier, Amy's Kitchen exemplifies supply chain certification equity sustained across natural retail channels. Daiya Foods anchors the proprietary formulation vector through cultured non-dairy cheese analog development. Banza occupies the legume-innovation position where chickpea-based crust extensions attract protein-seeking buyers in mainstream freezer sections.
| Leading Market Players |
|---|
| The White Rabbit Pizza Co. |
| Blackbird Foods |
| Amy's Kitchen |
| 365 by Whole Foods Market |
| Banza |
| Daiya Foods |
| Tofurky Company |
| American Flatbread |
| Sweet Earth Foods |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts for cashew and coconut oil lock in supply access and price visibility for European and North American manufacturers sourcing from Southeast Asian processing clusters. These arrangements insulate against commodity volatility while compressing margin flexibility for mid-tier producers lacking procurement scale.
Pricing Analysis
USDA Organic certification dictates the pricing tier structure across natural retail channels, separating premium-certified formulations from conventional freezer-aisle alternatives. Three-tier pricing stratifies across certified organic, clean-label conventional, and mass-market economy levels. Price differentiation hinges on certification grade and cold-chain delivery cost. Pricing pressure intensifies in the mass-market tier as private-label entrants replicate base formulations. Meal kit subscribers exhibit lowest price sensitivity; impulse supermarket buyers face highest elasticity.
Supply Chain Analysis
Inventory cycles for frozen finished goods extend lead times beyond ambient-food benchmarks, compressing working capital efficiency for distributors. Raw material sourcing concentrates in Vietnam and Indonesia for coconut oil, India for cashew derivatives, and the United States for precision-fermentation protein development. Manufacturing draws from par-baking equipment clusters in Germany and California. Single-source vulnerability in Southeast Asian nut processing creates exposure to climate-driven yield shocks. Distribution runs through refrigerated warehouse networks anchored by third-party cold-storage specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat, with USDA Organic and Non-GMO Project certification creating switching costs that lock retailer relationships and consumer loyalty against commodity alternatives.
For Market Incumbents: Secure precision-fermentation supply partnerships ahead of EFSA novel food clearance timelines to anchor premium positioning against starch-based legacy formulations. Deepen backward integration into certified organic wheat and legume flour milling to defend margin compression from ingredient cost volatility. Channel control through dedicated freezer section placement agreements with plant-based meal kit services reinforces shelf-space exclusivity.
For New Entrants and Emerging Players: Anchor in the legume-based crust segment where protein-seeking flexitarian households in North American mainstream retail show triple-digit adoption velocity with limited incumbent saturation. Target direct-to-consumer subscription corridors in metropolitan Germany and the United Kingdom where cold-chain infrastructure supports reliable frozen delivery without slotting-fee barriers. A customizable flavor-rotation platform with transparent supply chain storytelling unlocks trial among ethically motivated millennials.
For Investors and Strategic Acquirers: Proprietary vegan cheese formulators with precision-fermentation scale-up partnerships represent the highest-conviction acquisition archetype for long-term viability across the five-to-ten-year protein-transition horizon. Cell-cultured casein achieving cost parity with conventional analogs signals inflection toward margin expansion in premium tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision-Fermentation Scale-Up Partnership | Cell-cultured casein production achieves cost parity with starch-based analogs for premium tier expansion. |
| Direct-to-Consumer Cold-Chain Launch | Subscription replenishment models bypass supermarket slotting fees in metropolitan United States and Germany corridors. |
| Legume-Based Crust Line Extension | Chickpea and lentil formulations attract protein-seeking flexitarians beyond traditional vegan demographics. |
| USDA Organic Certification Investment | Clean-label verification unlocks natural retail shelf space previously inaccessible to conventional frozen pizza. |
| Plant-Based Meal Kit Integration | Dedicated freezer capacity agreements with German and United Kingdom subscription services secure recurring volume. |
Research Methodology
A spread of perspectives from frozen food brand managers, retail category buyers at natural grocery chains, cold-chain logistics operators, and plant-based ingredient procurement leads converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA dairy identity filings, USDA Organic certification databases, EFSA novel food application registers, and refrigerated warehouse capacity reports from third-party logistics providers. Bottom-up demand modeling triangulated against top-down retail audit data from Nielsen and Circana.
Segmentation dimensions modeled include product type certification tier, distribution channel cold-chain maturity, and end-user customization requirements across the projection horizon. CAGRs were derived from volume-weighted growth trajectories within each segment. Forecast inputs incorporated EFSA approval timeline scenarios for precision-fermentation proteins and EU Green Deal reformulation deadline impacts on European supply chains.
Material uncertainties — regulatory reclassification of cell-cultured proteins, climate-driven crop yield variability in Southeast Asia, and refrigerated transport cost volatility — sit outside the modeled envelope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Dehydrated Potato Market
Processed and Frozen Foods
IQF Food Products Market
Processed and Frozen Foods
Deli Meat Market
Processed and Frozen Foods
North America Frozen Pizza Market
Processed and Frozen Foods
Freeze Dried Fruits Market
Processed and Frozen Foods
Frozen Tortilla Market
Processed and Frozen Foods
Frozen-Cooked Ready Meals Market
Processed and Frozen Foods
Asia-Pacific Frozen Yogurt Market
Processed and Frozen Foods
Freeze Dried Tropical Fruits Market
Processed and Frozen Foods
Frozen Smoked Salmon Market
Processed and Frozen Foods
Middle East and Africa Frozen Food Market
Processed and Frozen Foods
Frozen Desserts Market
Processed and Frozen Foods
Popsicle Market
Processed and Frozen Foods
Freeze-Dried Food Market
Processed and Frozen Foods
Frozen Pork Belly Market
Processed and Frozen Foods
Kimchi Market