
 Frozen Yogurt Market | 2026-2036
Frozen Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Yogurt Market Analysis
The EU Green Deal is consolidating sustainability expectations across European dairy supply chains, pushing manufacturers toward lower-carbon production models and recyclable packaging commitments. Unilever leverages its global R&D network to reformulate frozen yogurt bases with reduced sugar profiles and plant-derived stabilizers. Danone anchors its competitive position through specialized probiotic strain integration and clean-label positioning across European retail channels. General Mills competes in North American foodservice with operational scale and distributor relationships that secure placement in quick-service restaurant chains.
Frozen yogurt is a frozen dairy dessert manufactured through controlled fermentation of milk with yogurt cultures, followed by blending with sweeteners, stabilizers, and flavoring agents before flash-freezing to maintain viable bacterial counts and creamy texture. The product serves commercial and retail markets as a positioned alternative to ice cream, typically offering lower fat content and live active cultures. Soft serve formats dominate foodservice throughput and machine-based dispensing economics, while hard scoop products sustain margin pools in grocery retail through premium positioning and artisanal flavor extensions. Distribution through retail stores captures the largest volume base, though online channels are gaining traction in direct-to-consumer frozen novelty subscriptions.
FDA standards of identity govern frozen yogurt composition and labeling requirements in the United States, including minimum milkfat thresholds and live culture viability claims that shape product formulation and marketing compliance. EFSA evaluates novel ingredient petitions and health claim substantiations that determine which probiotic or functional positioning statements gain market access across European member states. Stakeholders must monitor evolving sugar reduction mandates and front-of-pack labeling schemes that will determine which formulation architectures retain shelf space and consumer preference in key developed markets.
Market Dynamics
Clean-label formulation mandates from FDA and EFSA are compressing acceptable ingredient decks while probiotic viability standards reshape manufacturing economics across frozen yogurt production networks.
Growth Catalysts
- EU Green Deal packaging mandates:Recyclable cup and spoon requirements accelerate material innovation investments across European manufacturing facilities.
- Self-serve dispensing technology:Automated topping stations and portion-control systems reduce labor costs while capturing consumer customization preferences in United States foodservice.
- Dairy protein fortification:Whey and casein concentrate integration enables elevated protein positioning that commands shelf space in United States grocery retail.
Market Restraints
- Milk powder price volatility:New Zealand and European Union dairy commodity auctions transmit cost instability directly into frozen yogurt base formulations.
- Live culture stability limits:Flash-freezing throughput constraints cap viable bacterial counts in distributed products beyond 500-mile radii from production.
- Front-of-pack labeling schemes:United Kingdom traffic-light systems and French Nutri-Score compress permissible sugar thresholds in formulations targeting mass retail.
Strategic Opportunities
- Direct-to-consumer subscription channels:Flash-frozen novelty delivery models bypass traditional retail slotting fees and capture recurring revenue in United States urban corridors.
- Probiotic strain patent cliffs:Expiring exclusive licenses on Lactobacillus rhamnosus and Bifidobacterium lactis strains open formulation access for mid-tier manufacturers.
- Plant-based base convergence:Coconut and oat protein stabilization technologies enable clean-label vegan positioning that captures lactose-intolerant demand segments.
Industry Challenges
- Clean-label stabilizer sourcing:Locust bean gum and guar supply concentration in India creates procurement bottlenecks during monsoon harvest disruptions.
- Co-manufacturer certification timelines:Third-party organic and kosher audits extend new product launch cycles by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Yogurt Market |
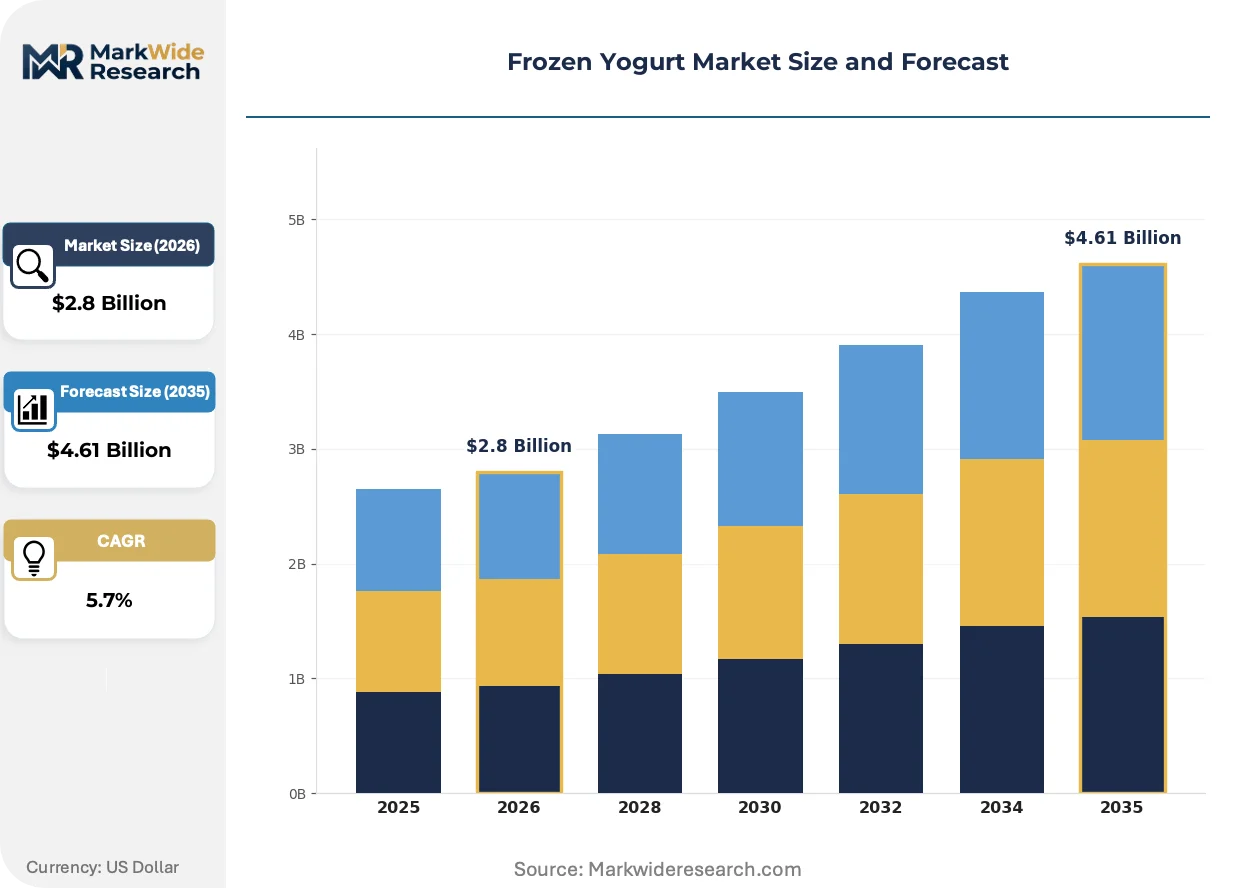
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Serve, Hard Scoop, Frozen Novelties, Toppings Flavor Profile: Chocolate, Vanilla, Strawberry, Mango Distribution Channel: Retail Stores, Foodservice, Online, Vending Machines End User: Individuals, Families, Businesses, Events |
| Companies Covered | Lactalis, Wells Enterprises, Unilever, Yoplait, Nestlé, Danone, General Mills, Chobani, Dairy Farmers of America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Yogurt Market Emerging Trajectories
Formulation science and dispensing automation are compressing production economics while regulatory pressure on sugar and packaging accelerates R&D redirection across manufacturer pipelines.
High-pressure processing for base pasteurization is electrifying microbial safety protocols without thermal degradation of protein structures. United States co-manufacturers are retrofitting existing lines at 15-20% annual adoption rates. This non-thermal pathway is electrifying artisanal brand entry by eliminating the capital barrier of traditional HTST tunnel systems.
EFSA's evolving health claim substantiation requirements for probiotic positioning are forcing clinical trial investments that only multinational dairy conglomerates can absorb. Strain-specific dossier submissions now exceed €2 million per claim attempt. European retail channels are responding by consolidating shelf space behind established players with approved gastrointestinal and immune function language.
Foodservice buyers are unbundling equipment leasing from ingredient supply contracts that historically locked operators into single-brand soft serve systems. Independent frozen yogurt shops in California and Texas are sourcing neutral base mixes from dairy cooperatives while deploying third-party dispensing hardware. This procurement fragmentation is most visible in United States secondary metropolitan markets where operator sophistication outpaces legacy distributor relationships.
Frozen Yogurt Market Segmentation
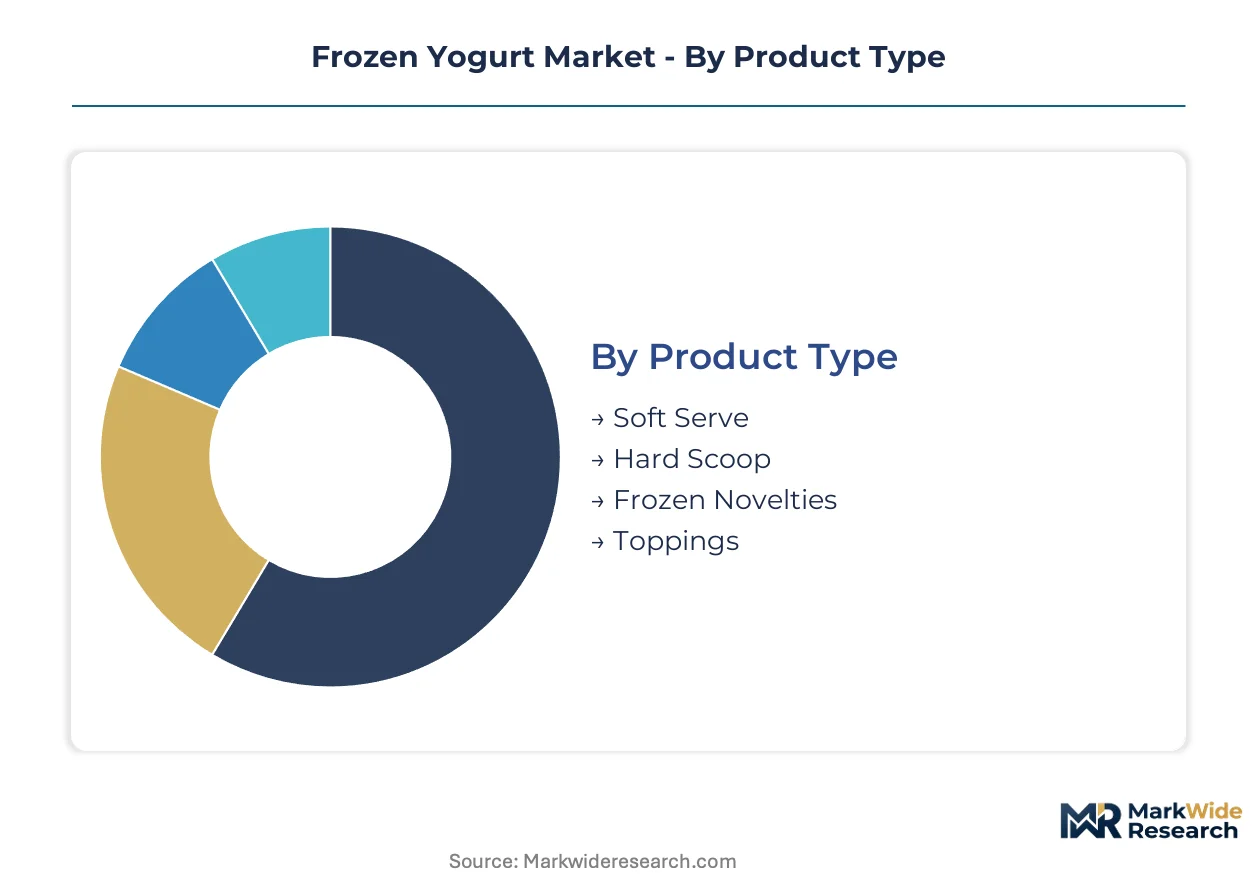
Segmentation in frozen yogurt reveals how formulation formats and dispensing economics split manufacturing investment across divergent margin structures. Supply chain configuration varies dramatically between flash-frozen retail pints and foodservice soft-serve systems.
Product Type:
Base mix concentration determines equipment requirements and co-manufacturer selection across the four format categories.
- Soft Serve:Liquid base mixes require specialized dispensing machines with controlled overrun systems to achieve 30-50% air incorporation. Foodservice operators in the United States concentrate procurement around automated topping stations that reduce labor costs while capturing consumer customization preferences.
- Hard Scoop:Fully frozen pints and quarts sustain premium positioning in grocery retail through artisanal flavor extensions and higher milkfat formulations. Margin pools here exceed soft-serve equivalents due to brand equity capture and extended shelf-life logistics.
- Frozen Novelties:Pre-portioned bars and sandwiches target convenience channels with grab-and-go formats.
- Toppings:Fruit purees, candy inclusions, and dry granola clusters complete the customization ecosystem.
Soft Serve absorbs the bulk of installed capacity; Frozen Novelties is expanding most quickly.
Flavor Profile:
Flavor concentration patterns reflect raw material sourcing geography and clean-label formulation constraints.
- Vanilla:Madagascar and Tahitian bean extract supply chains anchor premium positioning, with natural vanilla commanding fivefold price premiums over synthetic vanillin. United States retail channels favor bourbon vanilla profiles for their aromatic complexity.
- Chocolate:Cocoa butter content thresholds separate premium positioning from economy tiers, with single-origin Ecuadorian and Ghanaian sourcing gaining traction in European clean-label formulations.
- Strawberry:Seasonal fruit puree sourcing from California and Florida creates harvest-dependent supply windows.
- Mango:Alphonso and Ataulfo varietal concentrates from India and Mexico supply tropical positioning.
Vanilla commands the deepest supply relationships; Mango is climbing the fastest as tropical flavor adoption accelerates.
Distribution Channel:
Channel economics determine cold-chain investment intensity and margin retention for manufacturers.
- Retail Stores:Grocery and mass merchandiser freezer cases capture the largest volume base, though slotting fees and trade promotion spending compress net margins. United States expansion continues driving category momentum through premium private-label placement.
- Foodservice:Quick-service restaurant chains and self-serve frozen yogurt shops in the United States leverage operational scale and distributor relationships for machine-based dispensing economics.
- Online:Direct-to-consumer frozen novelty subscriptions bypass traditional retail slotting fees and capture recurring revenue in urban corridors.
- Vending Machines:Automated dispensing in airports and universities extends reach with limited labor overhead.
Retail Stores dominate volume throughput; Online channels are gaining share fastest through subscription model traction.
End User:
User segmentation aligns consumption occasion with portion sizing and price sensitivity thresholds.
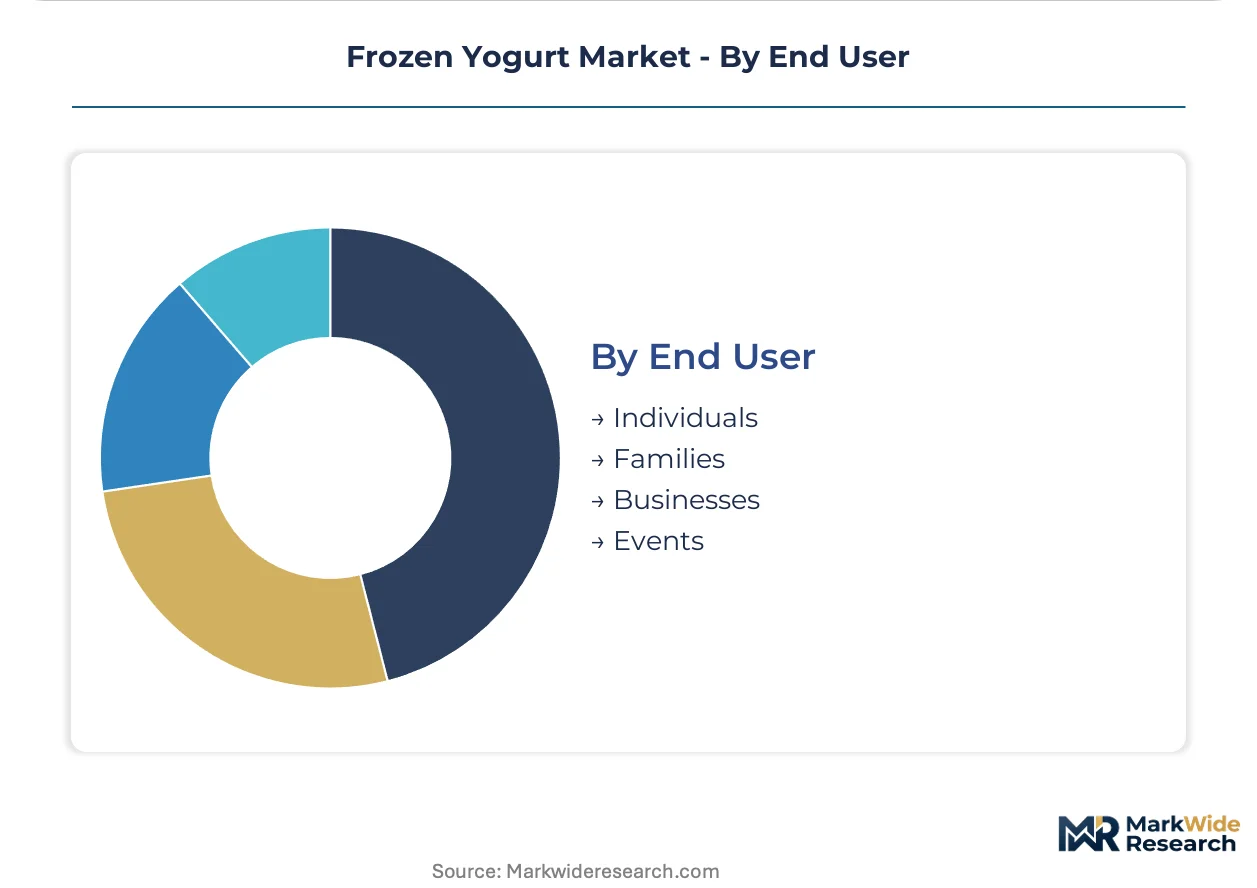
- Individuals:Single-serve cups and cones target health-conscious consumers seeking lower-fat dessert alternatives with controlled portion sizes.
- Families:Multi-quart take-home formats emphasize value pricing and crowd-pleasing flavor assortments.
- Businesses:Corporate catering and office pantry programs demand bulk packaging with extended thaw stability.
- Events:Wedding and festival catering requires mobile dispensing equipment and customized flavor rotations.
Families absorb the bulk of retail volume; Events is expanding most quickly as experiential catering demand rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors frozen yogurt innovation through its dense network of self-serve chains and health-conscious consumer bases. The metropolitan corridor channels R&D investment toward clean-label formulations and automated dispensing systems.
United States
Self-serve frozen yogurt chains and grocery retail expansion drive category momentum across California, Texas, and Florida. FDA standards of identity govern minimum milkfat thresholds and live culture viability claims that shape product formulation. Dallas-Fort Worth concentrates foodservice equipment manufacturing for automated topping stations and portion-control systems.
Germany
Clean-label positioning and probiotic strain integration command premium shelf space in Berlin and Munich retail channels. EFSA evaluates novel ingredient petitions and health claim substantiations that determine market access for functional positioning statements. Bavaria hosts specialized dairy cooperatives reformulating bases with reduced sugar profiles and plant-derived stabilizers.
France
Artisanal flavor extensions and single-origin cocoa sourcing gain traction in Parisian premium grocery formats. French Nutri-Score front-of-pack labeling compresses permissible sugar thresholds in mass retail formulations. The Auvergne-Rhône-Alpes corridor anchors dairy protein fortification research through specialized whey and casein concentrate integration.
United Kingdom
Traffic-light front-of-pack labeling systems and sugar reduction mandates reshape formulation architectures for grocery retail. The country's national food standards regulator enforces compositional requirements that determine shelf space retention. Greater London concentrates direct-to-consumer frozen novelty subscription logistics that bypass traditional slotting fees.
Canada
Health-conscious consumers in Toronto and Vancouver embrace frozen yogurt as a lower-fat dessert alternative with live active cultures. Health Canada governs dairy product standards and labeling requirements that align with cross-border trade protocols. Ontario's dairy processing corridor supplies neutral base mixes to independent operators deploying third-party dispensing hardware.
Frozen Yogurt Market Vendor Landscape
Premium-margin players sit above commodity-margin players across formulation sophistication and probiotic certification tiers. The vendor base organizes around multinational dairy conglomerates with clinical trial absorption capacity, mid-tier manufacturers exploiting patent cliffs on specialized strains, and regional dairy cooperatives supplying neutral bases to fragmented foodservice operators. Three archetypes dominate: R&D-intensive multinationals pursuing EFSA-approved health claims, private-label specialists serving grocery retail slotting fee environments, and equipment-integrated service providers locking in operator supply contracts. Competitive moves concentrate on co-manufacturer certification acceleration and direct-to-consumer channel bypass strategies.
Within the R&D-intensive multinational tier, Unilever and Danone exemplify players absorbing EFSA strain-specific dossier submission costs exceeding two million euros per claim attempt. General Mills occupies a position representing North American foodservice scale advantages through distributor relationships securing quick-service restaurant chain placement. Among dairy cooperative suppliers, Dairy Farmers of America anchors the neutral base mix segment serving independent operators unbundling equipment leasing from ingredient supply contracts.
| Leading Market Players |
|---|
| Lactalis |
| Wells Enterprises |
| Unilever |
| Yoplait |
| Nestlé |
| Danone |
| General Mills |
| Chobani |
| Dairy Farmers of America |
| Others |
Supply Flow & Price Mechanics
Captive integration into proprietary probiotic strain development anchors both supply security and premium pricing power for manufacturers absorbing EFSA dossier costs exceeding two million euros per health claim submission.
Pricing Analysis
Throughput-based pricing tied to viable bacterial count retention anchors soft-serve base contracts, with three-tier pricing structure across premium, standard, and economy levels separating EFSA-certified probiotic positioning from clean-label standard tiers and commodity private-label economy offerings. Price differentiation hinges on certification grade and volume scale, with cost compression in economy tiers intensifying because of milk powder auction volatility. Quick-service restaurant chains exhibit highest price sensitivity, while premium grocery retail maintains lowest sensitivity due to brand equity capture.
Supply Chain Analysis
Single-source vulnerability sits with Indian monsoon-dependent harvests for locust bean gum and guar stabilizers that feed clean-label formulation pipelines. Base production draws from United States, Germany, and France for dairy protein concentrate and specialized fermentation capacity. Raw material dependencies center on New Zealand and European Union milk powder auctions, Madagascar vanilla extract, and Indian hydrocolloid harvests. Tariff exposure on cocoa butter and tropical fruit purees creates margin instability. Distribution runs through temperature-controlled co-manufacturer networks into retail freezer cases and foodservice equipment leasing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Frozen yogurt operates as a cost-of-compliance market where EFSA health claim substantiation requirements erect barrier-to-entry moats favoring conglomerates with clinical trial absorption capacity over mid-tier challengers.
For Market Incumbents: Cement EFSA-approved strain exclusivity through patent portfolio extension and accelerated dossier submission timelines before Lactobacillus rhamnosus and Bifidobacterium lactis patent cliffs open formulation access. Deepen backward integration into dairy protein concentrate production across Bavaria and Auvergne-Rhône-Alpes corridors to neutralize milk powder auction volatility threatening margin stability in base mix manufacturing.
For New Entrants and Emerging Players: EU Green Deal packaging mandates in Germany and France open a window for recyclable cup and spoon material innovators to capture shelf space ahead of incumbent retrofit cycles. Target direct-to-consumer subscription logistics in Greater London and urban United States corridors as the most penetrable channel bypassing retail slotting fees, deploying flash-frozen novelty delivery models with recurring revenue anchoring initial market presence.
For Investors and Strategic Acquirers: Exit pathways concentrate in equipment-integrated service providers with locked-in operator supply contracts and established co-manufacturer certification timelines. Long-term viability favors players with EFSA-approved gastrointestinal and immune function language securing European retail consolidation. Watch probiotic strain patent cliff expiration velocity as the inflection signal determining mid-tier manufacturer formulation access and competitive pressure intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Health Claim Dossier Submission | Strain-specific approvals exceeding two million euros secure exclusive European retail shelf space. |
| Direct-to-Consumer Subscription Launch | Flash-frozen novelty delivery models bypass traditional retail slotting fees in urban corridors. |
| Co-Manufacturer Certification Acceleration | Organic and kosher audit compression reduces new product launch cycles by four to six months. |
| Plant-Based Base Convergence | Coconut and oat protein stabilization technologies capture lactose-intolerant demand segments. |
| Self-Serve Dispensing Technology Deployment | Automated topping stations reduce labor costs while capturing customization preferences in United States foodservice. |
Methodological Framework
Independent corroboration across FDA standards of identity filings, EFSA novel ingredient petitions, and European dairy cooperative production disclosures underwrites the qualitative findings. Primary interviews with frozen yogurt brand managers, co-manufacturer operations directors, retail category buyers, and foodservice equipment leasing specialists combined with secondary validation through customs records, Nielsen retail audit data, and SEC filings from publicly traded dairy conglomerates. Bottom-up volume triangulation across product type, flavor profile, and distribution channel segmentation intersects with top-down value reconciliation against dairy commodity auction benchmarks.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by soft-serve versus hard-scoop format, probiotic certification tier, and regional regulatory cluster. CAGRs derive from installed capacity utilization rates, cold-chain logistics expansion velocity, and front-of-pack labeling scheme adoption curves. Modeled inputs include milk powder auction price volatility indices, EFSA health claim approval timelines, and self-serve dispensing equipment penetration rates across United States metropolitan markets.
Caveats apply where EFSA health claim rejection rates, Indian monsoon harvest disruptions, or United Kingdom traffic-light labeling threshold revisions could materially shift the outlook. Forecasts reflect documented assumptions on live culture stability limits and flash-freezing throughput constraints. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Global Frozen Fish and Seafood Market
Processed and Frozen Foods
Cold Storage Market
Processed and Frozen Foods
North America French Fries Market
Processed and Frozen Foods
Frozen Pork Belly Market
Processed and Frozen Foods
Frozen-Cooked Ready Meals Market
Processed and Frozen Foods
IQF Food Products Market
Processed and Frozen Foods
Frozen Bread Market
Processed and Frozen Foods
Frozen Processed Meat Market
Processed and Frozen Foods
Frozen Meat Market
Processed and Frozen Foods
Frozen Meat and Fish Market
Processed and Frozen Foods
Vegan Frozen Pizza Market
Processed and Frozen Foods
Europe Ice Cream Market
Processed and Frozen Foods
Freeze Dried Melt Market
Processed and Frozen Foods
Low-Fat Low-Cholesterol Foods Market
Processed and Frozen Foods
Asia Pacific Freeze Dried Product Market
Processed and Frozen Foods
Processed and Frozen Vegetables Market