
 Turkey Cold Storage Market | 2026-2036
Turkey Cold Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Turkey Cold Storage Market Insights
Aftermarket temperature monitoring services is reconfiguring margin pools away from pure warehouse leasing toward integrated cold chain management contracts. Ekol Logistics leverages its multi-modal network to anchor pharmaceutical distribution across Anatolia. DHL Logistics competes through bonded cold storage capacity at Istanbul's logistics corridors. Borusan Lojistik sustains heavy investment in automated racking systems for frozen food consolidation.
Turkey cold storage denotes climate-controlled warehousing infrastructure operating between minus 25 degrees Celsius and plus 15 degrees Celsius, utilizing vapor-compression refrigeration cycles with ammonia or CO2 refrigerants to arrest microbiological degradation of temperature-sensitive goods. The primary commercial purpose centers on extending shelf life for perishable imports and exports transiting Turkey's dual-continent position. Meat and dairy segments dominate product-type revenue due to structural reliance on imported livestock feed and centralized slaughterhouse regulations. Pharmaceutical storage represents the fastest-growing application category, driven by biologics distribution requirements and hospital network expansion. Mechanical refrigeration technology occupies the majority of installed capacity, though cryogenic freezing installations are accelerating in seafood export zones.
Turkish Ministry of Agriculture and Forestry inspection protocols, alongside BIS-equivalent cold chain certification standards, mandate continuous temperature logging and HACCP documentation for cross-provincial food shipments. Energy efficiency regulations from the country's environmental ministry are forcing ammonia system retrofits and solar-integrated cooling investments. Stakeholders must monitor whether Ankara extends carbon reporting obligations to logistics real estate, as this would reshape capital allocation toward greenfield facilities with lower operational compliance costs.
Market Dynamics
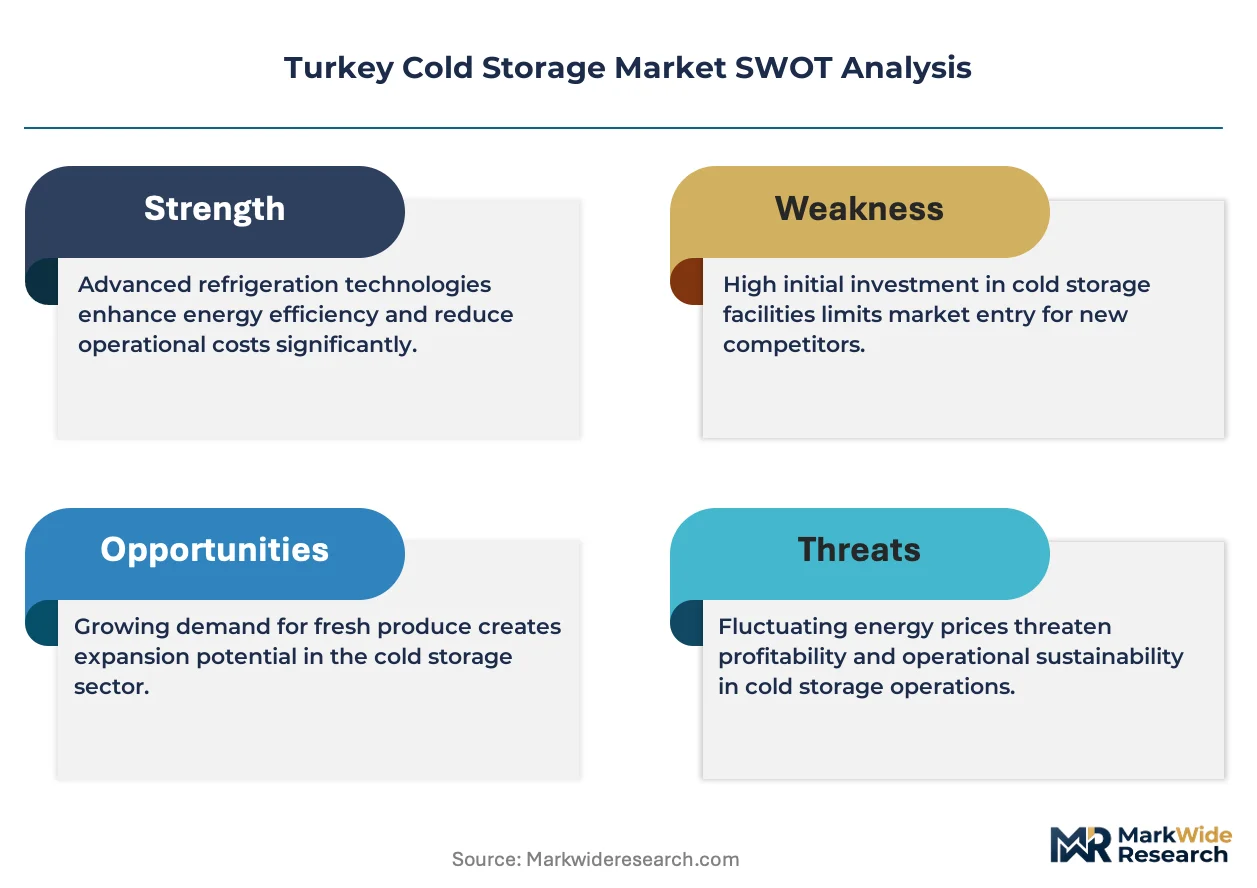
Turkish cold storage infrastructure faces a structural inflection point as ammonia system retrofits collide with solar-integrated cooling mandates and pharmaceutical compliance requirements tighten simultaneously.
Growth Catalysts
- Biologics Distribution Expansion:Turkish hospital network modernization is accelerating demand for validated 2-8°C pharmaceutical storage capacity across Anatolia.
- EU Green Deal Alignment Pressure:Export-oriented food processors are upgrading cold chain documentation to satisfy EFSA-equivalent traceability standards for European market access.
- Solar-Ammonia Hybrid Systems:Energy efficiency regulations from the environmental ministry are forcing adoption of photovoltaic-integrated refrigeration at port-linked distribution hubs.
Market Restraints
- Capital Intensity of Retrofits:Legacy freon-based facilities require complete refrigeration circuit replacement, compressing returns for mid-scale operators.
- Imported Component Dependency:Compressor and control system supply concentrates in German and Italian manufacturing bases, exposing Turkish operators to euro-denominated input volatility.
- Grid Instability in Eastern Anatolia:Unreliable electricity supply in southeastern provinces limits automated cold storage deployment regardless of demand fundamentals.
Strategic Opportunities
- Black Sea Coastal Expansion:Underdeveloped frozen seafood export infrastructure at Samsun and Trabzon ports offers first-mover positioning for integrated cold chain operators.
- Blockchain Temperature Verification:Convergence of distributed ledger technology with IoT sensor networks is enabling premium-priced custody documentation for high-value pharmaceutical shipments.
- Direct-to-Retailer Consolidation:Bypassing traditional wholesale markets through dedicated cold chain corridors to Migros and CarrefourSA distribution centers is capturing margin previously lost to intermediaries.
Industry Challenges
- Certified Technician Scarcity:Ammonia system operation and maintenance expertise remains concentrated in Istanbul and Izmir, constraining facility expansion to interior provinces.
- HACCP Documentation Burden:Turkish Ministry of Agriculture and Forestry inspection protocols require continuous multi-point temperature logging, creating compliance overhead that disadvantages smaller warehouse operators.
- Legacy Warehouse Integration:Automated racking and warehouse management system deployment in 1990s-era structures faces spatial constraints and foundation load limitations.
Report Scope
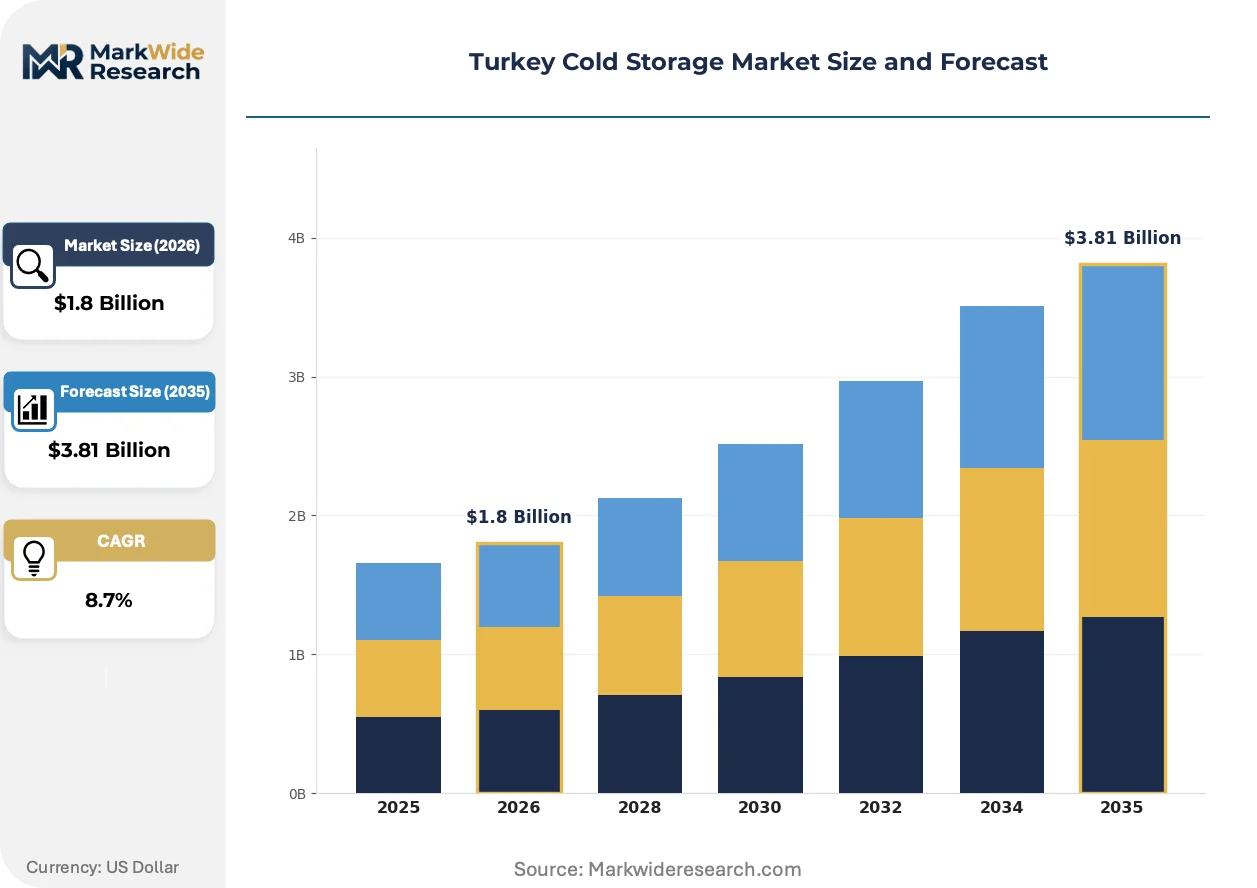
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkey Cold Storage Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Meat, Dairy Application: Food Preservation, Pharmaceutical Storage, Floral Storage, Biotech End User: Restaurants, Supermarkets, Wholesalers, Logistics Providers Technology: Mechanical Refrigeration, Cryogenic Freezing, Insulation, Temperature Control |
| Companies Covered | Ekol Logistics, DHL Logistics, Havi Logistics, Yusen Logistics, Polar Express cold chain logistics, Fasdat Gida Dagitim Logistics, Netlog Logistics, Borusan Lojistik, Arkas Lojistik, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkey Cold Storage Market Trends and Innovations
Digital instrumentation and renewable energy integration are compressing operational cost structures while regulatory documentation requirements reshape competitive differentiation criteria across Turkish cold storage.
IoT-enabled temperature monitoring systems are digitizing custody verification workflows through continuous cloud-logged sensor networks. Pharmaceutical distributors and export-oriented meat processors are adopting these platforms fastest, driven by Turkish Ministry of Agriculture and Forestry audit requirements. The technology is digitizing compliance documentation from paper-based batch records to real-time accessible dashboards, reducing inspection preparation labor and enabling premium service tier pricing.
Turkish environmental ministry energy efficiency regulations are mandating ammonia refrigerant conversion and solar thermal integration for facilities above defined capacity thresholds. Industrial consequence includes accelerated depreciation schedules for non-compliant assets and capital flight toward greenfield construction. Seafood export zones along the Aegean coast are most affected, with processors consolidating into purpose-built facilities rather than retrofitting aging infrastructure.
Consolidated procurement of integrated cold chain management contracts is displacing discrete warehouse leasing arrangements among multinational food processors. Third-party logistics providers are capturing multi-year agreements bundling transportation, storage, and compliance documentation. This shift is most visible in Istanbul's logistics corridors, where bonded cold storage capacity anchors pharmaceutical distribution contracts with predictable revenue streams.
Turkey Cold Storage Market Segmentation
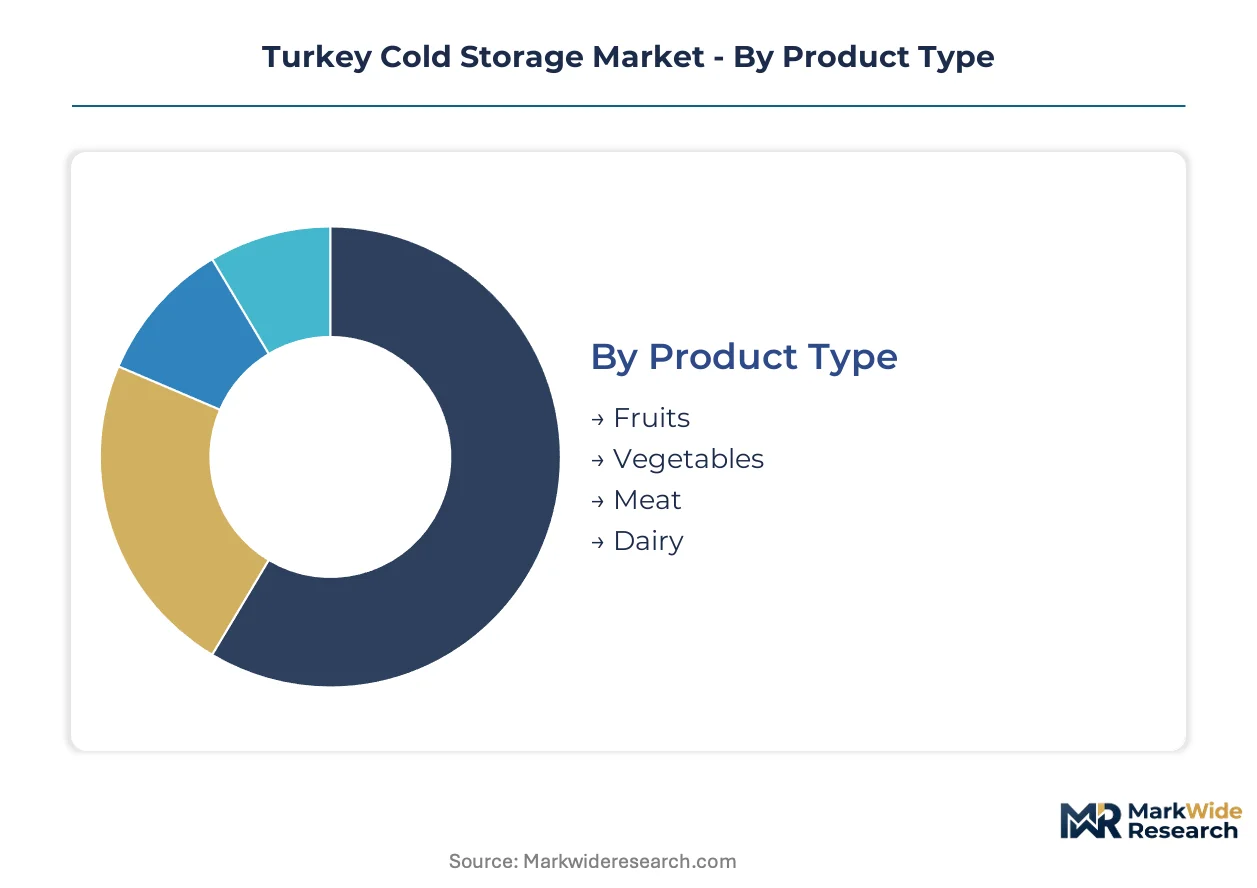
Turkey's cold storage market segments reflect divergent compliance burdens and capital requirements across food safety and pharmaceutical custody chains. Understanding these divisions clarifies where ammonia retrofits, solar integration mandates, and HACCP documentation costs concentrate operational pressure.
Product Type:
Mature categories dominate revenue while emerging segments face steeper regulatory compliance ramps.
- Meat:Centralized slaughterhouse regulations in Turkey mandate continuous minus 18°C freezing for cross-provincial distribution. Demand clusters around Istanbul and Bursa processing corridors where EU export certification requirements drive investment in automated blast freezing capacity.
- Dairy:Fresh cheese and yogurt products require precise plus 2°C to plus 6°C cold chains from production through retail. Aegean coast processors near Izmir anchor the strongest demand, constrained by Turkish Ministry of Agriculture and Forestry inspection protocols for raw milk traceability.
- Fruits:Citrus and stone fruit exports to Russia and Middle Eastern markets drive seasonal capacity utilization spikes.
- Vegetables:Tomato paste and frozen vegetable processors in the Marmara region absorb dedicated freezer infrastructure.
Meat handles the majority of throughput; pharmaceutical-adjacent dairy applications are expanding most quickly on share.
Application:
Cost tier differentiation separates commodity food preservation from premium-validated pharmaceutical custody services.
- Food Preservation:Traditional cold chain applications for perishable imports and exports transiting Turkey's dual-continent position. Istanbul port-linked distribution infrastructure serves export-oriented processors facing EU Green Deal alignment pressure for EFSA-equivalent traceability documentation.
- Pharmaceutical Storage:Validated 2-8°C capacity for biologics distribution across Anatolia's modernizing hospital networks. Turkish healthcare logistics modernization is accelerating demand faster than food segments, though facility certification costs remain prohibitive for mid-scale operators.
- Floral Storage:Cut flower exports from Antalya greenhouse clusters to European markets require humidity-controlled plus 1°C to plus 3°C environments.
- Biotech:Emerging cell therapy and diagnostic reagent storage demands minus 80°C cryogenic backup systems concentrated in Ankara research corridors.
Food Preservation retains the largest installed base; Pharmaceutical Storage is gaining share fastest as hospital network expansion outpaces traditional cold chain growth.
End User:
Customer type determines contract structure, with integrated logistics providers capturing multi-year agreements while fragmented wholesalers face margin compression.
- Logistics Providers:Third-party operators bundling transportation, storage, and compliance documentation under cold chain management contracts. Ekol Logistics and DHL Logistics anchor pharmaceutical distribution across Anatolia through bonded capacity at Istanbul's logistics corridors.
- Supermarkets:Migros and CarrefourSA distribution centers are consolidating direct-to-retailer cold chain corridors, bypassing traditional wholesale markets.
- Wholesalers:Traditional intermediary operators in Istanbul's Halic and Izmir's Kemeralti markets face HACCP documentation overhead that disadvantages smaller warehouse footprints.
- Restaurants:Hotel and food service chains in tourism-dependent Antalya and Bodrum generate seasonal demand spikes for frozen protein consolidation.
Logistics Providers control the largest contract value; Supermarkets are climbing the fastest as procurement centralization displaces wholesale intermediation.
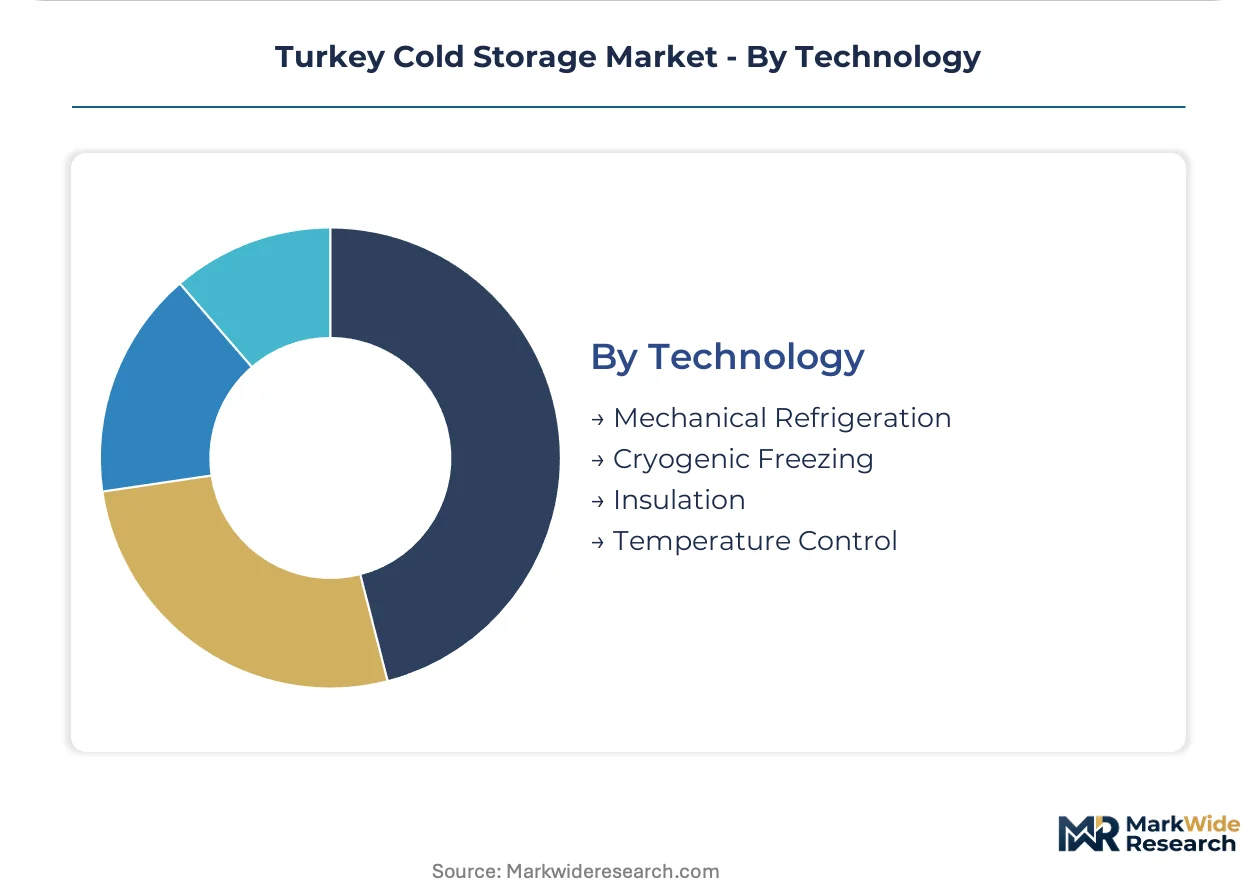
Technology:
Supply concentration in German and Italian compressor manufacturing shapes technology adoption timelines for Turkish operators exposed to euro-denominated input volatility.
- Mechanical Refrigeration:Vapor-compression systems with ammonia or CO2 refrigerants occupying the majority of installed capacity. Turkish environmental ministry energy efficiency regulations are forcing retrofits away from legacy freon-based circuits, compressing returns for mid-scale operators with 1990s-era infrastructure.
- Temperature Control:IoT-enabled sensor networks digitizing custody verification from paper-based batch records to real-time dashboards. Pharmaceutical distributors adopt these platforms fastest to satisfy Turkish Ministry of Agriculture and Forestry audit requirements.
- Cryogenic Freezing:Liquid nitrogen and carbon dioxide blast systems accelerating in seafood export zones along the Aegean coast for ultra-low minus 40°C processing.
- Insulation:Polyurethane panel and vacuum-insulated envelope upgrades mandated for greenfield construction as energy efficiency thresholds tighten.
Mechanical Refrigeration underpins the majority of capacity; Temperature Control is expanding most quickly as compliance documentation requirements reshape competitive differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Turkish sub-regions, with Istanbul-based buyers absorbing premium pharmaceutical storage rates while Anatolian interior markets remain acutely price-sensitive to per-unit warehousing costs.
Marmara Region
Istanbul and Bursa processing corridors anchor the majority of validated pharmaceutical capacity and EU-export meat certification infrastructure. Turkish Ministry of Agriculture and Forestry inspection protocols concentrate enforcement resources here, accelerating HACCP documentation digitization among bonded warehouse operators at Ambarli and Haydarpasa port zones.
Aegean Region
Izmir-centered dairy processors and seafood exporters drive seasonal capacity utilization spikes for frozen protein consolidation. The country's environmental ministry energy efficiency regulations are forcing ammonia retrofits at aging facilities near Aliaga port, pushing processors toward greenfield construction rather than circuit replacement.
Mediterranean Region
Antalya greenhouse clusters generate cut flower export demand for humidity-controlled plus 1°C to plus 3°C environments. Tourism-dependent hotel and food service chains in Bodrum create intermittent frozen storage requirements that challenge year-round facility economics.
Black Sea Region
Samsun and Trabzon ports offer underdeveloped frozen seafood export infrastructure with limited automated cold storage deployment. Grid instability across southeastern provinces constrains facility expansion regardless of catch volume growth from regional fishing cooperatives.
Central Anatolia
Ankara research corridors host emerging biotech storage demand for minus 80°C cryogenic backup systems. Hospital network modernization here outpaces local cold chain infrastructure, creating logistics gaps that Istanbul-based operators must bridge through extended distribution contracts.
Turkey Cold Storage Market Competitive Landscape
Integrated logistics providers and port-centric warehouse operators split the market between multi-year bundled contracts and transactional storage leases. Turkish cold storage exhibits tiered concentration, with bonded capacity at Istanbul logistics corridors commanding premium pricing while Anatolian interior markets fragment across mid-scale regional players. Three archetypes dominate: multinational third-party logistics bundling transportation and compliance documentation, Turkish industrial conglomerates leveraging captive real estate portfolios, and specialized pharmaceutical distributors with validated temperature infrastructure. Competitive moves center on ammonia system retrofits to satisfy environmental ministry mandates and solar-integrated cooling investments at port-linked distribution hubs.
Within the multinational logistics tier, Ekol Logistics and DHL Logistics occupy positions anchoring pharmaceutical distribution across Anatolia through bonded capacity at Istanbul's logistics corridors. Among Turkish industrial conglomerates, Borusan Lojistik exemplifies the capital-intensive archetype investing in automated racking systems for frozen food consolidation. These three named entities represent distinct strategic postures: Ekol leverages multi-modal network density, DHL competes through customs-advantaged cold storage positioning, and Borusan sustains heavy equipment deployment for temperature-controlled consolidation.
| Leading Market Players |
|---|
| Ekol Logistics |
| DHL Logistics |
| Havi Logistics |
| Yusen Logistics |
| Polar Express cold chain logistics |
| Fasdat Gida Dagitim Logistics |
| Netlog Logistics |
| Borusan Lojistik |
| Arkas Lojistik |
| Others |
Pricing and Supply Chain Analysis
Istanbul's bonded logistics corridors concentrate validated pharmaceutical cold storage capacity, granting operators at Ambarli and Haydarpasa port zones substantial pricing power over Anatolian interior markets where automated facility deployment remains sparse. Turkish Ministry of Agriculture and Forestry inspection protocols amplify this geographic rent by forcing HACCP-compliant documentation investments that smaller regional warehouses cannot absorb.
Pricing Analysis
Temperature monitoring service contracts now drive lifetime value beyond pure warehouse leasing, with integrated cold chain management agreements capturing multi-year revenue streams from pharmaceutical distributors. Price differentiation separates EU-export certified facilities from domestic-grade operations, while ammonia retrofit mandates compress margins for legacy freon-based operators in Izmir and Bursa. Cost compression in mid-scale frozen food consolidation is intensifying as solar-integrated cooling investments raise entry barriers. Logistics providers exhibit the lowest price sensitivity due to bundled contract structures, whereas traditional wholesalers in Halic and Kemeralti markets face acute per-unit warehousing cost pressure.
Supply Chain Analysis
Compressor and control system manufacturing concentrates in Germany and Italy, exposing Turkish operators to euro-denominated input volatility that feeds directly into facility expansion timelines. Ammonia refrigerant circuits, IoT sensor networks, and automated racking systems draw from these European supply bases, with delivery cycles tethered to continental production schedules. Single-source vulnerability in specialized pharmaceutical validation equipment constrains rapid capacity scaling for biologics storage. Distribution runs through port-linked consolidation hubs at Istanbul, Izmir, and Mersin before final-mile deployment across Anatolia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Turkey's cold storage market rewards service-attach strategies, with aftermarket temperature monitoring and compliance documentation expanding faster than pure warehouse leasing as pharmaceutical custody requirements tighten.
For Market Incumbents: Insulate core revenue by converting transactional storage leases into multi-year integrated cold chain management contracts bundling transportation and HACCP documentation. Vertical integration into captive solar-ammonia hybrid systems at port-linked distribution hubs defends margin position against environmental ministry retrofit mandates that threaten legacy freon-based assets. For New Entrants and Emerging Players: Black Sea coastal expansion at Samsun and Trabzon ports offers first-mover positioning where automated cold storage deployment remains underdeveloped despite growing frozen seafood export volume. Blockchain temperature verification for high-value pharmaceutical shipments provides a differentiated go-to-market angle against established Istanbul-based operators. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors logistics providers with validated pharmaceutical infrastructure and renewable-integrated cooling systems over commodity frozen food warehouse operators. Facilities with Turkish Ministry of Agriculture and Forestry pre-certification and solar-ammonia hybrid installations represent priority acquisition targets. The signal to watch is Ankara's potential extension of carbon reporting obligations to logistics real estate, which would accelerate capital flight toward greenfield assets.| Strategic Initiative | Industry Significance |
|---|---|
| Solar-Ammonia Hybrid Retrofit | Environmental ministry mandates force circuit replacement at aging Aegean coast facilities near Aliaga port. |
| Blockchain Temperature Verification | Distributed ledger integration with IoT sensors enables premium custody documentation for biologics shipments. |
| Direct-to-Retailer Consolidation | Bypassing traditional wholesale markets captures margin previously lost to Halic and Kemeralti intermediaries. |
| Black Sea Coastal Expansion | Underdeveloped frozen seafood infrastructure at Samsun and Trabzon offers first-mover positioning. |
| Certified Technician Training Programs | Ammonia system expertise concentration in Istanbul constrains interior province facility expansion. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across Turkey's cold storage value chain, including cold chain logistics directors at third-party providers, pharmaceutical distribution managers at hospital networks, frozen food procurement leads at Migros and CarrefourSA, and maintenance engineers at ammonia-based facilities. Secondary validation drew from Turkish Ministry of Agriculture and Forestry inspection protocols, environmental ministry energy efficiency regulations, customs trade data for refrigerated cargo flows, and SEC filings of multinational logistics operators with Turkish subsidiaries. Bottom-up facility capacity assessments were triangulated against top-down pharmaceutical and food industry consumption estimates.
Calibration against historical capacity utilization rates and regulatory compliance cost trajectories anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type, application category, end-user archetype, and technology tier, with particular attention to pharmaceutical storage certification levels and renewable energy integration status. CAGRs were derived from installed capacity expansion pipelines, hospital network modernization schedules, and export-oriented food processor investment plans.
The forecast holds incumbent behavior within observed patterns; aggressive moves by German and Italian equipment suppliers to establish local manufacturing partnerships would shift outcomes. Cross-checking against Turkish Statistical Institute industrial production indices and EU Green Deal implementation timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
North America Frozen Desserts Market
Processed and Frozen Foods
Frozen Mackerel Market
Processed and Frozen Foods
United States Frozen Yogurt Market
Processed and Frozen Foods
Global Frozen Breakfast Entrees/Sandwiches Market
Processed and Frozen Foods
United States Frozen Pizza Market
Processed and Frozen Foods
Cold Storage Market
Processed and Frozen Foods
Frozen Potato Market
Processed and Frozen Foods
Frozen Chicken Market
Processed and Frozen Foods
Latin America Frozen Finger Chips Market
Processed and Frozen Foods
Europe Ice Cream Market
Processed and Frozen Foods
Frozen Novelty Market
Processed and Frozen Foods
South America Frozen Desserts Market
Processed and Frozen Foods
Frozen Food and Snacks Market
Processed and Frozen Foods
Indonesia Frozen Food Market
Processed and Frozen Foods
Processed and Frozen Vegetables Market
Processed and Frozen Foods
Middle East and Africa Freeze-Dried Product Market