
 Cold Storage Market | 2026-2036
Cold Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Storage Market Intelligence
The capability gap in automation and network scale between global consolidators and regional specialists is reorganizing market dynamics. Lineage Logistics leverages its extensive automated warehouse network to offer integrated services at scale. Americold Logistics competes on its vast geographic footprint and deep relationships within the food production sector. In contrast, providers like RLS Logistics differentiate through specialized services for niche food and beverage clients.
Cold storage refers to the preservation of goods in a temperature-controlled supply chain, typically involving insulated structures. These facilities maintain specific temperature ranges, from chilled (+2°C to +10°C) to frozen (-18°C and below), to inhibit spoilage and maintain product efficacy. While the food & beverage segment constitutes the largest volume, the pharmaceuticals end-user category commands premium pricing due to stringent validation requirements. Value is shifting from basic storage services toward integrated logistics and real-time monitoring solutions.
Regulatory frameworks like the US FDA's Food Safety Modernization Act and EU food hygiene regulations mandate strict temperature documentation. Simultaneously, refrigerant use is governed by environmental rules such as the EPA's SNAP program in the United States and the EU F-Gas Regulation. Future success will depend on a provider's ability to balance capital investments in sustainable technology with the operational demands of expanding service offerings.
Market Dynamics
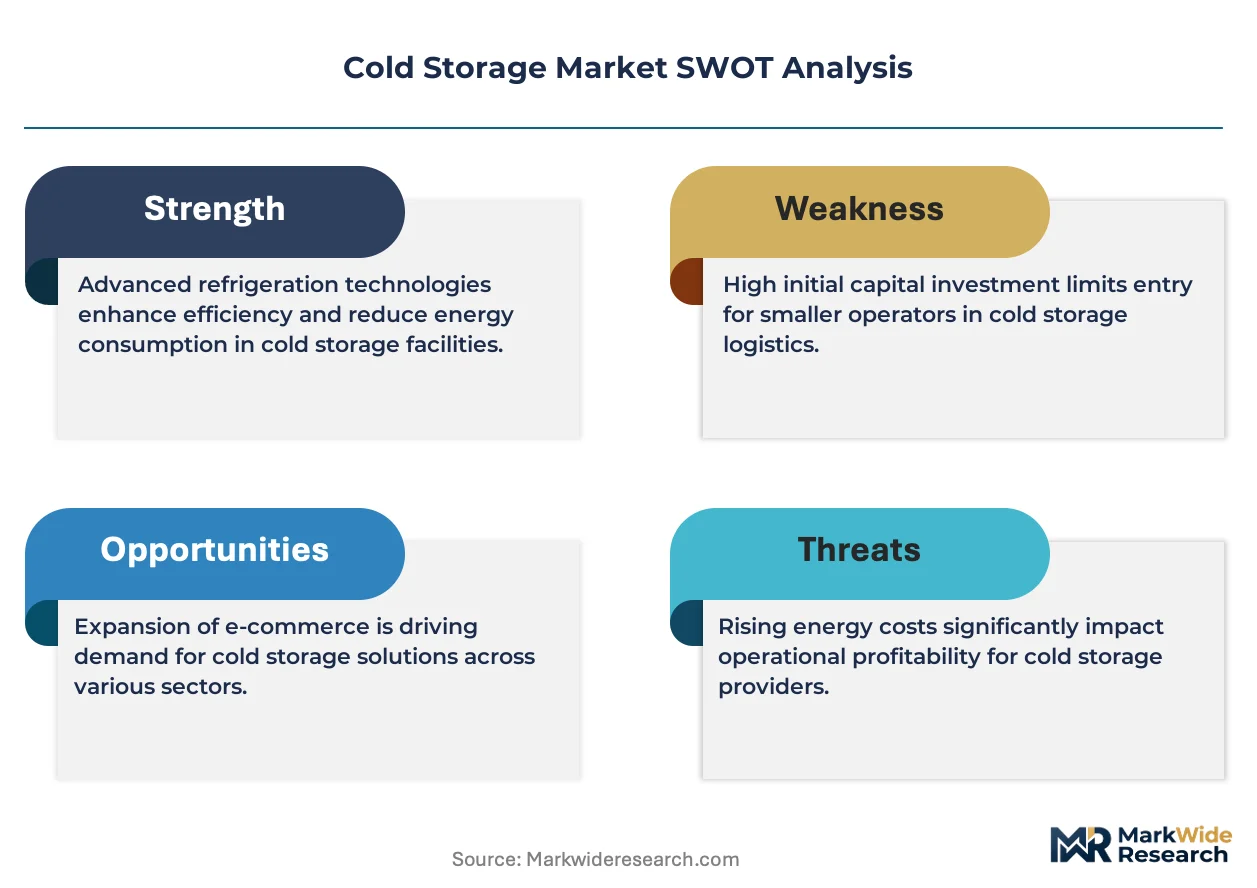
The convergence of stringent environmental regulations on refrigerants and escalating demands for validated, temperature-controlled logistics from the pharmaceutical sector is the central force reshaping the cold storage market. This dual pressure compels operators to invest in both sustainable technology and advanced service capabilities.
Growth Catalysts
- Pharmaceutical Sector Expansion:The proliferation of biologics, vaccines, and cell therapies necessitates investment in ultra-low temperature (ULT) and cryogenic storage capabilities, commanding premium service fees and driving specialized infrastructure development.
- Food Waste Reduction Policies:Government initiatives in countries like India aim to reduce post-harvest losses by promoting modern cold chain infrastructure, creating significant demand for new facility construction and logistics services.
- IoT Integration:The need to comply with food safety regulations, such as the US FDA's Food Safety Modernization Act, accelerates the adoption of IoT sensors for real-time temperature monitoring and supply chain visibility.
Market Restraints
- Energy Price Volatility:The high energy consumption of refrigeration systems exposes facility operators to significant financial risk from fluctuating electricity prices, particularly impacting profitability in markets across Europe.
- Refrigerant Phase-Outs:Environmental mandates like the EU F-Gas Regulation force costly transitions away from hydrofluorocarbons (HFCs) to natural alternatives like ammonia or CO2, which require specialized equipment and safety protocols.
- Land Scarcity and Cost:Limited availability and high prices for industrial land near major urban consumption centers in geographies such as Japan and Western Europe constrain the development of new, large-scale cold storage facilities.
Strategic Opportunities
- Last-Mile Cold Chain Services:Developing smaller, urban-centric refrigerated facilities to support direct-to-consumer grocery, pharmaceutical, and meal-kit delivery services opens a new, high-growth market segment for specialized providers.
- Emerging Market Infrastructure:Significant deficits in modern cold chain capacity across Southeast Asia and parts of Africa present a major white-space opportunity for building out integrated cold storage and logistics networks.
- Sustainable Technology Incentives:Policies like the US Inflation Reduction Act (IRA) provide tax credits and financial support for retrofitting facilities with energy-efficient insulation, solar power generation, and waste heat recovery systems.
Industry Challenges
- Skilled Labor Deficit:A persistent shortage of technicians qualified to install, operate, and maintain advanced automation systems and complex natural refrigerant-based cooling plants creates a significant operational bottleneck.
- High Capital Intensity:The substantial upfront investment required to build modern, automated high-bay warehouses presents a major barrier to entry and expansion for smaller, regional operators competing against global consolidators.
- Systems Integration Complexity:Ensuring seamless interoperability between a provider’s warehouse management system (WMS) and the diverse enterprise resource planning (ERP) software used by clients is a recurring challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Storage Market |
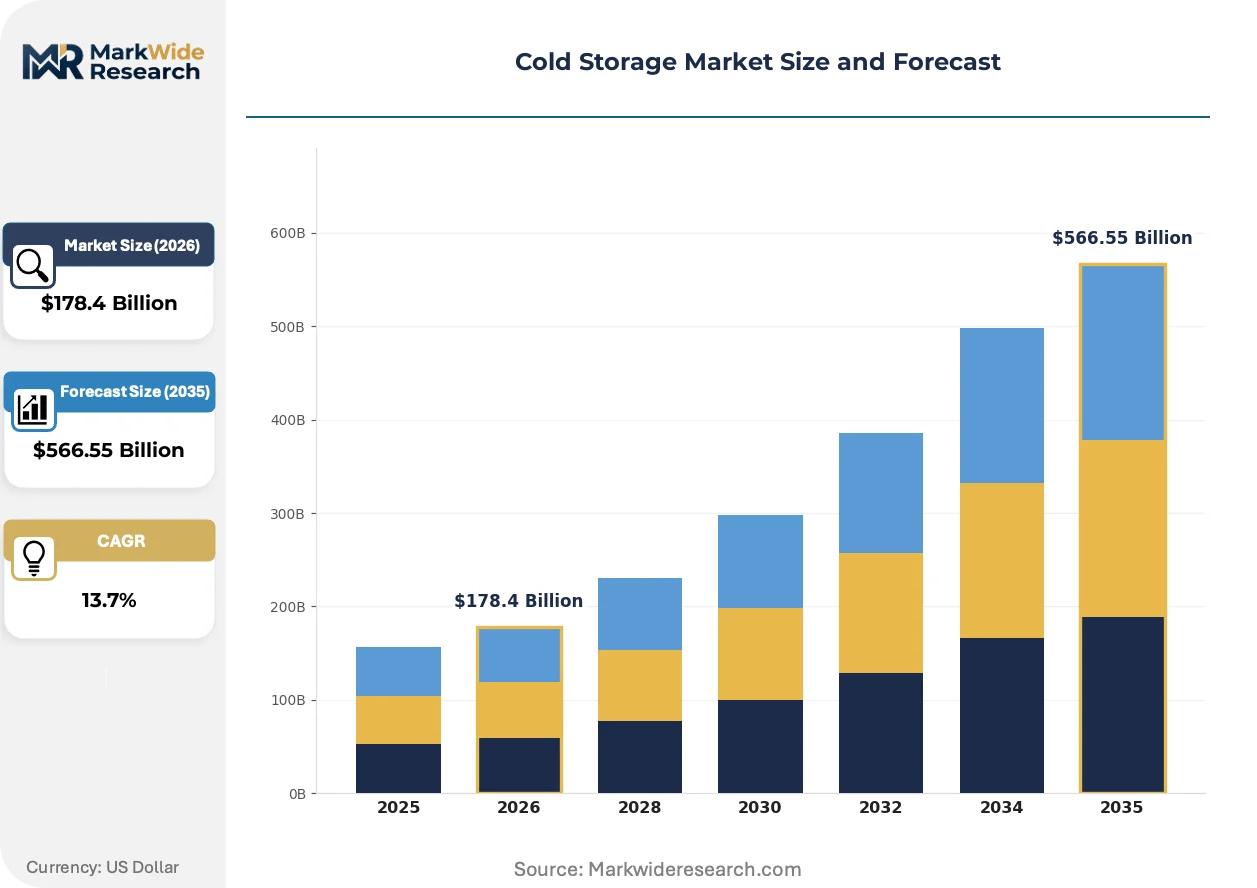
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $566.55 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerated Warehouses, Refrigerated Containers, Blast Freezers, Cold Storage Panels Temperature Range: Chilled, Frozen, Ambient, Sub-Zero End User: Food & Beverage, Pharmaceuticals, Agriculture, Chemicals Service Type: Storage, Transportation, Logistics, Monitoring |
| Companies Covered | NewCold, RLS Logistics, Lineage Logistics, H&M Bay, Denver Cold Storage, Americold Logistics, Burris Logistics, Green Rabbit, United States Cold Storage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Storage Market Strategic Shifts & Innovations
Technological advancement and regulatory pressures are transforming cold storage from a static real estate asset into a dynamic, service-oriented logistics function. The market's evolution is defined by the push for greater efficiency, end-to-end visibility, and environmental sustainability.
Automated Storage and Retrieval Systems (AS/RS) provide high-density product handling and rapid throughput in large-scale facilities. Major food distributors and pharmaceutical logistics providers are adopting this technology to mitigate labor shortages and improve inventory accuracy. The high capital cost of AS/RS is fragmenting the market, creating a performance gap between large consolidators and smaller, manual operators.
The US FDA's Food Safety Modernization Act (FSMA) mandates preventative controls and verifiable temperature documentation across the food supply chain. This shifts the compliance burden directly onto logistics providers, requiring auditable proof of control. The food and beverage segment is most affected, compelling investment in validated sensors and digital record-keeping systems to maintain market access.
End-users are moving from long-term, single-service contracts to flexible, integrated logistics partnerships. This model disrupts traditional warehousing by bundling storage with value-added services like blast freezing, packaging, and transportation management. The shift is most advanced within the quick-service restaurant and grocery retail sectors in North America and Europe.
Cold Storage Market Segmentation
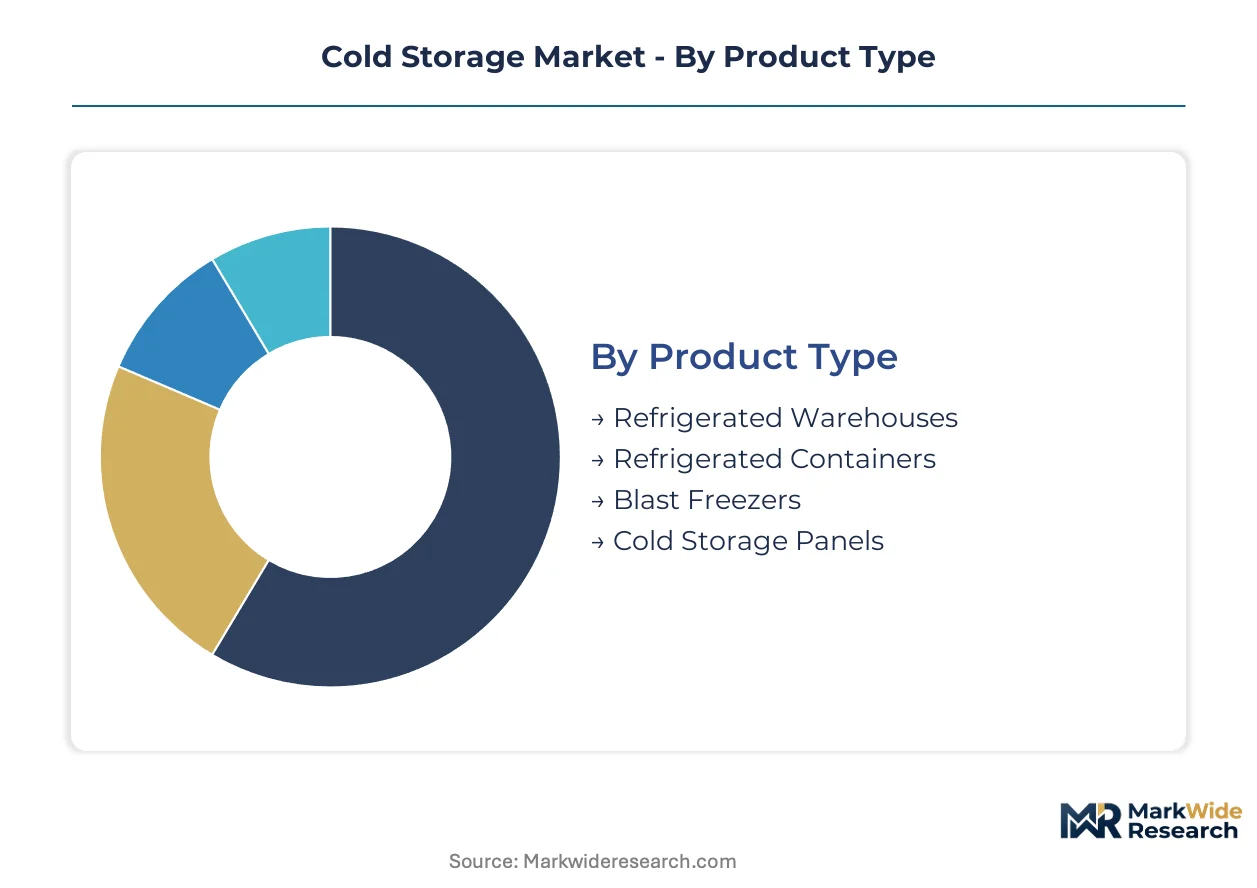
The cold storage market's segmentation reflects the diverse operational requirements across various product types, temperature ranges, end-users, and service offerings. Understanding these distinct segments is critical for providers to tailor infrastructure investments and service capabilities to specific client needs.
Product Type:
Margin pools within product type segmentation are largely influenced by the complexity and scale of infrastructure required for deployment and maintenance. High-density storage solutions command premium pricing due to their efficiency and specialized design.
- Refrigerated Warehouses:Large-scale, insulated structures designed for bulk storage of temperature-sensitive goods, often featuring advanced material handling systems. Demand concentrates in major logistics hubs across North America and Europe due to expanding grocery and pharmaceutical supply chains.
- Refrigerated Containers:Portable, self-contained units offering flexible, temporary, or mobile temperature-controlled storage, essential for intermodal transport. Usage is expanding in emerging markets like India for agricultural produce preservation and last-mile delivery solutions.
- Blast Freezers:Specialized equipment designed for rapid freezing of food products, quickly reducing temperature to inhibit microbial growth and preserve quality. These are crucial for seafood and meat processors seeking to extend product shelf life.
- Cold Storage Panels:Insulated structural components used to construct temperature-controlled environments, offering thermal efficiency for various facility types.
The dominant share belongs to Refrigerated Warehouses, while Refrigerated Containers are closing the gap fastest.
Temperature Range:
The application spectrum of cold storage facilities defines the operational parameters and technology investments for each temperature range. Specific temperature requirements directly impact energy consumption and equipment sophistication.
- Chilled:Maintains temperatures typically between +2°C and +10°C, suitable for fresh produce, dairy products, and certain pharmaceuticals. This range is critical for maintaining the integrity of perishable goods in urban distribution networks.
- Frozen:Operates at or below -18°C, primarily for meat, poultry, frozen foods, and long-term pharmaceutical storage. The segment requires robust insulation and energy-efficient refrigeration systems to manage high power demands.
- Ambient:Controlled environments where temperature is maintained within a stable, non-refrigerated range, protecting products from extreme heat or cold. This is often used for dry goods, some chemicals, and certain pharmaceutical excipients.
- Sub-Zero:Ultra-low temperature storage, often below -20°C, including cryogenic conditions, essential for biologics, vaccines, and cell therapies.
Frozen storage represents the largest volume segment, though Sub-Zero capabilities are gaining traction due to specialized biological products.
End User:
Customer demand for cold storage is dictated by product perishability, regulatory compliance requirements, and supply chain complexity. Each end-user segment presents unique challenges and opportunities for cold chain providers.
- Food & Beverage:The largest consumer of cold storage, encompassing fresh produce, dairy, meat, seafood, and processed frozen foods, requiring diverse temperature controls. Stringent food safety regulations from entities like the US FDA and EU food hygiene bodies drive investment in monitoring.
- Pharmaceuticals:Requires precise temperature control for vaccines, biologics, and cell therapies, often demanding ultra-low or cryogenic conditions. Compliance with regulations from agencies like the EMA and US FDA mandates rigorous validation and real-time monitoring.
- Agriculture:Focuses on post-harvest preservation of fruits, vegetables, and flowers to extend shelf life and reduce waste. Government initiatives in countries like India are promoting modern cold chain infrastructure for this sector.
- Chemicals:Stores temperature-sensitive industrial chemicals, reagents, and hazardous materials under controlled conditions to prevent degradation or reactions.
Food & Beverage remains the largest end-user segment, with Pharmaceuticals driving demand for the most stringent temperature controls.
Service Type:
The value proposition in cold storage is evolving from basic warehousing to integrated, real-time supply chain management solutions. Providers differentiate themselves through the breadth and sophistication of their service offerings.
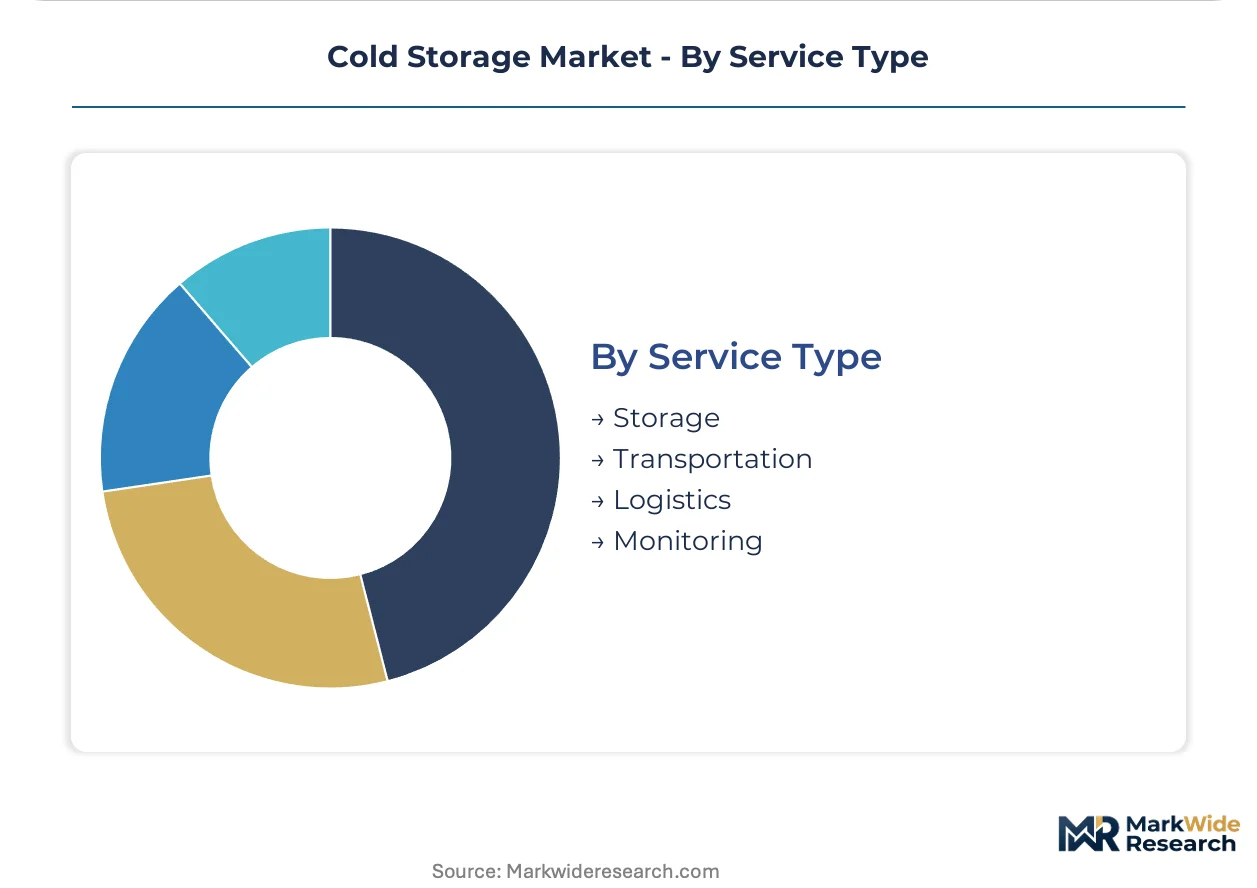
- Storage:Basic warehousing services for temperature-controlled goods, providing static space within a specified temperature range. This foundational service forms the core offering for most cold storage providers.
- Transportation:Movement of temperature-sensitive goods using refrigerated vehicles, railcars, or containers across various distances. This service is crucial for maintaining cold chain integrity from production to consumption.
- Logistics:Integrated supply chain management, including inventory management, order fulfillment, cross-docking, and value-added services like blast freezing or packaging. Global consolidators like Lineage Logistics leverage extensive networks for these offerings.
- Monitoring:Real-time tracking of temperature and other environmental conditions using IoT sensors and digital platforms to ensure product integrity and regulatory compliance.
Traditional Storage services form the foundational offering, while comprehensive Logistics and Monitoring solutions are expanding rapidly to meet complex client needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global cold storage market exhibits varied demand elasticity, with pharmaceutical cold chain services commanding premium pricing due to stringent validation requirements. In contrast, agricultural and food & beverage segments often prioritize cost-efficiency for bulk perishable goods. This dynamic influences infrastructure investment and service specialization across different geographies.
United States
Demand for cold storage in the United States is driven by pharmaceutical sector expansion and stringent food safety requirements. The US FDA's Food Safety Modernization Act mandates verifiable temperature documentation. Major logistics hubs like Chicago are seeing substantial investment in automated refrigerated warehouses.
India
India's cold chain market is expanding due to government initiatives for reducing post-harvest food waste and e-commerce growth. Policy support encourages modern cold chain infrastructure development. Key agricultural regions like Maharashtra are attracting investments in new refrigerated container facilities.
Germany
Germany's cold storage sector benefits from its strong pharmaceutical export industry and advanced food retail logistics. The EU F-Gas Regulation compels operators to transition to natural refrigerants. The Rhine-Ruhr metropolitan region observes increasing demand for energy-efficient cold storage solutions.
China
China's expanding middle class and heightened food safety concerns are fueling substantial cold storage growth. National food safety regulations necessitate improved temperature-controlled logistics. Major urban centers like Shanghai are experiencing rapid development of advanced refrigerated warehouses.
Japan
Japan's cold storage market is characterized by high demand for pharmaceutical distribution and last-mile urban logistics. Stringent quality standards influence technology choices for cold chain facilities. The Greater Tokyo Area sees concentrated investment in smaller, urban-centric refrigerated facilities for rapid delivery.
Cold Storage Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the cold storage market. The sector exhibits a tiered structure, with global consolidators leveraging automated networks for scale, while regional specialists focus on niche services. Strategic archetypes include large-scale integrators, specialized service providers, and emerging market developers. Major competitive moves involve capacity expansion through new facility construction and strategic partnerships to extend geographic reach.
At the scale-driven end, Lineage Logistics and Americold Logistics exemplify global consolidators with extensive networks and integrated service offerings. Lineage Logistics, with its automated warehouse infrastructure, provides comprehensive cold chain solutions across diverse geographies, anchoring the high-volume segment. Americold Logistics occupies a position as a major player, leveraging its vast geographic footprint and deep relationships within the food production sector to serve broad client bases. In contrast, RLS Logistics represents specialized service providers, differentiating through tailored solutions for niche food and beverage clients, often focusing on value-added services beyond basic storage.
| Leading Market Players |
|---|
| NewCold |
| RLS Logistics |
| Lineage Logistics |
| H&M Bay |
| Denver Cold Storage |
| Americold Logistics |
| Burris Logistics |
| Green Rabbit |
| United States Cold Storage |
| Others |
Cost & Logistics Intelligence
The transition from hydrofluorocarbon (HFC) refrigerants to natural alternatives like ammonia is reshaping cold storage supply chains. This shift necessitates new equipment investments, influencing service pricing and geographic development of facilities.
Pricing Analysis
Real-time monitoring and integrated logistics services drive lifetime value for cold storage providers. The dominant pricing structure is a hybrid model, combining long-term contract-based storage with transactional fees for value-added services. Price differentiation stems from the level of regulatory compliance, such as FDA validation, and the volume scale of goods handled. Cost compression in basic storage services is intensifying due to high energy consumption, with Food & Beverage clients exhibiting the highest price sensitivity, while the pharmaceutical sector remains least sensitive.
Supply Chain Analysis
The United States and Germany anchor the supply of advanced refrigerated warehouses and automated cold chain infrastructure. This specialized infrastructure draws from key inputs like insulated panels and high-efficiency refrigeration compressors. A structural risk involves land scarcity and high costs near major urban consumption centers, particularly in Western Europe. Distribution runs through integrated logistics networks, leveraging global consolidators for extensive reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cold storage market is experiencing a cyclical recovery, driven by the expanding pharmaceutical biologics pipeline. Investment in specialized ultra-low temperature capabilities reflects this renewed growth phase.
For Market Incumbents: Fortify existing network advantages by investing in sustainable technology and expanding automated high-bay warehouses. This defends against rising energy price volatility and the threat of stricter environmental regulations like the EU F-Gas Regulation. Consolidators should prioritize capital investments in natural refrigerant systems and energy-efficient insulation. This also mitigates labor shortages through advanced automation.
For New Entrants and Emerging Players: Lead with specialized last-mile cold chain services in urban centers, targeting direct-to-consumer grocery and pharmaceutical delivery. This white space offers significant growth opportunities in geographies like Japan's Greater Tokyo Area. Focus on integrated value-added services such as blast freezing and real-time monitoring to differentiate offerings. Emerging market infrastructure in Southeast Asia also presents a major opportunity for specialized providers.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with strong regional footprints and advanced technology capabilities. The market over the next 5-10 years will favor providers offering validated, compliant services. Target acquisition archetypes include specialized regional operators with ultra-low temperature storage expertise. The signal to watch is the increasing adoption rates of IoT integration for real-time monitoring and regulatory compliance.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Warehouse Construction | Reduces labor costs and improves throughput for global consolidators. |
| Natural Refrigerant Transition | Ensures compliance with EU F-Gas Regulation and reduces operational costs. |
| Last-Mile Delivery Network Development | Captures high-growth direct-to-consumer pharmaceutical and grocery segments. |
| Emerging Market Infrastructure Buildout | Addresses significant cold chain deficits in Southeast Asia and Africa. |
| IoT Sensor Integration | Provides real-time temperature monitoring for US FDA Food Safety Modernization Act compliance. |
Research Approach
The analysis maps refrigerated warehouses, blast freezers, and pharmaceutical cold chain services, each validated through primary interviews with logistics managers and facility operators. This involved conversations with regulatory compliance officers and pharmaceutical supply chain leads. Secondary validation drew from government trade statistics, industry association reports, and corporate financial filings. A bottom-up and top-down triangulation approach ensured robust market sizing and forecasting.
Market outputs were validated against external benchmarks and industry-specific growth projections. The analytical framework modeled market dynamics across the analysis window, segmenting by product type, temperature range, end-user, and service type. Compound annual growth rates were derived from historical trends and future demand drivers. Key forecast inputs included refrigerant phase-out schedules and the global pharmaceutical R&D pipeline.
Forecasts assume regulatory continuity in US FDA and EU F-Gas Regulation regimes; material policy shifts would require re-modeling. The projections reflect current market conditions and acknowledged risk factors like geopolitical disruptions. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
South America Frozen Desserts Market
Processed and Frozen Foods
US Frozen Food Market
Processed and Frozen Foods
French Fries Market
Processed and Frozen Foods
Refrigerated & Frozen Soup Market
Processed and Frozen Foods
Asia Pacific Frozen Desserts Market
Processed and Frozen Foods
Freeze Dried Vegetables Market
Processed and Frozen Foods
Dumplings Market
Processed and Frozen Foods
Frozen Pizza Market
Processed and Frozen Foods
North America Frozen Desserts Market
Processed and Frozen Foods
Frozen Mushroom Market
Processed and Frozen Foods
Asia-Pacific Frozen Food Market
Processed and Frozen Foods
Chilled Soup Market
Processed and Frozen Foods
Asia-Pacific Frozen Pizza Market
Processed and Frozen Foods
Frozen Meat Market
Processed and Frozen Foods
Global Frozen Fish and Seafood Market
Processed and Frozen Foods
Freeze Dried Mangos Market