
 Frozen Snacks Market | 2026-2036
Frozen Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Snacks Market Analysis
North America is fragmenting as frozen snack production scales across the United States, Canada, and Mexico to serve divergent channel needs. Nestlé leverages its global R&D network to sustain innovation pipelines in premium frozen appetizers. Tyson Foods anchors its position through backward integration into poultry supply chains for meat snack categories. Conagra Brands competes aggressively in the value tier through heritage brand portfolios distributed via mass retail.
Frozen snacks comprise pre-prepared, blast-frozen food items designed for reheating via oven, air fryer, or microwave, typically formulated for shelf stability between negative eighteen and negative twenty degrees Celsius and primary commercial purpose of reducing preparation time in both household and professional foodservice environments. Potato Products dominate volume through established French fry and hash brown formats with mature margin profiles, while Meat Snacks capture expanding margin pools as protein-forward positioning commands price premiums across retail freezers. Vegetable Snacks represent the fastest-growing product type as plant-based formulations and clean-label positioning attract health-conscious purchasers through supermarket and online retail channels.
The FDA governs nutrition labeling and ingredient disclosure requirements for frozen snacks sold in the United States, while the USDA oversees meat-based formulations through FSIS inspection protocols, and the EPA regulates refrigeration emissions under evolving fluorinated gas standards that shape cold-chain infrastructure investment decisions. The EU Green Deal and F-Gas Regulation impose parallel constraints on European production networks, accelerating capital redeployment toward lower-global-warming-potential freezing technologies. Stakeholders must monitor regulatory divergence between transatlantic jurisdictions to anticipate compliance costs that will determine competitive viability in premium versus economy positioning.
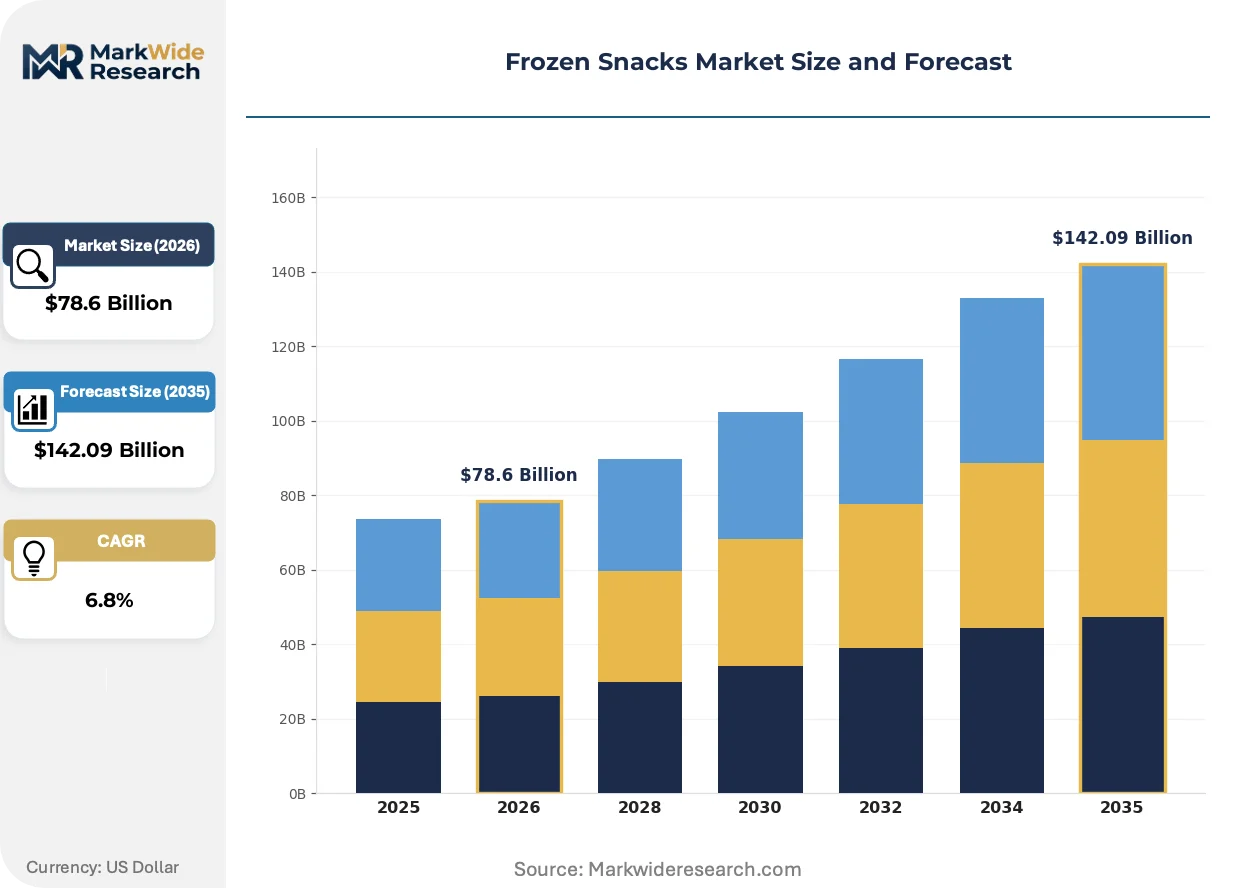
Market Dynamics
Labor cost inflation across foodservice operations is accelerating frozen snack procurement as operators seek to eliminate on-site prep labor while maintaining menu consistency across dispersed locations.
Growth Catalysts
- Air fryer penetration:Household adoption of countertop air-frying appliances is expanding addressable demand for frozen formats engineered specifically for rapid convective reheating without oil submersion.
- USDA-FSIS inspection protocols:Standardized federal oversight of meat-based frozen snacks is reducing food safety liability for foodservice buyers and enabling category expansion into K-12 and healthcare channels.
- Plant protein processing:Extrusion and high-moisture texturization advances are improving bite quality in vegetable-based snacks, attracting flexitarian purchasers previously loyal to meat formats.
Market Restraints
- Refrigerant phase-down obligations:EPA fluorinated gas standards and EU F-Gas Regulation are forcing capital-intensive cold-chain retrofits that compress margins for regional distributors operating legacy freezing equipment.
- Potato input volatility:Russet and specialty potato contract pricing fluctuates with Pacific Northwest irrigation availability, squeezing margin predictability for fry-dependent product lines.
- Clean-label reformulation costs:FDA updated Nutrition Facts requirements are mandating sodium and saturated fat reductions that degrade shelf stability and require expensive hydrocolloid or natural preservative substitutions.
Strategic Opportunities
- Direct-to-foodservice platforms:B2B e-procurement portals are bypassing traditional broadline distributors, enabling manufacturers to capture margin previously allocated to intermediary logistics layers.
- India cold-chain buildout:PLI scheme incentives for refrigerated transport and warehousing are opening organized retail penetration in tier-two cities previously served by ambient street-vendor alternatives.
- Dual-carbon compliance positioning:China's national dual carbon goals are creating premium positioning for frozen snack producers deploying CO2 transcritical freezing systems with verifiable emissions reductions.
Industry Challenges
- Refrigeration technician scarcity:Qualified service personnel for ultra-low-temperature cascade systems are concentrated in coastal metropolitan zones, extending equipment downtime for inland production facilities.
- Legacy ERP integration:Temperature-monitoring IoT sensor networks require middleware development to communicate with frozen food manufacturers' existing warehouse management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Snacks Market |
| Market Size in 2026 | $78.6 Billion |
| Market Size in 2035 | $142.09 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Potato Products, Frozen Desserts, Meat Snacks, Vegetable Snacks End User: Households, Restaurants, Cafes, Foodservice Operators Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesale Distributors Price Tier: Premium, Mid-Range, Economy, Discounted |
| Companies Covered | Nestlé, Tyson Foods, Conagra Brands, The Kraft Heinz Company, General Mills, Unilever, McCain Foods Limited, Nomad Foods, FRoSTA AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Snacks Market Emerging Trajectories
Reformulation chemistry and reheating physics are converging to expand the sensory quality window for frozen snacks, collapsing the historical trade-off between convenience and finished-product texture.
Modified atmosphere packaging is migrating from nitrogen-flushed pillow bags toward high-barrier multilayer films with embedded oxygen scavengers. Premium retail brands are adopting these materials to extend freezer-life without synthetic preservatives. The structural consequence is that clean-label positioning is migrating from niche organic SKUs into mass-market frozen appetizer lines previously dependent on BHA and TBHQ stabilization.
EU F-Gas Regulation is mandating progressive reduction in hydrofluorocarbon refrigerant use across commercial freezing operations. Frozen snack manufacturers with European production footprints are retrofitting compressors to accommodate propane or CO2 alternatives. Cold-store operators in Germany and the Netherlands are absorbing the highest compliance costs, accelerating consolidation toward operators with capital reserves for equipment replacement cycles.
Retail buyers are consolidating frozen snack assortment decisions at regional headquarters rather than delegating to individual store managers. This concentration is compressing supplier negotiation cycles and elevating importance of slotting fee structures and promotional calendar alignment. The shift is most pronounced in US supermarket chains operating centralized category management functions across multi-state footprints.
Frozen Snacks Market Segmentation
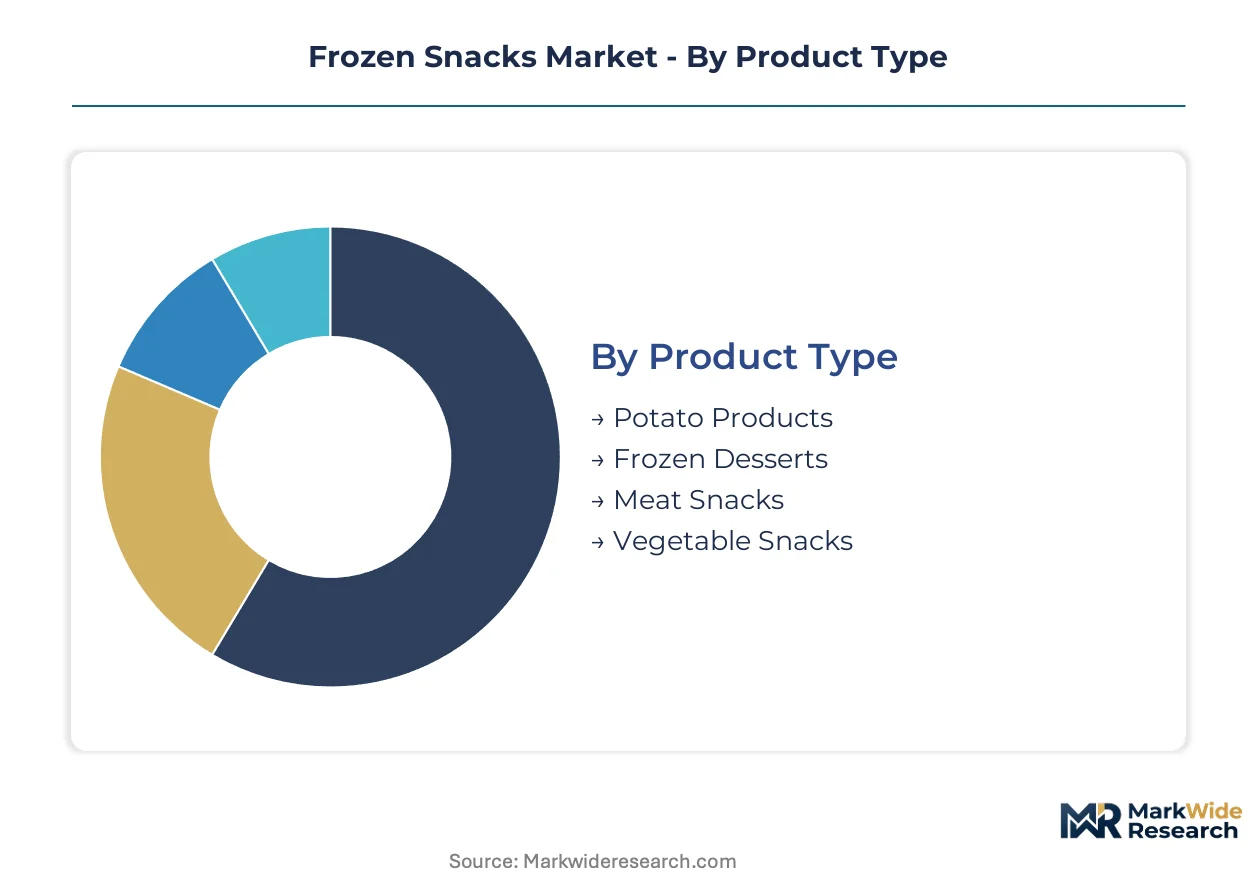
Segmentation in frozen snacks reveals how formulation chemistry, reheating physics, and channel economics split demand across divergent use cases. Manufacturers configure production lines and cold-chain investments around these divisions, with each segment imposing distinct margin pressures and regulatory exposure.
Product Type:
Blast-frozen formats span indulgent comfort foods to protein-forward functional positioning, with each category demanding specialized freezing curves and packaging barriers to preserve sensory quality through retail distribution.
- Meat Snacks:Poultry, beef, and pork-based formulations undergo USDA-FSIS inspection protocols before blast-freezing to negative eighteen degrees Celsius. Foodservice operators in the United States concentrate procurement here to eliminate on-site protein prep labor while maintaining menu consistency across dispersed locations.
- Vegetable Snacks:Extruded legume proteins and whole-vegetable formats leverage high-moisture texturization to achieve meat-comparable bite quality. Clean-label positioning and plant-based certification attract flexitarian purchasers through supermarket and online retail channels in California and New York metropolitan areas.
- Potato Products:Russet and specialty potato varieties dominate volume through established French fry and hash brown formats with mature margin profiles.
- Frozen Desserts:Sweet snack formats including frozen novelties and dessert bites target impulse purchase occasions in convenience retail.
Established volume favors Potato Products; emerging adoption favors Vegetable Snacks.
End User:
Channel concentration determines formulation priorities, with household purchasers prioritizing air fryer compatibility while commercial buyers emphasize holding stability and portion consistency.
- Foodservice Operators:Multi-unit restaurant chains and institutional cafeterias procure frozen snacks to standardize output across locations while compressing labor hours. K-12 and healthcare channel expansion accelerates as USDA-FSIS inspection protocols reduce food safety liability for buyers.
- Households:Residential purchasers drive demand for single-serve and small-format packaging engineered for countertop air fryer reheating without oil submersion.
- Restaurants:Independent dining establishments balance frozen procurement with scratch preparation to manage throughput during peak service periods.
- Cafes:Limited-service coffee and snack shops utilize frozen pastries and savory bites to extend menu breadth without kitchen infrastructure investment.
Labor cost pressures concentrate procurement growth within Foodservice Operators; air fryer penetration expands Household addressable demand.
Distribution Channel:
Cold-chain configuration and buyer concentration shape channel economics, with direct manufacturer relationships eroding traditional distributor margins.
- Supermarkets:Centralized category management at regional headquarters compresses supplier negotiation cycles and elevates slotting fee structures. Clean-label frozen appetizers migrate from niche organic SKUs into mass-market lines as retail buyers consolidate assortment decisions.
- Wholesale Distributors:Broadline foodservice distributors face margin compression as B2B e-procurement portals enable manufacturers to bypass intermediary logistics layers and capture direct relationships with multi-unit operators.
- Online Retail:Direct-to-consumer frozen snack delivery requires specialized insulated packaging and last-mile cold-chain coordination.
- Convenience Stores:Impulse-oriented frozen snack placement targets immediate consumption occasions with limited freezer door space.
Consolidated buyer power favors Supermarkets; disintermediation pressure favors Wholesale Distributor restructuring.
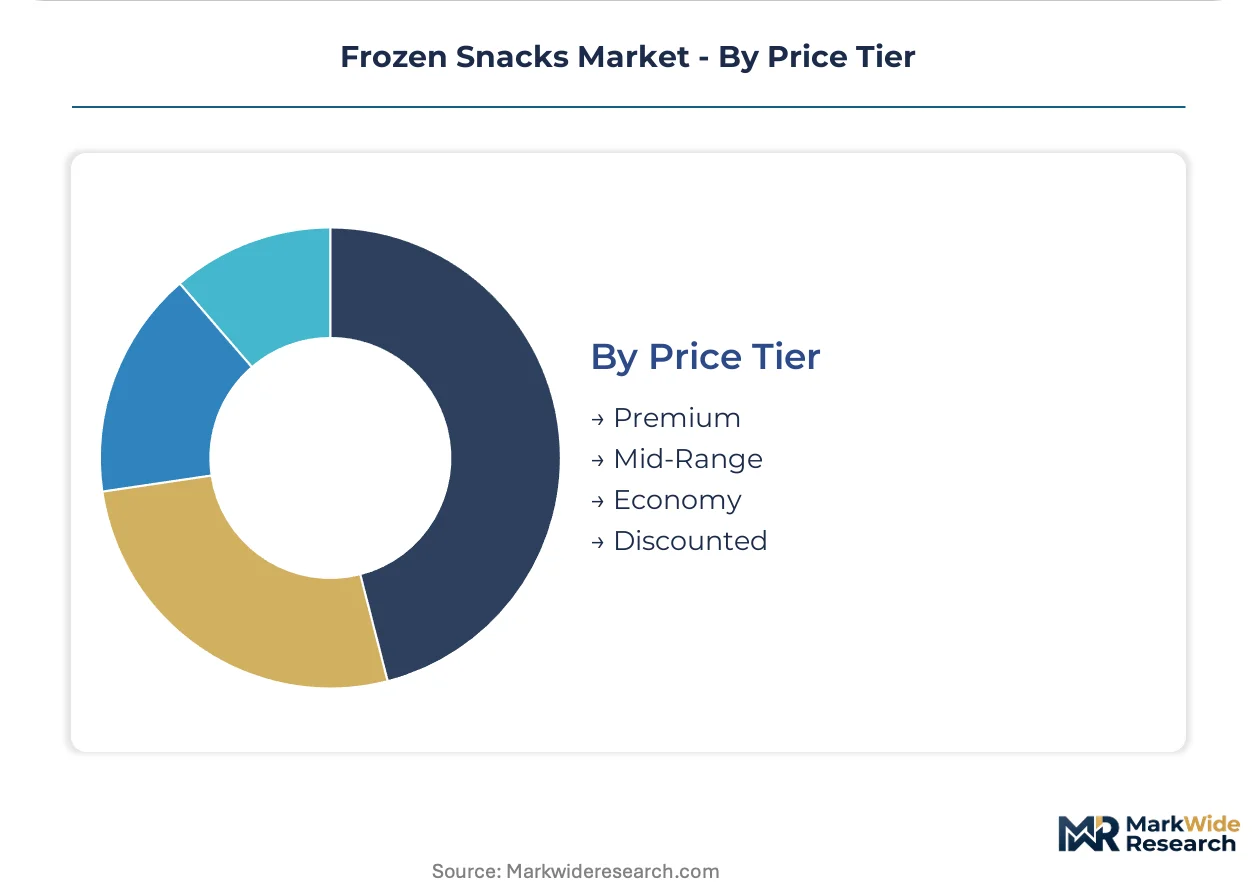
Price Tier:
Ingredient quality, certification premiums, and packaging sophistication stratify positioning across accessible and aspirational purchase occasions.
- Premium:Heritage breed proteins, organic certification, and modified atmosphere packaging with embedded oxygen scavengers extend freezer-life without synthetic preservatives. Nestlé and specialty brands deploy global R&D networks to sustain innovation pipelines in this tier.
- Economy:Value-tier positioning relies on heritage brand portfolios distributed via mass retail, with Conagra Brands competing aggressively through scale efficiencies and promotional calendar alignment.
- Mid-Range:Standard formulations balance recognizable ingredient decks with accessible price points for mainstream household penetration.
- Discounted:Promotional and closeout inventory channels move excess production volume with compressed margins.
Reformulation cost pressures squeeze Economy tier shelf stability; certification premiums expand Premium addressable base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Blast-freezing capacity clusters in the United States, Germany, China, and India, where cold-chain infrastructure investment and divergent regulatory regimes are redrawing procurement maps for frozen snack manufacturers.
United States
Foodservice operators across the Midwest and Southeast are expanding frozen snack procurement as labor costs climb in quick-service restaurant chains. FDA updated Nutrition Facts labeling requirements are pressuring reformulation toward sodium reduction and cleaner ingredient decks. Chicago and Dallas-Fort Worth metropolitan areas host the densest concentrations of cold-storage warehousing serving retail and away-from-home distribution networks.
Germany
Retail consolidation in the DACH region is compressing supplier negotiation cycles for frozen appetizer lines. EU F-Gas Regulation mandates progressive hydrofluorocarbon phase-down across commercial freezing operations, forcing capital-intensive compressor retrofits. The Ruhr industrial corridor and Bavarian logistics hubs absorb the highest compliance costs, accelerating cold-store consolidation toward operators with equipment replacement reserves.
China
Urban household penetration of countertop air fryers is expanding addressable demand for frozen formats engineered for rapid convective reheating. National dual carbon goals are creating premium positioning for producers deploying CO2 transcritical freezing systems with verifiable emissions reductions. Yangtze River Delta manufacturing clusters around Shanghai and Suzhou lead domestic production scale for both domestic consumption and export processing.
India
PLI scheme incentives for refrigerated transport and warehousing are opening organized retail penetration in tier-two cities previously served by ambient street-vendor alternatives. FSSAI labeling and safety standards are tightening import scrutiny on frozen meat-based formulations. Maharashtra and Gujarat cold-chain buildouts concentrate new blast-freezing capacity near Mumbai and Ahmedabad processing zones.
Frozen Snacks Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in ingredient supply and freezing technology. The frozen snacks sector presents a tiered structure where multinational packaged food conglomerates with global R&D networks occupy premium positioning, while regional processors and private-label specialists compete on volume efficiency. Three archetypes dominate: heritage-brand conglomerates with backward-integrated protein supply chains, plant-forward innovators leveraging extrusion advances, and value-tier specialists optimizing promotional calendar alignment. Consolidation activity concentrates in cold-chain asset acquisitions and cross-border brand portfolio transfers.
Among heritage-brand conglomerates, Nestlé and Tyson Foods exemplify divergent strategic positioning. Nestlé occupies the premium innovation tier through sustained R&D pipeline investment in frozen appetizer formats. Tyson Foods anchors protein-forward categories through captive poultry supply chain integration. Conagra Brands sits within the value-tier specialist archetype, competing via scale efficiencies and heritage brand distribution reach across mass retail channels.
| Leading Market Players |
|---|
| Nestlé |
| Tyson Foods |
| Conagra Brands |
| The Kraft Heinz Company |
| General Mills |
| Unilever |
| McCain Foods Limited |
| Nomad Foods |
| FRoSTA AG |
| Others |
Supply Flow & Price Mechanics
The I-35 freight corridor stretching from Dallas-Fort Worth to Minneapolis anchors frozen snack distribution economics, where refrigerated trucking rates fluctuate with diesel pricing and driver availability. This logistics backbone concentrates supply-side leverage among cold-chain operators while downstream price differentiation separates premium clean-label SKUs from economy-tier heritage brands.
Pricing Analysis
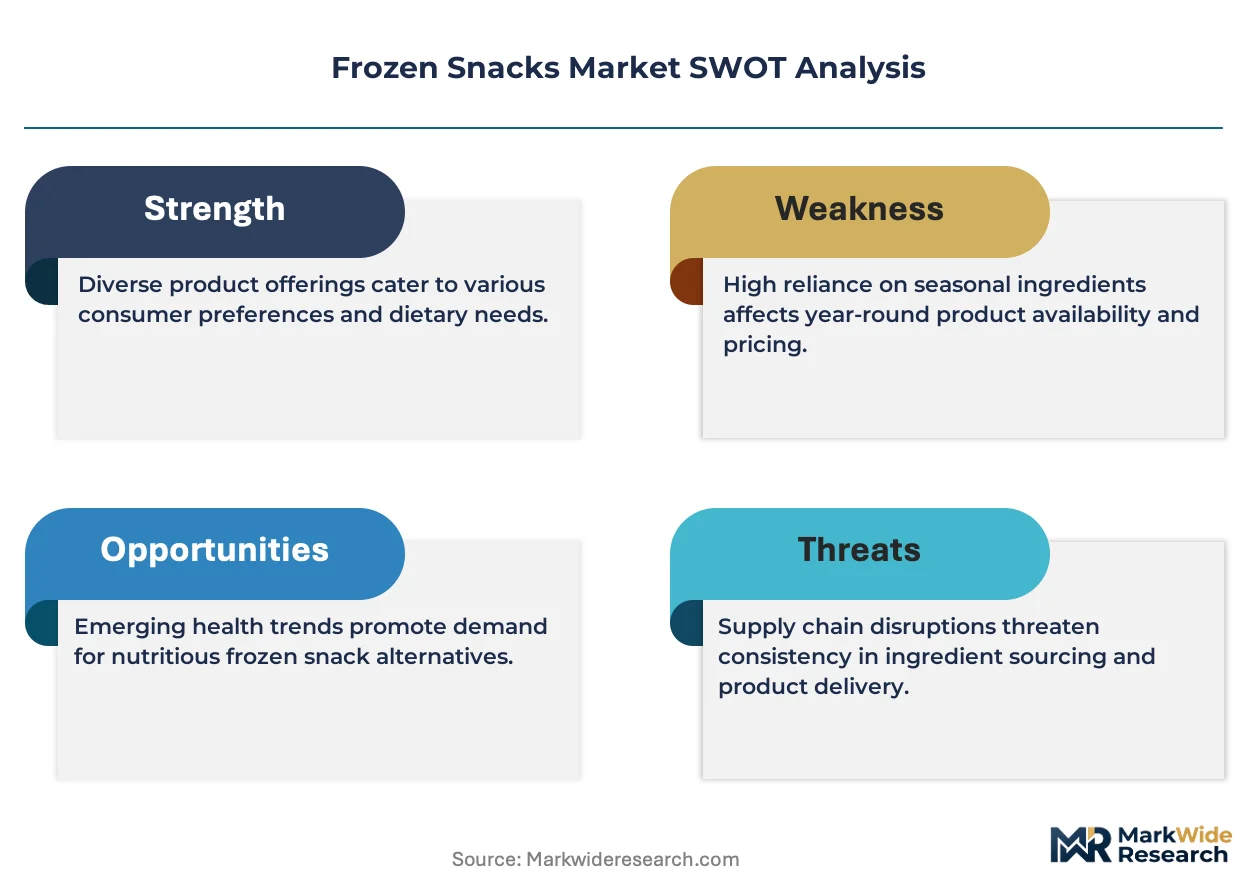
FDA updated Nutrition Facts requirements dictate the pricing tier structure across the frozen snacks sector by mandating sodium reduction and ingredient disclosure that escalates reformulation costs. Three-tier pricing structure across premium, standard, and economy levels separates Nestlé's R&D-intensive appetizers from Conagra's value-positioned heritage portfolios. Pricing pressure stems from clean-label reformulation investments degrading shelf stability margins. Foodservice operators exhibit highest price sensitivity due to procurement volume consolidation, while household purchasers in California and New York metropolitan areas absorb certification premiums.
Supply Chain Analysis
Extended payment terms from broadline distributors now stretch 60-90 days, compressing working capital for regional processors. Supply concentrates in the United States, Germany, and China, where blast-freezing capacity clusters near metropolitan cold-storage hubs. Raw material dependencies center on Pacific Northwest potato contracts, poultry supply chains, and extruded plant protein inputs. Single-source vulnerability runs through specialized CO2 transcritical refrigeration equipment. Distribution runs through B2B e-procurement portals disintermediating traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The frozen snacks market is recovering from input cost cyclicality as Pacific Northwest irrigation patterns stabilize potato contract availability. Labor cost inflation across foodservice operations sustains procurement momentum through the analysis window.
For Market Incumbents: Entrench defensive positions through backward integration into captive poultry supply chains and CO2 transcritical freezing retrofits ahead of EPA fluorinated gas phase-down deadlines. Nestlé and Tyson Foods should consolidate cold-chain asset acquisitions in the Midwest and Southeast to lock out regional challengers. Priority lever: R&D pipeline investment in air-fryer-compatible formats.
For New Entrants and Emerging Players: Tier-two Indian cities present underpenetration white space as PLI scheme incentives build refrigerated warehousing capacity outside Mumbai and Ahmedabad. Target flexitarian households through extruded legume protein snacks with FSSAI-compliant clean-label positioning. Go-to-market angle: direct-to-foodservice B2B portals bypassing broadline distributor margins.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational conglomerates divesting non-core frozen appetizer portfolios. Long-term viability hinges on dual-carbon compliance positioning for China export eligibility and EU F-Gas Regulation adherence. Signal to monitor: refrigerated transport PLI scheme allocation rates as India cold-chain buildout inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Air Fryer Format Development | R&D investment in rapid convective reheating physics expands addressable household demand. |
| CO2 Transcritical Retrofit | EPA fluorinated gas compliance preserves market access under evolving refrigeration emissions standards. |
| Direct-to-Foodservice Platform | B2B e-procurement bypasses broadline distributors to capture intermediary margin pools. |
| Plant Protein Extrusion Scale-Up | High-moisture texturization advances attract flexitarian purchasers from meat-based formats. |
| India Cold-Chain Buildout | PLI scheme refrigerated warehousing opens organized retail penetration in tier-two cities. |
Methodological Framework
The analysis maps meat snacks, vegetable snacks, potato products, and frozen desserts, each validated through category buyers at supermarket chains, procurement directors at multi-unit restaurant operators, cold-chain logistics managers, and plant protein R&D specialists. Primary interview intelligence triangulates against FDA filing databases, USDA-FSIS inspection records, Nielsen retail audit data, and customs import manifests. Bottom-up SKU-level volume builds reconcile with top-down category expenditure estimates.
Forecast assumptions held cold-chain infrastructure investment rates and air fryer household penetration curves fixed while varying labor cost inflation scenarios and potato input pricing volatility. Segmentation dimensions span product type, end user channel, distribution format, and price tier across the projection horizon. CAGRs derive from regression analysis against historical frozen food category growth elasticities, with explicit modeling of EPA refrigerant phase-down compliance cost pass-through.
Practitioners should monitor EPA enforcement timelines on fluorinated gas standards and FSSAI import scrutiny escalation for early signals of forecast revision risk. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Frozen Mackerel Market
Processed and Frozen Foods
Low-Fat Low-Cholesterol Foods Market
Processed and Frozen Foods
Chilled Meal Kits Market
Processed and Frozen Foods
South America Frozen Desserts Market
Processed and Frozen Foods
North America Frozen Finger Chips Market
Processed and Frozen Foods
Indonesia Frozen Food Market
Processed and Frozen Foods
United States Frozen Pizza Market
Processed and Frozen Foods
Processed and Frozen Fruits Market
Processed and Frozen Foods
Middle East and Africa Frozen Bread Market
Processed and Frozen Foods
Asia Pacific Freeze Dried Product Market
Processed and Frozen Foods
Frozen Fruit Bars Market
Processed and Frozen Foods
Frozen Chicken Market
Processed and Frozen Foods
Frozen Cheese Market
Processed and Frozen Foods
Frozen Dough Market
Processed and Frozen Foods
Frozen Food and Snacks Market
Processed and Frozen Foods
Frozen Sardine Market