
 GCC Frozen Fruits and Vegetables Market | 2026-2036
GCC Frozen Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Frozen Fruits and Vegetables Market Intelligence
Asset-light leasing arrangements for blast-freezing and cold-storage infrastructure are fragmenting competitive entry barriers across the Gulf. Pure Harvest Smart Farms leverages its controlled-environment agriculture expertise to supply premium frozen leafy greens with shorter farm-to-freezer cycles. Al Dahra Agriculture anchors its position through backward integration into Egyptian and Sudanese growing operations that sustain year-round raw material flows. Gorika Group competes by dominating the HORECA channel in Kuwait and Bahrain with customized bulk packaging formats.
Frozen fruits and vegetables comprise fresh produce that undergoes rapid individual quick freezing or blast freezing at temperatures below minus eighteen degrees Celsius, preserving cellular structure, nutritional content, and shelf stability for periods exceeding twelve months under uninterrupted cold chain conditions. The category serves commercial food manufacturing, institutional catering, and retail substitution markets where supply consistency outweighs fresh procurement volatility. Leafy Greens and Berries command premium positioning due to perishability challenges in fresh form and concentrated demand from smoothie manufacturers and hospitality groups. Foodservice channels represent the fastest-growing distribution pathway as Saudi and Emirati restaurant chains expand frozen ingredient standardization across multi-location operations. Bulk Containers dominate institutional procurement while Pouches gain traction in online retail segments targeting single-household deliveries.
SFDA's cold-chain traceability mandates in Saudi Arabia and UAE Ministry of Climate Change and Environment food safety standards are tightening market access for uncertified suppliers while rewarding HACCP-compliant operators with preferred vendor status in government tenders. The Emirates Authority for Standardization and Metrology (ESMA) labeling requirements for frozen produce origin and freezing date disclosure are reshaping packaging investment priorities across GCC distribution networks. Stakeholders must monitor evolving halal certification integration with frozen vegetable processing lines as GCC import authorities begin requiring slaughter-free process verification for certain frozen greens categories.
Market Dynamics
Central kitchen proliferation across Saudi and Emirati hospitality chains is compressing procurement cycles and forcing frozen produce specifications toward single-source standardization. This structural shift rewards suppliers capable of year-round volume consistency and HACCP-certified traceability documentation.
Growth Catalysts
- SFDA Cold-Chain Traceability Mandates:Saudi Arabia's enforcement of serialized temperature logging creates procurement preference for certified distributors capable of end-to-end documentation. Hotel and airline catering divisions now require this certification for vendor qualification.
- Controlled-Environment Agriculture:Vertical farming integration shortens farm-to-freezer cycles for premium leafy greens, preserving cellular structure and nutritional density that conventional field harvesting degrades during Gulf summer heat.
- Dubai Logistics Free Zones:Temperature-controlled warehousing infrastructure reduces spoilage losses for re-export operations across Bahrain, Kuwait, and Oman, positioning the emirate as the regional distribution hub.
Market Restraints
- Input Cost Volatility:Egyptian and Sudanese raw material flows face currency fluctuation exposure and Nile water allocation disputes that destabilize year-round supply commitments to GCC processors.
- Supply Concentration Risk:Blast-freezing infrastructure ownership concentrates among three Dubai-based cold-storage operators, creating bottleneck vulnerability during seasonal demand spikes.
- Regulatory Friction:ESMA labeling requirements for origin disclosure and freezing date mandate packaging redesign investments that smaller distributors cannot amortize across limited volume bases.
Strategic Opportunities
- Kuwait and Bahrain HORECA Penetration:These markets exhibit lower frozen vegetable substitution rates in independent restaurants compared to Saudi Arabia and the UAE, presenting first-mover expansion potential for customized bulk format suppliers.
- Halal-Certification Integration:Emerging SFDA requirements for slaughter-free process verification in certain frozen greens categories create compliance-based differentiation for early certifiers.
- Online Retail Pouch Formats:Single-household delivery channels in Dubai and Riyadh show accelerating demand for portion-controlled packaging that institutional bulk containers cannot address.
Industry Challenges
- Cold-Chain Engineering Talent Scarcity:GCC universities produce insufficient refrigeration technicians and thermal logistics specialists to staff expanding blast-freezing operations.
- Multi-Certification Timeline Compression:Simultaneous HACCP, halal, and organic accreditation processes create six-to-nine-month vendor qualification delays that exclude suppliers from annual tender cycles.
- Legacy ERP Integration:Central kitchen operators require real-time inventory APIs that many established distributors cannot deploy without core system replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Frozen Fruits and Vegetables Market |
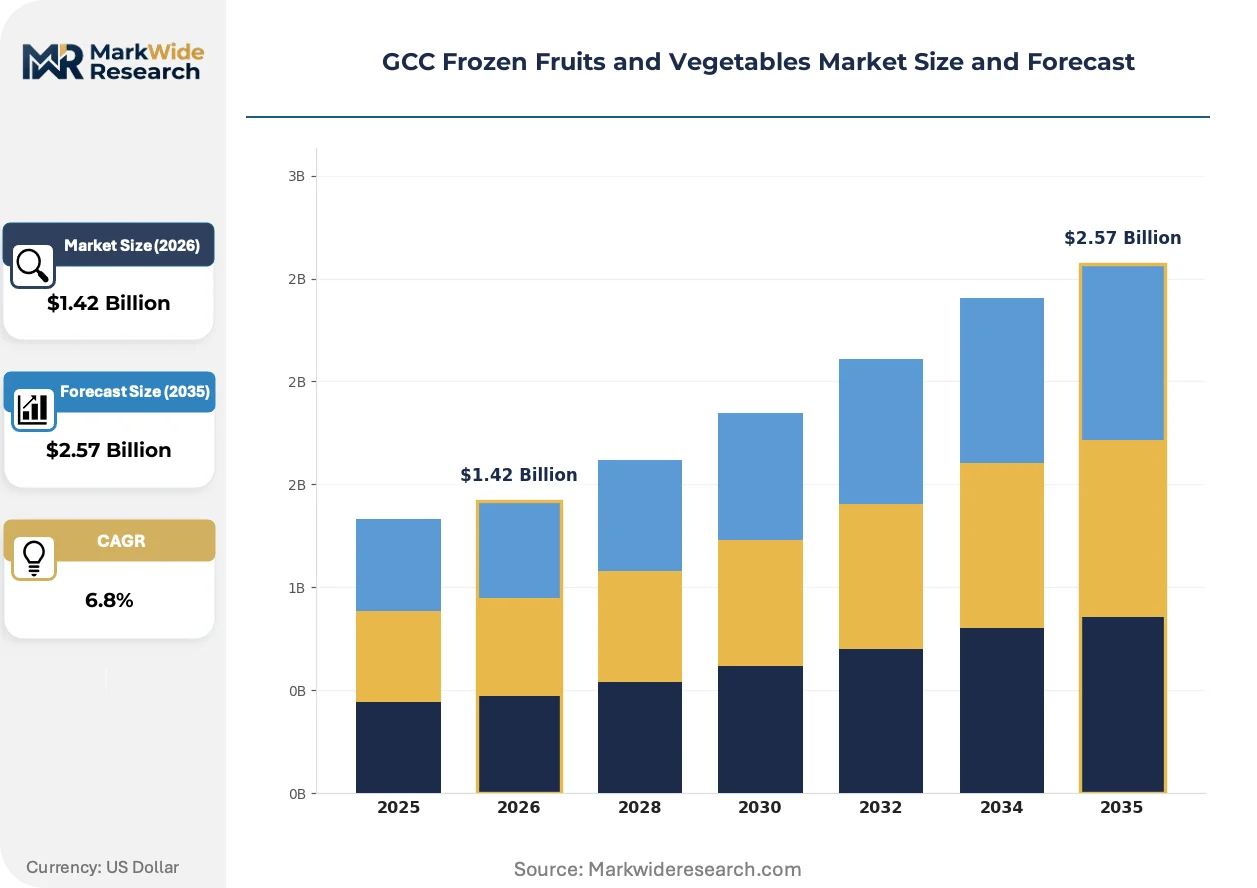
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Berries, Leafy Greens, Root Vegetables, Stone Fruits Packaging Type: Bags, Boxes, Pouches, Bulk Containers Distribution Channel: Supermarkets, Grocery Stores, Online Retail, Foodservice End User: Households, Restaurants, Cafés, Catering Services |
| Companies Covered | Fresh Fruits Company, Al Jazira Agriculture, Pure Harvest Smart Farms, VeggiTech, Gorika Group, Al Dahra Agriculture, Abu Dhabi Farmers' Services Center, Emirates Hydroponics Farms, Al Ghurair Foods, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Frozen Fruits and Vegetables Market Strategic Shifts & Innovations
Individual quick freezing technology advancement is compressing quality differentials between fresh and frozen produce, eliminating traditional taste-texture trade-offs that previously limited category expansion in premium hospitality segments.
Modular nitrogen tunnel freezing systems are rendering obsolete conventional blast-freezing chambers with fixed throughput capacities. Saudi central kitchen operators are adopting these scalable units to match processing volume with seasonal demand fluctuation without capital-intensive facility expansion. The technology is rendering obsolete the historical constraint that frozen produce procurement required annual volume commitments.
SFDA serialization mandates for temperature excursion documentation are forcing distributor investment in IoT-enabled cold-chain monitoring. The regulation requires real-time data transmission from transport vehicles to central databases, creating compliance infrastructure that smaller operators cannot fund independently. Frozen berry imports face the strictest enforcement timelines due to perishability sensitivity.
Smoothie manufacturers and health-focused café chains are consolidating supplier relationships around dual-certified organic-halal frozen leafy greens producers. This specification tightening excludes conventional commodity suppliers from premium channel access. The UAE exhibits the most pronounced procurement concentration, with Dubai-based beverage chains now requiring single-source accountability for traceability compliance.
GCC Frozen Fruits and Vegetables Market Segmentation
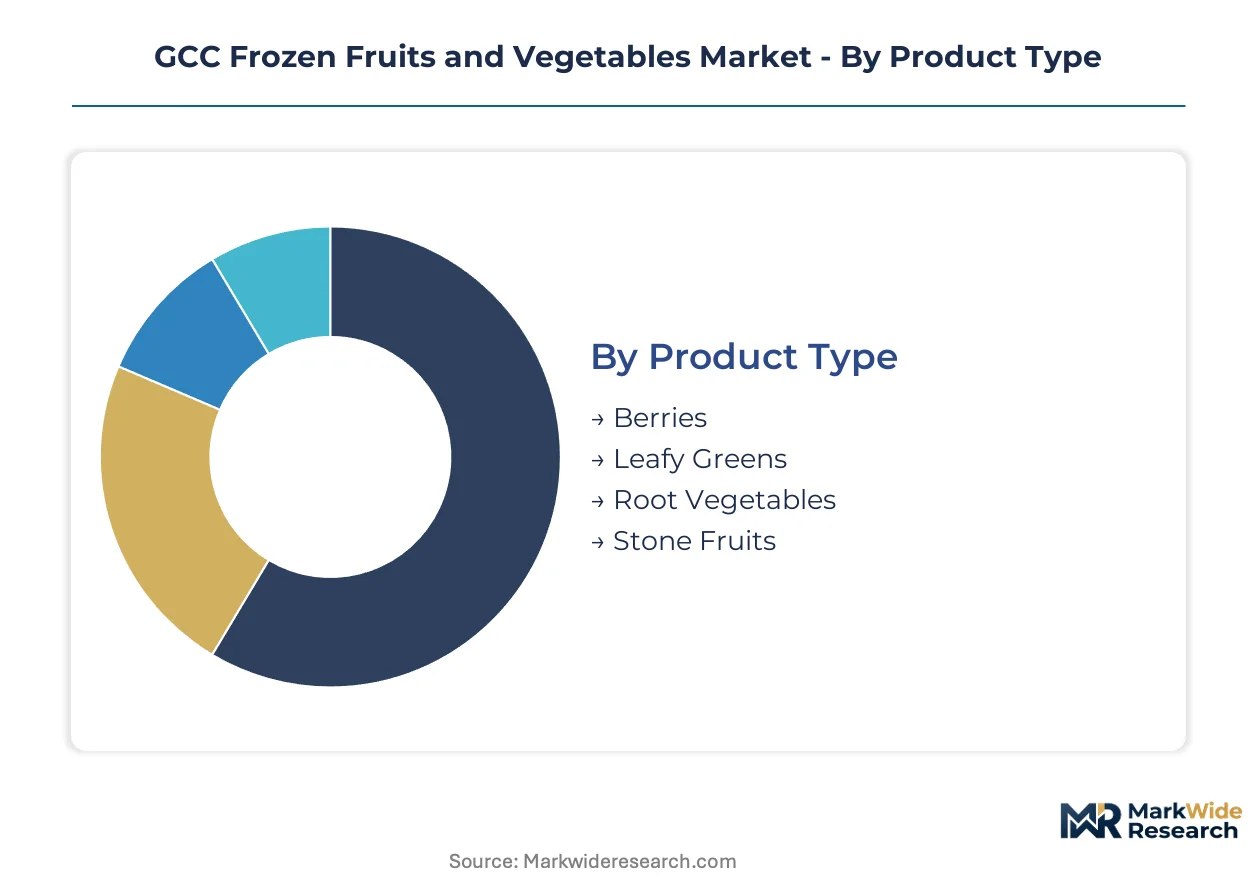
Segmentation in the GCC frozen produce market reveals distinct procurement patterns across product categories and packaging formats. Cold-chain infrastructure investments and regulatory compliance requirements create divergent margin profiles across these dimensions.
Product Type:
After-sales service intensity varies sharply across frozen produce categories, with perishability dictating cold-chain monitoring frequency and traceability documentation depth.
- Berries:Individual quick freezing preserves fragile cellular membranes in strawberries, blueberries, and raspberries. Dubai-based smoothie manufacturers and hospitality chains concentrate procurement here, driven by year-round demand consistency that fresh sourcing cannot match during Gulf summer heat.
- Leafy Greens:Spinach, kale, and mixed greens undergo rapid blast freezing within hours of controlled-environment harvest. Saudi central kitchen operators and UAE airline caterers prioritize this segment, compelled by SFDA traceability mandates that favor suppliers with serialized temperature logging.
- Root Vegetables:Carrots, potatoes, and beets offer longer frozen shelf stability with lower cold-chain sensitivity. Institutional food manufacturers in Kuwait and Bahrain favor these for cost-efficient bulk procurement.
- Stone Fruits:Peaches, plums, and cherries face seasonal availability constraints that frozen processing smooths. Retail substitution demand concentrates in Riyadh and Jeddah supermarket channels.
Leafy Greens holds the largest share; momentum sits with Berries.
Packaging Type:
Cost tier stratification separates premium pouch formats from economy bulk containers, with mid-tier bags and boxes occupying institutional procurement.
- Bags:Polyethylene-lined flexible packaging dominates retail freezer sections across Saudi Arabia and the UAE. Supermarket chains in Riyadh and Dubai specify resealable zipper configurations for household convenience.
- Boxes:Corrugated cardboard with wax coating serves foodservice distributors requiring stackable pallet configurations. Saudi central kitchen operators standardize on this format for inventory efficiency.
- Pouches:Stand-up pouches with spout configurations target single-household delivery channels. Online retail platforms in Dubai and Abu Dhabi show accelerating adoption, climbing the fastest as portion-controlled formats displace institutional bulk.
- Bulk Containers:Food-grade plastic totes and lined fiber drums exceed 10-kilogram capacity for manufacturing and catering procurement. HORECA channel distributors in Kuwait and Bahrain anchor volume here.
Bulk Containers dominates institutional procurement; Pouches gains share fastest in online retail.
Distribution Channel:
Customer type fragmentation splits procurement between household substitution and commercial ingredient sourcing, with divergent service level requirements.
- Supermarkets:Temperature-controlled retail freezer infrastructure concentrates in Saudi Arabia and the UAE. Carrefour, Lulu, and Union Coop chains drive branded frozen produce placement.
- Grocery Stores:Smaller-format independent retailers in Bahrain and Oman serve neighborhood catchments with limited SKU breadth. Local distributors maintain direct store delivery relationships.
- Online Retail:Talabat, Noon, and Amazon UAE platforms expand frozen category penetration through dark store fulfillment. Last-mile cold-chain investments enable single-pouch delivery economics.
- Foodservice:Restaurant chains, airline caterers, and institutional kitchens represent the steepest expansion trajectory. Saudi and Emirati hospitality groups consolidate procurement around HACCP-certified distributors.
Supermarkets holds the largest share; Foodservice climbs fastest.
End User:
Application maturity separates established institutional catering from emerging household frozen substitution patterns.
- Households:Retail consumers in Dubai and Riyadh increasingly substitute frozen for fresh produce, driven by convenience and reduced spoilage waste. Online grocery platforms accelerate this shift.
- Restaurants:Quick-service and casual dining chains across Saudi Arabia standardize frozen ingredient specifications for menu consistency. Central kitchen proliferation compresses supplier qualification timelines.
- Cafés:Specialty beverage and health-focused outlets in the UAE concentrate demand for organic-halal certified frozen berries and leafy greens. Smoothie manufacturers require dual-certified single-source accountability.
- Catering Services:Airline caterers, event operators, and institutional meal providers in Kuwait and Bahrain expand procurement volumes. Volume scale rewards suppliers with year-round consistency.
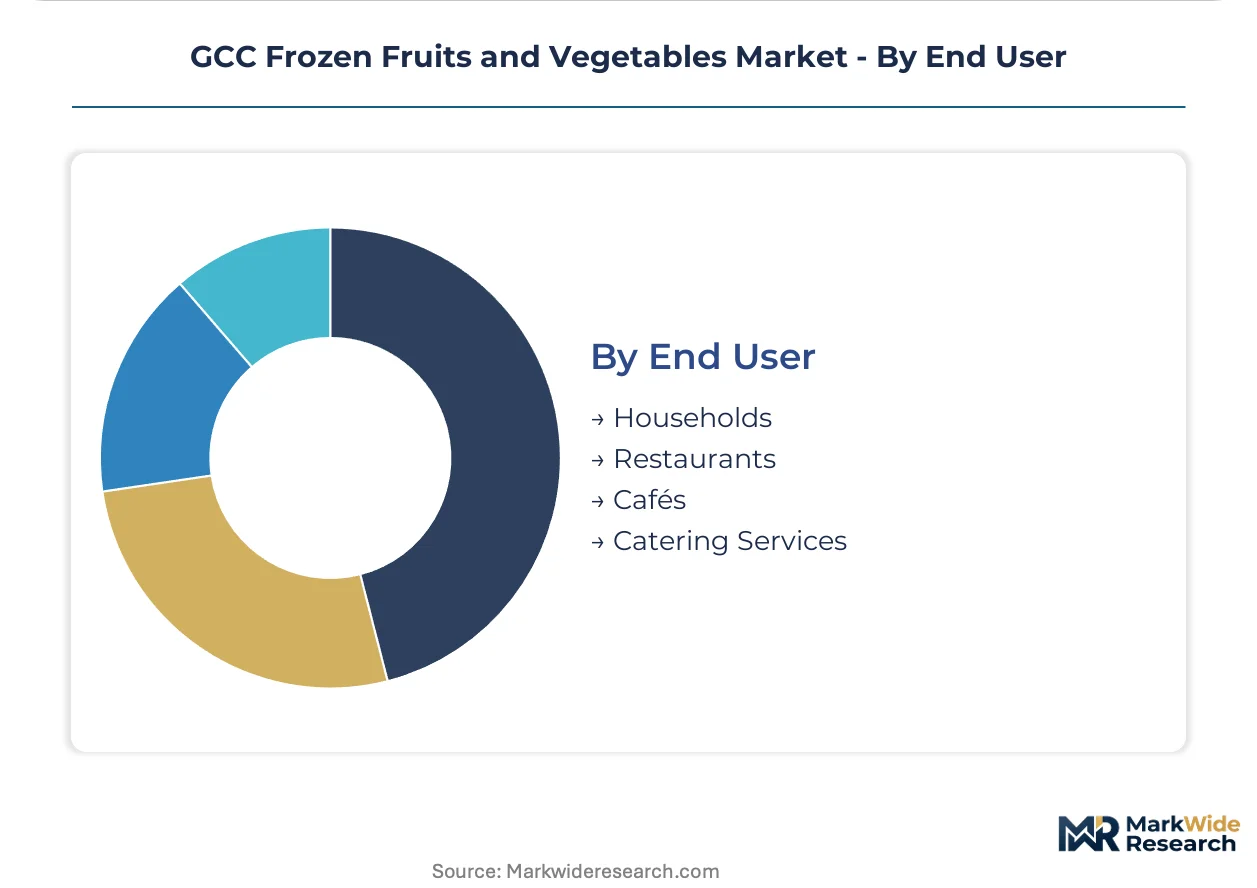
Restaurants holds the largest share; Cafés gains momentum fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The GCC frozen produce trade exhibits a pronounced re-export orientation, with Dubai's logistics infrastructure absorbing Egyptian and Sudanese raw material inflows before redistribution across smaller Gulf markets. Import dependency ratios exceed domestic processing capacity throughout the region, concentrating value-added freezing operations in Saudi Arabia and the UAE while Bahrain, Kuwait, and Oman remain net recipients.
Saudi Arabia
Central kitchen proliferation across Riyadh and Jeddah hospitality chains compresses procurement cycles toward single-source standardization. SFDA cold-chain traceability mandates require serialized temperature logging from farm gate to freezer, disqualifying uncertified distributors from government and airline catering tenders. The King Abdullah Economic City food processing zone anchors blast-freezing capacity expansion serving domestic HORECA channels.
United Arab Emirates
Dubai's logistics free zones offer temperature-controlled warehousing that reduces spoilage losses for berry and leafy green re-export across Bahrain, Kuwait, and Oman. MOHAP food safety standards and ESMA labeling requirements for origin disclosure reshape packaging investment priorities. Jebel Ali's cold-storage cluster concentrates three-quarters of regional blast-freezing infrastructure ownership.
Kuwait
Independent restaurants exhibit lower frozen vegetable substitution rates than Saudi or Emirati counterparts, presenting first-mover expansion potential for customized bulk format suppliers. The national food safety authority enforces import documentation parallel to SFDA frameworks, rewarding HACCP-compliant operators with preferred vendor status in institutional tenders. Shuwaikh's port modernization expands temperature-controlled handling capacity for Egyptian frozen produce arrivals.
Bahrain
Airline catering divisions at Bahrain International Airport expand frozen produce procurement volumes as Gulf carrier hub operations scale. The national standards body implements ESMA-aligned labeling requirements that mandate freezing date disclosure on retail packaging. Mina Salman industrial zone hosts emerging cold-chain infrastructure serving domestic foodservice and re-export to Eastern Saudi Arabia.
Oman
Sohar Port's free zone development targets frozen produce transshipment between Indian Ocean suppliers and GCC markets, though cold-chain infrastructure lags Dubai's maturity. The Ministry of Commerce and Industry enforces import quality standards that privilege certified suppliers with documented traceability. Muscat's hospitality sector growth drives foodservice channel expansion for frozen berry and leafy green procurement.
GCC Frozen Fruits and Vegetables Market Key Industry Players
On the supply side, the industry is consolidating around three strategic archetypes: controlled-environment agriculture specialists shortening farm-to-freezer cycles, backward-integrated agribusinesses securing year-round raw material flows from Egyptian and Sudanese operations, and HORECA-channel distributors dominating institutional procurement in underserved smaller Gulf markets. Competitive dynamics center on HACCP certification acquisition for SFDA tender eligibility and modular nitrogen tunnel freezing adoption to match processing volume with seasonal demand fluctuation.
Within the controlled-environment agriculture tier, Pure Harvest Smart Farms exemplifies premium positioning through vertical farming integration that preserves cellular structure in frozen leafy greens. Al Dahra Agriculture anchors the backward-integrated archetype through upstream control over Nile Basin growing operations. Gorika Group occupies the HORECA-channel specialist position in Kuwait and Bahrain with customized bulk packaging formats targeting independent restaurant procurement.
| Leading Market Players |
|---|
| Fresh Fruits Company |
| Al Jazira Agriculture |
| Pure Harvest Smart Farms |
| VeggiTech |
| Gorika Group |
| Al Dahra Agriculture |
| Abu Dhabi Farmers' Services Center |
| Emirates Hydroponics Farms |
| Al Ghurair Foods |
| Others |
Cost & Logistics Intelligence
Blast-freezing capacity underutilization in Dubai's Jebel Ali cold-storage cluster is compressing spot pricing for frozen berry processing while tightening contract terms for leafy green suppliers facing SFDA serialization mandates. This utilization asymmetry rewards operators with modular nitrogen tunnel systems that can flex throughput seasonally, while penalizing fixed-chamber owners locked into annual volume commitments with thinning margins.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in GCC frozen produce procurement. Price differentiation rests on HACCP certification grade and volume scale, with dual-certified organic-halal suppliers commanding 15-20% premiums over commodity-grade operators. Cost compression in standard-tier bulk containers is intensifying because Egyptian pound volatility feeds into raw material input instability. Quick-service restaurant chains exhibit highest price sensitivity due to centralized procurement consolidation, while UAE airline caterers show lowest sensitivity given traceability compliance requirements.
Supply Chain Analysis
Export-control regimes on advanced individual quick freezing technology limit equipment flows from European and Japanese manufacturers into Gulf processing facilities, constraining capacity expansion timelines. Geographic supply concentrates in Egypt, Sudan, and domestic UAE controlled-environment agriculture operations for raw material sourcing. Raw material dependencies center on Nile Basin vegetable harvests, imported berry cultivars, and nitrogen cryogenic supplies. Single-source vulnerability runs through Dubai's three-blast-freezing-operator bottleneck. Distribution runs through temperature-controlled logistics free zones with re-export orientation across Bahrain, Kuwait, and Oman.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shortage of certified cold-chain engineers and thermal logistics specialists across GCC universities is constraining blast-freezing capacity expansion and forcing wage inflation that erodes processor margins. This talent scarcity favors incumbents with established training pipelines and locks out undercapitalized entrants from SFDA tender eligibility.
For Market Incumbents: Harden HACCP-certified traceability documentation systems against SFDA serialization mandate expansion beyond frozen berries into leafy greens and root vegetables. Deepen backward integration into Sudanese growing operations to secure year-round raw material flows insulated from Nile water allocation disputes. Lock in multi-year leasing arrangements for modular nitrogen tunnel freezing units before equipment lead times extend further. For New Entrants and Emerging Players: Establish a beachhead in Kuwait and Bahrain HORECA channels where independent restaurant frozen vegetable substitution rates lag Saudi and Emirati benchmarks by 30-40%. Target customized bulk packaging formats that incumbent distributors have neglected in pursuit of centralized kitchen consolidation. Lead with halal-certification integration for slaughter-free process verification to capture emerging SFDA compliance differentiation. For Investors and Strategic Acquirers: Capital is best deployed toward controlled-environment agriculture specialists with vertical farming integration that shortens farm-to-freezer cycles below 48 hours. Long-term viability across the projection horizon favors operators with captive supply of premium leafy greens and direct API integration with central kitchen ERP systems. Watch for SFDA expansion of temperature excursion documentation requirements to stone fruits as the inflection signal for accelerated compliance infrastructure investment.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Nitrogen Tunnel Freezing Adoption | Scalable throughput matching seasonal demand fluctuation reduces capital intensity for Saudi central kitchen operators. |
| Backward Integration into Sudanese Growing Operations | Upstream control over Nile Basin harvests insulates year-round supply commitments from Egyptian currency volatility. |
| HACCP-Halal Dual Certification Investment | Compliance differentiation unlocks preferred vendor status in SFDA government tenders and UAE airline catering contracts. |
| IoT-Enabled Cold-Chain Monitoring Deployment | Real-time temperature logging infrastructure satisfies ESMA serialization mandates and excludes uncertified competitors. |
| Online Retail Pouch Format Expansion | Portion-controlled packaging addresses single-household delivery economics through Talabat and Noon dark store fulfillment. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with cold-chain logistics directors, central kitchen procurement heads, SFDA compliance officers, and airline catering supply managers; and secondary validation through customs trade databases, ESMA regulatory filings, Gulf food safety authority guidance documents, and hospitality sector procurement tender records. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Forecast inputs incorporated product type segmentation across berries, leafy greens, root vegetables, and stone fruits; packaging format differentiation between bulk containers, pouches, bags, and boxes; and distribution channel splits across foodservice, supermarkets, online retail, and grocery stores. CAGRs were derived from volume trajectory modeling calibrated to cold-chain infrastructure expansion timelines and regulatory compliance phase-in schedules. Industry-specific inputs included SFDA serialization mandate enforcement timelines and controlled-environment agriculture capacity buildout rates.
Macroeconomic conditions sit as an overlay; deviation in Egyptian pound exchange rates, Nile water allocation rulings, or Gulf hospitality sector employment growth would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and cold-chain infrastructure investment continuity. Material shifts in SFDA halal certification integration requirements or Dubai logistics free zone tariff structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Dry Mix Base for Frozen Desserts Market
Processed and Frozen Foods
South America Frozen Desserts Market
Processed and Frozen Foods
Germany Frozen Snack Market
Processed and Frozen Foods
Low-Fat Cool Whip Market
Processed and Frozen Foods
Freeze Dried Tropical Fruits Market
Processed and Frozen Foods
Freeze Dried Fruit Extract Market
Processed and Frozen Foods
Frozen Noodles and Rice Products Market
Processed and Frozen Foods
Frozen Fruit Bars Market
Processed and Frozen Foods
GCC Frozen Finger Chips Market
Processed and Frozen Foods
Frozen Desserts Market
Processed and Frozen Foods
Refrigerated & Frozen Soup Market
Processed and Frozen Foods
Freeze-Dried Food Market
Processed and Frozen Foods
Frozen Mackerel Market
Processed and Frozen Foods
Dehydrated Food Market
Processed and Frozen Foods
Global Chilled and Deli Foods Market
Processed and Frozen Foods
Asia-Pacific Frozen Yogurt Market