
 Frozen Meat Grinder Market | 2026-2036
Frozen Meat Grinder Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Meat Grinder Market Foresight
Food processing plants are broadening their share of frozen meat grinder procurement as butcher shops consolidate into centralized processing. GEA Food Solutions leverages its refrigeration-grinding integration to dominate European plant installations. Marel sustains technology leadership through automated portion-control systems that reduce giveaway. Hobart anchors the North American mid-market with service networks that shorten downtime for high-volume processors.
A frozen meat grinder is a refrigerated size-reduction machine that maintains sub-zero temperatures through jacketed housings and cryogenic or mechanical cooling circuits, typically processing blocks at minus 18 to minus 25 degrees Celsius to prevent fat smearing and microbial proliferation during comminution. Its primary purpose is to produce uniform particle distributions for sausage, ground meat, and further-processed products while preserving food safety and texture. Electric grinders lead the product type landscape due to throughput reliability in continuous operations, while blade technology commands the technology dimension because replaceable helical and kidney configurations adapt to varying fat-lean ratios. Industrial grinders represent the fastest-growing product tier as multi-national meatpackers replace legacy batch equipment with continuous-line systems.
FDA food contact substance regulations and EU MDR hygiene requirements shape grinder design by mandating 304 or 316 stainless steel surfaces, seamless welds, and clean-in-place validation protocols that add engineering cost but create compliance barriers for low-cost entrants. USDA inspection guidelines for official establishments further constrain market access by requiring equipment that supports HACCP documentation and traceability. Stakeholders must monitor how dual carbon goals in China and the EU are pressuring refrigerant choices in grinder cooling systems, as this will determine which suppliers retain specification approval in cross-border tenders.
Market Dynamics
Centralized meat processing consolidation is forcing grinder procurement toward continuous-line systems that integrate refrigeration, grinding, and portion control into single workflows. This structural pull favors capital-intensive equipment over standalone batch units.
Growth Catalysts
- EU MDR hygiene mandates:Stainless steel surface requirements and seamless weld standards are accelerating replacement cycles among European processors seeking compliance certification.
- Cryogenic cooling circuits:Mechanical refrigeration advances enable sub-zero temperature maintenance without liquid nitrogen dependency, reducing operating costs for high-throughput plants.
- Contract manufacturing expansion:Food processing plants in Germany are adding frozen grinding capacity to serve private-label sausage demand across Central European retail chains.
Market Restraints
- 316 stainless steel input costs:Nickel price volatility directly impacts jacketed housing fabrication, compressing margins for mid-tier equipment suppliers.
- German supplier concentration:ERBEL GmbH and Paul Kolbe GmbH anchor a dense cluster serving regional meatpackers, creating procurement bottlenecks during capacity crunches.
- F-Gas Regulation phase-down:EU restrictions on hydrofluorocarbon refrigerants are forcing cooling system redesigns that extend engineering timelines.
Strategic Opportunities
- USDA official establishment certification:Equipment supporting HACCP documentation and traceability opens access to federally inspected US processing facilities.
- Refrigeration-grinding integration:Combined mechanical cooling and size-reduction systems eliminate intermediate handling stages for multinational meatpackers.
- Clean-in-place validation protocols:Automated sanitation systems reduce labor costs and downtime, creating specification advantages in tender evaluations.
Industry Challenges
- Helical blade metallurgy expertise:Fat-lean ratio adaptation requires specialized heat-treatment knowledge that resides with a limited supplier base.
- Legacy batch equipment integration:Continuous-line retrofits demand custom engineering to interface with existing material handling infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Meat Grinder Market |
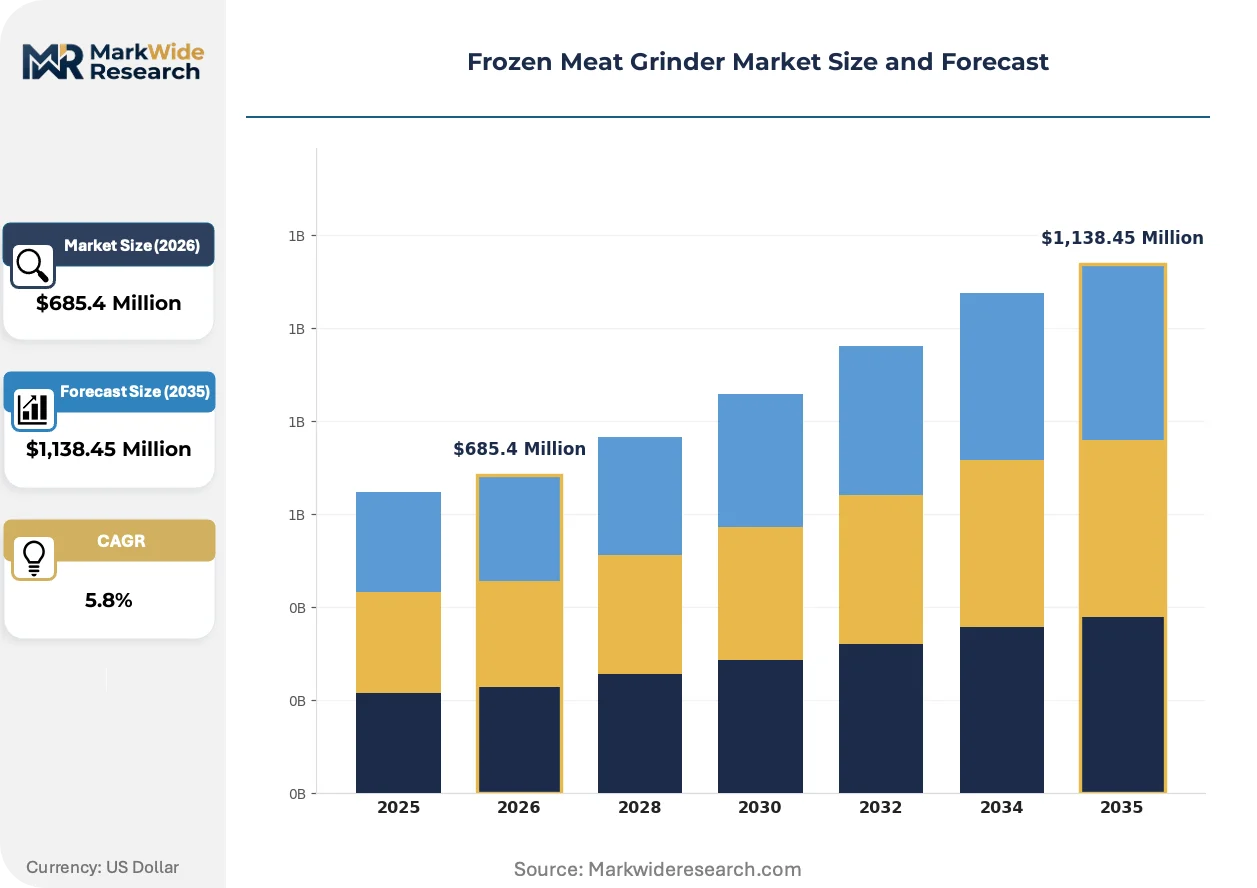
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Grinder, Electric Grinder, Commercial Grinder, Industrial Grinder Technology: Blade, Screw, Hydraulic, Pneumatic, Food Processor Application: Butcher Shops, Food Processing Plants, Catering Services, Meat Packaging Units End User: Restaurants, Hotels, Food Distributors, Quality Control Labs |
| Companies Covered | Barsso, ERBEL GmbH, GEA Food Solutions, Paul Kolbe GmbH, Hobart, Skyfood Equipment, Minerva Omega Group, BIRO Manufacturing, Marel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Meat Grinder Market Shifts & Advancements
Equipment design is pivoting toward closed-loop thermal management and automated portion control as processors seek to eliminate giveaway and microbial risk simultaneously. These advances are compressing the performance gap between premium and mid-market tiers.
Cryogenic nitrogen injection systems are converging with mechanical refrigeration circuits to create hybrid cooling architectures that maintain minus 25 degrees Celsius block temperatures. Multi-national meatpackers in Northern Europe are adopting these configurations fastest. This convergence is enabling single-pass grinding of previously frozen-then-thawed product categories, expanding addressable raw material inputs.
EU F-Gas Regulation refrigerant phase-down schedules are forcing cooling system redesigns toward natural refrigerants like CO2 and ammonia cascades. Equipment manufacturers must revalidate thermal performance under new fluid properties. German engineering clusters are responding with prototype test rigs ahead of 2030 compliance deadlines.
Buyer concentration among centralized processing cooperatives is displacing fragmented butcher shop procurement across Central European markets. Equipment vendors now face consolidated tender processes with longer sales cycles but larger contract values. This pattern is most visible in Bavaria and Baden-Württemberg, where rural slaughterhouse closures have accelerated since 2020.
Frozen Meat Grinder Market Segmentation
Frozen meat grinder procurement splits sharply between volume-driven industrial installations and precision-focused commercial units. Understanding these divides reveals where capital flows concentrate and which specifications command premium pricing.
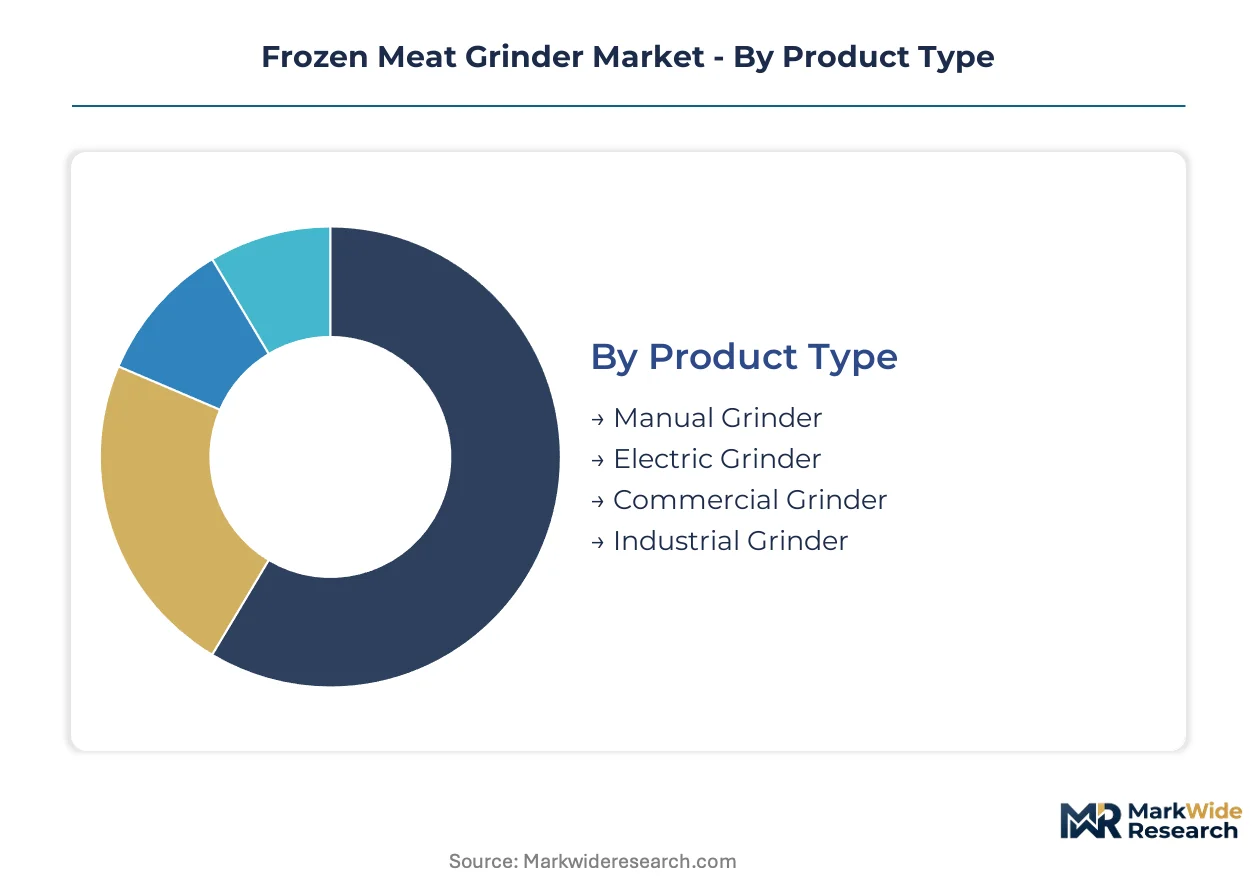
Product Type:
Volume tiers separate intermittent-use equipment from continuous-line systems designed for 24-hour operations. Electric and industrial configurations capture the bulk of replacement spending as processors consolidate capacity.
- Manual Grinder:Hand-cranked cast-iron or stainless steel units for specialty butchery and artisanal sausage production. Demand persists in Bavarian farm shops and Swiss Alpine processing cooperatives where batch sizes stay below 50 kilograms daily.
- Electric Grinder:Belt-driven or direct-drive motors delivering 200-800 kilograms per hour through standardized plate configurations. Food processing plants in Germany's Baden-Württemberg region specify these for mid-volume private-label contracts requiring flexibility across pork, beef, and poultry inputs.
- Commercial Grinder:Floor-standing units with integrated refrigeration jackets for independent meatpackers and regional distributors. These bridge the gap between batch and continuous operation with clean-in-place compatibility.
- Industrial Grinder:Continuous-line systems integrating cryogenic cooling, automated portion control, and HACCP data logging for multinational meatpackers. These configurations are expanding most quickly as centralized processing cooperatives replace legacy equipment across Central Europe.
Today's leader: Industrial Grinder. Tomorrow's challenger: Commercial Grinder.
Technology:
Cutting mechanism selection determines fat-lean ratio precision, thermal management efficiency, and maintenance intervals. Blade and screw systems dominate installed capacity while alternative drives address niche throughput requirements.
- Blade:Replaceable helical and kidney-shaped cutters in hardened tool steel or ceramic composites. German engineering clusters around ERBEL GmbH and Paul Kolbe GmbH concentrate metallurgical expertise for these configurations, creating specification advantages in EU MDR-compliant tenders.
- Screw:Auger-driven compression through perforated plates with variable pitch geometry. These systems handle higher fat content without temperature excursions and are gaining share fastest in poultry grinding applications where mechanical cooling integration matters most.
- Hydraulic:High-pressure piston drives for frozen block reduction in rendering and pet food processing. Limited to specialty applications where particle uniformity is secondary to throughput volume.
- Pneumatic:Compressed-air actuation for explosion-risk environments and mobile processing units. Deployed in temporary slaughterhouse installations and military field kitchens requiring spark-free operation.
- Food Processor:Multi-function benchtop units with grinding attachments for small-scale catering and quality control sampling. Restricted to sub-20 kilogram hourly capacity with no integrated temperature control.
Blade technology anchors current procurement. Screw configurations are climbing the fastest as refrigeration integration becomes standard.
Application:
End-use concentration shapes equipment specification, with centralized processing demanding continuous-line systems while fragmented retail channels sustain batch equipment demand.
- Butcher Shops:Declining installed base as rural slaughterhouse closures accelerate across Bavaria and rural France. Remaining operations specify compact electric grinders with NSF certification for direct retail sale compliance.
- Food Processing Plants:The dominant demand source, with German facilities expanding frozen grinding capacity for contract manufacturing of private-label sausage across Central European retail chains. These installations specify integrated refrigeration-grinding systems with USDA or EU MDR validation.
- Catering Services:Mobile and institutional kitchens requiring NSF-listed equipment for HACCP compliance. Volume constraints favor commercial-grade electric units over industrial continuous lines.
- Meat Packaging Units:Pre-portioning operations for retail-ready ground meat and patty forming. These facilities prioritize screw technology with precise fat analysis integration for label accuracy.
Food Processing Plants dominate capital deployment. Meat Packaging Units represent the steepest expansion trajectory as retail-ready product formats multiply.
End User:
Customer type determines specification complexity, with regulated establishments demanding traceability features absent in hospitality procurement.
- Restaurants:Independent and chain kitchens specifying countertop electric grinders for in-house burger and sausage programs. Volume limitations restrict demand to sub-500 kilogram daily throughput equipment.
- Hotels:Banquet and room service operations with intermittent grinding requirements. These buyers prioritize compact footprint and rapid clean-in-place cycles over maximum hourly capacity.
- Food Distributors:Centralized meatpacking and redistribution facilities serving retail and foodservice channels. These operations specify industrial continuous-line systems with automated portion control to minimize giveaway.
- Quality Control Labs:Analytical and R&D facilities requiring precise particle size distribution for product development and regulatory sampling. These niche buyers specify laboratory-grade blade systems with temperature logging and batch documentation.
Food Distributors capture the largest contract values. Quality Control Labs present premium pricing opportunities despite limited volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping frozen meat grinder procurement as processors migrate capacity toward jurisdictions with favorable compliance-cost structures. Equipment vendors are responding with modular designs that satisfy multiple regulatory regimes simultaneously.
Germany
ERBEL GmbH and Paul Kolbe GmbH anchor a dense engineering cluster in Baden-Württemberg serving Central European meatpackers. EU MDR hygiene mandates and F-Gas Regulation refrigerant phase-downs are accelerating replacement cycles among processors seeking compliance certification. Bavarian food processing plants are expanding frozen grinding capacity to capture private-label sausage contracts across retail chains.
United States
USDA official establishment certification requirements are concentrating demand among federally inspected facilities that require HACCP documentation and traceability features. FDA food contact substance regulations mandate 304 or 316 stainless steel surfaces that add engineering cost but create compliance barriers for low-cost entrants. Midwestern meatpacking corridors in Iowa and Nebraska are retrofitting legacy batch equipment with continuous-line systems.
China
Dual carbon goals under MEE oversight are pressuring refrigerant choices in grinder cooling systems, determining which suppliers retain specification approval in cross-border tenders. SAMR food safety standards are tightening surface finish requirements for imported equipment. Yangtze River Delta processing hubs are adopting hybrid cooling architectures that maintain sub-zero temperatures without liquid nitrogen dependency.
Italy
Minerva Omega Group exemplifies regional specialization in blade metallurgy for fat-lean ratio adaptation. EFSA hygiene guidelines and national HACCP enforcement are displacing fragmented butcher shop procurement toward centralized cooperatives. Emilia-Romagna sausage producers are specifying clean-in-place validation protocols to reduce labor costs and downtime.
Netherlands
GEA Food Solutions leverages refrigeration-grinding integration to dominate plant installations serving Benelux retail chains. REACH chemical compliance and CE marking requirements shape stainless steel sourcing decisions for jacketed housings. Randstad logistics corridors enable rapid equipment deployment for contract manufacturing expansions.
Frozen Meat Grinder Market Competitive Landscape
Capacity expansion dominates the current landscape as established fabricators scale output to serve consolidating meatpacker procurement. The vendor base separates into three distinct tiers: integrated refrigeration-grinding specialists, standalone equipment fabricators, and regional service-network operators. Strategic archetypes include technology licensors leveraging patent positions, vertically integrated stainless steel processors controlling input costs, and cooperative-owned engineering clusters serving localized demand. M&A activity and geographic licensing agreements represent the dominant competitive moves as players seek specification approval in cross-border tenders.
Among German engineering clusters, ERBEL GmbH and Paul Kolbe GmbH occupy positions within the precision-blade fabrication archetype, exemplifying regional concentration of metallurgical expertise. GEA Food Solutions, Marel, and Hobart represent contrasting scale-driven and service-network archetypes. These named entities anchor industry-level commentary without implying specific strategic actions or market positions beyond their visible structural roles.
| Leading Market Players |
|---|
| Barsso |
| ERBEL GmbH |
| GEA Food Solutions |
| Paul Kolbe GmbH |
| Hobart |
| Skyfood Equipment |
| Minerva Omega Group |
| BIRO Manufacturing |
| Marel |
| Others |
Supply & Pricing Matrix
EU MDR hygiene mandates and F-Gas refrigerant phase-downs are forcing processors to specify stainless steel jacketed housings and redesigned cooling circuits, which concentrates procurement among German engineering clusters and compresses margins for mid-tier fabricators unable to absorb nickel volatility or revalidation costs.
Pricing Analysis
Distributor margins for industrial frozen meat grinders typically run 12-18 percent above factory gate, with direct-to-OEM contracts commanding 8-12 percent discounts for volume commitments above 50 units annually. Three-tier pricing structure across premium, standard, and economy levels separates EU MDR-validated continuous-line systems from NSF-certified commercial units and basic electric batch grinders. Price differentiation hinges on certification grade and refrigeration integration depth. Cost compression in the standard tier is intensifying because nickel price volatility feeds directly into 316 stainless steel housing fabrication. Food processing plants show least price sensitivity due to compliance-driven replacement cycles, while independent butcher shops face acute budget constraints.
Supply Chain Analysis
Workforce availability for precision blade heat-treatment and cryogenic welding concentrates in Baden-Württemberg engineering clusters, with secondary fabrication capacity in northern Italy and scattered tool-steel processing in the United States. Raw material inputs draw from Swedish specialty steel mills for helical cutter blanks, Chinese rare-earth elements for magnetic drive components, and German refrigerant compressor assemblies. Single-source vulnerability sits with the limited supplier base holding metallurgical expertise for fat-lean ratio adaptation. Distribution runs through regional equipment distributors serving meatpacking cooperatives, with direct OEM relationships dominating multinational accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The frozen meat grinder market functions as a stable compounder anchored by regulatory-driven equipment replacement cycles that refresh installed bases regardless of protein demand fluctuations.
For Market Incumbents: Anticipate margin compression from nickel volatility and F-Gas compliance revalidation costs by deepening backward integration into stainless steel processing and captive refrigerant compressor assembly. Secure specification lock-in through early EU MDR certification and clean-in-place protocol patents before 2030 compliance deadlines harden procurement criteria. For New Entrants and Emerging Players: Quality control laboratories and R&D facilities present underserved buyer archetypes with premium pricing tolerance and limited incumbent presence. Target screw-technology configurations for poultry grinding applications where mechanical cooling integration creates specification gaps among blade-focused German specialists. Lead with automated HACCP documentation as your go-to-market wedge. For Investors and Strategic Acquirers: Asymmetric upside sits with precision-blade metallurgy specialists possessing heat-treatment IP and established EU MDR validation pathways. The five-to-ten-year viability window favors acquisition targets with captive stainless steel sourcing and refrigeration-grinding integration capabilities. Monitor F-Gas Regulation enforcement intensity as the signal for cooling system redesign demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigeration-Grinding Integration | Combined mechanical cooling and size-reduction eliminates handling stages for multinational meatpackers. |
| EU MDR Certification Investment | Stainless steel surface validation and seamless weld protocols create compliance barriers for low-cost entrants. |
| Natural Refrigerant Transition | CO2 and ammonia cascade redesigns ahead of F-Gas deadlines secure specification approval in cross-border tenders. |
| Clean-in-Place Protocol Development | Automated sanitation systems reduce labor costs and downtime for centralized processing cooperatives. |
| Helical Blade Metallurgy IP Acquisition | Heat-treatment expertise for fat-lean ratio adaptation concentrates among limited German engineering clusters. |
Research Methodology
Direct dialogue with plant engineers at food processing facilities, procurement leads at meatpacking cooperatives, aftermarket service heads at equipment distributors, and regulatory compliance officers at stainless steel fabricators grounded qualitative findings. Secondary validation drew from EU MDR technical documentation, FDA food contact substance filings, F-Gas Regulation implementation schedules, and German engineering cluster trade association reports. Bottom-up unit economics triangulated against top-down protein processing capacity expansion announcements.
Segment-level value outputs across the projection horizon reflect modeled interactions between product type, technology configuration, and end-use concentration. The analytical framework incorporated electric versus manual drive architectures, blade versus screw cutting mechanisms, and butcher shop versus food processing plant demand patterns. CAGRs were derived from replacement cycle timing, regulatory compliance deadlines, and contract manufacturing expansion trajectories. Cryogenic cooling circuit adoption rates and centralized cooperative procurement consolidation served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; industrial grinder and food processing plant categories carry tighter precision than manual grinder and butcher shop classifications due to visible tender documentation and capacity announcement transparency. Forecasts reflect assumptions around EU MDR enforcement consistency, nickel price stability, and F-Gas phase-down adherence. Material deviation in refrigerant regulatory timelines or protein demand shocks warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Processed and Frozen Vegetables Market
Processed and Frozen Foods
Global Frozen Breakfast Entrees/Sandwiches Market
Processed and Frozen Foods
Frozen Snacks Market
Processed and Frozen Foods
Europe Frozen Pizza Market
Processed and Frozen Foods
Cold Storage Market
Processed and Frozen Foods
Frozen Mushroom Market
Processed and Frozen Foods
Asia-Pacific Frozen Yogurt Market
Processed and Frozen Foods
Frozen Pork Belly Market
Processed and Frozen Foods
Low-Fat Cool Whip Market
Processed and Frozen Foods
Freeze Dried Fruit Extract Market
Processed and Frozen Foods
GCC Frozen Fruits and Vegetables Market
Processed and Frozen Foods
Kimchi Market
Processed and Frozen Foods
Popsicle and Ice Cream Bar Market
Processed and Frozen Foods
Freeze Dried Vegetables Market
Processed and Frozen Foods
Asia-Pacific Frozen Pizza Market
Processed and Frozen Foods
Europe Ice Cream Market