
 Fruit Puree Market | 2026-2036
Fruit Puree Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit Puree Market Analysis
Asset-light contract processing and third-party toll manufacturing is rewriting competitive entry dynamics for mid-tier puree suppliers. Döhler GmbH leverages its German ingredient technology base to sustain integrated flavor-puree formulations for beverage clients. SVZ International anchors European supply through specialized red fruit processing in the Netherlands and Poland. Tree Top competes from the Pacific Northwest with controlled orchard relationships and proprietary apple varietal programs.
Fruit puree consists of mechanically processed whole or peeled fruit reduced to a smooth, pumpable consistency, typically containing 10-30% natural soluble solids depending on source fruit and intended application. Industrial buyers specify brix levels, pulp content, and microbiological stability parameters to match formulation requirements in downstream manufacturing. Organic puree commands structural premiums in infant food applications where EFSA residue thresholds and parental label scrutiny concentrate margin pools. Beverage applications represent the highest-volume consumption channel, though bakery and sauces segments show faster format diversification into aseptic pouches and bag-in-box delivery systems.
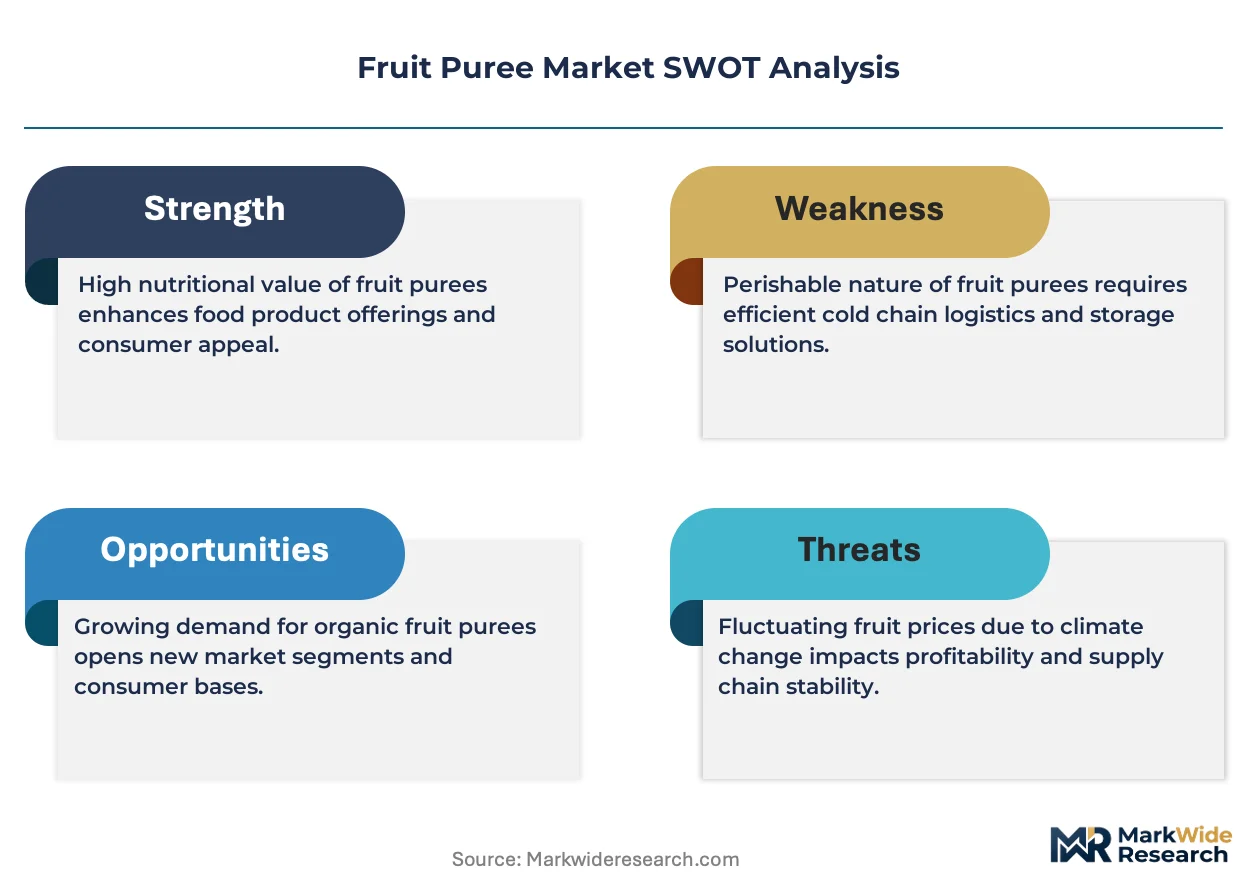
EU Green Deal farm-to-fork targets and REACH chemical safety protocols shape ingredient traceability mandates across European puree supply chains. FDA enforcement of Food Safety Modernization Act preventive controls affects import qualification for tropical puree entering US food manufacturing channels. Stakeholders must monitor evolving pesticide maximum residue limits from EFSA and emerging state-level packaging extended producer responsibility laws in California and New York that will reshape cost structures for single-serve and bulk formats alike.
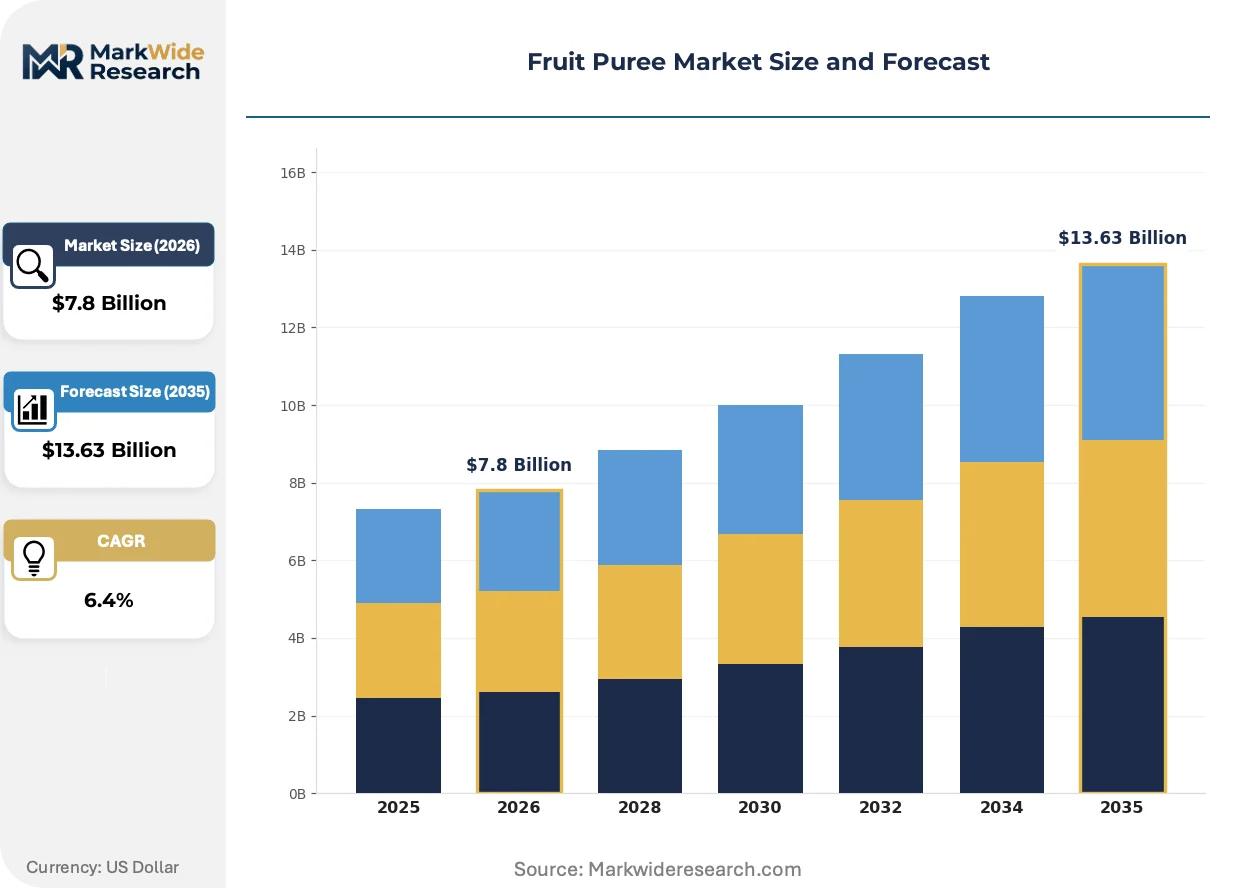
Market Dynamics
Clean-label formulation mandates from EFSA and the EU Green Deal are compressing conventional supply chains while accelerating organic procurement cycles across European infant food manufacturing.
Growth Catalysts
- EU Green Deal farm-to-fork targets:Sustainability criteria now govern procurement decisions for German and French infant food manufacturers, creating structural demand pull for certified organic puree supply.
- Aseptic processing technology:High-barrier pouch and bag-in-box formats extend shelf stability without refrigeration, unlocking foodservice and remote distribution channels for tropical fruit varieties.
- Red fruit concentrate demand:Beverage manufacturers in the Netherlands and Poland specify higher pulp content for premium smoothie applications, tightening supply for strawberry and raspberry puree grades.
Market Restraints
- Weather-dependent raw material volatility:Apple and stone fruit harvests in the Pacific Northwest face compression from irrigation constraints and heat stress, destabilizing input cost baselines for contract manufacturers.
- Single-source geography risk:Tropical puree processing concentrates in Southeast Asian corridors where port congestion and container availability create supply continuity exposure for European importers.
- REACH chemical safety protocols:ECHA registration requirements for processing aids and sanitizers extend qualification timelines for new supplier onboarding, creating friction for category expansion.
Strategic Opportunities
- Extended producer responsibility laws:California and New York packaging mandates will reshape cost structures for single-serve formats, creating first-mover advantage for recyclable pouch technologies.
- Controlled orchard backward integration:Pacific Northwest operators with proprietary apple varietal programs capture margin pools lost to third-party toll processors in commodity segments.
- Bakery application diversification:Clean-label fruit fillings for artisan bread and pastry segments remain underpenetrated relative to beverage, offering volume expansion for mid-brix puree grades.
Industry Challenges
- Microbiological stability certification:FDA preventive controls under FSMA demand validated kill-step documentation that small-scale tropical processors struggle to produce, excluding them from US import qualification.
- Flavor-puree formulation integration:Beverage clients require synchronized delivery of fruit bases with natural flavor systems, forcing toll manufacturers to coordinate multi-ingredient supply timing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit Puree Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Puree, Conventional Puree, Frozen Puree, Dried Puree Application: Beverages, Infant Food, Bakery Products, Sauces Packaging Type: Tetra Pak, Pouches, Jars, Cans End User: Food Manufacturers, Retailers, Restaurants, Household |
| Companies Covered | AGRANA Beteiligungs-AG, Döhler GmbH, Ingredion, Dennick FruitSource, Tree Top, Oregon Fruit Products, Kerry Group, SVZ International, Uren Food Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit Puree Market Emerging Trajectories
Processing technology and packaging format evolution are compressing traditional supply chain tiers while regulatory traceability mandates reconfigure procurement relationships across the value chain.
High-pressure processing (HPP) is migrating from niche organic segments into mainstream beverage manufacturing as a non-thermal pasteurization alternative. Mid-tier smoothie brands in Germany and France adopt HPP to extend refrigerated shelf life without chemical preservatives. This technology is compressing the advantage previously held by aseptic thermal processors, forcing equipment reinvestment across European toll manufacturing networks.
EFSA maximum residue limit (MRL) tightening for pesticide metabolites now governs import acceptance criteria for tropical puree entering EU infant food channels. The regulation disqualifies conventional mango and passion fruit lots from multiple origin countries, redirecting procurement toward certified organic supply pools with documented field-level compliance. Spanish and Italian processors respond by accelerating backward integration into North African organic orchard development.
Ingredient specification aggregation through beverage co-manufacturer platforms is consolidating purchase volumes previously fragmented across regional bakery and sauce producers. Large-format smoothie and juice brands now contract directly for tanker-load puree deliveries, bypassing traditional ingredient distributor tiers. This channel compression concentrates negotiating leverage with a handful of toll processors in the Netherlands and Germany.
Fruit Puree Market Segmentation
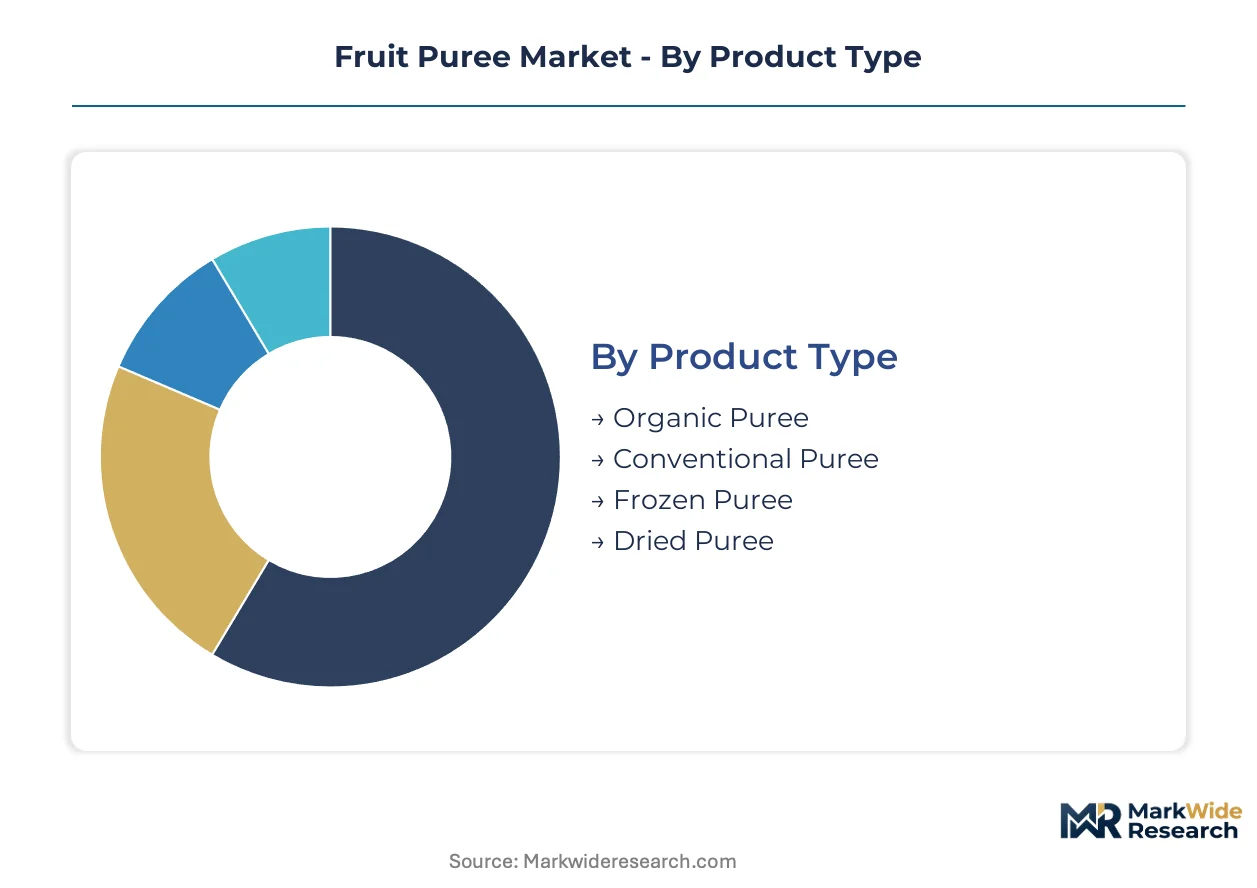
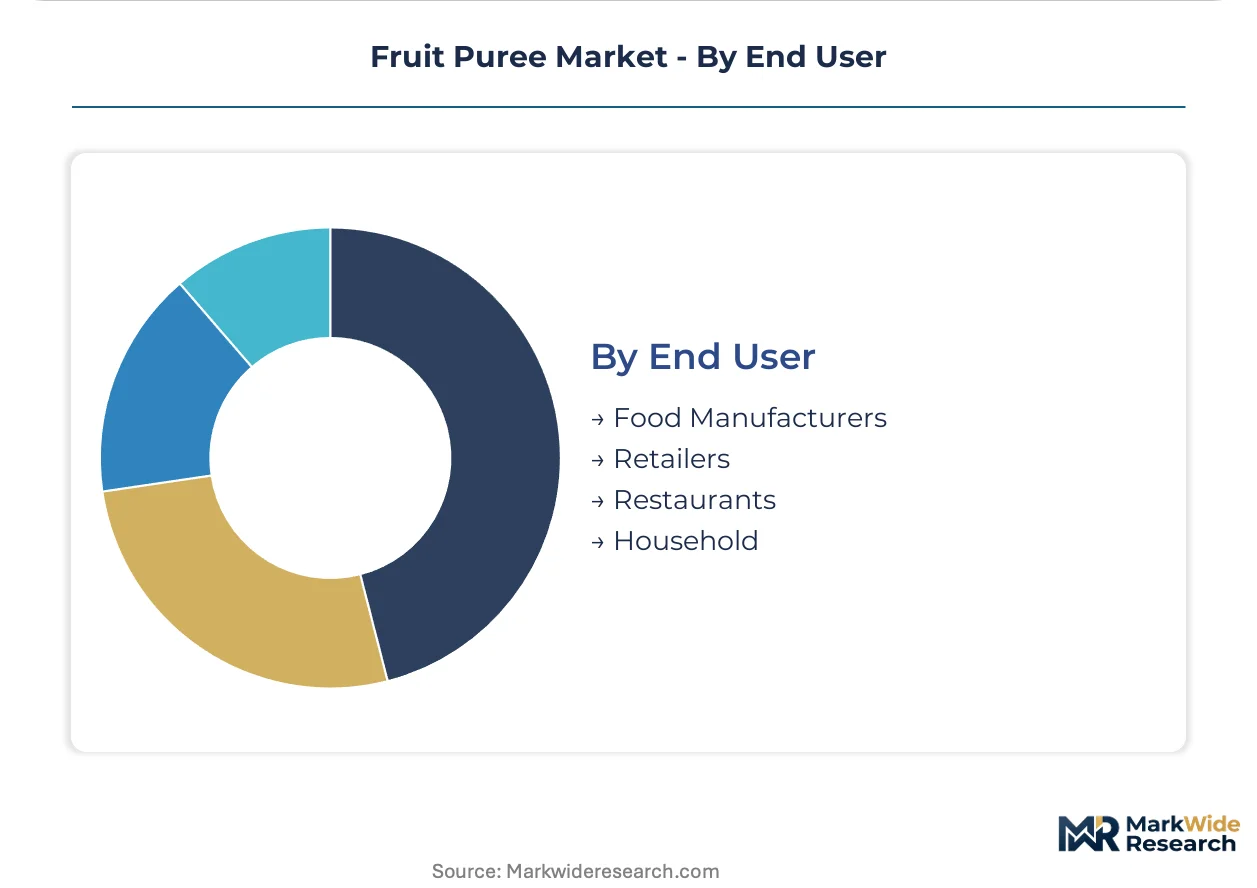
Fruit puree segmentation reveals how specification requirements diverge across infant food safety mandates, beverage formulation needs, and foodservice operational constraints. Buyers select grades based on brix targets, pulp content, and microbiological certification thresholds that vary sharply by downstream application.
Product Type:
Use-case spectrum spans residue-sensitive infant formulations to cost-optimized beverage bases with divergent certification burdens.
- Organic Puree:Certified production with documented field-level compliance and EFSA-aligned pesticide metabolite thresholds. German and French infant food manufacturers concentrate procurement here under EU Green Deal sustainability criteria, absorbing structural premiums for traceability assurance.
- Conventional Puree:Standard agricultural inputs with conventional processing aids. Beverage manufacturers in the Netherlands and Poland specify higher pulp content for mainstream smoothie applications where cost efficiency outweighs organic certification.
- Frozen Puree:Blast-frozen at -18°C to preserve volatile aromatic compounds without thermal degradation. Industrial bakeries and sauce producers favor this format for flavor retention in heat-processed finished goods.
- Dried Puree:Low-moisture powder form achieved through spray-drying or drum-drying. Nutritional bar manufacturers and dry mix applications specify this grade for extended ambient shelf stability and reduced freight costs.
Established volume favors conventional puree; emerging adoption favors organic puree.
Application:
Margin concentration shifts with formulation complexity and regulatory scrutiny intensity across end-use channels.
- Beverages:Highest-volume consumption channel encompassing smoothies, juices, and functional drinks. Dutch and German co-manufacturers specify tanker-load deliveries with synchronized natural flavor system integration.
- Infant Food:Most stringent microbiological stability requirements with validated kill-step documentation under FDA preventive controls. EFSA residue thresholds and parental label scrutiny sustain premium positioning.
- Bakery Products:Clean-label fruit fillings for artisan bread and pastry segments remain underpenetrated relative to beverage. Mid-brix puree grades suit laminated dough and fermented applications.
- Sauces:Tomato and tropical fruit bases for condiment and cooking sauce manufacturing. Aseptic bag-in-box formats extend foodservice distribution reach without refrigeration dependency.
Volume leadership sits with beverages; steepest expansion trajectory belongs to infant food.
Packaging Type:
Format selection balances shelf stability requirements against extended producer responsibility compliance costs.
- Tetra Pak:Aseptic carton systems with aluminum foil barrier layers. Long-life ambient distribution for retail juice and nectar applications dominates European procurement.
- Pouches:Flexible high-barrier laminates for single-serve and bulk foodservice delivery. California and New York packaging mandates will reshape cost structures for this format category.
- Jars:Glass containment with vacuum-sealed closures. Premium positioning for organic infant food where parental label scrutiny favors transparent packaging.
- Cans:Metal containment for institutional and remote distribution channels. Tropical puree processors in Southeast Asia favor this format for ocean freight durability.
Established infrastructure favors Tetra Pak; regulatory pressure favors pouch innovation.
End User:
Procurement scale and specification authority concentrate differently across integrated manufacturers versus fragmented foodservice operators.
- Food Manufacturers:Large-format smoothie and juice brands contract directly for tanker-load puree deliveries, bypassing traditional ingredient distributor tiers. Specification authority rests with beverage co-manufacturer platforms.
- Retailers:Private-label program development with strict clean-label and sustainability credential requirements. German and French retail chains drive organic puree volume through own-brand infant food lines.
- Restaurants:Foodservice operators specifying aseptic bag-in-box for back-of-house efficiency. Tropical fruit varieties gain traction in smoothie bar and casual dining channels.
- Household:Small-format retail purchases for home baking and direct consumption. Pouch formats dominate convenience-oriented positioning in this segment.
Negotiating leverage concentrates with food manufacturers; format experimentation flourishes among restaurants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Infant food manufacturers in Germany and France anchor procurement volume for organic puree grades, while beverage co-manufacturers in the Netherlands and Poland drive conventional demand for high-pulp red fruit varieties.
Germany
EU Green Deal sustainability criteria govern procurement decisions for infant food producers expanding organic puree sourcing. EFSA clean-label formulation mandates compress conventional supply chains while accelerating certified organic cycles. Bavarian ingredient technology clusters sustain integrated flavor-puree formulation capabilities for beverage clients.
France
Parental label scrutiny in infant food channels sustains premium positioning for single-fruit and blend organic varieties. REACH chemical safety protocols from ECHA extend qualification timelines for new supplier onboarding. Paris-based retail chains drive organic volume through private-label infant food program development.
Netherlands
Beverage manufacturers specify higher pulp content for premium smoothie applications, tightening supply for strawberry and raspberry puree grades. Aseptic processing technology adoption unlocks foodservice distribution channels for tropical fruit varieties. Specialized red fruit processing infrastructure concentrates in Dutch and Polish corridor operations.
United States
FDA enforcement of Food Safety Modernization Act preventive controls affects import qualification for tropical puree entering food manufacturing channels. California and New York state-level packaging extended producer responsibility laws reshape cost structures for single-serve and bulk formats. Pacific Northwest operators with controlled orchard relationships capture margin pools in apple varietal programs.
Poland
Red fruit concentrate demand from beverage co-manufacturers specifies tanker-load puree deliveries, bypassing traditional ingredient distributor tiers. EFSA maximum residue limit tightening for pesticide metabolites governs import acceptance criteria. Processing infrastructure in central Polish regions supports European supply chain consolidation for berry puree grades.
Fruit Puree Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. The vendor base organizes around integrated ingredient technology platforms, specialized toll processors, and orchard-backward operators. Three strategic archetypes dominate: flavor-puree integrators with beverage formulation capabilities, red fruit specialists with regional processing concentration, and Pacific Northwest operators with captive varietal programs. Competitive moves concentrate on capacity expansion in aseptic processing formats and strategic partnerships for organic supply chain certification.
Within the integrated ingredient technology tier, Döhler GmbH and Kerry Group occupy positions spanning formulation integration and multi-application supply. Among specialized toll processors, SVZ International exemplifies regional concentration advantages in red fruit processing corridors. At the orchard-backward end, Tree Top anchors controlled supply relationships in Pacific Northwest apple varietal development.
| Leading Market Players |
|---|
| AGRANA Beteiligungs-AG |
| Döhler GmbH |
| Ingredion |
| Dennick FruitSource |
| Tree Top |
| Oregon Fruit Products |
| Kerry Group |
| SVZ International |
| Uren Food Group |
| Others |
Supply Flow & Price Mechanics
Single-source geography risk in Southeast Asian tropical puree corridors dictates both the premium spread for certified organic grades and the consolidation pressure on European toll manufacturers seeking supply continuity assurance. EU Green Deal procurement mandates from German and French infant food producers compress conventional pricing tiers while amplifying structural premiums for traceable organic supply.
Pricing Analysis
Cost-plus contracts with indexed agricultural commodity benchmarks dominate long-term procurement agreements between beverage co-manufacturers and red fruit processors in the Netherlands and Poland. Price differentiation hinges on organic certification grade and volume scale, with tanker-load deliveries commanding standardization discounts against fragmented bakery and sauce segment orders. Cost compression in conventional puree grades intensifies as REACH protocol compliance extends qualification timelines and diverts procurement toward certified organic pools. Beverage manufacturers exhibit lowest price sensitivity due to formulation integration requirements, while foodservice operators in remote distribution channels face acute cost pressure from aseptic packaging format premiums.
Supply Chain Analysis
Tariff exposure between Southeast Asian processing hubs and European import gateways dominates supply chain risk calculus for tropical mango and passion fruit puree grades. Raw material sourcing concentrates in Thailand, Vietnam, and Indonesia for tropical varieties, while apple and stone fruit inputs draw from Pacific Northwest orchard operations in Washington and Oregon. Container availability volatility and port congestion in Southeast Asian corridors create single-source vulnerability for European infant food manufacturers dependent on tropical ingredient diversification. Distribution runs through specialized toll processors in the Netherlands and Germany before reaching beverage co-manufacturers and retail private-label programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-pressure processing technology migration from niche organic segments into mainstream beverage manufacturing constitutes a technological inflection reshaping competitive positioning and equipment reinvestment cycles across European toll manufacturing networks.
For Market Incumbents: Pre-empt HPP technology displacement by accelerating aseptic equipment reinvestment in Dutch and German processing corridors before mid-tier smoothie brands complete supplier qualification shifts. Defend margin pools through captive backward integration into North African organic orchard development, countering EFSA maximum residue limit tightening that disqualifies conventional tropical supply from infant food channels. For New Entrants and Emerging Players: Pursue underpenetrated bakery application segments for clean-label fruit fillings in artisan bread and pastry channels, where mid-brix puree grades face limited specialized competition relative to saturated beverage markets. Target recyclable pouch technology development for California and New York extended producer responsibility compliance, securing first-mover positioning ahead of incumbent format migration. For Investors and Strategic Acquirers: EU Green Deal farm-to-fork target implementation reshapes the acquisition landscape by concentrating valuation premiums on certified organic supply chain assets with documented field-level compliance infrastructure. Long-term viability favors toll processors with integrated flavor-puree formulation capabilities and controlled orchard relationships in climate-resilient geographies. Monitor EFSA pesticide metabolite threshold enforcement as the critical signal for procurement redirection timing and organic supply pool scarcity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Controlled Orchards | Pacific Northwest operators capture margin pools lost to third-party toll processors in commodity apple segments. |
| HPP Technology Deployment | Mid-tier German and French smoothie brands adopt non-thermal pasteurization to extend refrigerated shelf life without chemical preservatives. |
| Recyclable Pouch Format Development | California and New York packaging mandates create first-mover advantage for sustainable single-serve delivery systems. |
| North African Organic Orchard Development | Spanish and Italian processors accelerate field-level compliance infrastructure to meet EFSA residue threshold requirements. |
| Tanker-Load Direct Contracting | Large-format beverage brands bypass traditional ingredient distributor tiers, concentrating negotiating leverage with Dutch and German toll processors. |
Methodological Framework
A spread of perspectives from ingredient procurement managers at infant food manufacturers, beverage co-manufacturer technical directors, toll processing operations heads, and retail private-label program developers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against EFSA regulatory filings, EU Green Deal implementation documentation, FDA FSMA preventive control guidance, and trade flow records from customs and agricultural export databases. Bottom-up volume triangulation across product type, application, and packaging format segments was cross-checked against top-down market sizing from identified producer capacity declarations.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeling spanning organic versus conventional certification grades, beverage versus infant food versus bakery application channels, and aseptic pouch versus Tetra Pak versus glass jar packaging formats. CAGRs were derived from fitted growth curves applied to verified baseline consumption data, incorporating industry-specific inputs including EFSA maximum residue limit enforcement trajectories and California extended producer responsibility implementation schedules.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity price indices, container freight rates, or euro-dollar exchange volatility would shift the trajectory of import-dependent tropical puree procurement economics. Forecasts reflect documented assumptions regarding regulatory enforcement timing and technology adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Japan Frozen Fruit Puree Market
Fruits and Vegetables
United Kingdom Berries Market
Fruits and Vegetables
Farro Market
Fruits and Vegetables
Starchy Roots Market
Fruits and Vegetables
Celery Juice Market
Fruits and Vegetables
Aegle Marmelos Market
Fruits and Vegetables
Dragon Fruit Market
Fruits and Vegetables
Yellow Oyster Mushroom Market
Fruits and Vegetables
North America Organic Fruits Market
Fruits and Vegetables
Turkish Figs Market
Fruits and Vegetables
Frozen Vegetables Market
Fruits and Vegetables
Egypt Fruits and Vegetables Market
Fruits and Vegetables
South America Olive Market
Fruits and Vegetables
Mexico Lime Market
Fruits and Vegetables
Spain Table Grape Market
Fruits and Vegetables
Adzuki Beans Market