
 Frozen Baby Food Market | 2026-2036
Frozen Baby Food Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Baby Food Market Analysis
Working-parent households is pivoting toward frozen baby food as meal-preparation time compresses. Nestlé SA leverages its pediatric nutrition heritage to sustain brand trust across retail channels. General Mills Inc anchors its position through cold-chain distribution partnerships with mass-market grocers. HiPP GmbH & Co Vertrieb KG differentiates via organic ingredient sourcing and European formulation standards.
Frozen baby food comprises minimally processed, flash-frozen fruit, vegetable, meat, or mixed purees designed for infants transitioning to solids, typically manufactured through individual quick freezing to preserve micronutrient density and texture integrity. The product category serves commercial purposes by extending shelf life without chemical preservatives while meeting pediatric dietary guidelines for sodium, sugar, and allergen content. Vegetable purees command the largest volume share as parents prioritize savory first foods over fruit-forward alternatives. Online retailers represent the fastest-growing distribution channel, capturing margin pools through subscription models and direct-to-parent logistics. Reusable pouches dominate packaging innovation, though glass jars retain premium positioning in health food stores.
The FDA governs infant food labeling and contaminant thresholds in the United States, while the EFSA and EU Organic Regulation shape additive restrictions and certification requirements across European markets. China's NMPA and GB standards enforce formula-adjacent safety protocols that frozen purees increasingly must navigate for import clearance. Stakeholders should monitor evolving heavy-metal testing mandates and cold-chain energy regulations as sustainability criteria penetrate procurement decisions.
Market Dynamics
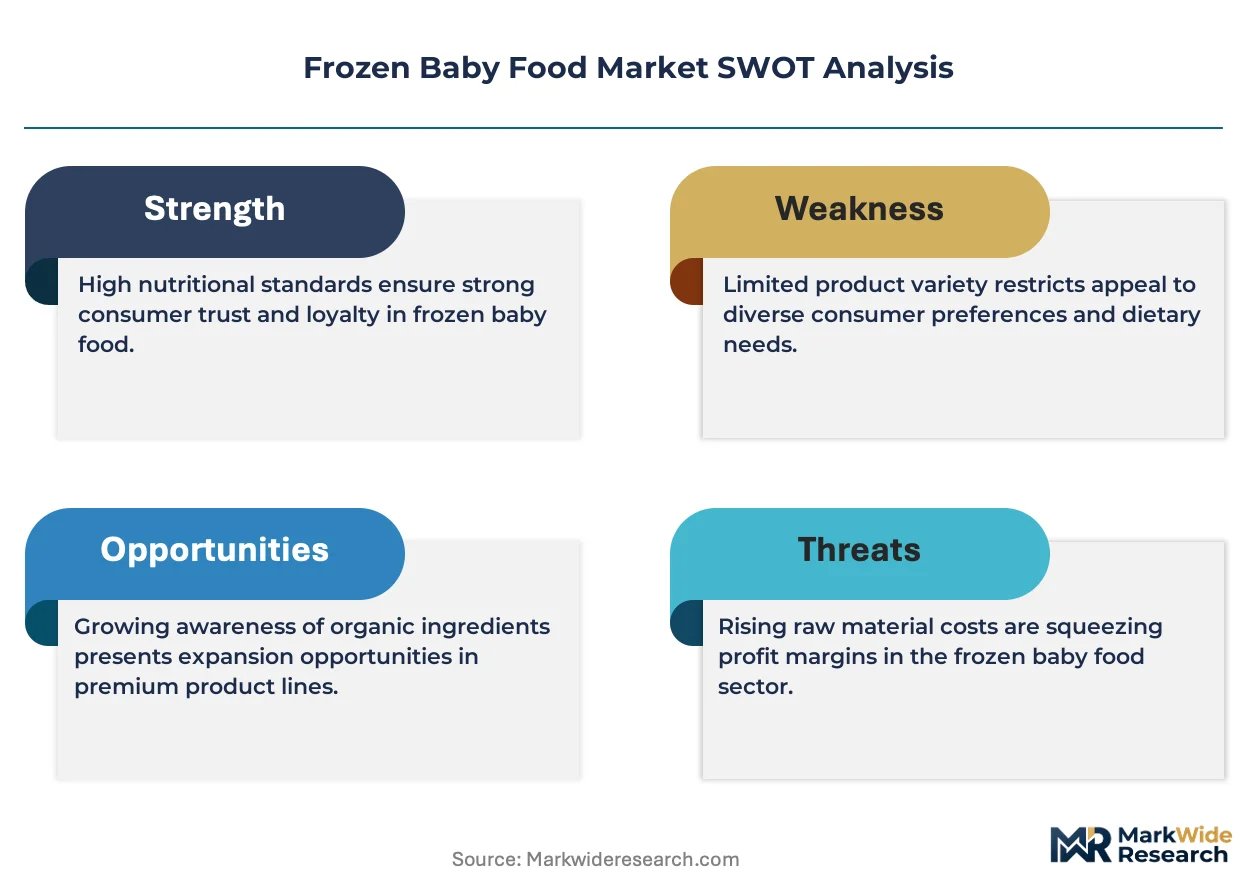
Flash-freezing technology advances are compressing production timelines while FDA heavy-metal testing mandates force reformulation investments across infant food portfolios. Cold-chain energy regulations now shape facility siting decisions.
Growth Catalysts
- Dual-income household density:Urban China and the United States register the highest concentration of working-parent households seeking time-compressed feeding solutions without nutritional compromise.
- EU Organic Regulation certification expansion:Cross-border recognition of organic standards reduces re-certification costs for frozen puree exporters targeting German and French retail channels.
- Individual quick freezing (IQF) process refinement:Cryogenic tunnel upgrades preserve micronutrient density in vegetable purees previously degraded by slower blast-freezing methods.
Market Restraints
- Specialized cold-chain infrastructure costs:Last-mile frozen delivery requires -18°C maintenance, elevating logistics spend versus ambient baby food alternatives.
- Input concentration in organic vegetable supply:Certified organic carrot and sweet potato sourcing clusters in specific California and Italian growing regions, creating weather-dependent availability risk.
- FDA contaminant threshold stringency:Updated guidance on arsenic, lead, cadmium, and mercury in infant foods forces ingredient testing protocols that extend batch release timelines.
Strategic Opportunities
- Subscription-based direct-to-parent distribution:Recurring delivery models bypass traditional grocery slotting fees while capturing lifetime value through pediatric nutrition continuity programs.
- Reusable pouch material innovation:Silicone and stainless-steel container formats address sustainability concerns that disposable plastic packaging faces in German and Nordic markets.
- China NMPA import pathway formalization:GB standard alignment for frozen purees opens cross-border e-commerce channels previously restricted to formula-focused approvals.
Industry Challenges
- Pediatric nutritionist talent scarcity:Formulation teams require dual expertise in food science and early childhood dietary guidelines, constraining R&D pipeline velocity.
- Cold storage facility permitting:Refrigeration energy intensity triggers environmental review delays in jurisdictions with aggressive carbon reduction mandates.
- Legacy ERP integration with traceability systems:Batch-level ingredient tracking for FDA compliance demands middleware investment that mid-tier processors struggle to resource.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Baby Food Market |
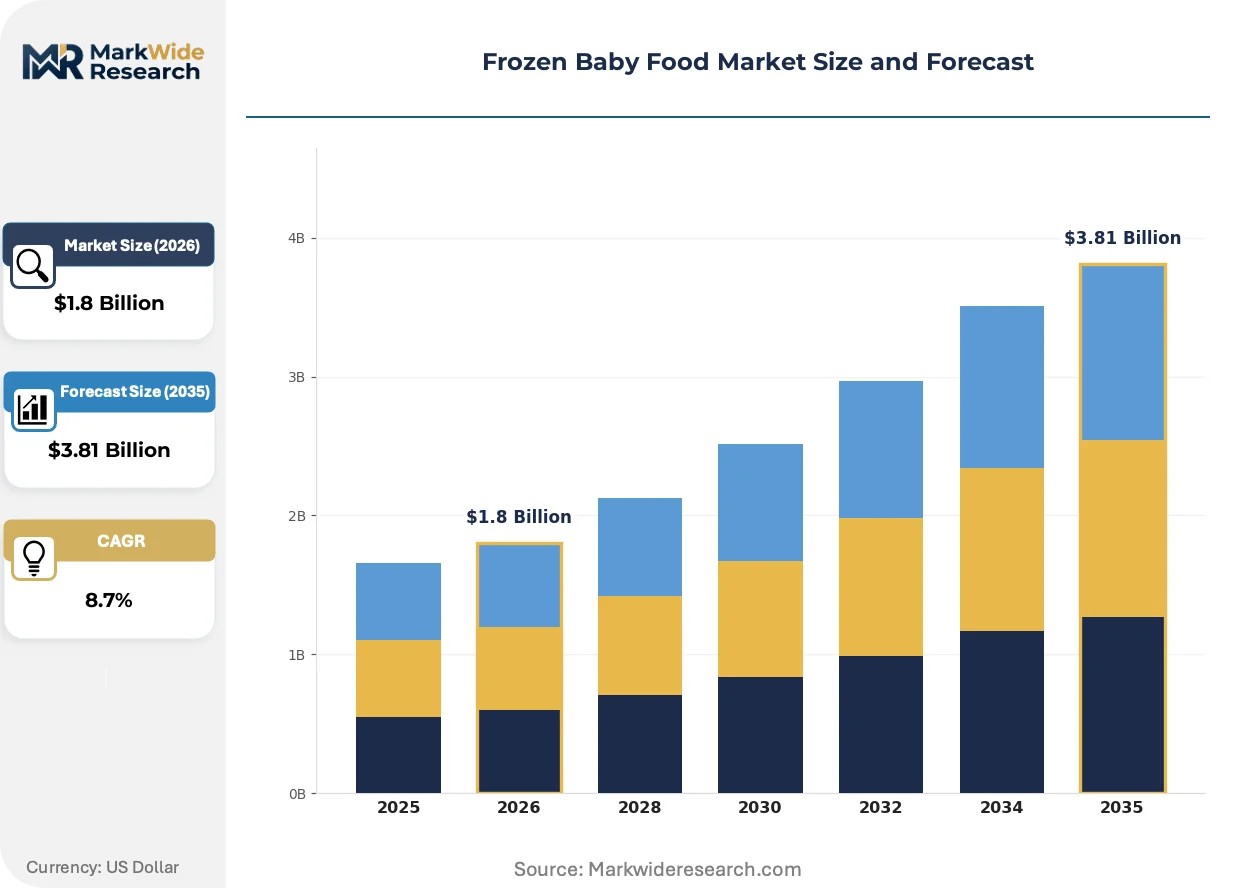
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Purees, Fruit Purees, Meat Purees, Mixed Purees Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Health Food Stores Packaging Type: Reusable Pouches, Glass Jars, Plastic Containers, Freeze-Dried Packs End User: Parents, Caregivers, Healthcare Providers, Nutritionists |
| Companies Covered | General Mills Inc, Conagra Brands Inc, Nestlé SA, HiPP GmbH & Co Vertrieb KG, Hero Group, Danone SA, The Kraft Heinz Company, Nomad Foods Ltd, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Baby Food Market Emerging Trajectories
Technology, regulatory, and behavioral vectors are simultaneously reshaping how frozen baby food reaches parent households. Each trend carries distinct implications for competitive positioning.
High-pressure processing (HPP) is consolidating as a pasteurization alternative that extends shelf life without thermal degradation of heat-sensitive vitamins. Premium-positioned brands in United States health food channels are adopting HPP to support clean-label claims. This technology is consolidating market share around processors capable of capital-intensive equipment deployment.
EFSA additive restriction updates are tightening permitted preservative categories across European frozen infant food formulations. Manufacturers reformulating for compliance report six-to-nine month validation cycles with notified bodies. Vegetable puree lines face the steepest adjustment burden given their reliance on ascorbic acid variants for color retention.
Parent purchasing through specialized infant nutrition platforms is displacing traditional supermarket aisle browsing. Chinese millennial parents demonstrate the highest platform-loyalty conversion rates, with subscription stickiness exceeding general e-commerce benchmarks. This behavioral shift concentrates marketing spend on influencer partnerships and pediatrician endorsement programs rather than trade promotion.
Frozen Baby Food Market Segmentation
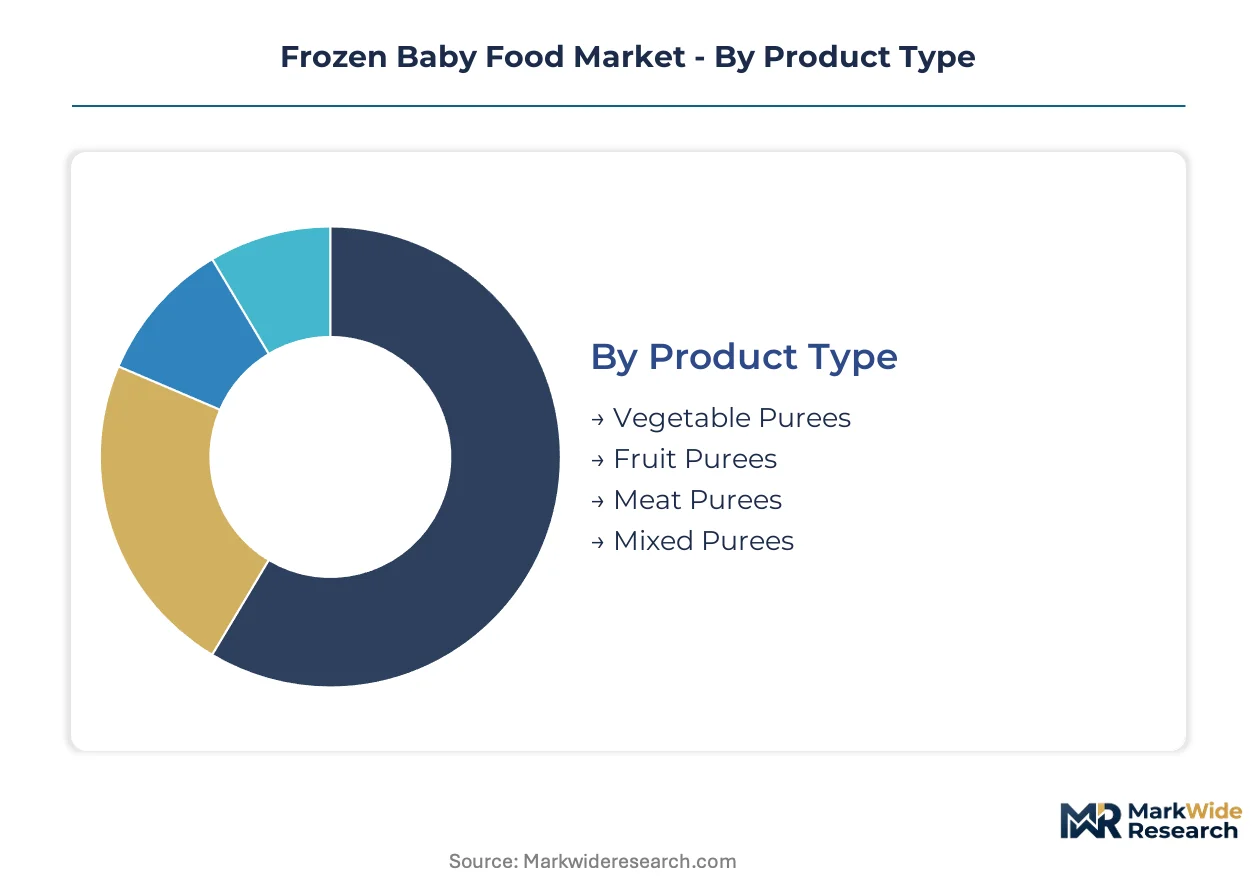
Frozen baby food segmentation reveals how regulatory requirements, logistics constraints, and purchasing behavior fragment commercial opportunity across distinct product and channel configurations. Each segment carries specific certification burdens and margin profiles that reshape competitive positioning.
Product Type:
Certification requirements vary sharply across product types, with vegetable purees facing the heaviest FDA heavy-metal testing protocols while meat purees trigger USDA dual-jurisdiction oversight.
- Vegetable Purees:Flash-frozen carrot, sweet potato, and pea formulations dominate volume through individual quick freezing that preserves beta-carotene and iron bioavailability. United States urban households drive demand as pediatricians recommend savory first foods to reduce sugar exposure.
- Fruit Purees:Apple and pear concentrates require ascorbic acid stabilization to prevent enzymatic browning, extending batch release timelines. German organic certification clusters concentrate demand among EFSA-compliant exporters.
- Meat Purees:Chicken and beef blends face USDA FSIS inspection alongside FDA infant food standards, elevating compliance costs.
- Mixed Purees:Multi-ingredient combinations complicate allergen labeling under EU Regulation 1169/2011.
Vegetable Purees sits at the top of the volume ranking, with Mixed Purees climbing the fastest.
Distribution Channel:
Cold-chain cost tiers stratify channel economics, with mass-market grocers absorbing logistics through scale while direct-to-parent models capture lifetime value through subscription mechanics.
- Supermarkets:Mass-market grocers leverage existing frozen aisle infrastructure to minimize slotting fees for established brands. Walmart and Kroger distribution partnerships anchor volume in the United States.
- Online Retailers:Subscription models bypass retail margin stacking while capturing pediatric nutrition continuity through recurring delivery. Chinese millennial parents show highest platform loyalty conversion.
- Convenience Stores:Limited frozen capacity restricts assortment to high-velocity SKUs in urban Japan.
- Health Food Stores:Premium positioning supports glass jar formats and HPP-processed lines in United States coastal cities.
Supermarkets retain volume leadership, though Online Retailers expand most quickly.
Packaging Type:
Material innovation cycles and sustainability mandates reshape procurement, with reusable formats gaining regulatory preference in Nordic jurisdictions.
- Reusable Pouches:Silicone and stainless-steel containers address German and Swedish plastic reduction targets while supporting premium pricing.
- Glass Jars:Inert material properties eliminate chemical migration concerns for acidic fruit purees, retaining health food channel preference.
- Plastic Containers:Polypropylene tubs dominate cost-sensitive mass-market distribution.
- Freeze-Dried Packs:Ambient-stable formats bypass cold-chain requirements for emergency stockpiling and travel use cases.
Plastic Containers hold the largest installed base, with Reusable Pouches gaining share fastest.
End User:
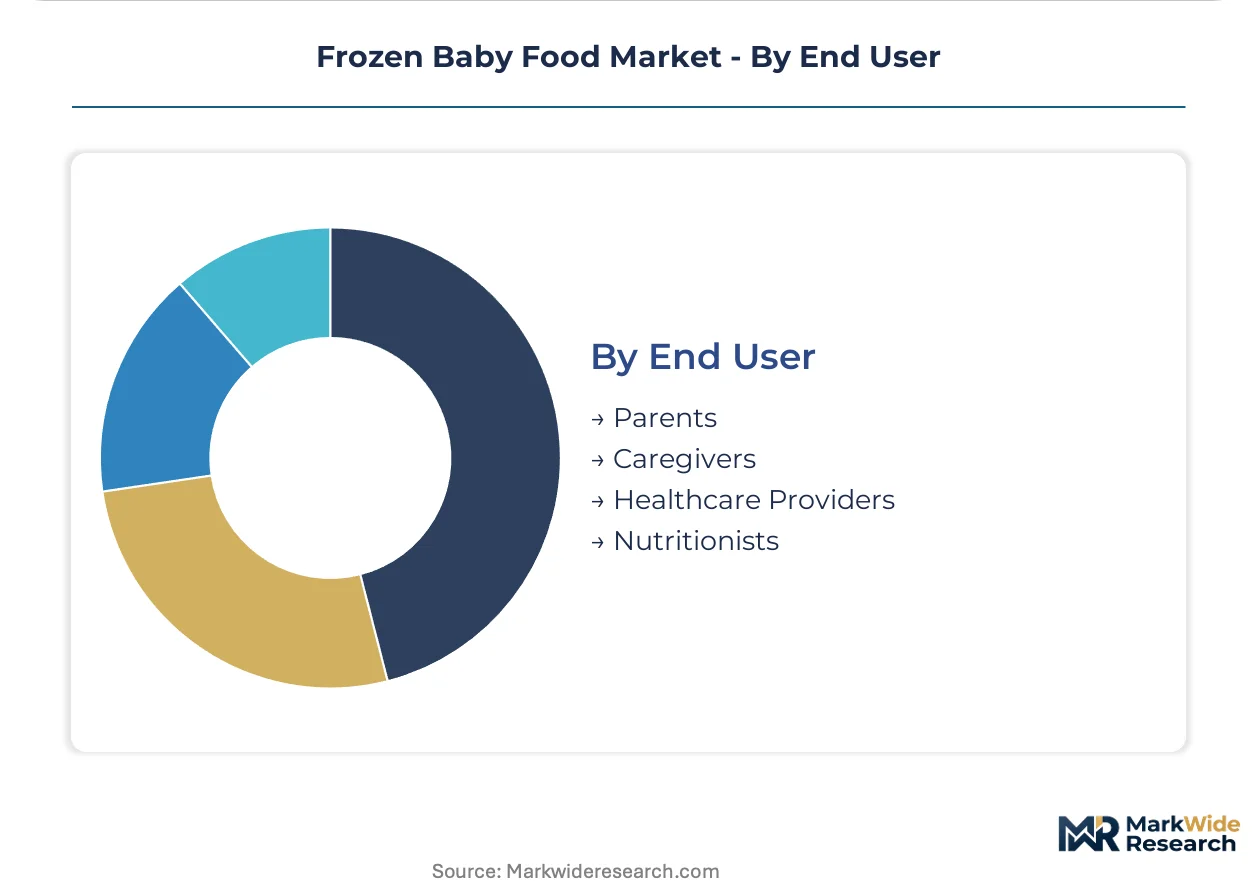
Purchasing authority and nutritional expertise levels create distinct service requirements, from convenience-seeking parents to protocol-driven healthcare institutions.
- Parents:Dual-income households prioritize time-compressed feeding solutions without nutritional compromise, driving subscription adoption.
- Nutritionists:Professional guidance shapes ingredient selection and allergen introduction sequencing for high-income segments.
- Caregivers:Daycare facilities require bulk formats with extended thawing windows.
- Healthcare Providers:Hospitals and clinics demand batch-level traceability for immunocompromised infant patients.
Parents account for the dominant purchase volume, with Healthcare Providers showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley organic vegetable belt anchors production capacity for flash-frozen infant purees destined for domestic and export markets. Dual-income household density in San Francisco, Los Angeles, and San Diego metro areas concentrates demand for time-compressed feeding solutions. FDA heavy-metal testing mandates implemented in 2024 have forced reformulation investments across processing facilities in Fresno and Sacramento counties.
United States
Urban households in New York, Chicago, and Seattle drive subscription adoption for direct-to-parent delivery models. The FDA's updated infant food safety guidance on arsenic and lead thresholds extends batch release timelines by 15-20 days. Flash-freezing technology clusters in Wisconsin and Minnesota leverage dairy-industry cold-chain infrastructure for vegetable puree processing.
Germany
EFSA-compliant organic certification commands premium positioning in Berlin, Munich, and Hamburg retail channels. The EU Organic Regulation reduces re-certification costs for exporters targeting French and Dutch markets. HiPP GmbH anchors production in Pfaffenhofen, with cold-storage facilities expanding in Bavaria to serve Nordic export demand.
China
Millennial parents in Shanghai, Beijing, and Shenzhen show highest platform-loyalty conversion for specialized infant nutrition platforms. NMPA GB standard alignment for frozen purees opens cross-border e-commerce channels previously restricted to formula approvals. Yangtze River Delta cold-chain infrastructure supports last-mile frozen delivery to tier-one urban households.
United Kingdom
London and Southeast England concentrate demand for premium glass-jar formats in health food retail. EFSA additive restrictions tighten permitted preservative categories, forcing six-to-nine month validation cycles with notified bodies. Midlands distribution hubs leverage existing frozen-food logistics networks for national supermarket penetration.
Frozen Baby Food Market Vendor Landscape
Portfolio diversification dominates the current landscape as legacy food conglomerates and specialized pediatric nutrition firms reposition around flash-freezing capabilities and organic certification tiers. The vendor base separates into three strategic archetypes: multinational packaged-food conglomerates with pediatric nutrition heritage, European organic specialists with vertically controlled supply chains, and regional private-label processors serving mass-market grocers. M&A activity concentrates on cold-chain logistics capabilities and organic ingredient sourcing networks. Technology licensing partnerships for high-pressure processing equipment represent a secondary competitive vector.
Within the multinational conglomerate tier, Nestlé SA and General Mills Inc exemplify scale-driven positioning anchored by retail distribution depth and pediatric nutrition continuity programs. HiPP GmbH & Co Vertrieb KG occupies a specialist position representing European organic formulation standards and controlled agricultural sourcing. These three entities illustrate the competitive tension between mass-market penetration and premium certification differentiation that defines current strategic positioning.
| Leading Market Players |
|---|
| General Mills Inc |
| Conagra Brands Inc |
| Nestlé SA |
| HiPP GmbH & Co Vertrieb KG |
| Hero Group |
| Danone SA |
| The Kraft Heinz Company |
| Nomad Foods Ltd |
| Abbott Laboratories |
| Others |
Supply Flow & Price Mechanics
Pediatric nutritionist talent concentration in California's Central Valley compresses R&D labor costs for organic formulation teams, widening spreads between premium certified-organic tiers and mass-market private-label positioning. Cold-chain energy intensity in last-mile delivery feeds directly into subscription pricing premiums versus supermarket aisle alternatives.
Pricing Analysis
Input-cost pass-through from certified organic vegetable sourcing dominates pricing dynamics, with California and Italian growing region premiums flowing directly to shelf price. Three-tier pricing structure across premium, standard, and economy levels separates EU Organic Regulation-certified lines from conventional flash-frozen and private-label economy tiers. Pricing pressure stems from FDA heavy-metal testing protocol extensions that inflate batch release overhead. Mass-market private-label buyers exhibit highest price sensitivity, while subscription-direct parents accept recurring premiums for pediatric nutrition continuity.
Supply Chain Analysis
Logistics and freight costs for -18°C cold-chain maintenance elevate landed costs 40-60% above ambient baby food alternatives, compressing margins on cross-border shipments. Supply concentrates in the United States, Germany, and China as production hubs, with California's Central Valley organic belt, Bavaria's HiPP Pfaffenhofen facility, and Yangtze River Delta cold-chain infrastructure anchoring regional capacity. Raw material dependencies center on certified organic carrot, sweet potato, and pea concentrates, plus cryogenic freezing equipment. Single-source vulnerability in California organic vegetable supply creates weather-dependent availability risk. Distribution runs through mass-market grocer frozen aisles, direct-to-parent subscription platforms, and health food specialty channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Frozen baby food functions as a stable compounder, with dual-income household density in urban centers providing durable demand irrespective of economic cyclicality.
For Market Incumbents: To counter subscription-based direct-to-parent entrants poaching pediatric nutrition continuity relationships, Nestlé SA and General Mills Inc should deepen backward integration into California Central Valley organic vegetable sourcing to secure input cost stability. Cold-chain logistics partnerships with mass-market grocers require reinforcement to defend retail slotting positions against private-label encroachment. For New Entrants and Emerging Players: Begin with China's cross-border e-commerce channels where NMPA GB standard alignment for frozen purees has opened previously restricted formula-focused pathways. German and Nordic reusable pouch segments present white-space opportunity given plastic reduction regulatory momentum. Influencer partnerships with pediatrician endorsement programs offer lower customer acquisition cost than trade promotion in supermarket environments. For Investors and Strategic Acquirers: Packaged food conglomerates with pediatric nutrition heritage represent the most active acquirer category in this space, seeking flash-freezing capabilities and organic certification tiers. Long-term viability rests on subscription model lifetime value capture and regulatory compliance infrastructure. Watch for FDA heavy-metal testing mandate enforcement intensity as inflection indicator for reformulation cost burdens across portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Vegetable Sourcing | Captive supply from California Central Valley reduces weather-dependent availability risk and input cost volatility. |
| Direct-to-Consumer Subscription Launch | Recurring delivery models bypass Kroger and Walmart slotting fees while capturing pediatric nutrition continuity value. |
| EU Organic Certification Investment | EFSA-compliant tiers command 30-50% shelf price premiums in Berlin and Munich retail channels. |
| Cold-Chain Logistics Partnership Expansion | Yangtze River Delta infrastructure access enables last-mile frozen delivery to Shanghai and Shenzhen households. |
| Reusable Pouch Material Innovation | Silicone and stainless-steel formats address German and Swedish plastic reduction targets with premium positioning. |
Methodological Framework
Bottom-up dual-income household demand modeling reconciled against top-down flash-freezing production capacity tracking forms the analytical core of this study. Primary interviews with pediatric nutrition formulation directors, cold-chain logistics operators, supermarket category buyers, and subscription platform executives combined with secondary validation against FDA enforcement discretion documents, EFSA additive restriction updates, NMPA GB standard filings, and Nielsen retail audit data. Triangulation across these sources ensures segmentation integrity.
Historical trendline analysis of frozen baby food volume and value trajectories informed projection mechanics across the analysis window. Segmentation dimensions modeled include product type, distribution channel, packaging format, and end user, with regulatory compliance tier as an additional industry-specific dimension. CAGRs were derived from fitted growth curves applied to demographic and technology adoption drivers, incorporating IQF process refinement timelines and cold-chain infrastructure buildout rates as forecast inputs.
Several conditions sit outside the modeled scope, including abrupt shifts in FDA heavy-metal testing enforcement, trade restriction impacts on California-Italy organic vegetable flows, and cryogenic equipment supply disruptions. Forecasts reflect documented assumptions regarding dual-income household formation rates and flash-freezing technology adoption curves. A model refresh is warranted upon material change in NMPA cross-border e-commerce pathway regulations for frozen purees.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
North America Freeze Dried Products Market
Processed and Frozen Foods
Frozen Meat and Fish Market
Processed and Frozen Foods
Asia-Pacific Frozen Pizza Market
Processed and Frozen Foods
South America Freeze Dried Products Market
Processed and Frozen Foods
Dehydrated Potato Market
Processed and Frozen Foods
Kimchi Market
Processed and Frozen Foods
Freeze Dried Fruits Market
Processed and Frozen Foods
Europe Frozen Food Market
Processed and Frozen Foods
GCC Frozen Finger Chips Market
Processed and Frozen Foods
Frozen Chicken Market
Processed and Frozen Foods
Cambodia Frozen Food Market
Processed and Frozen Foods
North America French Fries Market
Processed and Frozen Foods
Frozen Food Market
Processed and Frozen Foods
Global Frozen Breakfast Entrees/Sandwiches Market
Processed and Frozen Foods
Vegan Frozen Food Market
Processed and Frozen Foods
Frozen Fruit Bars Market