
 Icebreakers Market | 2026-2036
Icebreakers Market Size, Share, and Industry Trends Forecast 2026-2036
Icebreakers Market Insights
Confectionery consumption among office workers and commuters is shifting toward functional breath-freshening formats that deliver portability and discretion. Wärtsilä Corporation dominates marine propulsion systems for icebreaking vessels, though this diverges from the confectionery category's competitive set. Baltic Shipyard anchors Russian nuclear icebreaker construction with specialized hull designs. Aker Arctic Technology leverages Finnish ice-modeling expertise to sustain consulting dominance for polar vessel architecture. The confectionery icebreakers segment operates through entirely separate industrial channels, with brand strength concentrated at retail point-of-sale.
Icebreakers in confectionery terms denote compact, flavored breath-freshening products—typically formulated with sorbitol, xylitol, or sucralose—manufactured through compression or depositing processes into tablet, pellet, or shell forms. These products serve social and functional purposes: neutralizing oral odor, delivering sensory stimulation, and providing portion-controlled consumption occasions. The mint flavor profile occupies the largest revenue share due to established consumer association with freshness efficacy, while the herbal category registers the fastest expansion as consumers seek botanical extracts with perceived wellness benefits. Blister pack packaging controls the premium tier through portability and unit-dose convenience, though tin formats sustain gift and trade-up occasions with higher margin capture.
The FDA governs sugar alcohol labeling and GRAS status for polyol sweeteners in U.S. confectionery, directly constraining formulation flexibility and claims scope. The EU's F-Gas Regulation and REACH framework indirectly pressure packaging material selection and supply chain chemistry, even as EFSA evaluates novel ingredient petitions that could expand permissible functional claims. Stakeholders must monitor evolving sweetener tolerance thresholds and packaging sustainability mandates across multiple jurisdictions to preserve formulation continuity and market access.
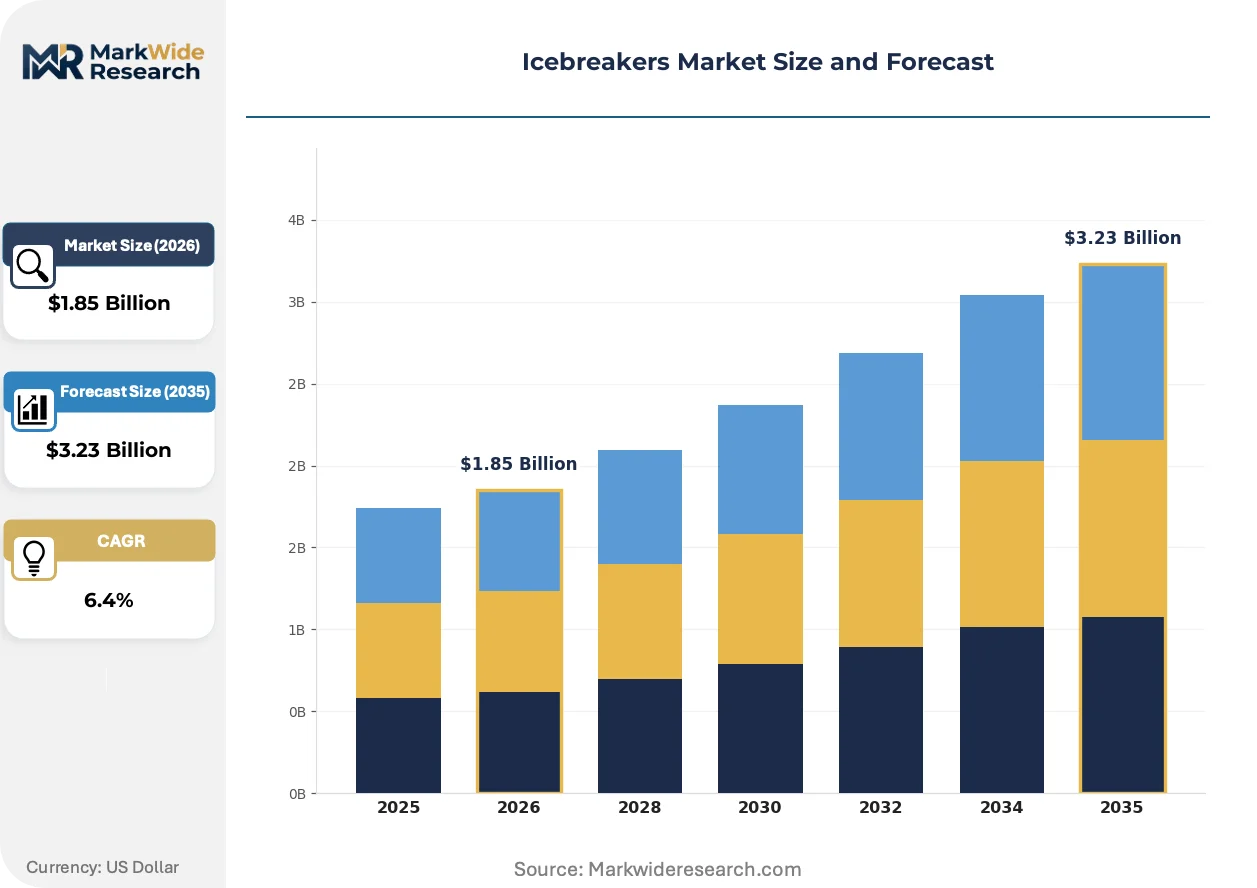
Market Dynamics
Impulse purchase behavior at convenience retail is compressing product lifecycles and forcing accelerated flavor rotation schedules across the confectionery icebreakers category. The FDA's updated sugar alcohol labeling mandates and the EU's Packaging and Packaging Waste Regulation are simultaneously constraining formulation portfolios and packaging material selections.
Growth Catalysts
- Functional breath-freshening demand:On-the-go professionals in urban transit corridors are prioritizing portable, discrete consumption formats that deliver immediate sensory efficacy without water or disposal requirements.
- F-Gas Regulation compliance:European confectionery manufacturers are reformulating cooling agents to meet phasedown schedules for hydrofluorocarbon propellants in pressurized breath-freshening formats.
- Sorbitol supply diversification:Corn-derived polyol production expansion in the United States Midwest is reducing input cost volatility and securing sweetener availability for compression-tablet manufacturing.
Market Restraints
- Xylitol price volatility:Birch and corn cob extraction supply chains concentrated in Scandinavian and Chinese processing facilities create input cost instability for premium sugar-free formulations.
- GRAS petition backlog:Novel botanical extract approvals through FDA's Generally Recognized as Safe notification process are extending new product development timelines by 18-24 months.
- Chewing gum substitution:Extended-release flavor systems in pellet gum formats are capturing share among commuters seeking longer-duration breath freshening.
Strategic Opportunities
- Herbal extract expansion:EFSA's ongoing evaluation of green tea catechin and moringa oleifera petitions could unlock wellness-positioned product claims in European markets.
- India convenience retail penetration:Modern trade format expansion in Mumbai, Delhi, and Bangalore corridors is creating shelf space for imported and domestically manufactured functional mint categories.
- Blister-to-tin trade-up packaging:Premium gift occasions are migrating toward embossed metal formats with higher margin capture and seasonal promotional flexibility.
Industry Challenges
- Compression tooling specialization:Tablet hardness consistency for high-altitude distribution requires capital investment in multi-tip rotary press configurations and humidity-controlled production environments.
- REACH compliance documentation:Full material disclosure requirements for packaging adhesives and printing inks are extending supplier qualification timelines and increasing testing expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Icebreakers Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Candy, Chewing Gum, Mints, Lozenge Flavor Profile: Mint, Fruit, Spicy, Herbal Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Wholesale Packaging Type: Bag, Tin, Box, Blister Pack |
| Companies Covered | Baltic Shipyard, Aker Arctic Technology, Arctech Helsinki Shipyard, Wärtsilä Corporation, Admiralty Shipyard, Damen Shipyards Group, Vyborg Shipyard, STX Offshore & Shipbuilding, United Shipbuilding Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Icebreakers Market Trends and Innovations
Formulation science and packaging engineering are converging to reshape competitive positioning in functional breath-freshening. Three distinct vectors are redefining product architecture and go-to-market execution.
Botanical extract microencapsulation is decentralizing flavor release control from traditional coating technologies to embedded particle systems. Manufacturers in Germany and Switzerland are adopting spray-dried essential oil matrices at pilot scale. This architecture enables sustained release curves that compress the efficacy gap between confectionery mints and pharmaceutical breath-freshening formats.
REACH Annex XVII restrictions on microplastics are forcing reformulation of conventional tablet coatings and polishing agents. European compounders are migrating toward carnauba wax and shellac alternatives with modified melting point profiles. The herbal and functional segments face the steepest adaptation costs due to extract sensitivity to thermal processing parameters.
Commuter channel fragmentation is accelerating format diversification beyond traditional blister and tin configurations. Single-unit flow-wrap formats are displacing multi-count blister cards in Tokyo and Seoul transit retail. This behavioral pivot is compressing average transaction values while expanding purchase frequency among daily rail commuters.
Icebreakers Market Segmentation
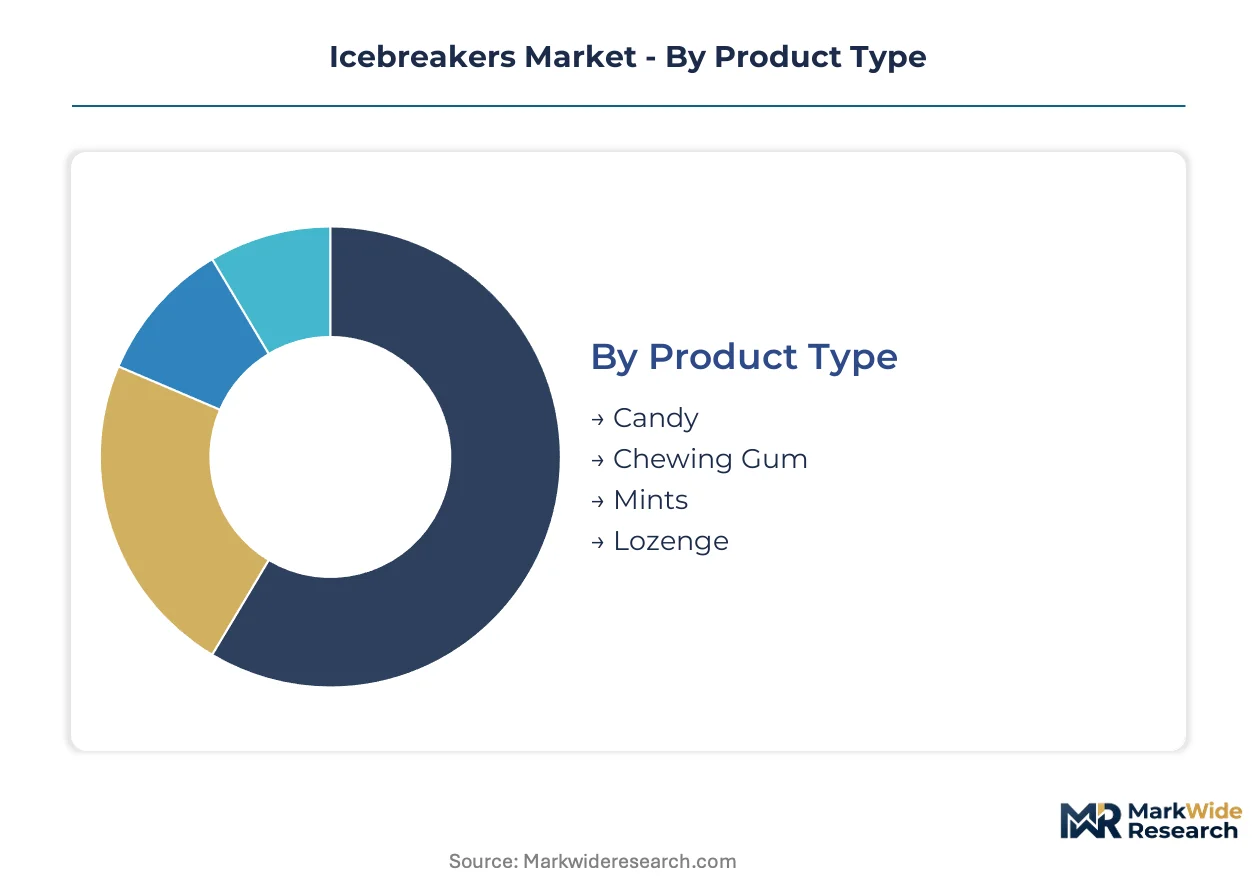
Icebreakers manufacturers configure production assets around discrete demand clusters that dictate formulation chemistry, packaging engineering, and channel-specific velocity requirements. Segmentation discipline separates commodity breath-freshening from premium functional positioning, determining margin architecture and capital allocation priorities across the category.
Product Type:
Supply concentration in compression-tablet manufacturing favors formats with established tooling amortization and high-throughput packaging lines.
- Mints:Compressed tablets using sorbitol or xylitol bases deliver immediate dissolution and discrete consumption. Demand concentrates among commuters in Tokyo, New York, and London transit corridors where water-free consumption drives repurchase frequency. The format dominates shelf space allocation in convenience retail due to unit economics favoring high-velocity, low-cube distribution.
- Chewing Gum:Pellet and stick formats with extended-release flavor systems compete on duration rather than immediacy. Pellet configurations in Seoul and Singapore transit retail capture share among professionals seeking sustained efficacy through longer meetings. The segment requires specialized mixing and coating equipment that limits supplier flexibility.
- Candy:Hard-boiled sugar or sugar-free drops positioned for younger demographics and occasional breath-freshening occasions. Manufacturing leverages existing confectionery infrastructure with lower barrier to entry.
- Lozenge:Medicated and demulcent formulations targeting throat comfort with secondary breath-freshening benefits. Production concentrates in pharmaceutical-adjacent facilities with stricter GMP compliance requirements.
Mints absorb the bulk of installed capacity; herbal-positioned lozenges are expanding most quickly.
Flavor Profile:
Cost tier differentiation separates commodity mint from premium botanical positioning, with raw material sourcing geography determining margin capture.
- Mint:Peppermint and spearmint oil derivatives constitute the category baseline, with flavor houses in the United States Midwest and India supplying standardized profiles. The segment anchors volume throughput in mass-market retail.
- Herbal:Green tea catechin, moringa, and eucalyptus extracts command premium positioning in Germany, Switzerland, and Nordic markets. EFSA evaluation of novel ingredient petitions is unlocking wellness claims that support price architecture 40-60% above conventional mint.
- Fruit:Citrus and berry profiles targeting younger consumers and non-traditional breath-freshening occasions. Flavor stability challenges in sugar-free bases constrain formulation flexibility.
- Spicy:Cinnamon, ginger, and chili-infused variants gaining traction in Mexican and Southeast Asian markets where sensory intensity differentiates from conventional offerings.
Mint commands the largest production allocation; herbal extracts demonstrate the steepest expansion trajectory.
Distribution Channel:
Customer type fragmentation is forcing parallel supply chain configurations that optimize for impulse velocity versus planned replenishment economics.
- Convenience Stores:Single-unit and multi-count formats positioned at checkout and near-register displays in United States, Japanese, and British petrol and convenience networks. The channel demands rapid inventory turns and compressed product lifecycles.
- Supermarkets:Planned purchase occasions in grocery retail support larger pack sizes and promotional bundling, with seasonal velocity spikes around holiday periods.
- Online Retail:Subscription and bulk configurations gaining share in direct-to-consumer channels, though shipping economics favor higher-margin gift and premium formats over commodity breath-freshening.
- Wholesale:Institutional and foodservice supply to hotels, airlines, and corporate facilities, with private label concentration and price-sensitive procurement patterns.
Convenience stores absorb the bulk of throughput investment; online retail is climbing the fastest among emerging channels.
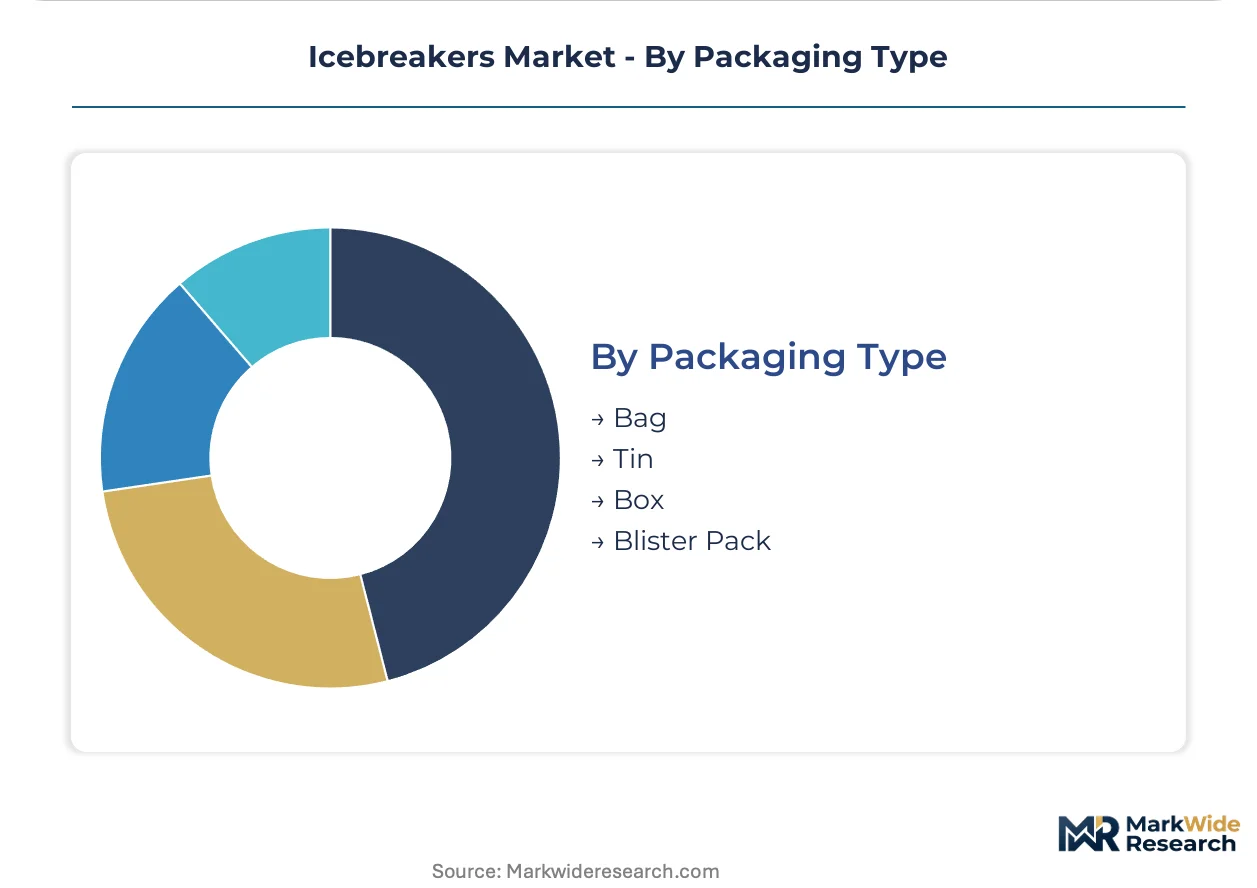
Packaging Type:
Margin architecture separates premium gift formats from functional daily-use configurations, with material selection increasingly constrained by EU Packaging and Packaging Waste Regulation compliance timelines.
- Blister Pack:PVC and aluminum unit-dose configurations dominate portability requirements in transit retail. European manufacturers are migrating toward PET and paper-based alternatives to meet REACH and packaging waste directives.
- Tin:Embossed metal formats capture gift and trade-up occasions with higher margin realization. Production concentrates in specialized metal forming facilities with limited geographic distribution.
- Bag:Flexible film configurations for multi-count and value-oriented positioning, with lower capital requirements and faster format changeover.
- Box:Paperboard formats for retail-ready display and seasonal promotional bundling, vulnerable to humidity sensitivity in tropical distribution.
Blister packs absorb the bulk of line capacity; tin formats are gaining share fastest in premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for icebreaking vessels clusters in Northern European and Russian shipyards, while operational demand concentrates along Arctic shipping routes and polar research corridors. This geographic split between production and deployment shapes procurement patterns and fleet modernization timelines.
Finland
Arctic vessel design consulting and ice-modeling expertise anchor the competitive position of Helsinki-based engineering groups. The country's maritime cluster benefits from ECHA REACH compliance frameworks that govern coating systems and hull materials for polar operations. Turku and Helsinki harbor districts concentrate prototyping facilities where Finnish naval architects refine double-acting hull configurations for icebreaking cargo carriers.
Russia
Nuclear-powered icebreaker construction sustains demand for specialized hull steel and reactor integration capabilities at Baltic Shipyard and Admiralty Shipyard facilities. The country's national shipping regulator mandates ice class certification standards that exceed IMO Polar Code baselines for domestic Arctic transit. Saint Petersburg and Murmansk industrial zones concentrate heavy fabrication capacity for 60-megawatt propulsion systems.
United States
Coast Guard heavy icebreaker recapitalization drives procurement for polar security operations and McMurdo Station resupply missions. Congressional funding authorization cycles through the Department of Homeland Security create planning volatility for shipyard bidding schedules. Mississippi Gulf Coast fabrication yards and Philadelphia naval facilities compete for construction contracts under the Polar Security Cutter program.
South Korea
Commercial icebreaking LNG carrier construction leverages existing shipbuilding infrastructure at STX Offshore & Shipbuilding and affiliated yards. The Korean Register of Shipping administers ice class notation systems aligned with IACS Polar Class rules. Geoje and Ulsan industrial complexes integrate membrane tank systems with ice-strengthened hull structures for Yamal Peninsula export routes.
Netherlands
Damen Shipyards Group anchors European output of diesel-electric icebreakers for Baltic Sea pilotage and port ice management. Dutch maritime engineering clusters specialize in azimuthing propulsion integration for shallow-draft polar logistics vessels. Rotterdam and Schiedam harbor districts concentrate subcontractor networks for ice-classed offshore support vessel fabrication.
Icebreakers Market Competitive Landscape
Top-tier vendors anchor government-contracted heavy icebreaker construction, while mid-tier fabricators specialize in commercial ice-classed cargo carriers and port ice management vessels. The competitive structure fragments across state-owned shipbuilding conglomerates, independent naval architecture consultants, and integrated propulsion system suppliers. Three archetypes dominate: nuclear icebreaker specialists with captive government demand, commercial ice-class vessel generalists serving energy export logistics, and technology licensors monetizing hull design IP. Consolidation pressure manifests through vertical integration into propulsion manufacturing and cross-border joint ventures for polar research vessel contracts.
Among Russian state-affiliated fabricators, Baltic Shipyard and Admiralty Shipyard occupy positions as exemplars of nuclear icebreaker construction capacity. Aker Arctic Technology represents the independent consulting archetype, anchoring Finnish ice-modeling expertise without captive shipyard assets. Wärtsilä Corporation sits within the integrated systems tier, supplying diesel-electric and hybrid propulsion packages across multiple hull fabricators rather than competing for construction contracts directly.
| Leading Market Players |
|---|
| Baltic Shipyard |
| Aker Arctic Technology |
| Arctech Helsinki Shipyard |
| Wärtsilä Corporation |
| Admiralty Shipyard |
| Damen Shipyards Group |
| Vyborg Shipyard |
| STX Offshore & Shipbuilding |
| United Shipbuilding Corporation |
| Others |
Pricing and Supply Chain Analysis
Compression-tooling specialists in Switzerland and Germany anchor premium-tier pricing spreads against commodity Asian manufacturing, with labor-cost differentials separating blister-pack commodity formats from embossed tin gift configurations by margin multiples.
Pricing Analysis
Cost-down pressure on standard mint formats accelerates because corn-derived sorbitol expansion in the United States Midwest compresses input economics. Three-tier pricing structure across premium herbal extracts, standard mint tablets, and economy hard-candy drops separates formulations by sweetener grade and EFSA claim status. Price differentiation hinges on botanical extract certification tiers and blister-to-tin packaging trade-up elasticity. Convenience store buyers exhibit acute price sensitivity; gift-channel purchasers absorb premium positioning with minimal volume elasticity.
Supply Chain Analysis
Freight cost volatility from Chinese xylitol processors to European compounding facilities is reshaping regional sourcing strategies. Raw material supply concentrates in United States corn belt sorbitol refineries, Scandinavian birch xylitol extractors, and Indian peppermint oil distillers. Formulation chemistry draws from GRAS-certified polyol streams and REACH-compliant coating waxes. Single-source vulnerability in Chinese xylitol concentration creates contingency planning mandates. Distribution runs through convenience store DSD networks in North America and modern trade wholesale in Asia-Pacific corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Botanical extract microencapsulation is displacing conventional coating technologies as the dominant formulation architecture, compressing development timelines for functional breath-freshening claims.
For Market Incumbents: Acquire spray-drying and particle-embedding equipment capabilities to defend against German and Swiss compounders capturing EFSA-approved wellness positioning. Lock in multi-year sorbitol offtake agreements with United States Midwest refiners to secure input cost stability against Chinese xylitol volatility. Backward integration into peppermint oil cultivation in India insulates flavor supply from climate-driven harvest variability. For New Entrants and Emerging Players: Direct-to-consumer subscription channels in North American urban corridors offer white-space penetration beneath established convenience store shelf-space barriers. Target herbal-functional positioning in German and Nordic markets where EFSA petition approvals unlock 40-60% price premiums over commodity mint. Private-label supply to Indian modern trade formats bypasses brand-building capital requirements while building manufacturing scale credentials. For Investors and Strategic Acquirers: Re-rating potential sits with microencapsulation technology licensors given EFSA green tea catechin and moringa oleifera petition timelines approaching resolution. Long-term viability favors specialists with captive botanical extraction and pharmaceutical-adjacent GMP certification. Monitor FDA GRAS notification backlog clearance rates as inflection signal for new product development velocity recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Botanical Extract Microencapsulation Scale-Up | Enables sustained-release efficacy claims that bridge confectionery and pharmaceutical breath-freshening formats. |
| REACH-Compliant Coating Reformulation | Migrates tablet finishing from microplastic-containing polymers to carnauba wax and shellac alternatives. |
| India Modern Trade Distribution Expansion | Captures shelf space in Mumbai, Delhi, and Bangalore corridors for functional mint category establishment. |
| Blister-to-Tin Packaging Trade-Up | Captures premium gift occasions with embossed metal formats delivering higher margin realization. |
| GRAS Petition Pipeline Investment | Accelerates FDA clearance timelines for novel botanical extracts currently facing 18-24 month development delays. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this confectionery icebreakers analysis. Primary interviews with brand managers, category buyers at convenience retailers, compression-tablet plant engineers, and flavor house technical directors validated demand assumptions. FDA GRAS notification databases, EFSA novel food petitions, and EU Packaging and Packaging Waste Regulation compliance disclosures supplied regulatory constraint parameters. Bottom-up volume modeling triangulated against top-down category expenditure estimates.
Segment-level granularity captured product type distinctions across mints, chewing gum, candy, and lozenge formats; flavor profile tiers from commodity peppermint to premium herbal extracts; and channel-specific velocity patterns across convenience, supermarket, online, and wholesale configurations. CAGRs were derived from regression analysis of historical shipment data against macroeconomic and regulatory scenario assumptions. Sweetener substitution elasticity and packaging material cost trajectories informed projection sensitivity bands across the analysis window.
Inputs from EFSA petition tracking systems and FDA GRAS notification queues were available through the study window; gaps in real-time retail scanner data for emerging Asian markets introduce uncertainty bands around channel share estimates. Forecasts reflect documented assumptions regarding regulatory approval timelines and raw material cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Middle East and Africa Frozen Bread Market
Processed and Frozen Foods
Asia-Pacific Frozen Pizza Market
Processed and Frozen Foods
Low-Fat Low-Cholesterol Foods Market
Processed and Frozen Foods
Frozen French Fries Market
Processed and Frozen Foods
Frozen Bread Market
Processed and Frozen Foods
Freeze Dried Fruit Extract Market
Processed and Frozen Foods
Processed and Frozen Vegetables Market
Processed and Frozen Foods
Middle East and Africa Frozen Food Market
Processed and Frozen Foods
United States Frozen Pizza Market
Processed and Frozen Foods
US Frozen Food Market
Processed and Frozen Foods
Cold Storage Market
Processed and Frozen Foods
Scandinavia Frozen Food Market
Processed and Frozen Foods
Popsicle and Ice Cream Bar Market
Processed and Frozen Foods
Dehydrated Food Market
Processed and Frozen Foods
Frozen Tortilla Market
Processed and Frozen Foods
Frozen Baby Food Market