
 Freeze Dried Fruit Extract Market | 2026-2036
Freeze Dried Fruit Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Freeze Dried Fruit Extract Market Analytics
Multi-source procurement is restructuring supply security for freeze dried fruit extract buyers. Olam Food Ingredients leverages its integrated sourcing networks across tropical growing regions to secure year-round raw material flows. European Freeze Dry anchors its position through captive freeze-drying capacity in northern Europe, while Kanegrade Limited specializes in tailored extract blends for beverage and confectionery clients.
Freeze dried fruit extract denotes concentrated fruit solids produced by sublimation dehydration, typically retaining 97-99% of original polyphenol content while reducing moisture to below 5%. The process preserves volatile aromatic compounds that spray-drying degrades, making these extracts indispensable for premium flavor systems in functional beverages and clean-label snacks. Powdered extracts command the widest formulation flexibility among product types, though whole fruit pieces sustain higher per-kilogram pricing in specialty retail channels. Beverage applications lead volume uptake as brands reformulate with recognizable fruit declarations rather than synthetic flavorants.
FDA GRAS self-determination governs U.S. market entry for conventional fruit extracts, while the EU's Novel Food Catalogue and EFSA health claim requirements constrain positioning around specific bioactive benefits. Food Manufacturers in the end-user tier face escalating documentation demands from both regulators and downstream retail partners. Stakeholders must weigh accelerated investment in organic-certified freeze-drying lines against the contracting timeline for conventional capacity payback.
Market Dynamics
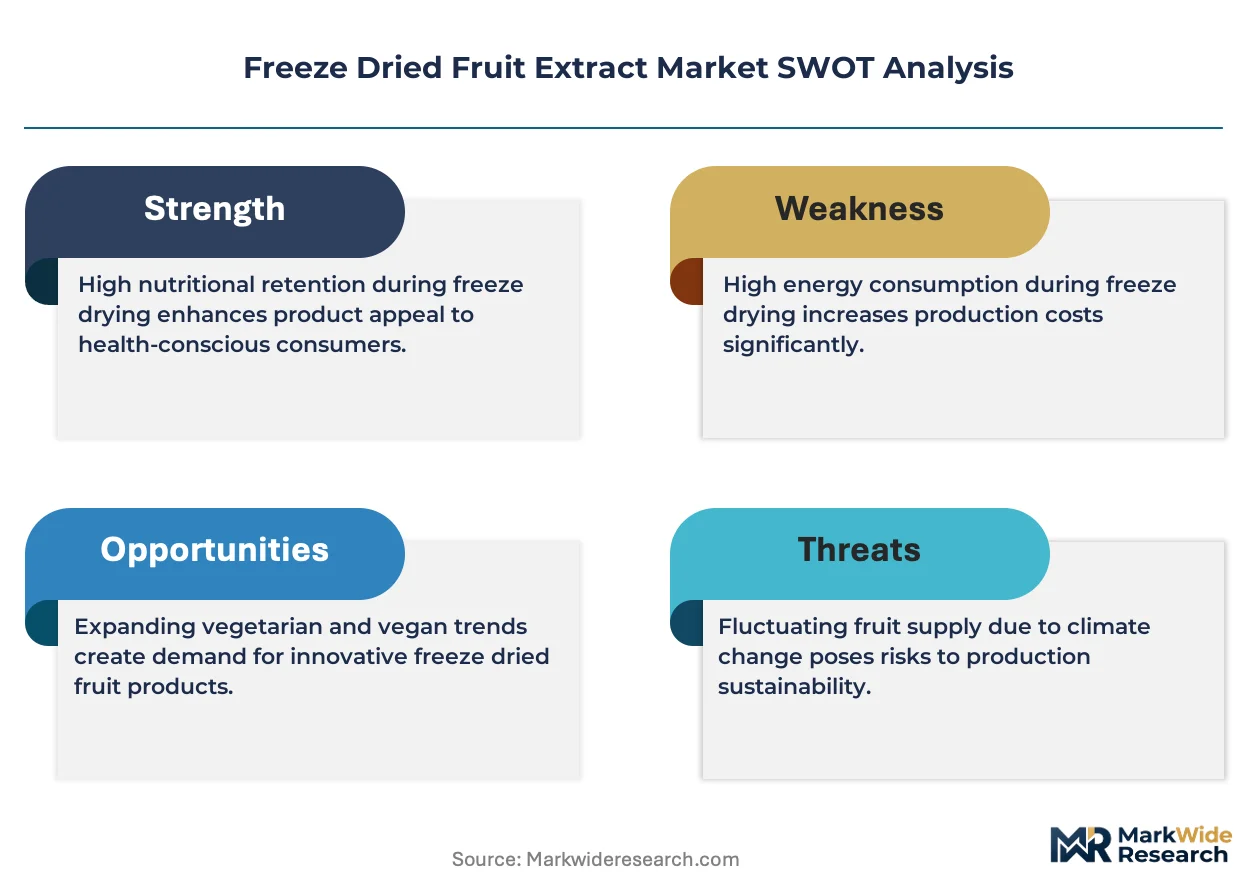
Clean-label formulation mandates from retail chains are compressing synthetic flavor replacement timelines, forcing beverage manufacturers to validate freeze-dried extract supply chains before reformulation deadlines. This pressure is restructuring procurement relationships around certified organic capacity and documented polyphenol retention rates.
Growth Catalysts
- EU Novel Food Catalogue alignment:Harmonized safety documentation requirements for fruit-derived ingredients are standardizing entry protocols, reducing regulatory friction for qualified suppliers.
- Functional beverage clean-label reformulation:Brands are replacing artificial flavorants with recognizable fruit declarations to meet retailer ingredient transparency mandates.
- German ingredient house clustering:Central European processing concentration enables just-in-time customized extract specifications for regional food manufacturers.
Market Restraints
- Freeze-drying energy intensity:Sublimation dehydration requires sustained vacuum and refrigeration loads, tying operating costs to volatile electricity pricing in European manufacturing zones.
- Tropical raw material concentration:Year-round fruit supply depends on sourcing networks across equatorial growing regions, exposing processors to climate-driven harvest variability.
- Spray-drying cost advantage:Conventional thermal dehydration retains sufficient flavor compounds for mid-tier applications at substantially lower capital and operating expenditure.
Strategic Opportunities
- Organic-certified freeze-drying line investment:Contract manufacturers with certified capacity command premium positioning as conventional capacity payback timelines contract.
- Powdered extract format expansion:Beverage formulation flexibility drives preference for concentrated fruit solids over whole pieces in industrial ingredient procurement.
- EFSA health claim pathway development:Documented polyphenol retention creates positioning potential for specific bioactive benefit claims in functional food applications.
Industry Challenges
- Organic certification timeline compression:Three-year conversion periods for freeze-drying facilities lag behind customer demand for certified supply.
- Polyphenol retention validation:Analytical capability gaps at mid-tier processors delay documentation packages required by EU Novel Food submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freeze Dried Fruit Extract Market |
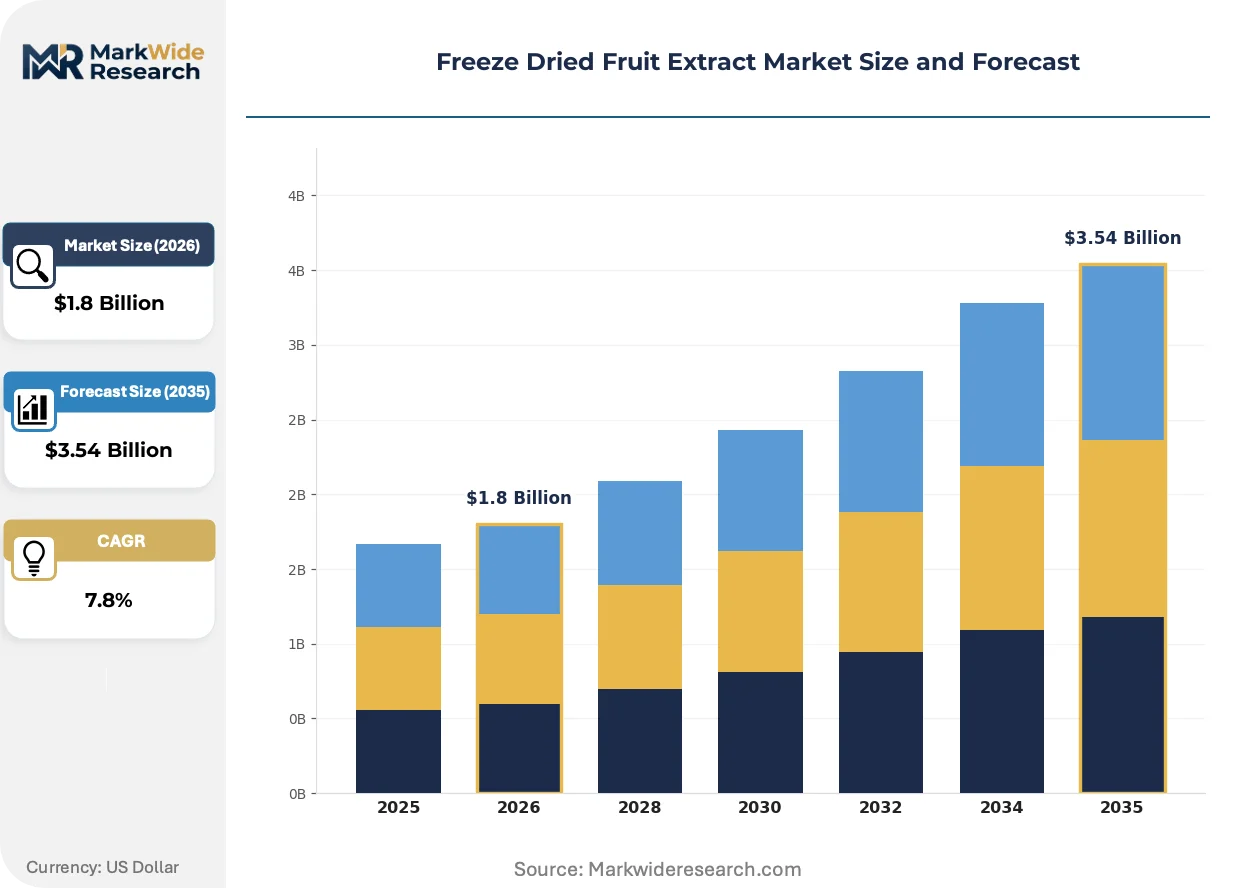
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.54 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Fruits, Powdered Extracts, Chips, Granules Application: Beverages, Snacks, Baking, Confectionery End User: Food Manufacturers, Retailers, Restaurants, Health Stores Distribution Channel: Online, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | Olam Food Ingredients, Dole Food Company, Döhler Group, Van Drunen Farms, Paradise Fruits Solutions GmbH & Co.KG, Nestlé, European Freeze Dry, Kanegrade Limited, Chaucer Foods Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freeze Dried Fruit Extract Market Evolving Landscape
Technology convergence between precision drying control systems and real-time moisture analytics is reshaping quality assurance protocols. Regulatory documentation automation and supply chain traceability platforms are compressing compliance timelines simultaneously.
Advanced lyophilization control systems with integrated sublimation endpoint detection are consolidating quality variance in premium extract production. Functional beverage manufacturers with reformulation deadlines are adopting these systems fastest. The technology is consolidating supplier tiers by disqualifying processors without validated moisture and polyphenol documentation.
REACH registration requirements for processing aids used in fruit extract manufacturing are tightening chemical disclosure obligations for European operators. Ingredient houses serving Central European food processors face expanded safety data sheet obligations. German contract manufacturers are responding by auditing tropical supplier processing chemical inventories.
Direct procurement relationships between beverage brands and freeze-drying operators are displacing traditional ingredient distributor intermediation. Large-volume functional drink manufacturers are negotiating multi-year supply agreements with certified processors. This pattern is most visible in Germany, where centralized European demand concentrates purchasing leverage.
Freeze Dried Fruit Extract Market Segmentation
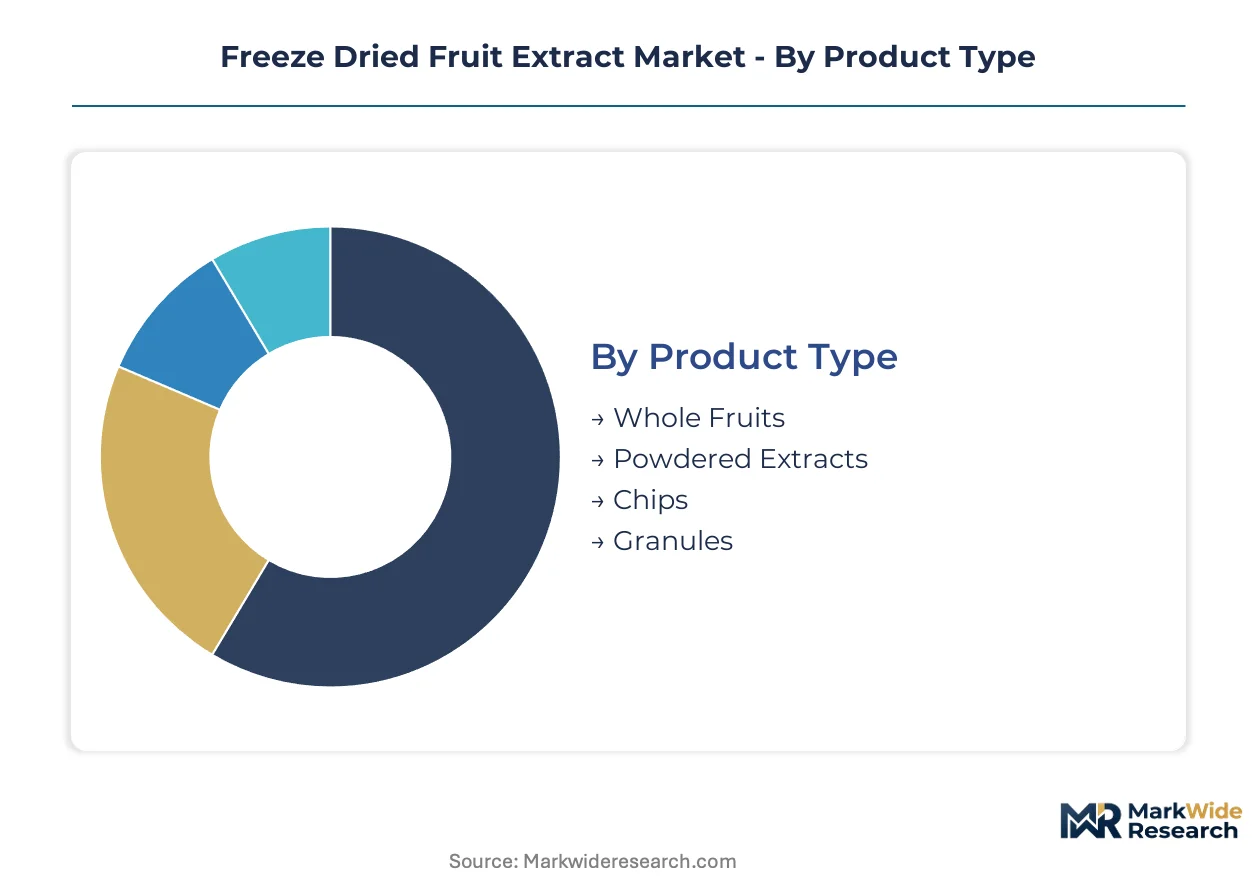
Freeze dried fruit extract procurement decisions pivot on formulation flexibility, regulatory documentation burden, and polyphenol retention validation. Understanding how buyers segment across product formats and channel structures clarifies where supplier investments yield defensible positioning.
Product Type:
Formulation requirements and per-kilogram value capture drive product type selection among beverage and confectionery buyers.
- Powdered Extracts:Concentrated fruit solids with sub-5% moisture content deliver maximum dissolution control for functional beverage matrices. German ingredient houses specify customized particle size distributions for clean-label reformulation timelines.
- Whole Fruits:Intact cellular structure preserves volatile aromatic compounds that premium snack brands leverage for sensory differentiation. Specialty retail channels sustain higher per-kilogram pricing despite lower volume throughput.
- Chips:Intermediate moisture formats suit bakery inclusions where structural integrity matters more than complete rehydration.
- Granules:Coarse particulate specifications serve confectionery applications requiring controlled release of fruit acidity and color.
Volume sits with powdered extracts; growth tilts toward whole fruits.
Application:
Clean-label mandates from retail chains are compressing synthetic replacement timelines across formulation categories.
- Beverages:Functional drink manufacturers prioritize documented polyphenol retention rates for EFSA-aligned health claim pathways. Powdered extract procurement concentrates among Central European processors with certified organic capacity.
- Snacks:Clean-label positioning demands recognizable fruit declarations replacing artificial flavorants in premium positioning tiers.
- Baking:Moisture reactivation properties determine extract selection for dough and batter systems where structural integrity competes with flavor delivery.
- Confectionery:Acid stability and color retention specifications govern fruit extract procurement for gummy and hard candy matrices.
Beverage procurement dominates current volume; confectionery applications are climbing the fastest as brands target permissible indulgence positioning.
End User:
Documentation requirements and supply security priorities diverge sharply across buyer sophistication tiers.
- Food Manufacturers:Industrial-scale buyers negotiate multi-year supply agreements with certified freeze-drying operators, displacing traditional distributor intermediation. Direct procurement relationships demand validated moisture analytics and polyphenol retention documentation.
- Retailers:Private-label development teams specify organic-certified supply chains for clean-label store brand positioning.
- Restaurants:Premium foodservice channels source whole fruit pieces for plate presentation where visual fruit identity commands menu pricing.
- Health Stores:Supplement-adjacent positioning emphasizes polyphenol concentration claims requiring EFSA-aligned substantiation packages.
Food manufacturers absorb the heaviest volume; health stores are gaining share fastest on functional positioning premiums.
Distribution Channel:
Channel selection reflects order scale, documentation requirements, and speed-to-formulation priorities.
- Online:Digital procurement platforms serve mid-tier processors with standardized extract specifications and compressed lead times.
- Specialty Stores:Ingredient houses provide technical consultation for customized blend development.
- Supermarkets:Retail consolidation is concentrating procurement leverage among chains with private-label freeze-dried fruit programs.
- Wholesale:Traditional distributor networks retain relevance for smaller manufacturers lacking direct processor relationships.
Wholesale channels handle current volume; online platforms are expanding most quickly as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tropical growing regions in Southeast Asia and Latin America anchor raw material flows for freeze-dried fruit extract processors. Manufacturing concentration clusters in Germany and the United States where beverage brands command procurement leverage. Regulatory divergence between FDA self-determination and EU Novel Food Catalogue compliance shapes regional investment priorities.
Germany
Ingredient houses in Hamburg and Cologne serve Central European beverage manufacturers with customized extract specifications. EFSA health claim requirements constrain positioning around polyphenol benefits, forcing documentation investments. The Bavarian processing corridor hosts contract manufacturers expanding certified organic freeze-drying capacity for clean-label supply chains.
United States
Functional beverage brands in California and the Pacific Northwest drive powdered extract procurement for reformulation timelines. FDA GRAS self-determination governs market entry with lower documentation burdens than European counterparts. Chicago-area distributors maintain inventory positions for mid-tier manufacturers lacking direct processor relationships.
China
Domestic freeze-drying capacity expansion targets export markets as tropical fruit processing scales in Guangdong and Hainan. SAMR food safety regulations tighten traceability documentation for ingredients entering premium channels. Yangtze River Delta ingredient traders consolidate procurement relationships with Southeast Asian raw material suppliers.
Brazil
Açai and tropical fruit concentrate production in Pará and Bahia feeds international extract demand. ANVISA novel food pathways remain underdeveloped, pushing Brazilian processors toward U.S. and EU export certification. São Paulo-based trading houses intermediate between Amazonian cooperatives and European freeze-drying operators.
India
Mango and guava processing clusters in Maharashtra and Andhra Pradesh supply pulp for export-oriented freeze-drying. FSSAI safety documentation requirements lag EU standards, constraining direct European market access. Karnataka-based ingredient exporters pursue organic certification to bypass conventional capacity competition.
Freeze Dried Fruit Extract Market Competitive Landscape
Capacity expansion dominates the current landscape as processors race to secure certified organic lines before conventional payback timelines contract. The vendor base stratifies across integrated tropical sourcing networks, captive European freeze-drying facilities, and specialized extract blenders. Three archetypes occupy distinct positions: agribusiness conglomerates with backward integration into raw material supply, regional processors with certified manufacturing assets, and formulation specialists serving beverage and confectionery technical requirements. M&A activity concentrates on acquiring organic-certified facilities, while strategic partnerships between tropical processors and European ingredient houses accelerate compliance documentation.
Among integrated sourcing operators, Olam Food Ingredients represents the agribusiness archetype with tropical network control. European Freeze Dry exemplifies regional processing concentration through captive northern European capacity. Kanegrade Limited occupies the formulation specialist tier with tailored extract blend capabilities for beverage clients.
| Leading Market Players |
|---|
| Olam Food Ingredients |
| Dole Food Company |
| Döhler Group |
| Van Drunen Farms |
| Paradise Fruits Solutions GmbH & Co.KG |
| Nestlé |
| European Freeze Dry |
| Kanegrade Limited |
| Chaucer Foods Ltd |
| Others |
Value Network & Pricing Analysis
Functional beverage manufacturers with reformulation deadlines command procurement leverage through multi-year supply agreements, compressing pricing power toward certified organic processors with validated polyphenol documentation. This buyer concentration rewards freeze-drying operators that bundle analytical certification with volume commitments, while conventional capacity faces margin erosion.
Pricing Analysis
Service bundling separates premium-tier suppliers from commodity competitors, with EFSA-aligned documentation packages and organic certification commanding substantial premiums over basic moisture-validated extracts. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and analytical depth. Cost compression in conventional capacity is intensifying because spray-drying alternatives satisfy mid-tier beverage applications at lower capital burden. Food manufacturers with direct processor relationships exhibit lowest price sensitivity; wholesale-dependent mid-tier processors face acute margin pressure.
Supply Chain Analysis
Skilled lyophilization technicians remain scarce in Bavaria and northern Germany, constraining expansion timelines for certified organic lines despite capital availability. Raw material flows draw from Vietnam, Thailand, and Ecuador for tropical fruit supply, while processing concentrates in Germany and the United States. Single-source vulnerability in Southeast Asian pulp supply exposes European operators to climate-driven harvest variability. Distribution runs through direct procurement relationships displacing traditional ingredient distributors for large-volume beverage accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision drying control systems with real-time sublimation endpoint detection are displacing legacy batch-controlled freeze-drying infrastructure, rewarding early adopters with documented polyphenol retention rates.
For Market Incumbents: Deepen backward integration into tropical raw material networks to secure year-round supply continuity against climate volatility. Expand certified organic capacity in the Bavarian processing corridor before three-year conversion timelines lock out late entrants. Spray-drying cost advantages in mid-tier applications threaten conventional freeze-drying margins; defend positioning through analytical service bundling. For New Entrants and Emerging Players: EU Novel Food Catalogue alignment in Europe opens a window for contract manufacturers with pre-validated documentation packages to capture reformulation-driven demand from beverage brands. Target health store channels with EFSA-aligned polyphenol concentration claims, the most penetrable segment for substantiation-capable entrants. Lead with digital procurement platforms offering compressed lead times and standardized specifications to mid-tier processors lacking direct supplier relationships. For Investors and Strategic Acquirers: The window for entry favors regional processors with captive certified capacity in Germany or the United States. Acquisition focus should center on freeze-drying facilities with active organic certification and validated moisture analytics capability. Watch for inflection in EU enforcement patterns around Novel Food documentation rejections as signal for competitive consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Investment | Three-year conversion timelines lock in premium positioning ahead of conventional capacity obsolescence. |
| Backward Integration into Tropical Supply | Olam Food Ingredients demonstrates network control securing year-round raw material flows. |
| Precision Drying Control Deployment | Real-time sublimation endpoint detection consolidates supplier tiers by disqualifying undocumented processors. |
| EFSA Health Claim Pathway Development | Documented polyphenol retention enables functional positioning in beverage applications. |
| Direct Procurement Relationship Building | Large-volume German beverage manufacturers negotiate multi-year supply agreements bypassing distributors. |
Research Methodology
Independent corroboration across freeze-drying equipment manufacturers, tropical fruit pulp exporters, and functional beverage formulators underwrites the qualitative findings in this study. Primary interviews with plant managers at European contract manufacturers, procurement leads at Central European ingredient houses, regulatory affairs specialists navigating EU Novel Food submissions, and category buyers at German retail chains combined with secondary validation. Trade data from customs authorities, EFSA novel food application registers, and energy pricing disclosures for European manufacturing zones anchored quantitative inputs. Bottom-up capacity assessments and top-down demand projections triangulate market sizing.
Rate-of-change decomposition across product format adoption, certification tier penetration, and application segment expansion generated segment-specific growth patterns across the projection horizon. Modeling dimensions span powdered extract versus whole fruit formats, organic versus conventional certification tiers, beverage versus confectionery versus snack applications, and direct procurement versus distributor-mediated channel structures. CAGRs derive from fitted adoption curves applied to validated baseline volumes. Forecast inputs incorporate EU Novel Food approval timelines and freeze-drying energy cost trajectories.
The model assumes a particular technology adoption path; alternative pathways for precision lyophilization control systems would alter the outlook if deployment lags behind reformulation deadlines. Forecasts reflect documented assumptions around regulatory enforcement intensity and certification conversion rates. Material deviation in EU Novel Food rejection rates or Southeast Asian harvest volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
United Arab Emirates Frozen Food Market
Processed and Frozen Foods
Indonesia Frozen Food Market
Processed and Frozen Foods
North America Freeze Dried Products Market
Processed and Frozen Foods
South America Frozen Desserts Market
Processed and Frozen Foods
Processed and Frozen Fruits Market
Processed and Frozen Foods
Europe Frozen Pizza Market
Processed and Frozen Foods
Frozen Tortilla Market
Processed and Frozen Foods
Frozen Smoked Salmon Market
Processed and Frozen Foods
Ice Cream and Frozen Dessert Market
Processed and Frozen Foods
Dehydrated Potato Products Market
Processed and Frozen Foods
IQF Food Products Market
Processed and Frozen Foods
Asia Pacific Freeze Dried Product Market
Processed and Frozen Foods
Asia Pacific Frozen Desserts Market
Processed and Frozen Foods
Low-Fat Low-Cholesterol Foods Market
Processed and Frozen Foods
Europe Frozen Food Market
Processed and Frozen Foods
Frozen Dumplings Market