
 Global Cerebral Somatic Oximeters Market | 2026-2036
Global Cerebral Somatic Oximeters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cerebral Somatic Oximeters Market Foresight
Near-infrared spectroscopy miniaturization is reshaping how cerebral somatic oximeters integrate into operating room workflows and portable care settings. Medtronic leverages its cardiac surgery ecosystem to embed oximetry into broader hemodynamic monitoring suites. Masimo sustains technology leadership through advanced signal processing algorithms that reduce motion artifact in critical care environments. Nonin Medical specializes in compact, battery-powered designs that extend monitoring into ambulatory and transport applications.
Cerebral somatic oximeters are non-invasive medical devices that use near-infrared light wavelengths to measure regional oxygen saturation in brain tissue and other vital organs, typically operating at 650-1000 nanometers with real-time display capabilities for perfusion assessment during procedures where cerebral ischemia risk is elevated. Their primary commercial purpose centers on reducing postoperative neurological complications through early detection of oxygen desaturation events in surgical and intensive care contexts. Desktop oximeters dominate hospital operating rooms where multi-channel monitoring and EMR integration justify capital investment, while wireless sensors represent the fastest-expanding category as facilities prioritize patient mobility and reduced cable clutter in recovery environments. Near-Infrared Spectroscopy anchors the technology landscape due to its established clinical validation, though photoacoustic technology is gaining research traction for deeper tissue penetration and improved spatial resolution.
The FDA enforces Class II medical device controls through 510(k) premarket notification pathways that demand substantial equivalence demonstrations for new cerebral oximetry platforms entering the United States. Europe's MDR requires enhanced clinical evidence and notified body oversight for oximeter certifications under stricter biocompatibility and performance-testing protocols than predecessor directives. Japan's PMDA maintains distinct pharmaceutical and medical device agency review standards that shape product registration timelines for manufacturers targeting Asian surgical markets. Stakeholders must monitor evolving harmonization efforts between ISO 80601-2-56 physiological monitoring standards and national implementation variations that could accelerate or complicate multi-regional product rollouts.
Market Dynamics
Near-infrared spectroscopy miniaturization is compressing device footprints while expanding placement flexibility across operating theaters, emergency transport, and neonatal intensive care units.
Growth Catalysts
- FDA 510(k) pathway clarity:Streamlined premarket notification for cerebral oximetry devices accelerates commercialization timelines for manufacturers targeting United States surgical centers.
- Cardiac surgery volume concentration:Rising aortic and valve procedure counts in tertiary hospitals drive continuous brain oxygen monitoring adoption during cardiopulmonary bypass.
- Photoacoustic imaging advances:Deeper tissue penetration capabilities extend monitoring utility beyond superficial cortical regions into subcortical structures.
Market Restraints
- Indium gallium arsenide detector costs:Specialized photodetector materials constrain bill-of-materials flexibility and amplify price sensitivity in emerging markets.
- Europe MDR clinical evidence requirements:Enhanced post-market surveillance obligations extend certification timelines and inflate regulatory compliance expenditures.
- Pulse oximetry substitution pressure:Lower-cost peripheral oxygen saturation monitoring limits budget allocation for dedicated cerebral platforms in cost-constrained facilities.
Strategic Opportunities
- India surgical infrastructure expansion:Government hospital modernization programs create first-mover positioning for non-invasive neuromonitoring vendors in tier-two cities.
- Artificial intelligence-signal processing convergence:Machine learning artifact rejection algorithms enable reliable monitoring in ambulatory and motion-intensive transport settings.
- Japan PMDA priority review designation:Expedited pathways for breakthrough medical devices shorten market entry cycles for novel oximetry platforms.
Industry Challenges
- Biomedical optics engineering scarcity:Specialized expertise in near-infrared spectroscopy hardware design concentrates among limited academic and industry talent pools.
- ISO 80601-2-56 harmonization delays:Divergent national implementations of physiological monitoring standards complicate unified product architecture strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cerebral Somatic Oximeters Market |
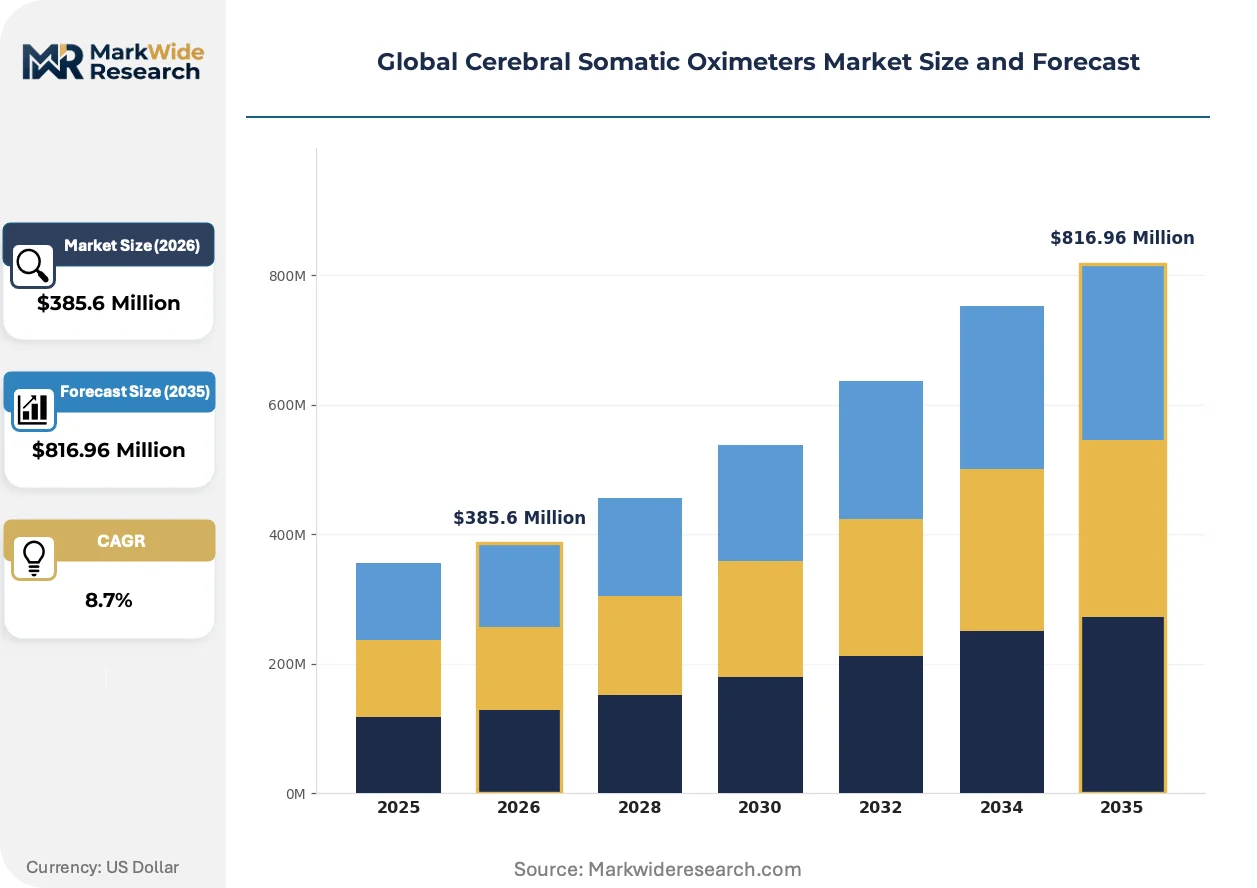
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $816.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Oximeters, Desktop Oximeters, Wearable Monitors, Wireless Sensors Technology: Near-Infrared Spectroscopy, Reflectance Pulse Oximetry, Transmission Pulse Oximetry, Photoacoustic Technology Application: Cardiac Surgery, Neonatal Care, Neurosurgery, Critical Care Monitoring End User: Hospitals, Ambulatory Surgery Centers, Specialty Clinics, Research Institutions |
| Companies Covered | Medtronic, Masimo, Edwards Lifesciences, Nonin Medical, ISS Inc., GE Healthcare, Hamamatsu Photonics, Terumo Corporation, Mespere LifeSciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cerebral Somatic Oximeters Market Shifts & Advancements
Digital integration and algorithmic enhancement are transforming cerebral oximetry from isolated monitoring tools into networked clinical decision support components.
Wireless sensor architectures are virtualizing traditional bedside console dependencies. Cardiac surgery departments at major United States academic medical centers deploy battery-powered patches eliminating tethered cables during patient positioning changes. This virtualization compresses equipment footprint requirements while enabling continuous monitoring through transport corridors and recovery bays.
Europe's MDR intensifies clinical performance documentation obligations for cerebral oximetry manufacturers. Notified bodies demand expanded biocompatibility testing and post-market clinical follow-up protocols. Pediatric and neonatal application segments face disproportionate evidence generation burdens due to vulnerable population safeguards.
Hospital value analysis committees now dominate cerebral oximetry procurement decisions. Materials management departments displace individual surgeon preference in capital equipment selection. Germany's university hospital networks exhibit this pattern most acutely, with standardized device contracts replacing specialty-specific purchasing autonomy.
Global Cerebral Somatic Oximeters Market Segmentation
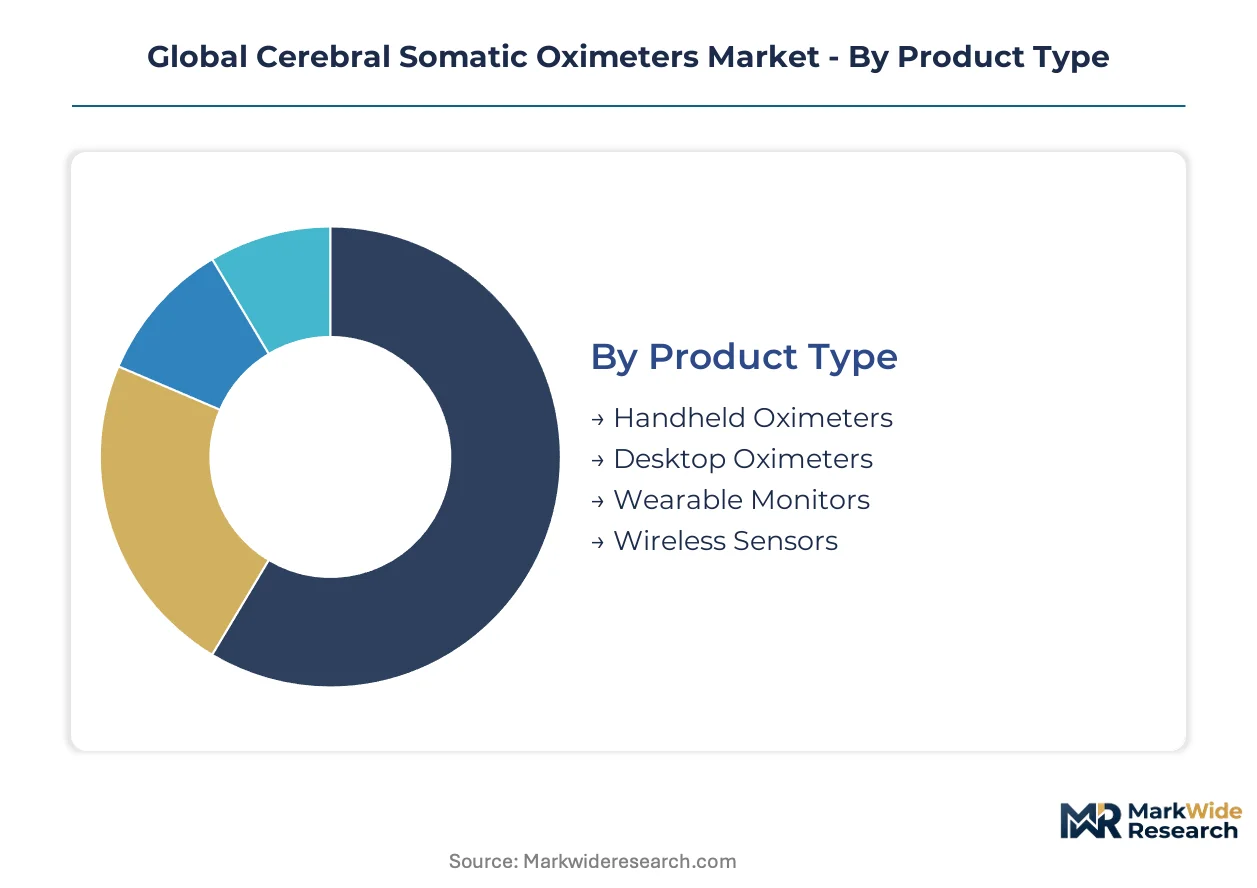
Cerebral somatic oximeters serve distinct clinical workflows spanning high-acuity operating theaters to mobile transport settings. Product architecture, sensing technology, and care environment each create divergent performance requirements and procurement patterns.
Product Type:
Use cases range from capital-intensive multi-channel installations to single-patient disposable patches.
- Desktop Oximeters:Multi-channel console systems integrate with hospital EMR infrastructure and anesthesia workstations. United States academic medical centers prioritize these platforms for cardiac surgery suites where simultaneous bilateral cerebral monitoring is standard of care.
- Wireless Sensors:Battery-powered adhesive patches eliminate cable tethering during patient transport and positioning changes. German university hospitals deploy these across recovery corridors to maintain continuous monitoring without console relocation.
- Handheld Oximeters:Portable units with integrated displays suit emergency departments and field transport where immediate readout is essential.
- Wearable Monitors:Extended-wear designs target ambulatory monitoring and step-down units requiring patient mobility.
The dominant share belongs to Desktop Oximeters, while Wireless Sensors is closing the gap fastest.
Technology:
Signal generation methods differentiate penetration depth, spatial resolution, and motion artifact susceptibility.
- Near-Infrared Spectroscopy:Established platforms emit 650-1000 nanometer wavelengths to measure regional oxygen saturation through scalp and skull. Japan's PMDA maintains extensive clinical validation databases for NIRS-based devices, accelerating regulatory clearance for manufacturers with proven algorithms.
- Photoacoustic Technology:Laser-induced ultrasound detection enables deeper tissue penetration beyond cortical surfaces into subcortical structures. Research institutions in the United States and Germany pilot these systems for enhanced spatial mapping during complex neurosurgical procedures.
- Reflectance Pulse Oximetry:Surface-reflected light measurement adapts forehead and somatic placement for pediatric applications.
- Transmission Pulse Oximetry:Transillumination architecture suits thin-tissue neonatal monitoring where emitter-detector opposition is anatomically feasible.
Near-Infrared Spectroscopy commands installed base leadership, though Photoacoustic Technology is gaining share fastest in research-forward institutions.
Application:
Procedure-specific risk profiles determine monitoring intensity and regulatory evidence requirements.
- Cardiac Surgery:Cardiopulmonary bypass and aortic arch procedures generate sustained demand for bilateral cerebral monitoring. United States tertiary centers mandate continuous oximetry during valve replacements and aortic repairs to detect embolic events and hypoperfusion.
- Neonatal Care:Premature infant cerebral oxygen monitoring requires specialized sensor sizes and population-specific algorithm validation. European MDR imposes enhanced clinical evidence burdens for neonatal indications due to vulnerable population safeguards.
- Neurosurgery:Craniotomy and aneurysm clipping procedures utilize regional saturation trending to identify ischemic territory.
- Critical Care Monitoring:Post-operative and traumatic brain injury surveillance extends monitoring into ICU environments.
Cardiac Surgery retains the largest procedure volume attachment, while Neonatal Care is expanding most quickly amid preterm birth intervention priorities.
End User:
Capital allocation authority and reimbursement frameworks shape purchasing behavior across facility types.
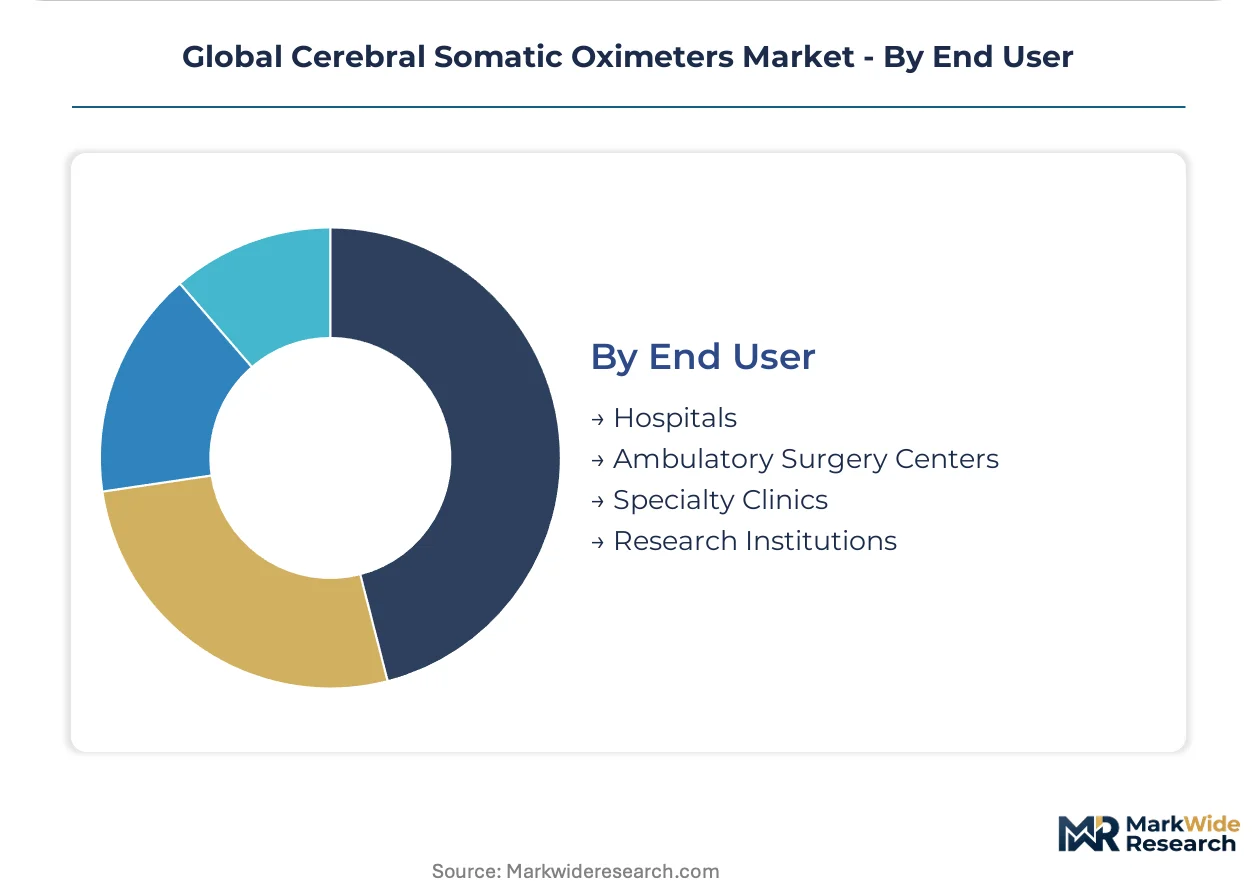
- Hospitals:Tertiary and community hospitals concentrate procurement volume through value analysis committees that standardize device contracts. Germany's university hospital networks exemplify centralized purchasing that displaces individual surgeon preference.
- Ambulatory Surgery Centers:Freestanding cardiac and orthopedic facilities prioritize compact, multi-parameter devices that justify capital expenditure through high case turnover.
- Specialty Clinics:Pediatric and neurological focused practices seek portable platforms for office-based monitoring.
- Research Institutions:Academic medical centers and contract research organizations drive adoption of novel sensing modalities for clinical trial endpoints.
Hospitals control the dominant procurement volume, while Ambulatory Surgery Centers are gaining share fastest as surgical migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of cerebral somatic oximeters concentrate from manufacturing centers in the United States, Germany, and Japan toward surgical markets in China, India, and Brazil. Import dependency in emerging economies creates pricing leverage for established device manufacturers. Regulatory divergence between FDA, MDR, and PMDA frameworks shapes regional commercialization timelines.
United States
Cardiac surgery volumes at Cleveland Clinic and Mayo Clinic drive bilateral cerebral monitoring adoption during cardiopulmonary bypass procedures. The FDA maintains Class II 510(k) premarket notification requirements that demand substantial equivalence demonstrations for new oximetry platforms. Boston's medical device corridor anchors domestic manufacturing and algorithm development for signal processing advances.
Germany
University hospital networks in Berlin and Munich standardize device contracts through centralized value analysis committees that displace individual surgeon preference. The MDR imposes enhanced clinical evidence and post-market surveillance obligations that extend certification timelines for manufacturers. Baden-Württemberg's precision optics cluster supplies photodetector components to regional device assemblers.
Japan
Preterm birth intervention priorities accelerate neonatal cerebral oxygen monitoring adoption in Tokyo and Osaka tertiary centers. The PMDA maintains extensive clinical validation databases for near-infrared spectroscopy devices that accelerate regulatory clearance for proven algorithms. Nagoya's medical electronics manufacturing base produces compact sensor assemblies for domestic and Asian export markets.
China
Hospital infrastructure modernization in Shanghai and Beijing expands operating room neuromonitoring capabilities for cardiac and neurosurgical procedures. The NMPA implements distinct review standards for Class II medical devices that shape product registration timelines for international manufacturers. Shenzhen's electronics manufacturing ecosystem drives cost compression in wireless sensor component supply.
India
Government hospital modernization programs in tier-two cities create first-mover positioning for non-invasive neuromonitoring vendors entering previously unserved surgical markets. The CDSCO regulates medical device imports and domestic manufacturing under evolving standards that increasingly align with ISO frameworks. Maharashtra's Mumbai-Pune pharmaceutical and medical device corridor concentrates distribution logistics for subcontinental market access.
Global Cerebral Somatic Oximeters Market Competitive Landscape
On the supply side, the industry is consolidating around diversified medical technology conglomerates with established cardiac surgery and critical care ecosystems. Tiered competitive positioning separates integrated platform vendors from specialized neuromonitoring boutiques. Two strategic archetypes dominate: diversified hemodynamic monitoring suites and focused cerebral oximetry specialists. Dominant competitive moves include portfolio diversification into adjacent perfusion monitoring segments and technology licensing partnerships for algorithm enhancement.
Among diversified medical technology conglomerates, Medtronic and GE Healthcare exemplify platform integration strategies that embed cerebral oximetry within broader hemodynamic monitoring architectures. Masimo occupies a position within the signal processing specialist tier, with algorithmic differentiation in motion artifact reduction. Nonin Medical represents the compact portable design archetype, with battery-powered configurations extending monitoring into transport and ambulatory settings. These three anchors illustrate how competitive positioning stratifies across integrated suite vendors, algorithm specialists, and portable device innovators.
| Leading Market Players |
|---|
| Medtronic |
| Masimo |
| Edwards Lifesciences |
| Nonin Medical |
| ISS Inc. |
| GE Healthcare |
| Hamamatsu Photonics |
| Terumo Corporation |
| Mespere LifeSciences |
| Others |
Supply & Pricing Matrix
Baden-Württemberg's precision optics cluster concentrates indium gallium arsenide photodetector production, anchoring margin pools with console manufacturers in the United States and Germany who command pricing power through FDA-cleared algorithm bundles.
Pricing Analysis
Hospital value analysis committees anchor pricing negotiations through centralized procurement contracts that displace individual surgeon preference. Three-tier pricing structure across premium, standard, and economy levels separates multi-channel desktop systems with EMR integration from wireless sensor patches and handheld emergency units. Cost compression in economy-tier portable devices is intensifying because Shenzhen-based electronics manufacturers drive component cost reductions. Ambulatory surgery centers exhibit highest price sensitivity due to capital constraint, while United States academic medical centers demonstrate lowest sensitivity given bundled reimbursement for cardiac surgery episodes.
Supply Chain Analysis
United States export controls on advanced photodetector technologies limit flows of indium gallium arsenide components to Chinese device assemblers, constraining supply flexibility. Manufacturing concentrates in Germany, Japan, and the United States for precision optical assemblies, while China and Malaysia handle final sensor packaging and wireless module integration. Supply chains draw from specialized indium gallium arsenide wafers, near-infrared laser diodes, and medical-grade adhesive substrates. Single-source vulnerability concentrates in Japanese photodetector foundries serving Tokyo and Osaka sensor manufacturers. Distribution runs through hospital GPO contracts, specialty medical device distributors, and direct sales to university hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from regulatory cycle compression as MDR transition delays and FDA 510(k) backlog clearance restore normalized commercialization timelines.
For Market Incumbents: Harden algorithm IP moats through expanded FDA 510(k) clearances for motion artifact reduction in transport settings, while securing exclusive supply agreements with Baden-Württemberg photodetector foundries to constrain competitor access to precision optical components. Build backward integration into NIRS sensor head manufacturing to capture margin pools currently held by Japanese contract manufacturers. For New Entrants and Emerging Players: Tier-two Indian cities with government hospital modernization programs represent the most penetrable entry point for wireless sensor platforms that bypass capital-intensive console competition. Photoacoustic technology research partnerships with United States academic medical centers offer differentiated positioning against established NIRS incumbents. Pursue CDSCO registration pathways ahead of multinational competitors to secure first-mover procurement relationships. For Investors and Strategic Acquirers: Capital is best deployed toward algorithm-specialist firms with FDA-cleared signal processing libraries and established hospital system validation data. Long-term viability hinges on reimbursement code capture for cerebral monitoring in cardiac surgery bundles. Watch for PMDA priority review designations as inflection signals for breakthrough device platform potential.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Expansion | Accelerated clearance timelines restore normalized commercialization cadence for algorithm-enhanced platforms. |
| CE Marking Pathway Investment | MDR clinical evidence generation builds defendable regulatory moats against lower-resourced competitors. |
| Hospital System Partnership | Value analysis committee relationships secure multi-year procurement contracts displacing surgeon preference. |
| Software Companion Development | AI-enabled artifact rejection extends monitoring utility into ambulatory and transport environments. |
| Reimbursement Strategy | CPT code capture for cerebral oximetry in cardiac surgery episodes anchors sustainable revenue streams. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with cardiac surgeons, biomedical engineers, hospital purchasing committee chairs, and GPO contracts managers; and secondary validation through FDA 510(k) filings, PMDA approval databases, hospital procurement records, and ISO 80601-2-56 implementation tracking. Bottom-up segmentation modeling triangulated against top-down macro sizing across product type, technology platform, application segment, and end-user facility tier.
Forecast inputs span surgical volume trajectories, regulatory pathway timelines, and reimbursement framework evolution across the analysis window. Segmentation dimensions modeled include product architecture, sensing technology, procedure type, and facility capital allocation authority. CAGRs derive from procedure volume elasticity, device replacement cycles, and pricing trajectory assumptions. Industry-specific inputs incorporate cardiopulmonary bypass case forecasts and neonatal intensive care admission patterns.
Macroeconomic conditions sit as an overlay; deviation in surgical reimbursement rates, medical device tariff schedules, or healthcare capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory harmonization progress and hospital infrastructure investment continuity. Material shifts in FDA 510(k) review timelines or MDR notified body capacity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Live Cell Encapsulation Market
Medical Devices
Lacrimal Devices Market
Medical Devices
Global Nasal Spray Market
Medical Devices
Medical Coatings for Implants Market
Medical Devices
Pulse Lavage Market
Medical Devices
Pectus Bar System Market
Medical Devices
Upper Limb Prosthetics Market
Medical Devices
Global Implantable Drug Delivery Market
Medical Devices
Wearable Breast Pumps Market
Medical Devices
Embolization Plugs Market
Medical Devices
Photomedicine Technology Market
Medical Devices
Global Auto-Injectors Market
Medical Devices
Craniomaxillofacial Plate and Installation Tools Market
Medical Devices
Global Advanced Bipolar Direct Energy Device Market
Medical Devices
EMEA Surgical Microscopes Market
Medical Devices
Implantable Collamer Lens Market