
 LED Flip Chip Market | 2026-2036
LED Flip Chip Market Size, Share, and Industry Trends Forecast 2026-2036
LED Flip Chip Market Foresight
EU RoHS and REACH compliance is rebalancing the cost-of-entry calculus for packaged LED imports into European consumer electronics channels. Samsung Electronics leverages captive semiconductor foundry capacity to internalize epitaxy and packaging steps for its display backlighting divisions. Epistar Corporation anchors Taiwan's compound semiconductor supply base with concentrated gallium nitride wafer production. Nichia Corporation differentiates through phosphor-conversion IP and vertical control over rare-earth material sourcing.
LED flip chip denotes a light-emitting diode architecture where electrodes and bonding pads reside on the same substrate face, enabling direct mounting without wire bonds and yielding thermal resistance below 2 K/W junction-to-board. This structure serves high-luminance applications where conventional wire-bonded configurations fail under thermal cycling or spatial density constraints. High-Power LEDs dominate current shipment volumes due to penetration in automotive forward lighting and stadium illumination. Micro LEDs represent the fastest-expanding product category as panel makers advance transfer yields for direct-view displays. Display Technology applications command premium pricing relative to General Illumination owing to tighter binning requirements and shorter product refresh cycles.
FCC emission standards in the United States, EU Ecodesign requirements under the EU Green Deal, and China's GB standards on solid-state lighting efficacy collectively shape product qualification timelines and regional market access conditions. Japan's METI maintains JIS standards that restrict mercury-containing legacy sources, indirectly accelerating LED flip chip substitution in industrial settings. Stakeholders must monitor foundry utilization rates for gallium nitride-on-silicon capacity and the trajectory of laser lift-off yield improvements as determinants of cost parity against conventional vertical chip architectures.
Market Dynamics
Automotive headlamp architectures are forcing a substrate-level transition as thermal cycling requirements exceed wire-bonded LED limits, compressing supplier qualification timelines and rewarding foundries with gallium nitride-on-silicon capacity.
Growth Catalysts
- GB Standards on Solid-State Lighting:China's efficacy mandates under the dual carbon goals disqualify conventional packaged LEDs from government procurement, redirecting volume toward flip chip suppliers with junction-to-board thermal resistance below 2 K/W.
- Automotive Forward Lighting:NHTSA beam-pattern regulations and EU ECE R48 compliance are accelerating OEM adoption of high-luminance arrays that wire-bonded architectures cannot thermally sustain.
- Laser Lift-Off Yield Improvements:Epitaxy houses in Taiwan and South Korea are achieving commercial viability for gallium nitride-on-sapphire transfer to silicon carriers, collapsing cost differentials against vertical chip formats.
Market Restraints
- Rare-Earth Phosphor Volatility:Cerium-doped yttrium aluminum garnet supply concentrates in Chinese separation facilities, exposing non-integrated packagers to spot-price spikes that flip chip architectures cannot absorb through phosphor-thickness reduction alone.
- Foundry Utilization Constraints:Gallium nitride-on-silicon capacity clusters in Hsinchu and Pyeongtaek corridors, creating allocation bottlenecks when display panel makers and automotive Tier 1s synchronize procurement cycles.
- Micro LED Transfer Yield Limits:Mass transfer equipment for direct-view displays remains below commercial thresholds for sub-50-micron chips, deferring revenue recognition for epitaxy investments predicated on consumer television volumes.
Strategic Opportunities
- Stadium and Horticultural Illumination:Spectral-tunable flip chip arrays command premium positioning in controlled-environment agriculture where photosynthetic photon flux density requirements exceed conventional LED output ceilings.
- EU Ecodesign Requirements:The EU Green Deal's phased mercury lamp bans under RoHS Annex III are compressing replacement cycles in industrial settings, creating retrofit demand for junction-mounted architectures compatible with existing heat-sink footprints.
- Silicon Photonics Convergence:Hybrid integration of flip chip emitters with CMOS driver circuits is emerging in LiDAR modules for advanced driver-assistance systems, opening adjacent revenue streams beyond general illumination.
Industry Challenges
- Compound Semiconductor Process Engineering Talent:Gallium nitride metal-organic chemical vapor deposition reactor operation and defect-density characterization require specialized expertise concentrated in Taiwan's National Chiao Tung University pipeline, constraining foundry expansion outside established clusters.
- Dual-Certification Timelines:Automotive AEC-Q101 qualification and IEC 62717 performance testing for general illumination impose sequential validation periods that delay product launches by 18-24 months, compressing effective revenue windows before refresh cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Flip Chip Market |
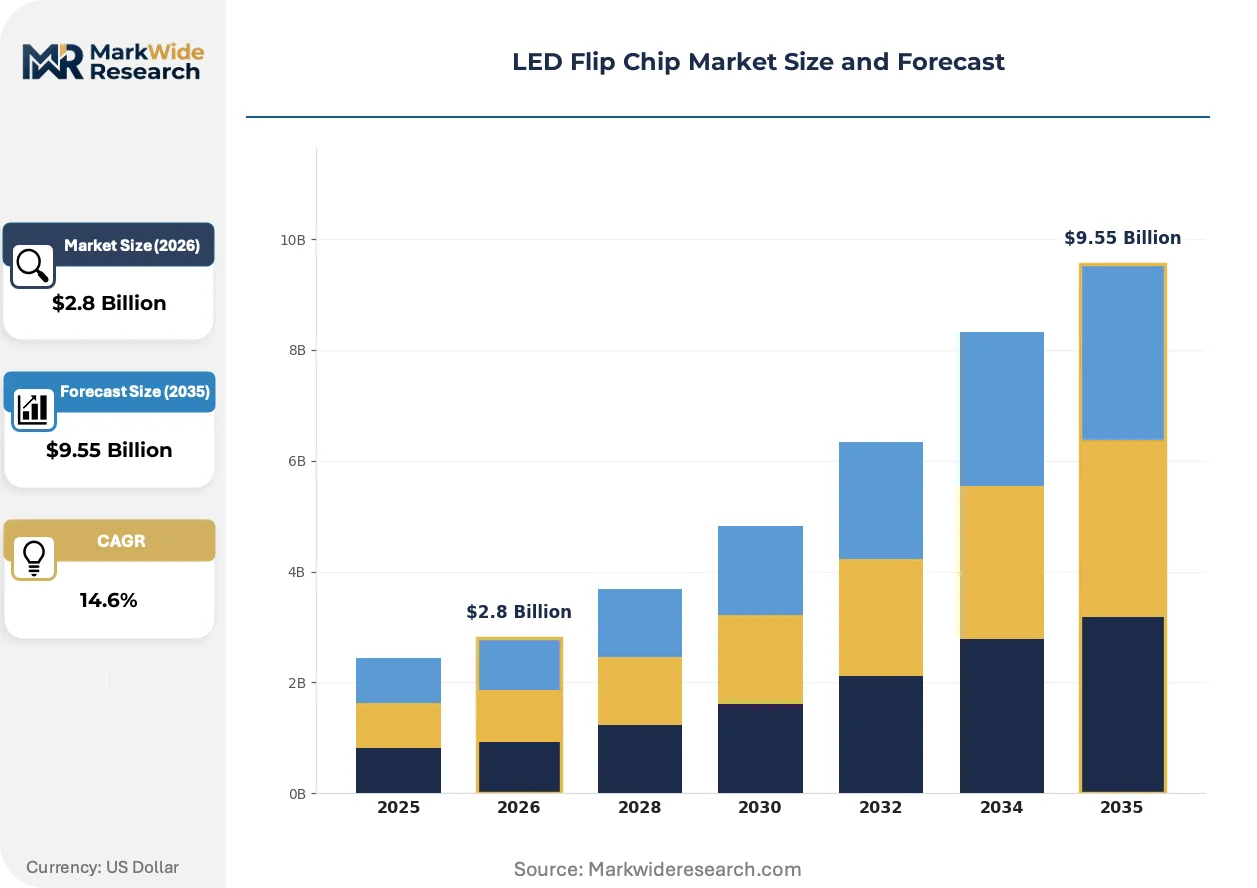
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Power LEDs, Miniature LEDs, Micro LEDs, Conventional Chip On Board Application: Automotive Lighting, Display Technology, General Illumination, Backlighting Solutions End User: Consumer Electronics, Automotive Manufacturers, Industrial Equipment, Architectural Firms Installation: Surface Mount, Through-Hole, Integrated Module, Adhesive Bonding |
| Companies Covered | Samsung Electronics, Epistar Corporation, Nichia Corporation, Sanan Optoelectronics, Amkor Technology, OSRAM Opto Semiconductors, TSMC, Intel Corporation, Lumileds Holding B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Flip Chip Market Shifts & Advancements
Epitaxy-to-package process flows are fragmenting as equipment vendors decouple deposition, lithography, and bonding steps, enabling modular capacity expansion without captive fab construction.
Gallium nitride-on-silicon epitaxy is modularizing across the supply base. Tier 2 foundries in Malaysia and Vietnam are licensing reactor configurations from established Taiwanese equipment suppliers, bypassing the capital intensity of proprietary process development. This diffusion is compressing minimum efficient scale thresholds and enabling regional suppliers to qualify for automotive Tier 2 contracts previously reserved for integrated IDMs.
REACH Annex XIV authorization requirements for cadmium-containing quantum dot phosphors are restructuring European display supply chains. Panel makers are accelerating flip chip adoption with on-chip nitride phosphor conversion to preempt regulatory exclusion from premium television segments. Germany's KBA and France's ANSM have aligned type-approval timelines with ECHA sunset dates, forcing synchronized product redesigns across backlighting divisions.
Consolidated procurement by display panel makers is displacing fragmented distributor networks. Samsung Electronics and BOE Technology Group are negotiating direct epitaxy supply agreements with multi-year volume commitments, extracting price transparency through wafer-level costing models. This concentration is most visible in South Korea's Gyeonggi-do cluster, where foundry gate fees now incorporate yield-risk sharing provisions previously borne by packaging houses.
LED Flip Chip Market Segmentation
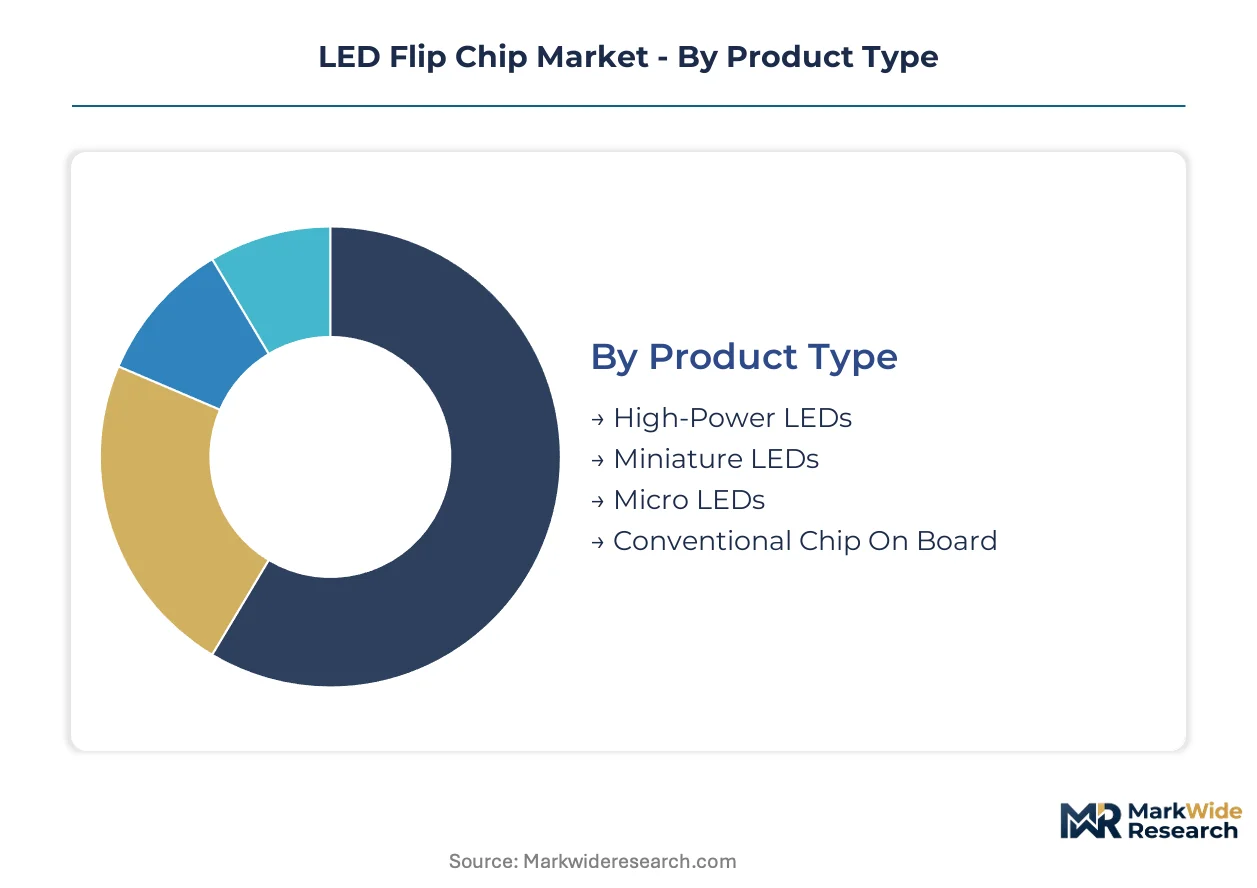
LED flip chip architectures exhibit divergent capital requirements across product tiers, with micro LED investments demanding billion-dollar fab commitments while surface-mount packages scale through modular equipment. Segmentation clarity enables suppliers to align foundry capacity with qualification timelines and margin profiles.
Product Type:
Capital intensity varies sharply across this dimension, with gallium nitride-on-silicon epitaxy and mass transfer equipment creating order-of-magnitude differences in upfront investment.
- High-Power LEDs:Devices engineered for junction temperatures exceeding 150°C through optimized thermal vias and ceramic submounts. Automotive forward lighting in Germany and Japan concentrates procurement, with NHTSA beam-pattern compliance forcing thermal performance thresholds wire-bonded alternatives cannot meet.
- Micro LEDs:Sub-50-micron emitters requiring laser lift-off transfer from sapphire to silicon carriers with placement accuracy below 1 micron. Panel makers in South Korea's Gyeonggi-do cluster drive qualification volumes, though mass transfer yield limits defer commercial television shipments.
- Miniature LEDs:Mid-size format bridging conventional and micro architectures, typically 50-200 microns.
- Conventional Chip On Board:Legacy wire-bonded alternative facing displacement by flip chip thermal advantages in high-luminance applications.
High-Power LEDs absorb the bulk of installed capacity; Micro LEDs are expanding most quickly.
Application:
Margin structure separates this dimension, with display technology commanding premium binning fees and shorter refresh cycles against general illumination's volume pricing.
- Display Technology:Direct-view and backlighting applications requiring sub-2-nm wavelength uniformity and 99.9% pixel yield. Samsung Electronics and BOE Technology Group concentrate procurement in South Korea and China, with EU REACH Annex XIV cadmium restrictions accelerating nitride phosphor conversion adoption.
- Automotive Lighting:Forward and signal applications subject to AEC-Q101 thermal cycling and ECE R48 photometric compliance. OEM qualification timelines in Stuttgart and Toyota City reward foundries with proven gallium nitride-on-silicon reliability data.
- General Illumination:Commercial and residential retrofit markets where China's GB efficacy mandates disqualify conventional packaged LEDs from government procurement.
- Backlighting Solutions:Edge-lit and full-array configurations for liquid-crystal displays facing substitution pressure from direct-view micro LED panels.
Display Technology extracts the highest per-unit margins; Automotive Lighting is climbing the fastest as thermal requirements harden.
End User:
Procurement sophistication distinguishes this dimension, with automotive Tier 1s demanding wafer-level traceability against consumer electronics volume consolidation.
- Automotive Manufacturers:Vertically integrated lighting divisions at Volkswagen Group and Toyota Motor Corporation specifying junction-to-board thermal resistance below 2 K/W. Germany's KBA and Japan's MLIT align type-approval timelines, compressing supplier qualification windows.
- Consumer Electronics:Television and smartphone panel makers consolidating epitaxy procurement through multi-year wafer supply agreements. China's BOE and South Korea's Samsung Electronics extract price transparency through yield-risk sharing provisions.
- Industrial Equipment:Factory automation and machine vision applications requiring spectral stability under continuous operation.
- Architectural Firms:Specifiers of tunable white and dynamic color systems for facade and landscape integration.
Consumer Electronics concentrates procurement volume; Automotive Manufacturers are gaining share fastest as thermal specifications tighten.
Installation:
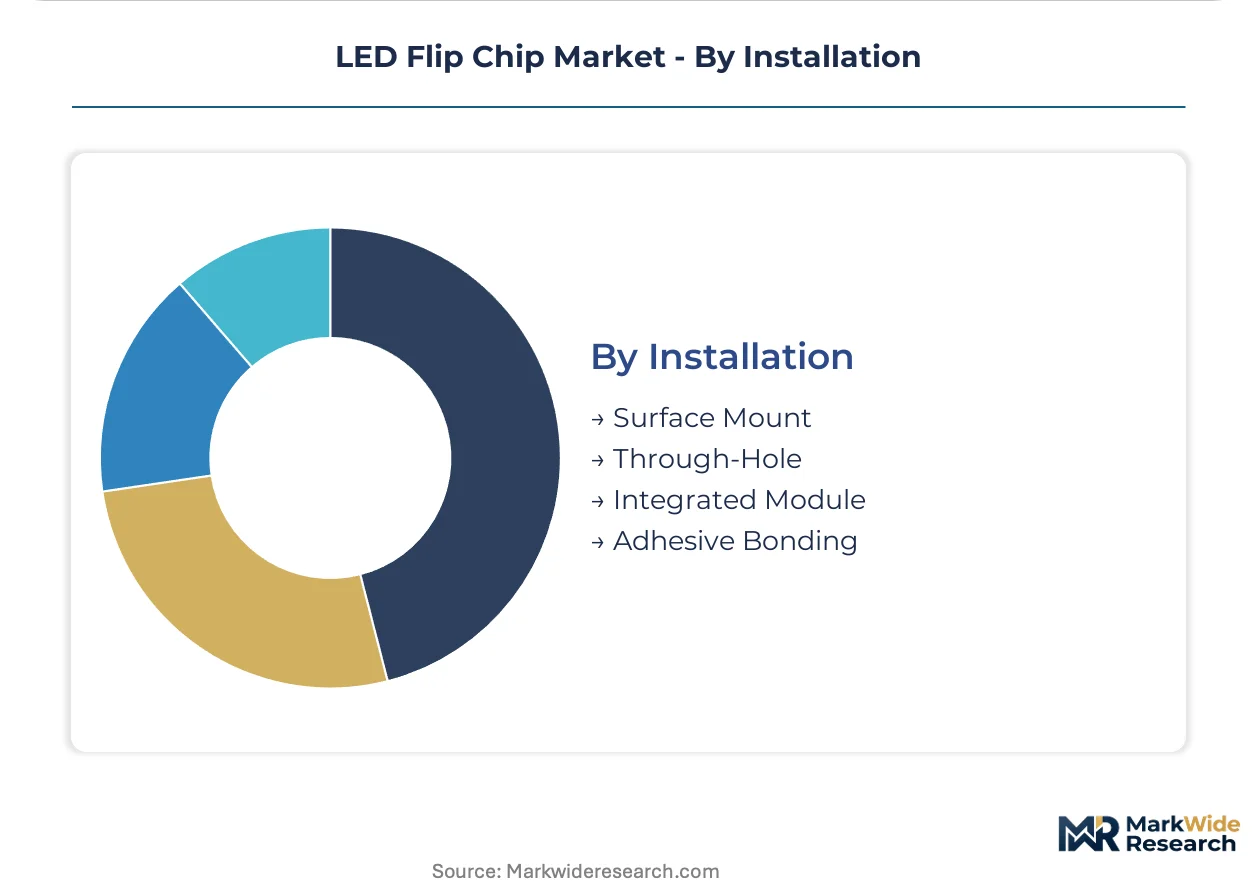
Process compatibility separates this dimension, with surface-mount dominance in electronics assembly against integrated module requirements in automotive headlamp housings.
- Surface Mount:Standard pick-and-place compatibility with reflow soldering profiles. Electronics manufacturing services in Shenzhen and Taipei deploy high-speed placement equipment for display backlighting modules.
- Integrated Module:Pre-assembled emitter arrays with integrated optics and thermal management. Automotive headlamp suppliers in Ingolstadt and Toyota City specify module-level qualification to compress Tier 1 assembly steps.
- Through-Hole:Legacy mounting for industrial retrofit applications with existing printed circuit board footprints.
- Adhesive Bonding:Thermally conductive die-attach for high-power density arrays where solder joint reliability fails under thermal cycling.
Surface Mount dominates shipment volume; Integrated Module is expanding most quickly as automotive architectures consolidate subassemblies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in East Asian manufacturing corridors where foundry investments in gallium nitride-on-silicon capacity cluster around established compound semiconductor ecosystems. China's dual carbon goals and automotive thermal specifications in Germany and Japan are redirecting procurement toward flip chip architectures with junction-to-board thermal resistance below 2 K/W.
China
Automotive forward lighting and display panel manufacturing dominate procurement volumes. GB standards on solid-state lighting efficacy under the dual carbon goals disqualify conventional packaged LEDs from government procurement. Yangtze River Delta clusters around Shanghai and Suzhou concentrate epitaxy and packaging investments.
South Korea
Samsung Electronics and display panel makers drive qualification volumes for micro LED architectures. MFDS alignment with EU REACH Annex XIV cadmium restrictions accelerates nitride phosphor conversion adoption. Gyeonggi-do corridor foundries negotiate wafer-level yield-risk sharing provisions with direct epitaxy supply agreements.
Taiwan
Epistar Corporation anchors concentrated gallium nitride wafer production serving global display backlighting divisions. National Chiao Tung University pipeline supplies specialized metal-organic chemical vapor deposition reactor operation expertise. Hsinchu Science Park clusters foundry utilization for gallium nitride-on-silicon capacity.
Germany
Volkswagen Group lighting divisions specify junction-to-board thermal resistance below 2 K/W for headlamp architectures. KBA type-approval timelines align with ECHA sunset dates for cadmium-containing quantum dot phosphors. Stuttgart and Ingolstadt automotive clusters compress supplier qualification windows.
Japan
Toyota Motor Corporation vertically integrated lighting divisions demand proven gallium nitride-on-silicon reliability data. METI JIS standards restrict mercury-containing legacy sources in industrial settings. Toyota City and Nagoya clusters reward foundries with thermal cycling performance exceeding wire-bonded LED limits.
LED Flip Chip Market Competitive Landscape
East Asian producers anchor one tier; European and North American specialists hold differentiated positions in automotive qualification and phosphor IP. The vendor base concentrates around integrated device manufacturers with captive epitaxy capacity and pure-play foundries serving fabless packaging houses. Three archetypes dominate: gallium nitride epitaxy specialists, automotive-qualified module integrators, and display-centric phosphor-conversion IP holders. Capacity expansion through gallium nitride-on-silicon reactor licensing and backward integration into rare-earth phosphor sourcing represent the dominant competitive moves.
Within the epitaxy-specialist tier, Epistar Corporation and Sanan Optoelectronics occupy positions defined by concentrated gallium nitride wafer production. Samsung Electronics exemplifies the vertically integrated archetype through internalized foundry capacity serving captive display divisions. Nichia Corporation anchors the phosphor-conversion IP tier through vertical control over rare-earth material sourcing.
| Leading Market Players |
|---|
| Samsung Electronics |
| Epistar Corporation |
| Nichia Corporation |
| Sanan Optoelectronics |
| Amkor Technology |
| OSRAM Opto Semiconductors |
| TSMC |
| Intel Corporation |
| Lumileds Holding B.V. |
| Others |
Supply & Pricing Matrix
Rare-earth oxide spot indices for cerium and yttrium feed directly into phosphor-conversion cost stacks, compressing margins for non-integrated packagers while rewarding suppliers with captive separation capacity in China's Jiangxi corridor. This commodity cascade stratifies pricing tiers around thermal performance certification and phosphor sourcing integration levels.
Pricing Analysis
Volume-mass shipments of high-power automotive LEDs trade at compressed margins against micro LED epitaxy wafers that command 3-4x per-unit premiums for display panel procurement. Pricing stratifies across AEC-Q101 automotive certification tiers, GB-standard compliance grades for Chinese government procurement, and uncertified commercial retrofit segments. Cost compression in general illumination runs through gallium nitride-on-silicon foundry gate fee negotiations as Samsung Electronics and BOE Technology Group extract yield-risk sharing provisions. Automotive Tier 1s exhibit lowest price sensitivity due to thermal specification lock-in, while architectural retrofit distributors face highest sensitivity to phosphor-thickness reduction trade-offs.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Hsinchu, and Gyeonggi-do operate hub-and-spoke patterns feeding surface-mount assembly lines across East Asian electronics manufacturing services. Gallium nitride epitaxy concentrates in Taiwan, South Korea, and China, with metal-organic chemical vapor deposition reactor capacity anchored in Hsinchu Science Park and Yangtze River Delta clusters. Sapphire substrate and rare-earth phosphor dependencies tether supply chains to Chinese separation facilities and Ukrainian/Russian neon gas processing. Single-source vulnerability in cerium-doped yttrium aluminum garnet supply creates allocation risk during automotive and display procurement cycle synchronization. Distribution runs through direct epitaxy supply agreements with multi-year wafer-level commitments displacing fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
LED flip chip market consolidation is accelerating as China's dual carbon goals and automotive thermal specifications disqualify conventional packaged LED suppliers, forcing asset-light packagers toward acquisition or exit.
For Market Incumbents: To counter foundry utilization constraints in Hsinchu and Pyeongtaek corridors, captive gallium nitride-on-silicon capacity expansion in Malaysia and Vietnam licensing corridors secures automotive Tier 2 qualification pathways. Backward integration into rare-earth phosphor sourcing through offtake agreements with Chinese separation facilities absorbs cerium price volatility that non-integrated competitors cannot pass through. For New Entrants and Emerging Players: EU REACH Annex XIV cadmium restrictions in European display supply chains open a window for nitride phosphor conversion specialists to capture premium television backlighting procurement. Stadium and horticultural illumination in North American and European controlled-environment agriculture represents the most penetrable white-space segment, with spectral-tunable array qualification timelines shorter than automotive AEC-Q101 cycles. Go-to-market positioning through direct foundry partnerships bypasses distributor margin extraction. For Investors and Strategic Acquirers: Distressed-cycle entries favor automotive-qualified module integrators with proven gallium nitride-on-silicon reliability data in Germany's Stuttgart and Ingolstadt clusters. Long-term viability hinges on 5-10 year thermal specification hardening across NHTSA and EU ECE R48 regulatory evolution. Laser lift-off yield inflection at commercial micro LED television volumes signals epitaxy investment monetization timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Phosphor Sourcing | Absorbs Jiangxi corridor price volatility that compresses non-integrated packager margins. |
| Gallium Nitride-on-Silicon Foundry Licensing | Enables Malaysia and Vietnam Tier 2 suppliers to qualify for automotive contracts previously reserved for IDMs. |
| AEC-Q101 Certification Investment | Unlocks Volkswagen Group and Toyota Motor Corporation procurement specifications below 2 K/W thermal resistance. |
| Direct Epitaxy Supply Agreement Negotiation | Extracts wafer-level price transparency through yield-risk sharing provisions with Samsung Electronics and BOE. |
| Nitride Phosphor Conversion R&D | Preempts EU REACH Annex XIV exclusion from premium European television display segments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted across epitaxy process engineers, automotive Tier 1 procurement managers, display panel supply chain directors, and phosphor conversion R&D leads. Semiconductor equipment vendor disclosures, SEC 10-K filings from listed LED manufacturers, and China's MIIT GB standard draft comment periods provided validation triangulation. Bottom-up wafer shipment aggregation and top-down display panel area demand modeling were cross-referenced for convergence.
Data-stream reconciliation across epitaxy utilization rates, mass transfer equipment installation counts, and automotive headlamp LED content-per-vehicle metrics shaped the analytical framework. Segmentation dimensions modeled include product architecture, application thermal specification tier, end-user procurement sophistication level, and regional regulatory compliance cluster. CAGRs were derived from compound growth path fitting across the projection horizon. Foundry gate fee trajectories and laser lift-off yield improvement curves served as LED-specific forecast inputs.
Caveats apply where gallium nitride-on-silicon reactor capacity expansion delays or rare-earth export restriction shocks could materially shift the outlook. Forecasts reflect assumptions around procurement cycle synchronization patterns and regulatory sunset timeline adherence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Monochrome Outdoor LED Display Market
LED
India Indoor LED Lighting Market
LED
Surface Mount PLCC Leds Market
LED
Brazil LED Market
LED
Architectural LED Products Market
LED
Infrared (IR) LED Market
LED
UK LED Lighting Market
LED
High-Brightness Light-Emitting Diodes (LED) Headlamps Market
LED
UK Outdoor LED Lighting Market
LED
Middle East LED Lighting Market
LED
Indonesia LED Market
LED
Bluetooth LED Bulb Market
LED
North America LED Packaging Market
LED
LED Control Unit Market
LED
Mini LED Market
LED
Gan Substrate Market