
 Global Waterproof LED Module Market | 2026-2036
Global Waterproof LED Module Market Size, Share, and Industry Trends Forecast 2026-2036
Global Waterproof LED Module Market Intelligence
A divergence in manufacturing automation and vertical integration is unwinding the competitive hierarchy. Large-scale producers like Samsung Electronics leverage vast semiconductor fabrication capabilities to control costs. In contrast, specialists such as Osram differentiate through deep expertise in high-performance automotive and industrial lighting. Nichia sustains its market position by focusing on proprietary phosphor and semiconductor material innovations, commanding premium pricing in specialized segments.
A waterproof LED module is a self-contained lighting device engineered for durability, typically featuring an Ingress Protection (IP) rating of IP67 or higher. These units use silicone or epoxy resin encapsulation to protect internal circuitry from moisture and dust. Their primary purpose is providing reliable illumination for outdoor signage, architectural features, and marine applications. High-Power LED Modules are seeing accelerated adoption for stage and landscape lighting, while the outdoor signage application remains the largest volume driver.
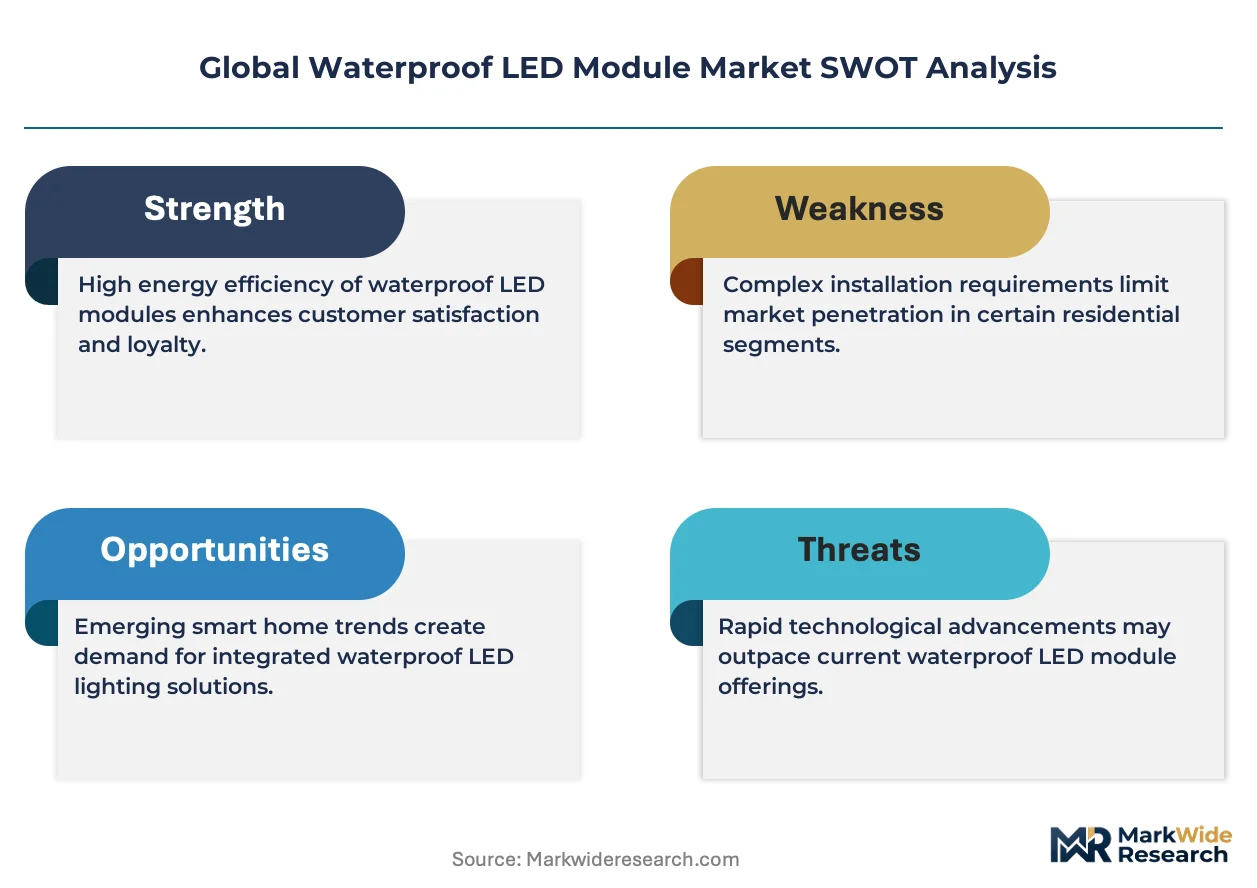
Regulatory frameworks directly shape product development. In Europe, CE marking and RoHS compliance are mandatory, restricting hazardous materials and ensuring safety. China’s GB standards impose strict requirements on energy efficiency and performance for LED products. These regulations force manufacturers to manage distinct supply chains for different regions. Navigating varied compliance pathways while managing component costs is a central strategic challenge for market participants.
Market Dynamics
The market's trajectory is defined by the push for greater energy efficiency, driven by regulations like China's dual carbon goals. This force compels innovation in material science and circuit design to meet performance targets for outdoor and architectural applications without compromising durability.
Growth Catalysts
- Digital Advertising Expansion:The proliferation of dynamic digital billboards and public information displays in urban centers drives volume demand for reliable, weather-resistant LED modules.
- Energy Efficiency Mandates:Government initiatives, including the EU's Ecodesign requirements and China's energy standards, incentivize the replacement of legacy lighting with more efficient LED technology, creating a significant replacement market.
- Advanced Encapsulation Materials:Innovations in silicone and epoxy resins are improving Ingress Protection ratings and thermal management, expanding the addressable market to harsher environments like marine and industrial settings.
Market Restraints
- Silicone and Phosphor Costs:Price volatility for key raw materials like high-purity silicone and proprietary phosphors creates margin pressure, particularly for manufacturers competing in the high-volume signage segment.
- Thermal Management Complexity:High-power LED modules generate significant heat, and inadequate thermal dissipation can lead to premature failure and color shifts, limiting their effective lifespan in compact enclosures.
- Divergent Regional Standards:Manufacturers face increased costs and supply chain complexity managing separate product lines to comply with Europe's CE marking and China's GB standards simultaneously.
Strategic Opportunities
- Horticultural Lighting:The expansion of controlled environment agriculture presents an opportunity for specialized waterproof LED modules designed to withstand high humidity while delivering specific light spectrums for plant growth.
- Infrastructure Projects in Southeast Asia:Large-scale public infrastructure and smart city projects in countries like Vietnam and Indonesia offer new growth avenues for architectural and public space illumination.
- Integration with IoT Controls:Embedding wireless connectivity and sensors into modules creates value-added smart lighting systems for remote monitoring, diagnostics, and adaptive illumination in smart city applications.
Industry Challenges
- Lengthy Certification Cycles:Obtaining IP, CE, and RoHS certifications for new product designs is a time-consuming and expensive process that can delay market entry and tie up engineering resources.
- Phosphor Patent Litigation:Ongoing intellectual property disputes and complex licensing agreements surrounding critical phosphor and semiconductor technologies create legal risks and barriers to entry for smaller firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Waterproof LED Module Market |
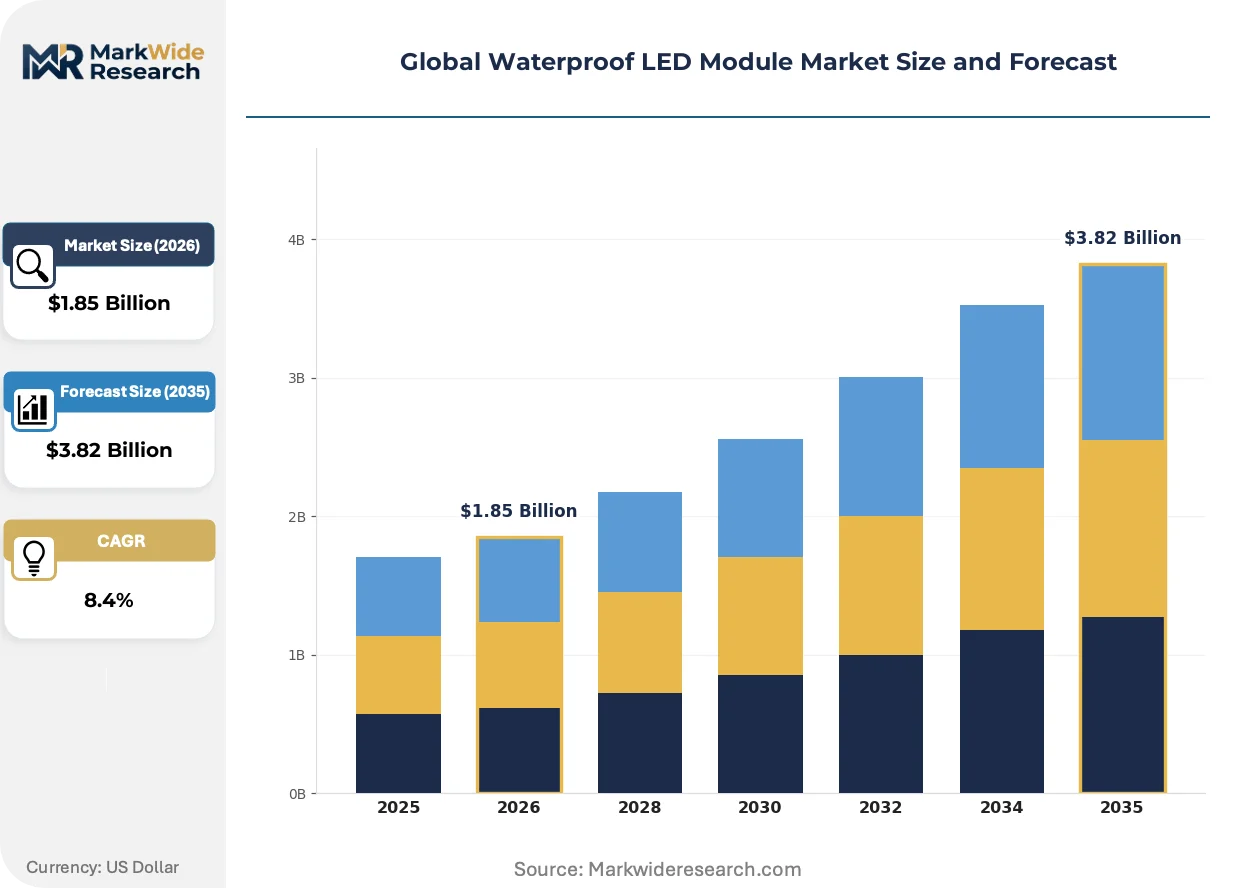
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard LED Modules, High-Power LED Modules, Flexible LED Modules, COB LED Modules Application: Outdoor Signage, Automotive Lighting, Landscape Lighting, Stage Lighting, Marine Lighting Installation Type: Surface Mount, Recessed Mount, Suspended Mount, Embedded Installation End User: Advertising Agencies, Vehicle Manufacturers, Event Organizers, Architectural Firms |
| Companies Covered | Samsung Electronics, Philips Lighting (Signify), Osram, Cree, Nichia, LG Innotek, Lextar, Everlight, Absen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Waterproof LED Module Market Strategic Shifts & Innovations
Product evolution is driven by the dual pressures of miniaturization for higher-resolution displays and the integration of smart controls for adaptive lighting systems. These shifts are occurring alongside a tightening regulatory environment that scrutinizes material composition and energy consumption across the product lifecycle.
Chip-on-Board (COB) technology integrates multiple LED chips directly onto a substrate, creating a single, dense lighting source. This approach is gaining rapid adoption in architectural and high-power floodlighting applications where uniform, intense light is required. COB technology is displacing traditional Surface-Mount Device (SMD) modules in these segments by offering superior lumen density and simplified thermal management.
The European Union's Restriction of Hazardous Substances (RoHS) directive strictly limits the use of materials like lead and mercury in electronic equipment. This regulation forces manufacturers to re-engineer soldering processes and source compliant components, often at a higher cost. The outdoor signage and architectural lighting segments are most affected, requiring dedicated supply chains for products sold into the EU market.
A shift towards specification-driven procurement is evident, where architects and lighting designers demand custom-tailored modules for specific projects. This trend bypasses traditional distribution channels in favor of direct engagement between end-users and manufacturers or specialized integrators. This model is most prominent in large-scale architectural facade lighting and themed entertainment projects in the United States and the Middle East.
Global Waterproof LED Module Market Segmentation
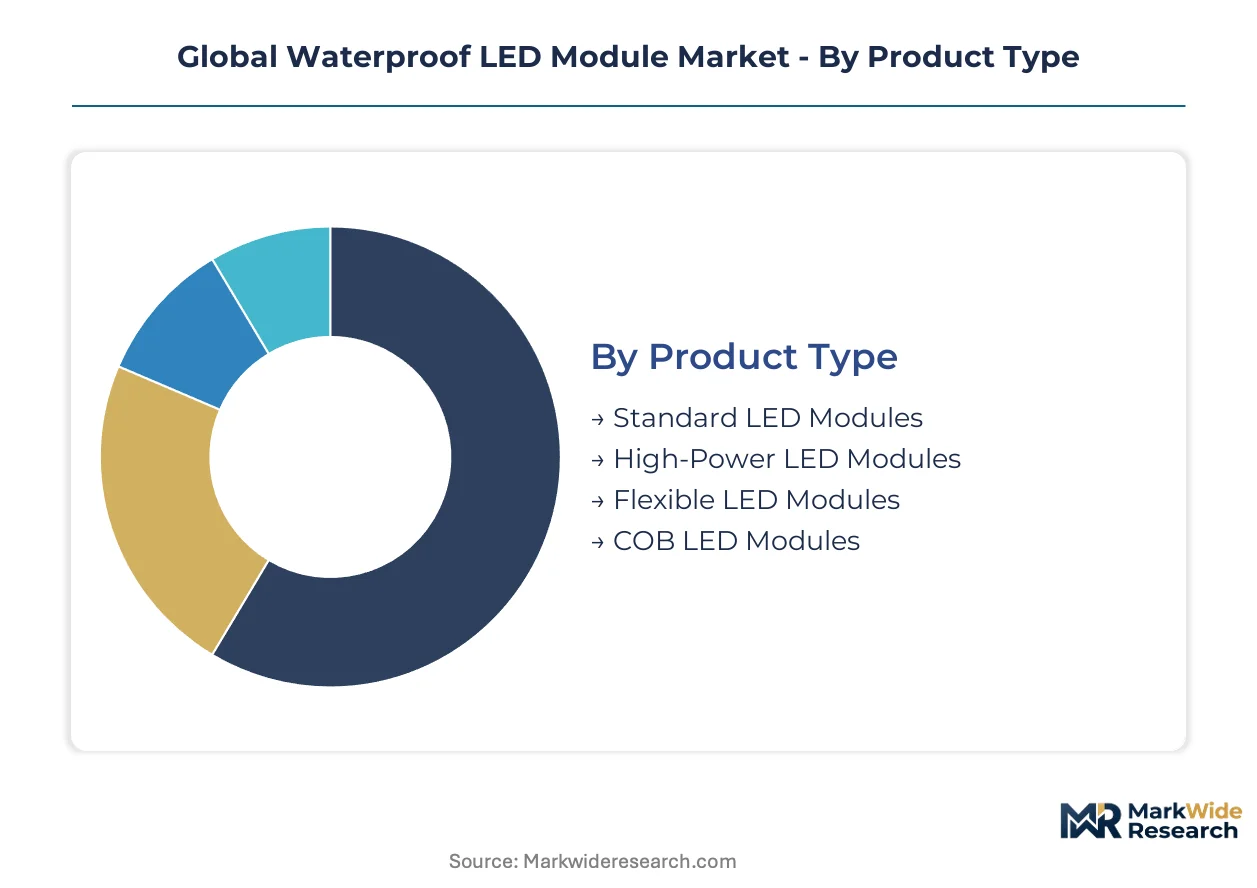
Segmentation provides a granular view of the Global Waterproof LED Module market, revealing distinct demand patterns and competitive dynamics. Analyzing these segments helps manufacturers tailor product development and market entry strategies. Each category reflects unique technological requirements and end-user preferences across various applications.
Product Type:
Substitution pressure is most evident in the Standard LED Modules segment, as COB and High-Power alternatives offer superior performance for specific applications. Manufacturers are innovating to differentiate product offerings.
- High-Power LED Modules:These units are engineered for maximum light output and intensity, often featuring advanced thermal management. Demand concentrates in stage and landscape lighting, driven by the need for powerful, long-throw illumination in large venues and public spaces.
- COB LED Modules:Chip-on-Board technology integrates multiple LED chips onto a single substrate, creating a dense, uniform light source with high lumen density. Demand is significant in architectural facade lighting across the United States and Europe, driven by requirements for seamless and intense visual effects.
- Standard LED Modules:These modules provide basic illumination for general-purpose applications, emphasizing cost-effectiveness and broad utility.
- Flexible LED Modules:Designed with bendable substrates, these modules conform to curved or irregular surfaces for creative lighting designs.
Standard LED Modules retain volume leadership; COB LED Modules hold the steepest expansion curve.
Application:
Volume concentration dictates the strategic focus within the application segments, with outdoor signage representing the largest market share. Specialized applications require unique product attributes.
- Outdoor Signage:These modules are built for durability and high visibility in external environments, crucial for dynamic digital billboards and public information displays. Demand is robust in urban centers across China and Southeast Asia, driven by the expansion of digital advertising infrastructure.
- Landscape Lighting:Designed to withstand harsh weather, these modules provide aesthetic and functional illumination for parks, gardens, and public areas. Demand is strong in large-scale infrastructure projects in countries like Vietnam and Indonesia, driven by urban beautification initiatives.
- Automotive Lighting:Waterproof LED modules are integrated into vehicle headlamps, taillights, and interior lighting systems for reliability.
- Stage Lighting:These modules deliver high-intensity, color-rich illumination for concerts, theatrical productions, and live events.
- Marine Lighting:Engineered to endure saltwater exposure and extreme humidity, these modules are used in boats, docks, and underwater installations.
This segment sees robust demand from outdoor advertising, while marine applications are gaining traction.
Installation Type:
Technical complexity varies significantly across installation types, influencing product design and integration requirements. Each method serves distinct functional and aesthetic purposes.
- Surface Mount:Modules are directly affixed to the exterior of a surface, offering straightforward installation and visible light sources. Demand is consistent in retrofit projects across Europe, driven by the ease of upgrading existing lighting infrastructure.
- Embedded Installation:These modules are fully integrated within a structure, providing a seamless, flush finish that conceals the light source. Demand is concentrated in high-end architectural projects in the Middle East, driven by minimalist design preferences.
- Recessed Mount:Modules are partially set into a cavity, creating a less obtrusive lighting effect than surface-mounted options.
- Suspended Mount:These modules hang from ceilings or overhead structures, often used for ambient or task lighting in commercial spaces.
Flexibility in deployment characterizes this category, with surface mount options offering broad utility.
End User:
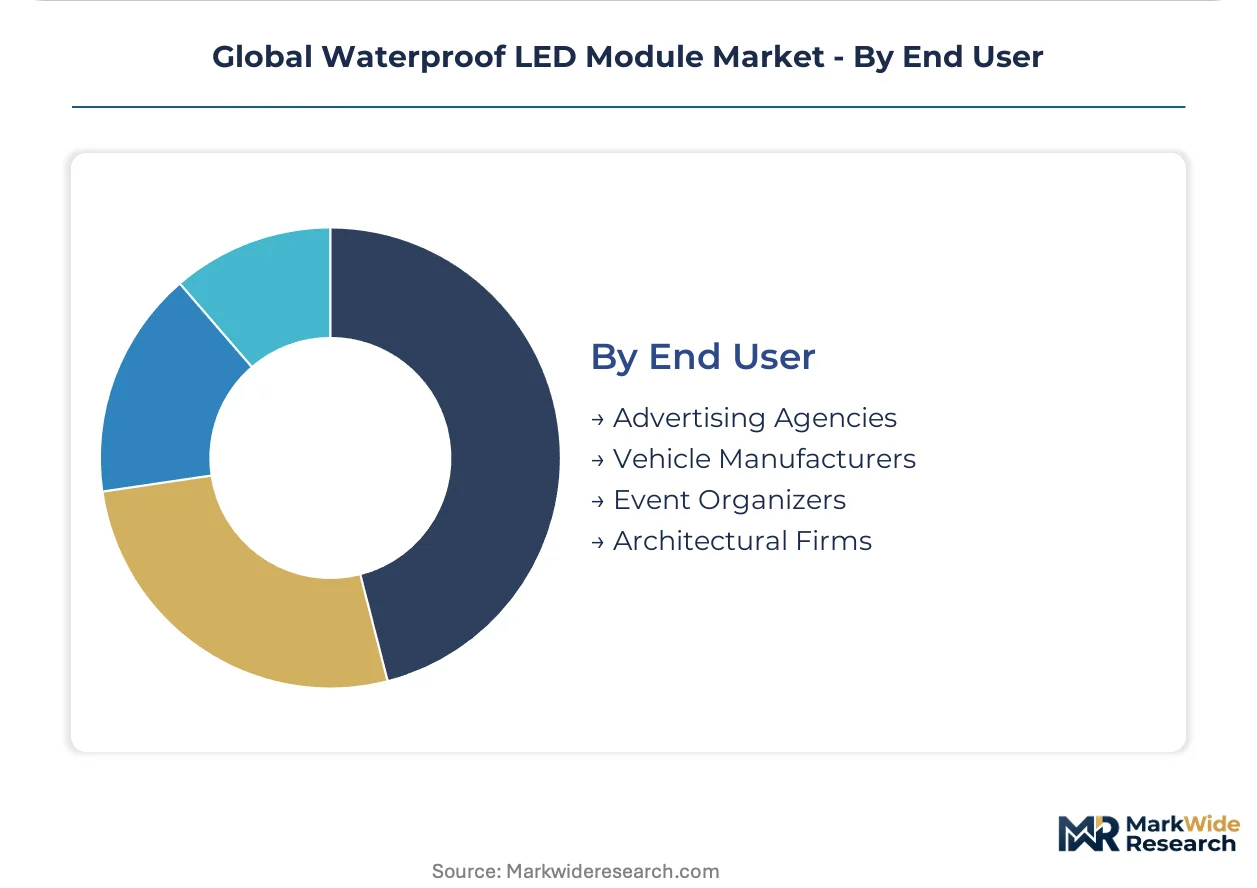
Project scale and specific procurement patterns define the end-user segments, each requiring tailored product specifications and support. Collaboration with these entities is crucial for market penetration.
- Advertising Agencies:These firms procure waterproof LED modules for large-format digital billboards and dynamic outdoor displays. Demand originates from major brand campaigns across the United States, driven by the need for impactful visual communication.
- Architectural Firms:These entities specify waterproof LED modules for building facades, public art installations, and urban landscaping projects. Demand is strong from smart city developments in Southeast Asia, driven by integrated design requirements.
- Vehicle Manufacturers:Companies in the automotive sector integrate specialized waterproof LED modules into their vehicle designs.
- Event Organizers:These professionals utilize robust LED modules for temporary installations at festivals, concerts, and exhibitions.
This segment reflects the diverse professional needs across the value chain, with advertising agencies being prominent consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for waterproof LED modules diverges significantly, with developed markets like the United States dictating premium specifications while high-volume production in China influences global cost structures. This asymmetry shapes manufacturing investment and supply chain optimization efforts across continents. Manufacturers balance innovation with cost-efficiency to meet varied regional demands.
United States
Demand for high-power LED modules in architectural and large-scale commercial projects drives volume. The Inflation Reduction Act (IRA) incentivizes energy-efficient lighting installations, benefiting advanced LED technologies. Silicon Valley and other tech hubs foster innovation in smart lighting integration for urban spaces.
China
Outdoor signage and smart city initiatives generate substantial demand for durable LED modules. China's dual carbon goals impose strict energy efficiency standards on all LED products, compelling local innovation. Manufacturing clusters in Shenzhen and Guangzhou are central to global supply chains for these components.
Germany
Specification-driven procurement for infrastructure and automotive lighting projects maintains demand for specialized modules. CE marking and RoHS compliance are mandatory, ensuring product safety and environmental standards. The Munich region is a hub for high-performance lighting research and development.
Japan
Architectural facade lighting and industrial applications require high-reliability waterproof LED modules. METI (Ministry of Economy, Trade and Industry) promotes advanced lighting technologies through various initiatives. Tokyo's urban development projects frequently integrate sophisticated LED solutions for public spaces.
Vietnam
Public infrastructure and urban beautification projects create demand for landscape and outdoor signage lighting. Government-backed smart city developments in Hanoi and Ho Chi Minh City drive adoption of integrated LED systems. Local manufacturing capabilities are expanding to meet regional needs for durable lighting.
Global Waterproof LED Module Market Key Industry Players
Concentration sits with large-scale electronics conglomerates that leverage existing semiconductor fabrication capabilities. The market structure exhibits a tiered consolidation, with a few global giants dominating volume segments and numerous specialized firms serving niche applications. Strategic archetypes include vertically integrated manufacturers, technology innovators, and regional specialists. Companies pursue geographic expansion and portfolio diversification to capture market share.
Within the scale-driven end, Samsung Electronics anchors a significant portion of the high-volume market, leveraging its extensive semiconductor fabrication capabilities to control costs. Osram occupies a position as a specialist in high-performance automotive and industrial lighting, differentiating through deep technical expertise and product reliability. Nichia exemplifies a technology innovator, sustaining its market position through proprietary phosphor and semiconductor material innovations, commanding premium pricing in specialized segments. These players collectively demonstrate the diverse strategies employed to maintain competitive advantage.
| Leading Market Players |
|---|
| Samsung Electronics |
| Philips Lighting (Signify) |
| Osram |
| Cree |
| Nichia |
| LG Innotek |
| Lextar |
| Everlight |
| Absen |
| Others |
Cost & Logistics Intelligence
Project-based procurement, common in large architectural and infrastructure projects, locks in both supply access and pricing visibility for specialized waterproof LED modules. This model balances the need for custom solutions with supplier commitment.
Pricing Analysis
The customization-premium spread defines pricing across the waterproof LED module market, with project-based pricing dominating for specialized architectural and high-power modules. Price differentiation stems from certification levels like CE marking and the degree of thermal management integration. Pricing pressure stems from volatile high-purity silicone and proprietary phosphor costs, particularly impacting the high-volume outdoor signage segment. Advertising agencies are generally more price-sensitive for standard modules than architectural firms procuring custom solutions.
Supply Chain Analysis
Access to advanced semiconductor fabrication capabilities underwrites the supply of high-performance LED chips. Geographic supply concentration centers on China, South Korea, and Japan for critical LED components and phosphors. Commodity price volatility for these key inputs presents a structural risk for module producers. Distribution primarily runs through specialized integrators and direct engagement channels for architectural and project-based applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is experiencing a cyclical recovery, primarily driven by renewed global infrastructure spending. Urban beautification initiatives and smart city developments are stimulating demand for advanced lighting solutions.
For Market Incumbents:
Shield core market share by deepening vertical integration into advanced material science for encapsulation and phosphors. Invest in R&D for next-generation thermal management solutions to counter performance degradation in high-power modules. Consolidate supply chain relationships to mitigate raw material price volatility for silicone and specialized resins. Focus on securing CE marking and GB standards compliance for diverse regional market access.
For New Entrants and Emerging Players:
A streamlined certification pathway for specific regional standards, like a fast-track for Vietnam's infrastructure projects, offers a market entry point. Target specialized white-space applications such as horticultural lighting, which requires unique light spectrums and humidity resistance. Focus on developing integrated IoT controls for adaptive illumination systems in smart city applications. A direct-to-integrator go-to-market angle allows for custom solutions and avoids established distribution channels.
For Investors and Strategic Acquirers:
Specialized technology firms possessing proprietary phosphor formulations or advanced encapsulation IP represent attractive acquisition targets over the next 5-10 years. These firms offer differentiation against commoditization in standard module segments. Regional integrators with strong project execution capabilities in Southeast Asia also present strategic value. A key signal to watch is the volume of patent filings in advanced material science and smart lighting control interfaces.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphor Production | Controls critical input costs and secures supply for Nichia and Osram. |
| Expand IoT-Enabled Module Portfolio | Creates value-added smart lighting systems for urban centers in the United States. |
| Regional Manufacturing Hub in Southeast Asia | Reduces logistics costs and enhances responsiveness for Vietnam's infrastructure projects. |
| Invest in Advanced Encapsulation R&D | Improves IP ratings and thermal performance for marine and industrial applications. |
| Pursue CE Marking and GB Standards Compliance | Ensures market access and regulatory adherence for Europe and China. |
Research Approach
A standing panel of architectural firm principals, advertising agency executives, LED module engineers, and procurement managers provided ongoing calibration for market sizing. This study combined extensive primary interviews with industry stakeholders and rigorous secondary validation. Data sources included government reports, industry association data, company financial statements, and patent databases. Bottom-up and top-down triangulation ensured robust market estimates.
Outputs were validated against external benchmarks and cross-referenced with macroeconomic indicators across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, installation type, end user, and regional regulatory environment. Compound Annual Growth Rates were derived from historical trends and projected market dynamics. Key forecast inputs included digital advertising spend and public infrastructure investment.
Decision-makers should treat outputs as directional under current raw material price stability and regulatory frameworks; material deviation would warrant model refresh. Forecasts reflect assumptions on technological advancements; raw material price shocks or new regulatory mandates pose risks. Outcomes outside this envelope require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Superluminescent Diodes Market
LED
LED Light Market
LED
Asia Pacific LED Lighting Market
LED
LED Services Market
LED
Global LED Phosphor Market
LED
Mini LED Display Market
LED
High-Brightness Light-Emitting Diodes (LED) Headlamps Market
LED
France Indoor LED Lighting Market
LED
Germany LED Lighting Market
LED
Europe LED Packaging Market
LED
LED Modular Display Market
LED
Asia Pacific Indoor LED Lighting Market
LED
North America LED Lighting Market
LED
High Power LED Market
LED
Microled Market
LED
LED Encapsulation Market