
 LED Lighting Solution Market | 2026-2036
LED Lighting Solution Market Size, Share, and Industry Trends Forecast 2026-2036
LED Lighting Solution Market Analytics
Chinese chip-on-board packaging capacity is decoupling from legacy fluorescent supply chains as domestic foundries scale gallium nitride wafer output. Signify leverages vertical integration across luminaire assembly and connected lighting software to sustain margin capture in commercial retrofits. Nichia Corporation anchors premium automotive headlamp die supply through phosphor-conversion patents that competitors cannot easily replicate. Samsung LED competes aggressively in backlighting for display panels while extending its foundry services to third-party brands.
LED lighting solutions are solid-state electroluminescent devices that convert electrical current directly into visible light through semiconductor junctions, typically achieving luminous efficacy above 150 lumens per watt in commercial-grade packages. Their primary purpose is to displace incandescent and fluorescent technologies across general illumination, display backlighting, and signaling applications where energy efficiency and operational longevity reduce total cost of ownership. The commercial segment dominates installed value due to long operating hours in offices, warehouses, and retail environments that maximize payback on higher upfront fixture costs. Smart technology is expanding fastest as networked controls, occupancy sensing, and daylight harvesting integrate with building management systems to unlock additional energy savings beyond lamp efficacy alone. Municipalities represent a concentrated margin pool because street and area lighting contracts bundle decades of maintenance into single procurement decisions that favor established suppliers with service infrastructure.
The US Department of Energy maintains efficacy and color quality standards through CALiPER testing protocols that filter substandard imports from federal procurement channels. The EU Ecodesign Directive and RoHS restrictions on hazardous substances constrain mercury-containing legacy lamp sales while accelerating LED substitution across member states. China's GB standards for solid-state lighting, administered by standardization authorities under MIIT oversight, set domestic performance floors that shape both local consumption and export compatibility. Stakeholders must monitor how carbon accounting rules in major economies begin to embed embodied emissions from semiconductor fabrication into public tender scoring.
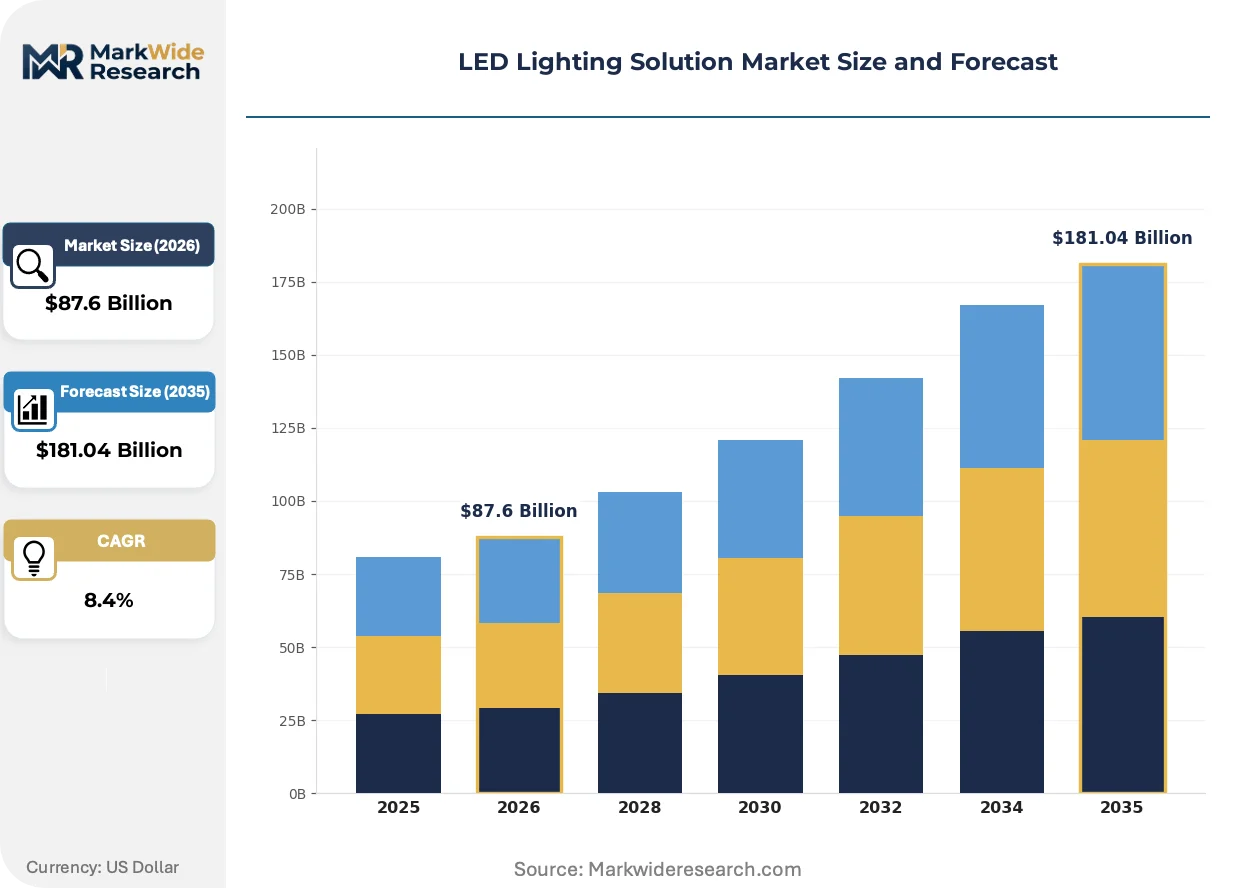
Market Dynamics
The LED Lighting Solution Market is experiencing structural compression as gallium nitride wafer foundries in China decouple from legacy fluorescent supply chains, forcing luminaire assemblers to rebuild procurement relationships around domestic chip-on-board packaging capacity.
Growth Catalysts
- EU Ecodesign Directive:The directive phases out mercury-containing legacy lamps across member states, creating mandatory replacement cycles in commercial and municipal installations.
- Smart city infrastructure:Municipalities bundle decades of maintenance into single procurement decisions, accelerating street and area lighting retrofit programs.
- Gallium nitride wafers:Domestic Chinese foundries scale output of this semiconductor substrate, reducing import dependency for high-efficacy die production.
Market Restraints
- Phosphor-conversion patents:Premium automotive headlamp die supply remains concentrated with holders of unexpired intellectual property, limiting competitor entry.
- CALiPER compliance costs:The US Department of Energy testing protocol filters substandard imports, raising certification barriers for offshore manufacturers.
- Mercury RoHS restrictions:Legacy fluorescent lamp disposal and recycling infrastructure creates stranded asset risk for distributors with fluorescent inventory.
Strategic Opportunities
- Connected lighting software:Building management system integration creates recurring revenue streams beyond hardware sales in commercial retrofits.
- Carbon accounting rules:Embodied emissions from semiconductor fabrication are embedding into public tender scoring, favoring suppliers with transparent supply chains.
- Backlighting for display panels:Third-party foundry services extend die supply beyond captive brands into consumer electronics manufacturing.
Industry Challenges
- Occupancy sensing integration:Facility managers face complexity unbundling legacy controls from networked LED systems during retrofit projects.
- GB standards alignment:China's MIIT-administered performance floors require continuous recertification for export compatibility, compressing product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Lighting Solution Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $181.04 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential, Commercial, Industrial, Decorative Technology: Smart, Conventional, Dimmable, Color Changing End User: Retailers, Homeowners, Corporations, Municipalities Application: Indoor, Outdoor, Automotive, Emergency |
| Companies Covered | Signify, Osram, Acuity Brands, Cree Lighting, Eaton, Nichia Corporation, Samsung LED, Panasonic Corporation, Zumtobel Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Lighting Solution Market Evolving Landscape
Semiconductor packaging architectures and networked control protocols are actively compressing the competitive landscape, favoring suppliers with captive foundry capacity and software integration capabilities over pure-play luminaire assemblers.
Chip-on-board LED arrays are consolidating the mid-power general illumination segment by eliminating discrete package substrates and wire bonds. Warehouse operators and big-box retailers adopt these integrated die configurations for high-bay installations. The technology is consolidating supplier tiers as luminaire brands without wafer-level partnerships lose cost position.
China's GB standards for solid-state lighting, administered under MIIT oversight, now mandate minimum luminous efficacy thresholds that exceed legacy import specifications. Domestic manufacturers retool production lines to meet these floors, while exporters must maintain dual-certification inventories. The commercial segment faces the steepest compliance burden as municipal tenders incorporate these standards into technical scoring.
Daylight harvesting algorithms are reshaping procurement specifications for large-format commercial installations. Engineering-procurement-construction firms now bundle sensor networks with fixture supply, displacing traditional electrical distributor channels. This pattern is most visible in German and Dutch office construction markets where building codes mandate automatic dimming controls.
LED Lighting Solution Market Segmentation
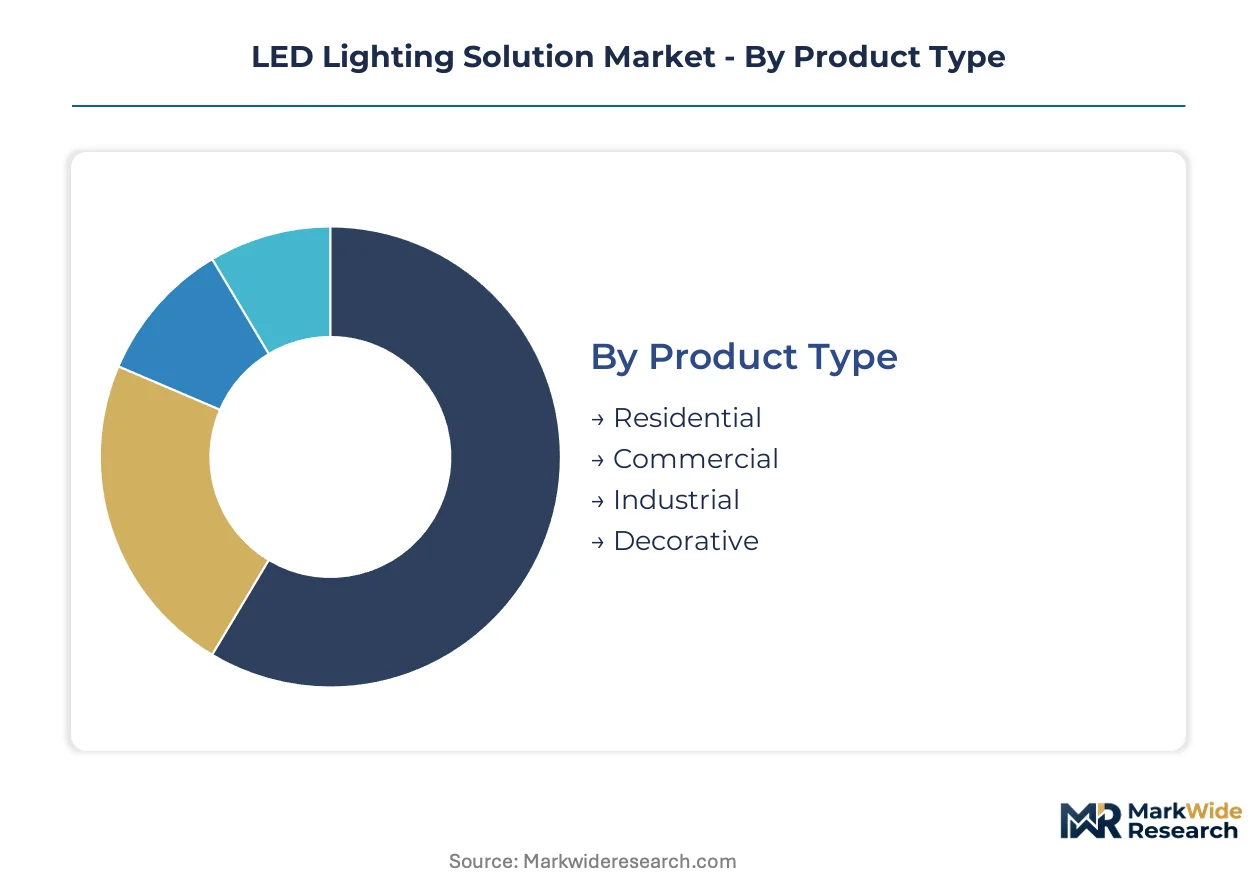
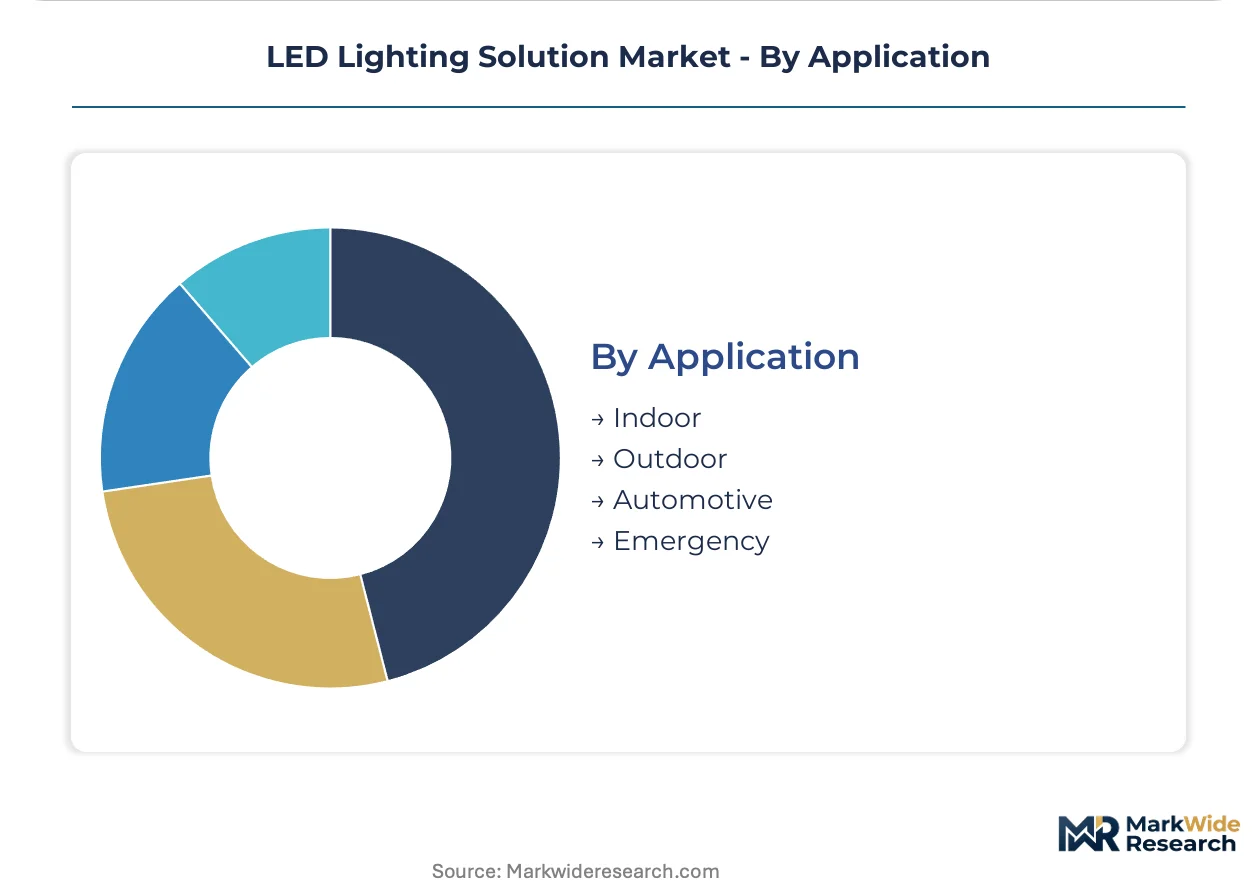
LED lighting solutions fragment across four intersecting dimensions that determine procurement specifications, margin profiles, and supplier qualification requirements. Product type and technology axes capture the hardware-software boundary where value capture is shifting, while end user and application segments dictate certification burdens and channel access.
Product Type:
Luminous efficacy thresholds and operating hour intensity separate these categories by payback calculation methodology.
- Commercial:High-bay fixtures and troffer retrofits dominate installed value through continuous operation in offices, warehouses, and retail environments. Facility managers in Germany and the Netherlands prioritize daylight harvesting compatibility in new construction tenders.
- Industrial:Explosion-rated housings and vibration-resistant assemblies serve manufacturing floors where failure costs exceed hardware price multiples. Chinese foundry output of gallium nitride wafers is compressing cost premiums for high-efficacy industrial die.
- Residential:Socket-compatible retrofits compete on lumens-per-dollar in home improvement retail channels.
- Decorative:Architectural accent and cove lighting emphasizes color consistency over raw efficacy in hospitality and premium residential settings.
Commercial leads on scale; Industrial leads on momentum.
Technology:
Control protocol integration determines whether hardware margins sustain or collapse toward commodity die pricing.
- Smart:Networked fixtures with occupancy sensing and building management system integration command recurring software revenue streams. Municipal street lighting contracts in China bundle decades of maintenance into single procurement decisions favoring connected infrastructure.
- Conventional:Basic on-off operation without dimming or network connectivity serves cost-constrained retrofits where payback hinges solely on wattage reduction.
- Dimmable:Phase-cut and 0-10V protocols enable daylight harvesting compliance in jurisdictions with automatic dimming mandates.
- Color Changing:Tunable white and RGB configurations serve circadian lighting specifications in healthcare and education facilities.
Conventional retains volume dominance; Smart is climbing the fastest.
End User:
Procurement sophistication and contract duration separate these buyers by supplier relationship requirements.
- Municipalities:Street and area lighting contracts span 10-20 year service agreements that bundle installation, maintenance, and energy management. US Department of Energy CALiPER protocols filter substandard imports from federal procurement channels.
- Corporations:Enterprise facility managers negotiate master service agreements covering multi-site retrofit rollouts with standardized specifications.
- Retailers:Electrical distributors and home improvement chains compete on inventory breadth and contractor loyalty programs.
- Homeowners:Consumer-direct and retail replacement purchases emphasize instant payback and installation simplicity.
Municipalities anchor margin pools; Corporations are gaining share fastest.
Application:
Environmental exposure and regulatory safety standards create divergent certification and housing requirements.
- Indoor:General illumination across offices, schools, and healthcare facilities where EU Ecodesign Directive mandates are phasing out mercury-containing legacy lamps. China's GB standards under MIIT oversight now exceed legacy import specifications for luminous efficacy.
- Outdoor:Street, area, and facade lighting faces IP ratings and thermal management challenges in extreme climates.
- Automotive:Headlamp and signal applications require phosphor-conversion patents that concentrate premium die supply with limited licensors.
- Emergency:Battery-backed egress and exit fixtures must maintain output during grid failure per national fire safety codes.
Indoor dominates installed base; Outdoor shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China outpaces the United States in municipal retrofit contract volume, yet German engineering-procurement-construction firms set the technical specifications that shape global tender requirements for connected lighting systems.
China
Domestic gallium nitride wafer foundries under MIIT oversight now supply chip-on-board packaging capacity that eliminates import dependency for high-efficacy die production. GB standards for solid-state lighting mandate luminous efficacy thresholds exceeding legacy import specifications, forcing exporters to maintain dual-certification inventories. Yangtze River Delta manufacturers dominate luminaire assembly for both domestic consumption and export markets.
United States
Commercial facility managers in Texas and California negotiate master service agreements covering multi-site retrofit rollouts with standardized daylight harvesting specifications. The Department of Energy's CALiPER testing protocol filters substandard imports from federal procurement channels, raising certification barriers for offshore manufacturers. Midwest distribution hubs serve contractor loyalty programs that emphasize inventory breadth and rapid fulfillment.
Germany
Engineering-procurement-construction firms in the Netherlands and Germany now bundle sensor networks with fixture supply, displacing traditional electrical distributor channels in office construction markets. The EU Ecodesign Directive phases out mercury-containing legacy lamps across member states, creating mandatory replacement cycles in commercial installations. Bavaria-based industrial lighting specialists supply explosion-rated housings for manufacturing floors across Central Europe.
Japan
Automotive headlamp die supply concentrates with phosphor-conversion patent holders serving premium vehicle programs for domestic and export manufacturers. METI-administered efficiency standards shape procurement specifications for building retrofits in Tokyo and Osaka metropolitan areas. Kyushu-based semiconductor packaging operations feed both captive automotive brands and third-party luminaire assemblers.
India
Urban modernization programs in Maharashtra and Gujarat accelerate street and area lighting retrofit contracts that bundle decades of maintenance into single procurement decisions. BIS certification requirements for solid-state lighting products create compliance hurdles for unqualified imports. Delhi-NCR electrical distributors compete on contractor financing terms for commercial high-bay installations in warehousing and logistics corridors.
LED Lighting Solution Market Competitive Landscape
Chinese producers anchor one tier through domestic wafer foundry scale and government-backed urban modernization programs; European and Japanese specialists hold premium positions through phosphor-conversion patents and automotive die supply. The vendor base organizes into three strategic archetypes: vertically integrated semiconductor-luminaire combinations, pure-play foundry service providers, and software-integrated connected lighting platforms. Capacity expansion in gallium nitride wafer output and strategic partnerships for building management system integration represent the dominant competitive moves reshaping procurement relationships.
Within the patent-protected premium tier, Nichia Corporation and Samsung LED occupy positions that competitors cannot easily replicate through alternative technical approaches. Signify exemplifies the vertically integrated archetype spanning luminaire assembly and connected lighting software. These three anchors demonstrate how value capture concentrates with suppliers controlling either unexpired intellectual property or captive foundry capacity combined with recurring software revenue streams.
| Leading Market Players |
|---|
| Signify |
| Osram |
| Acuity Brands |
| Cree Lighting |
| Eaton |
| Nichia Corporation |
| Samsung LED |
| Panasonic Corporation |
| Zumtobel Group |
| Others |
Value Network & Pricing Analysis
Municipal procurement bundling of 10-20 year maintenance contracts into single tender decisions forces luminaire assemblers to absorb upfront cost compression while securing long-dated revenue streams, reshaping how suppliers negotiate wafer foundry contracts and inventory financing.
Pricing Analysis
Distributor margins in commercial retrofit channels absorb the steepest compression as engineering-procurement-construction firms displace traditional electrical distributors by bundling sensor networks with fixture supply. Project-based pricing dominates municipal street lighting tenders where decades of maintenance are embedded in upfront capital allocation, while transactional per-unit pricing persists in residential socket-compatible retrofits competing on lumens-per-dollar. Price differentiation separates CALiPER-certified suppliers eligible for federal procurement from uncertified imports facing exclusion, with volume scale and GB standards compliance as secondary tiering factors. Pricing pressure stems from Chinese gallium nitride wafer foundries scaling chip-on-board packaging capacity and eroding cost premiums for high-efficacy die. Corporate facility managers show lowest price sensitivity given master service agreements standardizing specifications across multi-site rollouts, whereas home improvement retail channels face extreme sensitivity where payback hinges solely on wattage reduction.
Supply Chain Analysis
Regional distribution centers in the US Midwest and Yangtze River Delta operate on hub-and-spoke patterns feeding contractor loyalty programs and municipal tender fulfillment. Supply concentrates in China for gallium nitride wafer foundry output and chip-on-board packaging, with Japan anchoring premium automotive headlamp die through phosphor-conversion patent holders, and Germany supplying explosion-rated industrial housings. Raw material dependencies include sapphire substrates for LED epitaxy, rare-earth phosphors for color conversion, and aluminum heat sinks for thermal management. Single-source vulnerability concentrates in unexpired phosphor-conversion intellectual property limiting competitor entry to premium automotive segments. Distribution runs through electrical distributors competing on inventory breadth, though EPC direct procurement is displacing this layer in German and Dutch office construction markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
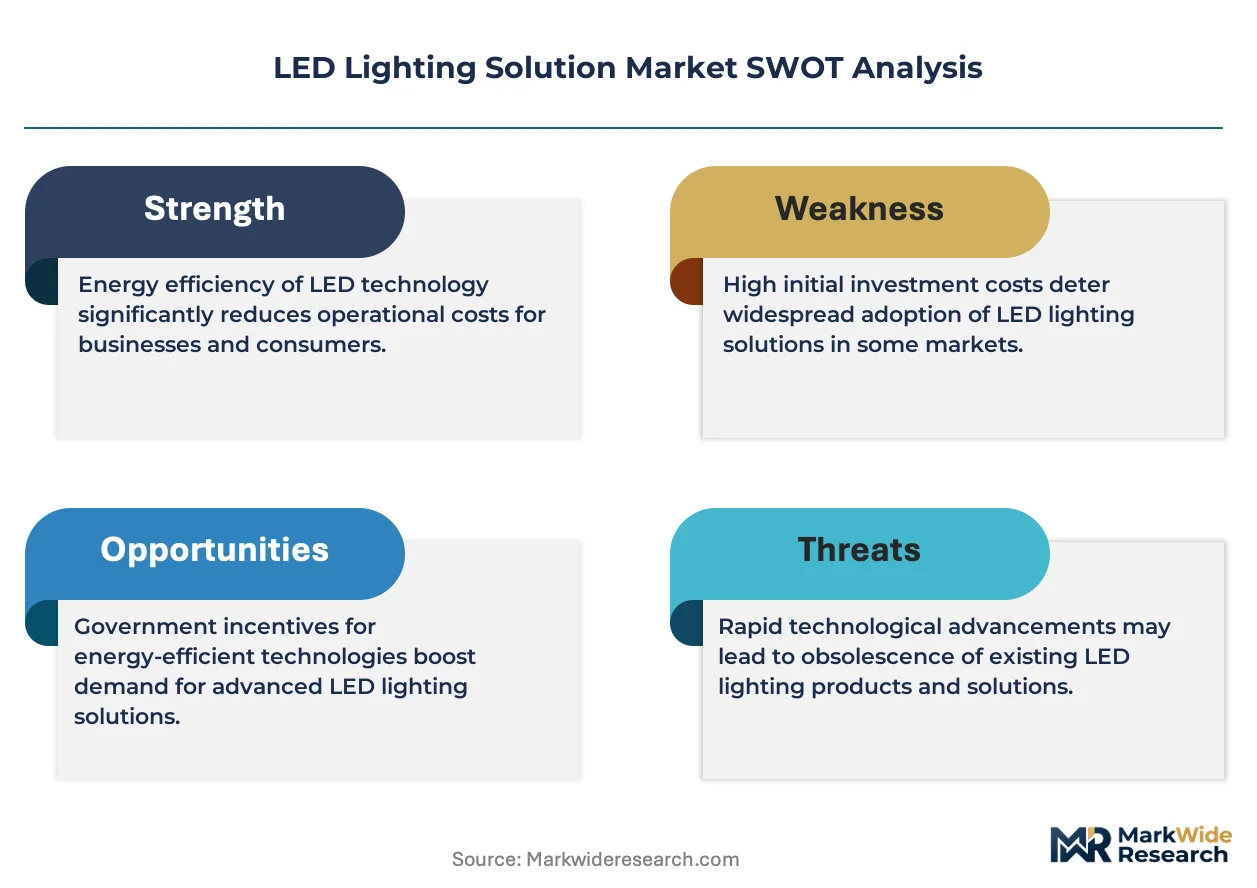
This market functions as a geographic-arbitrage play where European engineering-procurement-construction firms extract premium pricing for connected lighting specifications while Chinese foundry scale compresses input costs for luminaire assembly, exploiting the regulatory gap between EU Ecodesign Directive mandates and MIIT-administered GB standard enforcement timelines.
For Market Incumbents: Hedge phosphor-conversion patent expiration exposure by accelerating captive foundry partnerships in gallium nitride wafer production before unlicensed competitors erode automotive die premiums. Secure backward integration into chip-on-board packaging capacity to defend margin position against pure-play luminaire assemblers losing cost position. Reinforce building management system software integration to sustain recurring revenue streams beyond hardware commoditization. For New Entrants and Emerging Players: Begin with daylight harvesting algorithm development targeting German and Dutch office construction markets where building codes mandate automatic dimming controls and EPC firms actively seek sensor-integrated fixture suppliers. White-space exists in third-party foundry services for display panel backlighting where Samsung LED's extension of die supply to consumer electronics brands demonstrates viable entry. Pursue carbon accounting transparency as a go-to-market wedge for public tender scoring in jurisdictions embedding embodied emissions from semiconductor fabrication. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated semiconductor-luminaire combinations controlling captive foundry capacity and connected lighting software platforms, given the structural compression forcing pure-play assemblers into margin-destroying procurement competition. Long-term viability over a 5-10 year window favors suppliers with MIIT-compliant certification infrastructure and municipal service networks. Target acquisition archetypes include regional distributors with contractor financing capabilities in Indian warehousing corridors or Japanese packaging operations feeding automotive programs. The signal to watch is carbon accounting rule adoption velocity in major economies embedding semiconductor fabrication emissions into tender scoring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into GaN Wafer Production | Captive supply of gallium nitride substrates eliminates import dependency and compresses die costs for high-efficacy packages. |
| Building Management System Platform Integration | Recurring software revenue from networked controls offsets hardware margin erosion in commercial retrofit markets. |
| Carbon Accounting Supply Chain Transparency | Embodied emissions disclosure meets emerging public tender scoring criteria in EU and North American procurement channels. |
| Chip-on-Board Packaging Capacity Expansion | Elimination of discrete package substrates and wire bonds consolidates cost position in mid-power general illumination. |
| Municipal Service Infrastructure Buildout | Decade-spanning maintenance bundling in street lighting contracts creates defensive moats against price-only competitors. |
Research Methodology
Multiple input streams — structured interviews with luminaire procurement managers and facility engineering directors, regulatory filing analysis from MIIT and the US Department of Energy, and trade flow data from semiconductor packaging operations — were reconciled against secondary validation from SEC filings of listed lighting manufacturers and EPC contract award databases. Primary fieldwork captured perspectives from municipal street lighting procurement officers, electrical distributor category managers, and automotive Tier 1 supplier quality engineers. Secondary sources included CALiPER testing protocol disclosures, EU Ecodesign Directive implementation reports, and GB standards certification registries. Bottom-up segment sizing triangulated against top-down macroeconomic drivers produced convergent estimates.
Historical volume trajectories were cross-referenced against panel input from industry participants to establish baseline growth patterns across the projection horizon. The analytical framework modeled segmentation across product type, technology tier, end-user procurement sophistication, and application environment, with additional dimensioning by regional regulatory cluster given divergent Ecodesign, CALiPER, and GB standard enforcement timelines. CAGRs were derived from slope-consistency checks against wafer foundry capacity expansion schedules and municipal retrofit program announcements. Industry-specific forecast inputs included gallium nitride substrate output projections and smart city infrastructure investment pipelines.
Several conditions sit outside the modeled scope, including unannounced phosphor-conversion patent litigation outcomes, abrupt tariff reconfigurations affecting semiconductor packaging equipment, and pandemic-scale disruptions to sapphire substrate supply chains. Forecasts reflect documented assumptions regarding MIIT standard enforcement continuity and EU member state transposition timelines for Ecodesign updates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
South America Indoor LED Lighting Market
LED
China LED Lighting Market
LED
Chip on Board LED Market
LED
Japan LED Market
LED
Arrow LED Displays Market
LED
LED Panel Light Drivers Market
LED
Indonesia LED Market
LED
Dot-Matrix LED Displays Market
LED
Asia Pacific Indoor LED Lighting Market
LED
High-Intensity LED Logo and Livery Lighting Systems Market
LED
Outdoor LED Display Market
LED
LED and OLED Display Market
LED
China Indoor LED Lighting Market
LED
Gan Micro LED Market
LED
LED Flip Chip Market
LED
US LED Downlight Market